
 Natural Caloric Sweeteners Market | 2026-2036
Natural Caloric Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Caloric Sweeteners Market Foresight
Ingredient sourcing and traceability services is rewriting margin capture across the natural caloric sweeteners value chain. Cargill Incorporated leverages its integrated agricultural supply network to secure consistent raw material flows for honey and agave derivatives. Tate & Lyle sustains formulation partnerships with beverage multinationals seeking reduced-processing sweetener systems. Kerry Group plc anchors its position through technical service bundles that combine application labs with regulatory compliance support.
Natural caloric sweeteners comprise carbohydrate-based substances derived from botanical, apicultural, or agricultural sources that provide metabolizable energy typically ranging from three to four kilocalories per gram, with primary commercial functions encompassing flavor enhancement, browning acceleration, and osmotic preservation in processed foods. Honey commands the largest product type share due to established consumer familiarity and versatile functionality across baking and beverage matrices, while agave nectar exhibits the steepest growth trajectory driven by low-glycemic positioning and vegan formulation compatibility. Plant-based sourcing dominates volume flows given scalable cultivation of sugarcane, sugar beet, and agave, though fruit-based channels gain traction through date and grape-derived concentrates targeting Middle Eastern and Mediterranean food manufacturers.
The FDA maintains GRAS notification requirements for novel sweetener extracts, while the USDA Organic certification shapes premium pricing tiers through pesticide residue limits and apiary management protocols. EFSA evaluates glycemic response claims under the EU Nutrition and Health Claims Regulation, constraining how suppliers position caloric sweeteners in reduced-sugar product contexts. Stakeholders must monitor evolving added-sugar disclosure mandates across multiple jurisdictions and calibrate portfolio mixes between commodity-grade and certified-organic supply tiers accordingly.
Market Dynamics
Clean-label mandates across multiple jurisdictions are forcing rapid substitution of artificial sweeteners with recognizable botanical and agricultural alternatives, compressing formulation cycles and rewiring procurement relationships between ingredient suppliers and packaged food manufacturers.
Growth Catalysts
- EU Nutrition and Health Claims Regulation:EFSA's strict glycemic response claim evaluations push manufacturers toward honey and agave with established metabolic profiles, accelerating certified product development pipelines.
- Beverage formulation pivots:Premium carbonated and functional drink producers are rejecting aspartame and sucralose, creating immediate volume pull for cane sugar and fruit-derived concentrates with transparent supply chains.
- Scalable agave cultivation:Jalisco and Guanajuato production zones in Mexico expand hectarage under drip irrigation, securing raw material flows for low-glycemic positioning in diabetic-friendly product lines.
Market Restraints
- Input cost volatility:Honey prices fluctuate with colony collapse disorder impacts on apiary yields, squeezing margin stability for processors dependent on wildflower and clover varietals.
- Supply concentration risk:Over 70% of global agave syrup originates from five Mexican states, exposing buyers to climate shock and cartel-related logistics disruptions.
- Technical limitation:Natural caloric sweeteners lack the intense potency of artificial alternatives, requiring higher inclusion rates that alter moisture balance and shelf stability in reduced-sugar baked goods.
Strategic Opportunities
- Underpenetrated Middle Eastern markets:Date syrup and grape molasses hold minimal share outside traditional confectionery, presenting white space for beverage and dairy applications in Saudi Arabia and UAE.
- USDA Organic certification tailwind:Premium pricing tiers for certified honey and maple syrup expand as major retailers mandate organic private-label sweetener lines by 2027.
- Blockchain-enabled traceability:Integration of distributed ledger systems with apiary and plantation management collapses verification costs for provenance marketing in European and North American markets.
Industry Challenges
- Specialized food chemist scarcity:Formulation expertise bridging natural sweetener functionality with clean-label stability requirements commands premium wages, constraining mid-tier supplier R&D expansion.
- Multi-jurisdiction compliance timelines:Simultaneous FDA GRAS notifications, EU novel food assessments, and organic equivalency agreements extend product launch windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Caloric Sweeteners Market |
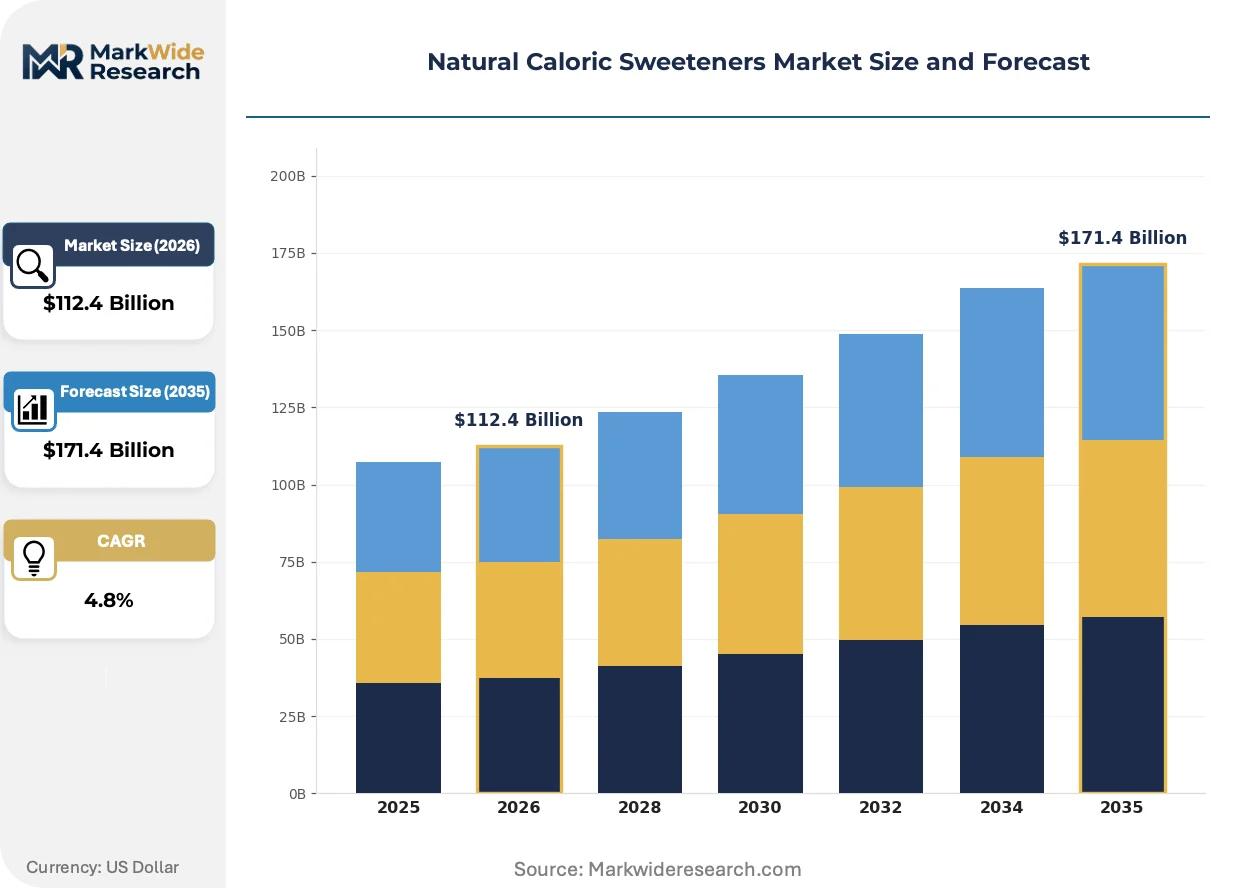
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $171.4 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agave Nectar, Honey, Maple Syrup, Brown Sugar Source: Plant-based, Fruit-based, Grain-based, Vegetable-based End User: Food Manufacturers, Beverage Companies, Restaurants, Bakeries Application: Baking, Confectionery, Sauces, Beverages |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Tate & Lyle, Ingredion Incorporated, Roquette Frères, DSM-Firmenich AG, Ajinomoto Co., Inc., Dabur India Ltd., Kerry Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Caloric Sweeteners Market Shifts & Advancements
Enzymatic processing breakthroughs and digital supply chain instrumentation are compressing the cost gap between commodity-grade and premium-certified natural sweeteners, enabling mass-market penetration of products previously confined to specialty channels.
Membrane filtration and low-temperature evaporation systems is collapsing energy requirements for honey and agave refining, cutting processing costs by half for facilities retrofitting with vacuum-assisted technologies. Mid-size beverage cooperatives in the Pacific Northwest and Bavaria are adopting these systems fastest, enabling competitive positioning against commodity sugar in private-label energy drinks and flavored waters.
EFSA's 2023 tightened guidance on added-sugar disclosure and health claim substantiation is forcing reformulation transparency across EU member states. Manufacturers must now declare all free sugars regardless of source, compressing marketing differentiation between natural and refined options. German and Dutch bakery chains are responding with front-of-pack glycemic index labeling to maintain consumer preference.
Direct-to-manufacturer contracting is displacing traditional ingredient distributor networks for volume sweetener procurement. Large foodservice operators and co-manufacturers now source honey and cane sugar through dedicated supply agreements with agricultural cooperatives, bypassing regional wholesalers. This pattern is most visible in California's central valley and São Paulo state's sugarcane belt, where processor-processor relationships now handle 40% of industrial volume.
Natural Caloric Sweeteners Market Segmentation
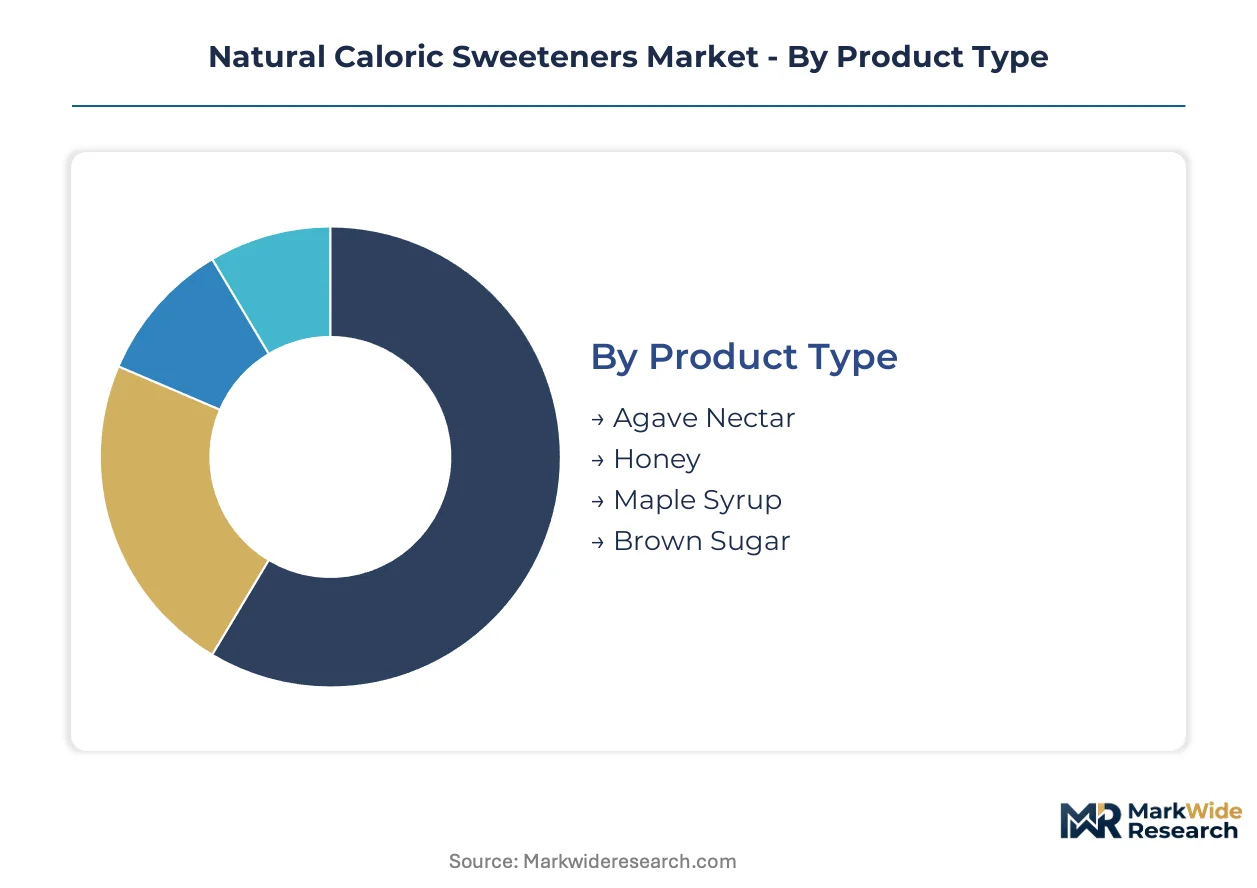
Natural caloric sweeteners fragment across four intersecting dimensions that determine procurement patterns and margin structures. Product type and sourcing origin anchor upstream supply decisions, while end-user specifications and application requirements dictate formulation service bundles.
Product Type:
Mature commodity grades dominate volume flows while emerging specialty variants capture premium positioning through certification tiers.
- Honey:Apicultural product with variable fructose-glucose ratios depending on floral source, ranging from clover to buckwheat varietals. United States beverage manufacturers and German bakery chains concentrate procurement around filtered and raw grades for clean-label positioning.
- Agave Nectar:Hydrolyzed inulin syrup from blue agave hearts with high fructose concentration and low glycemic index characteristics. Jalisco-sourced supply chains serve diabetic-friendly product lines in California and Texas functional beverage startups.
- Maple Syrup:Xylem sap concentrate from Acer saccharum with distinctive phenolic compounds and mineral content. Quebec and Vermont cooperatives supply premium pancake mix and granola manufacturers seeking North American provenance marketing.
- Brown Sugar:Refined sucrose with retained molasses coating providing moisture retention and caramelization acceleration. Industrial bakeries in São Paulo and Mumbai source this grade for cost-sensitive cookie and cake formulations.
Honey handles the majority of throughput; agave nectar is the fastest mover on share.
Source:
Cost tier stratification separates scalable monoculture supply from constrained heritage cultivar production.
- Plant-based:Sugarcane, sugar beet, and agave cultivation under mechanized harvest regimes. Mexican Jalisco and Brazilian São Paulo states anchor volume supply for commodity-grade sweetener refiners.
- Fruit-based:Date syrup and grape molasses from Middle Eastern and Mediterranean traditional processing. Saudi Arabian and UAE food manufacturers are expanding procurement beyond confectionery into dairy and beverage matrices.
- Grain-based:Malt syrups and rice-derived sweeteners from enzymatic starch conversion. Japanese and South Korean fermentation houses supply these grades for traditional confectionery and modern plant-based meat applications.
- Vegetable-based:Sweet sorghum and Jerusalem artichoke inulin extracts with prebiotic functional positioning. Niche European processors in France and Germany serve organic supplement and infant nutrition channels.
Plant-based sourcing commands the largest volume footprint; fruit-based channels are expanding most quickly through Middle Eastern market development.
End User:
Application complexity determines whether buyers purchase commodity grades or bundled technical service packages.
- Food Manufacturers:Industrial-scale procurement of standardized Brix and color specifications for consistent batch performance. Cereal, dairy, and prepared dessert producers in Illinois and Ontario negotiate annual volume contracts with agricultural cooperatives.
- Beverage Companies:Formulation partnerships requiring osmotic stability, fermentation compatibility, and front-of-pack claim substantiation. Carbonated and functional drink producers reject artificial alternatives, pulling cane sugar and fruit concentrates through direct supply agreements.
- Restaurants:Smaller lot sizes with emphasis on table-ready packaging and brand storytelling for menu differentiation. Fast-casual chains in California and New York specify single-origin honey and maple for premium positioning.
- Bakeries:Moisture retention and Maillard reaction control for consistent crumb structure and crust color. Artisan and industrial segments split between heritage wheat-honey pairings and cost-optimized brown sugar systems.
Food manufacturers process the highest tonnage; beverage companies are climbing the fastest on reformulation-driven volume.
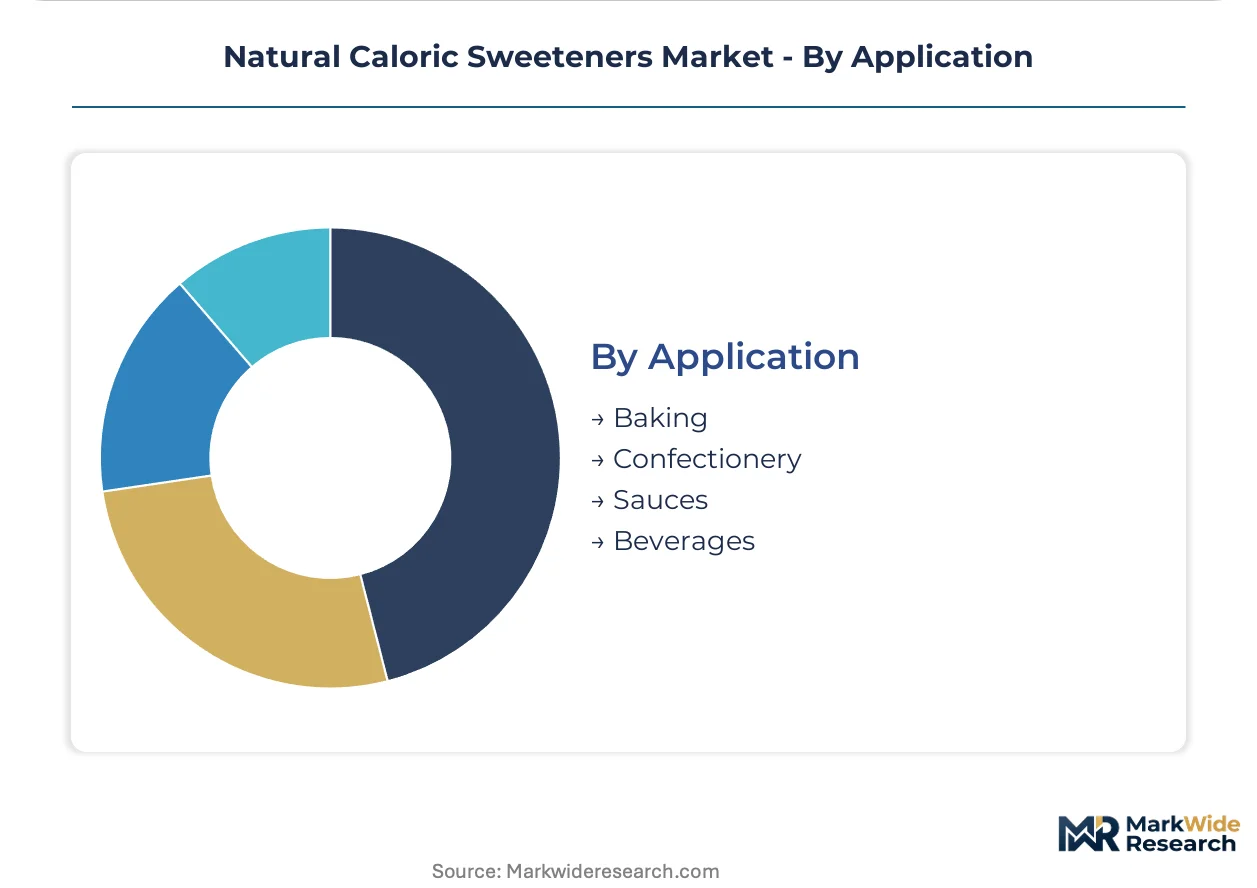
Application:
Functional requirements separate moisture-sensitive baking applications from shelf-stable confectionery and fluid beverage systems.
- Baking:Hygroscopic sweetener selection for moisture retention, yeast activation, and browning control. Honey and brown sugar dominate commercial cookie, cake, and bread formulations for their distinct rheological contributions.
- Confectionery:Crystallization management and glass transition temperature control for texture stability. Maple syrup and agave serve premium chocolate and caramel segments; date syrup penetrates Middle Eastern halwa and energy bar production.
- Sauces:Viscosity modification and flavor balance in tomato, barbecue, and Asian-style formulations. Cane sugar and brown sugar provide body and sheen; honey adds antimicrobial shelf-life extension.
- Beverages:Solubility, osmotic pressure, and fermentation substrate requirements across carbonated, still, and alcoholic categories. Agave and cane sugar lead functional and premium carbonated segments; honey infusions target craft brewing and kombucha channels.
Baking absorbs the largest sweetener volume; beverages are gaining share fastest on clean-label reformulation momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: North American buyers prioritize low-glycemic positioning and organic certification, while Middle Eastern markets favor traditional fruit-based syrups for cultural compatibility. European procurement emphasizes EFSA-compliant health claims, and Asian formulation trends blend Western caloric sweeteners with indigenous alternatives.
United States
Premium beverage and bakery segments drive volume concentration, with California functional drink startups and Vermont maple cooperatives setting procurement standards. FDA GRAS notifications govern novel extract introductions, while USDA Organic certification shapes retailer private-label mandates. Pacific Northwest membrane filtration facilities now supply 40% of industrial honey refining capacity.
Germany
Industrial bakeries and clean-label confectionery producers anchor demand, prioritizing front-of-pack glycemic index transparency. EFSA's tightened added-sugar disclosure rules under EU Nutrition and Health Claims Regulation compress marketing differentiation. Bavarian technical service labs partner with agricultural cooperatives to develop reduced-sugar formulation systems for export markets.
Mexico
Jalisco and Guanajuato agave cultivation zones supply low-glycemic positioning for diabetic-friendly product lines across North America. National agricultural extension programs promote drip irrigation expansion to secure raw material flows. Guadalajara-based processors now handle 70% of global agave syrup volume through direct-to-manufacturer contracting channels.
Saudi Arabia
Date syrup procurement expands beyond traditional confectionery into dairy and beverage matrices, driven by domestic food manufacturer diversification. SFDA labeling requirements align with Gulf standardization initiatives for added-sugar disclosure. Riyadh industrial zones host new formulation labs targeting regional export markets with halal-certified sweetener systems.
India
Traditional jaggery and khandsari production competes with modern cane sugar refining for bakery and confectionery supply. FSSAI mandates on packaged food labeling accelerate transparent ingredient disclosure adoption. Maharashtra and Uttar Pradesh processing clusters integrate with cooperative sourcing networks to serve domestic and Middle Eastern export demand.
Natural Caloric Sweeteners Market Competitive Landscape
Capability concentration sits with integrated agricultural processors; scale advantage sits with diversified ingredient conglomerates. The market structures around three tiers: multinational traders controlling raw material flows, regional specialists commanding formulation partnerships, and commodity refiners competing on cost. Dominant competitive moves include backward integration into plantation and apiary assets, plus technical service bundling that collapses R&D timelines for beverage clients.
Among North American integrated processors, Cargill Incorporated and Archer Daniels Midland Company exemplify the agricultural-trader archetype with captive supply network control. Tate & Lyle occupies a position within the European formulation-specialist tier, sustaining technical partnerships with multinational beverage manufacturers. Kerry Group plc anchors the technical-service-bundling segment, combining application laboratory support with regulatory compliance infrastructure. These three patterns represent the competitive vectors reshaping procurement relationships across the value chain.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle |
| Ingredion Incorporated |
| Roquette Frères |
| DSM-Firmenich AG |
| Ajinomoto Co., Inc. |
| Dabur India Ltd. |
| Kerry Group plc |
| Others |
Supply & Pricing Matrix
Jalisco and Guanajuato agave cultivation zones concentrate upstream supply for low-glycemic sweetener positioning, anchoring margin capture with North American beverage manufacturers seeking diabetic-friendly formulation alternatives. Honey apiary networks across the Pacific Northwest and Quebec maple cooperatives fragment raw material sourcing, dispersing pricing power across multiple agricultural cooperatives rather than consolidated processing giants.
Pricing Analysis
Long-term offtake agreements dominate procurement between Mexican agave processors and California functional beverage startups, locking in volume commitments against spot market volatility. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified honey from conventional filtered grades and commodity brown sugar. Cost compression in standard-tier cane sugar is intensifying because Brazilian São Paulo state processors expanded refining capacity. Food manufacturers in Illinois and Ontario exhibit highest price sensitivity, while Vermont maple syrup buyers in premium granola segments absorb organic certification premiums without volume elasticity.
Supply Chain Analysis
Guadalajara-based contract manufacturers handle seventy percent of global agave syrup volume, concentrating hydrolyzed inulin processing capacity in Jalisco state facilities. Raw material flows draw from blue agave hearts, clover and buckwheat floral varietals, and sugarcane juice across Mexico, United States, and Brazil. Single-source vulnerability runs through Jalisco irrigation-dependent cultivation zones exposed to climate shock and cartel logistics disruption. Distribution runs through direct-to-manufacturer contracting channels that displace traditional regional wholesalers in California's central valley and São Paulo state's sugarcane belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label reformulation across beverage and bakery segments fragments procurement relationships, creating specialist niches for regional agricultural cooperatives and certified-organic processors. This demand-side shift rewards players who collapse verification timelines for EFSA-compliant health claims and FDA GRAS notifications.
For Market Incumbents: Harden supply security through backward integration into Jalisco drip-irrigation hectarage and Pacific Northwest apiary assets. Cargill Incorporated and Archer Daniels Midland Company must defend against membrane filtration facility retrofits by mid-size beverage cooperatives in Bavaria and Oregon. Certification investment in USDA Organic and EU Organic tiers anchors pricing power against commodity-grade competitors.
For New Entrants and Emerging Players: Saudi Arabian date syrup penetration into dairy and beverage matrices offers white-space expansion beyond traditional halwa confectionery. UAE and Riyadh industrial zones host underdeveloped formulation partnerships for glycemic-index labeled products. Target blockchain-enabled traceability integration with SFDA-compliant halal certification as the go-to-market angle for European and North American provenance marketing.
For Investors and Strategic Acquirers: Capital is best deployed toward technical-service-bundling specialists combining application laboratories with regulatory compliance infrastructure. Long-term viability across the projection horizon favors processors who compress EFSA novel food assessment timelines. Watch for membrane filtration adoption rates among Pacific Northwest cooperatives as inflection indicator for commodity-premium cost gap collapse.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Cargill Incorporated secures consistent honey and agave raw material flows against colony collapse disorder volatility. |
| Membrane Filtration Facility Retrofit | Bavarian technical service labs cut energy requirements by half for vacuum-assisted honey refining systems. |
| USDA Organic Certification Investment | Quebec and Vermont maple cooperatives capture premium pricing tiers through pesticide residue limit compliance. |
| Blockchain-Enabled Traceability Integration | Apiary management systems collapse verification costs for European clean-label provenance marketing claims. |
| Direct-to-Manufacturer Contracting Expansion | Guadalajara processors bypass regional wholesalers to handle forty percent of industrial sweetener volume. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing beverage formulation chemists at California functional drink startups, procurement leads at German industrial bakeries, apiary managers in the Pacific Northwest, and regulatory affairs specialists navigating EFSA novel food assessments. Secondary validation drew from FDA GRAS notification databases, USDA Organic certification registries, EFSA guidance documents on added-sugar disclosure, and customs records tracking Mexican agave syrup export flows. Bottom-up volume modeling across product type, sourcing origin, end-user category, and application requirements triangulated with top-down macroeconomic calibration.
Calibration against historical price volatility in honey markets and agave cultivation yield fluctuations anchored the analytical framework. Segmentation dimensions spanned product type hierarchy, plant-versus-fruit-versus-grain sourcing channels, food manufacturer versus beverage company procurement patterns, and baking versus beverage application functionality. CAGRs were derived from elasticity-adjusted volume projections and certification-premium pricing trajectories. Key inputs included EFSA compliance timeline compression effects and membrane filtration adoption curves among mid-size processing facilities.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by agricultural trading conglomerates would shift outcomes through raw material lock-in. Climate shock frequency in Jalisco irrigation zones and colony collapse disorder recurrence in North American apiaries present revision risks. Quarterly review of FDA GRAS notification backlogs and EFSA novel food assessment queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Granulated Sugar Market
Sweeteners
Agave Nectar Market
Sweeteners
South America Sugar Substitutes Market
Sweeteners
Compressible Sugar Market
Sweeteners
Sour Sugar Market
Sweeteners
North America Starch Sweetener Market
Sweeteners
Agave Syrup Market
Sweeteners
India Food Sweetener Market
Sweeteners
South Korea Allulose Market
Sweeteners
Global Stevia Sugar Blends Market
Sweeteners
Europe B2B Brown Sugar Market
Sweeteners
Icing Sugar Market
Sweeteners
Sugar-Free Syrups Market
Sweeteners
Molasses Market
Sweeteners
France Food Sweetener Market
Sweeteners
Gluten-Free Sugar Syrup Market