
 Argentina Food Sweetener Market | 2026-2036
Argentina Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Food Sweetener Market Outlook
Ingredient customization revenue is reshaping margin capture across the Argentina food sweetener value chain. Cargill Incorporated leverages its Rosario crushing and refining footprint to anchor bulk high fructose corn syrup supply to domestic bottlers. Tate & Lyle PLC specializes in modified starch and sweetener blends that differentiate beverage and dairy formulations for industrial buyers. Archer Daniels Midland Company sustains origination advantages through its grain handling network across Santa Fe and Buenos Aires provinces.
Food sweeteners comprise caloric and non-caloric substances added to confer sweetness, typically measured by sucrose equivalence and thermal stability profiles, with applications spanning taste modulation, browning control, and shelf-life extension in processed goods. Sugar still occupies the largest volume share among product types, though stevia extracts are recording the fastest conversion rates as beverage brands reformulate around clean-label positioning. Within end users, the dairy segment concentrates premium formulation activity around protein-fortified drinks and reduced-sugar yogurts.
ANMAT, Argentina's national food and drug regulator, enforces additive maximum-use levels and labeling disclosures that directly determine which sweetener systems processors may deploy. The country's alignment with MERCOSUR technical standards further conditions import eligibility and cross-border formulation consistency for multinational manufacturers. Stakeholders must monitor pending updates to the Argentine Food Code regarding novel sweetener approvals and front-of-pack warning label thresholds.
Market Dynamics
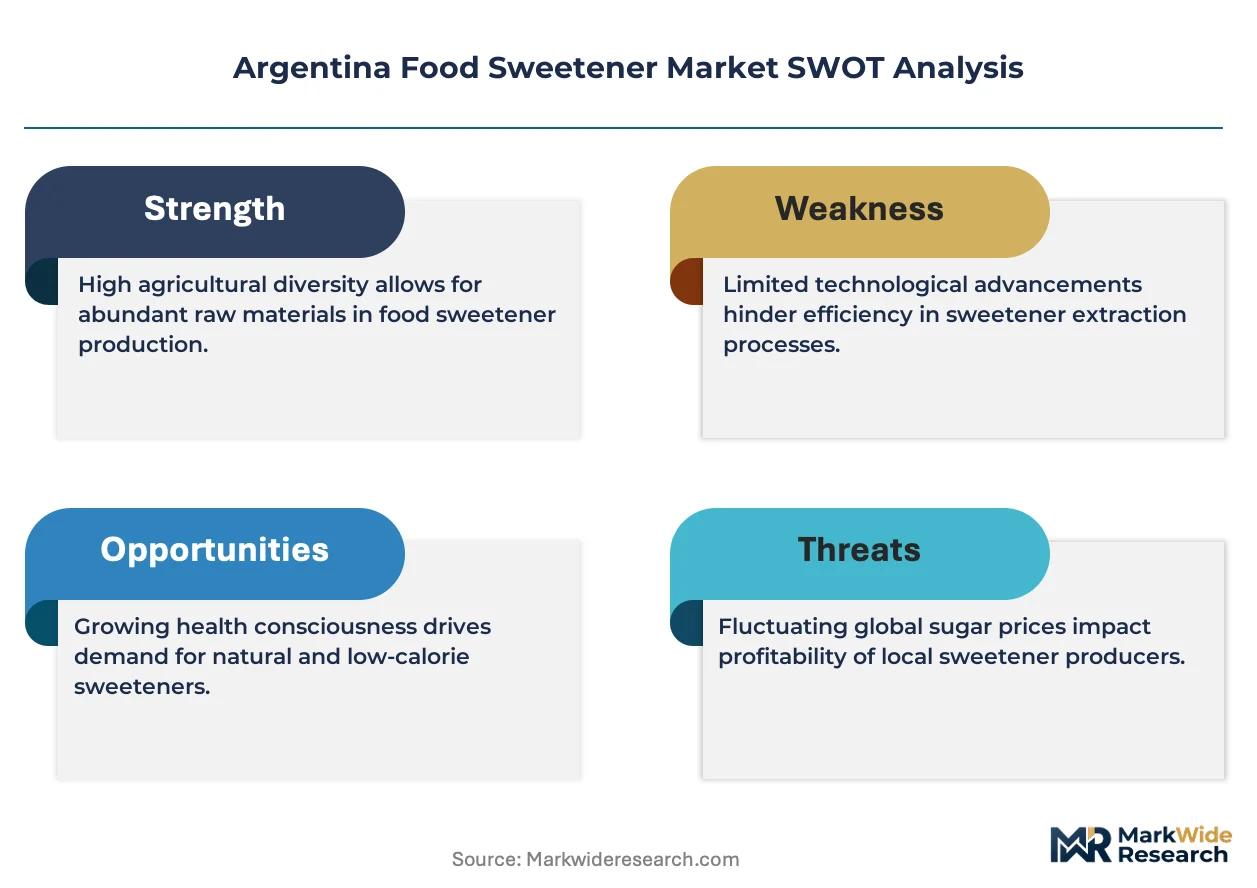
ANMAT's tightening additive labeling rules are forcing processors across Buenos Aires and Córdoba to abandon synthetic sweetener systems and rebuild formulations around plant-derived alternatives, compressing reformulation timelines and reshaping supplier relationships throughout the Pampas dairy belt.
Growth Catalysts
- Beverage Industry Reformulation:Bottlers in Buenos Aires and Córdoba are converting production lines to low-calorie formulations, creating sustained pull for stevia and monk fruit extracts as clean-label positioning becomes a non-negotiable retail requirement.
- ANMAT Labeling Mandates:Argentina's national food and drug regulator now requires front-of-pack disclosure of synthetic additives, accelerating displacement of aspartame and sucralose in favor of recognizable plant-based ingredients.
- Pampas Dairy Belt Concentration:Yogurt and flavored milk processors across Santa Fe and Buenos Aires provinces are clustering demand for customized sweetener blends that maintain mouthfeel while reducing sugar content.
Market Restraints
- Input Cost Volatility:Stevia leaf supply from Misiones province fluctuates with rainfall patterns, creating margin pressure for extract processors unable to lock in multi-year agricultural contracts.
- Import Dependency for Specialty Enzymes:Argentina's biotechnology sector lacks domestic capacity for glucosyltransferase production, forcing sweetener blenders to source from Brazilian or North American suppliers with extended lead times.
- Technical Limitation in Heat Stability:Reb-A stevia extracts degrade above 80°C, excluding them from baked goods applications and ceding volume share to erythritol and maltitol in the confectionery segment.
Strategic Opportunities
- Underpenetrated Patagonia Region:Neuquén and Río Negro provinces host emerging craft beverage producers seeking localized sweetener supply partnerships, bypassing consolidated Buenos Aires distribution channels.
- Regulatory Tailwind from MERCOSUR Alignment:Argentina's harmonization with regional technical standards enables cross-border formulation consistency, allowing processors to scale recipes across Uruguay, Paraguay, and Brazil without regulatory friction.
- Emerging Application in Protein Fortification:Sports nutrition manufacturers are integrating allulose and erythritol into ready-to-drink shakes, opening a premium price tier beyond traditional beverage and dairy segments.
Industry Challenges
- Specialized Formulation Talent Scarcity:Food technologists with expertise in synergistic sweetener blends—combining high-potency extracts with bulk polyols—command premium compensation and remain concentrated in Rosario and Buenos Aires metropolitan areas.
- Certification Timeline Compression:Novel sweetener approvals through ANMAT's novel food pathway require 18-24 month evaluation cycles, delaying product launches and freezing R&D investment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Food Sweetener Market |
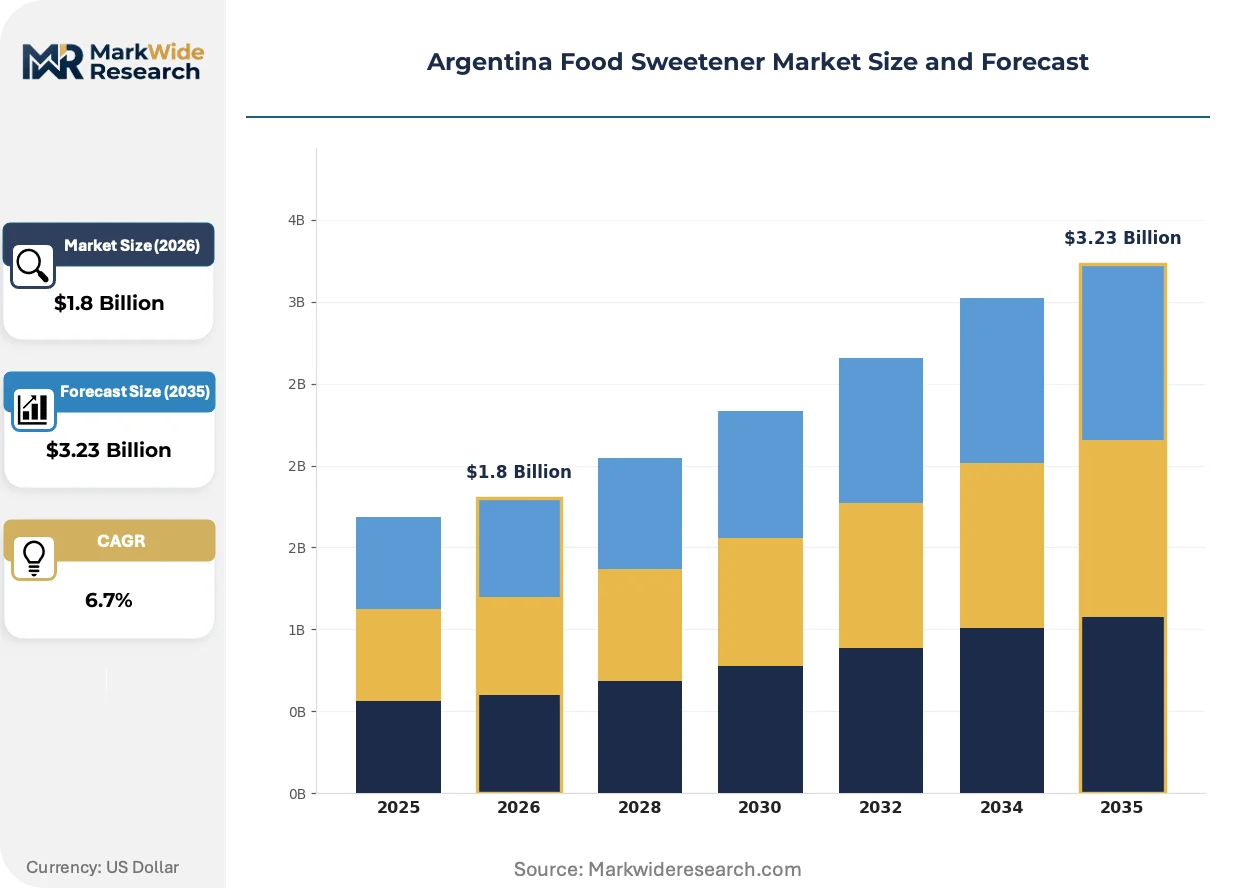
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sugar, High Fructose Corn Syrup, Aspartame, Stevia End User: Beverage Industry, Bakery, Confectionery, Dairy Form: Liquid, Granular, Powder, Syrup Application: Food Processing, Retail, Consumer Products, Food Service |
| Companies Covered | International Flavors & Fragrances Inc, Glucovil Argentina S A, Louis Dreyfus Company, Argentbio SA, Tate & Lyle PLC, NutraSweet Company, Archer Daniels Midland Company, ANAGALIDE SA, Cargill Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Food Sweetener Market Strategic Shifts
Digital integration across Argentina's sweetener supply chain is compressing formulation cycles and enabling real-time customization for industrial buyers, while regulatory pressure and shifting procurement patterns are restructuring how processors source and specify ingredients.
Near-infrared spectroscopy paired with machine learning algorithms is digitizing quality control at crushing and refining facilities, allowing Rosario-based processors to predict steviol glycoside content in raw leaf shipments before extraction begins. Dairy formulators in the Pampas region are adopting these predictive tools to lock in sweetness consistency across seasonal harvest variations. The technology is digitizing procurement decisions that previously relied on post-delivery laboratory verification, compressing supplier qualification timelines from weeks to days.
ANMAT's pending updates to the Argentine Food Code regarding front-of-pack warning labels are forcing beverage manufacturers to eliminate synthetic sweeteners from formulations targeting school-age consumers. Industrial buyers are responding by requesting certificate-of-analysis documentation that traces sweetener provenance to specific agricultural cooperatives. The dairy segment faces the most acute compliance pressure, as flavored milk products currently rely heavily on sucralose to achieve sweetness without added sugar volume.
Direct sourcing partnerships between Pampas dairy processors and Misiones stevia cooperatives are displacing traditional distributor-mediated procurement, with buyers establishing multi-year offtake agreements that specify glycoside purity tiers. These arrangements are compressing the traditional three-tier supply structure and transferring price risk from processors to agricultural producers. The shift is most visible among mid-scale yogurt manufacturers in Santa Fe province seeking supply security amid currency volatility.
Argentina Food Sweetener Market Segmentation
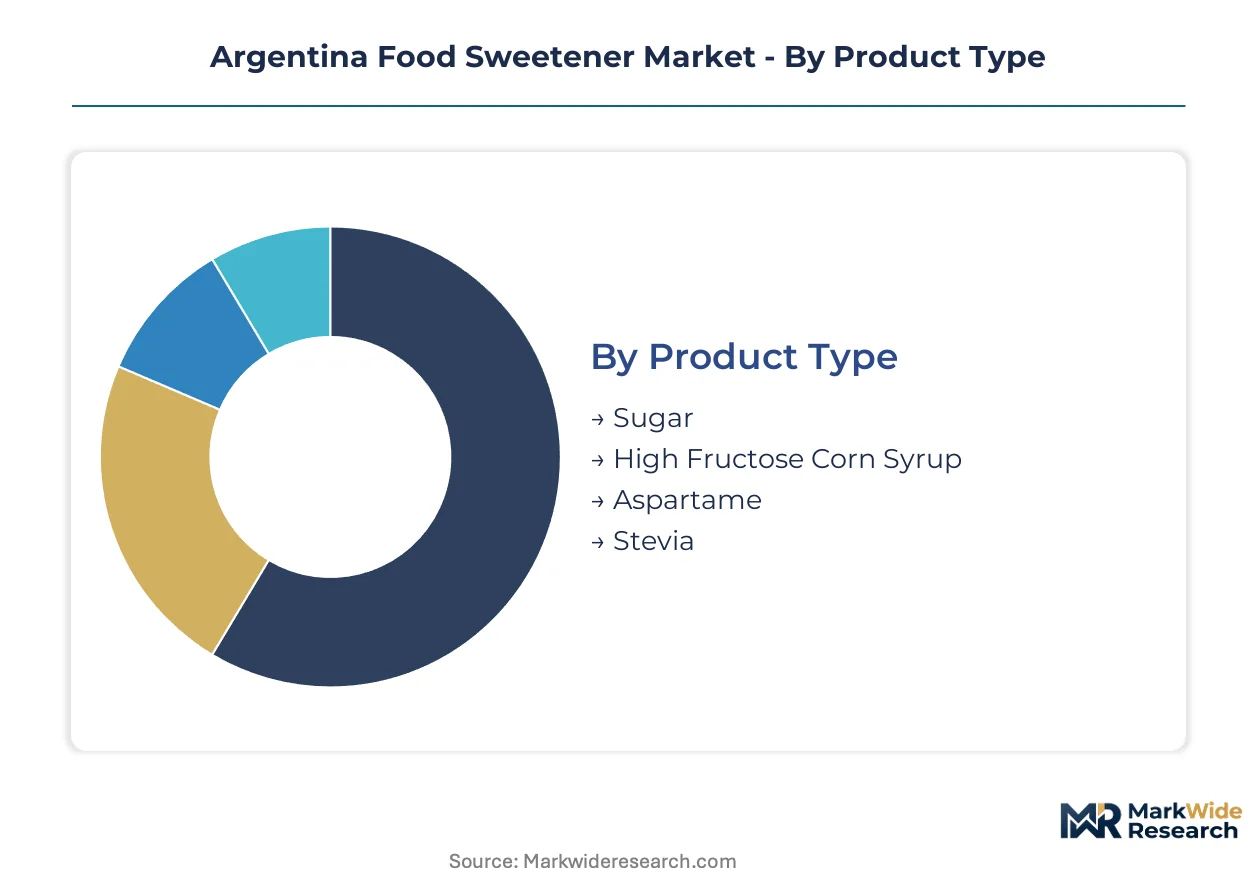
Sweetener procurement patterns across Argentina's Pampas dairy belt and Buenos Aires beverage corridors vary sharply by product chemistry and end-use thermal requirements. Formulators select systems based on ANMAT labeling thresholds, heat stability constraints, and clean-label positioning mandates that differ fundamentally across dairy, beverage, and baked goods applications.
Product Type:
Mature caloric sweeteners dominate volume flows through Rosario crushing infrastructure, while plant-derived high-potency extracts are capturing reformulation commitments as ANMAT disclosure rules harden against synthetic additives.
- Sugar:Sucrose from Tucumán and Jujuy cane mills supplies bulk sweetness for traditional confectionery and standard beverage lines. Pampas dairy processors rely on crystalline sugar for mouthfeel retention in premium yogurt formulations where clean-label positioning tolerates caloric content.
- High Fructose Corn Syrup:Derived from Santa Fe province corn origination, this liquid sweetener serves Buenos Aires bottlers seeking cost-optimized carbonated drink production. Cargill's Rosario refining footprint anchors domestic supply security for industrial-scale beverage manufacturing.
- Aspartame:Synthetic dipeptide sweetener facing displacement as ANMAT front-of-pack warning labels flag artificial additive content; residual demand concentrates in legacy diet soda formulations.
- Stevia:Misiones province leaf extraction yields reb-A and stevioside glycosides for reformulated low-calorie beverages; thermal stability limitations restrict bakery deployment.
Sugar retains volume leadership; Stevia holds the steepest expansion curve.
End User:
Application heat profiles and label transparency requirements split demand across four processing verticals, with cold-chain dairy and ambient beverage commanding distinct sweetener specification regimes.
- Beverage Industry:Buenos Aires and Córdoba bottlers drive bulk procurement of high fructose corn syrup and stevia extracts for carbonated and still drink portfolios; ANMAT disclosure mandates accelerate plant-derived system adoption.
- Dairy:Santa Fe and Buenos Aires province yogurt and flavored milk processors require sweetness modulation without added sugar volume, favoring stevia-allulose blends that maintain protein fortification stability.
- Bakery:Heat-stable polyols including erythritol and maltitol serve Argentine bread and pastry manufacturers where reb-A degradation above 80°C excludes stevia from oven applications.
- Confectionery:Hard candy and chocolate producers in Greater Buenos Aires balance cost and crystallization control through sucrose-maltitol combinations.
Beverage Industry commands procurement scale; Dairy is gaining share fastest through protein-fortified drink expansion.
Form:
Physical state determines handling infrastructure requirements and dissolution kinetics, with liquid systems favored for continuous-process beverage lines and solid forms dominating batch-oriented dairy and bakery operations.
- Liquid:High fructose corn syrup and stevia extract solutions pump directly into bottling line mixing tanks; Rosario-to-Buenos Aires tanker logistics shape regional supply economics.
- Powder:Spray-dried stevia glycosides and maltitol powders serve dairy powder premix operations and sports nutrition dry blend facilities.
- Granular:Crystalline sucrose and erythritol granules flow through standard bakery metering equipment without process modification.
- Syrup:Viscous agave and rice syrup alternatives occupy niche organic positioning in Patagonia craft beverage segments.
Liquid form retains volume leadership; Powder is climbing the fastest through sports nutrition dry-mix demand.
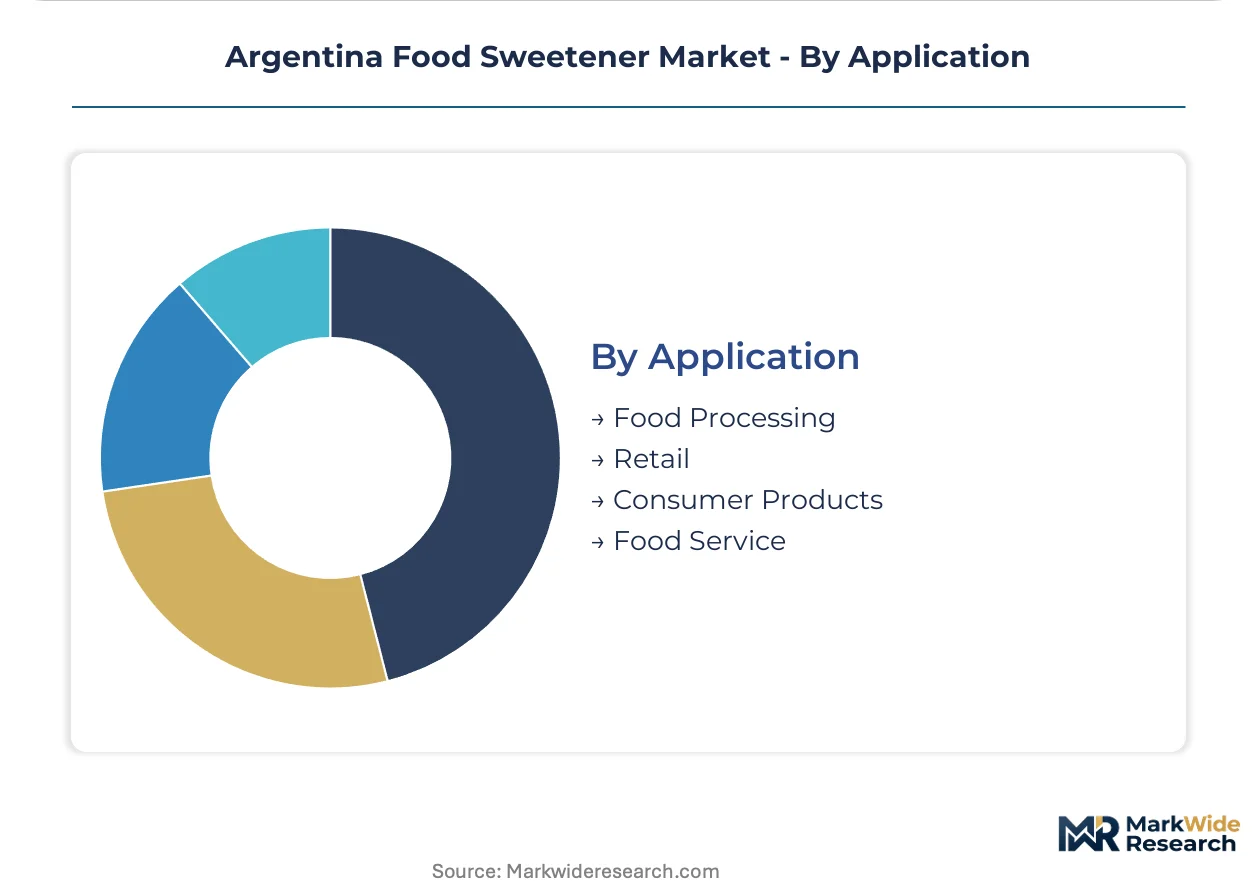
Application:
Channel-specific regulatory exposure and formulation complexity create divergent sweetener specification patterns across industrial processing, retail distribution, and food service deployment.
- Food Processing:Industrial dairy and beverage manufacturers in Buenos Aires province specify customized sweetener blends with certificate-of-analysis documentation tracing agricultural provenance to Misiones cooperatives.
- Retail:Packaged consumer goods face acute ANMAT front-of-pack warning label pressure, driving supermarket chains to delist products containing synthetic sweeteners targeting school-age demographics.
- Food Service:Argentine restaurant and café operators source bulk liquid sweeteners through consolidated distributors with limited clean-label differentiation.
- Consumer Products:Direct-to-consumer tabletop sweetener packets and home baking formulations occupy marginal volume share dominated by imported stevia brands.
Food Processing retains volume leadership; Retail holds the steepest reformulation-driven expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Argentina's sweetener market, with Pampas dairy processors absorbing premium costs for clean-label formulations while Patagonia craft producers remain highly sensitive to input fluctuations.
Buenos Aires Province
Beverage bottlers in Greater Buenos Aires drive bulk procurement of high fructose corn syrup and stevia extracts for carbonated drink portfolios. ANMAT's front-of-pack warning label mandates accelerate displacement of synthetic sweeteners in formulations targeting school-age demographics. Industrial clusters in La Matanza and Tigre concentrate mixing and bottling infrastructure serving domestic retail chains.
Santa Fe Province
Yogurt and flavored milk processors across the Pampas dairy belt demand customized stevia-allulose blends that maintain protein fortification stability without added sugar volume. The province's alignment with MERCOSUR technical standards enables cross-border formulation consistency for exporters shipping to Uruguay and Brazil. Rosario anchors crushing and refining infrastructure linking local corn origination to liquid sweetener supply.
Córdoba Province
Mid-scale beverage manufacturers in Córdoba city are converting production lines to low-calorie formulations, creating sustained pull for monk fruit extracts as clean-label positioning hardens. Provincial regulators enforce additive maximum-use levels that determine which sweetener systems processors may deploy. The city's industrial parks host blending facilities serving central Argentina's retail distribution networks.
Misiones Province
Stevia leaf cultivation concentrates in Misiones' subtropical growing regions, supplying raw material to extract processors facing margin pressure from rainfall-dependent harvest volatility. Agricultural cooperatives negotiate multi-year offtake agreements with Pampas dairy buyers seeking supply security amid currency fluctuations. The province lacks domestic glucosyltransferase production capacity, forcing reliance on imported biotechnology inputs.
Neuquén and Río Negro Provinces
Emerging craft beverage producers across Patagonia seek localized sweetener supply partnerships bypassing consolidated Buenos Aires distribution channels. Underpenetrated market conditions create openings for direct sourcing arrangements with Misiones agricultural cooperatives. Bariloche and Neuquén city host small-scale mixing operations targeting premium organic positioning in regional retail.
Argentina Food Sweetener Market Competitive Environment
Vertically integrated agribusiness conglomerates and specialized ingredient formulators split the market along scale-versus-customization lines. Three archetypes dominate: multinational traders with origination-to-refining footprints, regional blenders with formulation expertise, and agricultural cooperatives with captive leaf supply. Competitive dynamics center on backward integration into raw material sourcing and forward integration into technical formulation services for industrial buyers.
Within the multinational tier, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven positions anchored through grain handling networks and crushing infrastructure. Tate & Lyle PLC occupies a specialization niche in modified starch and sweetener blends. These three entities represent contrasting strategic postures—bulk commodity security versus differentiated formulation capability—shaping how industrial buyers structure procurement relationships across the Pampas dairy belt and Buenos Aires beverage corridors.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc |
| Glucovil Argentina S A |
| Louis Dreyfus Company |
| Argentbio SA |
| Tate & Lyle PLC |
| NutraSweet Company |
| Archer Daniels Midland Company |
| ANAGALIDE SA |
| Cargill Incorporated |
| Others |
Value Chain & Pricing Dynamics
Rosario's crushing and refining infrastructure anchors Argentina's sweetener supply base, with Cargill's corn origination network and Tate & Lyle's specialty formulation capacity concentrating upstream power that translates directly into pricing leverage over Pampas dairy processors and Buenos Aires bottlers.
Pricing Analysis
After-sales formulation services now drive lifetime value capture as industrial buyers lock in multi-year technical support contracts alongside ingredient supply. Three-tier pricing structure across premium certified-organic stevia, standard food-grade extracts, and economy high fructose corn syrup reflects glycoside purity and ANMAT compliance documentation levels. Pricing pressure stems from Misiones harvest volatility forcing processors to absorb agricultural margin swings. Small-scale Patagonia craft producers exhibit highest price sensitivity, while multinational beverage bottlers leverage volume scale for contract stability.
Supply Chain Analysis
Supplier-financing facilities extended by Rosario-based traders to Misiones agricultural cooperatives are stabilizing leaf procurement against currency fluctuations. Raw material flows concentrate in Argentina's corn belt, Brazil's enzyme biotechnology sector, and Paraguay's emerging stevia cultivation zones. Stevia leaf supply, glucosyltransferase enzymes, and allulose feedstock constitute critical input dependencies. Single-source vulnerability in specialty enzyme sourcing from Brazilian suppliers creates structural exposure. Distribution runs through Buenos Aires consolidation hubs serving Pampas dairy processors and Córdoba beverage manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's food sweetener market operates as a regulatory-moat story where ANMAT's novel food approval pathway and front-of-pack labeling mandates create entrenched switching costs that protect incumbent formulation relationships.
For Market Incumbents: Build certification moats by accelerating ANMAT pre-submission consultations for next-generation glycoside extracts ahead of pending Argentine Food Code updates. Deepen backward integration into Misiones agricultural cooperatives through equity stakes that lock in reb-A supply tiers. Counter emerging monk fruit extract entrants by embedding technical service teams within Santa Fe yogurt processor R&D facilities. For New Entrants and Emerging Players: Mid-scale sports nutrition manufacturers in Córdoba represent the most penetrable entry point, as protein-fortified shake formulators seek allulose-erythritol blends outside consolidated Buenos Aires distribution channels. Neuquén craft beverage producers offer white-space partnerships bypassing traditional three-tier supply structures. Lead with direct sourcing arrangements that trace agricultural provenance to specific Misiones cooperatives, satisfying industrial buyer certificate-of-analysis requirements. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because formulation talent scarcity in synergistic sweetener blends and ANMAT regulatory expertise concentrate value in mid-cap regional blenders with captive agricultural relationships. Target acquisition archetypes include Rosario-based processors with in-house extraction capacity and established Pampas dairy customer lock-in. Monitor ANMAT novel food approval timeline compression as the inflection signal indicating regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stevia Cultivation | Equity stakes in Misiones cooperatives transfer price risk from processors to agricultural producers. |
| ANMAT Pre-Submission Consultation Investment | Early regulatory engagement compresses 18-24 month novel food evaluation cycles for competitive launch timing. |
| Technical Service Team Embedding | Resident formulation support at Santa Fe dairy processors deepens customer switching costs. |
| Direct Sourcing Partnership Development | Multi-year offtake agreements with Patagonia craft producers bypass consolidated Buenos Aires distribution channels. |
| Sports Nutrition Application Expansion | Allulose integration into Córdoba protein-fortified shakes opens premium pricing tiers beyond traditional segments. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with food technology directors at Pampas dairy processors, procurement leads at Buenos Aires beverage bottlers, agricultural cooperative managers in Misiones, and ANMAT regulatory affairs specialists. Secondary validation drew from Argentine Food Code submissions, MERCOSUR technical standard harmonization documents, customs trade data on sweetener imports, and SEC filings of multinational ingredient suppliers. Bottom-up volume estimates from individual processor procurement patterns were triangulated against top-down market sizing derived from crushing capacity utilization rates across Santa Fe and Buenos Aires provinces.
Calibration against historical volume trajectories and ANMAT approval timelines anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product chemistry tier, end-use thermal application profile, physical form factor, and channel-specific regulatory exposure. CAGRs were derived through regression analysis of processor procurement growth rates adjusted for reformulation cycle timing. Key forecast inputs incorporated ANMAT pending regulatory update probabilities and Misiones agricultural yield variance projections.
Practitioners should monitor ANMAT novel food pathway backlog expansion and MERCOSUR cross-border formulation standard revision schedules for early signals of regulatory timeline shifts. Forecasts reflect documented assumptions regarding stevia leaf supply stability and industrial buyer clean-label commitment durability. Macroeconomic currency volatility, ANMAT regulatory stringency deviation, or biotechnology enzyme sourcing disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Europe Stevia Market
Sweeteners
Europe B2B Brown Sugar Market
Sweeteners
Dry Sweeteners Market
Sweeteners
Sugar Beet Juice Extract Market
Sweeteners
Caramelized Sugars Market
Sweeteners
D-Mannose Market
Sweeteners
Japan Food Sweetener Market
Sweeteners
Japan Allulose Market
Sweeteners
Vanilla Sugar Market
Sweeteners
Liquid Sugar Market
Sweeteners
Sugar Syrups Market
Sweeteners
Xylitol Injection Market
Sweeteners
Sucrose Esters Market
Sweeteners
Europe Starch Sweetener Market
Sweeteners
Middle East and Africa Sugar Substitutes Market
Sweeteners
Natural Sweeteners Market