
 Saccharin Market | 2026-2036
Saccharin Market Size, Share, and Industry Trends Forecast 2026-2036
Saccharin Market Intelligence
Chinese bulk chemical producers is hardening their grip on upstream saccharin sodium intermediates, tightening feedstock access for smaller downstream blenders. PMC Specialties Group leverages its Ohio-based purification infrastructure to serve North American pharmaceutical contracts with high-grade material. Kaifeng Xinghua Fine Chemical anchors the global supply base through integrated toluene sulfonation capacity in Henan province. Kyung-In Synthetic Corporation competes on pharmaceutical-grade certifications for export into regulated European markets.
Saccharin is a high-intensity, non-nutritive sweetener derived from toluene sulfonation, typically manufactured as sodium or calcium salt with sweetness approximately 300-500 times that of sucrose, and it functions primarily as a zero-calorie sweetening agent in processed foods, beverages, and pharmaceutical coatings. Powder formulations dominate industrial procurement for bulk food manufacturing due to handling efficiency and dosing precision, while liquid saccharin gains share in beverage syrup concentrates where rapid dissolution matters. The pharmaceutical segment sustains premium pricing through United States Pharmacopeia and European Pharmacopoeia compliance requirements that filter out commodity-grade suppliers.
The FDA governs saccharin use in food through 21 CFR 180.37 with residual labeling mandates, while the EPA regulates manufacturing discharge under Clean Water Act permits, and India's FSSAI enforces additive purity ceilings that reshape import eligibility for foreign producers. EFSA's ongoing re-evaluations of intense sweetener toxicology profiles create compliance drift that favors producers with dedicated regulatory affairs functions. Stakeholders must monitor evolving maximum permissible limits in major import jurisdictions to avoid stranded inventory or reformulation costs.
Market Dynamics
Chinese state-owned chemical conglomerates have captured upstream toluene sulfonation capacity, concentrating feedstock access and forcing downstream blenders to accept price volatility or exit the market entirely.
Growth Catalysts
- Diabetes prevalence:Rising diabetic populations in India and Southeast Asia drive pharmaceutical procurement of saccharin for sugar-free formulations. India's FSSAI maintains additive purity standards that favor certified importers.
- REACH compliance:European pharmaceutical manufacturers source saccharin exclusively from suppliers meeting ECHA registration requirements, creating premium demand for documented supply chains.
- Beverage reformulation:Cost-stable sweetener substitution is accelerating among Southeast Asian bottlers facing sucrose price swings.
Market Restraints
- Toluene feedstock volatility:Crude oil price fluctuations transmit directly to saccharin production economics, squeezing margin recovery for non-integrated processors.
- Henan supply concentration:Over half of global sodium saccharin intermediate capacity sits within a single Chinese province, creating single-point-of-failure exposure.
- Natural sweetener substitution:Stevia and monk fruit extracts are capturing clean-label beverage formulations, compressing saccharin's addressable market in premium consumer segments.
Strategic Opportunities
- Pediatric pharmaceutical coatings:Unmet demand exists for USP-grade saccharin in palatable antibiotic formulations across Sub-Saharan African markets.
- Clean Water Act discharge permits:EPA regulatory stringency is creating competitive moats for North American producers with compliant effluent treatment infrastructure.
- Liquid concentrate formats:Rapid-dissolution saccharin solutions for fountain beverage systems represent underexploited channel potential in quick-service restaurant supply chains.
Industry Challenges
- Pharmacopeial certification timelines:USP and EP compliance documentation requires 18-24 month validation cycles, straining working capital for new market entrants.
- Legacy equipment retrofit costs:Toluene sulfonation plants face pressure to install vapor recovery systems under tightening MEE enforcement in China.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saccharin Market |
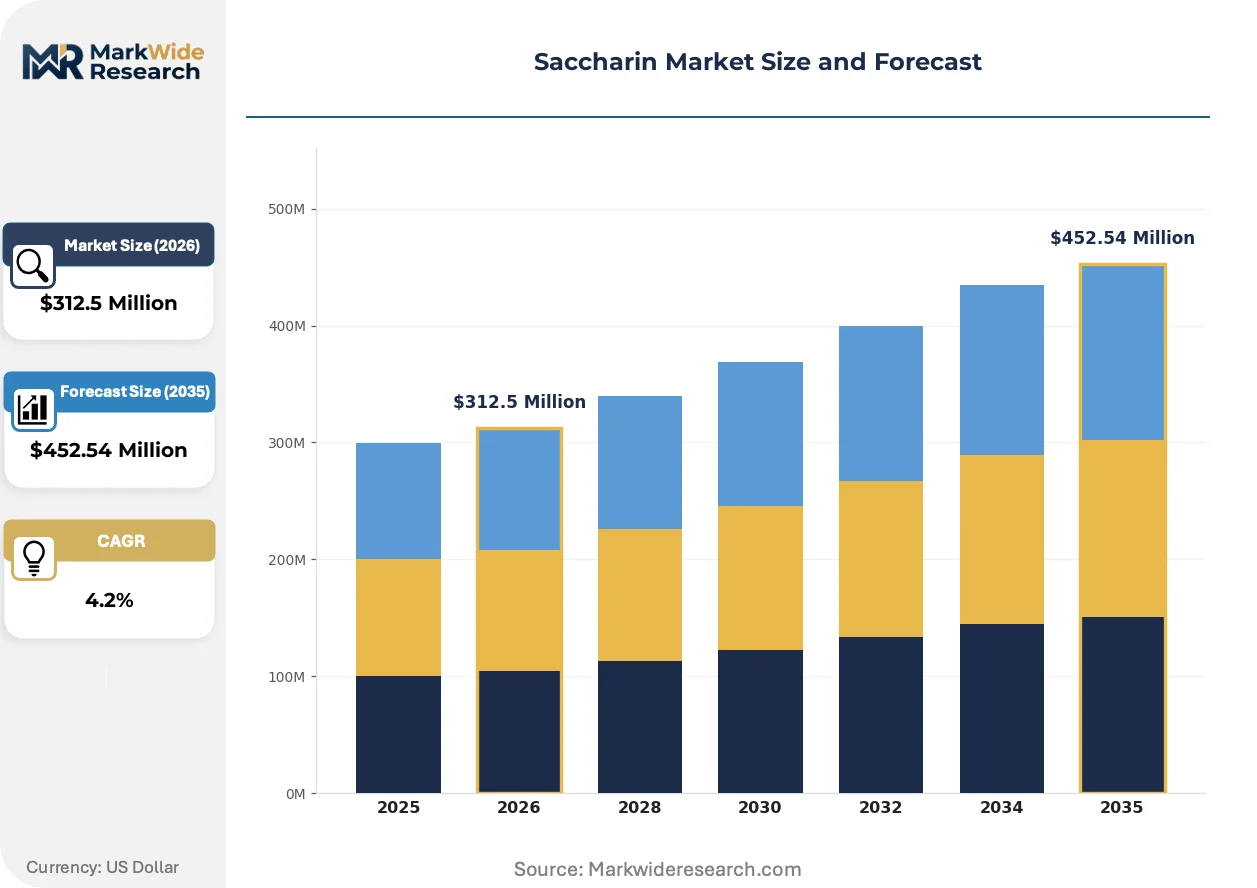
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $452.54 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Powder, Tablet End User: Food Industry, Beverage Industry, Pharmaceutical, Personal Care Distribution Channel: Online, Supermarkets, Wholesale, Specialty Stores Application: Sweetener, Food Preservative, Flavor Enhancer, Dietary Supplements |
| Companies Covered | PMC Specialties Group, Kaifeng Xinghua Fine Chemical, Shanghai Fortune Chemical, Salvi Chemical Industries Ltd., Vishnu Chemicals Ltd., Kyung-In Synthetic Corporation, Henan Kaifeng Pingmei Shenma Xinghua Fine Chemical Co., Ltd., JMC Corporation, PRODUCTOS ADITIVOS, S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saccharin Market Strategic Shifts & Innovations
Continuous processing technology and regulatory data transparency are compressing batch cycle times while expanding the addressable market for certified pharmaceutical-grade material.
Membrane filtration systems are absorbing residual toluene and sulfonation byproducts at the purification stage, enabling pharmaceutical manufacturers to meet tightening USP heavy metals specifications without secondary crystallization steps. European API contract manufacturers are retrofitting Ohio-sourced units into existing sodium saccharin lines. This hardware shift is absorbing capital that previously flowed into geographic expansion, consolidating production footprint rather than fragmenting it.
EFSA's systematic re-evaluation of intense sweetener toxicology profiles is forcing suppliers to maintain living dossiers of genotoxicity and carcinogenicity studies. The agency's 2023 guidance on acceptable daily intake calculations has triggered reformulation reviews across confectionery and tabletop sweetener categories. German and French food law enforcement bodies are now demanding batch-level certificates of analysis that trace back to original toluene sourcing.
Large beverage conglomerates are consolidating sweetener procurement under centralized technical buying teams with direct supplier audit authority, displacing the traditional distributor-mediated model. This concentration of buying power is compressing price negotiation cycles and demanding just-in-time inventory commitments from saccharin sodium producers. The shift is most visible in India, where multinational bottlers have established direct technical relationships with Henan-based manufacturers, bypassing Mumbai trading houses that previously controlled import flows.
Saccharin Market Segmentation
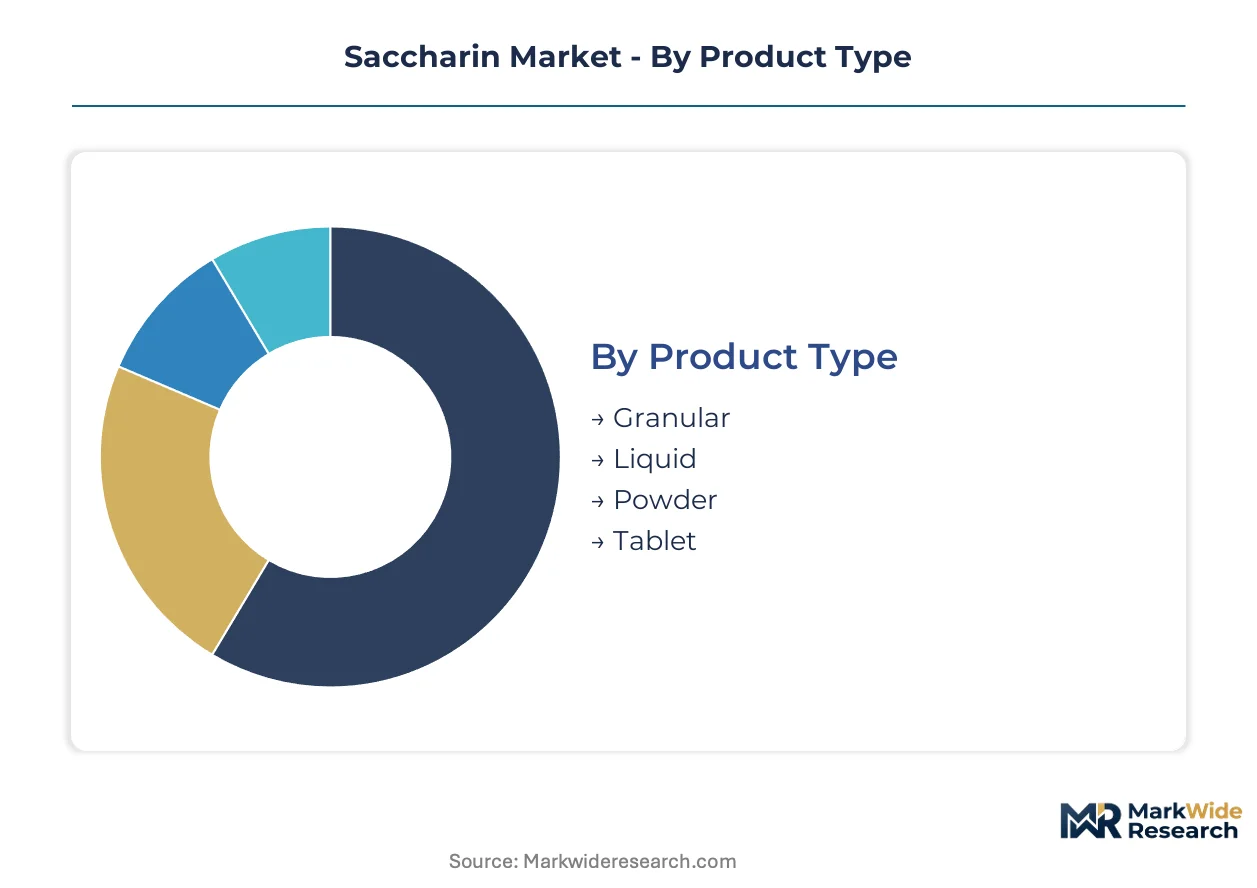
Saccharin's diverse physical forms and end-use specifications create distinct procurement channels with varying purity requirements and pricing tiers. Pharmaceutical-grade material commands certification premiums that commodity food-grade volumes cannot capture.
Product Type:
Physical specification determines handling efficiency, dissolution kinetics, and dosing precision across industrial applications.
- Powder:Fine crystalline sodium saccharin dominates bulk food manufacturing procurement due to metering accuracy in automated blending lines. Henan province processors supply powder grades to Indian beverage bottlers reformulating away from sucrose volatility.
- Liquid:Rapid-dissolution aqueous solutions serve fountain beverage syrup concentrates where homogeneous distribution matters. Southeast Asian quick-service restaurant supply chains are adopting liquid formats for just-in-time fountain system replenishment.
- Granular:Free-flowing agglomerated crystals suit tabletop sweetener packaging with reduced dusting.
- Tablet:Compressed unit-dose formats target pharmaceutical compounding and dietary supplement manufacturing.
Powder leads on scale; liquid leads on momentum.
End User:
Customer type stratifies saccharin procurement by regulatory stringency and certification burden.
- Pharmaceutical:USP and EP compliance mandates filter out commodity-grade suppliers, sustaining premium pricing through documented supply chains. Pediatric antibiotic formulations in Sub-Saharan Africa represent unmet demand for certified palatable coatings.
- Beverage Industry:Cost-stable sweetener substitution accelerates among Southeast Asian bottlers facing raw sugar price swings. Direct technical relationships with Henan manufacturers are displacing Mumbai trading house intermediation.
- Food Industry:Processed food manufacturers procure powder grades for baked goods and confectionery under FSSAI purity ceilings in India.
- Personal Care:Toothpaste and mouthwash formulators utilize saccharin for non-cariogenic sweetness in oral hygiene products.
Beverage Industry leads on scale; Pharmaceutical leads on momentum.
Distribution Channel:
Channel selection reflects buyer scale, technical requirements, and inventory velocity needs.
- Wholesale:Bulk chemical distributors move tonnage quantities to food and beverage manufacturers with established formulation specifications.
- Online:E-procurement platforms serve small-scale compounders and research institutions requiring rapid sample turnaround.
- Supermarkets:Retail tabletop sweetener packaging reaches consumer households through conventional grocery channels.
- Specialty Stores:Pharmacy and health food retailers stock pharmaceutical-grade and dietary supplement formats.
Wholesale leads on scale; online leads on momentum.
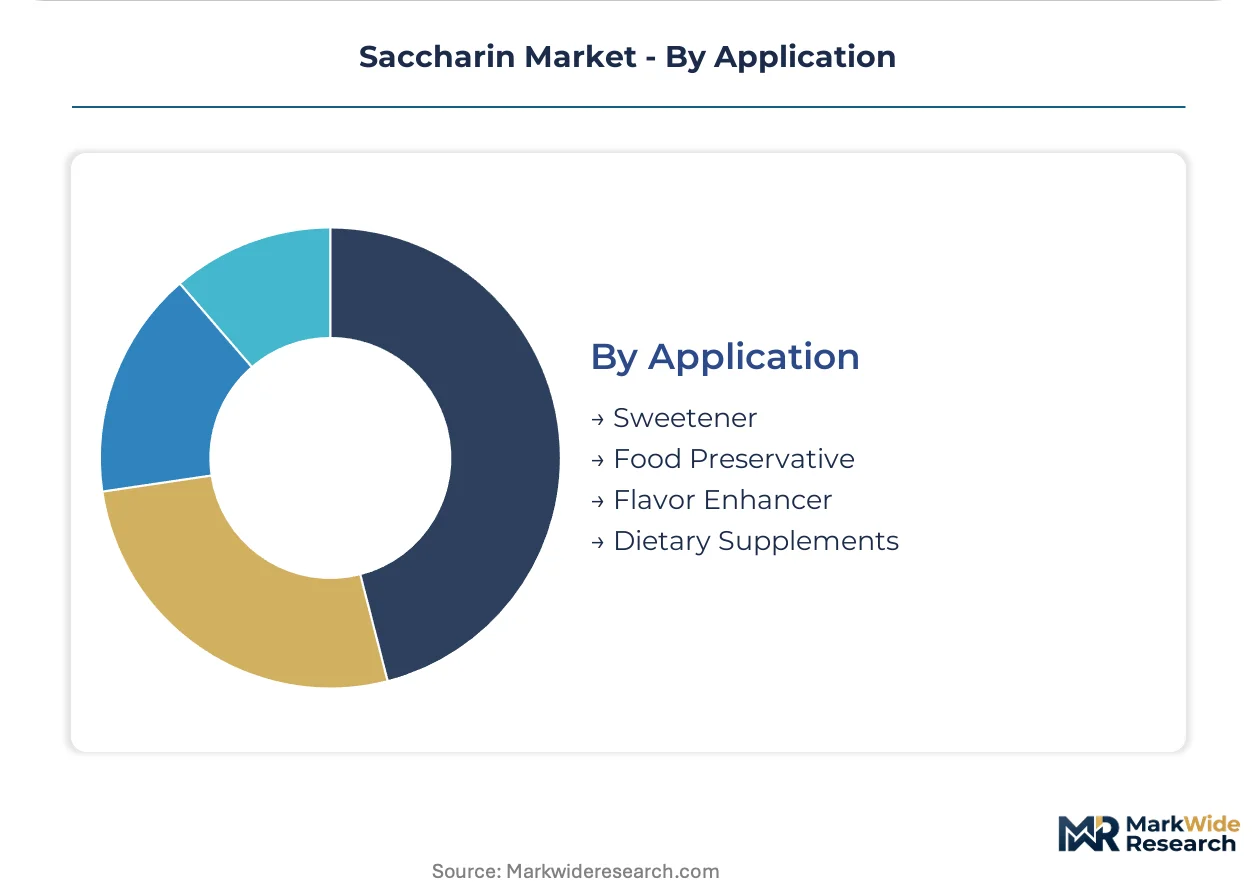
Application:
Functional use case determines purity grade, regulatory pathway, and value capture potential.
- Sweetener:Primary zero-calorie function in processed foods and beverages accounts for volume concentration. EFSA's ongoing ADI recalculations are triggering reformulation reviews across European confectionery categories.
- Flavor Enhancer:Synergistic amplification of other taste modalities supports reduced-sodium savory applications.
- Food Preservative:Microbial inhibition properties extend shelf life in specific formulation contexts.
- Dietary Supplements:Palatability improvement in vitamin and mineral delivery systems serves diabetic and pediatric populations.
Sweetener leads on scale; dietary supplements leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting saccharin procurement toward jurisdictions with lower compliance burdens, even as major import markets harden purity standards. Production capacity migrates toward integrated chemical clusters where feedstock access and environmental enforcement create cost differentials.
China
Henan province concentrates over half of global sodium saccharin intermediate capacity within its toluene sulfonation corridor. The Ministry of Ecology and Environment is tightening vapor recovery mandates, forcing legacy equipment retrofits that favor state-owned chemical conglomerates with capital reserves. Kaifeng's integrated refiners are absorbing smaller processors unable to meet discharge permit upgrades.
India
Diabetic population expansion and beverage reformulation are accelerating pharmaceutical-grade procurement from FSSAI-certified importers. The Food Safety and Standards Authority of India enforces additive purity ceilings that disqualify uncertified foreign suppliers. Mumbai trading houses are losing intermediation power as multinational bottlers establish direct technical relationships with upstream manufacturers.
United States
Pharmaceutical manufacturers are expanding USP-grade saccharin procurement for pediatric and sugar-free diabetic formulations. The FDA governs food use through residual labeling mandates under 21 CFR 180.37, while the EPA's Clean Water Act permit stringency creates competitive moats for domestic producers with compliant effluent infrastructure. Ohio-based purification facilities are capturing North American pharmaceutical contracts.
Germany
European pharmaceutical manufacturers source exclusively from ECHA-registered suppliers meeting REACH documentation requirements. EFSA's systematic re-evaluation of intense sweetener toxicology is forcing living dossier maintenance for genotoxicity and carcinogenicity studies. German food law enforcement now demands batch-level certificates tracing to original toluene sourcing.
Brazil
Beverage bottlers facing sucrose price volatility are accelerating cost-stable sweetener substitution in processed food formulations. ANVISA's pharmaceutical regulator maintains import eligibility standards that reshape procurement toward documented supply chains. São Paulo's industrial food corridor is absorbing regional blending capacity as Southeast Asian suppliers seek Latin American market access.
Saccharin Market Key Industry Players
Chinese producers anchor the upstream intermediate tier; North American and European specialists hold pharmaceutical-grade purification and certification capabilities. The vendor base stratifies across three functional layers: integrated toluene sulfonators with captive feedstock, regional blenders serving commodity food-grade demand, and pharmacopeia-compliant refiners capturing premium pharmaceutical contracts. Two dominant competitive moves are reshaping positioning: backward integration into toluene supply chains and geographic consolidation of purification assets under single-site regulatory compliance.
Among Chinese integrated producers, Kaifeng Xinghua Fine Chemical and Henan Kaifeng Pingmei Shenma Xinghua Fine Chemical Co., Ltd. exemplify the upstream concentration archetype, occupying positions within the Henan province chemical corridor where toluene sulfonation capacity and environmental permit access create structural barriers. PMC Specialties Group represents the North American premium-tier vector, anchoring pharmaceutical-grade supply through Ohio-based infrastructure. Kyung-In Synthetic Corporation sits within the export-specialist tier, serving regulated European markets through documented supply chain compliance.
| Leading Market Players |
|---|
| PMC Specialties Group |
| Kaifeng Xinghua Fine Chemical |
| Shanghai Fortune Chemical |
| Salvi Chemical Industries Ltd. |
| Vishnu Chemicals Ltd. |
| Kyung-In Synthetic Corporation |
| Henan Kaifeng Pingmei Shenma Xinghua Fine Chemical Co., Ltd. |
| JMC Corporation |
| PRODUCTOS ADITIVOS, S.A. |
| Others |
Cost & Logistics Intelligence
Captive toluene sulfonation capacity within Chinese state-owned chemical conglomerates anchors both upstream supply security and downstream pricing leverage, compressing margin recovery for non-integrated processors while amplifying volatility transmission from crude oil feedstock markets.
Pricing Analysis
Distributor margin compression in Mumbai trading houses is accelerating direct technical relationships between multinational bottlers and Henan-based manufacturers. Three-tier pricing structure across USP-grade pharmaceutical, food-grade certified, and commodity industrial tiers reflects certification burden and documentation depth. Cost compression in commodity powder grades is intensifying because natural sweetener substitution in clean-label segments is eroding volume base. Beverage bottlers exhibit highest price sensitivity due to reformulation frequency, while pharmaceutical manufacturers accept premium positioning for documented supply chains.
Supply Chain Analysis
Refurbishment flows for legacy toluene sulfonation equipment are absorbing capital that previously expanded geographic footprint, consolidating production within Henan province rather than fragmenting capacity. Supply concentrates in China, India, and the United States, with toluene feedstock, sulfonation catalysts, and membrane filtration systems as critical inputs. Single-source vulnerability in Henan province creates single-point-of-failure exposure for global sodium saccharin intermediate supply. Distribution runs through wholesale chemical distributors serving tonnage food manufacturers, with e-procurement platforms gaining share among small-scale compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EPA discharge permit stringency in North America creates competitive moats for compliant domestic producers against lower-cost but environmentally constrained Chinese supply.
For Market Incumbents: Lock in pharmacopeial certification maintenance through dedicated regulatory affairs functions as EFSA's systematic re-evaluation of intense sweetener toxicology accelerates compliance drift. Secure captive toluene supply agreements or backward integration into sulfonation capacity to defend against feedstock volatility squeezing non-integrated processors. Prioritize Ohio-based purification infrastructure investment for North American pharmaceutical contract capture. For New Entrants and Emerging Players: Begin with liquid concentrate format specialization for Southeast Asian quick-service restaurant supply chains, where rapid-dissolution requirements and just-in-time replenishment create white-space opportunity absent from commodity powder competition. Target Sub-Saharan African pediatric pharmaceutical coatings as the most penetrable segment, leveraging USP-grade certification gaps in regional antibiotic formulation supply. Deploy direct technical sales teams to bypass entrenched Mumbai trading house intermediation. For Investors and Strategic Acquirers: Consolidation pressure builds where pharmacopeial compliance documentation requires 18-24 month validation cycles, straining working capital for sub-scale operators and forcing exit to well-capitalized buyers. Long-term viability favors integrated producers with captive toluene sulfonation and environmental permit access across the analysis window. Monitor EFSA acceptable daily intake recalculation announcements as inflection indicators triggering reformulation demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Toluene Sulfonation | Captive feedstock access insulates margin recovery from crude oil volatility transmission. |
| Pharmacopeial Certification Investment | USP and EP compliance documentation filters out commodity-grade competitors in pharmaceutical supply. |
| Membrane Filtration Technology Deployment | Ohio-sourced units enable heavy metals specification compliance without secondary crystallization steps. |
| Liquid Concentrate Format Development | Rapid-dissolution solutions penetrate quick-service restaurant fountain system replenishment channels. |
| Direct Technical Relationship Establishment | Bypassing Mumbai trading houses captures margin from multinational beverage bottler procurement consolidation. |
Research Approach
Bottom-up beverage and pharmaceutical procurement modeling reconciled against top-down toluene sulfonation capacity tracking forms the analytical core. Primary interviews with plant managers at Henan province chemical processors, procurement leads at Indian beverage bottlers, regulatory affairs directors at European API contract manufacturers, and technical buying teams at multinational food conglomerates combined with secondary validation from customs and trade data, FSSAI additive purity filings, EFSA toxicology re-evaluation dossiers, and SEC 10-K disclosures from listed chemical producers. Triangulation across supply-side capacity announcements and demand-side procurement patterns ensures statistical integrity.
Input-output matrices map toluene feedstock cost transmission through sulfonation, purification, and formulation stages across the projection horizon. Segmentation dimensions include physical form specification, end-use regulatory tier, geographic production hub, and distribution channel type. CAGRs derive from volume-weighted average growth across modeled segments, with industry-specific inputs capturing diabetic population expansion rates in India and Southeast Asia, beverage reformulation frequency tied to sucrose price volatility, and EFSA acceptable daily intake recalculation timelines.
Several conditions sit outside the modeled scope, including abrupt MEE enforcement escalations in China, natural sweetener technology breakthroughs collapsing clean-label substitution economics, and geopolitical trade restriction implementations. Forecasts reflect assumptions around regulatory stability and feedstock cost transmission elasticity. Practitioners should monitor EFSA genotoxicity study releases, NMPA food additive purity standard revisions, and crude oil price volatility spikes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Asia Pacific Food Sweetener Market
Sweeteners
Beetroot Molasses Market
Sweeteners
Asia-Pacific Starch Sweetener Market
Sweeteners
North America Plant-Derived and Synthetic Sugar Market
Sweeteners
Brown Rice Syrup Market
Sweeteners
Maltitol Market
Sweeteners
United Kingdom Food Sweetener Market
Sweeteners
Brazil Food Sweetener Market
Sweeteners
Sugar Free Lifesavers Market
Sweeteners
Natural Malt Sweeteners Market
Sweeteners
Japan Allulose Market
Sweeteners
Indonesia Food Sweetener Market
Sweeteners
Europe Natural Sweetener Market
Sweeteners
Coconut Sugar Market
Sweeteners
Global Stevia Sugar Blends Market
Sweeteners
Europe Sugar Substitute Market