
 Erythritol Market | 2026-2036
Erythritol Market Size, Share, and Industry Trends Forecast 2026-2036
Erythritol Market Analysis
EU F-Gas Regulation is hardening compliance costs for synthetic erythritol producers reliant on petrochemical feedstocks. Cargill leverages its corn-based fermentation infrastructure across North American biorefineries to sustain cost advantages in natural erythritol supply. Zhucheng Dongxiao Biotechnology anchors China's export pipeline through integrated glucose-to-erythritol fermentation at scale. Tate & Lyle differentiates via specialty blend formulations targeting bakery and confectionery technical specifications.
Erythritol is a four-carbon sugar alcohol produced through microbial fermentation of glucose or hydrogenation of carbohydrates, delivering approximately 70% of sucrose sweetness with negligible caloric content and zero glycemic impact. Its primary commercial purpose centers on bulk sugar replacement in reduced-calorie and diabetic-friendly food systems where crystallization behavior and cooling effect match technical requirements. Natural erythritol commands premium positioning in health food brands and clean-label portfolios, while powdered erythritol dominates bakery applications due to its fine particle distribution and hygroscopic stability. Blends integrating erythritol with high-intensity sweeteners represent the fastest-expanding application segment as beverage companies pursue optimized sweetness temporal profiles.
FDA nutrition labeling mandates and the EU's added-sugar disclosure requirements are reshaping formulation procurement across North American and European food manufacturers. China's SAMR enforces GB standards for sugar alcohol purity and labeling that govern export eligibility from Shandong and Hebei production bases. Stakeholders must monitor fermentation yield improvements and regulatory divergence between jurisdictions to calibrate capacity allocation and certification investments.
Market Dynamics
Fermentation yield improvements and regulatory divergence between jurisdictions are compressing margins for synthetic producers while rewarding integrated biorefinery operators with captive glucose supply.
Growth Catalysts
- EU F-Gas Regulation:Synthetic erythritol producers face escalating compliance costs, redirecting procurement toward fermentation-derived alternatives. Natural erythritol gains shelf space in European clean-label portfolios.
- Beverage reformulation:Carbonated and functional drink manufacturers across North America pursue sugar reduction targets. Erythritol blends with high-intensity sweeteners optimize sweetness temporal profiles.
- China:Domestic fermentation capacity expansion in Shandong and Hebei provinces anchors export-oriented production clusters. SAMR GB standards govern purity and labeling eligibility.
Market Restraints
- Feedstock concentration:Corn glucose supply volatility affects North American fermentation economics. Drought cycles in Midwest growing regions transmit directly to input costs.
- Cooling effect limitation:Erythritol's endothermic dissolution restricts applications in warm beverages and certain confectionery formats where thermal profile matters.
- Allulose substitution:This rare sugar delivers comparable bulk with superior browning and freezing point depression. Bakery and ice cream formulators increasingly split trials between the two.
Strategic Opportunities
- India:FSSAI sugar reduction mandates and diabetic population expansion create formulation pull. Domestic production capacity remains underdeveloped versus import demand.
- Cell-cultured meat:Growth media formulation requires low-glycemic carbon sources. Erythritol serves as a non-metabolizable osmolyte in bioreactor environments.
- Japan:METI's functional food labeling system rewards substantiated glycemic claims. Erythritol's zero-GI positioning aligns with FOSHU and Foods with Function Claims frameworks.
Industry Challenges
- Fermentation scale-up:Industrial microbiology talent scarcity constrains yield optimization programs. Yeast strain engineering and process control expertise command premium compensation.
- Multi-jurisdiction certification:simultaneous FDA GRAS maintenance, EFSA novel food dossiers, and SAMR export registration create timeline compression. Documentation requirements diverge on purity thresholds and analytical methods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Erythritol Market |
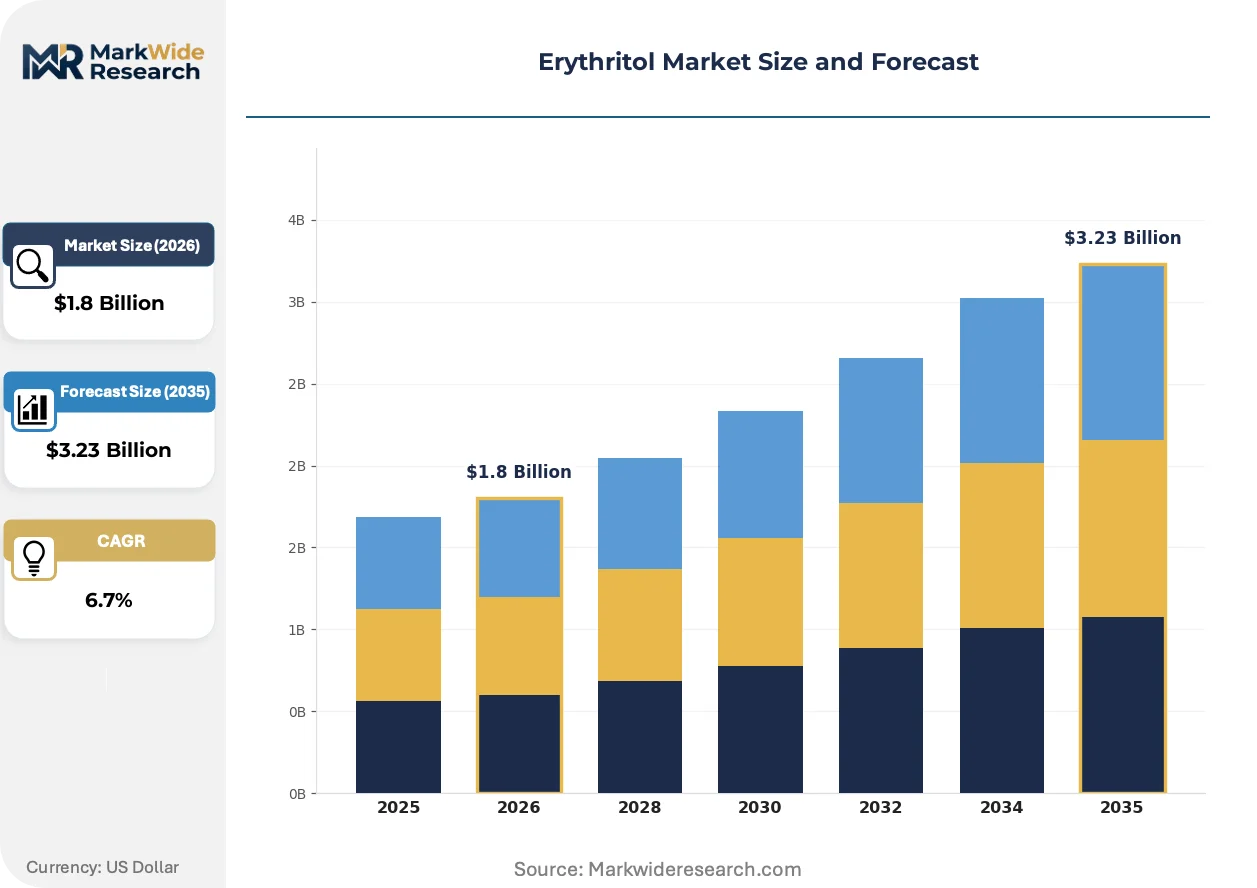
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Erythritol, Synthetic Erythritol, Blends, Powdered Erythritol Application: Beverages, Bakery Products, Confectionery, Dairy Products End User: Food Manufacturers, Beverage Companies, Health Food Brands, Retail Consumers Packaging Type: Bags, Containers, Boxes, Pouches |
| Companies Covered | Archer Daniels Midland (ADM), Zhucheng Dongxiao Biotechnology, Cargill, Foodchem International Corporation, Baolingbao Biology, Tate & Lyle, Shandong Sanyuan Biotechnology, Nikken Chemical, Jungbunzlauer Suisse AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Erythritol Market Emerging Trajectories
Bioprocess intensification and regulatory disclosure mandates are rewriting competitive requirements across erythritol supply chains. Technical differentiation now hinges on fermentation efficiency and certification breadth.
Continuous fermentation systems with cell retention technology are overtaking batch processes in new capacity installations. Large-scale biorefinery operators in China and North America adopt perfusion configurations to boost volumetric productivity. This hardware transition is compressing capital requirements per ton of annual output and widening the efficiency gap between integrated and merchant producers.
REACH registration deadlines for imported sugar alcohols are tightening documentary requirements for European market access. ECHA substance evaluation protocols now demand extended toxicity datasets beyond baseline food safety approvals. Specialty blenders and pure-play suppliers alike must expand regulatory affairs staffing to maintain formulation eligibility.
Beverage procurement teams now specify certified low-carbon fermentation origins in RFP documentation. Clean-label positioning extends beyond ingredient lists to encompass supply chain transparency and Scope 3 emissions disclosure. This specification shift is most visible in Nordic markets where retailer sustainability scorecards influence listing decisions.
Erythritol Market Segmentation
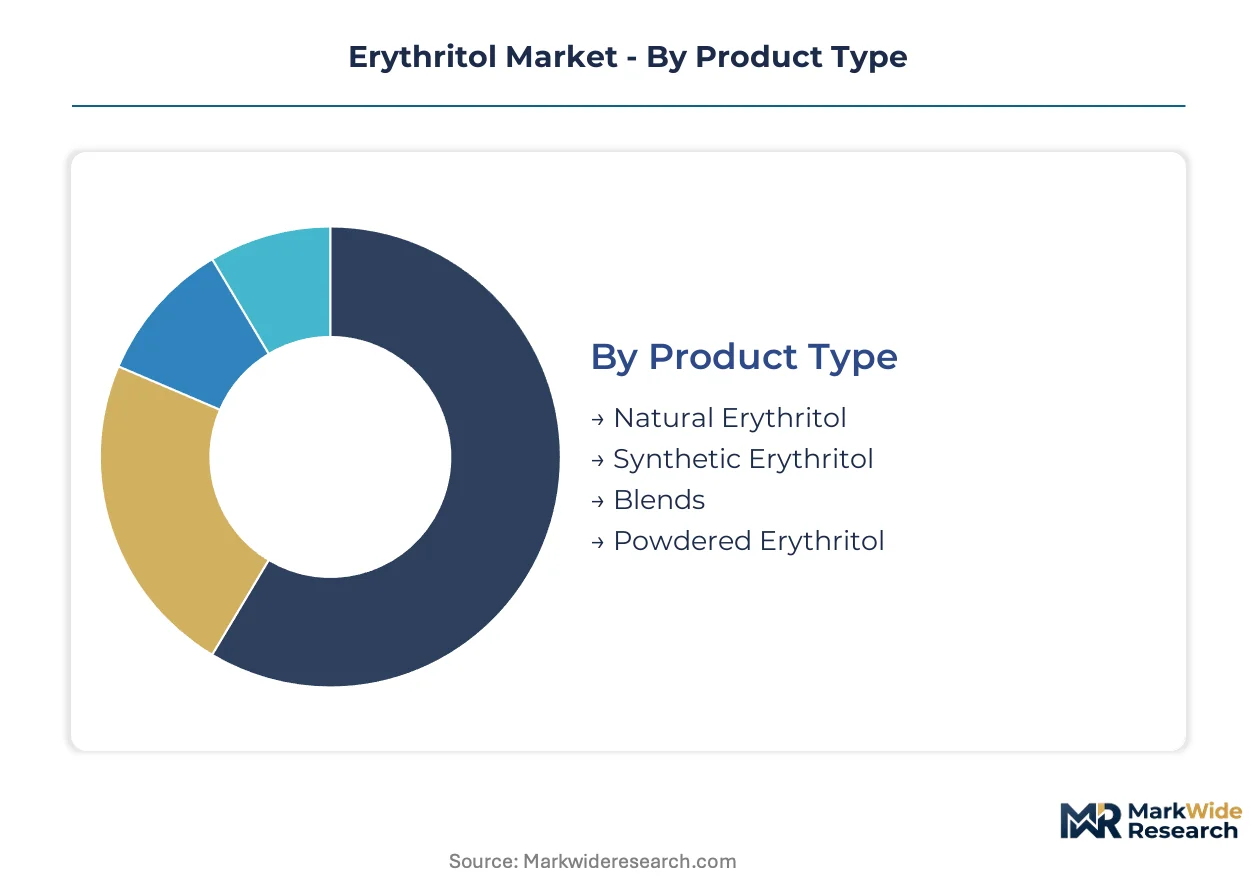
Erythritol procurement teams segment supply by fermentation origin and physical form to match clean-label positioning with technical performance requirements. Formulation specifications vary sharply across beverage carbonation systems, bakery crystallization behavior, and confectionery thermal profiles.
Product Type:
Reformulation cycles in North American and European beverage portfolios are accelerating replacement of synthetic origins with fermentation-derived alternatives.
- Natural Erythritol:Microbial fermentation of corn or wheat-derived glucose yields crystalline powder with certified non-GMO and organic eligibility. European clean-label portfolios and US natural health food brands specify this grade exclusively, with procurement teams auditing fermentation facility carbon intensity.
- Synthetic Erythritol:Petrochemical hydrogenation of carbohydrate substrates produces chemically identical molecules at lower unit cost. EU F-Gas Regulation compliance costs and REACH documentation burdens are compressing margins for merchant producers serving European industrial buyers.
- Blends:Erythritol-stevia and erythritol-monk fruit combinations optimize sweetness temporal profiles in reduced-sugar beverages. Tate & Lyle and Cargill dominate proprietary blend formulations targeting specific beverage technical specifications.
- Powdered Erythritol:Fine particle distribution below 100 microns delivers hygroscopic stability for bakery dry mixes and confectionery dusting applications. Particle size engineering commands premium positioning in artisan baking supply channels.
Volume placements concentrate in Natural Erythritol; the faster expansion belongs to Blends.
Application:
Cost tier differentiation separates mass-market beverage reformulation from premium confectionery technical specifications.
- Beverages:Carbonated soft drinks, functional waters, and ready-to-drink teas specify erythritol for bulk sugar replacement without glycemic impact. Cooling effect limitations restrict concentrations in warm-fill applications, driving blend formulations with high-intensity sweeteners.
- Bakery Products:Cookies, cakes, and pastry applications exploit erythritol's crystallization behavior and moisture retention. Allulose substitution trials are splitting procurement budgets as formulators test superior browning performance in premium cookie lines.
- Confectionery:Hard candies, chewing gums, and chocolate coatings leverage cooling effect as a sensory attribute. Shandong and Hebei export clusters supply bulk crystalline grades to European confectionery manufacturers under SAMR GB standard certification.
- Dairy Products:Ice cream and yogurt applications require freezing point depression control where erythritol's colligative properties limit scoopability at high inclusion rates. Premium dairy alternatives in Nordic markets specify low-carbon fermentation origins.
Reformulation budgets concentrate in Beverages; Confectionery is climbing the fastest on clean-label premiumization.
End User:
Customer type determines specification stringency, from retail private-label flexibility to pharmaceutical-grade documentation.
- Food Manufacturers:Industrial bakeries and snack producers specify bulk crystalline or powdered grades with consistent particle size distribution. FDA GRAS maintenance and multi-jurisdiction certification requirements drive supplier consolidation toward integrated biorefinery operators.
- Beverage Companies:Carbonated and functional drink formulators prioritize sweetness temporal profile optimization through erythritol-high-intensity sweetener blends. Procurement RFPs increasingly specify Scope 3 emissions disclosure and certified low-carbon fermentation origins.
- Health Food Brands:Clean-label positioning demands non-GMO, organic, and natural fermentation certifications with full supply chain transparency. Premium pricing tolerance supports smaller batch sizes and specialized packaging formats.
- Retail Consumers:Direct-to-consumer channels move packaged crystalline and powdered erythritol through e-commerce and specialty grocers. Packaging size and convenience features drive purchase decisions in this price-sensitive segment.
Procurement volume concentrates in Food Manufacturers; Health Food Brands are gaining share fastest on clean-label premium expansion.
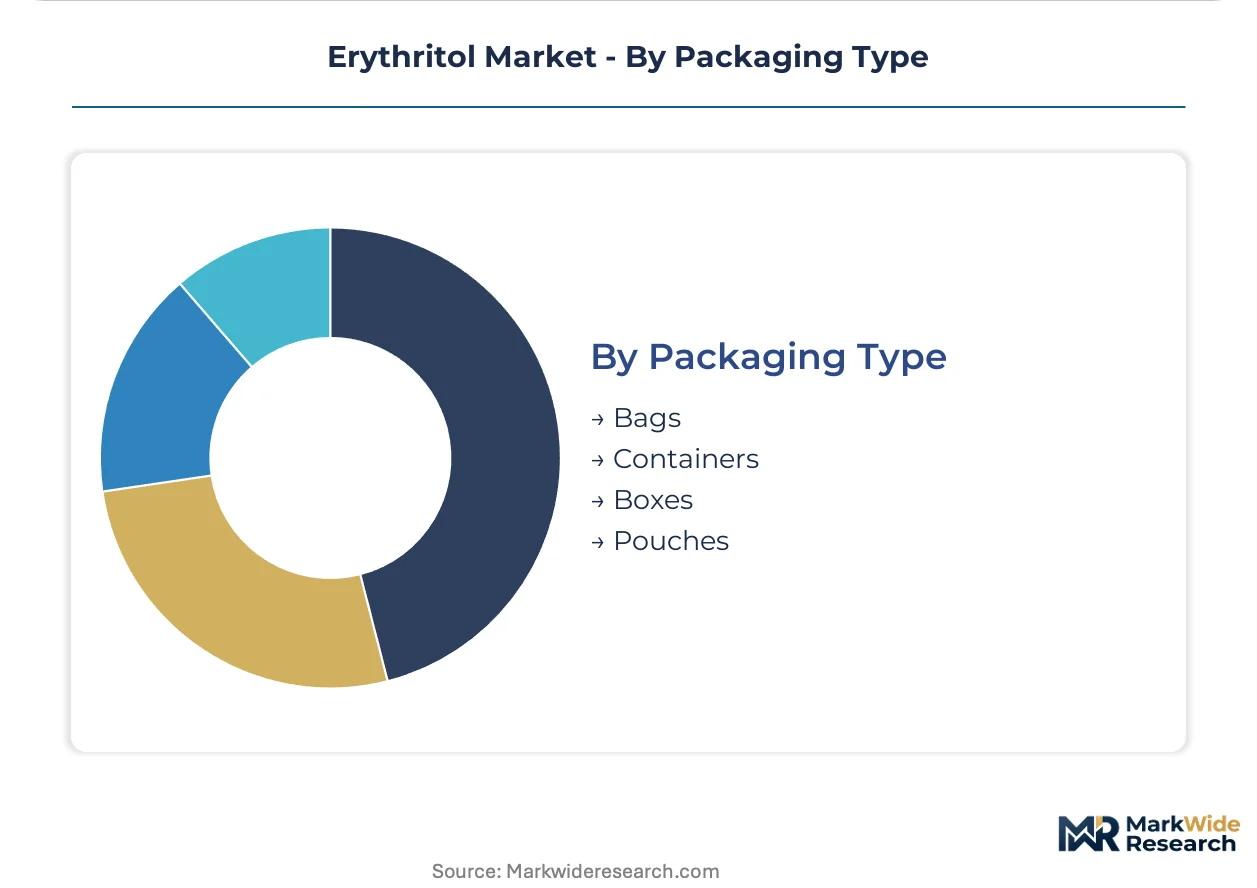
Packaging Type:
Supply chain configuration and distribution channel requirements dictate format selection from bulk industrial to retail-ready units.
- Bags:Multi-wall paper or woven polypropylene sacks deliver 25-50kg bulk shipments to industrial food manufacturers. Moisture barrier specifications vary by climate exposure during Atlantic and Pacific transit routes.
- Containers:Rigid plastic or fiber drums provide intermediate bulk handling for confectionery and dairy processing facilities. UN certification requirements govern hazardous material classifications in maritime shipping.
- Boxes:Corrugated retail cases organize consumer-sized pouches and canisters for warehouse club and grocery distribution. Shelf-ready packaging designs reduce stocking labor for retail partners.
- Pouches:Flexible stand-up and flat pouches with resealable closures dominate health food brand positioning and direct-to-consumer channels. High-barrier metallized films extend shelf stability in humid storage environments.
Industrial throughput concentrates in Bags; Pouches are expanding most quickly on e-commerce channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province's fermentation industrial parks concentrate erythritol capacity through integrated glucose supply chains and export-oriented processing zones. FDA GRAS certifications and EFSA novel food dossiers govern market eligibility across consuming regions.
United States
Beverage reformulation programs at carbonated and functional drink manufacturers drive procurement volumes. FDA updated nutrition labeling mandates require added-sugar disclosure, compressing formulation timelines. Corn Belt biorefineries in Iowa and Illinois anchor fermentation feedstock supply for domestic natural erythritol production.
China
Shandong and Hebei provinces host export-oriented fermentation clusters with integrated glucose-to-erythritol processing. SAMR GB standards govern purity thresholds and labeling eligibility for international shipment. Zhucheng and Weifang industrial zones expand bioreactor capacity to serve European and North American beverage procurement.
Germany
EU F-Gas Regulation compliance costs redirect industrial buyers from synthetic toward fermentation-derived alternatives. ECHA REACH registration deadlines tighten documentary requirements for sugar alcohol imports. North Rhine-Westphalia's food ingredient distributors consolidate procurement toward certified low-carbon fermentation origins.
India
FSSAI sugar reduction mandates and diabetic population expansion create formulation demand in bakery and confectionery segments. Domestic fermentation capacity remains underdeveloped versus import requirements. Maharashtra and Gujarat food manufacturers trial erythritol-allulose blends in premium cookie and ice cream lines.
Japan
METI's functional food labeling system rewards substantiated glycemic claims through FOSHU and Foods with Function Claims frameworks. Erythritol's zero-GI positioning aligns with substantiation requirements for reduced-calorie product positioning. Kanto region beverage and dairy manufacturers specify fermentation-origin certification in supplier qualification.
Erythritol Market Vendor Landscape
Chinese producers anchor one tier; North American and European specialists hold formulation and blend technology positions. The vendor base distributes across integrated fermentation operators, merchant ingredient suppliers, and proprietary blend developers. Strategic archetypes include captive biorefinery operators with upstream glucose control, specialty blend formulators targeting beverage technical specifications, and export-oriented fermentation scale players. Competitive moves concentrate on fermentation yield optimization and multi-jurisdiction certification expansion.
Among integrated biorefinery operators, Cargill and Archer Daniels Midland represent North American fermentation infrastructure archetypes with captive corn glucose supply. Zhucheng Dongxiao Biotechnology occupies a position within Chinese export-oriented capacity expansion. Tate & Lyle exemplifies specialty blend formulation positioning targeting beverage and confectionery technical specifications. These anchors illustrate geographic and capability segmentation across natural supply, synthetic transition, and value-added formulation tiers.
| Leading Market Players |
|---|
| Archer Daniels Midland (ADM) |
| Zhucheng Dongxiao Biotechnology |
| Cargill |
| Foodchem International Corporation |
| Baolingbao Biology |
| Tate & Lyle |
| Shandong Sanyuan Biotechnology |
| Nikken Chemical |
| Jungbunzlauer Suisse AG |
| Others |
Supply Flow & Price Mechanics
Beverage procurement teams specifying certified low-carbon fermentation origins in RFP documentation are compressing pricing power for synthetic producers while rewarding integrated biorefinery operators with captive glucose supply and documented carbon intensity audits. This specification shift forces supply chain reconfiguration toward Shandong and Hebei export clusters with verified fermentation infrastructure.
Pricing Analysis
Short lead-time premiums attach to certified natural erythritol grades with expedited FDA GRAS documentation and EFSA novel food dossier completion. Three-tier pricing structure across premium natural fermentation, standard synthetic hydrogenation, and economy unverified bulk separates procurement budgets by certification stringency. Cost compression in synthetic tiers stems from EU F-Gas Regulation compliance burdens and REACH registration documentary requirements. Health food brands exhibit lowest price sensitivity due to clean-label positioning tolerance, while industrial food manufacturers negotiate aggressively on volume contracts.
Supply Chain Analysis
Reverse-logistics flows for fermentation-derived erythritol center on reprocessing off-spec crystalline batches into powdered grades for bakery applications. Supply concentrates in China, the United States, and Germany, with corn glucose feedstock drawing from Midwest growing regions and Shandong industrial zones. Single-source vulnerability attaches to EU import dependency on Chinese fermentation capacity for natural grades. Distribution runs through bulk bag shipments to industrial food manufacturers and flexible pouches for health food brand channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as multi-jurisdiction certification requirements and fermentation yield optimization demands force smaller merchant producers toward exit or acquisition. Regulatory divergence between FDA, EFSA, and SAMR standards compresses timelines for undercapitalized players.
For Market Incumbents: Anchor fermentation yield advantages through continuous bioreactor technology adoption and cell retention engineering investments. Defend against allulose substitution threats by locking long-term beverage formulation partnerships with proprietary erythritol-stevia blend specifications. Prioritize backward integration into corn glucose supply through Midwest biorefinery capacity control.
For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and broader European markets opens a window for fermentation-origin erythritol specialists with certified low-carbon production. Target India's underdeveloped domestic capacity versus FSSAI sugar reduction mandate pull. Pursue cell-cultured meat growth media applications as a technical differentiation angle with lower certification barriers than food-grade supply.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated biorefinery operators given beverage procurement's Scope 3 emissions disclosure requirements and clean-label premium expansion. Long-term viability favors captive glucose supply with multi-jurisdiction certification breadth. Monitor SAMR export registration timeline compression for early signals of Chinese capacity rationalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Scale-Up | Perfusion bioreactor adoption in Shandong industrial parks compresses capital per ton output. |
| Multi-Jurisdiction Certification Investment | Simultaneous FDA GRAS maintenance and EFSA novel food dossiers secure European beverage eligibility. |
| Proprietary Blend Formulation Development | Erythritol-stevia combinations optimize sweetness temporal profiles for carbonated drink reformulation. |
| Low-Carbon Fermentation Origin Verification | Scope 3 emissions documentation satisfies Nordic retailer sustainability scorecard requirements. |
| Cell-Cultured Meat Growth Media Supply | Non-metabolizable osmolyte applications in bioreactor environments diversify revenue beyond food-grade. |
Methodological Framework
Trade databases, fermentation industry association filings, and regulatory submission records formed the secondary backbone for supply-side capacity and certification mapping. Primary interviews with bioprocess engineering directors, beverage procurement leads, and food ingredient distribution channel heads combined with secondary validation through bottom-up and top-down triangulation. SAMR GB standard documentation, ECHA REACH registration filings, and FDA GRAS notification databases anchored quantitative supply estimates.
Bottom-up volume modeling aggregated fermentation capacity by production cluster and yield assumptions, while top-down demand calibration cross-referenced beverage reformulation program announcements and sugar reduction mandate timelines. Segmentation dimensions included fermentation origin grade, physical form specification, application technical requirements, and end-user certification stringency. CAGRs derived from elasticity-adjusted demand projections and capacity expansion announcements across the analysis window. Forecast inputs incorporated corn glucose price volatility assumptions and EU F-Gas Regulation compliance cost trajectories.
The model assumes a particular technology adoption path for continuous fermentation systems; alternative pathways for batch process yield breakthroughs would alter the outlook for synthetic producer competitiveness. Forecasts reflect assumptions on regulatory timeline adherence and feedstock supply stability. Practitioners should monitor SAMR export registration processing delays and Midwest drought cycle severity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
North America Low-Calorie Sweeteners Market
Sweeteners
Africa Stevia Market
Sweeteners
Sucrose Acetate Isobutyrate Market
Sweeteners
Global Brown Sugar Market
Sweeteners
Egypt Food Sweetener Market
Sweeteners
Saudi Arabia Allulose Market
Sweeteners
China Allulose Market
Sweeteners
Beetroot Molasses Market
Sweeteners
Xylose Market
Sweeteners
Maltol and Ethyl Maltol Market
Sweeteners
Glucose-Fructose Syrup (GFS) Market
Sweeteners
Food Sweetener Market
Sweeteners
Brazil Food Sweetener Market
Sweeteners
United States Xylitol Market
Sweeteners
Sugar Alcohol Market