
 Plant-Derived Sweetener Market | 2026-2036
Plant-Derived Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Derived Sweetener Market Insights
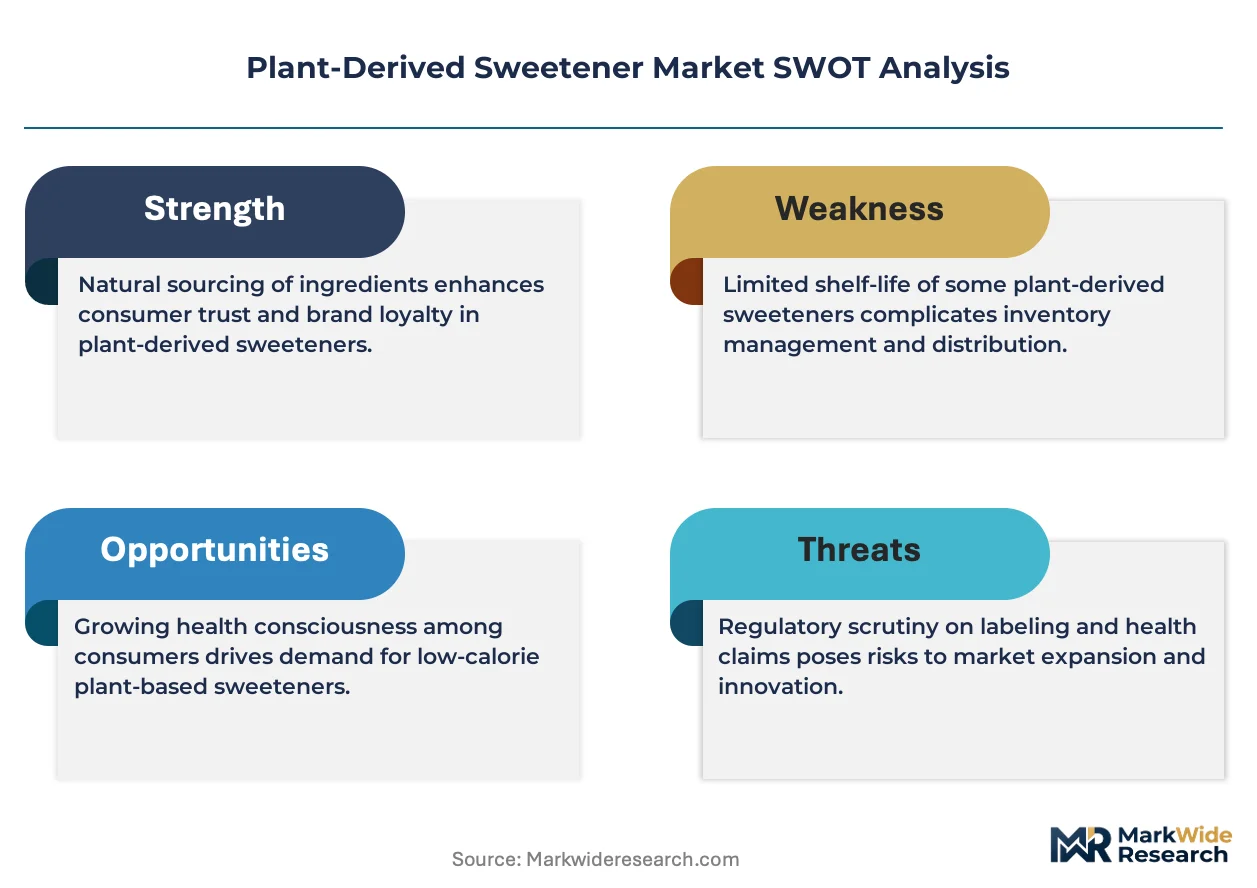
Foodservice distribution is rewriting procurement patterns for plant-derived sweeteners as beverage chains and institutional kitchens demand bulk-format, label-friendly alternatives. Cargill Incorporated leverages its vertically integrated stevia supply from South American cultivation through extraction to secure contract stability with multinational beverage clients. PureCircle Limited anchors its position through proprietary bioconversion technology that enhances Reb M yields from leaf biomass. Roquette Frères competes via its European tapioca-derived erythritol operations, sustaining supply security amid raw material volatility.
Plant-derived sweeteners encompass high-intensity glycosides, polyols, and syrups extracted or refined from botanical sources, typically achieving 50-400 times the sweetness intensity of sucrose with minimal caloric contribution, functioning primarily as sugar replacers in processed foods and beverages. Stevia glycoside formulations lead product type revenue due to regulatory acceptance breadth across FDA GRAS, EFSA approvals, and Japan's FOSHU system, while monk fruit extract captures the fastest growth trajectory driven by its clean taste profile and absence of bitter aftertaste in high-purity Mogroside V applications. Powder and granular forms dominate industrial procurement volumes, though liquid formats gain share in beverage manufacturing lines optimized for pump-based dosing systems.
FDA GRAS notification requirements, EFSA Novel Food regulations, and Japan's Ministry of Health, Labour and Welfare FOSHU approval framework collectively determine market access timelines and formulation investment recovery periods for new entrants. The EU Green Deal's Farm to Fork strategy targets 10% reduction in added sugars across member state food supplies, redirecting R&D expenditure toward botanical extraction efficiency and fermentation-derived glycoside scaling. Stakeholders must monitor evolving purity thresholds and maximum usage levels in CODEX-aligned national standards, as these specifications determine competitive moats between extraction-based and bioconversion-based supply models.
Market Dynamics
The FDA's updated GRAS determination pathway is compressing approval timelines for novel glycoside formulations while simultaneously elevating purity thresholds that favor bioconversion-based production models over traditional extraction.
Growth Catalysts
- Beverage Industry Reformulation:Carbonated soft drink and ready-to-drink tea manufacturers are replacing high-fructose corn syrup with stevia glycoside blends to meet clean-label commitments. This procurement surge concentrates in North American and Japanese bottling facilities.
- EU Green Deal Farm to Fork:The strategy mandates 10% reduction in added sugars across member state food supplies, redirecting R&D expenditure toward botanical extraction efficiency and fermentation-derived glycoside scaling.
- Enzymatic Bioconversion:Proprietary enzyme platforms now convert low-value steviol glycosides into high-purity Reb M, improving taste profiles without expanding leaf cultivation acreage.
Market Restraints
- Leaf Supply Concentration:Raw stevia biomass production clusters in Paraguay and China, exposing processors to climate volatility and geopolitical friction in concentrated sourcing corridors.
- EFSA Novel Food Timelines:European approval pathways for new glycoside variants extend 18-24 months, delaying formulation investment recovery and freezing product launch schedules.
- Allulose Price Compression:Synthetic rare sugar alternatives manufactured via corn starch isomerization undercut plant-derived high-intensity sweeteners on per-serving cost in bakery applications.
Strategic Opportunities
- Southeast Asia Expansion:Indonesia, Vietnam, and Thailand lack mature stevia supply infrastructure despite surging middle-class demand for reduced-sugar packaged foods.
- Pharmaceutical Excipient Applications:Pediatric and geriatric dosage forms increasingly specify monk fruit extract as a non-cariogenic, non-glycemic taste-masking agent in chewable tablets.
- Direct-to-Manufacturer Platforms:Digital procurement portals bypass traditional ingredient distributors, enabling mid-size beverage brands to access certified organic glycoside lots with full traceability documentation.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Fermentation scale-up expertise for glycoside production remains concentrated in pharmaceutical hubs, forcing sweetener specialists to compete for limited talent pools.
- CODEX Alignment Complexity:Divergent maximum usage levels across JECFA, FDA, and national standards force manufacturers to maintain multiple formulation specifications for identical product SKUs.
- Extraction Facility Retrofit Costs:Conventional stevia processors face capital-intensive equipment upgrades to meet evolving solvent residue limits in EU and Japanese import regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Derived Sweetener Market |
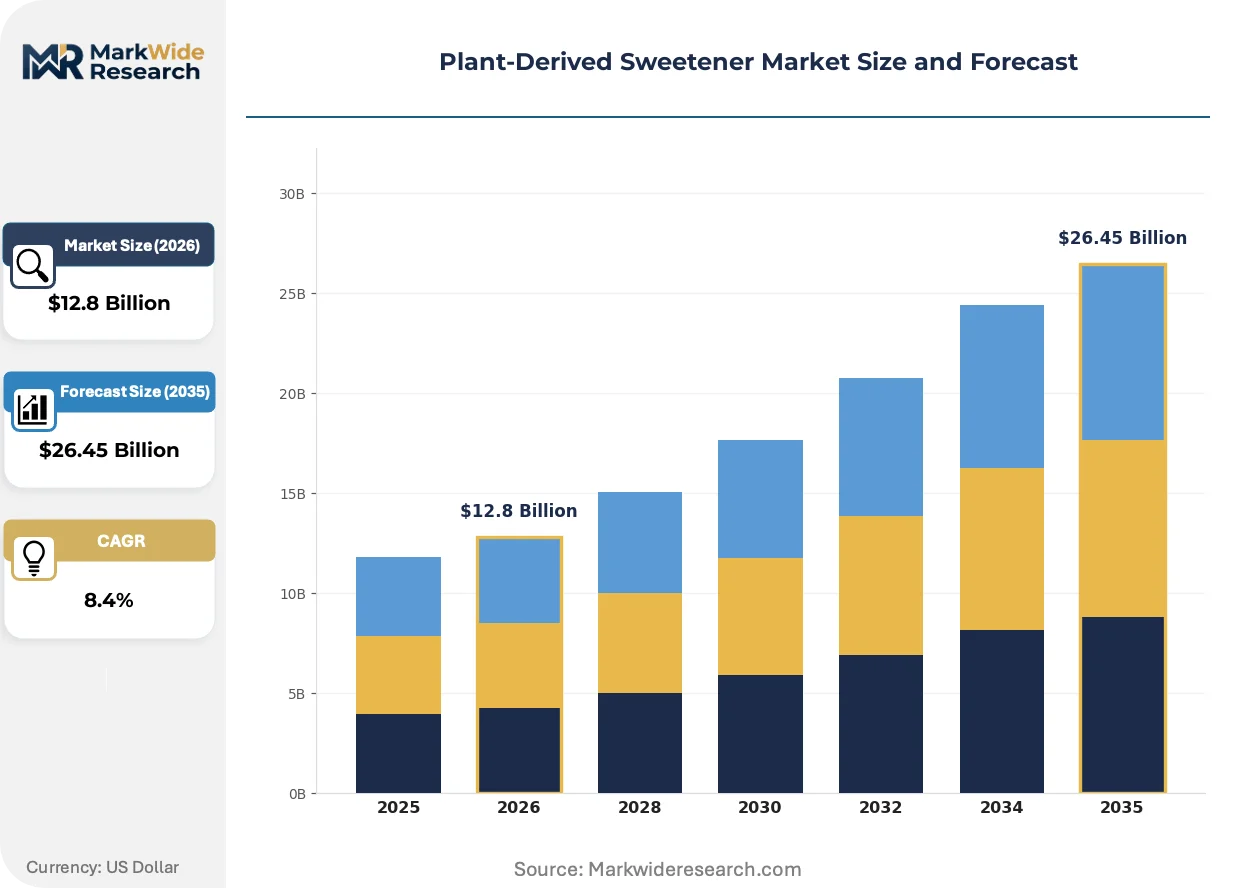
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
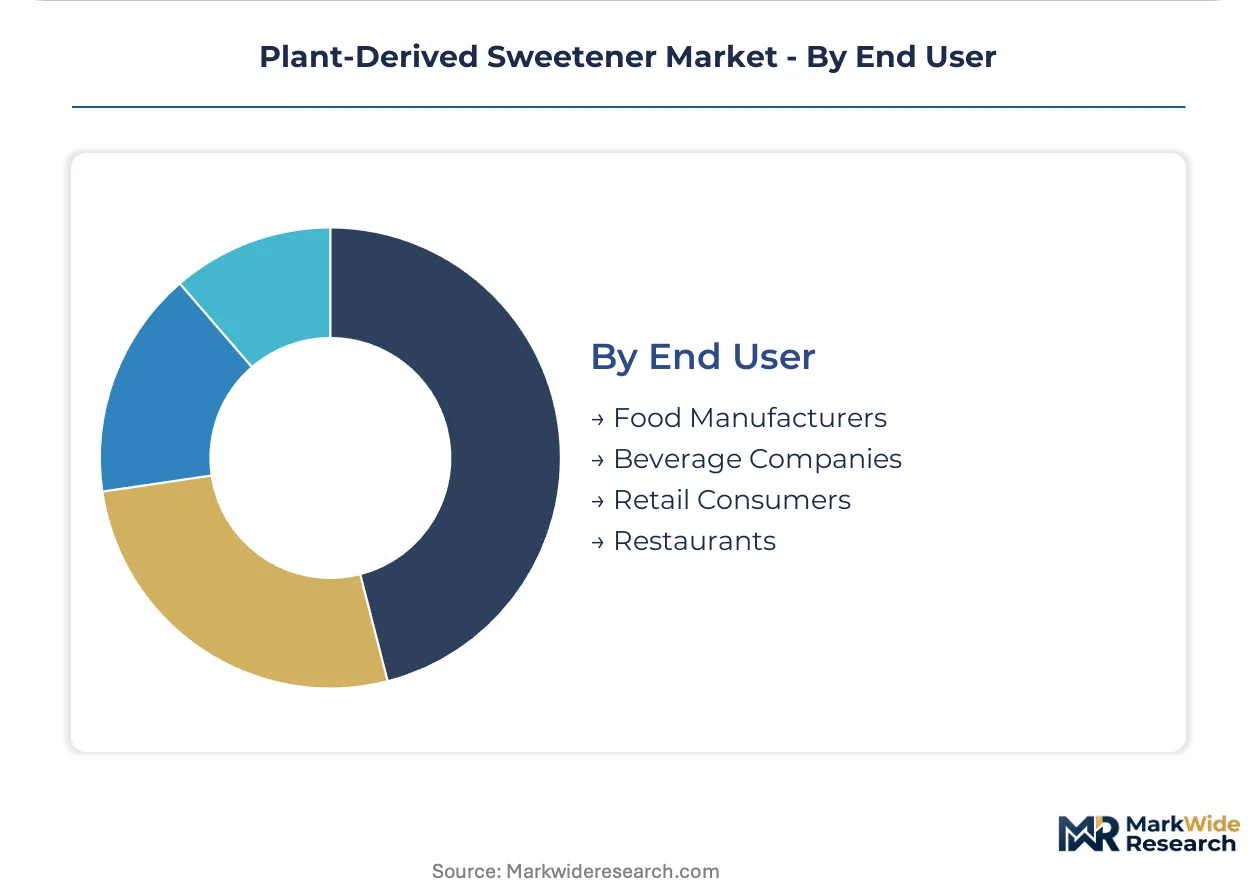
| Segmentation | Product Type: Stevia, Monk Fruit, Agave Syrup, Erythritol Application: Beverages, Bakery, Confectionery, Dairy Form: Liquid, Powder, Granular, Crystal End User: Food Manufacturers, Beverage Companies, Retail Consumers, Restaurants |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Tate & Lyle PLC, Ingredion Incorporated, DuPont, PureCircle Limited, Roquette Frères, GLG Life Tech Corporation, Merisant Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Derived Sweetener Market Trends and Innovations
Bioconversion technology and regulatory precision are converging to reshape competitive moats, with production economics increasingly favoring controlled fermentation over agricultural cultivation.
Enzymatic glycoside modification is migrating from pilot-scale demonstration to commercial deployment across North American and European manufacturing facilities. Specialty enzyme suppliers now license immobilized-cell platforms to sweetener processors seeking to bypass leaf supply constraints. This technology is migrating from niche premium applications toward mass-market beverage formulations, compressing the cost differential between extraction-derived and fermentation-derived Reb M.
EFSA's tightened specifications for steviol glycoside purity and maximum acceptable daily intake calculations are forcing reformulation across European confectionery and dairy categories. Manufacturers must resubmit dossiers for existing product lines, triggering supply contract renegotiations with glycoside suppliers. The regulatory pressure concentrates most intensely in Germany and France, where private-label retailers have accelerated clean-label commitments ahead of formal mandate timelines.
Foodservice operators are consolidating sweetener procurement through centralized purchasing cooperatives that specify certified sustainable sourcing and third-party carbon footprint verification. Institutional buyers in the United States and Japan now require blockchain-traceable supply documentation from stevia and monk fruit extract suppliers. This behavioral shift is most visible in quick-service restaurant chains and hospital systems, where procurement teams trade volume commitments for price stability and supply security guarantees.
Plant-Derived Sweetener Market Segmentation
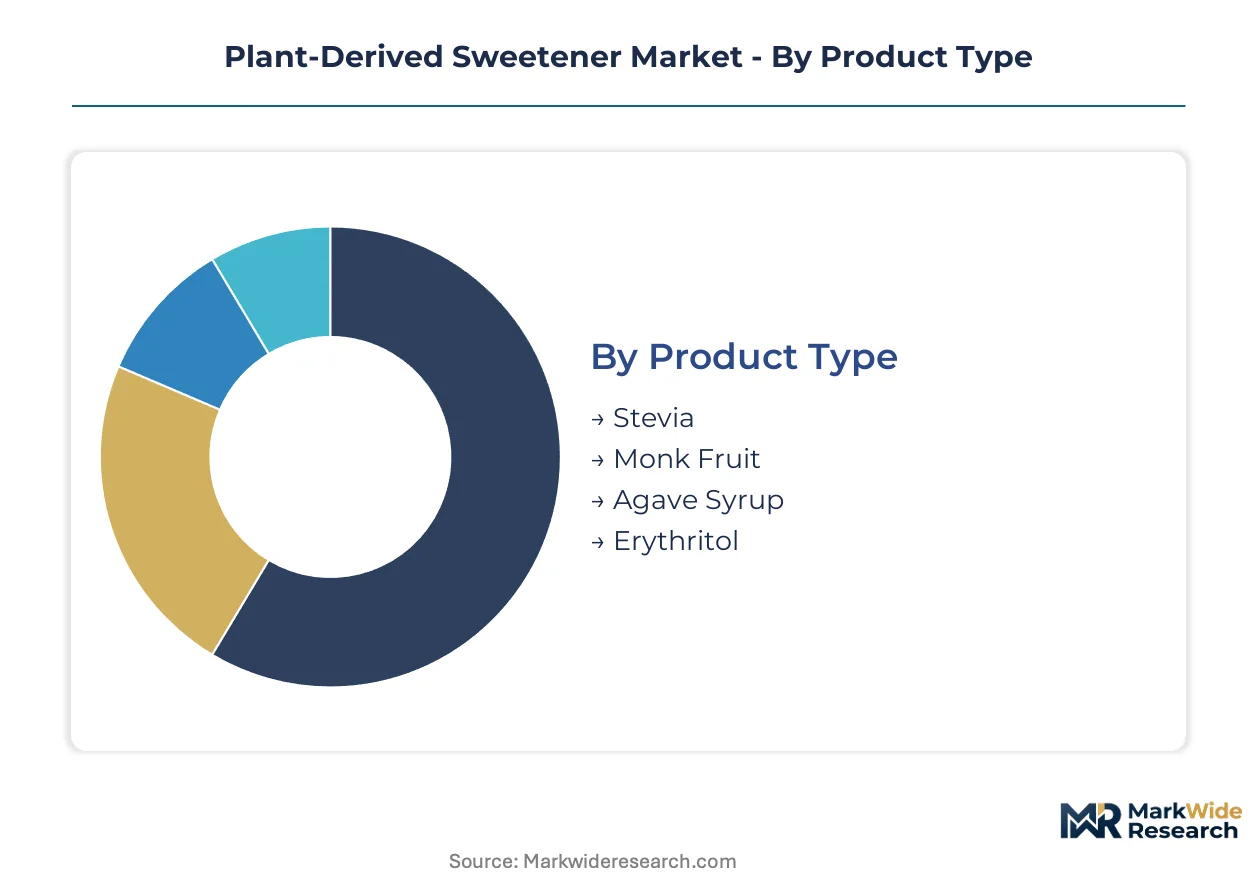
Segmentation in plant-derived sweeteners reveals how formulation requirements, regulatory thresholds, and procurement economics split demand across distinct technical and commercial channels. Understanding these divisions exposes where margin pools concentrate and where supply constraints create procurement bottlenecks.
Product Type:
Cost tier positioning determines procurement volumes and margin capture across extraction-based versus bioconversion-based supply models.
- Stevia:Glycoside formulations derived from Stevia rebaudiana leaves achieve sweetness intensities 200-400 times sucrose. Beverage manufacturers in the United States and Japan specify stevia for reduced-sugar carbonated drinks, though leaf supply concentration in Paraguay and China creates price volatility.
- Monk Fruit:Mogroside V extracts from Siraitia grosvenorii deliver clean taste profiles without bitter aftertaste at high purity grades. Pharmaceutical formulators specify monk fruit for pediatric chewable tablets, while beverage brands adopt it for premium positioning.
- Agave Syrup:Fructose-rich nectar from Agave tequilana serves organic food manufacturers seeking non-GMO label claims.
- Erythritol:Sugar alcohol from corn or tapioca fermentation provides bulk sweetness with zero glycemic impact for bakery applications.
Stevia holds installed capacity. Monk fruit is rotating up the share rankings.
Application:
End-use specifications dictate purity thresholds, maximum usage levels, and formulation compatibility requirements.
- Beverages:Ready-to-drink tea and carbonated soft drink manufacturers drive procurement intensity for high-intensity glycosides. Pump-based dosing systems in bottling facilities favor liquid formats, while powder glycosides serve dry-mix applications.
- Bakery:Maillard reaction requirements and moisture retention needs push formulators toward erythritol and agave blends. European Union sugar reduction mandates under the Farm to Fork strategy accelerate reformulation timelines.
- Confectionery:Hard candies and chewing gums specify heat-stable glycosides with precise crystallization behavior.
- Dairy:Yogurt and ice cream applications demand cold-soluble sweeteners with clean flavor release profiles.
Beverages command formulation R&D budgets. Bakery is gaining share fastest.
Form:
Physical state determines equipment compatibility, dissolution kinetics, and supply chain handling economics.
- Liquid:Concentrated glycoside solutions enable precise metering in automated beverage production lines. Japanese and U.S. bottling facilities specify liquid Reb M for reduced-sugar formulations.
- Powder:Spray-dried glycosides serve dry-blend manufacturers requiring extended shelf stability and simplified logistics.
- Granular:Free-flowing crystals mimic sucrose handling properties for foodservice tabletop dispensing.
- Crystal:Large-format erythritol crystals provide bulking function in sugar-free baking applications.
Powder holds installed capacity. Liquid is rotating up the share rankings.
End User:
Customer type shapes order scale, certification requirements, and traceability documentation intensity.
- Food Manufacturers:Packaged goods producers specify certified organic glycosides with blockchain traceability for clean-label product lines. FDA GRAS documentation and EFSA Novel Food approvals determine supplier qualification.
- Beverage Companies:Multinational bottlers negotiate multi-year supply contracts with volume commitments and price stability guarantees. Cargill and PureCircle anchor procurement relationships through captive cultivation and bioconversion technology.
- Retail Consumers:Direct-to-consumer brands emphasize single-ingredient positioning and sustainable sourcing claims.
- Restaurants:Foodservice operators consolidate procurement through purchasing cooperatives requiring carbon footprint verification.
Food manufacturers hold installed capacity. Beverage companies are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in plant-derived sweeteners tilts toward Paraguay and China where leaf cultivation concentrates, while formulation value capture clusters in the United States and Japan where beverage brands command premium positioning for clean-label products.
United States
Beverage manufacturers in Atlanta and Purchase drive procurement intensity for high-purity Reb M glycosides. FDA GRAS notification pathways compress approval timelines for novel steviol formulations. Chicago-based ingredient distributors now require blockchain-traceable supply documentation from stevia extract suppliers.
China
Raw stevia biomass production in Guangxi and Shandong provinces supplies global extraction facilities. SAMR oversight of food additive standards tightens purity thresholds for glycoside imports. Qingdao and Shanghai house concentration facilities serving Japanese and European bottling contracts.
Japan
Reduced-sugar FOSHU-approved beverages command shelf-space premiums in Tokyo and Osaka retail channels. METI coordinates with the Ministry of Health, Labour and Welfare on maximum usage level calculations for monk fruit extracts. Nagoya-area bottling facilities specify liquid glycoside formats for automated dosing systems.
Germany
EFSA Novel Food approval timelines extend 18-24 months for new glycoside variants, freezing product launch schedules. The EU Green Deal Farm to Fork strategy redirects R&D expenditure toward fermentation-derived sweetener scaling. Hamburg and Rotterdam serve as entry points for South American leaf biomass.
Brazil
ANVISA alignment with CODEX standards determines import acceptance for high-intensity sweetener formulations. São Paulo-based food manufacturers specify certified organic agave syrup for non-GMO label claims. The Southeast industrial corridor houses blending facilities serving Mercosur packaged goods markets.
Plant-Derived Sweetener Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base organizes around three structural tiers: multinational agribusiness conglomerates with captive cultivation networks, bioconversion technology licensors with proprietary enzyme platforms, and regional extraction processors serving geographic niche markets. Two dominant competitive moves define current positioning: backward integration into leaf supply chains to secure biomass access, and technology licensing partnerships to bypass capital-intensive fermentation scale-up requirements.
Among North American agribusiness conglomerates, Cargill Incorporated and Archer Daniels Midland Company exemplify platform integrators with upstream control over South American cultivation corridors. PureCircle Limited occupies a position within the bioconversion technology tier, representing specialists in enzymatic glycoside modification. European polyol manufacturers including Roquette Frères and Tate & Lyle PLC anchor the sugar alcohol segment through fermentation-based supply security.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| DuPont |
| PureCircle Limited |
| Roquette Frères |
| GLG Life Tech Corporation |
| Merisant Company |
| Others |
Pricing and Supply Chain Analysis
Paraguayan and Chinese leaf cultivation corridors concentrate upstream biomass supply, anchoring margin capture with processors who command long-term offtake contracts while downstream beverage brands compete on formulation premiums. Bioconversion technology is redistributing pricing power toward fermentation specialists who bypass agricultural volatility entirely.
Pricing Analysis
Configured-to-order pricing for high-purity Reb M glycosides commands a substantial premium over standard stevia extract grades, with three-tier pricing structure across premium, standard, and economy levels separating pharmaceutical-grade monk fruit from foodservice bulk stevia from commodity agave syrup. Price differentiation rests on certification tier—organic, non-GMO, and FOSHU-approved lots—and volume scale, with multinational bottlers locking in multi-year contracts at lower unit costs. Cost compression in standard stevia glycosides is intensifying because enzymatic bioconversion is displacing leaf-dependent extraction. Food manufacturers show highest price sensitivity due to reformulation volume exposure, while pharmaceutical formulators absorb premiums for taste-masking specifications.
Supply Chain Analysis
Upstream stevia leaf feedstock draws from Paraguay, China, and select Kenyan cultivation zones, with monk fruit biomass sourcing almost exclusively from Guangxi province and Guilin prefecture. Raw material dependencies center on steviol glycoside content in harvested leaves, enzyme inputs for bioconversion platforms, and tapioca or corn starch for erythritol fermentation. Single-source vulnerability in Chinese monk fruit concentration exposes processors to SAMR export licensing shifts. Distribution runs through Rotterdam and Hamburg for European compounders, with direct vessel routes from Qingdao serving Japanese bottlers under just-inventory protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as clean-label beverage reformulation accelerates procurement intensity beyond historical penetration rates in conventional sugar reduction applications.
For Market Incumbents: Insulate contract stability by deepening backward integration into South American cultivation corridors and securing exclusive enzyme platform licenses from specialty biotech suppliers. Synthetic rare sugar alternatives including allulose threaten displacement in bakery applications, requiring defensive capacity expansion in fermentation-derived glycoside production. FDA GRAS notification expertise constitutes a defendable moat against European and Asian entrants facing extended approval timelines. For New Entrants and Emerging Players: Build out white-space positions in Southeast Asian supply infrastructure, where Indonesian and Vietnamese beverage markets lack mature stevia extraction capacity despite surging middle-class demand. Pharmaceutical excipient applications for monk fruit extract offer the most penetrable segment given existing regulatory familiarity and premium pricing tolerance. A direct-to-manufacturer digital procurement platform enables bypass of established distributor networks while capturing traceability-conscious mid-size brands. For Investors and Strategic Acquirers: Capital is best deployed toward bioconversion technology licensors with scalable enzyme platforms and existing pharmaceutical-grade certification, as these assets capture margin migration away from agricultural extraction. Long-term viability over the coming decade hinges on fermentation economics achieving cost parity with leaf-derived supply. The signal to watch is EFSA novel food approval velocity for next-generation glycoside variants, which would validate platform scalability and trigger consolidation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Cargill's Paraguayan stevia estates secure biomass access independent of spot leaf markets. |
| Enzyme Platform Licensing | PureCircle's proprietary bioconversion technology enables Reb M production without expanding cultivation acreage. |
| Pharmaceutical Excipient Certification | Monk fruit extract qualification for pediatric dosage forms opens premium pricing tiers in taste-masking applications. |
| Direct-to-Manufacturer Digital Procurement | Blockchain-traceable glycoside portals bypass traditional ingredient distributors for mid-size beverage brands. |
| EFSA Novel Food Dossier Investment | Early submission for next-generation glycoside variants captures first-mover positioning in European sugar reduction mandates. |
Research Methodology
A spread of perspectives from beverage formulation directors, sweetener procurement leads at multinational bottlers, extraction facility engineers, and regulatory affairs specialists at GRAS notification consultancies converged on the working assumptions that stevia glycoside adoption curves and monk fruit penetration rates would follow distinct trajectories. Primary fieldwork combined structured interviews with secondary validation through FDA GRAS notification databases, EFSA novel food register filings, Japanese MHLW FOSHU approval records, and customs trade data tracking leaf biomass movements from Paraguay and China. Bottom-up capacity modeling and top-down demand estimation triangulated on volume figures across the analysis window.
Demand-supply-balance framing anchored the analytical framework, with segmentation across product type, application, physical form, and end-user category modeled throughout the forecast period. CAGRs were derived from weighted scenario analysis incorporating beverage industry reformulation commitments, EU Farm to Fork sugar reduction mandates, and enzymatic bioconversion scale-up curves. Industry-specific inputs included steviol glycoside purity thresholds in evolving CODEX standards and maximum usage level calculations under JECFA guidelines.
Stress conditions across leaf supply disruption in Chinese cultivation zones, EFSA approval timeline extensions, and synthetic rare sugar price compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about bioconversion cost curves and regulatory acceptance velocities. Cross-checking against customs data on actual glycoside import volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Glucose Syrup Market
Sweeteners
Xylitol Market
Sweeteners
Resistant Maltodextrin Market
Sweeteners
Xylose Market
Sweeteners
Dextrates Market
Sweeteners
Sugar Beet Juice Extract Market
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
Palm Sugar Market
Sweeteners
Gluten-Free Sugar Syrup Market
Sweeteners
Brown Rice Syrup Market
Sweeteners
North America Food Sweetener Market
Sweeteners
High-Intensity Sweeteners Market
Sweeteners
South America Low-Calorie Sweeteners Market
Sweeteners
Australia Food Sweetener Market
Sweeteners
Naturally Derived Sweeteners Market
Sweeteners
Sorbitol Market