
 Gluten-Free Sugar Syrup Market | 2026-2036
Gluten-Free Sugar Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten-Free Sugar Syrup Market Analysis
Asset-light contract manufacturing and third-party tolling agreements is rewriting competitive entry barriers for mid-sized syrup brands. Cargill, Incorporated leverages its North American grain-processing infrastructure to sustain bulk supply contracts with industrial bakers. Gulshan Polyols Ltd. anchors South Asian production capacity for sorbitol-based syrup derivatives. Torani differentiates through flavor-infused specialty formulations targeting café and beverage channels.
Gluten-free sugar syrup denotes any liquid sweetener certified below twenty parts per million gluten content, typically manufactured through enzymatic hydrolysis of starches or direct extraction from plant saps and fruit concentrates, with viscosity ranging from ten to fifty degrees Brix depending on end-use application. The product serves primarily as a binding and bulking agent in baked goods, a flavor carrier in beverages, and a humectant in confectionery where wheat-derived malt syrups are prohibited. Maple syrup and agave nectar command premium shelf positioning in health stores and specialty retailers, while brown rice syrup dominates food manufacturer procurement for its neutral flavor profile and cost efficiency in granola and energy bar production. Plant-based sweetener sources now outpace grain-based alternatives in new product development pipelines, reflecting broader shifts toward allergen-free and paleo-positioned formulations.
The FDA enforces gluten-free labeling standards under the Food Allergen Labeling and Consumer Protection Act, while the EU's REACH and General Food Law Regulation mandate contaminant traceability across imported syrup shipments. Health Canada and the PMRA coordinate parallel gluten threshold enforcement for cross-border North American trade, creating compliance complexity for multi-market suppliers. Stakeholders must monitor evolving certification requirements from the Gluten-Free Certification Organization and national regulators to secure shelf access in premium retail channels.
Market Dynamics
The FDA's tightened gluten-free labeling thresholds below twenty parts per million are forcing wholesale reformulation across starch-derived syrup supply chains, compressing margins for malt-based producers while accelerating enzymatic hydrolysis investments among compliant manufacturers.
Growth Catalysts
- Clean-label bakery mandates:North American bakery chains now specify certified gluten-free syrups for dessert line differentiation, pulling volume from industrial malt alternatives.
- EU export compliance:German artisanal and industrial confectioners source certified alternatives to meet REACH traceability requirements for cross-border shipments.
- Enzymatic hydrolysis scale-up:Continuous processing technology reduces conversion costs for rice and tapioca starches, narrowing the price gap with wheat-derived inputs.
Market Restraints
- Input cost volatility:Organic brown rice and tapioca root prices fluctuate with Southeast Asian harvest cycles, squeezing contract margins for North American tollers.
- Supply concentration risk:South Asian sorbitol derivative production clusters expose buyers to monsoon-disrupted logistics and port congestion at Mumbai and Chennai.
- Technical viscosity limits:Plant-based syrups above forty degrees Brix crystallize unpredictably, restricting their deployment in hard candy and fondant applications where wheat malt syrups dominate.
Strategic Opportunities
- Paleo-positioned formulations:Maple and coconut nectar variants command shelf-space premiums in US health-specialty retail, with whitespace in club-store private label programs.
- Beverage channel expansion:Flavor-infused specialty syrups for café cold-brew and craft cocktail applications bypass commodity pricing pressure entirely.
- Carbon labeling alignment:EU Green Deal supply-chain disclosure rules favor low-carbon intensity tapioca and coconut processing over energy-intensive grain conversion.
Industry Challenges
- Certification timeline compression:Gluten-Free Certification Organization audit backlogs stretch six to nine months, delaying new product launches for seasonal bakery programs.
- Legacy equipment retrofit costs:Dedicated gluten-free production lines require segregated enzymatic reactors and CIP systems, demanding seven-figure capex commitments from mid-sized processors.
- Cross-contamination protocols:Shared tanker and drum logistics networks struggle to maintain chain-of-custody documentation for twenty parts per million thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten-Free Sugar Syrup Market |
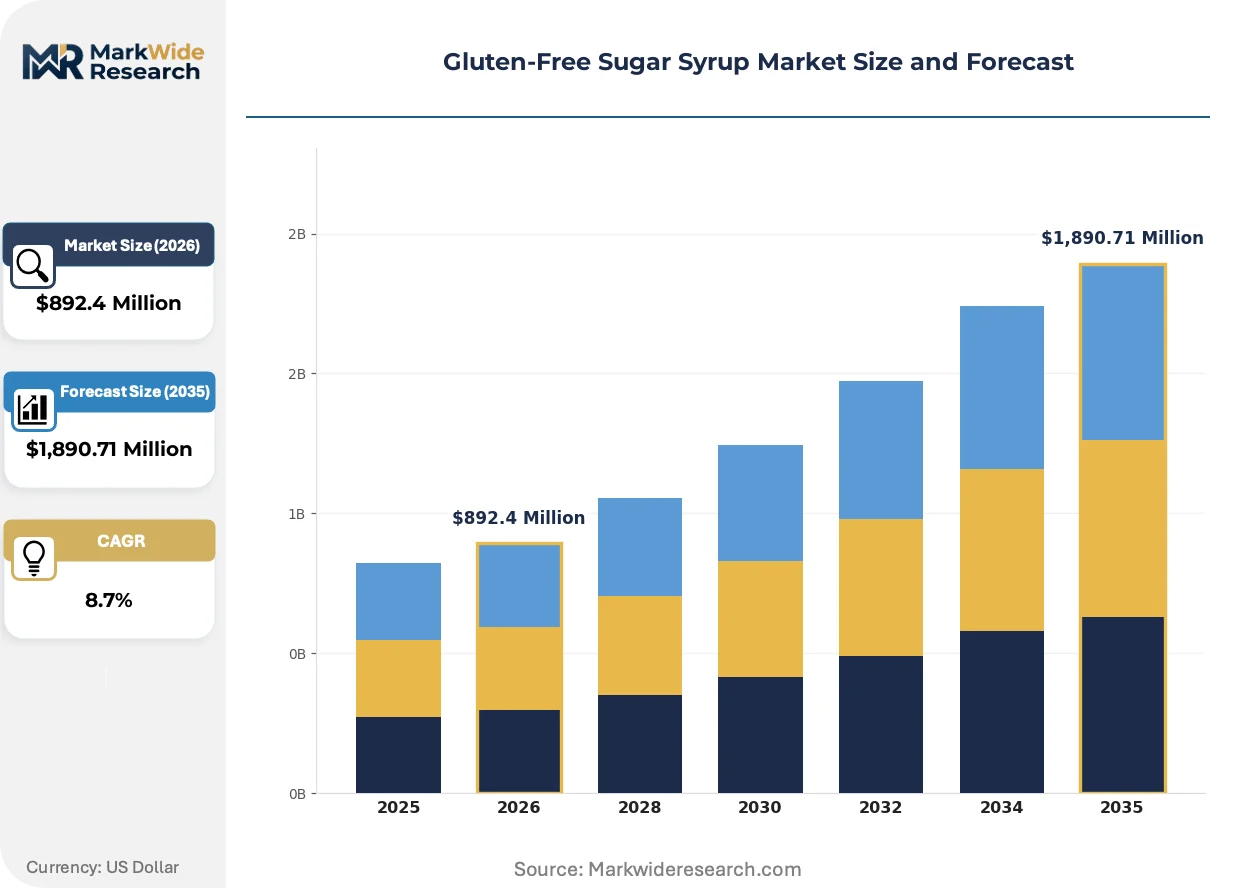
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,890.71 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Maple Syrup, Agave Nectar, Brown Rice Syrup, Coconut Syrup Sweetener Source: Fruit-Based, Grain-Based, Plant-Based, Vegetable-Based End User: Food Manufacturers, Beverage Producers, Bakers, Home Cooks Distribution Channel: Online Retailers, Supermarkets, Health Stores, Specialty Stores |
| Companies Covered | B&G Foods, Inc, Cargill, Incorporated, MONIN, Torani, Whole Earth Brands, Canadian Organic Maple Co. Ltd, Blue Ocean Biotech, Tereos, Gulshan Polyols Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten-Free Sugar Syrup Market Emerging Trajectories
Enzymatic processing advances and regulatory disclosure mandates are converging to reshape formulation priorities, with plant-based feedstocks displacing grain derivatives across premium positioning tiers.
Membrane filtration technology for color and impurity removal is hybridizing with traditional enzymatic hydrolysis, enabling neutral-flavor tapioca and rice syrups to match wheat malt performance in granola and energy bar binding. Large-scale North American contract manufacturers are adopting these hybrid systems to service clean-label bakery contracts without flavor masking agents. The technology is compressing the premium gap between certified gluten-free and conventional commodity syrups.
REACH contaminant traceability requirements for imported syrup shipments are mandating blockchain-enabled documentation from extraction through final packaging. EU customs authorities now reject shipments lacking batch-level gluten testing certificates from accredited laboratories. Industrial confectioners in Germany and the Netherlands are responding by consolidating supplier bases to vertically integrated processors with captive analytical capabilities.
Direct procurement relationships between bakery chains and certified tollers are displacing traditional ingredient distributor intermediaries, compressing margin layers and accelerating formulation feedback loops. This disintermediation is most visible in US coastal metropolitan markets where regional bakery groups negotiate annual volume commitments against guaranteed supply security clauses.
Gluten-Free Sugar Syrup Market Segmentation
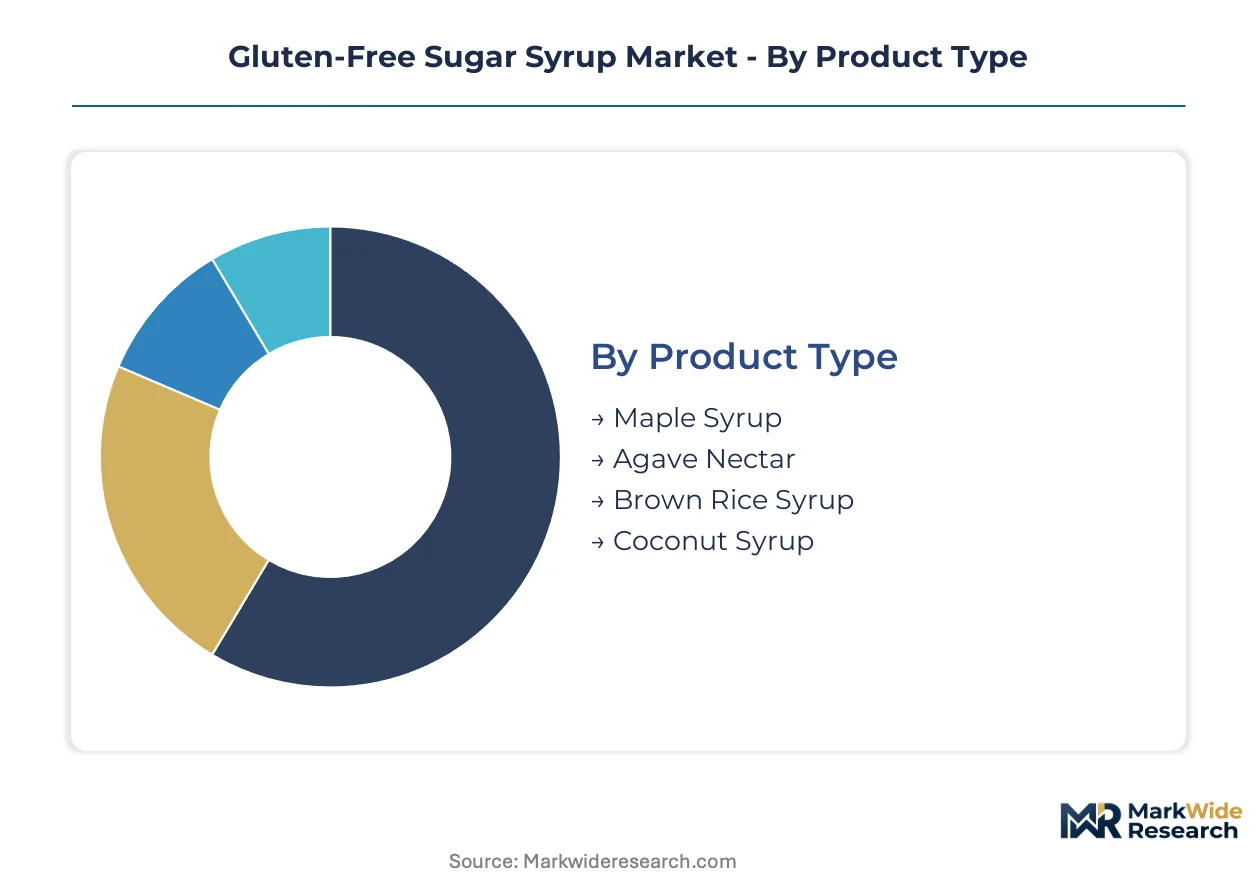
Gluten-free sugar syrup purchasing patterns diverge sharply across product formats and buyer sophistication levels. Industrial procurement teams prioritize certified bulk supply chains, while specialty retail channels reward origin-story differentiation and third-party certification badges.
Product Type:
After-sales service intensity varies dramatically across syrup categories, with premium variants demanding technical formulation support and commodity grades trading on spot-market responsiveness.
- Maple Syrup:Boiled sap from Acer saccharum trees, graded by color density and mineral content. Artisanal bakeries in Vermont and Quebec specify Grade A Dark for robust flavor profiles in clean-label dessert lines, paying premiums for single-origin traceability.
- Brown Rice Syrup:Enzymatically hydrolyzed starch from Oryza sativa, delivering neutral sweetness and binding functionality. Energy bar manufacturers in California and Oregon source this grade for granola applications where wheat malt syrups are prohibited.
- Agave Nectar:Filtered sap from Agave tequilana, high in fructose with low glycemic index positioning. Mexican and Texan bottlers dominate supply.
- Coconut Syrup:Reduced sap from Cocos nucifera inflorescences, mineral-rich with caramel notes. Southeast Asian processors control raw material access.
By volume, Brown Rice Syrup leads. By growth pace, Coconut Syrup is ahead.
Sweetener Source:
Cost tier stratification separates commodity grain derivatives from premium plant-based alternatives, with price spreads widening at organic certification thresholds.
- Plant-Based:Coconut nectar, agave sap, and date concentrates extracted directly from vascular tissues. Paleo-positioned brands in US health-specialty retail command shelf-space premiums for these variants, bypassing commodity pricing pressure entirely.
- Grain-Based:Rice, sorghum, and millet starches processed through enzymatic hydrolysis. German industrial confectioners source certified alternatives to meet REACH traceability requirements for EU-compliant export production.
- Fruit-Based:Concentrated apple, pear, and grape juices reduced to syrup consistency. Washington State and Italian Trentino-Alto Adige processors dominate.
- Vegetable-Based:Tapioca and sweet potato starches converted through acid-enzyme treatment. Thai and Vietnamese harvest cycles dictate input cost volatility.
By volume, Grain-Based dominates manufacturing procurement. By margin expansion, Plant-Based is pulling ahead.
End User:
Application-specific viscosity and certification requirements fragment procurement specifications across buyer categories.
- Food Manufacturers:Industrial-scale buyers requiring twenty parts per million certified bulk supply with guaranteed lot consistency. Cargill's North American grain-processing infrastructure sustains multi-year contracts with industrial bakers reformulating dessert lines under FDA's tightened gluten-free labeling thresholds.
- Beverage Producers:Flavor-infused syrup demand for café cold-brew and craft cocktail applications. Torani's specialty formulations target this channel with premium positioning.
- Bakers:Artisanal and semi-industrial operations requiring technical viscosity control for binding and humectant functions. Brooklyn and Portland bakery clusters specify certified alternatives.
- Home Cooks:Retail-packaged volumes through supermarkets and health stores, price-sensitive with strong brand loyalty to origin narratives.
By volume, Food Manufacturers absorb the largest share. By contract value growth, Beverage Producers are expanding most quickly.
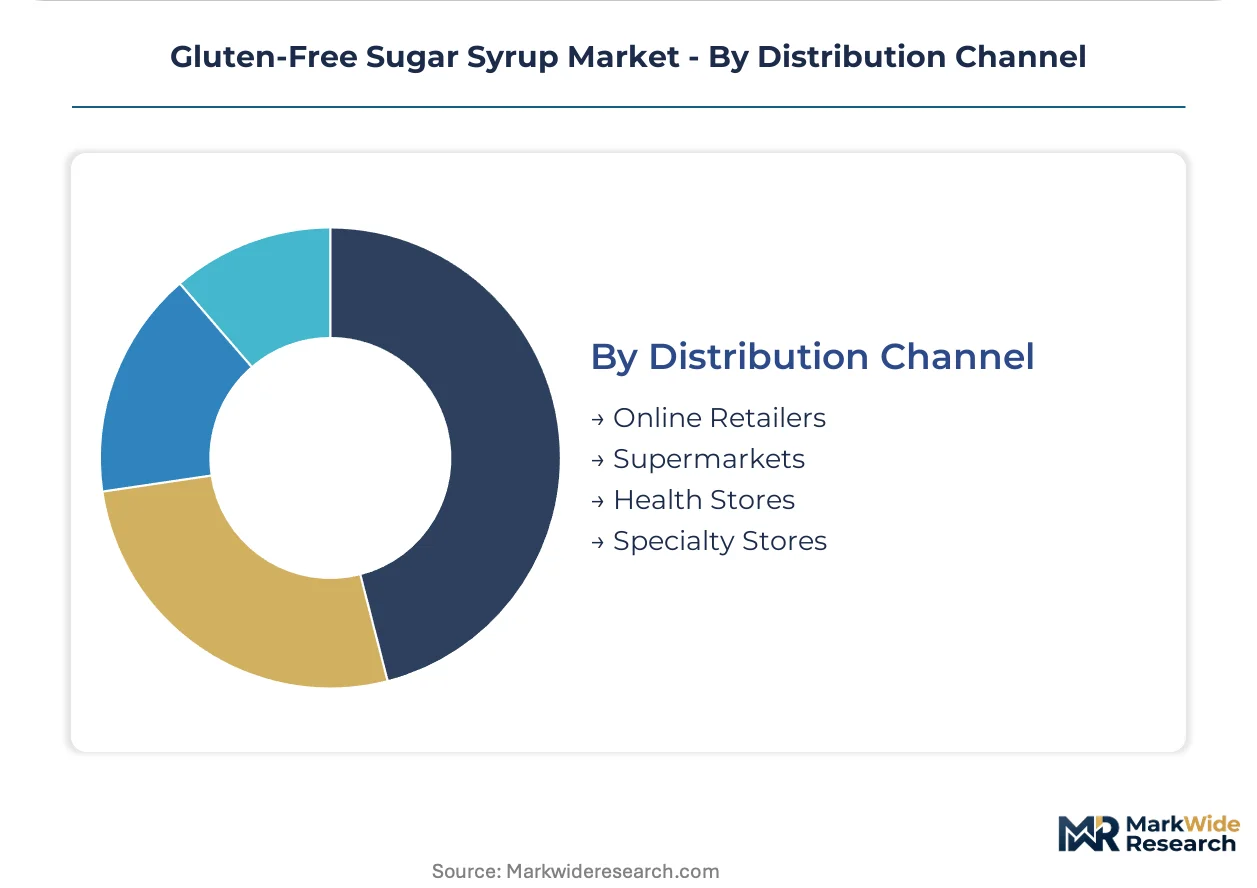
Distribution Channel:
Customer type and purchase frequency determine channel economics, with institutional buyers bypassing traditional intermediaries.
- Supermarkets:Mass-market retail requiring three-tier pricing structure across premium, standard, and economy levels. Kroger and Safeway chains in US coastal metropolitan markets negotiate annual volume commitments against guaranteed supply security clauses.
- Specialty Stores:Curated assortment with origin-story and certification badge prominence. Whole Foods Market's regional buyers consolidate supplier bases to vertically integrated processors with captive analytical capabilities.
- Online Retailers:Direct-to-consumer subscription models and bulk pantry replenishment. Amazon and Thrive Market algorithms favor products with blockchain-enabled documentation.
- Health Stores:Independent operators with staff-trained recommendation influence. Co-op networks in Minnesota and Wisconsin prioritize local and regional sourcing.
By volume, Supermarkets move the most units. By margin rate, Specialty Stores outperform.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances vary sharply across major consuming markets, with Germany running structural deficits in certified gluten-free inputs while the United States and Canada balance domestic production against specialty import requirements for premium positioning tiers.
United States
Clean-label bakery mandates from coastal metropolitan chains pull volume through dedicated tolling agreements. The FDA enforces gluten-free labeling thresholds below twenty parts per million under the Food Allergen Labeling and Consumer Protection Act. Brooklyn and Portland bakery clusters specify certified alternatives for binding and humectant functions in dessert line reformulations.
Germany
Artisanal and industrial confectioners source certified alternatives to meet EU REACH traceability requirements for cross-border shipments. The EU's General Food Law Regulation mandates contaminant documentation across imported syrup batches. Cologne and Hamburg processing hubs consolidate supplier bases to vertically integrated processors with captive analytical capabilities.
Canada
Health Canada and the PMRA coordinate parallel gluten threshold enforcement with US regulators, creating compliance complexity for cross-border suppliers. The country's national food safety regulator maintains twenty parts per million standards aligned with FDA benchmarks. Quebec maple syrup processors leverage single-origin traceability for premium export positioning into US health-specialty retail.
Thailand
Tapioca root harvest cycles dictate input cost volatility for enzymatic hydrolysis processors serving North American tollers. The country's agricultural ministry oversees starch export quality certification for EU-bound shipments. Bangkok and Korat industrial zones anchor Southeast Asian production capacity for neutral-flavor syrup derivatives.
India
Sorbitol derivative production clusters expose buyers to monsoon-disrupted logistics and port congestion at Mumbai and Chennai. The FSSAI mandates gluten threshold compliance for packaged food exports to European markets. Gujarat and Maharashtra processing corridors supply brown rice syrup intermediates to energy bar manufacturers in California and Oregon.
Gluten-Free Sugar Syrup Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient supply. The vendor base stratifies across three tiers: multinational grain processors with captive enzymatic infrastructure, regional tollers with segregated gluten-free lines, and specialty flavor houses with beverage channel access. Dominant competitive moves include backward integration into starch processing assets and strategic partnerships with certified organic raw material cooperatives.
Among North American grain-processing conglomerates, Cargill, Incorporated occupies a position exemplifying scale-driven supply security for industrial bakery contracts. Gulshan Polyols Ltd. anchors South Asian production capacity for sorbitol-based derivatives, representing the regional toller archetype with dedicated export compliance infrastructure. Torani sits within the specialty flavor tier, occupying a position that bypasses commodity pricing pressure through café and beverage channel positioning.
| Leading Market Players |
|---|
| B&G Foods, Inc |
| Cargill, Incorporated |
| MONIN |
| Torani |
| Whole Earth Brands |
| Canadian Organic Maple Co. Ltd |
| Blue Ocean Biotech |
| Tereos |
| Gulshan Polyols Ltd. |
| Others |
Supply Flow & Price Mechanics
Thai tapioca root harvest cycles and Indian sorbitol derivative production clusters concentrate upstream margin capture among Southeast Asian starch processors, while North American industrial bakers and German confectioners absorb downstream price volatility through long-term tolling agreements and certified supply premiums.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with annual volume commitments against guaranteed supply security clauses. Pricing stratifies across premium single-origin maple and coconut nectar tiers, standard certified grain-based alternatives, and economy-grade fruit concentrates. Cost compression in organic brown rice inputs is intensifying because Southeast Asian harvest variability squeezes contract margins for North American tollers. Food manufacturers exhibit highest price sensitivity due to bulk procurement scale, while beverage producers tolerate premiums for flavor-infused specialty formulations.
Supply Chain Analysis
Tapioca root from Thailand, brown rice from India, and maple sap from Quebec feed into enzymatic hydrolysis and reduction processing stages. Raw material sourcing draws from monsoon-dependent agricultural cycles, energy-intensive starch conversion infrastructure, and seasonal tree-tapping labor pools. Single-source vulnerability runs through Mumbai and Chennai port congestion disrupting sorbitol derivative shipments. Distribution runs through direct procurement relationships between bakery chains and certified tollers displacing traditional ingredient distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gluten-free sugar syrup market functions as a regulatory-moat arena where FDA and EU certification entrenchment creates switching costs that lock industrial buyers into validated supplier relationships.
For Market Incumbents: Insulate market position by deepening backward integration into captive organic brown rice and tapioca starch processing assets in Thailand and Vietnam. Prioritize segregated gluten-free production line capex to preempt six-to-nine-month Gluten-Free Certification Organization audit backlogs that threaten seasonal bakery program launches. Channel control through direct tolling agreements with coastal metropolitan bakery chains reinforces switching cost advantages against emerging regional tollers. For New Entrants and Emerging Players: Pursue whitespace in paleo-positioned coconut nectar and maple syrup private label programs for US club-store channels where origin-story differentiation commands shelf-space premiums. Target beverage producer segments with flavor-infused specialty formulations for café cold-brew and craft cocktail applications that bypass commodity pricing pressure entirely. A go-to-market angle anchored in blockchain-enabled REACH traceability documentation addresses EU customs rejection risks that constrain incumbent shipment flexibility. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional tollers possessing segregated gluten-free production infrastructure and captive analytical laboratories in Germany and the Netherlands. The five-to-ten-year viability window favors processors with backward integration into certified organic raw material cooperatives and hybrid membrane filtration-enzymatic hydrolysis technology platforms. The signal to watch is FDA threshold tightening below twenty parts per million accelerating forced reformulation demand from malt-based syrup incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Starch Processing | Captive tapioca and brown rice supply secures margin control against Southeast Asian harvest volatility. |
| Segregated Gluten-Free Production Line Investment | Dedicated enzymatic reactors and CIP systems preempt certification audit backlogs stretching six to nine months. |
| Blockchain-Enabled Traceability Implementation | Batch-level documentation satisfies EU REACH requirements and prevents customs rejection at German ports. |
| Flavor-Infused Specialty Formulation Development | Torani's café and beverage channel positioning demonstrates premium pricing escape from commodity pressure. |
| Direct Tolling Agreement Expansion | Brooklyn and Portland bakery cluster contracts compress distributor margin layers and accelerate formulation feedback loops. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with ingredient procurement managers at industrial bakeries, regulatory affairs leads at certifying bodies, plant managers at enzymatic processing facilities, and category buyers at specialty retailers; alongside secondary validation through FDA gluten-free labeling guidance documents, EU REACH contaminant traceability regulations, FSSAI export compliance filings, and customs trade data on syrup shipments. Bottom-up volume triangulation against top-down market sizing anchored the analytical framework.
Forecast inputs considered sweetener source segmentation across plant-based, grain-based, fruit-based, and vegetable-based categories; end-user demand patterns spanning food manufacturers, beverage producers, bakers, and home cooks; and distribution channel dynamics through supermarkets, specialty stores, online retailers, and health stores. CAGRs were derived from regression analysis of historical volume trends against projected clean-label bakery mandate penetration and EU export compliance requirements.
Macroeconomic conditions sit as an overlay; deviation in Southeast Asian agricultural commodity prices, energy costs for enzymatic processing, and currency fluctuation affecting import-dependent European confectioners would shift the trajectory. Cross-checking against Gluten-Free Certification Organization audit queue data and EU customs rejection rates for non-compliant syrup shipments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Japan Allulose Market
Sweeteners
Polyphenol Sweetener Market
Sweeteners
Dextrose Syrup Market
Sweeteners
North America Plant-Derived and Synthetic Sugar Market
Sweeteners
India Food Sweetener Market
Sweeteners
Clarified Rice Syrup Market
Sweeteners
Maltodextrin Market
Sweeteners
Australia Allulose Market
Sweeteners
Middle East and Africa Sugar Substitutes Market
Sweeteners
Allulose Market
Sweeteners
Saudi Arabia Allulose Market
Sweeteners
Asia-Pacific Cane Sugar Market
Sweeteners
Europe Food Sweetener Market
Sweeteners
White Sugar Market
Sweeteners
Intensive Sweeteners Market
Sweeteners
United Kingdom Food Sweetener Market