
 Bag Closure Clips Market | 2026-2036
Bag Closure Clips Market Size, Share, and Industry Trends Forecast 2026-2036
Bag Closure Clips Market Outlook
Fragmentation among artisan food producers and specialty retailers is expanding the addressable customer base beyond traditional supermarket chains. Kwik Lok Corporation dominates bread-bag closure systems through its global bakery partnerships. Bedford Industries anchors the North American produce tie segment with in-house extrusion capabilities. Schutte Bagclosures competes on custom color-matching and print-on-clip branding for private-label programs.
Bag closure clips are mechanical fastening devices manufactured from polypropylene, nylon, or biodegradable polymers, designed to create repeatable seals on flexible packaging through spring tension, magnetic force, or interlocking profiles. Polypropylene clips sustain the largest volume share due to cost efficiency in high-speed bread and produce lines, while biodegradable plastics represent the fastest-expanding material category as converters respond to extended producer responsibility frameworks. Plastic clips occupy the dominant product position across commercial bakery and retail produce applications, whereas magnetic clips command premium positioning in reusable household storage systems.
EU REACH and the Single-Use Plastics Directive restrict conventional polymer formulations, compelling migration toward certified compostable alternatives. The US FDA maintains indirect food contact standards that govern resin selection and migration limits for closure devices. California's SB 54 extended producer responsibility law creates state-level compliance complexity for national suppliers. Stakeholders must monitor regulatory divergence between European chemical restrictions and US state-level packaging laws when configuring material strategies and geographic production footprints.
Market Dynamics
Converters face simultaneous pressure from EU REACH chemical restrictions and California SB 54 extended producer responsibility mandates, forcing dual-track material qualification programs that compress development cycles and raise compliance costs across polymer supply chains.
Growth Catalysts
- Biodegradable polymer substitution:Certified compostable resins are capturing share in fresh-produce packaging as bakery chains face EPR compliance deadlines. German retailers are piloting PLA-based closures in private-label bread lines.
- Food retail private-label expansion:Supermarket chains are consolidating packaging specifications across bakery and produce categories, creating volume anchors for specialized clip converters with print-on-clip branding capabilities.
- EU Single-Use Plastics Directive:The ban on conventional plastic cutlery and stirrers is expanding to closure devices, creating regulatory pull for bio-based alternatives in France and Italy.
Market Restraints
- Resin price volatility:Polypropylene feedstock costs swing with propylene monomer availability, squeezing margin on high-volume bread-bag contracts where price indexing lags spot markets by 6-9 months.
- Concentrated extrusion capacity:North American in-house extrusion capabilities are concentrated among three legacy producers, creating supply vulnerability for mid-tier converters without backward integration into resin compounding.
- Compostable certification bottlenecks:TÜV and BPI certification timelines stretch 14-18 months, blocking rapid market entry for novel bio-based formulations even where technical performance matches conventional polymers.
Strategic Opportunities
- Artisan bakery fragmentation:Specialty sourdough and craft bread producers in Portland, Melbourne, and Copenhagen are rejecting standard twist-ties, creating demand for premium printed clips at 3-4x commodity pricing.
- Reusable household systems:Magnetic closure clips are penetrating kitchen storage categories through direct-to-consumer channels, bypassing traditional food-packaging procurement entirely.
- Indian organized retail growth:Reliance Retail and D-Mart are standardizing produce packaging across their networks, importing European clip specifications that domestic converters are racing to match.
Industry Challenges
- Bio-resin processing expertise:PLA and PHA compounds require tighter temperature control during injection molding than polypropylene, and technicians with dual-material competency command 40% wage premiums in tight labor markets.
- Legacy equipment retrofit costs:Converters running 1990s-era high-speed bread-bag lines face six-figure capital outlays to handle compostable resins without degradation or cycle-time penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bag Closure Clips Market |
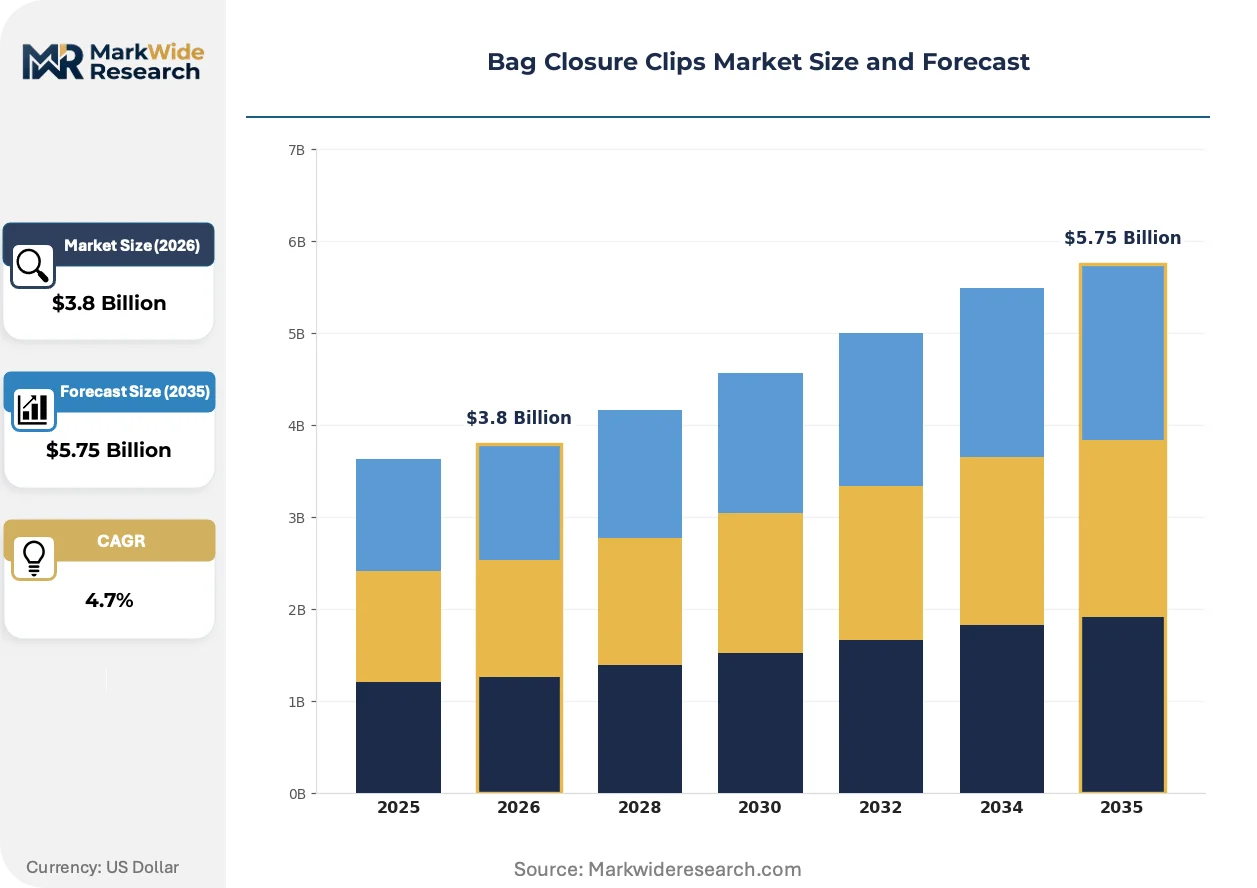
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Twist Ties, Plastic Clips, Magnetic Clips, Velcro Straps Material: Polypropylene, Nylon, Steel, Biodegradable Plastics Usage Type: Household, Commercial, Industrial, Packaging Closure Mechanism: Clip-On, Snap-On, Twist, Seal |
| Companies Covered | Kwik Lok Corporation, Schutte Bagclosures, Bedford Industries, Plas-Ties, Multivac, Tipton Corp, HSA USA Group, M&Q Plastic Products, ITW Envopak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bag Closure Clips Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are converging to rewrite polymer selection criteria, while distribution channel fragmentation is opening parallel demand tracks outside conventional food-packaging procurement.
PHA-based closure compounds are absorbing development investment from European compounders seeking drop-in replacements for fossil-derived resins. Artisan bakery chains in Denmark and the Netherlands are qualifying these materials for short-shelf-life applications where oxygen barrier requirements are less stringent. The technology is absorbing margin compression from dual-track inventory requirements as converters maintain parallel PP and bio-resin production lines.
REACH Annex XVII restrictions on intentionally added microplastics are forcing reformulation of conventional polypropylene additives. Compounders must eliminate certain lubricants and nucleating agents, degrading processing efficiency on legacy equipment. The bakery segment in Germany and France is most affected, with major retailers now requiring full material disclosure documentation upstream of contract renewal.
Direct sourcing from clip converters is displacing distributor intermediaries in mid-size produce packing operations. Regional salad processors in Spain and California are establishing direct relationships with Schutte and Bedford to secure color-matching consistency and reduce lead times. The pattern is most visible in organic produce verticals where packaging aesthetics support premium positioning at retail.
Bag Closure Clips Market Segmentation
Bag closure clip procurement diverges sharply across end-use contexts, with food-packaging automation demanding precision-engineered solutions while household storage prioritizes reusability. Material selection and closure mechanism choices cascade through manufacturing investment requirements, inventory complexity, and regulatory compliance exposure.
Product Type:
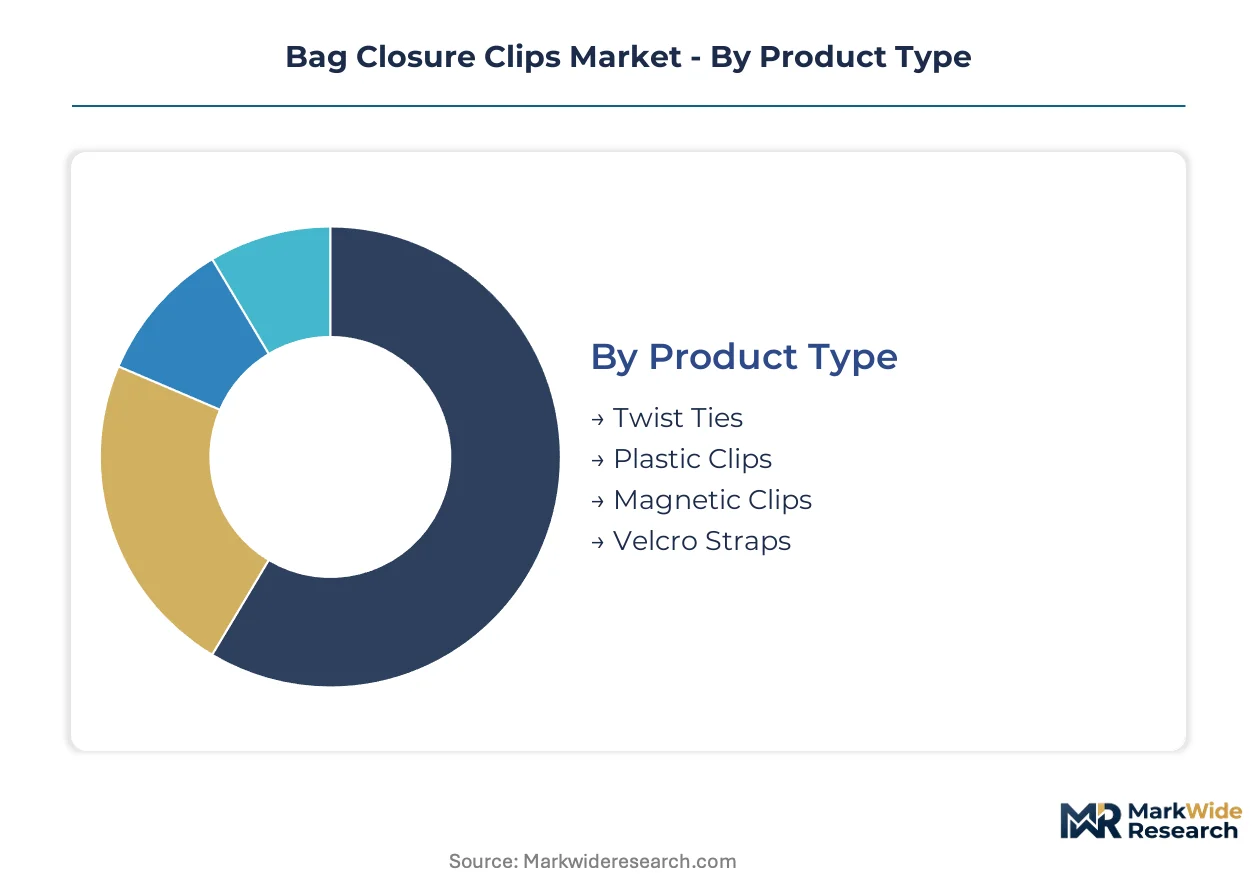
Capital intensity peaks with magnetic clips requiring rare-earth magnet integration and precision molding, while twist ties demand minimal upfront equipment.
- Plastic Clips:Injection-molded polypropylene or nylon components with spring-tension jaws designed for high-speed bakery and produce line integration. German bread-packaging clusters and North American salad processors anchor volume demand as retailers consolidate private-label specifications.
- Twist Ties:Thin metal wire cores sheathed in paper or plastic, offering lowest unit cost for commodity bread and bulk produce applications. Artisan bakery fragmentation in Portland and Copenhagen is shifting preference toward printed premium variants at elevated price points.
- Magnetic Clips:Neodymium magnet assemblies encased in polymer housings for reusable household storage systems.
- Velcro Straps:Hook-and-loop textile fasteners targeting heavy-duty industrial bundling and reusable packaging formats.
Plastic clips absorb the bulk of installed capacity; magnetic clips are expanding most quickly through direct-to-consumer channels.
Material:
Resin selection determines processing temperature windows, cycle times, and regulatory compliance pathways across converter operations.
- Polypropylene:Dominant thermoplastic offering balanced stiffness, chemical resistance, and cost efficiency for high-speed injection molding. Fresh-produce packaging lines in Spain and California run predominantly on PP formulations, though REACH Annex XVII additive restrictions are forcing reformulation investments.
- Biodegradable Plastics:PLA and PHA compounds requiring tighter temperature control and longer qualification timelines. TÜV and BPI certification bottlenecks stretch 14-18 months, yet EU Single-Use Plastics Directive compliance deadlines are pulling adoption in France and Italy.
- Nylon:Higher-performance engineering resin for temperature-resistant industrial applications.
- Steel:Core material for twist-tie wire and magnetic clip substrates.
Polypropylene commands the largest production footprint; biodegradable plastics are climbing the fastest amid extended producer responsibility mandates.
Usage Type:
Customer procurement patterns separate into high-volume contract manufacturing versus fragmented spot purchasing with diverging service requirements.
- Commercial:Food retail chains and contract packagers operating automated bread-bag and produce-line equipment. Reliance Retail and D-Mart in India are importing European clip specifications, forcing domestic converter capacity expansion.
- Household:Consumer-direct sales through kitchen storage and organization channels. Magnetic closure systems are bypassing traditional food-packaging procurement entirely via e-commerce platforms.
- Industrial:Heavy-duty bundling and logistics applications requiring tensile strength specifications.
- Packaging:Specialized converters serving branded and private-label CPG clients.
Commercial usage dominates contract value; household channels are gaining share fastest through digital distribution.
Closure Mechanism:
Mechanical design choices trade off sealing reliability, reopening convenience, and line-speed compatibility in automated environments.
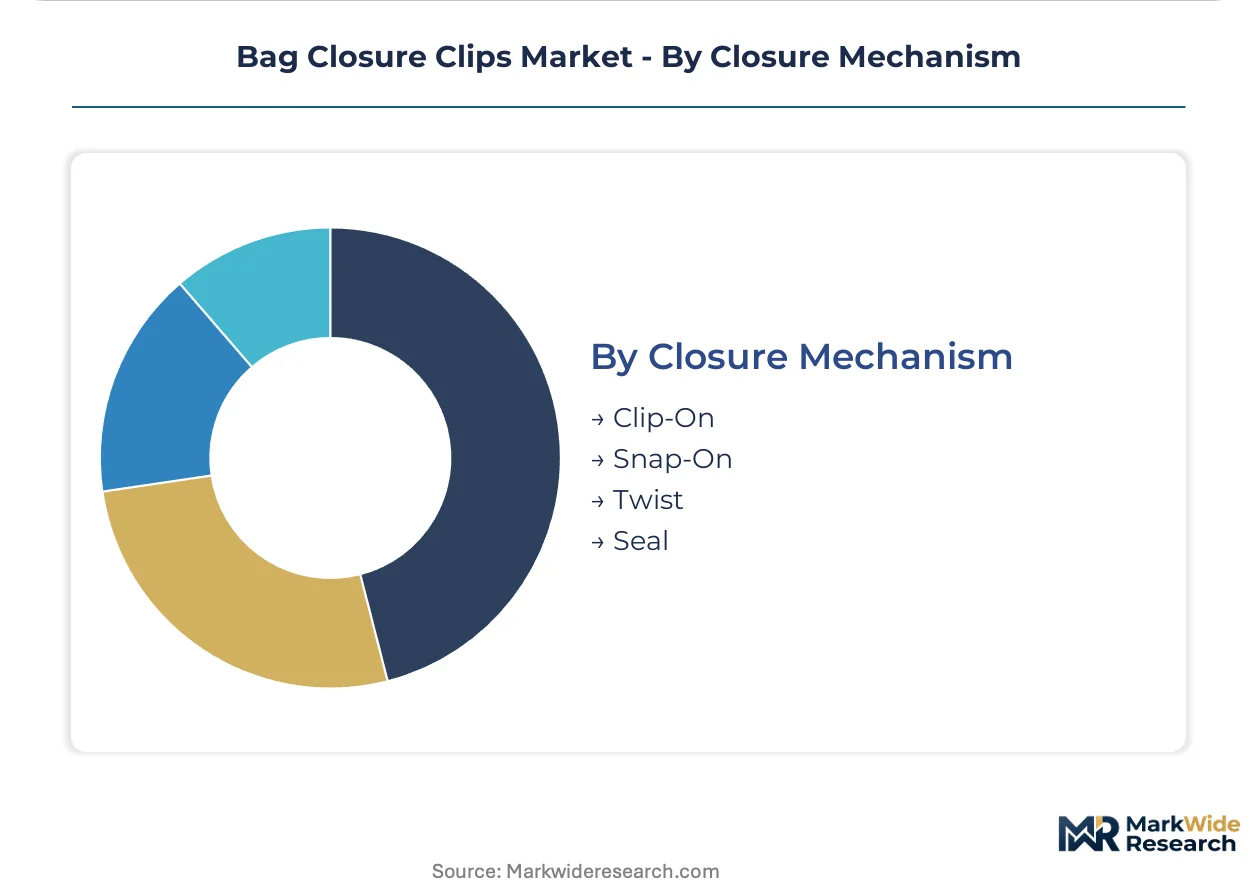
- Clip-On:Spring-loaded jaw mechanisms providing repeatable seal integrity for bakery bags. Kwik Lok Corporation's global bakery partnerships standardize this format across major retail chains.
- Twist:Manual wire-rotation sealing for commodity applications with lowest equipment integration costs.
- Snap-On:Interlocking profile closures for produce bags requiring consumer-friendly reopening.
- Seal:Permanent or semi-permanent adhesive-based closure systems for tamper-evident applications.
Clip-on mechanisms anchor industrial throughput; snap-on formats are expanding most quickly in organic produce premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates bakery and fresh-produce packaging demand through its dense network of artisan bread producers and retail chains. The country's packaging converters are navigating EPR compliance deadlines while expanding capacity for biodegradable alternatives.
Germany
Private-label bread lines at Edeka and Rewe are consolidating clip specifications across their networks. The EU Single-Use Plastics Directive is pushing converters toward TÜV-certified compostable resins by 2025. The Baden-Württemberg packaging cluster around Stuttgart hosts specialized injection molders serving both bakery and organic produce segments.
United States
California salad processors and Florida citrus packers are standardizing color-matched closure systems for premium retail positioning. The state's SB 54 extended producer responsibility law creates compliance complexity for national suppliers shipping across state lines. Bedford Industries anchors North American produce tie production through its Minnesota extrusion campus.
India
Reliance Retail and D-Mart are importing European clip specifications as they standardize produce packaging across their expanding store networks. The FSSAI maintains indirect food contact standards that govern resin selection for closure devices. Domestic converters in Maharashtra and Gujarat are racing to match imported quality benchmarks.
France
Major retail chains are requiring full material disclosure documentation upstream of contract renewal for bakery packaging. REACH Annex XVII restrictions on intentionally added microplastics are forcing reformulation of conventional polypropylene additives. The Lyon packaging corridor hosts compounders developing PHA-based drop-in replacements for fossil-derived resins.
Italy
Artisan pasta and bakery producers in Emilia-Romagna are rejecting standard twist-ties in favor of premium printed clips. The EU Single-Use Plastics Directive ban on conventional plastic cutlery is expanding to closure devices, creating regulatory pull for bio-based alternatives. Bologna-based converters are piloting PLA-based closures for short-shelf-life applications.
Bag Closure Clips Market Competitive Environment
German and Dutch specialists anchor the premium color-matching tier; North American producers hold volume positions in high-speed bread-bag automation. The vendor base separates into three strategic archetypes: integrated extrusion-injection operators, specialized branding-focused converters, and regional distributors with direct-sourcing relationships. Capacity expansion and print-on-clip technology licensing represent the dominant competitive moves as retailers consolidate specifications.
Within the integrated manufacturing tier, Kwik Lok Corporation and Bedford Industries exemplify geographic anchoring strategies—one through global bakery partnerships, the other through captive extrusion capabilities. Schutte Bagclosures occupies a position among specialized converters competing on custom color-matching and private-label branding programs. These three names represent the structural split between scale-driven automation suppliers and flexibility-focused specialists.
| Leading Market Players |
|---|
| Kwik Lok Corporation |
| Schutte Bagclosures |
| Bedford Industries |
| Plas-Ties |
| Multivac |
| Tipton Corp |
| HSA USA Group |
| M&Q Plastic Products |
| ITW Envopak |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between TÜV-certified compostable clips and conventional polypropylene variants manifests in parallel supply chain configurations. Premium bio-resin formulations command elevated procurement thresholds through extended qualification timelines, while commodity PP clips flow through consolidated extrusion-injection networks anchored in Germany and Minnesota.
Pricing Analysis
Volume-margin splits separate high-speed bread-bag contracts from artisan bakery premium positioning. Three-tier pricing structure across premium printed clips, standard private-label variants, and economy twist-ties reflects customization depth and certification burden. Cost compression in commodity PP segments intensifies because resin price indexing lags spot propylene markets by six to nine months. National supermarket chains exhibit lowest price sensitivity; specialty sourdough producers in Copenhagen and Portland absorb three-to-four-fold premiums for branded closure aesthetics.
Supply Chain Analysis
Dual-sourcing requirements from Reliance Retail and D-Mart compel Indian packagers to qualify both European importers and domestic Maharashtra converters. Raw material flows draw from Saudi propylene feedstock, German compounding expertise, and Chinese magnet substrates for household magnetic systems. Single-source vulnerability concentrates in North American in-house extrusion capacity held by legacy Minnesota producers. Distribution runs through direct converter relationships displacing distributor intermediaries in Spanish and Californian organic produce verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH additive restrictions and California SB 54 mandates are compressing development cycles, forcing sub-scale converters toward exit or acquisition as compliance costs outrun revenue bases.
For Market Incumbents: Deepen backward integration into resin compounding to capture margin compression from dual-track PP and bio-resin inventory requirements. Anchor capacity expansion in Baden-Württemberg to serve Edeka and Rewe consolidation programs while TÜV certification timelines block mid-tier entrants. For New Entrants and Emerging Players: Enter via direct-to-consumer magnetic clip channels bypassing traditional food-packaging procurement entirely. Target artisan bakery fragmentation in Melbourne and Emilia-Romagna where premium printed clips escape commodity pricing gravity. Pursue private-label branding partnerships with organic produce processors seeking color-matching consistency. For Investors and Strategic Acquirers: Re-rating potential sits with specialized converters possessing print-on-clip technology and existing TÜV/BPI certification pipelines given EU Single-Use Plastics Directive enforcement acceleration. Long-term viability favors acquisition targets with demonstrated dual-material processing competency and technician retention in tight labor markets. Monitor compostable certification backlog clearance as inflection signal for bio-resin formulation viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captures margin from volatile propylene feedstock swings across German bakery supply contracts. |
| Print-on-Clip Technology Licensing | Enables private-label branding for Edeka and Rewe consolidation programs in Baden-Württemberg. |
| TÜV Certification Pipeline Investment | Accelerates market entry for PLA and PHA formulations ahead of EU directive deadlines. |
| Direct-to-Consumer Channel Development | Bypasses traditional produce-procurement intermediaries through magnetic clip e-commerce platforms. |
| Dual-Material Processing Capability Buildout | Addresses technician scarcity commanding forty percent wage premiums in tight labor markets. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with bakery procurement managers, produce packaging engineers, converter plant managers, and retail category buyers. ECHA REACH restriction updates, FDA indirect food contact guidance, and California SB 54 implementation timelines provided regulatory boundary conditions. Bottom-up volume builds from injection molding capacity utilization and top-down demand estimates from retail chain private-label expansion programs underwent iterative triangulation.
Granularity-level modeling distinguished polypropylene from biodegradable plastic formulations, clip-on from twist closure mechanisms, and commercial from household usage channels across the projection horizon. Segment-level CAGRs derived from elasticity-adjusted volume projections and price trajectory assumptions. Resin price volatility indices, certification timeline distributions, and equipment retrofit cost curves informed industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Single-Use Plastics Directive enforcement or propylene supply disruption scenarios. Deviation in compostable resin processing yield rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Morocco Plastic Caps and Closures Market
Caps and Closures
Cuvette Caps Market
Caps and Closures
Spout Closures Market
Caps and Closures
Tear Tab Cap Market
Caps and Closures
Germany Plastic Caps and Closures Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
France Plastic Caps and Closures Market
Caps and Closures
Peelable Lid Stock Market
Caps and Closures
Caps and Closures Market
Caps and Closures
Handheld Induction Cap Sealers Market
Caps and Closures
Twist Caps Market
Caps and Closures
Thailand Plastic Caps and Closures Market
Caps and Closures
United Arab Emirates Plastic Caps and Closures Market
Caps and Closures
Fez Caps Market
Caps and Closures
Sleeve Rubber Stoppers Market
Caps and Closures
PCR Closures Market