
 Pump Dispenser Market | 2026-2036
Pump Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Pump Dispenser Market Insights
E-commerce direct-to-consumer fulfillment is reshaping how pump dispensers reach end buyers. AptarGroup leverages its global manufacturing footprint to serve multinational cosmetics brands with customized dosing solutions. Silgan Dispensing anchors North American supply through dedicated production lines for food-grade applications. Albéa Group competes on sustainability credentials with monomaterial pump designs that simplify recycling streams.
A pump dispenser is a mechanical or electromechanical device that meters fluid through a reciprocating piston or diaphragm mechanism, typically achieving dose volumes between 0.1 mL and 5.0 mL per actuation depending on spring calibration and chamber geometry. Its primary commercial purpose is to deliver controlled, hygienic, and repeatable product doses for consumer and industrial liquids. Manual dispensers still occupy the largest volume share across food and home care applications where cost sensitivity dominates procurement decisions. Automatic and electronic dispensers are capturing faster expansion in pharmaceutical and laboratory settings where touch-free operation reduces contamination risk. Plastic remains the default material selection for mass-market cosmetics, though stainless steel variants command premium positioning in professional salon and medical environments.
FDA regulations govern pump dispensers used in pharmaceutical and food-contact applications through stringent material safety and migration testing protocols. EPA guidelines influence chemical industry specifications, particularly for dispensers handling solvents or corrosive substances. REACH and the EU Green Deal are reshaping material choices in Europe by restricting certain polymer additives and mandating recyclability disclosures. Stakeholders must monitor how evolving extended producer responsibility frameworks alter cost structures and design requirements across their served geographies.
Market Dynamics
REACH compliance and the EU Green Deal are forcing material substitutions across European pump dispenser supply chains, while refillable format adoption by cosmetics brands is compressing single-use demand. Manufacturers face simultaneous pressure to eliminate problematic polymer additives and redesign for circularity without sacrificing dosing precision.
Growth Catalysts
- Refillable format mandates:EU packaging regulations are accelerating brand adoption of reusable pump systems in personal care, creating sustained demand for durable, high-cycle components.
- Touch-free pharmaceutical protocols:Electronic dosing systems are capturing share in laboratory and clinical settings where FDA contamination-control guidelines prioritize hygienic operation.
- Germany's manufacturing corridor concentration:Dense clustering of personal care formulators in the Rhine-Ruhr region generates localized procurement pull for precision dispensing equipment.
Market Restraints
- Specialized polymer supply concentration:Engineering-grade thermoplastics suitable for food-contact and pharmaceutical pumps concentrate among a limited supplier base, exposing converters to input volatility.
- REACH additive restrictions:ECHA's expanding list of restricted substances in polymers forces reformulation cycles that extend development timelines and raise compliance costs.
- Mechanical durability limits:Spring fatigue and seal degradation in high-frequency refillable applications constrain product lifecycle claims and warranty exposure.
Strategic Opportunities
- Monomaterial design white space:Simplified recycling streams enabled by single-polymer pump constructions align with EU extended producer responsibility frameworks emerging under the Green Deal.
- Indian personal care manufacturing expansion:CDSCO regulatory harmonization and domestic production incentives are attracting multinational cosmetics brands seeking localized supply.
- Smart dosing convergence:Integration of IoT-enabled actuation counters with electromechanical pumps creates value-added data services for adherence-tracking pharmaceutical applications.
Industry Challenges
- Polymer science talent scarcity:Formulation expertise for compliant, recyclable elastomer seals and spring housings concentrates among experienced compounders with limited workforce expansion.
- Migration testing timeline compression:FDA and EFSA food-contact certification protocols require extended stability studies that delay product launches despite accelerated brand demand cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pump Dispenser Market |
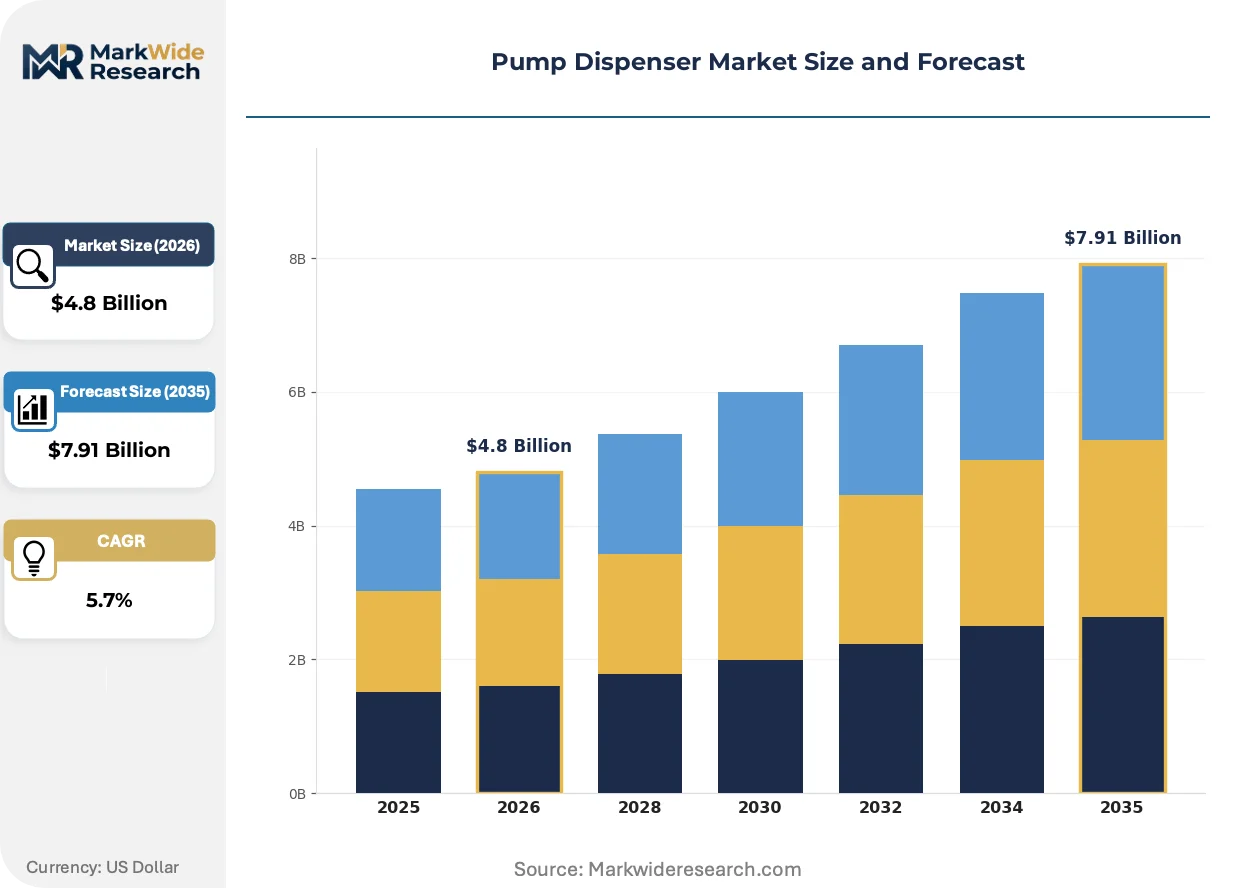
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
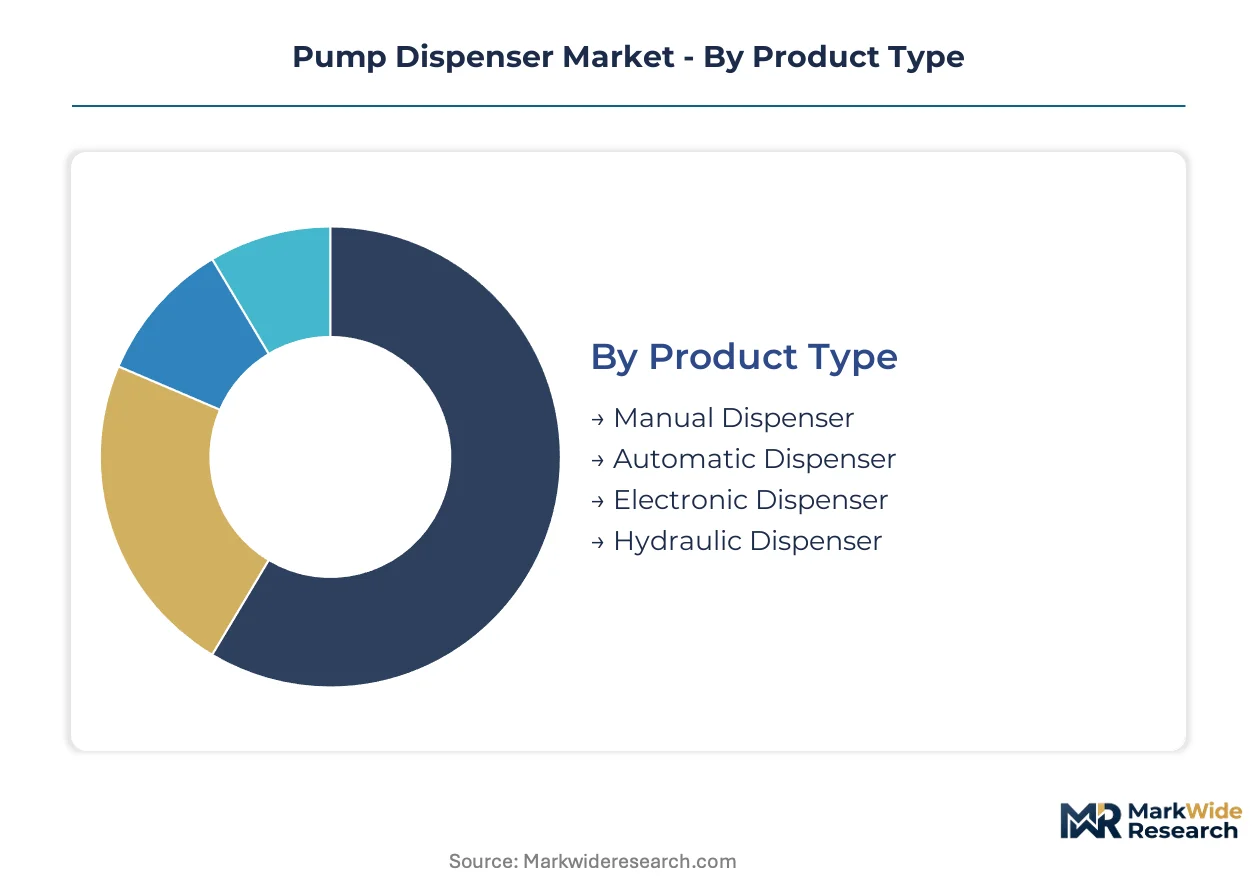
| Segmentation | Product Type: Manual Dispenser, Automatic Dispenser, Electronic Dispenser, Hydraulic Dispenser Application: Food Industry, Chemical Industry, Cosmetics, Pharmaceutical Material: Plastic, Stainless Steel, Aluminum, Glass End User: Restaurants, Manufacturing Facilities, Laboratories, Homes |
| Companies Covered | AptarGroup, Silgan Dispensing, Albéa Group, Rieke Corporation, Frapak Packaging, Coster Group, Quadpack, Guala Dispensing, Mitani Valve, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pump Dispenser Market Trends and Innovations
Electromechanical actuation and connected dosing systems are digitizing how pumps verify and record delivery, while regulatory pressure on material composition intensifies design complexity. These forces are compressing traditional mechanical-only architectures and elevating software-enabled differentiation.
Smart pump technology incorporating pressure sensors and wireless connectivity is digitizing compliance verification in pharmaceutical and clinical environments. Hospital systems and contract research organizations are piloting these systems for medication adherence monitoring. The technology is digitizing what was previously undocumented dosing behavior, creating audit trails that satisfy Joint Commission accreditation requirements.
REACH authorization processes and the EU Green Deal's packaging waste directives are restricting legacy polymer additives across European supply chains. Industrial consequences include forced substitution of phthalate plasticizers and certain flame retardants in pump components. Personal care and food-contact applications face the most acute reformulation pressure, with converters accelerating bio-based alternative qualification.
Direct-to-consumer subscription models are compressing traditional distributor intermediation in cosmetics and home care dispensing. Brands are consolidating procurement relationships to capture packaging specification control and sustainability data transparency. This channel restructuring is most visible in North American and Western European markets where e-commerce penetration in personal care has matured fastest.
Pump Dispenser Market Segmentation
Pump dispenser procurement patterns diverge sharply across operating environments, with service intensity, contamination tolerance, and actuation frequency dictating specification requirements. Understanding these segment boundaries enables suppliers to align engineering investments with margin concentration.
Product Type:
After-sales service intensity escalates dramatically from mechanical to electromechanical formats, with electronic variants requiring firmware updates, sensor calibration, and battery replacement programs that reshape supplier-customer relationships.
- Manual Dispenser:Spring-loaded piston mechanisms deliver 0.1–5.0 mL doses through reciprocating chamber compression. Demand concentrates in German personal care manufacturing corridors where REACH-compliant polymer selection dominates procurement specifications. Food and home care brands prioritize this format for cost-sensitive high-volume applications.
- Automatic Dispenser:Touch-free infrared or capacitive triggering eliminates cross-contamination in pharmaceutical and laboratory settings. FDA contamination-control protocols in US hospital systems are accelerating specification of these systems for medication adherence programs. Service contracts typically include annual sensor recalibration and actuator replacement cycles.
- Electronic Dispenser:Microprocessor-controlled dosing with IoT connectivity enables remote monitoring and dosage logging. Clinical research organizations pilot these for Joint Commission audit trails.
- Hydraulic Dispenser:Fluid-pressure actuation handles high-viscosity industrial chemicals and solvents. EPA guidelines influence material specifications for corrosive substance handling.
By volume, Manual Dispenser leads. By growth pace, Electronic Dispenser is ahead.
Application:
Margin structures compress toward commodity levels in food processing while pharmaceutical and cosmetics applications sustain premium pricing through validation documentation and customization requirements.
- Cosmetics:Precision dosing and aesthetic finish requirements drive specification complexity for premium skincare and fragrance applications. Refillable format mandates under EU packaging regulations are forcing durable component redesigns across Rhine-Ruhr manufacturing clusters. E-commerce direct-to-consumer fulfillment is compressing traditional distributor intermediation.
- Pharmaceutical:FDA material safety and migration testing protocols govern all food-contact and drug-delivery applications. Electronic dosing systems with adherence-tracking capabilities are capturing share in US hospital systems. Extended stability studies delay product launches despite accelerated brand demand cycles.
- Food Industry:FSSAI and FDA food-contact certifications require extended qualification timelines. Mass-market condiment and sauce applications prioritize cost minimization.
- Chemical Industry:Solvent resistance and corrosion tolerance dictate elastomer and housing material selection. EPA guidelines influence specifications for hazardous substance handling.
By revenue concentration, Cosmetics leads. By regulatory complexity, Pharmaceutical is expanding most quickly.
Material:
Supply-side concentration in engineering-grade thermoplastics creates input volatility, while sustainability mandates are forcing substitution cycles across European supply chains.
- Plastic:Polypropylene and polyethylene constructions dominate mass-market applications through injection-molded cost efficiency. REACH additive restrictions are forcing reformulation of phthalate plasticizers and flame retardants across EU supply chains. Monomaterial designs are emerging to simplify recycling streams under extended producer responsibility frameworks.
- Stainless Steel:304 and 316-grade variants command premium positioning in professional salon and medical environments where sterilization compatibility is mandatory. FDA pharmaceutical applications specify these for repeated autoclave cycles.
- Aluminum:Lightweight corrosion resistance suits portable and travel-format cosmetics packaging. Recyclability credentials align with EU Green Deal circularity targets.
- Glass:Chemical inertness and premium aesthetic positioning serve high-end fragrance and pharmaceutical applications. Fragility limits actuation mechanism integration.
By unit volume, Plastic leads. By sustainability-driven substitution intensity, Aluminum is climbing fastest.
End User:
Procurement authority and specification control vary dramatically across customer types, with institutional buyers demanding validation documentation that residential channels rarely require.
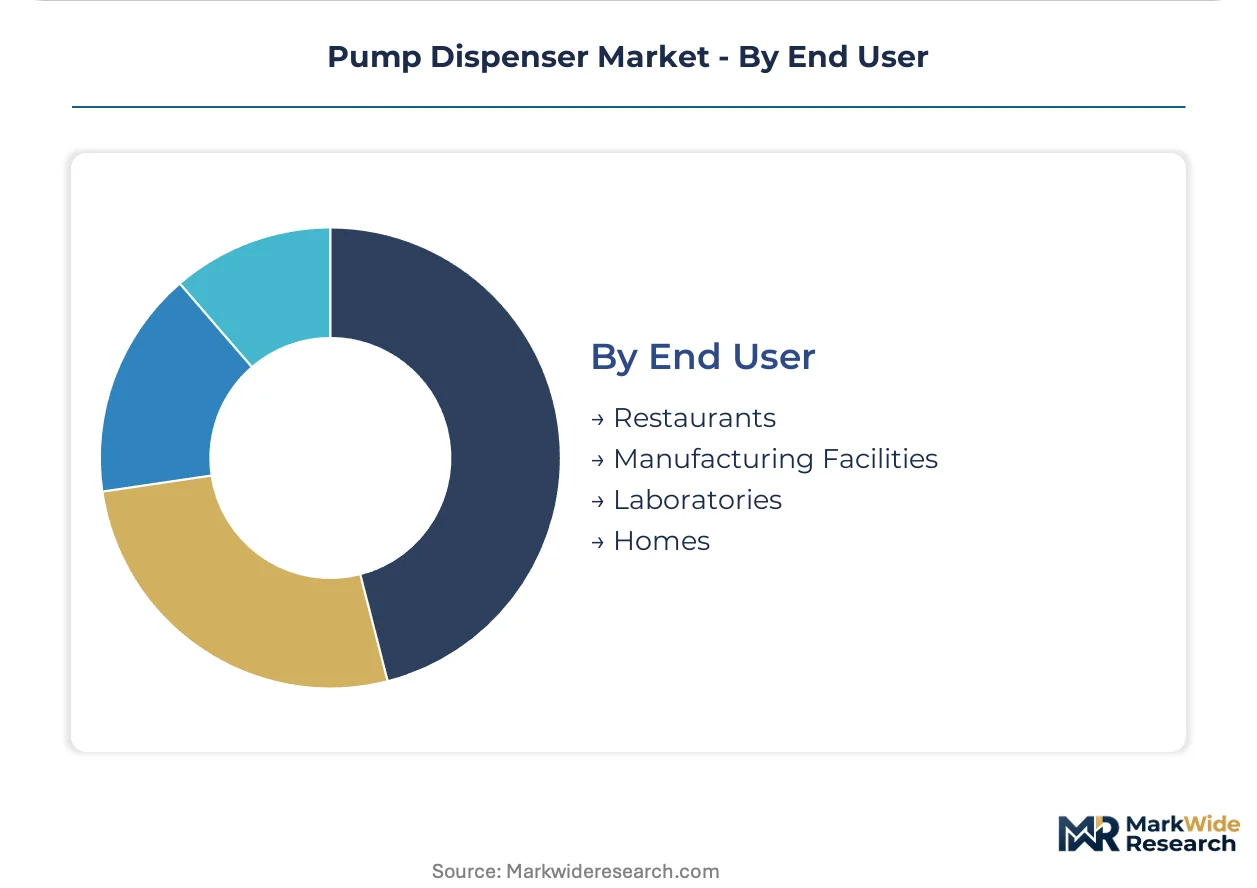
- Laboratories:Precision dosing repeatability and contamination control dominate specification requirements. Touch-free electronic systems are capturing share in clinical and research settings where FDA protocols prioritize hygienic operation. Smart pump technology with wireless connectivity creates audit trails for accreditation compliance.
- Manufacturing Facilities:High-cycle durability and maintenance accessibility drive total-cost-of-ownership calculations. Food-grade and chemical-process applications concentrate demand for specialized polymer formulations.
- Restaurants:NSF certification and ease of cleaning dominate food-service procurement. Condiment and sauce dispensing prioritizes cost minimization.
- Homes:E-commerce subscription models are consolidating brand control over packaging specifications. Direct-to-consumer fulfillment is most mature in North American markets.
By specification complexity, Laboratories leads. By channel restructuring velocity, Homes is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pump dispenser pricing power concentrates in German precision manufacturing corridors while cost-sensitive volume procurement gravitates toward Chinese injection-molding clusters. REACH compliance costs and EU Green Deal circularity mandates widen this asymmetry. Regional specialization patterns reflect divergent regulatory intensity and end-use concentration.
United States
FDA contamination-control protocols in hospital systems and pharmaceutical manufacturing drive specification of touch-free electronic dosing systems. EPA guidelines influence material selection for chemical industry applications handling solvents. Contract research organizations in the Boston-Cambridge corridor pilot smart pump technology for medication adherence monitoring and Joint Commission audit trails.
Germany
Rhine-Ruhr manufacturing clusters generate localized procurement pull for precision dispensing equipment serving personal care formulators. REACH additive restrictions force reformulation of phthalate plasticizers across polymer supply chains. Hamburg and North Rhine-Westphalia house dedicated production lines engineered for high-cycle durability in refillable cosmetic applications.
China
Domestic cosmetics manufacturing expansion and e-commerce fulfillment infrastructure create demand for cost-optimized manual dispenser formats. NMPA regulatory harmonization accelerates qualification timelines for pharmaceutical-grade components. Yangtze River Delta injection-molding clusters supply mass-market personal care brands with standardized pump architectures.
India
CDSCO regulatory alignment and PLI scheme production incentives attract multinational cosmetics brands seeking localized supply chains. FSSAI food-contact certification requirements extend qualification timelines for condiment and sauce dispensing applications. Maharashtra and Gujarat manufacturing corridors concentrate domestic formulator demand for precision dosing equipment.
France
ANSM pharmaceutical packaging standards and EU Green Deal extended producer responsibility frameworks reshape material specifications for premium fragrance applications. Île-de-France and Provence-Alpes-Côte d'Azur clusters sustain demand for aesthetic-finish pump designs in luxury cosmetics. CNIL data governance requirements influence connected dosing system architecture for clinical trial applications.
Pump Dispenser Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision-molded chambers and calibrated springs. The vendor base organizes around three archetypes: multinational packaging conglomerates with global manufacturing footprints, regional specialists serving localized regulatory requirements, and niche compounders engineering compliant elastomer formulations. Competitive maneuvering concentrates on monomaterial design patents and strategic partnerships with cosmetics brands seeking sustainability credentials.
Among diversified packaging conglomerates, AptarGroup and Silgan Dispensing exemplify platform integrators with multinational manufacturing scale. Albéa Group occupies a position within the sustainability-focused tier, representing the archetype of suppliers competing on circular design credentials. These three anchors illustrate how competitive positioning diverges between precision-engineering heritage and sustainability-led differentiation.
| Leading Market Players |
|---|
| AptarGroup |
| Silgan Dispensing |
| Albéa Group |
| Rieke Corporation |
| Frapak Packaging |
| Coster Group |
| Quadpack |
| Guala Dispensing |
| Mitani Valve |
| Others |
Pricing and Supply Chain Analysis
REACH additive authorization bottlenecks determine both the premium spread for compliant polymer formulations and the geographic reconfiguration of European supply chains toward German and French compounding hubs. Buyers face extended qualification timelines that compress standard-product margins while elevating certified-component pricing tiers.
Pricing Analysis
The customization-premium spread separates configured-to-order precision dosing systems from standardized manual dispenser architectures. Three-tier pricing structure across premium, standard, and economy levels reflects FDA certification grade and volume scale differentiation. Cost compression in mass-market food and home care tiers is intensifying because e-commerce subscription models consolidate procurement authority with brand owners. Manufacturing facilities and laboratories demonstrate the least price sensitivity due to total-cost-of-ownership calculations, while residential channels exhibit acute sensitivity to per-unit acquisition costs.
Supply Chain Analysis
Tariff exposure between Chinese injection-molding clusters and European personal care formulators dominates supply chain risk assessments for standard dispenser components. Engineering-grade thermoplastics and calibrated spring assemblies draw from German, Chinese, and South Korean production bases. Single-source vulnerability concentrates in specialized elastomer seal formulations qualified for pharmaceutical applications. Distribution runs through direct-to-consumer fulfillment centers and regional distributor networks serving manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-commerce subscription consolidation and direct brand procurement are shifting buyer power toward multinational cosmetics and pharmaceutical companies. This concentration fragments negotiating leverage among smaller regional distributors.
For Market Incumbents: Build regulatory certification moats by accelerating FDA and REACH compliance documentation for refillable high-cycle components. Deepen backward integration into polymer compounding to secure additive-compliant material streams against ECHA restriction expansions. Anchor capacity additions in Germany's Rhine-Ruhr corridor to capture localized demand from personal care formulators. For New Entrants and Emerging Players: Pursue monomaterial design white space in EU extended producer responsibility frameworks where incumbent patent portfolios remain thin. Target Indian personal care manufacturing expansion under CDSCO harmonization and PLI scheme incentives. Lead with sustainability credentials and circular design documentation as the primary go-to-market angle. For Investors and Strategic Acquirers: EU Green Deal packaging waste directives reshape the acquisition landscape by elevating targets with validated recyclable pump architectures. Five-to-ten year viability favors compounders with polymer science talent depth and established migration testing protocols. Watch ECHA authorization timeline compression as the inflection signal for compliance-cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Monomaterial Design Patent Portfolio | Single-polymer constructions simplify recycling streams under EU Green Deal circularity mandates. |
| Backward Integration into Polymer Compounding | In-house production of REACH-compliant elastomer seals reduces input volatility from specialized suppliers. |
| Smart Dosing IoT Platform Development | Wireless connectivity creates audit trails for Joint Commission pharmaceutical accreditation requirements. |
| Indian Manufacturing Footprint Establishment | CDSCO regulatory alignment and PLI incentives attract multinational cosmetics brand procurement. |
| Direct-to-Consumer Channel Partnership | E-commerce subscription models consolidate brand control over packaging specifications and sustainability data. |
Research Methodology
Initial hypotheses were tested against primary input from pump dispenser procurement managers at multinational cosmetics brands, polymer compounding technical directors, regulatory affairs leads at packaging converters, and aftermarket service heads at laboratory equipment distributors and refined through secondary validation. FDA 510(k) filings, ECHA authorization databases, EU packaging directive implementation records, and customs trade data provided foundational inputs. Bottom-up demand modeling across end-use segments triangulated against top-down market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application vertical, material composition, and end-user procurement authority. CAGRs were derived from trend extrapolation of volume and value indicators. Industry-specific forecast inputs incorporated REACH authorization timeline assumptions and e-commerce channel penetration trajectories.
Sensitivities concentrate around ECHA additive restriction expansions, FDA migration testing protocol revisions, and polymer feedstock price volatility. Forecasts reflect documented assumptions about regulatory implementation schedules and substitution technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Food Portion Pack Market
Packaging Containers
Glass Vape Cartridge Market
Packaging Containers
Bottles Market
Packaging Containers
Single Serve Packaging Market
Packaging Containers
Food Grade Bottles Market
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
Cluster Packaging Market
Packaging Containers
Telescope Box Market
Packaging Containers
Non-Corrugated Boxes Market
Packaging Containers
Gable Top Liquid Cartons Market
Packaging Containers
Slide Tray Box Market
Packaging Containers
Inverted Squeeze Bottle Market
Packaging Containers
Acrylic Boxes Market
Packaging Containers
Insulated Food Containers Market
Packaging Containers
Euro Box Market
Packaging Containers
Double Seam Bowl Market