
 Hinged Dispensing Caps Market | 2026-2036
Hinged Dispensing Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Hinged Dispensing Caps Market Foresight
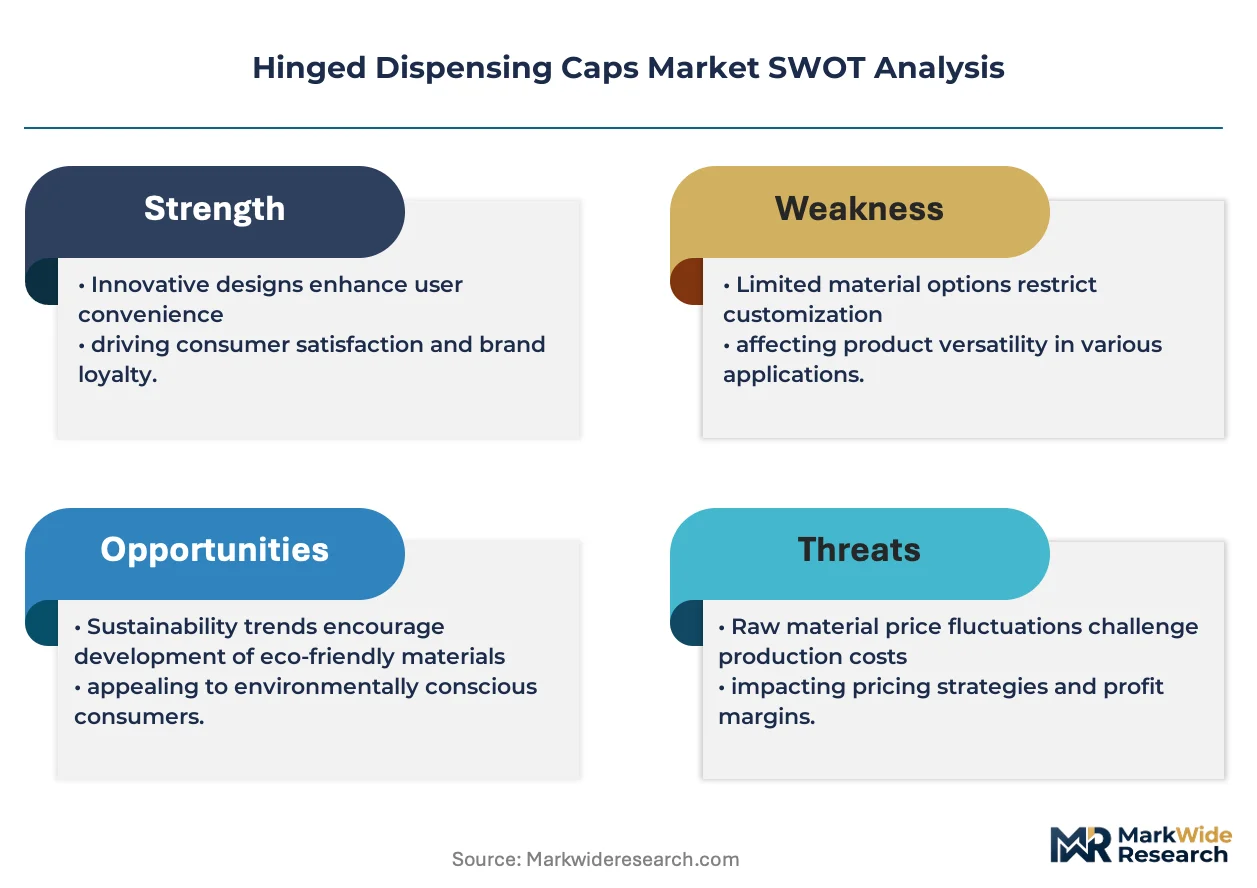
North American injection molding capacity is decoupling from traditional beverage-only applications as converters retool for pharmaceutical-grade cleanroom production. AptarGroup leverages its multi-material expertise to serve regulated drug delivery formats. Berry Global anchors North American supply through its broad thermoplastics platform. Silgan Holdings competes via metal-plastic hybrid technologies that serve dual-barrier pharmaceutical requirements.
Hinged dispensing caps are single-piece closures with an integral living hinge that permits repeated opening and resealing without component separation, typically molded from polypropylene or polyethylene with wall thicknesses of 0.3 to 1.2 millimeters to ensure flex fatigue resistance across thousands of actuation cycles. Their primary commercial purpose is to combine consumer convenience with contamination control in portable, retail-ready packaging. Plastic caps dominate unit economics due to resin cost advantages and cycle time efficiency in high-cavitation tooling, while child-resistant designs command premium positioning through specialized mold actions and compliance testing protocols. Flip-top mechanisms lead volume in personal care and pharmaceutical segments where one-handed operation drives patient adherence.
FDA 21 CFR regulations govern child-resistant effectiveness testing, while the EU MDR imposes traceability and biocompatibility standards on closures for sterile drug products. EPA and state-level extended producer responsibility frameworks in California and New York are beginning to mandate post-consumer recycled content thresholds for single-use packaging components. Stakeholders must monitor how recycled resin qualification protocols evolve alongside tightening pharmacopeial extractables testing requirements.
Market Dynamics
Pharmaceutical serialization mandates and biologics packaging complexity are compressing supplier qualification timelines while elevating cleanroom-grade polypropylene specifications across contract manufacturing networks.
Growth Catalysts
- FDA 21 CFR child-resistant mandates:Pediatric poisoning prevention rules tighten testing protocols for OTC analgesics and liquid formulations, forcing portfolio upgrades at contract packagers.
- Biologics cold-chain expansion:Temperature-sensitive monoclonal antibody delivery formats demand hinge designs that maintain seal integrity across freeze-thaw cycles without material embrittlement.
- EU MDR traceability requirements:Unique device identification on sterile closures pushes converters toward laser-markable resins and integrated QR code embossing capabilities.
Market Restraints
- Propylene feedstock volatility:North American steam cracker outages and Middle Eastern export curtailments transmit directly to polypropylene pellet pricing, squeezing converter margins on fixed-price pharmaceutical contracts.
- Cleanroom certification bottlenecks:ISO 14644 Class 7 validation queues at third-party laboratories extend qualification timelines for new resin grades, delaying product launches.
- Metal closure substitution:Aluminum screw caps with induction seals retain share in effervescent tablet and hygroscopic powder segments where oxygen barrier performance exceeds polymer capabilities.
Strategic Opportunities
- Post-consumer recycled content mandates:California and New York extended producer responsibility frameworks create first-mover advantage for converters achieving FDA food-contact equivalency certification for recycled polypropylene streams.
- Combination drug-device convergence:Auto-injector and nasal spray platforms integrate hinged dosing caps with dose-counters, opening technical partnerships between closure specialists and device OEMs.
- Direct-to-consumer pharmacy channels:Amazon Pharmacy and CVS CarePass subscription models prioritize one-handed dispensing convenience, favoring flip-top formats over traditional threaded closures in home delivery packaging.
Industry Challenges
- Extractables testing capacity constraints:USP <661.1> and <1661> migration studies face 16-20 week backlogs at qualified analytical laboratories, stalling regulatory submissions for new resin formulations.
- Multi-cavity mold maintenance expertise:Living hinge fatigue performance depends on precise gate location and cooling channel geometry, yet skilled toolroom technicians with pharmaceutical packaging experience remain scarce in Midwest manufacturing corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hinged Dispensing Caps Market |
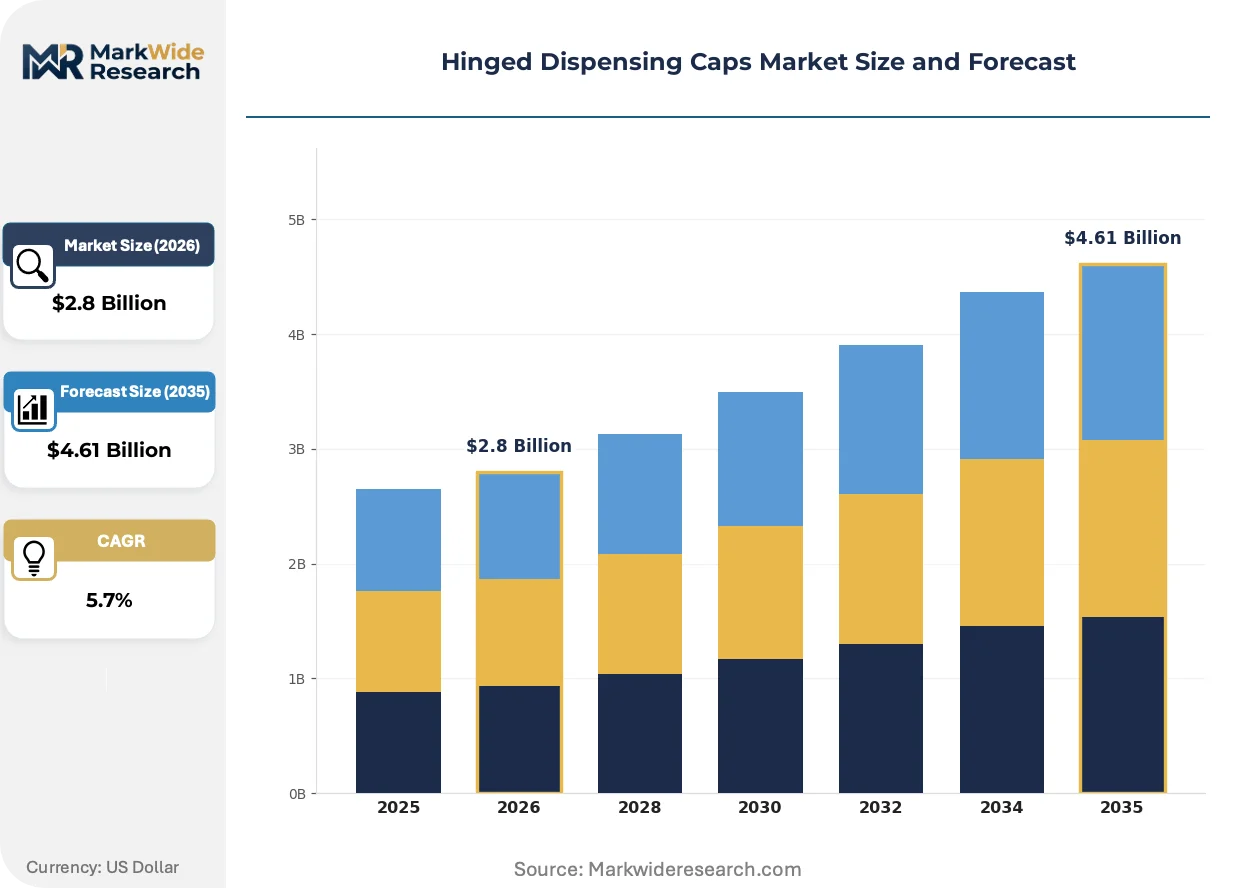
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Caps, Metal Caps, Silicone Caps, Composite Caps Closure Mechanism: Flip Top, Snap On, Screw Top, Push To Open End User: Food Industry, Beverage Industry, Pharmaceuticals, Household Products Design Style: Standard, Customized, Ergonomic, Child-Resistant |
| Companies Covered | AptarGroup Inc., Amcor plc, Silgan Holdings Inc., Albéa Group, Closure Systems International, Mold-Rite Plastics, Berry Global Inc., United Caps, Bericap GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hinged Dispensing Caps Market Shifts & Advancements
Material science breakthroughs and regulatory harmonization pressures are compressing development cycles while expanding the functional boundaries of single-piece closure architectures.
Biobased polypropylene derived from Neste renewable feedstocks is unifying carbon reduction commitments with existing pharmaceutical packaging qualification pathways. Novo Nordisk and Sanofi procurement teams have accelerated pilot programs for insulin pen and vial formats, collapsing the traditional three-year resin validation cycle into eighteen-month equivalence studies that leverage existing USP extractables databases.
REACH Annex XVII restrictions on intentionally added microplastics are compelling European converters to reformulate hinge lubricants and mold release agents ahead of 2027 enforcement deadlines. The substitution of polytetrafluoroethylene-based compounds with bio-ester alternatives affects flex fatigue performance, driving collaborative testing protocols between resin suppliers and the European Medicines Agency to establish interim biocompatibility benchmarks for affected closure designs.
Hospital and long-term care procurement consortia are consolidating supplier panels around dual-source qualified manufacturers, displacing fragmented purchasing across individual pharmacy departments. Premier and Vizient group purchasing organizations now mandate ISO 15378 certification and documented disaster recovery plans for primary packaging components, concentrating volume among converters with validated secondary production sites in geographically separated regions.
Hinged Dispensing Caps Market Segmentation
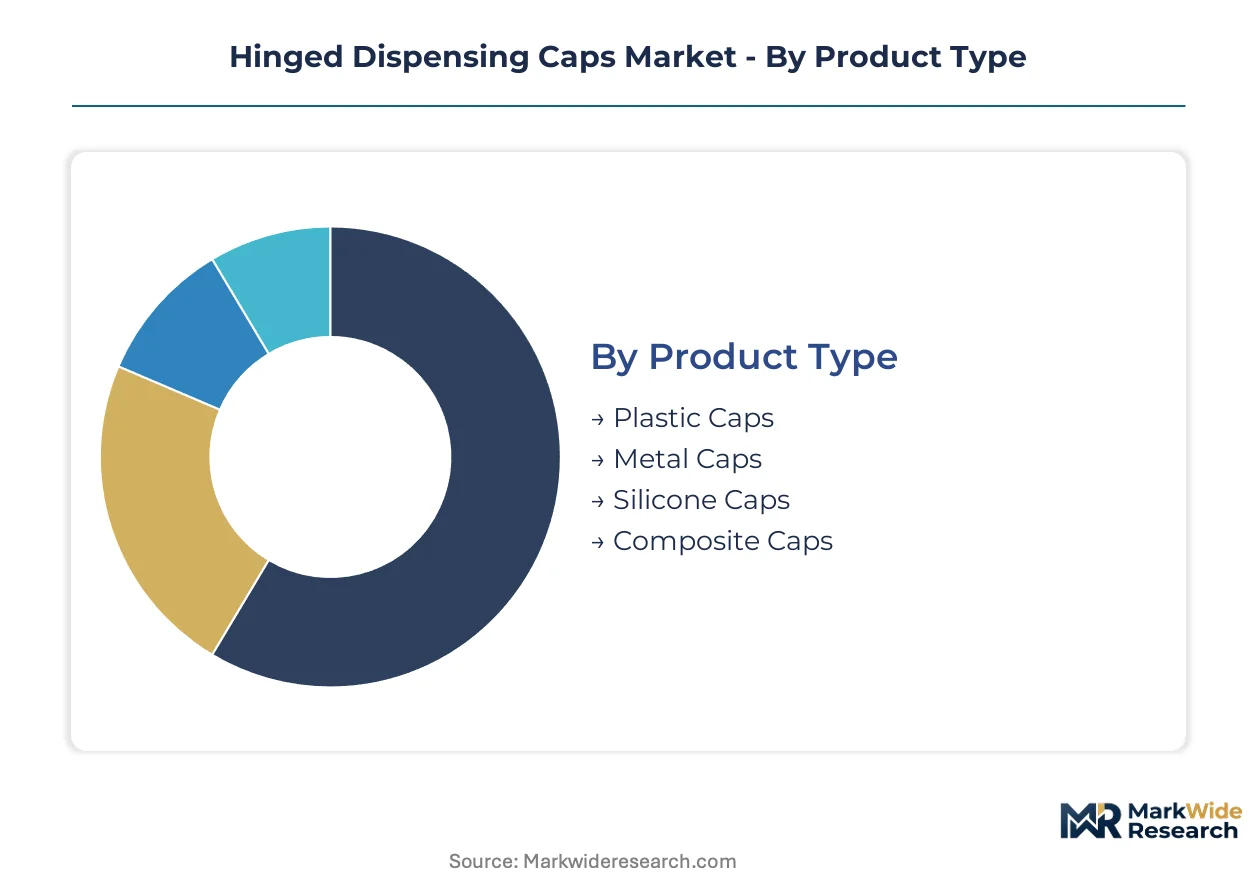
Segmentation in hinged dispensing caps reveals how material selection, mechanism design, and regulatory compliance intersect to determine pricing power and customer loyalty. Pharmaceutical and food safety mandates create divergent specification clusters that reshape converter investment priorities across each dimension.
Product Type:
Standardization dominates commodity resin grades, while pharmaceutical and barrier applications demand customized polymer formulations with validated extractables profiles.
- Plastic Caps:Polypropylene and polyethylene homopolymers deliver cycle time efficiency in 128-cavity tooling, with living hinges engineered for 10,000+ flex cycles. Demand concentrates in United States contract packaging for OTC analgesics, where FDA 21 CFR child-resistant testing mandates force continuous mold refinement.
- Metal Caps:Aluminum and tinplate hybrids with induction-seal interfaces provide oxygen and moisture barriers exceeding polymer capabilities. European effervescent tablet manufacturers in Germany and Switzerland specify these for hygroscopic formulations, though unit economics limit volume expansion.
- Silicone Caps:Medical-grade LSR (liquid silicone rubber) serves biologics vial sealing with platinum-cured purity.
- Composite Caps:Multi-material co-injection bonds rigid PP substrates with elastomeric sealing elements.
Most installed capacity flows through Plastic Caps. Expansion is steepest in Composite Caps.
Closure Mechanism:
Volume scale favors single-motion designs, while compliance requirements in regulated sectors sustain multi-step mechanisms despite user friction.
- Flip Top:Integral living hinge permits one-handed actuation with 0.3-1.2mm wall thickness optimized for fatigue resistance. Amazon Pharmacy and CVS CarePass subscription channels in the United States prioritize this format for home delivery adherence.
- Push To Open:Compression-activated dispensing suits viscous formulations and controlled dosing. German and French pharmaceutical contract packagers specify these for ophthalmic and nasal spray applications where accidental actuation risks patient safety.
- Snap On:Audible engagement confirms closure for food and beverage applications.
- Screw Top:Threaded retention dominates legacy beverage and industrial chemical packaging.
Flip Top mechanisms command the largest share of pharmaceutical-grade output. Push To Open configurations are gaining share fastest in device-integrated drug delivery.
End User:
Regulatory stringency varies sharply across sectors, with pharmaceutical and food applications demanding ISO 15378 certification that household and beverage segments rarely require.
- Pharmaceuticals:Sterile closure requirements under EU MDR and FDA 21 CFR drive cleanroom molding investments, with serialization-ready laser-markable resins becoming standard. Novo Nordisk and Sanofi procurement teams now mandate eighteen-month resin validation cycles for insulin delivery formats.
- Food Industry:FDA food-contact compliance and California extended producer responsibility frameworks push converters toward recycled polypropylene qualification. Nestle and Unilever sustainability targets accelerate pilot programs for post-consumer content integration.
- Beverage Industry:Carbonation retention and tamper-evidence dominate specification.
- Household Products:Cost-driven procurement tolerates wider specification variance.
Pharmaceuticals absorb the highest per-unit tooling investment. Food Industry demand is climbing the fastest as EPR mandates proliferate.
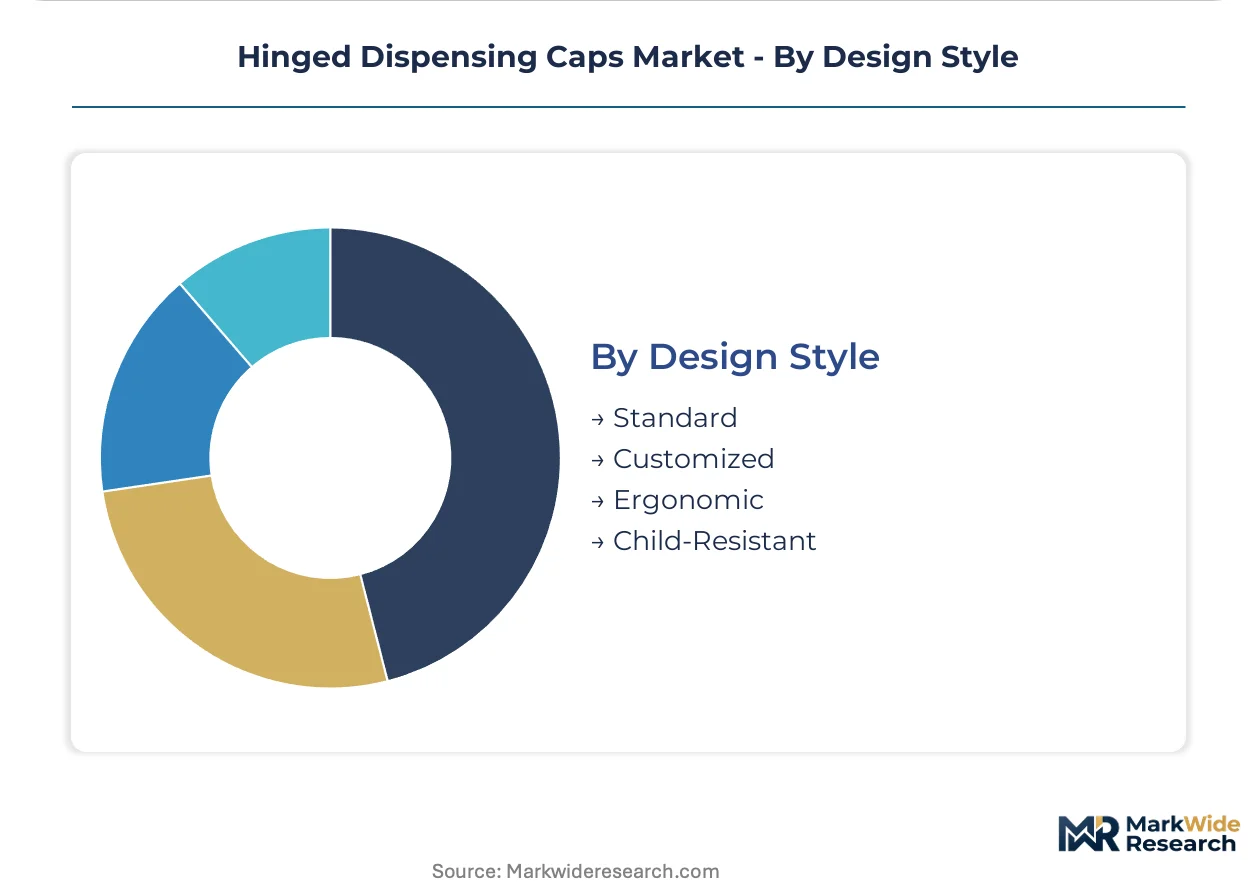
Design Style:
Patient safety regulations and aging demographics reshape design priorities, with child-resistant and ergonomic formats commanding premium positioning.
- Child-Resistant:Dual-action mechanisms requiring simultaneous push-and-turn or squeeze-and-lift motions satisfy FDA 16 CFR 1700 protocols. United States OTC analgesic and liquid formulation packagers face mandatory portfolio upgrades, with specialized mold actions adding 15-25% to tooling costs.
- Ergonomic:Contoured surfaces and reduced actuation force accommodate arthritic users and long-term care settings. Premier and Vizient group purchasing organizations in the United States now specify these for hospital formulary compliance.
- Standard:Unmodified geometries serve cost-sensitive commodity applications.
- Customized:Brand-specific embossing and color matching differentiate retail shelf presence.
Standard designs retain the broadest installed base. Child-Resistant formats are expanding most quickly as pediatric poisoning prevention rules tighten globally.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the highest per-unit tooling investment for pharmaceutical-grade hinged dispensing caps, while Germany anchors European supply through its precision molding clusters serving effervescent and biologics packaging formats.
United States
Contract packaging organizations in New Jersey and Pennsylvania are upgrading lines to serve biologics and OTC drug portfolios. FDA 21 CFR child-resistant mandates force continuous mold refinement for pediatric poisoning prevention. The Midwest manufacturing corridor around Chicago concentrates multi-cavity mold maintenance expertise, though skilled toolroom technicians remain scarce.
Germany
Effervescent tablet manufacturers specify aluminum-tinplate hybrid caps for hygroscopic formulations requiring oxygen barriers. REACH Annex XVII restrictions on intentionally added microplastics compel converters to reformulate hinge lubricants ahead of 2027 enforcement. The Baden-Württemberg region hosts collaborative testing protocols between resin suppliers and the European Medicines Agency.
China
NMPA serialization mandates compress supplier qualification timelines while elevating cleanroom-grade polypropylene specifications. The Yangtze River Delta clusters converter capacity serving both domestic pharmaceutical growth and export contract manufacturing. Shanghai-based procurement teams prioritize laser-markable resins for traceability compliance.
India
CDSCO tightening of packaging standards for sterile drug products drives adoption of ISO 15378-certified closures. Maharashtra and Gujarat house expanding contract manufacturing networks serving global generic pharmaceutical supply chains. Mumbai procurement consortia now mandate documented disaster recovery plans for primary packaging components.
Switzerland
Swissmedic biocompatibility standards for sterile closures push converters toward integrated QR code embossing capabilities. The Basel pharmaceutical cluster demands hinge designs maintaining seal integrity across freeze-thaw cycles for temperature-sensitive monoclonal antibody delivery. Novartis and Roche procurement teams have accelerated pilot programs collapsing traditional resin validation cycles.
Hinged Dispensing Caps Market Competitive Landscape
United States producers anchor one tier; German and Swiss specialists hold premium positioning through precision molding expertise for regulated pharmaceutical formats. The supplier base concentrates around three strategic archetypes: diversified packaging conglomerates with multi-material platforms, mid-cap converters with pharmaceutical cleanroom certifications, and metal-plastic hybrid specialists serving dual-barrier requirements. Competitive moves center on backward integration into resin compounding and geographic expansion through validated secondary production sites.
Within the diversified conglomerate tier, AptarGroup and Berry Global exemplify multi-material expertise serving regulated drug delivery formats. Silgan Holdings occupies a position among metal-plastic hybrid specialists. These three represent distinct competitive anchors: AptarGroup exemplifies multi-material drug delivery capabilities, Berry Global anchors North American thermoplastics supply breadth, and Silgan Holdings sits within the dual-barrier pharmaceutical segment.
| Leading Market Players |
|---|
| AptarGroup Inc. |
| Amcor plc |
| Silgan Holdings Inc. |
| Albéa Group |
| Closure Systems International |
| Mold-Rite Plastics |
| Berry Global Inc. |
| United Caps |
| Bericap GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
Toolroom technicians with pharmaceutical packaging expertise in the Midwest manufacturing corridor command wage premiums that widen spreads between ISO 15378-certified premium tiers and uncertified commodity supply. Labor-cost differentials between cleanroom-qualified and standard injection molding operations feed directly into pricing stratification across child-resistant, ergonomic, and standard design categories.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard polypropylene caps while pharmaceutical-grade cleanroom output holds firm. Three-tier pricing structure across premium certified, mid-tier validated, and economy commodity levels separates FDA 21 CFR-compliant child-resistant mechanisms from basic flip-top formats. Cost compression in standard resin grades intensifies because contract packagers consolidate volume around dual-source qualified manufacturers. Hospital procurement consortia exhibit lowest price sensitivity; household product distributors remain most responsive to per-unit differentials.
Supply Chain Analysis
Skilled mold maintenance technicians remain scarce in Midwest manufacturing corridors and Baden-Württemberg precision clusters, constraining throughput expansion for multi-cavity pharmaceutical tooling. Geographic supply concentrates in the United States, Germany, and China, with each anchoring distinct specification tiers. Raw material flows draw from North American steam crackers, Middle Eastern polypropylene exports, and Neste renewable feedstocks for biobased grades. Single-source vulnerability runs through specialized resin compounding operations qualified for USP extractables protocols. Distribution runs through contract packaging organizations and group purchasing organizations with validated secondary site requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement teams at Novo Nordisk and Sanofi collapse resin validation cycles toward eighteen-month equivalence studies. Premium specification demand from biologics cold-chain expansion reinforces pricing power for converters with ISO 15378 certification and documented disaster recovery plans.
For Market Incumbents: Extend cleanroom molding capacity into geographically separated secondary production sites to satisfy Premier and Vizient disaster recovery mandates. Deepen backward integration into resin compounding for laser-markable pharmaceutical grades. Metal-plastic hybrid specialists threaten share in effervescent tablet segments; anchor position through biobased polypropylene pilot programs with collapsed validation timelines.
For New Entrants and Emerging Players: Contract packaging organizations in India's Maharashtra and Gujarat corridors offer the most penetrable entry path. Target CDSCO-sterile packaging upgrades among generic pharmaceutical exporters lacking ISO 15378 certification. Pursue technical partnerships with device OEMs for auto-injector and nasal spray combination products where dose-counter integration creates specification stickiness.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap converters with pharmaceutical cleanroom certifications but undiversified geographic footprints. Five-to-ten year viability hinges on achieving FDA food-contact equivalency for post-consumer recycled polypropylene streams ahead of California and New York extended producer responsibility enforcement. Watch for REACH Annex XVII reformulation completion as inflection signal for European hinge lubricant substitution winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO 14644 Class 7 validation queues at third-party laboratories extend qualification timelines, creating first-mover advantage for converters with in-house certification capabilities. |
| Biobased Resin Qualification | Neste renewable feedstock pilot programs at Novo Nordisk and Sanofi collapse traditional three-year resin validation cycles into equivalence studies leveraging existing USP databases. |
| Post-Consumer Recycled Content Integration | California and New York extended producer responsibility frameworks mandate recycled polypropylene thresholds, favoring converters achieving FDA food-contact equivalency certification. |
| Device OEM Technical Partnership | Auto-injector and nasal spray platforms integrate hinged dosing caps with dose-counters, opening recurring revenue streams through combination drug-device convergence. |
| Geographic Secondary Site Validation | Premier and Vizient group purchasing organizations mandate documented disaster recovery plans, concentrating volume among converters with validated production sites in separated regions. |
Research Methodology
Multiple input streams — regulatory filing analysis, trade data reconciliation, and primary stakeholder engagement — were reconciled through bottom-up and top-down triangulation. Conversations with contract packaging executives, pharmaceutical procurement leads, toolroom operations managers, and resin supplier technical directors informed operational assumptions. Secondary validation drew from FDA 21 CFR guidance documents, EU MDR implementation texts, USP extractables protocols, and state-level extended producer responsibility frameworks.
Historical volume trajectories were cross-referenced against panel input from mold maintenance technicians and cleanroom operations specialists to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include closure mechanism type, material grade tier, end-use regulatory cluster, and geographic production hub. CAGRs were derived from elasticity-adjusted demand curves incorporating biologics cold-chain expansion rates and pharmaceutical serialization mandate compliance timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to propylene feedstock volatility, cleanroom certification bottlenecks, and metal closure substitution in hygroscopic formulations. Forecasts reflect documented assumptions about resin qualification pathway durations and regulatory enforcement calendars. Material deviation in REACH Annex XVII reformulation deadlines, FDA recycled content equivalency rulings, or USP extractables testing capacity expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Laminated Tube Closure Market
Caps and Closures
Spray Caps Market
Caps and Closures
PCR Closures Market
Caps and Closures
Nordic Plastic Caps and Closures Market
Caps and Closures
Tube Closures Market
Caps and Closures
France Plastic Caps and Closures Market
Caps and Closures
Child Resistant Dropper Caps Market
Caps and Closures
Cuvette Caps Market
Caps and Closures
Foam End Caps Market
Caps and Closures
Smooth Hinge Caps and Closure Market
Caps and Closures
Handheld Induction Cap Sealers Market
Caps and Closures
North America Plastic Caps and Closures Market
Caps and Closures
Bag Closures and Seals Market
Caps and Closures
PVC-Free Cap Liners Market
Caps and Closures
Sleeve Rubber Stoppers Market
Caps and Closures
Drum Plugs Market