
 Disposable Cups and Lids Market | 2026-2036
Disposable Cups and Lids Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Cups and Lids Market Outlook
Quick-service beverage chains is pivoting toward fiber-based hot cup systems as thermal performance standards tighten. Huhtamäki Oyj leverages its molded fiber R&D footprint across Europe and North America to sustain leadership in compostable lid innovation. Dart Container Corporation anchors the North American cold cup segment through extensive polystyrene and PET manufacturing scale. Berry Global Inc. competes via diversified plastic resin sourcing and regional distribution density.
Disposable cups and lids comprise single-use beverage containment systems manufactured from paperboard with polyethylene barriers, expanded polystyrene, polypropylene, or molded pulp derivatives, engineered to maintain liquid integrity across temperature ranges from frozen beverages to near-boiling coffee. Hot cups lead material innovation as fiber-based barrier coatings displace conventional plastic linings under regulatory pressure. Biodegradable materials represent the fastest-expanding material segment, though margin pools remain concentrated in plastic formats where scale economies and established recycling infrastructure persist. Specialty cups command premium positioning through custom printing and seasonal designs, while lid attachment mechanisms and sip-hole configurations differentiate functional performance across cafe and food truck end users.
The U.S. Food and Drug Administration governs food-contact substance migration limits, while the EPA's emerging per- and polyfluoroalkyl substances restrictions constrain fluorinated barrier coatings in fiber cups. The EU Green Deal and associated Packaging and Packaging Waste Regulation mandate extended producer responsibility and recyclability targets that reshape material selection across export-oriented suppliers. Stakeholders must monitor evolving state-level plastic prohibitions in the United States and compostability certification requirements in Europe to align capital allocation with compliance trajectories.
Market Dynamics
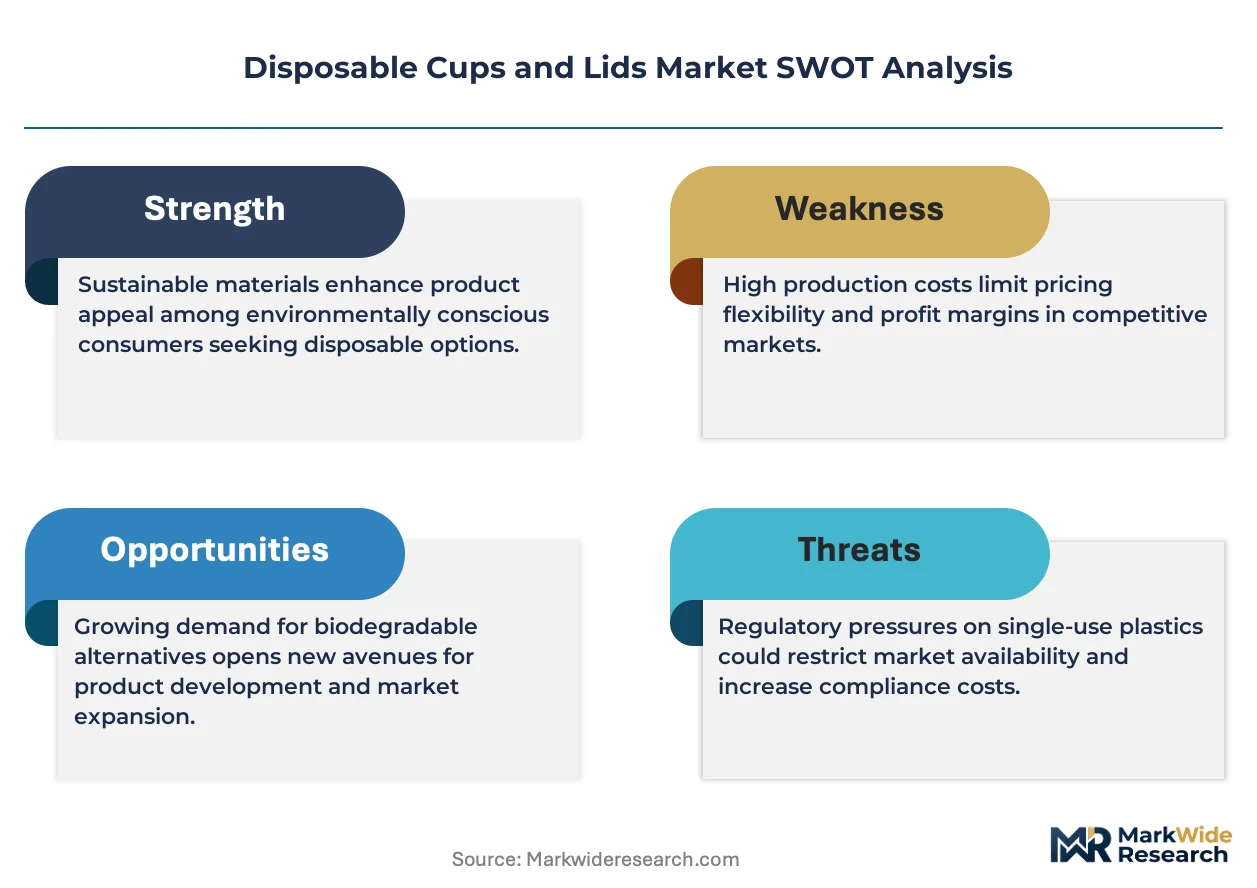
Regulatory bans on single-use plastics are compressing the addressable market for conventional polystyrene and polypropylene formats while simultaneously expanding certified compostable alternatives. This structural pressure is reallocating capital toward barrier-coated fiber R&D and regional composting infrastructure.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates force brand owners to source recyclable or compostable formats, accelerating fiber cup adoption across export-oriented suppliers.
- Quick-service beverage chains:Organized café operators in India and the United States are specifying bulk procurement of paper-based hot cups to preempt compliance costs and consumer backlash.
- Molded fiber barrier coatings:Advances in aqueous and PLA-lined technologies enable thermal performance parity with polyethylene, opening substitution pathways in premium hot beverage segments.
Market Restraints
- Pulp and resin input volatility:Kraft paperboard prices fluctuate with energy and forestry costs, squeezing converter margins and limiting price competitiveness against established plastic formats.
- Composting infrastructure gaps:Industrial composting facility density remains concentrated in Germany, the Netherlands, and select U.S. West Coast markets, rendering certified compostable cups non-compostable in most disposal environments.
- Fluorinated barrier restrictions:EPA per- and polyfluoroalkyl substances constraints eliminate proven grease-resistant coatings, forcing premature technology transitions before scalable alternatives achieve commercial validation.
Strategic Opportunities
- India urban foodservice corridors:Delivery aggregator growth and organized café expansion create bulk purchasing nodes for locally manufactured paper cups with domestic supply chain advantages.
- California and New York state-level mandates:Progressive single-use plastic prohibitions ahead of federal timelines create premium positioning windows for early-certified compostable suppliers.
- Direct-to-roaster distribution:Specialty coffee roasters are bypassing traditional broadline distributors to source custom-printed seasonal cups, enabling margin capture through design differentiation and shorter lead times.
Industry Challenges
- Barrier coating formulation expertise:Scarcity of polymer scientists with food-contact migration testing experience slows product development cycles and regulatory submission timelines.
- Certification fragmentation:Divergent compostability standards between BPI, TÜV Austria, and regional European schemes force redundant testing expenditures and inventory segmentation.
- Legacy equipment retrofit costs:Converting lines optimized for polyethylene extrusion require substantial capital reconfiguration to process aqueous or PLA barrier systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Cups and Lids Market |
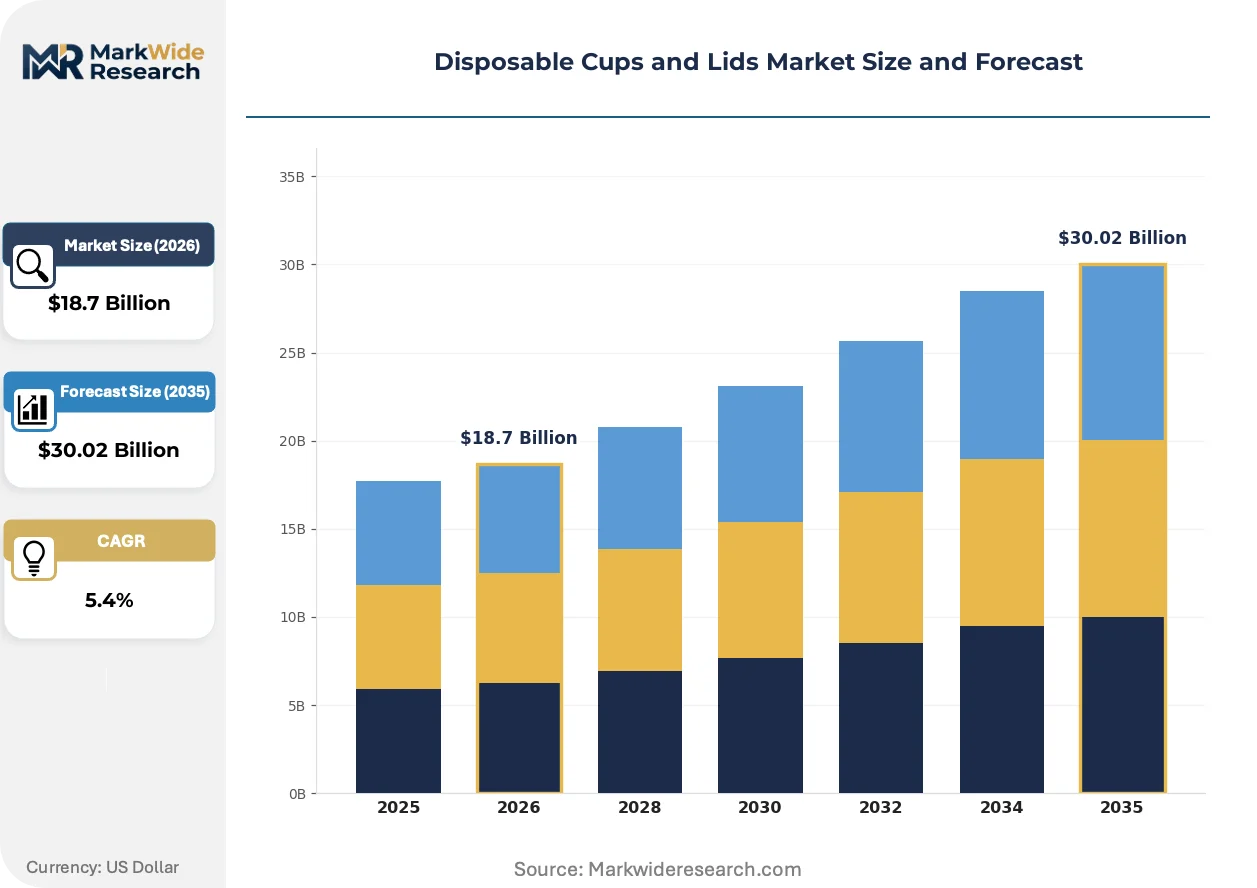
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Cups, Cold Cups, Lids, Specialty Cups Material: Paper, Plastic, Biodegradable, Styrofoam End User: Cafes, Restaurants, Events, Food Trucks Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Huhtamäki Oyj, Dart Container Corporation, Berry Global Inc., Greiner AG, Pactiv Evergreen Inc., Georgia-Pacific, WestRock Company, Graphic Packaging International Inc., Genpak LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Cups and Lids Market Strategic Shifts
Material science advances and regulatory precision are converging to redefine performance benchmarks across temperature-rated containment systems. The competitive frontier has shifted from unit cost minimization to functional certification and end-of-life verifiability.
Aqueous barrier coatings are consolidating technical validation as the successor to polyethylene-lined paperboard in hot cup applications. Quick-service chains in California and the European Union are specifying these formats for 2026 compliance deadlines. This consolidation is compressing the development timeline for alternative barrier technologies and concentrating R&D investment among suppliers with existing food-contact regulatory dossiers.
REACH restrictions on intentionally added microplastics and the EU Green Deal's recyclability targets are forcing resin selection transparency across export supply chains. Converters serving European markets must now document polymer composition and recyclability pathways to maintain shelf access. Cold cup segments reliant on PET and polystyrene face the steepest reformulation requirements, with some suppliers pivoting toward chemically recycled content to satisfy mass-balance accounting rules.
Consolidated procurement by delivery aggregators is compressing supplier margins while elevating volume predictability. India's Swiggy and Zomato platforms now negotiate direct manufacturing agreements for standardized cup formats, displacing fragmented distributor networks. This concentration is most visible in Mumbai and Bangalore, where dedicated production lines serve aggregator-specified designs with 48-hour replenishment cycles.
Disposable Cups and Lids Market Segmentation
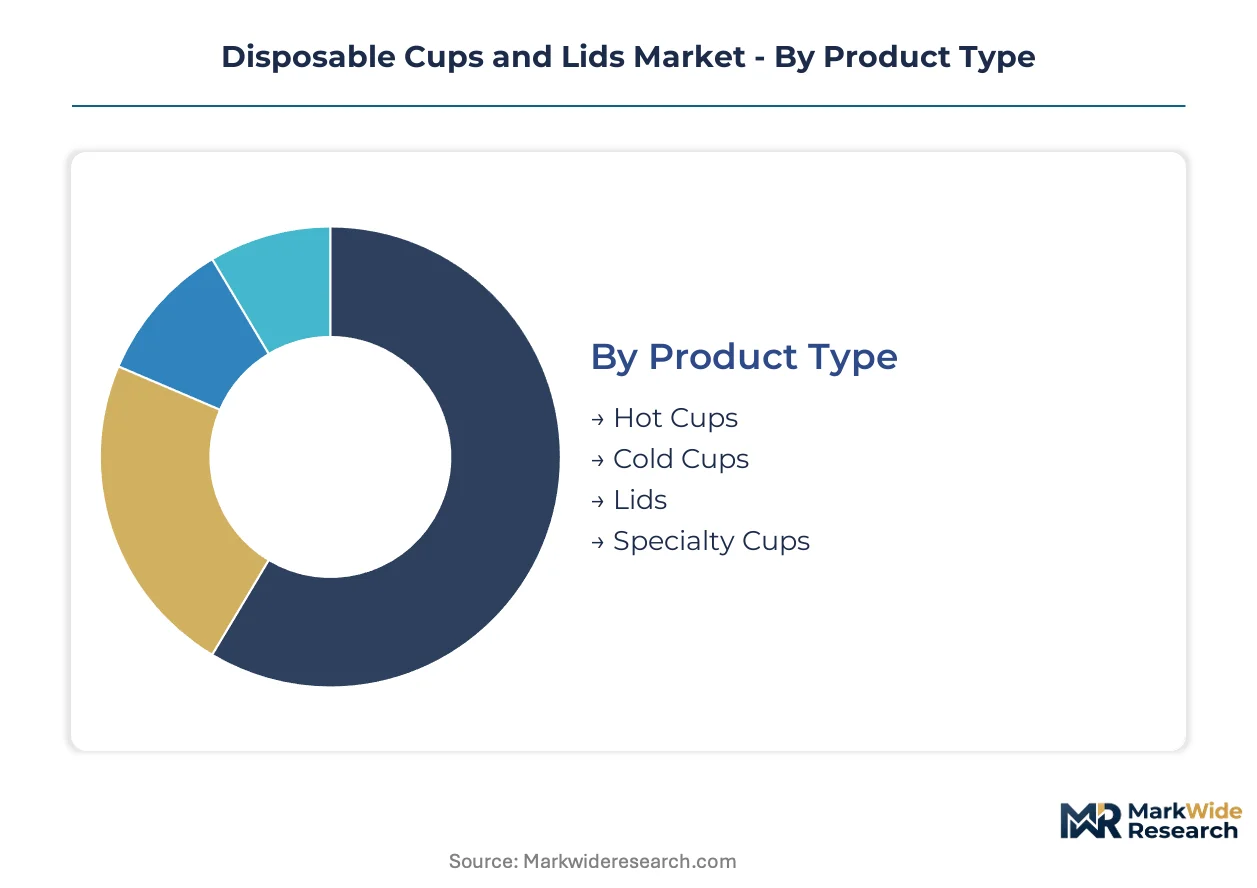
Segmentation in disposable cups and lids tracks how temperature requirements, material compliance, and channel access fragment purchasing decisions across foodservice operators. Each axis reveals distinct margin structures and capital allocation priorities for converters and distributors.
Product Type:
Temperature rating and liquid containment specifications determine barrier engineering investments and thermal performance testing protocols.
- Hot Cups:Double-walled paperboard with polyethylene or aqueous barrier coatings maintains structural integrity above 85°C. Quick-service beverage chains in California and the European Union specify these formats for regulatory compliance ahead of single-use plastic prohibitions.
- Cold Cups:Clear PET, polystyrene, or polypropylene construction prioritizes visibility and condensation resistance. India's urban foodservice corridors drive bulk procurement through delivery aggregator platforms with standardized 48-hour replenishment cycles.
- Lids:Molded fiber and plastic sip-hole configurations match cup diameter tolerances and spill-resistance standards.
- Specialty Cups:Custom-printed seasonal designs and textured finishes serve premium roasters and event caterers with shorter lead time requirements.
Hot Cups lead on scale; Specialty Cups lead on momentum.
Material:
End-of-life pathways and regulatory pressure intensity segment converter R&D budgets and certification expenditures.
- Paper:Kraft paperboard with barrier coatings dominates hot beverage containment where compostability certification unlocks shelf access in EU markets. FDA migration limits and EPA per- and polyfluoroalkyl substances constraints force coating reformulation cycles.
- Plastic:PET, polypropylene, and polystyrene retain cost advantages in cold cup segments with established recycling infrastructure. REACH restrictions on intentionally added microplastics compel resin transparency documentation across export supply chains.
- Biodegradable:PLA-lined and molded pulp derivatives carry BPI or TÜV Austria certification requirements. Industrial composting facility density gaps in most U.S. and Asian markets limit actual disposal pathway realization despite premium positioning.
- Styrofoam:Expanded polystyrene faces accelerating municipal bans while legacy manufacturing scale persists in cost-sensitive institutional channels.
Plastic leads on scale; Biodegradable leads on momentum.
End User:
Volume predictability and design customization requirements shape supplier relationship structures and contract terms.
- Cafes:Organized café chains in India and the United States negotiate direct manufacturing agreements for branded cup formats with seasonal design flexibility.
- Restaurants:Quick-service and full-service operators prioritize unit cost minimization through broadline distributor relationships with standardized SKUs.
- Events:Stadium and festival operators source high-volume, short-lead-time orders with minimal customization requirements.
- Food Trucks:Mobile operators favor compact storage formats and dual-temperature compatibility with limited inventory carrying capacity.
Cafes lead on scale; Food Trucks lead on momentum.
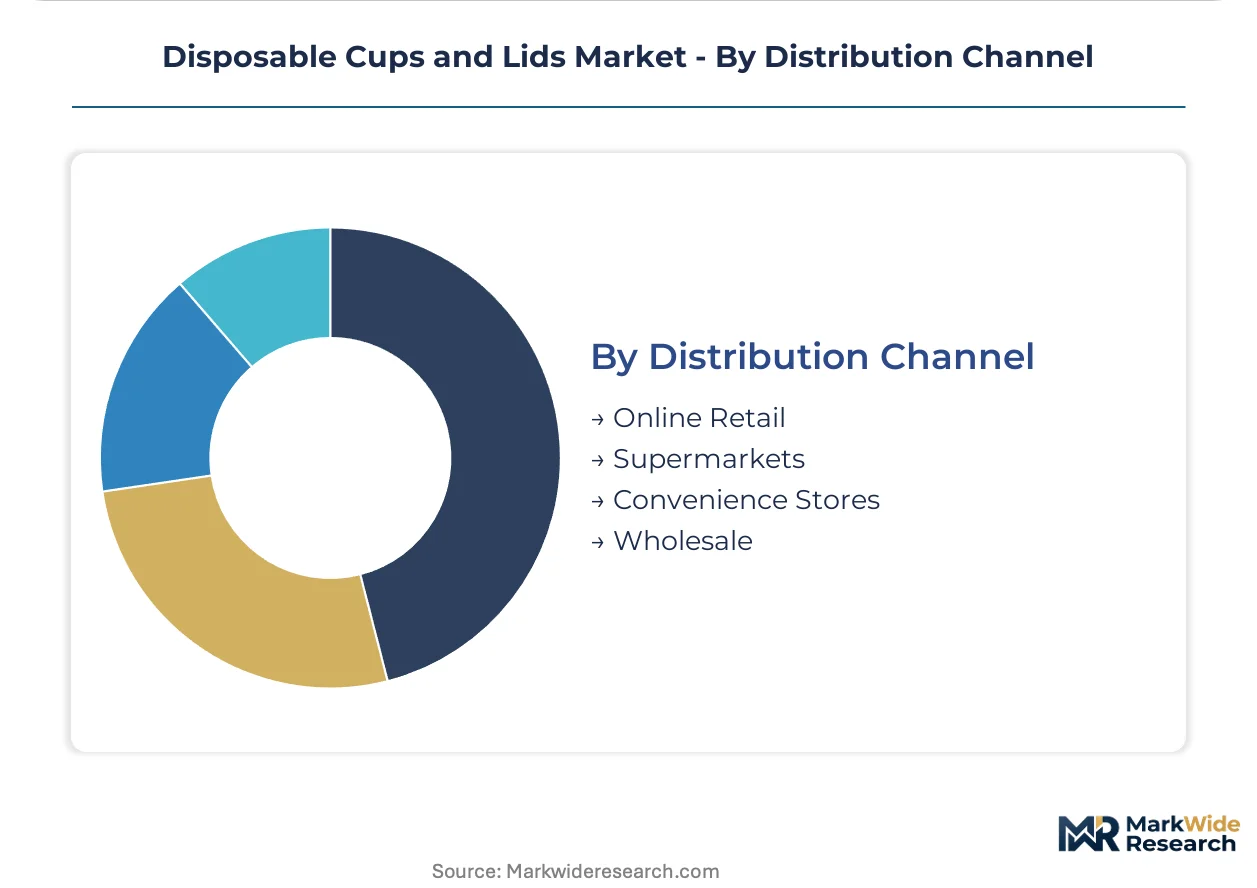
Distribution Channel:
Inventory velocity and customer acquisition costs determine margin capture and working capital intensity across channel types.
- Online Retail:E-commerce platforms serve small-batch specialty roasters and event planners with custom printing tools and rapid proofing cycles.
- Supermarkets:Mass retail chains stock private-label and branded consumer packs for home entertaining with seasonal promotional calendars.
- Convenience Stores:C-store operators prioritize grab-and-go cup-and-lid bundles with minimal shelf space requirements and high turnover velocity.
- Wholesale:Broadline distributors maintain multi-format inventory for foodservice accounts with consolidated procurement and delivery logistics.
Wholesale leads on scale; Online Retail leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's urban foodservice corridors concentrate procurement volumes for paper-based hot cup formats, with delivery aggregators and organized café chains driving bulk purchasing nodes across Mumbai, Bangalore, and Delhi-NCR.
United States
Quick-service beverage chains in California and New York are pivoting toward fiber-based hot cup systems ahead of state-level single-use plastic prohibitions. The EPA's per- and polyfluoroalkyl substances restrictions constrain fluorinated barrier coatings in fiber cups, forcing coating reformulation cycles. Los Angeles and San Francisco anchor West Coast compostable packaging procurement, with dedicated distribution networks serving café density.
Germany
Industrial composting facility density in Germany and the Netherlands enables actual disposal pathway realization for certified compostable cups. The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility, accelerating fiber cup adoption across export-oriented suppliers. Hamburg and Berlin concentrate molded fiber R&D footprints for aqueous barrier coating commercialization.
India
Organized café chains and delivery aggregators in Mumbai and Bangalore negotiate direct manufacturing agreements for standardized cup formats with 48-hour replenishment cycles. FSSAI food-contact regulations govern migration limits for paperboard barriers in hot beverage containment. Domestic supply chain advantages favor locally manufactured paper cups across Maharashtra and Karnataka urban corridors.
China
Dual carbon goals and MEE environmental enforcement are compressing polystyrene manufacturing scale while expanding PLA-lined cup production capacity. GB standards for food-contact materials govern barrier coating safety in export-oriented converter facilities. The Yangtze River Delta and Pearl River Delta concentrate molded pulp derivative manufacturing for biodegradable format expansion.
France
ANSM food-contact substance oversight and EU Green Deal recyclability targets reshape material selection for cups entering French retail channels. REACH restrictions on intentionally added microplastics compel resin transparency documentation across supply chains. The Île-de-France region anchors premium roaster procurement for custom-printed seasonal cup formats with shorter lead time requirements.
Disposable Cups and Lids Market Competitive Environment
Capacity expansion dominates the current landscape as converters reconfigure extrusion lines for aqueous and PLA barrier systems. The vendor base organizes around three strategic archetypes: integrated fiber packaging conglomerates with molded pulp R&D scale, diversified plastic resin converters with regional distribution density, and specialty converters serving direct-to-roaster custom printing demand. M&A activity concentrates on barrier coating technology acquisition, while strategic partnerships address composting infrastructure gaps in underpenetrated markets.
Among integrated packaging groups, Huhtamäki Oyj and Dart Container Corporation occupy positions representing distinct competitive vectors. Huhtamäki exemplifies the fiber-based barrier innovation archetype with European and North American R&D footprints. Dart Container anchors the scale-driven plastic format segment through established manufacturing presence. Berry Global sits within the diversified resin sourcing tier, competing via regional distribution density across multiple material platforms.
| Leading Market Players |
|---|
| Huhtamäki Oyj |
| Dart Container Corporation |
| Berry Global Inc. |
| Greiner AG |
| Pactiv Evergreen Inc. |
| Georgia-Pacific |
| WestRock Company |
| Graphic Packaging International Inc. |
| Genpak LLC |
| Others |
Value Chain & Pricing Dynamics
California's single-use plastic prohibition gates qualified supply for fiber-based hot cup systems, restricting premium-tier pricing access to converters with validated aqueous barrier coatings and BPI compostability certification. This regulatory filter concentrates margin capture among suppliers possessing established food-contact regulatory dossiers while excluding legacy polystyrene manufacturers from compliance-driven procurement channels.
Pricing Analysis
Distributor margin layers in North American foodservice channels absorb 15-25 points before wholesale pricing reaches café operators. Three-tier pricing structure across certified compostable, standard PE-lined, and economy polystyrene levels segments buyer segments by regulatory exposure and brand positioning requirements. Cost compression in standard PE-lined tiers is intensifying because kraft paperboard input volatility squeezes converter margins against fixed contract pricing. Quick-service restaurant chains exhibit lowest price sensitivity due to compliance-driven procurement mandates, while independent food trucks demonstrate highest sensitivity to per-unit differentials.
Supply Chain Analysis
Workforce availability constraints in China's Yangtze River Delta and Pearl River Delta manufacturing zones limit molded pulp derivative expansion despite PLA-lined cup capacity buildout. Supply concentration draws from China, India, and Germany for barrier-coated fiber production, with resin inputs resting on petroleum-derived polyethylene and bio-based PLA feedstocks. Single-source vulnerability in aqueous barrier coating polymer science expertise creates formulation bottlenecks. Distribution runs through broadline foodservice distributors with consolidated procurement relationships, though delivery aggregator direct manufacturing agreements in India bypass traditional channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where the EU Packaging and Packaging Waste Regulation's extended producer responsibility mandates force sustained demand migration toward certified compostable formats regardless of underlying commodity cost cycles.
For Market Incumbents: Cement barrier coating formulation expertise through captive hiring of polymer scientists with food-contact migration testing experience, locking out competitors from regulatory submission timelines. Acquire regional composting infrastructure partnerships in underpenetrated U.S. Midwest and Southeast markets to close the disposal pathway gap that threatens compostable cup value propositions. Vertical integration into kraft paperboard sourcing mitigates pulp input volatility squeezing converter margins.
For New Entrants and Emerging Players: Launch via direct-to-roaster distribution models targeting specialty coffee operators in France's Île-de-France region and California's Los Angeles basin, bypassing entrenched broadline distributor relationships. White-space concentration sits in custom-printed seasonal cup formats with 48-hour lead time capabilities, where design differentiation commands premium positioning absent from standardized aggregator procurement. Penetrate food truck mobile operator segments with dual-temperature compatible compact storage formats addressing limited inventory carrying capacity constraints.
For Investors and Strategic Acquirers: Roll-up economics work for regional barrier coating technology specialists because certification fragmentation between BPI, TÜV Austria, and European national schemes forces redundant testing expenditures that scale advantages consolidate. Long-term viability over the next decade rests on aqueous barrier coating patent estates and established food-contact regulatory dossiers. Watch for EPA per- and polyfluoroalkyl substances enforcement acceleration as the inflection signal triggering premature technology transitions and stranded asset risk in fluorinated coating-dependent facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Barrier Coating Patent Acquisition | Secures food-contact regulatory dossiers ahead of EPA fluorinated coating restrictions. |
| Industrial Composting Infrastructure Partnership | Closes disposal pathway gaps threatening certified compostable cup value propositions in underpenetrated markets. |
| Direct-to-Roaster Distribution Launch | Captures margin through design differentiation and shorter lead times bypassing broadline channels. |
| Delivery Aggregator Manufacturing Agreement | Locks volume predictability with Swiggy and Zomato platforms displacing fragmented distributor networks in India. |
| Legacy Equipment Retrofit for PLA Processing | Enables aqueous and PLA barrier system production on lines previously optimized for polyethylene extrusion. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with foodservice procurement directors, packaging converter plant managers, regulatory affairs leads at barrier coating suppliers, and sustainability officers at quick-service restaurant chains. Secondary validation drew from FDA food-contact substance filings, EPA per- and polyfluoroalkyl substances regulatory dockets, EU Packaging and Packaging Waste Regulation implementation guidance, and FSSAI food-contact compliance records. Bottom-up volume modeling triangulated against top-down macroeconomic demand indicators.
Segment-weighting approaches distributed value and volume across temperature-rated cup formats, barrier coating material platforms, and end-user channel structures throughout the projection horizon. The analytical framework modeled hot cup, cold cup, lid, and specialty cup product types against paper, plastic, biodegradable, and styrofoam material segments. CAGRs derived from regression analysis of historical procurement patterns and regulatory compliance timeline impacts. Industry-specific forecast inputs included delivery aggregator platform growth curves and municipal single-use plastic prohibition implementation schedules.
Several conditions sit outside the modeled scope, including potential breakthroughs in home-compostable barrier technologies and radical shifts in consumer disposal behavior independent of infrastructure availability. Forecasts reflect assumptions regarding regulatory enforcement consistency and industrial composting facility buildout rates. Material deviation in EPA per- and polyfluoroalkyl substances enforcement acceleration or EU Green Deal recyclability target revision warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Stackable Plastic Trays Market
Containers
Vials Market
Containers
Light Density Polyethylene (LDPE) Bottles Market
Containers
Lever Lid Tinplate Containers Market
Containers
Insert Trays Market
Containers
HDPE Blow Molding and Injection Molding Containers Market
Containers
Chest-Style Insulated Containers Market
Containers
Popcorn Containers Market
Containers
Tottle Containers Market
Containers
Hinged Lid Compostable Container Market
Containers
Pocket Containers Market
Containers
Americas Container Technology Market
Containers
Thin Wall Containers Market
Containers
Reconditioned IBC Market
Containers
Two Compartment Bottles Market
Containers
Hinged Lid Tins Market