
 Tear-Tab Lids Market | 2026-2036
Tear-Tab Lids Market Size, Share, and Industry Trends Forecast 2026-2036
Tear-Tab Lids Market Analytics
EU Single-Use Plastics Directive enforcement is hardening specifications for recyclable lid substrates across European foodservice channels. Amcor Limited leverages its integrated film-to-lid manufacturing footprint to supply compliant structures at scale. Berry Global Inc. anchors North American supply through dedicated thermoforming lines serving dairy and ready-to-drink segments. Silgan Holdings Inc. competes on metal tear-tab formats for infant formula and nutritional powders where barrier performance remains non-negotiable.
Tear-tab lids are pre-scored, partially detachable closures engineered from polypropylene, aluminum, or paperboard laminates that enable single-handed opening without complete removal from the container. Heat-seal lacquer compatibility with cup substrates and puncture resistance under steam sterilization define functional performance for shelf-stable applications. Plastic lids dominate volume due to cost efficiency in cold-fill beverage and yogurt segments, while metal tear-tabs retain premium positioning in infant nutrition where oxygen barrier properties command margin pools. Composite structures incorporating paperboard layers represent the fastest-growing category as brands pursue source-reduction targets without sacrificing rigidity.
FDA food-contact notification requirements govern resin selection and additive migration limits for U.S.-distributed tear-tab lids, while EU REACH restrictions on perfluorinated substances constrain coating chemistry options for European converters. ISO 8317 child-resistant testing protocols shape design feature development for pharmaceutical and household chemical applications. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate-specific recycling infrastructure investments to align portfolio development with collection-system realities.
Market Dynamics
EU Single-Use Plastics Directive enforcement is compressing substrate choice for converters while quick-service restaurant chains accelerate grab-and-go format expansion, creating simultaneous pull and push forces on specification engineering.
Growth Catalysts
- Ready-to-drink coffee formats:Single-serve beverage packaging in convenience channels drives specification volume for polypropylene tear-tab lids designed for cold-fill lines.
- EU Single-Use Plastics Directive:Recyclability mandates harden substrate specifications across European foodservice, forcing converter investment in compliant film-to-lid structures.
- Infant formula shelf-stable packaging:Metal tear-tab formats retain non-negotiable barrier performance requirements in nutritional powder segments.
Market Restraints
- Resin cost volatility:Polypropylene feedstock fluctuations compress converter margins on high-volume cold-fill beverage lid contracts.
- Perfluorinated substance restrictions:EU REACH constraints on coating chemistry eliminate established heat-seal lacquer options for European converters.
- Paperboard laminate technical ceiling:Steam sterilization puncture resistance limits composite structure penetration in shelf-stable dairy applications.
Strategic Opportunities
- Source-reduction targets:Composite structures incorporating paperboard layers represent white-space growth as brands pursue rigidity without weight.
- Child-resistant pharmaceutical formats:ISO 8317 testing protocol adoption creates design feature development opportunities in household chemical and pharma segments.
- Extended producer responsibility frameworks:Evolving collection-system investments in substrate-specific recycling infrastructure reward early portfolio alignment.
Industry Challenges
- Heat-seal lacquer reformulation:FDA food-contact notification timelines for new resin selections extend product development cycles.
- Additive migration compliance:Migration limit testing for U.S.-distributed lids requires specialized analytical capacity that concentrates among accredited laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tear-Tab Lids Market |
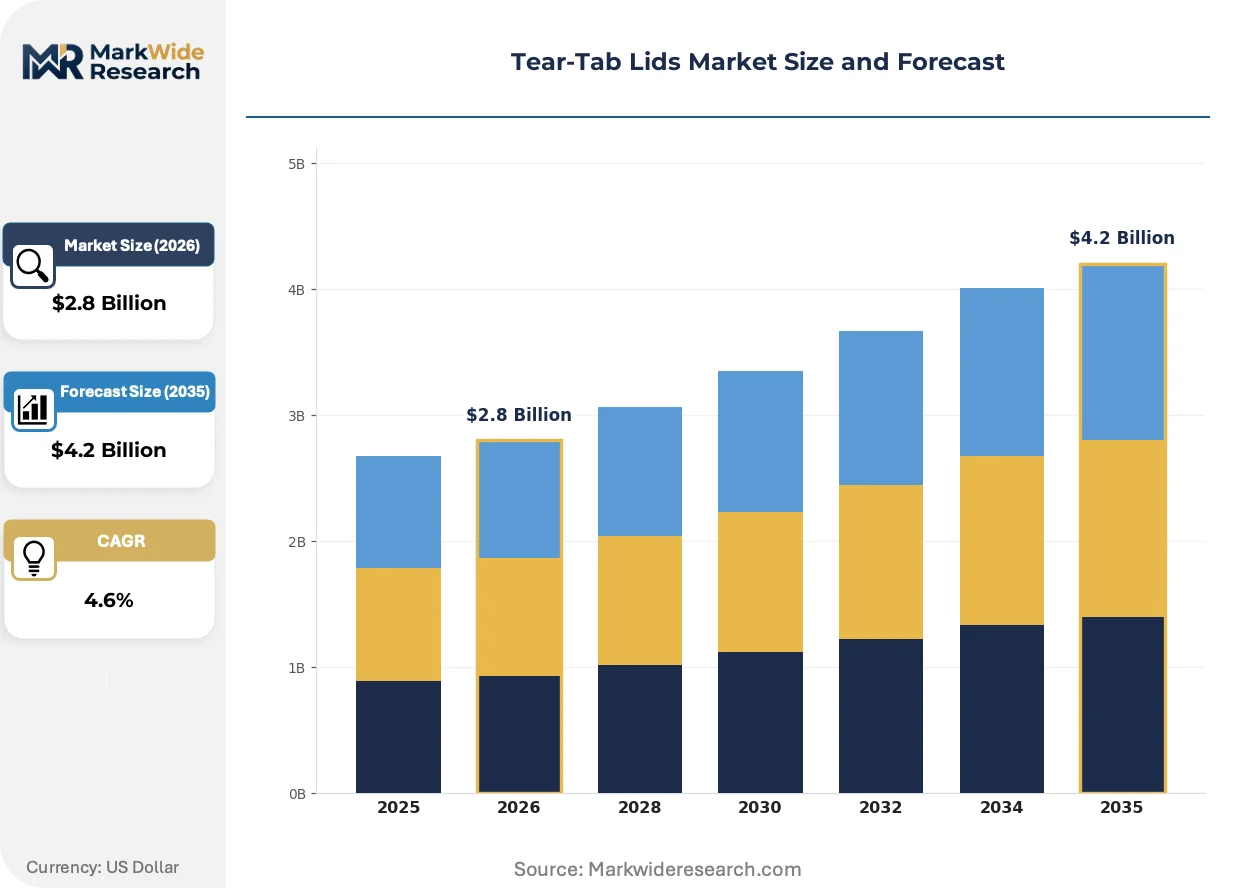
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Paperboard, Composite Closure Mechanism: Snap-On, Pull-Tab, Twist-Off, Easy Open End User: Food Industry, Beverage Sector, Pharmaceuticals, Consumer Goods Design Feature: Child-Resistant, Tamper-Evident, Leak-Proof, Ergonomic |
| Companies Covered | Essentra Pty Ltd., Aaron Packaging Inc., Letica Corporation, Amcor Limited, Crown Holdings, Inc., Silgan Holdings Inc., Sonoco Products Company, Berry Global Inc., Ball Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tear-Tab Lids Market Evolving Landscape
Material science convergence and regulatory chemistry constraints are forcing simultaneous substrate diversification and coating system reinvention across converter operations.
Paperboard-polypropylene composite laminates are decentralizing supply concentration in cold-fill beverage lids. Ready-to-drink brands in North American convenience channels are adopting these structures at pilot scale. The technology is decentralizing volume share from pure polypropylene converters toward integrated paperboard-lid manufacturers with film extrusion capabilities.
EU REACH perfluorinated substance restrictions are eliminating incumbent coating chemistries for heat-seal lacquer compatibility. Industrial consequence includes forced reformulation investment and extended FDA notification timelines for European-origin structures. Infant formula and nutritional powder segments are responding by retaining metal tear-tab formats where barrier performance overrides substrate cost considerations.
Quick-service restaurant procurement consolidation is compressing supplier qualification timelines for tear-tab lid specifications. National chain buyers are unbundling after-sales technical service from unit pricing negotiations. This pattern is most visible in United States grab-and-go format expansion where dairy and ready-to-drink coffee brands demand simultaneous cost reduction and specification customization.
Tear-Tab Lids Market Segmentation
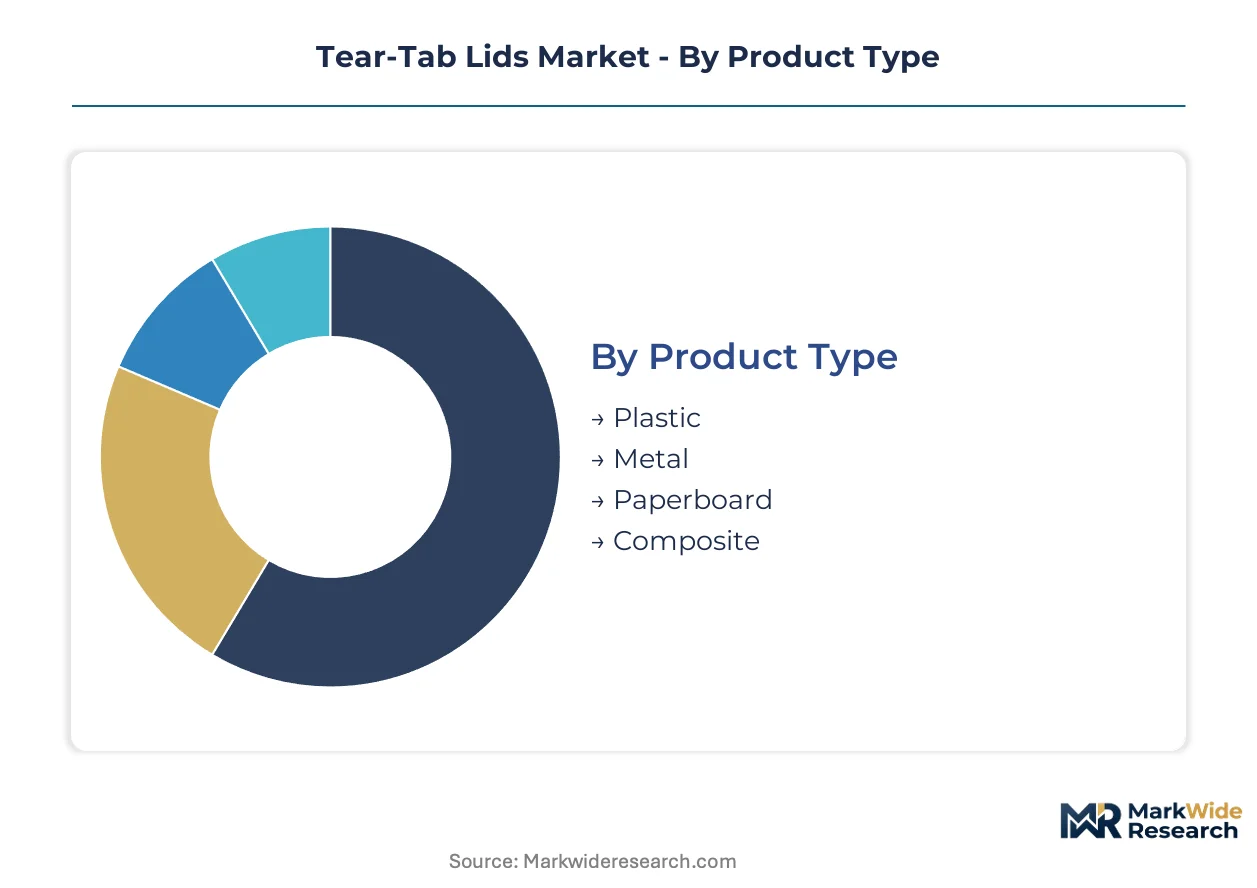
Tear-tab lid specifications diverge sharply across substrate chemistry, closure physics, and end-use sterilization requirements. Converter portfolio strategy must align material selection with the specific barrier, opening force, and regulatory compliance demands of each application cluster.
Product Type:
Substrate technology determines heat-seal compatibility, puncture resistance under retort conditions, and recyclability pathway access.
- Plastic:Polypropylene structures dominate cold-fill beverage and yogurt applications through cost efficiency and thermoformability. United States quick-service restaurant chains specify these lids for grab-and-go dairy formats where oxygen barrier demands remain moderate.
- Metal:Aluminum tear-tabs deliver non-negotiable barrier performance for infant formula and nutritional powders. Silgan Holdings anchors supply for shelf-stable segments where steam sterilization puncture resistance commands premium positioning.
- Paperboard:Source-reduction mandates drive pilot adoption in ready-to-drink coffee channels. Integrated paperboard-lid manufacturers with captive film extrusion capture emerging volume.
- Composite:Paperboard-polypropylene laminates balance rigidity against weight targets. EU Single-Use Plastics Directive recyclability specifications accelerate converter investment in these structures.
Mature deployment sits with plastic substrates across high-volume cold-fill lines. Newer deployment is concentrated in composite structures as brands pursue source-reduction without sacrificing functional performance.
Closure Mechanism:
Opening kinematics segment by end-user dexterity requirements, line speed compatibility, and tamper-evidence needs.
- Snap-On:Friction-fit engagement suits high-speed dairy filling operations. Berry Global thermoforming lines supply these mechanisms for North American yogurt and ready-to-drink segments where line efficiency dominates procurement criteria.
- Pull-Tab:Pre-scored partial detachment enables single-handed opening without complete lid removal. Convenience channel beverage brands specify this mechanism for consumption-while-mobile scenarios.
- Twist-Off:Threaded engagement delivers reclosability for multi-serve applications. Consumer goods segments favor this mechanism where portion control extends product use cycles.
- Easy Open:Reduced force thresholds address aging demographics and accessibility requirements. Pharmaceutical and household chemical applications integrate these features with ISO 8317 child-resistant testing protocols.
Volume concentration favors snap-on mechanisms in dairy processing. Specification innovation is accelerating most quickly in easy-open formats as accessibility regulations tighten across developed markets.
End User:
Application sterilization protocols and migration limit requirements segment converter technical service investments.
- Food Industry:Retort-stable lids for shelf-stable meals and sauces demand puncture resistance under 121°C steam sterilization. FDA food-contact notification governs resin and additive selection for United States distribution.
- Beverage Sector:Cold-fill polypropylene lids for ready-to-drink coffee and dairy dominate convenience channel procurement. Amcor supplies compliant film-to-lid structures at scale for this segment.
- Pharmaceuticals:ISO 8317 child-resistant testing shapes design feature development. Dual-function lids combining adult accessibility with child deterrence command specialized converter capability.
- Consumer Goods:Household chemical applications require chemical resistance and venting features distinct from food-contact specifications. REACH perfluorinated substance restrictions constrain coating chemistry options for European-origin structures.
Established converter relationships concentrate in food and beverage channels. Technical service expansion is targeting pharmaceutical formats as regulatory testing protocols proliferate.
Design Feature:
Functional differentiation segments by risk mitigation priority and user demographic targeting.
- Child-Resistant:ISO 8317 protocol compliance requires specific force thresholds and cognitive complexity in opening sequences. Pharmaceutical and household chemical segments mandate these features through national poison prevention regulations.
- Tamper-Evident:Visual or mechanical indicators of prior opening protect supply chain integrity. Infant formula brands specify these features as non-negotiable given nutritional safety sensitivities.
- Leak-Proof:Seal integrity under distribution vibration and temperature cycling prevents spoilage and liability exposure. Ready-to-drink coffee brands demand validation for inverted storage scenarios.
- Ergonomic:Grip geometry and force distribution accommodate limited dexterity and single-handed operation. Aging population demographics in Japan and Western Europe drive specification evolution.
Baseline deployment includes tamper-evidence across food and beverage applications. Ergonomic feature development is gaining share fastest as accessibility standards harden in major developed markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American tear-tab lid specification engineering through its concentration of quick-service restaurant headquarters and dairy processing infrastructure. The metropolitan corridor hosts procurement decision centers for national beverage chains that dictate substrate standards across cold-fill packaging networks.
United States
Quick-service restaurant chains headquartered in Illinois and California accelerate grab-and-go format expansion, driving polypropylene lid volume for ready-to-drink coffee. FDA food-contact notification requirements govern resin selection for distributed products. Dallas-Fort Worth thermoforming clusters supply dairy and beverage converters with dedicated production lines.
Germany
EU REACH perfluorinated substance restrictions eliminate established heat-seal lacquer chemistries for converters serving Central European markets. ECHA compliance timelines extend product development cycles for film-to-lid structures. Bavarian packaging technology clusters concentrate reformulation investment for recyclable substrate alternatives.
China
Domestic infant formula brands upgrade shelf-stable packaging specifications, sustaining demand for metal tear-tab barrier performance. SAMR food-contact standards tighten additive migration testing protocols for imported resin systems. Yangtze River Delta converter parks integrate film extrusion with thermoforming for dairy sector supply.
Japan
Aging demographics drive ergonomic easy-open lid specifications for single-serve beverage accessibility compliance. METI guidance on plastic resource circulation accelerates source-reduction targets for composite laminate structures. Kansai region dairy processors pilot paperboard-polypropylene hybrid formats for yogurt applications.
Brazil
Ready-to-drink coffee brands expand convenience channel distribution, importing specification standards from North American parent companies. ANVISA food-contact regulations align with Mercosur technical standards for polypropylene additive limits. São Paulo state thermoformers scale capacity for dairy sector cold-fill contracts.
Tear-Tab Lids Market Competitive Landscape
Premium-margin players sit above commodity-margin players across barrier performance specialization, with metal tear-tab formats commanding structural margin pools in infant nutrition while polypropylene converters compete on throughput efficiency in beverage applications. The vendor base organizes around three strategic archetypes: integrated film-to-lid manufacturers with captive resin supply, dedicated metal packaging specialists with retort sterilization expertise, and composite material innovators bridging paperboard and polymer capabilities. Dominant competitive moves include backward integration into resin compounding and strategic partnerships with quick-service restaurant procurement consortia.
Among North American diversified packaging conglomerates, Berry Global Inc., Crown Holdings, Inc., and Ball Corporation exemplify scale-driven archetypes that anchor supply relationships across beverage and foodservice channels. Berry Global occupies a position within thermoformed plastics supply for dairy applications. Crown Holdings exemplifies metal packaging specialization with historical concentration in barrier-critical segments. Ball Corporation sits within the aluminum substrate tier where oxygen impermeability commands specification premiums. These entities represent the competitive tension between commodity-scale efficiency and performance-premium positioning that defines converter strategy across regional markets.
| Leading Market Players |
|---|
| Essentra Pty Ltd. |
| Aaron Packaging Inc. |
| Letica Corporation |
| Amcor Limited |
| Crown Holdings, Inc. |
| Silgan Holdings Inc. |
| Sonoco Products Company |
| Berry Global Inc. |
| Ball Corporation |
| Others |
Value Network & Pricing Analysis
Polypropylene resin feedstock volatility propagates through three distinct pricing tiers as converters balance spot-market exposure against long-term quick-service restaurant contracts. EU REACH compliance costs for heat-seal lacquer reformulation concentrate margin pressure on European-origin structures while metal tear-tab formats retain premium positioning through infant formula barrier specifications.
Pricing Analysis
Throughput-based pricing anchors converter contracts with national beverage chains, where line-speed guarantees and technical service bundling separate premium thermoforming partnerships from commodity lid supply. Price differentiation rests on FDA food-contact certification tier and captive resin compounding capability, with integrated film-to-lid manufacturers commanding structural premiums over toll-converter competitors. Pricing pressure stems from resin cost compression in high-volume cold-fill beverage segments, where quick-service restaurant procurement consolidation intensifies unit-price negotiations. Dairy processors exhibit highest price sensitivity due to thin operating margins, while infant formula brands prioritize barrier performance over substrate cost.
Supply Chain Analysis
Extended producer responsibility frameworks are forcing reverse-logistics infrastructure investment as EU member states mandate substrate-specific collection systems for composite lid structures. Raw material supply concentrates in United States Gulf Coast polypropylene production, German chemical clusters for heat-seal lacquer formulations, and Chinese aluminum smelting for metal tear-tab formats. Converter operations draw from imported resin systems subject to SAMR additive testing protocols in China and FDA notification timelines in North America. Single-source vulnerability sits with specialized heat-seal lacquer chemistries eliminated by perfluorinated substance restrictions. Distribution runs through dairy processor co-location networks and quick-service restaurant distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Tear-Tab Lids Market operates as a cost-of-compliance arena where EU Single-Use Plastics Directive enforcement and FDA food-contact notification requirements erect regulatory moats favoring incumbent converters with accredited laboratory relationships and established resin qualification pipelines.
For Market Incumbents: Deepen backward integration into resin compounding to insulate margins from polypropylene feedstock volatility threatening high-volume beverage contracts. Prioritize ISO 8317 certification investment for pharmaceutical and household chemical lid formats, where child-resistant testing protocols create specification stickiness against emerging composite material competitors. For New Entrants and Emerging Players: Quick-service restaurant regional procurement consortia represent the most penetrable channel for composite paperboard-polypropylene lid supply, as national chains decentralize vendor qualification to reduce concentration risk. Target pilot-scale ready-to-drink coffee brands in North American convenience channels with source-reduction value propositions. Differentiate through integrated film extrusion capabilities that pure paperboard converters lack. For Investors and Strategic Acquirers: ECHA compliance timeline extensions for heat-seal lacquer reformulation are the leading indicator that European converter consolidation will accelerate as smaller players exhaust capital reserves. Frame long-term viability around substrate diversification capability across plastic, metal, and composite formats. Monitor FDA food-contact notification backlog durations as the inflection signal for U.S. market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Seal Lacquer Reformulation Investment | EU REACH compliance secures market access for European converter operations against eliminated incumbent chemistries. |
| Captive Resin Compounding Capacity | Backward integration into polypropylene supply shields margins from Gulf Coast feedstock volatility affecting commodity converters. |
| ISO 8317 Certification Acquisition | Child-resistant testing protocol compliance opens pharmaceutical and household chemical segments with specification stickiness. |
| Composite Laminate Pilot Scale-Up | Paperboard-polypropylene structures capture source-reduction demand from ready-to-drink brands pursuing sustainability targets. |
| Quick-Service Restaurant Technical Service Bundling | After-sales engineering support differentiates premium converter relationships from price-only commodity supply. |
Research Methodology
Multi-period observation of resin cost indices, regulatory filing timelines, and quick-service restaurant format expansion anchored the trend analysis, supplemented by interviews with thermoforming plant managers, dairy procurement leads, regulatory affairs directors at packaging converters, and quick-service restaurant supply chain planners. Secondary validation drew from FDA food-contact notification databases, ECHA restriction proposal tracking, SEC 10-K filings of diversified packaging conglomerates, and customs trade data for polypropylene and aluminum substrate flows. Bottom-up volume modeling across substrate types and closure mechanisms triangulated against top-down market sizing from packaging industry association reports.
Input-output matrices linked resin feedstock cost trajectories, line-speed throughput assumptions, and regulatory compliance cost burdens to volume and value projections across the analysis window. Segmentation dimensions modeled include substrate chemistry, closure mechanism physics, end-use sterilization requirements, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for format substitution effects and regulatory-driven specification shifts. Industry-specific forecast inputs incorporated quick-service restaurant grab-and-go format expansion rates and EU extended producer responsibility framework implementation schedules.
Caveats apply where FDA notification timeline extensions, ECHA perfluorinated substance restriction scope expansions, or resin supply disruptions could materially shift the outlook. Practitioners should monitor SAMR food-contact standard tightening in China and METI plastic resource circulation guidance evolution in Japan for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Ribbed Phenolic Caps Market
Caps and Closures
Fixed Length Seals Market
Caps and Closures
Foamed End Caps Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
Morocco Plastic Caps and Closures Market
Caps and Closures
Spain Plastic Cap and Closure Market
Caps and Closures
Bag Closures Market
Caps and Closures
Humidity Indicator Plugs Market
Caps and Closures
Handheld Induction Cap Sealers Market
Caps and Closures
Spray Caps Market
Caps and Closures
Disc Top Caps Market
Caps and Closures
Non-Aerosol Overcaps Market
Caps and Closures
Brush Caps Market
Caps and Closures
Resealable Closures and Spouts Packaging Market
Caps and Closures
United Kingdom Plastic Caps and Closures Market
Caps and Closures
T-Top Closures Market