
 Bag Closures and Seals Market | 2026-2036
Bag Closures and Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Bag Closures and Seals Market Outlook
Biodegradable polymer formulation is narrowing the performance gap between conventional plastics and compostable alternatives in bag closure manufacturing. Kwik Lok Corporation leverages its global distribution network to sustain leadership in bread bag clip systems across North American bakeries. Bedford Industries anchors its position through proprietary wire-twist technology that dominates fresh produce packaging channels. Schutte Bagclosures differentiates via European manufacturing scale that competes aggressively on lead times for retail-ready seal products.
Bag closures and seals are mechanical or adhesive fastening devices—typically constructed from polypropylene, polyethylene, tinplate wire, or polylactic acid blends—engineered to secure flexible packaging openings against contamination, moisture ingress, and tampering. Heat seal closures occupy the largest volume share due to their integration with automated form-fill-seal lines in food processing plants, while biodegradable materials represent the fastest-expanding segment as compostability certifications become mandatory for single-use packaging in regulated European markets. Zip lock formats command premium positioning in reusable pouch applications, whereas press seal variants serve cost-sensitive industrial bulk bag segments where resealability remains secondary to initial containment.
The FDA governs direct food-contact materials under 21 CFR 177, while the EU Packaging and Packaging Waste Regulation imposes extended producer responsibility targets that reshape material selection across export-oriented suppliers. ISO 22000 food safety management standards further filter market access for closure manufacturers serving multinational food brands. Stakeholders must monitor evolving compostability certification requirements as regulatory divergence between North American and European frameworks complicates unified product portfolio strategies.
Market Dynamics
Biodegradable polymer formulation is collapsing the performance premium that conventional polypropylene closures commanded in food packaging, forcing incumbent suppliers to accelerate material R&D or cede shelf-space to compostable alternatives certified under tightening EU Packaging and Packaging Waste Regulation mandates.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility targets are mandating compostable materials for single-use packaging, creating pull-through demand for polylactic acid blend closures across European retail channels.
- Fresh produce packaging:Wire-twist closure systems dominate bakery and fruit segments where resealability extends shelf life, with German retailers maintaining the strictest specification standards for moisture barrier performance.
- Automated form-fill-seal integration:Heat seal closures align with high-speed processing lines in food manufacturing plants, reducing labor costs and contamination risk in ready-meal and snack production.
Market Restraints
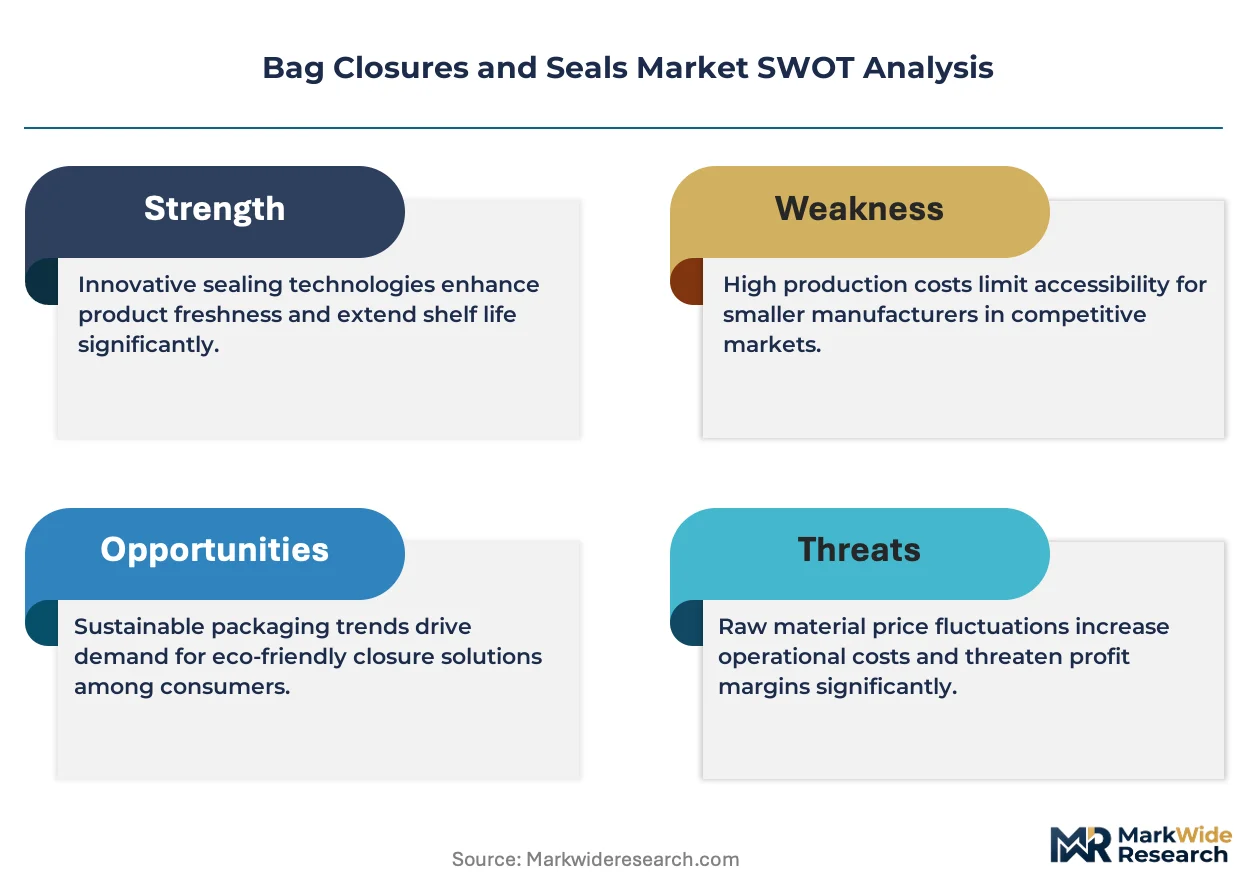
- Polylactic acid feedstock volatility:Corn and sugarcane price fluctuations transmit directly to biodegradable closure manufacturing costs, compressing margins for converters without long-term agricultural supply agreements.
- China polymer supply concentration:Polypropylene resin for conventional closures sources predominantly from Asian petrochemical complexes, exposing European and North American molders to freight cost spikes and tariff uncertainty.
- Compostability certification fragmentation:Divergent EN 13432 and ASTM D6400 testing protocols create compliance friction for suppliers attempting unified product portfolios across Atlantic markets.
Strategic Opportunities
- Indian organized retail expansion:Modern grocery formats in Mumbai and Delhi are adopting zip-lock pouch standards previously confined to export-oriented processing, opening premium closure demand in a price-sensitive market.
- Pharmaceutical secondary packaging:Tamper-evident seal specifications for over-the-counter drugs are migrating from bottle caps to flexible pouch closures, creating specification upgrade opportunities in FDA-regulated supply chains.
- Reusable packaging mandates:France's anti-waste law for a circular economy incentivizes durable press-seal formats for bulk goods, displacing single-use twist-ties in institutional catering procurement.
Industry Challenges
- ISO 22000 audit complexity:Food safety management certification timelines stretch 12-18 months for closure manufacturers adding new polymer grades, delaying market entry for reformulated biodegradable products.
- Legacy equipment retrofit costs:Converting injection molding lines from polypropylene to polylactic acid blends requires screw and barrel modifications, capex that mid-tier suppliers struggle to finance without customer volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bag Closures and Seals Market |
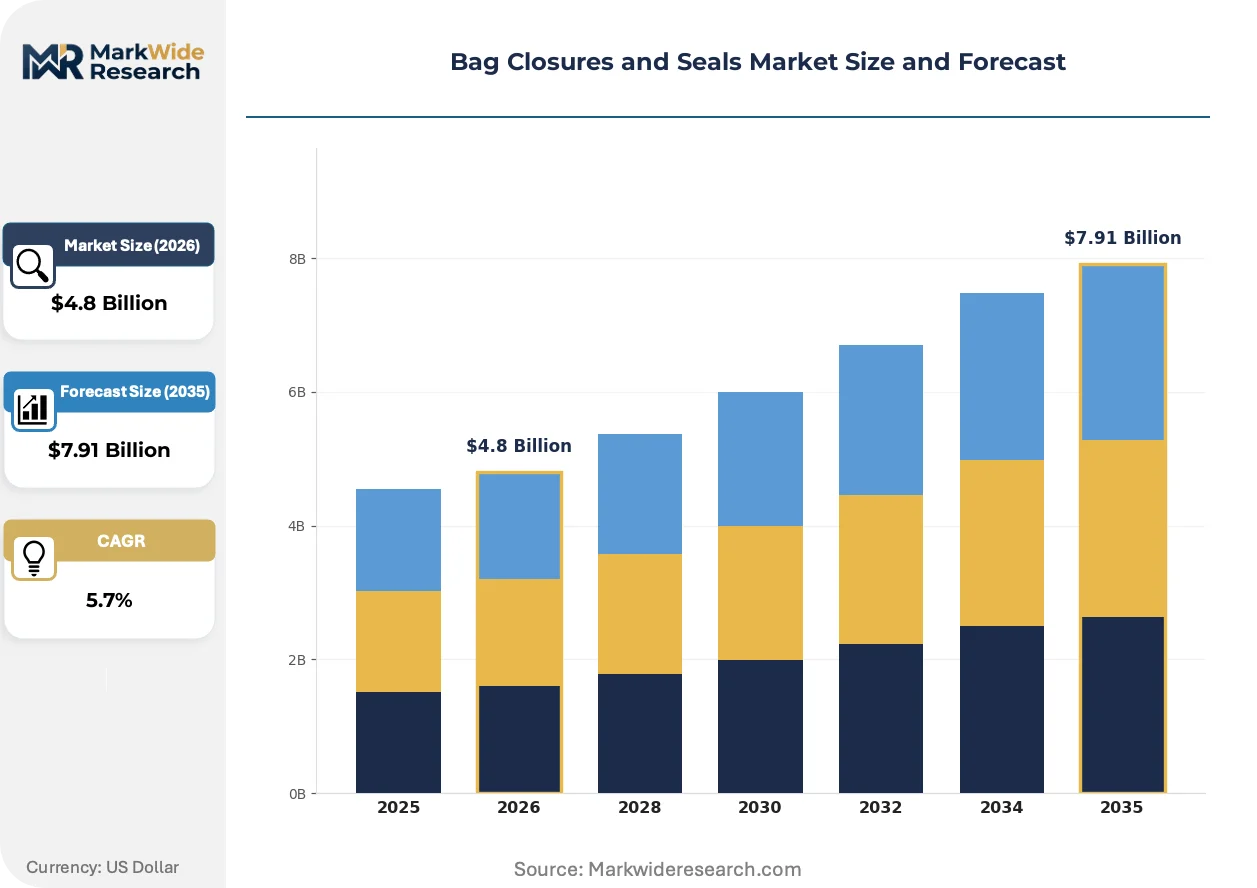
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
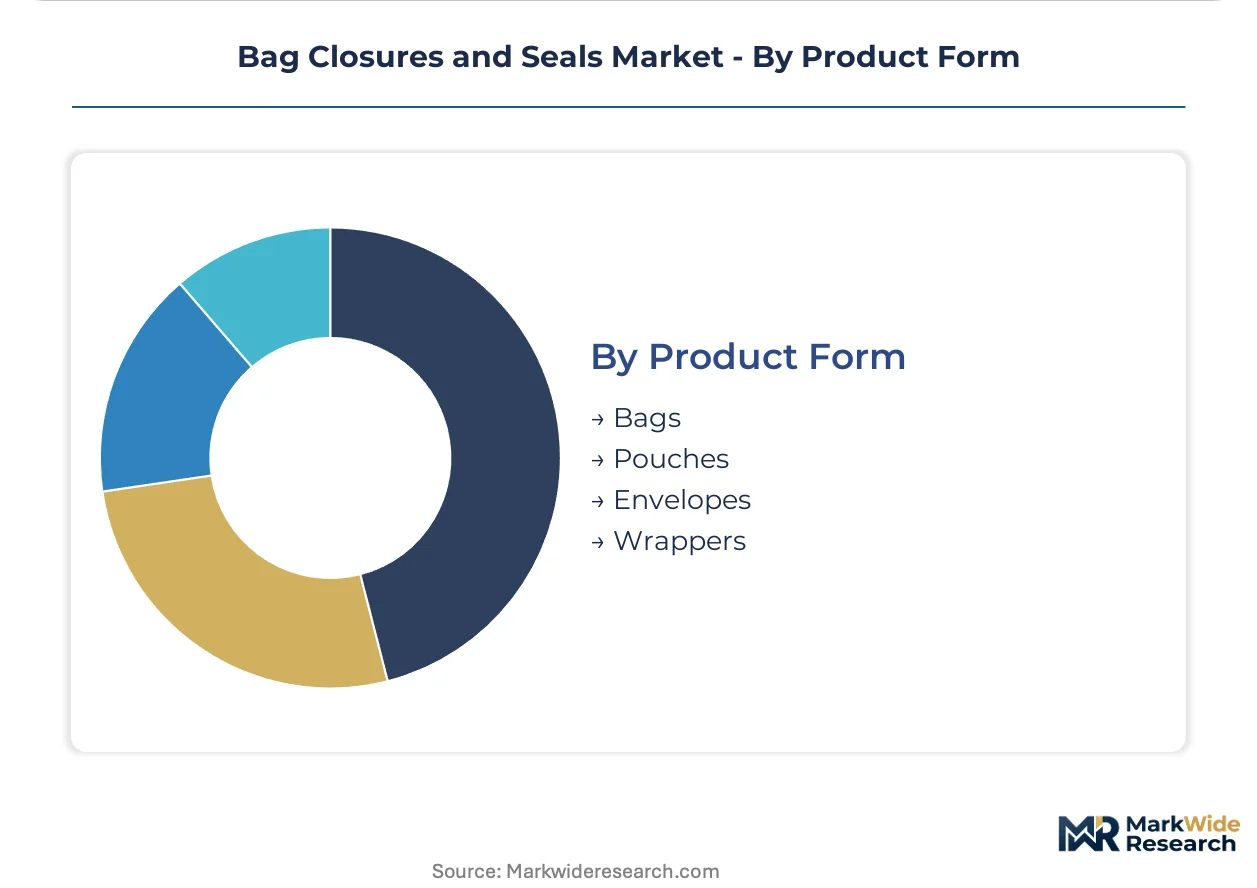
| Segmentation | Closure Type: Zip Lock, Press Seal, Heat Seal, Velcro Material: Plastic, Metal, Paper, Biodegradable Application: Food Packaging, Medical Supplies, Retail, Industrial Use Product Form: Bags, Pouches, Envelopes, Wrappers |
| Companies Covered | Kwik Lok Corporation, Schutte Bagclosures, Bedford Industries, Plas-Ties, Co., ITW Envopak, Zhenjiang Hongda Commodity Co., Ltd., Multipack, TruSeal, A. Rifkin Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bag Closures and Seals Market Strategic Shifts
Material science advances and regulatory compression are converging to redefine competitive advantage in closure manufacturing, with sustainability credentials now filtering procurement decisions ahead of unit cost in premium food and pharmaceutical segments.
Polylactic acid blend formulations are collapsing the tensile strength and heat-resistance gaps that previously confined biodegradable closures to cold-chain applications. North American organic food brands are specifying these materials for ambient bread and produce packaging, pressuring conventional polypropylene suppliers to demonstrate equivalent performance in accelerated shelf-life testing or face specification exclusion.
REACH substance restrictions are tightening phthalate and heavy metal thresholds in food-contact closures, forcing reformulation of plasticizer packages in flexible seal compounds. German bakery chains are demanding full material disclosure documentation, with non-compliant suppliers losing approved vendor status regardless of price position.
Direct procurement from converter to retail private-label team is compressing traditional distribution layers, with supermarket technical buyers now specifying closure performance metrics directly. This pattern is most visible in French and UK fresh produce segments, where centralized buying offices are consolidating supplier panels and unbundling legacy broker relationships that added margin without technical value.
Bag Closures and Seals Market Segmentation
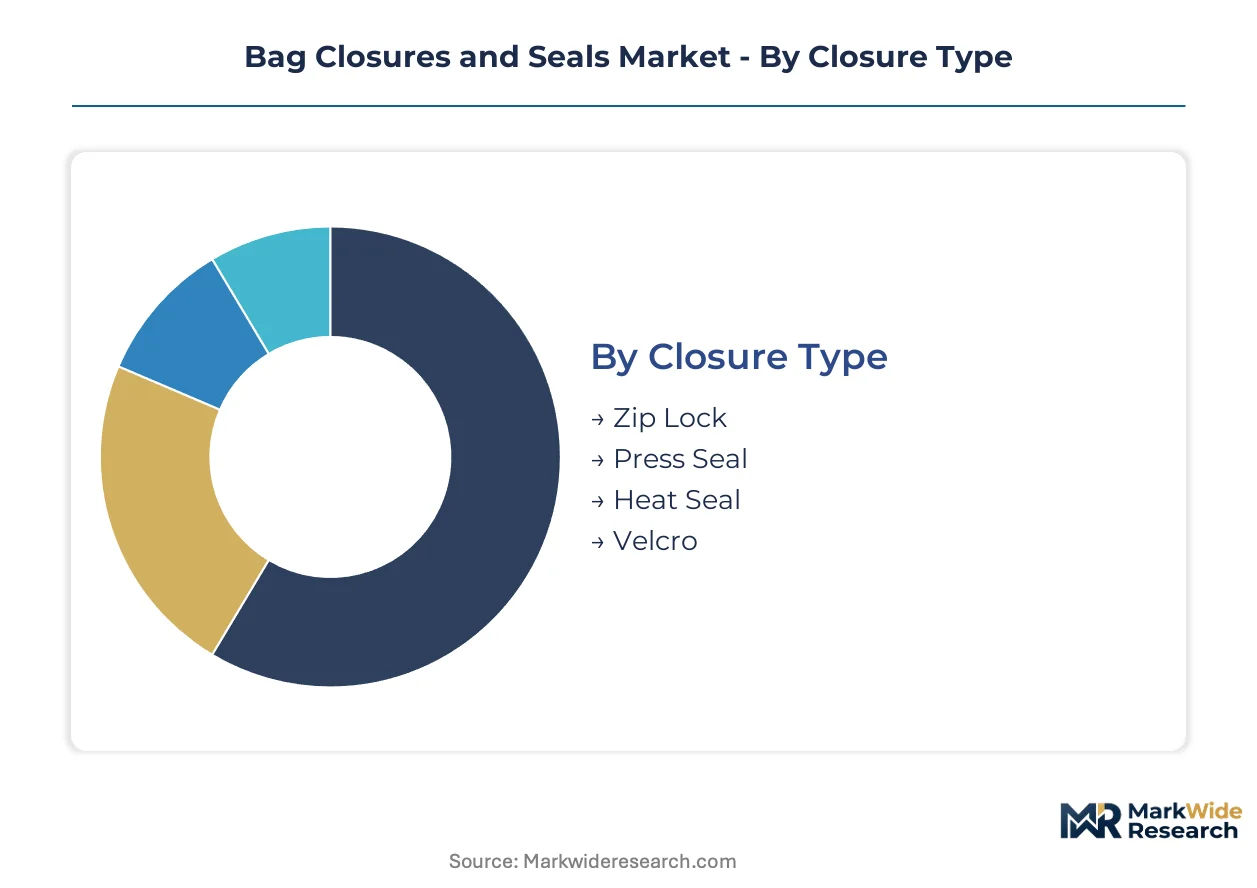
Segmentation in bag closures and seals reveals how material science, regulatory pressure, and end-use performance requirements fragment procurement patterns across food, pharmaceutical, and industrial channels. Understanding these divides exposes where specification premiums concentrate and where commodity competition erodes margin.
Closure Type:
Closure formats span resealable consumer convenience to single-use industrial containment, with automation compatibility and shelf-life extension driving specification divergence across end-use segments.
- Zip Lock:Interlocking plastic tracks molded from polyethylene or polypropylene blends enable repeated opening and closing without tool assistance. Premium organic food brands in Germany and France specify these for ambient grain and nut pouches where consumer reuse aligns with anti-waste regulatory positioning.
- Press Seal:Pressure-activated adhesive strips or cohesive coatings bond flexible film layers through manual compression. Industrial bulk bag applications in US chemical handling favor this format for initial containment where resealability adds cost without operational benefit.
- Heat Seal:Thermal fusion of polymer layers creates hermetic barriers against moisture and oxygen ingress. Automated form-fill-seal lines in ready-meal processing plants integrate these closures for contamination control at line speeds exceeding 200 units per minute.
- Velcro:Hook-and-loop textile fasteners laminated to flexible substrates support reusable packaging systems. France's institutional catering procurement under circular economy mandates specifies these for durable bulk goods transport.
By volume, Heat Seal leads through food manufacturing automation. By growth pace, Zip Lock is ahead on organic and premium retail expansion.
Material:
Raw material selection now pivots on compostability certification compliance rather than purely mechanical performance, with EU regulatory deadlines compressing conventional polymer incumbent positions.
- Plastic:Polypropylene and polyethylene resins dominate existing installed base through tensile strength, moisture barrier performance, and injection molding process maturity. FDA 21 CFR 177 compliance documentation supports pharmaceutical and food-contact applications across North American supply chains.
- Biodegradable:Polylactic acid blends and starch-based compounds achieve EN 13432 compostability certification required for single-use packaging under EU Packaging and Packaging Waste Regulation mandates. German bakery chains now specify these for bread bag clips previously molded from conventional polypropylene.
- Metal:Tinplate wire formulations deliver twist-tie functionality with puncture resistance for fresh produce handling. Bedford Industries anchors market position through proprietary wire-twist technology serving North American fruit and vegetable distribution.
- Paper:Kraft and coated paper substrates support fiber-based packaging alignment with plastic reduction targets. Limited moisture resistance confines current applications to dry goods and short-shelf-life bakery items.
Plastic retains volume leadership through legacy equipment and cost position. Biodegradable materials are climbing the fastest on regulatory pull-through and retail private-label sustainability commitments.
Application:
End-use segmentation maps directly onto regulatory intensity, with food and medical channels imposing material disclosure and safety management certification barriers that filter supplier participation.
- Food Packaging:Direct-contact applications demand FDA or EFSA compliance plus ISO 22000 food safety management certification. Extended shelf-life requirements in German fresh produce and bakery segments drive specification for moisture barrier performance and resealability.
- Medical Supplies:Sterile barrier packaging for devices and consumables requires validated seal integrity under ISO 11607. Migration from rigid containers to flexible pouches creates specification upgrade opportunities for tamper-evident closure systems.
- Retail:Private-label technical buyers in French and UK supermarket chains now specify closure performance metrics directly, compressing traditional distribution margins. Zip-lock and press-seal formats dominate consumer-facing pouch applications.
- Industrial Use:Bulk chemical and agricultural product handling prioritizes initial containment cost over resealability. Heat seal and tie-wire formats serve this price-sensitive segment where automation integration varies by facility scale.
Food Packaging commands volume concentration through daily consumption replenishment. Medical Supplies are gaining share fastest on device packaging format migration.
Product Form:
Packaging geometry determines closure mechanical loading and sealing equipment compatibility, with pouch and bag formats diverging on automation investment requirements.
- Bags:Side-sealed or bottom-gusseted constructions accommodate bulk volume with closure stress distributed across wide seal areas. Fresh produce and bakery distribution in Germany standardizes on bag formats with integrated wire-twist or clip closures.
- Pouches:Stand-up and flat pouch geometries support retail shelf presentation and consumer handling convenience. Indian organized retail expansion in Mumbai and Delhi adopts zip-lock pouch standards for premium grain and snack segments.
- Envelopes:Lightweight paper or film constructions for document and small-item protection use adhesive or press-seal closures. E-commerce growth drives demand for tamper-evident envelope seals in postal and courier applications.
- Wrappers:Single-sheet flexible formats for confectionery and portion-controlled foods employ heat seal or twist-wrap closure methods. High-speed wrapping equipment in chocolate and candy processing lines specifies heat seal compatibility.
Bags lead by volume through produce and industrial bulk applications. Pouches are expanding most quickly on retail premiumization and emerging market format adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German bakery chains and fresh produce distributors command the strictest closure specifications, while regulatory divergence between EU compostability mandates and North American FDA frameworks fragments supplier strategies across Atlantic markets.
Germany
Bakery and fresh produce sectors drive specification intensity for moisture barrier performance. The EU Packaging and Packaging Waste Regulation imposes extended producer responsibility targets that mandate compostable materials by regulatory deadlines. The Baden-Württemberg industrial corridor hosts precision molding operations serving retail private-label technical buyers who demand full material disclosure documentation.
United States
North American organic food brands specify polylactic acid blend closures for ambient bread packaging. FDA governs direct food-contact materials under 21 CFR 177, requiring compliance documentation for pharmaceutical and food-contact applications. The Upper Midwest fruit and vegetable distribution networks anchor wire-twist closure demand through proprietary technology serving produce handling requirements.
France
Institutional catering procurement under anti-waste law for a circular economy incentivizes durable press-seal formats for bulk goods. The national regulator enforces REACH substance restrictions tightening phthalate thresholds in food-contact closures. The Île-de-France region concentrates supermarket centralized buying offices that specify closure performance metrics directly, compressing traditional distribution layers.
India
Modern grocery formats in Mumbai and Delhi adopt zip-lock pouch standards previously confined to export-oriented processing. The Food Safety and Standards Authority of India filters market access through packaging material safety requirements. The Maharashtra organized retail expansion opens premium closure demand in price-sensitive segments where grain and snack pouch adoption accelerates.
China
Polypropylene resin supply concentration exposes molders to freight cost volatility and tariff uncertainty. The Ministry of Ecology and Environment advances dual carbon goals that reshape material selection priorities for export-oriented suppliers. The Yangtze River Delta petrochemical complexes dominate polymer feedstock production for conventional closure manufacturing.
Bag Closures and Seals Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented tiers where no single entity commands decisive share. The vendor base distributes across integrated multinational suppliers, regional molding specialists, and niche technology holders. Three archetypes dominate: automated equipment-integrated suppliers, biodegradable material pioneers, and wire-twist technology anchors. Competitive moves concentrate on geographic expansion through distribution partnerships and portfolio diversification into compostable certifications.
Among North American equipment-integrated suppliers, Kwik Lok Corporation and Bedford Industries occupy positions representing channel control through bakery and produce sector relationships. Schutte Bagclosures exemplifies European manufacturing scale competing on lead times for retail-ready seal products. Zhenjiang Hongda Commodity Co., Ltd. anchors Chinese supply concentration serving resin-dependent conventional closure production.
| Leading Market Players |
|---|
| Kwik Lok Corporation |
| Schutte Bagclosures |
| Bedford Industries |
| Plas-Ties, Co. |
| ITW Envopak |
| Zhenjiang Hongda Commodity Co., Ltd. |
| Multipack |
| TruSeal |
| A. Rifkin Co. |
| Others |
Value Chain & Pricing Dynamics
China polymer supply concentration exposes European and North American molders to freight cost spikes and tariff uncertainty, compressing pricing spreads between premium biodegradable tiers and economy polypropylene grades while simultaneously forcing converters to diversify resin sourcing across Atlantic and Asian supply bases.
Pricing Analysis
Cost-plus contracts with polypropylene resin indexation dominate procurement between molders and food processors, locking margins to petrochemical feedstock volatility. Price differentiation rests on compostability certification grade and automation integration level, with EN 13432-certified closures commanding premiums over conventional grades. Pricing pressure intensifies in wire-twist segments as Bedford Industries' proprietary technology anchors buyer concentration. Industrial bulk bag buyers exhibit highest price sensitivity, while German bakery chains prioritize moisture barrier performance over unit cost.
Supply Chain Analysis
Upstream feedstock flows from Yangtze River Delta petrochemical complexes, US Gulf Coast propylene crackers, and Middle Eastern polymer export terminals. Corn and sugarcane agricultural supply chains feed polylactic acid biopolymer production for compostable grades. Single-source vulnerability concentrates in Asian resin supply for conventional closures. Distribution runs through converter-direct relationships with supermarket centralized buying offices, displacing legacy broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through supermarket centralized buying offices in France and Germany, with technical procurement teams unbundling legacy distribution layers and consolidating supplier panels to three approved vendors per closure category.
For Market Incumbents: Pre-empt specification exclusion by accelerating polylactic acid blend R&D to match conventional polypropylene tensile strength in ambient bread packaging applications. Secure long-term agricultural supply agreements to stabilize biodegradable feedstock costs against corn price volatility. Invest in ISO 22000 certification maintenance as EFSA tightens food-contact material disclosure requirements. For New Entrants and Emerging Players: Indian organized retail expansion in Mumbai and Delhi presents the most penetrable white-space target, with modern grocery formats adopting zip-lock pouch standards previously confined to export processing. Target pharmaceutical secondary packaging segments where tamper-evident seal specifications migrate from bottle caps to flexible pouches. Pursue direct technical relationships with French institutional catering procurement teams under circular economy mandates. For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation reshapes the acquisition landscape by mandating compostable materials for single-use packaging, elevating targets with EN 13432 certification and polylactic acid formulation capabilities. Mid-tier European molders with stranded polypropylene capacity face margin compression and represent consolidation candidates. Monitor biodegradable resin price convergence against conventional polymers as the inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Material Certification | EN 13432 compliance opens EU retail channels under extended producer responsibility mandates. |
| Backward Integration into Resin Supply | Captive polylactic acid production insulates margins from agricultural commodity volatility. |
| Automation Equipment Partnership | Integration with form-fill-seal line OEMs locks in high-volume food processor contracts. |
| Direct Retail Technical Sales | Relationships with supermarket buying offices disintermediate legacy distribution margins. |
| Pharmaceutical Seal Development | Tamper-evident specifications for flexible pouches access FDA-regulated premium segments. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with plant managers at closure manufacturing facilities, procurement leads at German and French supermarket chains, technical directors at food processing OEMs, and regulatory affairs specialists at compostability certification bodies; alongside secondary validation through EU Packaging and Packaging Waste Regulation implementation documents, FDA 21 CFR 177 compliance filings, EN 13432 test protocol records, and customs trade data for polypropylene and polylactic acid resin flows. Bottom-up volume modeling across closure types, materials, and applications triangulated against top-down market sizing.
Forecast inputs considered biodegradable polymer formulation advances, automation integration rates in ready-meal processing, and regulatory deadline phasing across EU member states. Segmentation dimensions modeled include closure format, material certification tier, end-use regulatory intensity, and geographic adoption pattern. CAGRs derived from elasticity analysis of resin cost pass-through and substitution dynamics between conventional and compostable materials.
Practitioners should monitor EU member state implementation variance for extended producer responsibility targets, polylactic acid feedstock price spreads against polypropylene, and ISO 22000 audit timeline extensions for early signals of forecast revision. Cross-checking against customs import data for closure manufacturing equipment is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Spigot End Cap Market
Caps and Closures
Crimp Top Cap Market
Caps and Closures
PET Dome Lids Market
Caps and Closures
Sterile Lids Market
Caps and Closures
Twist Caps Market
Caps and Closures
Benelux Plastic Caps and Closures Market
Caps and Closures
Magnetic Closure Box Market
Caps and Closures
Snap Cap Vials Market
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
Elastomeric Closures Market
Caps and Closures
Morocco Plastic Caps and Closures Market
Caps and Closures
Low Profile Compact System Closures Market
Caps and Closures
Middle East and Africa Plastic Caps and Closures Market
Caps and Closures
Peelable Lid Stock Market
Caps and Closures
Russia Plastic Caps and Closures Market
Caps and Closures
Global Aluminum Caps for Packaging Market