
 Non-Aerosol Overcaps Market | 2026-2036
Non-Aerosol Overcaps Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Aerosol Overcaps Market Outlook
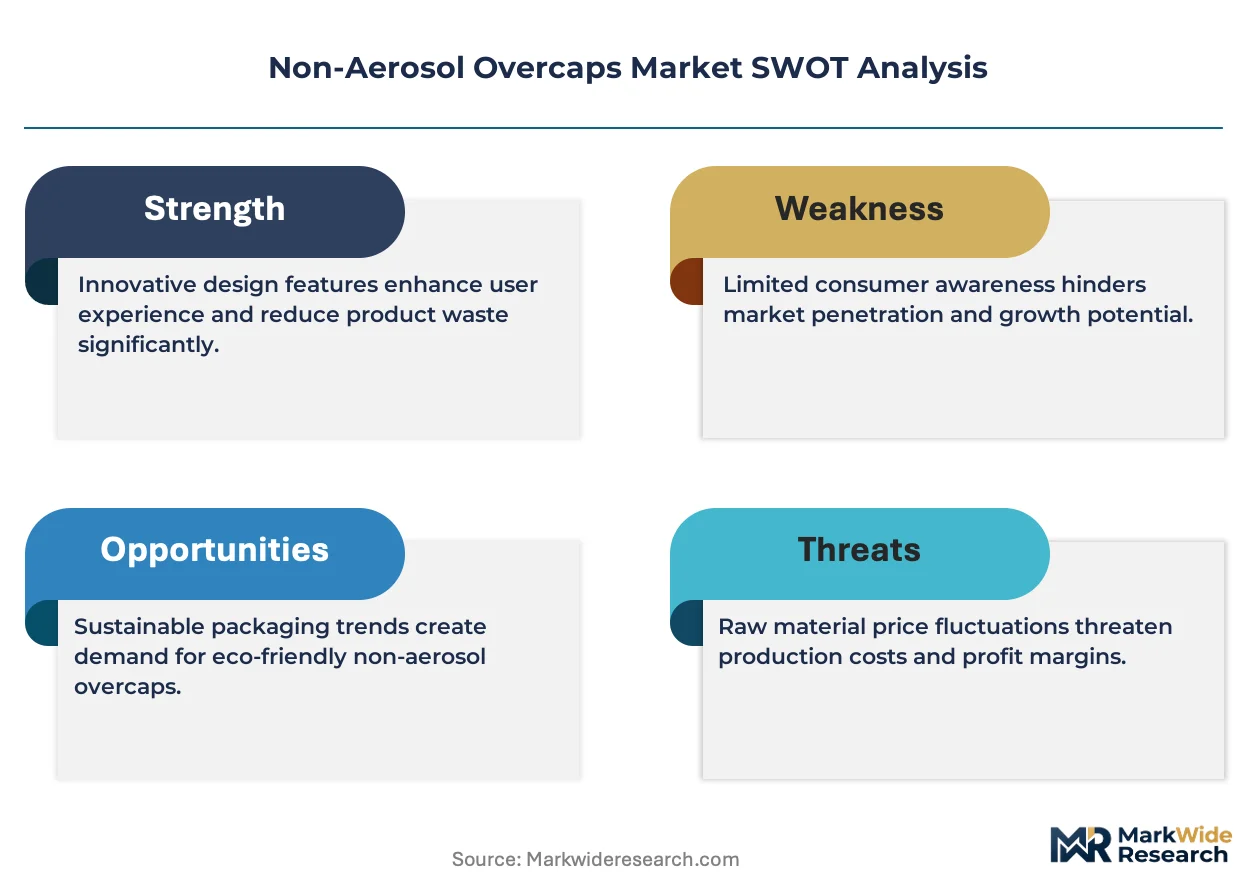
The gap between premium and commodity tiers is broadening as pharmaceutical and cosmetic brands specify multi-functional overcaps with integrated child-resistant and tamper-evident features, while bulk household segments prioritize cost-minimized press-on formats. Berry Global Inc. leverages its North American blow-molding footprint to supply high-volume snap-on programs for consumer packaged goods. Huhtamaki Oyj anchors European demand through specialized barrier-laminated closure systems. AptarGroup, Inc. differentiates via precision dosing overcaps for nasal and topical pharmaceutical applications.
Non-aerosol overcaps are mechanical closure devices engineered to seal non-pressurized containers, typically manufactured through injection molding of polypropylene or polyethylene with dimensional tolerances of ±0.1 mm to ensure thread engagement and seal integrity. Their primary purpose is to protect product formulation stability, enable controlled dispensing, and communicate safety status to end users. Flip top caps dominate volume in food and beverage due to single-handed operation requirements, while child-resistant designs command margin premiums in pharmaceutical channels. Plastic materials sustain roughly four-fifths of unit demand, though metal overcaps retain share in spirits and high-end cosmetics where heft signals quality.
The FDA enforces 21 CFR requirements for pharmaceutical container closures, including child-resistant packaging mandates that directly shape overcap design specifications and testing protocols. REACH and the EU Packaging and Packaging Waste Directive impose material disclosure and recyclability obligations on suppliers serving European brand owners. California's Proposition 65 adds chemical labeling burdens for plastic formulations containing flagged substances. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to regionalize formulation portfolios or pursue unified global specifications.
Market Dynamics
Pharmaceutical serialization mandates and the EU Single-Use Plastics Directive are compressing converter lead times while forcing resin formulation changes across European supply chains. Brand owners now specify multi-functional overcaps combining child-resistance, tamper-evidence, and dispensing precision in single injection-molded units.
Growth Catalysts
- REACH material disclosure:European converters accelerate post-consumer recycled polypropylene qualification to preempt regulatory penalties and secure brand owner contracts.
- Pharmaceutical packaging expansion:Nasal and topical drug delivery formats require precision-dosing overcaps with dimensional tolerances below ±0.1 mm.
- Germany's Rhine-Ruhr cluster:Concentrated blow-molding and injection-molding capacity enables rapid prototyping and short-run customization for cosmetic brand owners.
Market Restraints
- Post-consumer resin price volatility:rPP and rPE feedstock costs fluctuate with municipal collection system yields, compressing converter margins on sustainability-specified contracts.
- Tooling concentration in Southern China:High-cavitation injection mold fabrication depends on a limited supplier base, extending new product development timelines.
- California Proposition 65:Chemical labeling requirements for flagged plastic additives create compliance friction for exporters serving the US West Coast.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO packaging regulations are tightening, creating demand for imported child-resistant closure systems as domestic capacity lags.
- Smart packaging integration:NFC-enabled overcaps combining physical tamper-evidence with digital authentication are gaining traction in spirits and luxury cosmetics.
- Extended Producer Responsibility frameworks:France's Citeo and Germany's Der Grüne Punkt create preferential sourcing channels for converters with certified recycling partnerships.
Industry Challenges
- Multi-cavity mold commissioning:Validating 96-cavity and 128-cavity tools for high-volume food and beverage programs demands 12-18 month lead times and specialized process engineering talent.
- Legacy line integration:Pharmaceutical packagers face downtime costs and mechanical incompatibility when retrofitting new overcap formats onto existing capping equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Aerosol Overcaps Market |
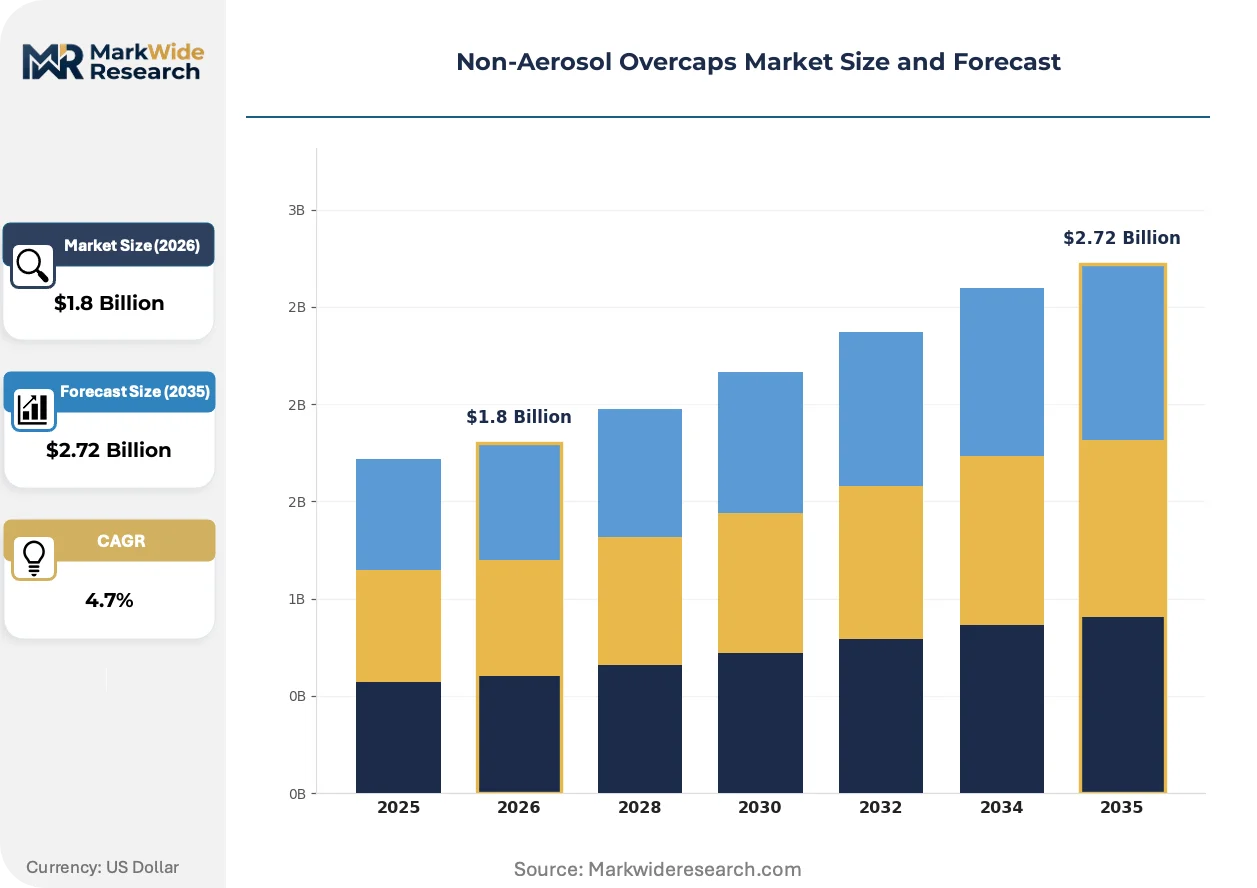
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip Top Caps, Screw Caps, Press-On Caps, Snap-On Caps Material: Plastic, Metal, Rubber, Silicone End User: Cosmetic Industry, Pharmaceutical Industry, Food & Beverage, Household Products Design Feature: Child-Resistant, Tamper-Evident, Reusable, Ergonomic |
| Companies Covered | Berry Global Inc., Huhtamaki Oyj, Precision Valve Corp., Rieke Corp, Claytoon Corp., O. Berk Company, Cobra Plastics, Dubuque Plastics, AptarGroup, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Aerosol Overcaps Market Strategic Shifts
Automation and material science convergence is redefining overcap value propositions, with converters investing in vision-inspection systems and bio-based resin formulations to meet pharmaceutical and cosmetic brand specifications simultaneously.
Vision-guided robotic sorting is automating post-mold defect removal and assembly operations previously dependent on manual labor. Pharmaceutical contract packagers in Germany and Switzerland deploy these systems to achieve lot-level traceability required by FDA 21 CFR and EMA serialization mandates. The technology is automating quality assurance workflows that once bottlenecked high-mix, low-volume production runs.
The EU Packaging and Packaging Waste Directive's 2030 recyclability targets are forcing redesigns of multi-component overcaps. Converters serving French and German cosmetic brands now eliminate metal springs and disparate resin grades to achieve mono-material structures. Spirits manufacturers in Scotland and Cognac respond by specifying aluminum overcaps with embossed branding to signal premium positioning outside plastic-dependent supply chains.
Brand owner procurement teams consolidate supplier panels from fifteen-plus vendors to four or five strategic partners capable of integrated design, tooling, and regulatory filing support. Food and beverage multinationals in the Netherlands and Belgium lead this consolidation, replacing transactional spot-buying with multi-year framework agreements. The shift concentrates volume with converters possessing in-house metrology labs and FDA master file registrations.
Non-Aerosol Overcaps Market Segmentation
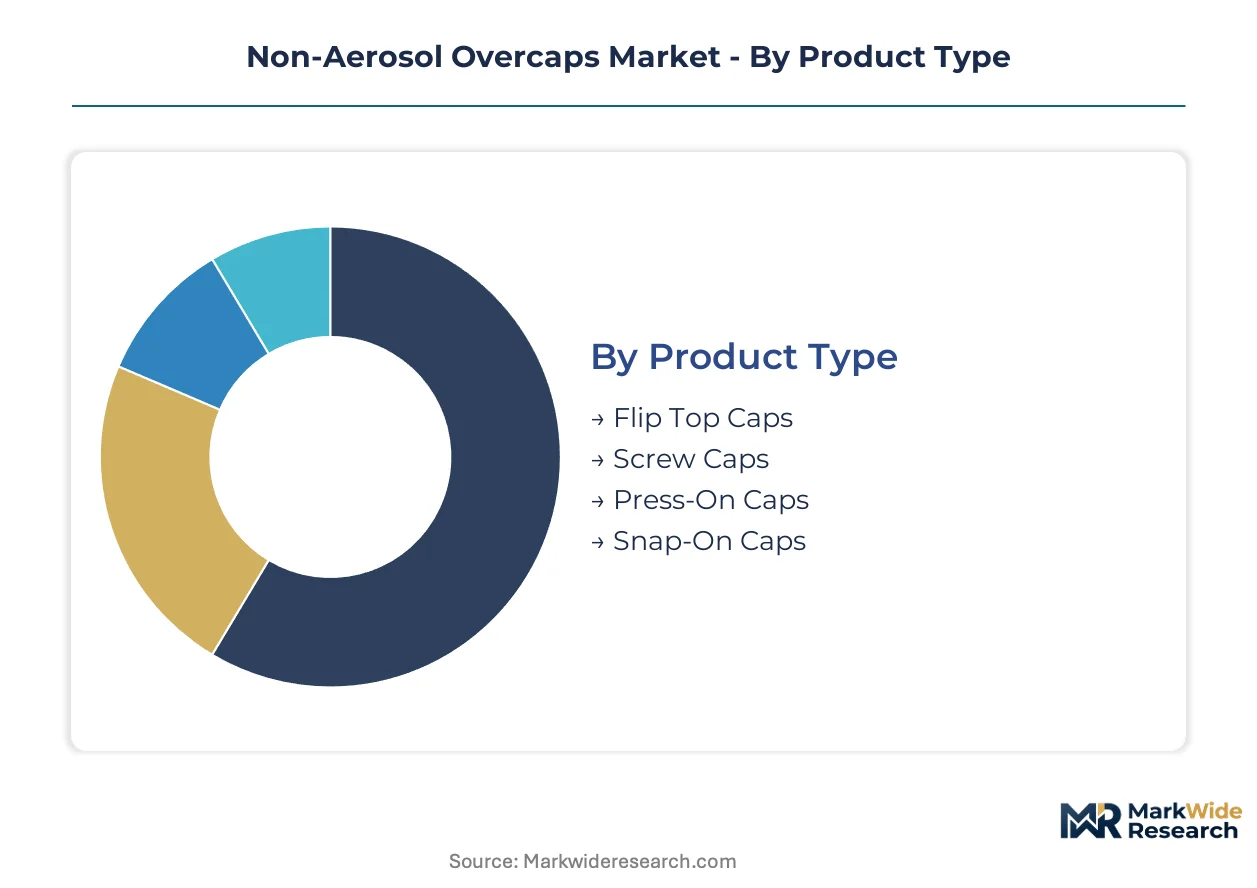
Converters configure tooling and resin selection around four distinct segmentation axes that determine regulatory burden, margin structure, and customer switching costs. Each axis creates divergent capability requirements that shape competitive positioning among injection molders and brand owner procurement strategies.
Product Type:
Mechanism design dictates cavity complexity, cycle time, and downstream automation compatibility across filling lines.
- Flip Top Caps:Hinged polypropylene constructions with living-hinge durability exceeding 5,000 actuation cycles. Demand concentrates in German beverage and Dutch condiment packaging where single-handed dispensing is mandatory. FDA 21 CFR thread specifications and EU food contact compliance drive qualification timelines.
- Screw Caps:Threaded closures with torque specifications between 15-25 inch-pounds for pharmaceutical compliance. Swiss and German generic drug manufacturers specify these for oral solid dose bottles under EMA serialization mandates. Metal shell overmolding adds premium positioning for spirits in Scotland and Cognac.
- Press-On Caps:Friction-fit designs for cost-minimized household chemical applications. Indian and Southeast Asian converters dominate volume production.
- Snap-On Caps:Audible engagement mechanisms for tamper-evident confirmation. French cosmetic brands favor these for serum and essence packaging.
Mature deployment sits with screw caps across established pharmaceutical supply chains. Newer deployment is concentrated in flip top variants for functional beverage and on-the-go food formats.
Material:
Resin selection balances regulatory compliance, recyclability credentials, and tactile properties that signal quality to end users.
- Plastic:Polypropylene and polyethylene homopolymers and copolymers constitute the dominant substrate, with post-consumer recycled grades qualifying under EU Packaging and Packaging Waste Directive targets. REACH substance disclosure requirements accelerate rPP adoption among converters supplying Rhine-Ruhr cosmetic clusters.
- Metal:Aluminum and tinplate constructions retain share in premium spirits and high-end cosmetics where heft and cold-touch perception justify cost premiums. Scotland's whisky industry and France's perfume houses specify embossed metal overcaps to differentiate shelf presence outside plastic-dependent supply chains.
- Rubber:Thermoplastic elastomer liners and gaskets for chemical resistance in agrochemical and industrial applications.
- Silicone:Medical-grade formulations for pharmaceutical dosing precision and biocompatibility requirements.
Plastic formulations dominate unit economics at scale. Metal substrates command the steepest price premiums and slowest volume expansion.
End User:
Industry verticals impose divergent certification, traceability, and lead time requirements that filter supplier capabilities.
- Cosmetic Industry:Barrier-laminated and metallized finishes for shelf differentiation. German and French brand owners specify mono-material structures to preempt EU recyclability mandates.
- Pharmaceutical Industry:Child-resistant and tamper-evident combinations with FDA master file documentation. Swiss contract packagers and German generic manufacturers drive demand for 96-cavity and 128-cavity validated tooling.
- Food & Beverage:Oxygen and moisture barrier specifications for shelf-life extension. Dutch and Belgian multinationals consolidate supplier panels to framework agreements.
- Household Products:Cost-optimized press-on and snap-on formats for bleach, detergent, and surface cleaner applications. Volume concentrates with high-cavitation producers in Southern China.
Pharmaceutical specifications carry the highest compliance burden and longest qualification cycles. Household segments permit the fastest supplier switching and most aggressive price negotiation.
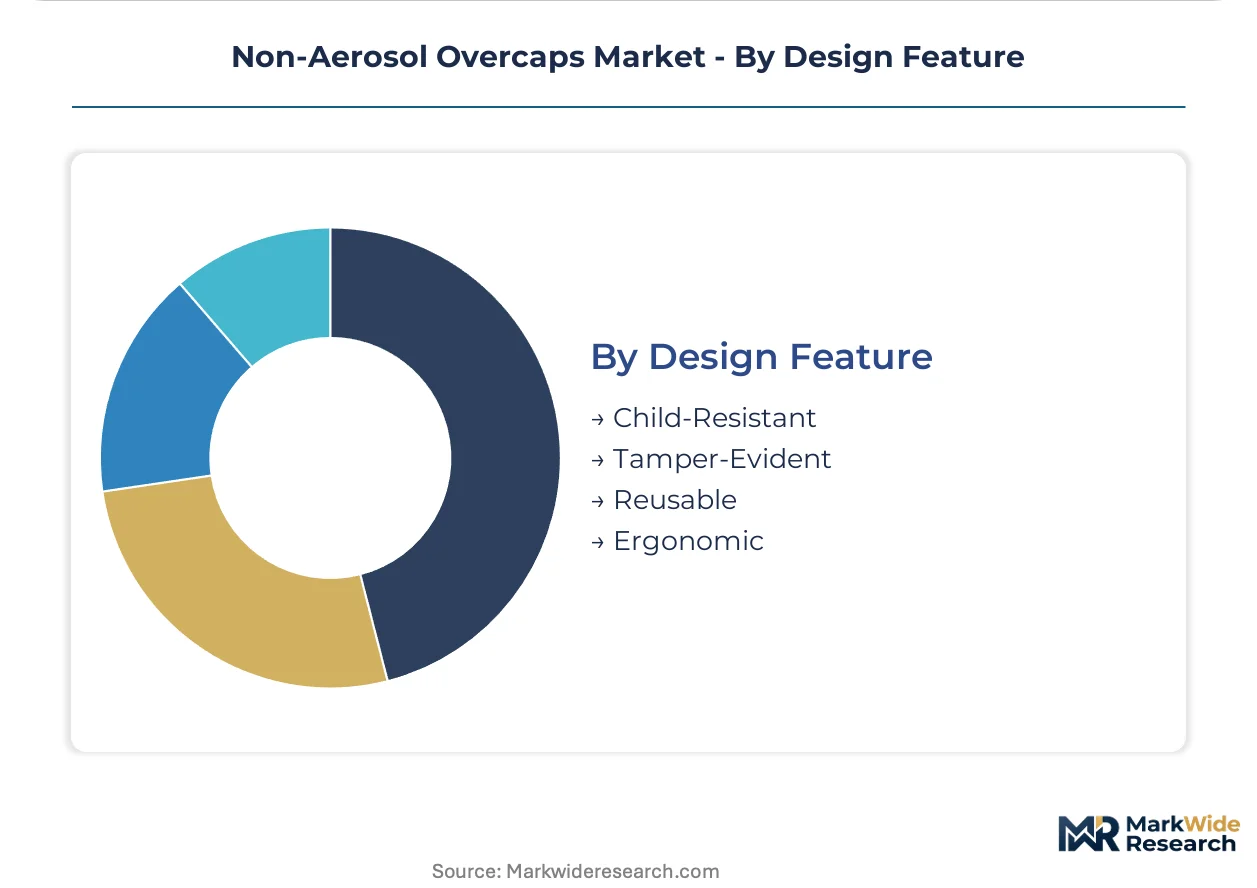
Design Feature:
Functional integration determines mold complexity, assembly operations, and end-user interaction patterns.
- Child-Resistant:Push-and-turn or squeeze-and-turn mechanisms requiring coordinated dual-action opening. CDSCO regulations in India and FDA 21 CFR mandates in the US create import demand as domestic converter capacity lags in emerging markets.
- Tamper-Evident:Breakaway bands, shrink sleeves, or induction-sealed membranes providing visual integrity confirmation. EMA serialization requirements and US DSCSA mandates elevate these to standard specification in pharmaceutical channels.
- Reusable:Refill-compatible thread designs and durability specifications for circular economy business models. French Citeo and German Der Grüne Punkt EPR frameworks incentivize these structures.
- Ergonomic:Contoured surfaces and textured grips for accessibility and aging populations. Japanese cosmetic brands and European disability-accessibility regulations drive specification.
Child-resistant and tamper-evident combinations represent the most technically demanding integration. Pure ergonomic differentiation remains concentrated in premium cosmetic and senior-care positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr corridor anchors converter capacity for pharmaceutical and cosmetic overcap supply chains across the analysis window.
Germany
EMA serialization mandates and the EU Single-Use Plastics Directive drive demand for multi-functional child-resistant closures. REACH material disclosure requirements accelerate post-consumer recycled polypropylene adoption among Rhine-Ruhr injection molders. The Düsseldorf-Cologne packaging cluster concentrates blow-molding and tooling expertise for rapid cosmetic brand prototyping.
United States
FDA 21 CFR pharmaceutical packaging regulations and California Proposition 65 chemical labeling requirements shape converter compliance strategies. CDSCO-aligned import demand from Indian pharmaceutical manufacturers creates export opportunities for child-resistant closure systems. Chicago-area converters supply high-volume snap-on programs for Midwest-based consumer packaged goods multinationals.
India
CDSCO tightening of pharmaceutical packaging regulations outpaces domestic child-resistant closure manufacturing capacity. FSSAI food contact compliance requirements extend qualification timelines for imported flip-top formats. Mumbai-Pune pharmaceutical manufacturing corridors drive demand for precision-dosing overcap imports as local tooling lags.
Switzerland
Swissmedic pharmaceutical serialization mandates and EMA traceability requirements elevate specification complexity for contract packagers. Precision dosing tolerances below ±0.1 mm filter supplier capabilities toward validated high-cavitation molders. Basel-Zurich pharmaceutical clusters specify barrier-laminated closure systems for nasal and topical drug delivery formats.
France
Citeo extended producer responsibility frameworks incentivize mono-material overcap designs eliminating metal springs and disparate resin grades. ANSM pharmaceutical packaging regulations align with EMA serialization mandates for tamper-evident combinations. Cognac spirits manufacturers specify embossed aluminum overcaps to signal premium positioning outside plastic-dependent supply chains.
Non-Aerosol Overcaps Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification burden and regulatory filing capabilities. The vendor base stratifies between validated pharmaceutical specialists, high-cavitation food and beverage suppliers, and regional cost-optimized press-on producers. Three archetypes dominate: FDA master file holders serving pharmaceutical serialization mandates, framework agreement suppliers to Dutch and Belgian multinationals, and Southern China-based high-cavitation molders for household chemical volume. Competitive moves concentrate on supplier panel consolidation by brand owner procurement teams and backward integration into post-consumer recycled resin compounding.
Among North American diversified packaging conglomerates, Berry Global Inc. and AptarGroup, Inc. occupy positions spanning pharmaceutical compliance and consumer goods scale. Finnish-based Huhtamaki Oyj exemplifies the European barrier-lamination specialist archetype. These three entities represent contrasting geographic anchors and capability configurations without implying specific strategic actions or market share positions.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Huhtamaki Oyj |
| Precision Valve Corp. |
| Rieke Corp |
| Claytoon Corp. |
| O. Berk Company |
| Cobra Plastics |
| Dubuque Plastics |
| AptarGroup, Inc. |
| Others |
Value Chain & Pricing Dynamics
Tooling engineers concentrated in Southern China's high-cavitation mold fabrication centers create labor-cost differentials that widen pricing spreads between validated pharmaceutical-grade overcaps and commodity press-on formats. Rhine-Ruhr injection molders absorb premium wage structures to deliver FDA master file documentation and REACH-compliant resin formulations, while Indian and Southeast Asian converters exploit lower process engineering costs to dominate household chemical volume tiers.
Pricing Analysis
Outcome-based pricing anchors pharmaceutical overcap contracts to lot-level traceability guarantees and serialization compliance rather than per-unit resin weight. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated child-resistant closures with master file documentation from EU food-contact certified flip-tops and unvalidated press-on commodity formats. Cost compression in standard-tier snap-on caps is intensifying because post-consumer recycled polypropylene feedstock costs fluctuate with municipal collection yields. Household product manufacturers exhibit the highest price sensitivity, while Swiss and German pharmaceutical contract packagers prioritize compliance certification over unit cost.
Supply Chain Analysis
Process engineering talent scarcity in Germany, Switzerland, and the United States limits validated high-cavitation mold commissioning capacity for pharmaceutical serialization programs. Raw material flows draw from Saudi petrochemical feedstocks for virgin polypropylene, Belgian compounders for barrier-laminated formulations, and German mechanical sorting facilities for post-consumer recycled grades. Single-source vulnerability concentrates in 96-cavity and 128-cavity mold fabrication dependent on Southern Chinese tooling networks. Distribution runs through framework agreement channels serving Dutch and Belgian food and beverage multinationals alongside spot-buy procurement for Indian household chemical converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward integration into post-consumer recycled resin compounding separates framework agreement suppliers from transactional spot-buy competitors. Control over rPP feedstock qualification and REACH documentation emerges as the decisive downstream lever.
For Market Incumbents: To counter supplier panel consolidation by brand owner procurement teams, deepen captive supply of post-consumer recycled polypropylene compounding capacity in the Rhine-Ruhr corridor and secure Der Grüne Punkt certification for preferential EPR framework access. Validate additional 128-cavity tooling for high-volume food and beverage programs to defend throughput advantages against Southern Chinese cost competitors. For New Entrants and Emerging Players: Begin with CDSCO-aligned child-resistant closure imports for Mumbai-Pune pharmaceutical manufacturing corridors where domestic tooling capacity lags regulatory tightening. Target precision-dosing overcap niches for nasal and topical drug delivery formats requiring dimensional tolerances below ±0.1 mm. Establish metrology lab partnerships to shortcut FDA master file registration timelines. For Investors and Strategic Acquirers: Re-rating potential sits with FDA master file holders possessing validated high-cavitation tooling and in-house barrier-lamination capabilities given EMA serialization mandate expansion across European generic drug manufacturers. Long-term viability over a five-to-ten year window favors converters with certified recycling partnerships under France's Citeo and Germany's Der Grüne Punkt EPR frameworks. Monitor NFC-enabled smart packaging integration traction in spirits and luxury cosmetics as inflection indicator for premium-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPP Compounding | Captive recycled resin supply secures REACH compliance and Der Grüne Punkt preferential sourcing. |
| High-Cavitation Tooling Validation | 96-cavity and 128-cavity mold commissioning filters competitors from pharmaceutical serialization contracts. |
| Smart Packaging Integration | NFC-enabled tamper-evidence differentiation captures spirits and luxury cosmetic premium positioning. |
| Framework Agreement Consolidation | Multi-year supply contracts with Dutch and Belgian multinationals replace transactional spot-buy relationships. |
| CDSCO-Aligned Import Positioning | Child-resistant closure qualification for Indian pharmaceutical corridors exploits domestic capacity constraints. |
Study Parameters
Independent corroboration across injection molding plant managers, pharmaceutical packaging procurement leads, barrier-lamination R&D directors, and EPR framework administrators underwrites the qualitative findings. Primary interviews with FDA regulatory affairs specialists and EU polymer compliance officers combined with secondary validation from ECHA substance databases, FDA 21 CFR guidance documents, CDSCO packaging circulars, and customs trade data establish material flow baselines. Bottom-up tooling capacity surveys and top-down resin consumption estimates triangulate market sizing.
Rate-of-change decomposition separates volume expansion from value migration across mechanism design complexity, resin grade tier, end-use industry certification burden, and geographic regulatory cluster stringency. Segmentation dimensions modeled include product type, material substrate, design feature integration, and regional production hub concentration. CAGRs were derived from trend extrapolation of validated high-cavitation mold commissioning timelines and post-consumer recycled resin adoption curves across the analysis window. Industry-specific forecast inputs incorporate EMA serialization mandate implementation pace and EU Packaging and Packaging Waste Directive recyclability target compliance rates.
Underlying measurement precision varies by segment; pharmaceutical-grade child-resistant closures with FDA master file documentation carry tighter precision than commodity press-on household formats. Forecasts reflect assumptions regarding CDSCO regulatory alignment timing and REACH substance disclosure enforcement intensity. Material deviation in EU Single-Use Plastics Directive implementation pace or Southern Chinese tooling capacity expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Pressure Sensitive Wads Market
Caps and Closures
Latin America Plastic Caps and Closure Market
Caps and Closures
Box Latch Market
Caps and Closures
Beverage Caps and Closures Market
Caps and Closures
Dropper Caps Market
Caps and Closures
End Cap Market
Caps and Closures
Bag Closures and Seals Market
Caps and Closures
US Caps and Closure Market
Caps and Closures
Tear Tab Cap Market
Caps and Closures
Child Resistant Dropper Caps Market
Caps and Closures
Benelux Plastic Caps and Closures Market
Caps and Closures
Egypt Plastic Caps and Closures Market
Caps and Closures
Linerless Closures Market
Caps and Closures
Bag Closures Market
Caps and Closures
Caps and Closures Market
Caps and Closures
PVC-Free Cap Liners Market