
 Plunger Stopper Market | 2026-2036
Plunger Stopper Market Size, Share, and Industry Trends Forecast 2026-2036
Plunger Stopper Market Analytics
Multi-source procurement for elastomer formulations is shifting as pharmaceutical packagers diversify beyond legacy supply relationships. West Pharma leverages its vertically integrated coating capabilities to sustain premium positioning in biologics-ready stoppers. Datwyler anchors European supply through Swiss compounding expertise and cleanroom molding infrastructure. Jiangsu Best competes on cost-advantaged bromobutyl output while extending capacity for silicone-coated variants.
A plunger stopper is an elastomeric or polymeric sealing component engineered to fit syringe barrels, typically manufactured via compression or injection molding with specified durometer, extractables profile, and break-loose glide-force parameters, serving to maintain sterility and dose accuracy in parenteral drug delivery. Silicone-coated rubber variants dominate biologics applications where low particulate generation and consistent break-loose force protect protein stability. Plastic and metal segments occupy narrower niches; plastic stoppers lead in cost-sensitive disposable syringes while metal-clad designs serve high-pressure auto-injector systems where dimensional rigidity prevents creep under spring load.
FDA extractables and leachables guidelines, EMA GMP Annex 1 revisions on contamination control, and ISO 8871 elastomeric closure standards collectively tighten material qualification burdens and favor suppliers with validated analytical laboratories. The EU MDR and REACH restrictions on nitrosamine precursors in rubber accelerators further filter compounder qualification pools. Stakeholders must monitor regulatory divergence between FDA and EMA on silicone oil quantification limits, as dual-compliance testing costs will reshape supplier selection criteria.
Market Dynamics
EMA and FDA extractables testing protocols are compressing supplier qualification timelines while biologics fill-finish expansion in China and Germany concentrates procurement power among compounders with validated analytical laboratories.
Growth Catalysts
- Biologics fill-finish expansion:Parenteral protein therapies require silicone-coated elastomer stoppers with sub-visible particulate controls. Contract manufacturers in China and Germany are scaling dedicated lines.
- REACH nitrosamine restrictions:ECHA limits on rubber accelerator precursors filter qualified compounder pools. Suppliers with validated alternative curing systems capture displaced volume.
- Dual carbon targets:China's MEE emissions standards for rubber processing push domestic compounders toward cleaner bromobutyl synthesis. Low-carbon output qualifies for preferential procurement.
Market Restraints
- Bromobutyl feedstock volatility:Isobutylene-isoprene monomer supply ties to petrochemical refining cycles. Price swings compress molding margins for non-integrated compounders.
- Cleanroom molding concentration:Swiss and German facilities control high-purity elastomer output. Geographic concentration creates single-source vulnerability for EMA-compliant packagers.
- Plastic stopper substitution:Cyclic olefin polymer alternatives challenge rubber in cost-sensitive disposable syringes. Thermal stability gaps limit biologics penetration.
Strategic Opportunities
- Indian biologics manufacturing:CDSCO's accelerated approval pathways for biosimilars attract fill-finish investment. Domestic elastomer molding capacity lags demand.
- Connected device integration:Auto-injector systems combining prefilled syringes with electronic dose tracking create demand for dimensional-precision stoppers. Electronics-syringe convergence opens specification windows.
- EMA GMP Annex 1 contamination controls:Revised sterile manufacturing guidelines mandate enhanced closure integrity testing. Validated suppliers capture upgrade-driven replacement cycles.
Industry Challenges
- Extractables analytical capacity:ISO 8871 and USP <1664> testing requires mass spectrometry and chromatography expertise. Qualified analytical chemists command premium compensation in Basel and Boston clusters.
- Silicone oil quantification divergence:FDA and EMA maintain differing limits on lubricant migration. Dual-protocol validation extends qualification timelines and multiplies testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plunger Stopper Market |
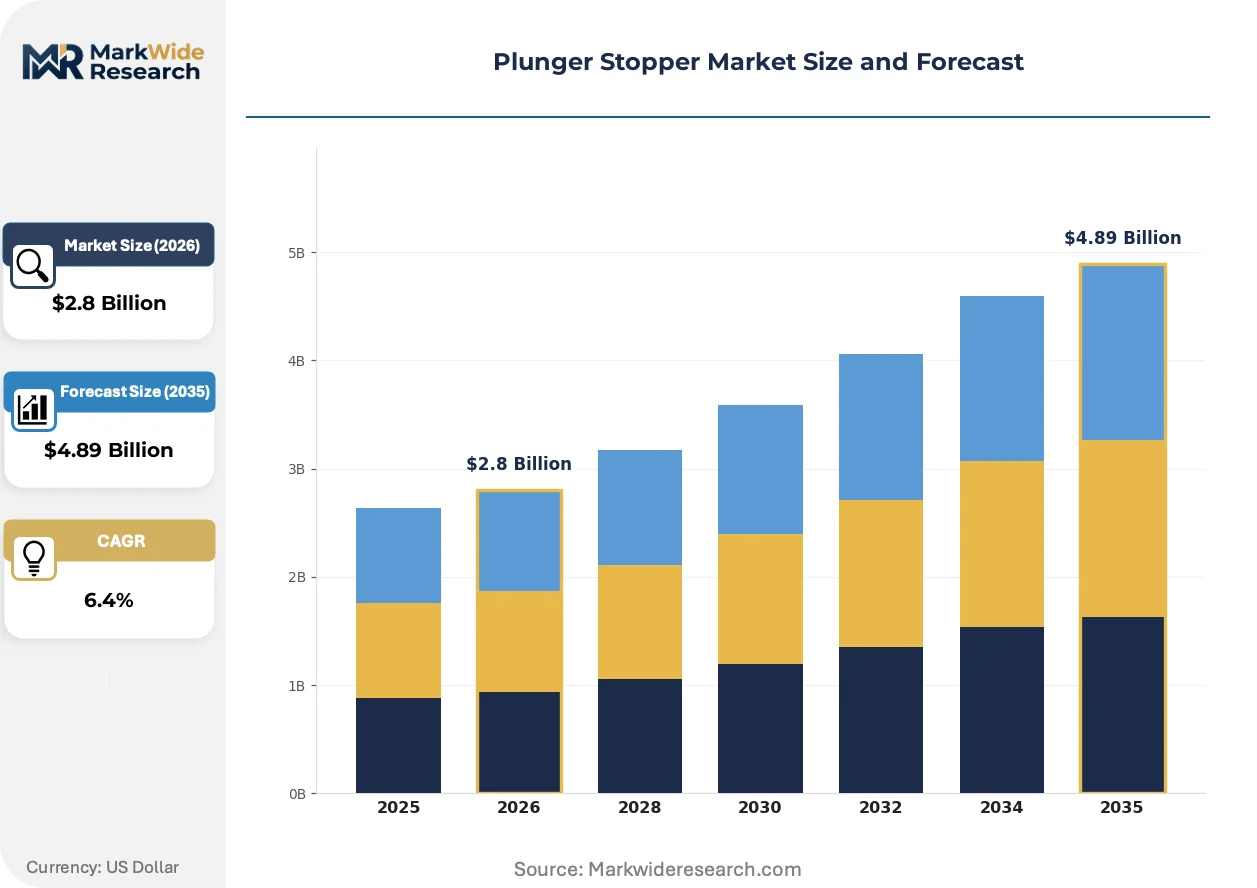
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Rubber, Silicone, Metal End User: Pharmaceuticals, Food & Beverage, Chemicals, Cosmetics Size: Small, Medium, Large, Extra Large Certification: FDA Approved, ISO Certified, CE Marked, Others |
| Companies Covered | West Pharma, Datwyler, Jiangsu Best, Hubei Huaqiang, Hebei First Rubber, Jintai, Jiangsu Hualan, Shandong Pharmaceutical Glass, Samsung Medical Rubber, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plunger Stopper Market Evolving Landscape
Material science advances and regulatory harmonization pressures are compressing product development cycles while elevating performance thresholds for parenteral packaging components.
Laminated film-coated elastomer technology is rewriting stopper surface engineering. The multilayer barrier system eliminates direct drug-rubber contact for high-sensitivity biologics. Large-molecule fill-finish sites in Germany and Massachusetts are qualifying these stoppers for monoclonal antibody portfolios. The technology is compressing competitive advantage around coating chemistry rather than base rubber formulation.
EMA's revised GMP Annex 1 contamination control guidelines entered force with stricter particulate and bioburden limits for sterile closures. The regulation mandates barrier technology and environmental monitoring upgrades throughout the elastomer conversion chain. Swiss and Irish compounding facilities are investing in isolator-based molding lines to maintain EMA compliance. High-purity stopper supply is consolidating among suppliers with captive cleanroom infrastructure.
Buyers are consolidating vendor relationships around full-service qualification packages. Pharmaceutical packagers in China and the United States are reducing approved supplier lists from six to three compounders. The shift favors vertically integrated manufacturers with in-house extractables testing and regulatory documentation. Procurement compression is most visible among mid-scale biotechs lacking internal analytical resources.
Plunger Stopper Market Segmentation
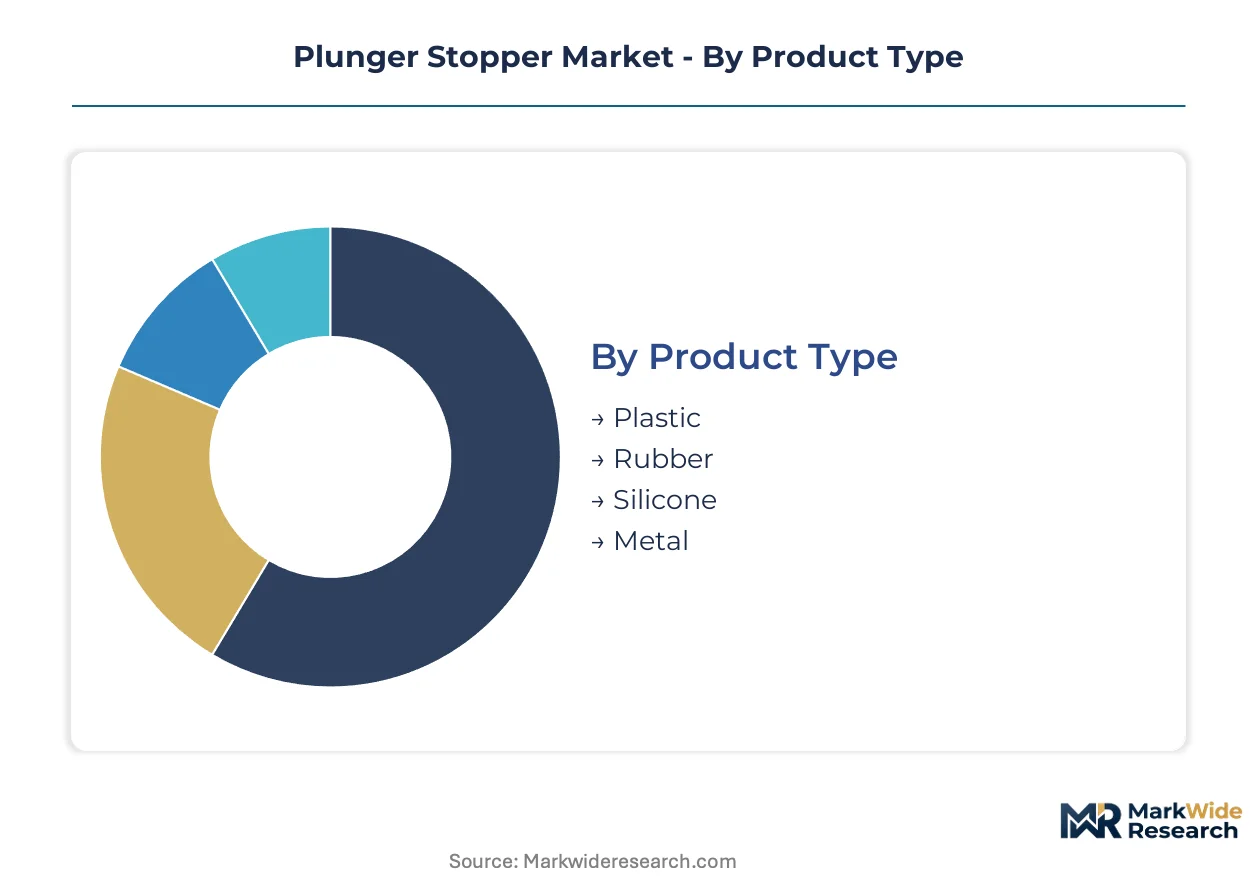
Plunger stopper procurement decisions split across material chemistry, dimensional precision, and regulatory validation tiers. Buyers in biologics manufacturing prioritize extractables profiles and coating consistency over unit cost, while disposable syringe assemblers optimize for molding throughput and feedstock stability.
Product Type:
Material selection separates applications by sterility requirements, chemical compatibility, and mechanical load tolerance.
- Rubber:Bromobutyl and chlorobutyl formulations dominate parenteral packaging through superior gas barrier properties and self-sealing after needle penetration. German and Chinese fill-finish sites specify coated variants to meet EMA and FDA extractables protocols for protein-based therapies.
- Silicone:Platinum-cured elastomer stoppers deliver ultra-low particulate generation and consistent break-loose glide force for monoclonal antibody delivery systems. Massachusetts and Basel biologics clusters specify these for high-value injectable portfolios where protein aggregation risks command premium material costs.
- Plastic:Cyclic olefin polymer and polypropylene stoppers serve cost-sensitive disposable syringes in mass vaccination campaigns. Thermal stability limitations restrict penetration into refrigerated biologics storage applications.
- Metal:Aluminum-clad or stainless steel designs reinforce dimensional rigidity in high-pressure auto-injector spring mechanisms. Swiss device manufacturers integrate these for dose accuracy in adrenaline and migraine rescue therapies.
Volume sits with rubber; growth tilts toward silicone.
End User:
Demand intensity varies by sector-specific regulatory burden and batch failure cost exposure.
- Pharmaceuticals:Parenteral drug manufacturers consume the majority of high-purity elastomer output, with fill-finish lines in China, Germany, and the United States driving specification standards. EMA GMP Annex 1 revisions and FDA extractables guidelines compress supplier qualification pools to compounders with validated analytical laboratories.
- Chemicals:Industrial reagent and diagnostic fluid packaging demands chemical-resistant sealing without pharmaceutical-grade documentation burdens. Chinese domestic compounders serve this tier through cost-optimized bromobutyl formulations.
- Cosmetics:Premium skincare ampoules and airless dispensers specify silicone-coated stoppers for aesthetic glide and oxidation protection. South Korean and French luxury packaging houses drive small-volume, high-margin procurement.
- Food & Beverage:Wine preservation systems and culinary dispensers occupy a narrow niche with limited overlap in elastomer formulation expertise. Migration testing under EFSA and FDA food contact regulations constrains material sourcing.
Pharmaceuticals commands procurement volume; cosmetics exhibits the steepest expansion trajectory.
Size:
Dimensional scaling aligns with syringe barrel standardization and dosing precision requirements.
- Small:0.5-1 mL stoppers serve high-potency biologics and pediatric vaccines where dose accuracy tolerances tighten. Prefillable syringe standardization around ISO 11040-4 dimensions concentrates demand.
- Medium:2-5 mL configurations dominate general therapeutic injections and diagnostic reagent packaging. Chinese contract manufacturers scale molding capacity for this mid-range specification.
- Large:10-20 mL designs accommodate contrast media and irrigation solutions. Lower unit volumes spread across fragmented regional device suppliers.
- Extra Large:50 mL and above stoppers serve specialized applications in cell culture media and veterinary therapeutics. Custom tooling requirements limit supplier participation.
Medium dimensions anchor production planning; small formats gain share through biologics concentration trends.
Certification:
Regulatory documentation tiers create supplier stratification and procurement pre-qualification gates.
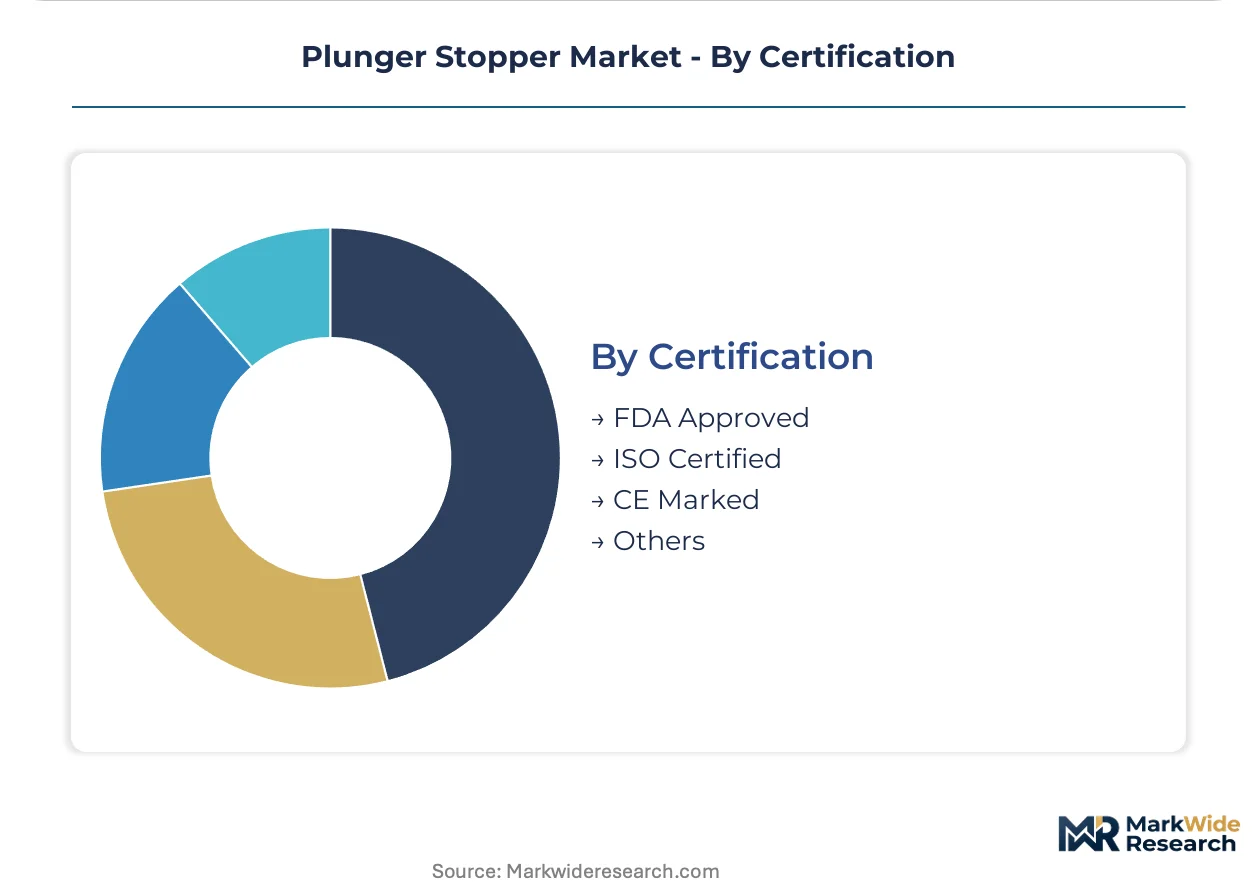
- FDA Approved:Drug Master File submissions and Type III drug master file references enable U.S. commercial drug product approvals. Boston and Research Triangle Park biotech clusters mandate this tier for IND-enabling and commercial supply.
- ISO Certified:ISO 8871 elastomeric closure standards and ISO 15378 primary packaging materials certifications underpin EMA-compliant supply. Swiss and Irish compounding facilities maintain these as baseline market access credentials.
- CE Marked:Medical device regulation compliance supports syringe-drug combination product pathways in European Economic Area markets. Post-EU MDR transition, notified body involvement has extended certification timelines.
- Others:Japan PMDA, China NMPA, and Brazil ANVISA registrations serve regional market access without global recognition. Domestic compounders in India and China accumulate these for local biologics manufacturing protection.
FDA and ISO tiers concentrate procurement power; CE Marked documentation is climbing fastest under EU MDR enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Isobutylene-isoprene monomer supply from petrochemical refining clusters in China, Germany, and the United States anchors plunger stopper manufacturing geography. EMA and FDA extractables protocols compress supplier qualification timelines across these three production centers. Procurement power concentrates where biologics fill-finish expansion intersects with validated analytical laboratory capacity.
United States
FDA Type III Drug Master File submissions enable commercial supply for Boston and Research Triangle Park biotech clusters. The agency's extractables and leachables guidelines tighten material qualification burdens for parenteral packaging. Massachusetts fill-finish sites specify silicone-coated elastomer stoppers for monoclonal antibody portfolios, driving premium-tier procurement.
Germany
EMA GMP Annex 1 contamination control revisions mandate enhanced closure integrity testing for sterile manufacturing. REACH nitrosamine restrictions on rubber accelerator precursors filter qualified compounder pools. Bavarian and Hesse-based compounding facilities invest in isolator-based molding lines to maintain EMA-compliant supply for domestic biologics manufacturers.
China
NMPA registration requirements and MEE emissions standards for rubber processing reshape domestic compounder competitiveness. Dual carbon targets push bromobutyl synthesis toward cleaner production pathways. Jiangsu and Shandong rubber compounders serve both local biologics fill-finish sites and export packaging houses with cost-advantaged output.
Switzerland
Swissmedic oversight and ISO 15378 primary packaging certifications underpin high-purity elastomer supply for European markets. Swiss compounding expertise anchors regional supply through cleanroom molding infrastructure. Basel biologics clusters specify platinum-cured silicone stoppers where protein aggregation risks command premium material costs.
India
CDSCO accelerated approval pathways for biosimilars attract fill-finish investment without matching domestic elastomer molding capacity. Maharashtra and Gujarat pharmaceutical manufacturing expansion outpaces local rubber compounder qualification. Procurement dependency on imported stoppers creates supply security concerns for emerging biologics production.
Plunger Stopper Market Competitive Landscape
Capacity expansion dominates the current landscape as compounders scale cleanroom molding infrastructure to meet EMA GMP Annex 1 compliance deadlines. The vendor base stratifies across three tiers: vertically integrated multinationals with captive analytical laboratories, regional specialists with validated coating capabilities, and cost-optimized domestic compounders serving standard-grade applications. Strategic archetypes include full-service qualification providers, feedstock-integrated rubber specialists, and device-integrated component suppliers. Geographic expansion and backward integration into bromobutyl compounding represent the dominant competitive moves.
Among the named participants, West Pharma exemplifies the vertically integrated archetype through its coating technology positioning. Datwyler occupies a position within the European specialist tier leveraging Swiss compounding heritage. Jiangsu Best represents the cost-optimized Chinese compounder segment extending capacity for silicone-coated variants. These three anchors illustrate how procurement compression toward approved supplier lists favors compounders with validated analytical infrastructure and regulatory documentation depth.
| Leading Market Players |
|---|
| West Pharma |
| Datwyler |
| Jiangsu Best |
| Hubei Huaqiang |
| Hebei First Rubber |
| Jintai |
| Jiangsu Hualan |
| Shandong Pharmaceutical Glass |
| Samsung Medical Rubber |
| Others |
Value Network & Pricing Analysis
Analytical chemists with mass spectrometry expertise in Basel and Boston command premium compensation that widens spreads between validated premium-tier stoppers and standard-grade alternatives. EMA GMP Annex 1 compliance timelines compress qualification windows, forcing buyers to absorb higher bundled validation costs or face supply disruption.
Pricing Analysis
Extractables testing packages bundled with regulatory documentation separate full-service compounders from unbundled material suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with FDA Type III Drug Master File holders capturing biologics premiums and domestic Chinese compounders competing on per-unit molding economics. Pricing pressure stems from REACH nitrosamine restrictions filtering qualified supplier pools and concentrating volume among validated alternatives. Disposable syringe assemblers exhibit highest price sensitivity, while Massachusetts and Basel monoclonal antibody manufacturers prioritize coating consistency over unit cost.
Supply Chain Analysis
Ocean freight volatility from Chinese bromobutyl compounders to European fill-finish sites injects cost unpredictability into procurement planning. Manufacturing gravity centers on China, Germany, and Switzerland, with isobutylene-isoprene monomer supply tethered to regional petrochemical refining cycles. Cleanroom molding capacity concentrates among Swiss and German facilities, creating single-source vulnerability for EMA-compliant packagers. Distribution runs through pharmaceutical contract manufacturers and device integrators with approved supplier list pre-qualification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into bromobutyl compounding and captive coating technology represents the dominant competitive race, as feedstock control and surface engineering capabilities determine margin sustainability across regulatory compliance tiers.
For Market Incumbents: Extend isolator-based molding capacity in Switzerland and Germany to capture EMA GMP Annex 1 upgrade-driven replacement cycles. Deepen analytical laboratory capabilities in Basel and Boston clusters to compress dual-protocol FDA-EMA qualification timelines. Defensive positioning against laminated film-coated elastomer technology requires accelerated R&D partnerships with German fill-finish sites.
For New Entrants and Emerging Players: Contract research organizations with biologics fill-finish expertise offer channel access to bypass incumbent supplier list consolidation. Target Indian CDSCO-registered biosimilar manufacturing where domestic elastomer molding capacity lags demand penetration. White-space opportunities concentrate in silicone-coated variants for auto-injector systems combining prefilled syringes with electronic dose tracking.
For Investors and Strategic Acquirers: The window for entry favors compounders with validated cleanroom infrastructure and existing ISO 15378 certifications. Long-term viability hinges on regulatory documentation depth rather than unit cost positioning. Watch for EMA-FDA silicone oil quantification harmonization as inflection signal for dual-compliance testing cost restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Molding Capacity Expansion | Isolator-based lines in Swiss and German facilities secure EMA GMP Annex 1 compliance deadlines. |
| Backward Integration into Bromobutyl Compounding | Captive isobutylene-isoprene supply hedges petrochemical feedstock volatility for margin stability. |
| Laminated Film-Coating Technology Partnership | Multilayer barrier systems eliminate drug-rubber contact for Massachusetts monoclonal antibody portfolios. |
| Indian Biologics Manufacturing Joint Venture | CDSCO accelerated approval pathways attract fill-finish investment ahead of domestic elastomer capacity. |
| Dual-Protocol Analytical Laboratory Investment | Mass spectrometry capacity in Basel and Boston clusters compresses FDA-EMA qualification timelines. |
Research Methodology
EMA regulatory filings, FDA Type III Drug Master File submissions, and ISO 8871 certification databases formed the secondary backbone for supplier qualification mapping. Primary interviews with fill-finish operations directors, regulatory affairs managers at pharmaceutical packagers, elastomer compounding technical leads, and procurement officers at contract manufacturing organizations validated secondary intelligence. Bottom-up triangulation across material-grade volume estimates and top-down reconciliation against biologics fill-finish capacity expansion anchored market sizing.
Bottom-up modeling segmented demand across rubber, silicone, plastic, and metal material chemistries, dimensional precision tiers, and certification-grade procurement channels. Cross-segment CAGRs were derived from biologics manufacturing expansion rates, regulatory compliance upgrade cycles, and substitution elasticity between coated elastomer and laminated film technologies. Forecast inputs incorporated REACH nitrosamine restriction implementation timelines and NMPA registration pathway acceleration in China.
Several conditions sit outside the modeled scope, including sudden bromobutyl feedstock supply disruptions, unilateral EMA-FDA silicone oil limit divergence, and auto-injector device standardization failures. Forecasts reflect assumptions about regulatory harmonization progress and cleanroom molding capacity commissioning schedules. Stakeholders should weight assumptions against their own operating context and dual-protocol testing expenditure thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Global Die Cut Lids Market
Caps and Closures
Fixed Length Seals Market
Caps and Closures
Fez Caps Market
Caps and Closures
Plastic Tamper Evident Closures Market
Caps and Closures
Germany Plastic Caps and Closures Market
Caps and Closures
Twist Caps Market
Caps and Closures
Flat Valve Caps and Closures Market
Caps and Closures
Humidity Indicator Plugs Market
Caps and Closures
Beverage Caps and Closures Market
Caps and Closures
Foam End Caps Market
Caps and Closures
Laminated Tube Closure Market
Caps and Closures
Screw Closure Market
Caps and Closures
Europe Metal Caps and Closures Market
Caps and Closures
Canada Plastic Caps and Closures Market
Caps and Closures
Latin America Plastic Caps and Closure Market
Caps and Closures
Global Aluminum Caps and Closures Market