
 Bar Top Corks Market | 2026-2036
Bar Top Corks Market Size, Share, and Industry Trends Forecast 2026-2036
Bar Top Corks Market Analytics
Multi-source procurement toward vertically integrated supply chains is realigning how wineries and distilleries secure bar top cork inventories. Corticeira Amorim leverages its Portuguese cork forest holdings to control raw material flows from harvest through finished closure. WidgetCo competes through synthetic bar top alternatives that bypass agricultural supply volatility. Berlin Packaging sustains broad distribution networks across North American beverage accounts.
Bar top corks are cylindrical closure devices, typically 19–25 mm in diameter, manufactured from natural cork bark or extruded polymer composites, designed to seal bottles with a protruding grip for manual extraction without tools. Their primary commercial purpose is to provide resealable, brand-visible closures for premium spirits, wine, and specialty food vessels. Natural cork material commands the highest margin pool among material type segments due to scarcity of certified Quercus suber bark and heritage positioning in spirits bottling. Synthetic and composite categories are expanding fastest in beverage packaging applications where lot consistency and taint elimination outweigh terroir signaling. Standard size configurations dominate volume, though custom dimensions in micro and large formats extract premium pricing from craft distilleries seeking differentiation.
FDA food-contact substance regulations in the United States and EU REACH chemical restrictions govern extractable compounds and migration limits for all closure materials contacting alcoholic beverages. EFSA and the EU F-Gas Regulation indirectly shape material selection by pressuring reduction of synthetic petroleum inputs in favor of renewable feedstocks. Stakeholders must monitor evolving biodegradability certifications and closed-loop collection mandates that will determine which material platforms retain shelf access across key export markets.
Market Dynamics
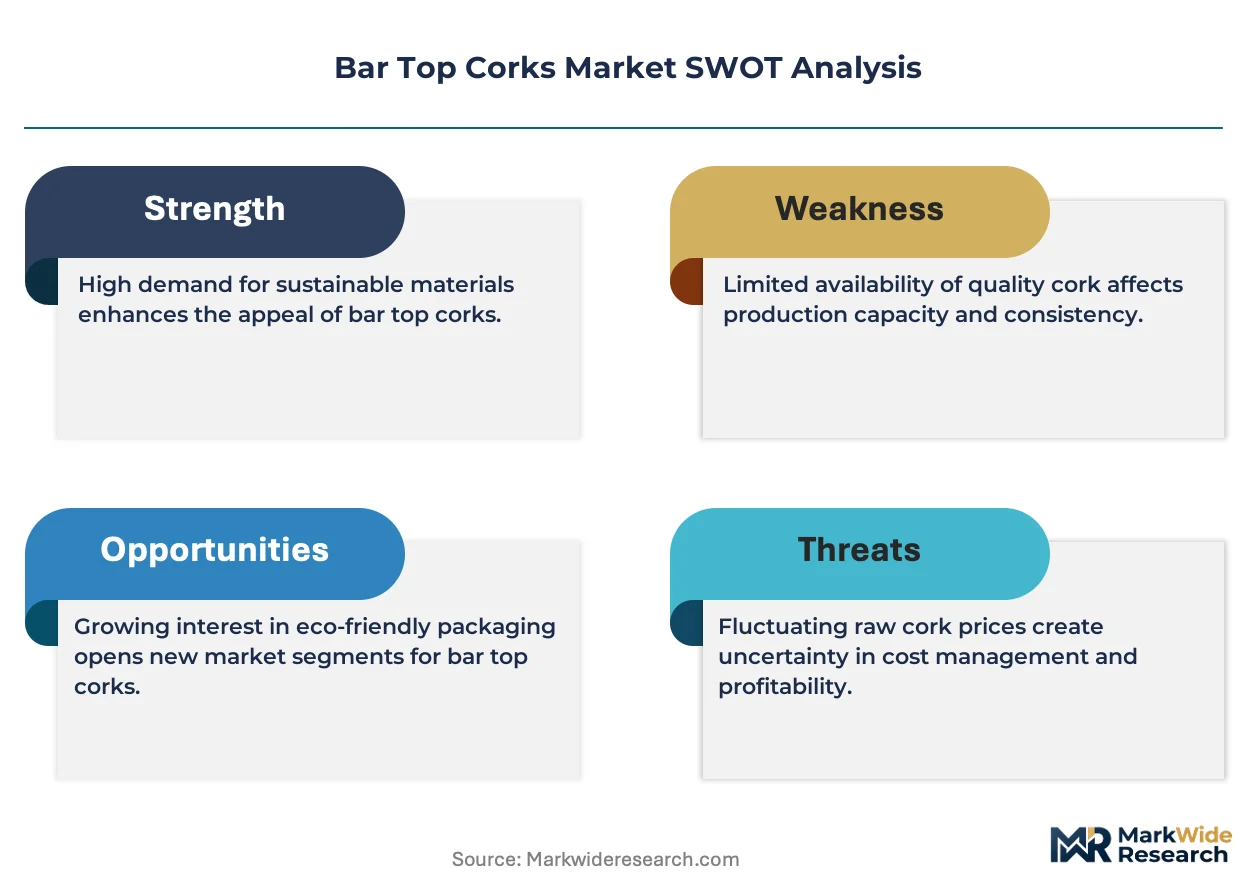
EU REACH chemical compliance standards and the EU Green Deal are tightening material specifications for closure manufacturers, forcing reformulation of synthetic bar top corks and accelerating natural cork certification requirements across Portuguese supply chains.
Growth Catalysts
- Craft Spirits Expansion:Premium craft distilleries in the United States and Germany are expanding natural cork bar top adoption for heritage positioning and manual resealability in high-proof bottling.
- EU Green Deal:Renewable feedstock mandates under the EU F-Gas Regulation are pressuring reduction of petroleum-based synthetic inputs, favoring certified Quercus suber bark sourcing.
- Portuguese Forest Infrastructure:Historic cork oak reserves and established processing clusters in the Alentejo region concentrate harvest-to-finished-closure capability unmatched by competing geographies.
Market Restraints
- Agricultural Supply Volatility:Nine-year cork oak bark harvest cycles create raw material timing mismatches against quarterly beverage production schedules.
- Geographic Concentration Risk:Overreliance on Portuguese cork forest holdings exposes buyers to regional drought, wildfire, and climate-induced yield fluctuation.
- Technical Performance Ceiling:Natural cork's 2-5% taint incidence rate persists despite surface treatment advances, driving risk-averse distilleries toward synthetic alternatives.
Strategic Opportunities
- Indian Premium Spirits:Underpenetrated craft gin and single malt whisky bottlers in Maharashtra and Karnataka present first-mover natural cork positioning opportunities.
- Biodegradability Certification:Emerging closed-loop collection mandates in France and Germany will determine which material platforms retain retail shelf access.
- Digital Print Convergence:Laser-etched bar top corks combined with NFC authentication tags enable anti-counterfeiting and direct-to-consumer engagement for luxury spirits brands.
Industry Challenges
- Certification Timeline Compression:EU REACH pre-registration dossiers for new polymer formulations require 18-24 month toxicology review cycles that lag behind product development schedules.
- Legacy Equipment Retrofit Costs:Distillery capping lines engineered for 19mm standard formats face six-figure capital outlays to accommodate custom 25mm micro-batch configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bar Top Corks Market |
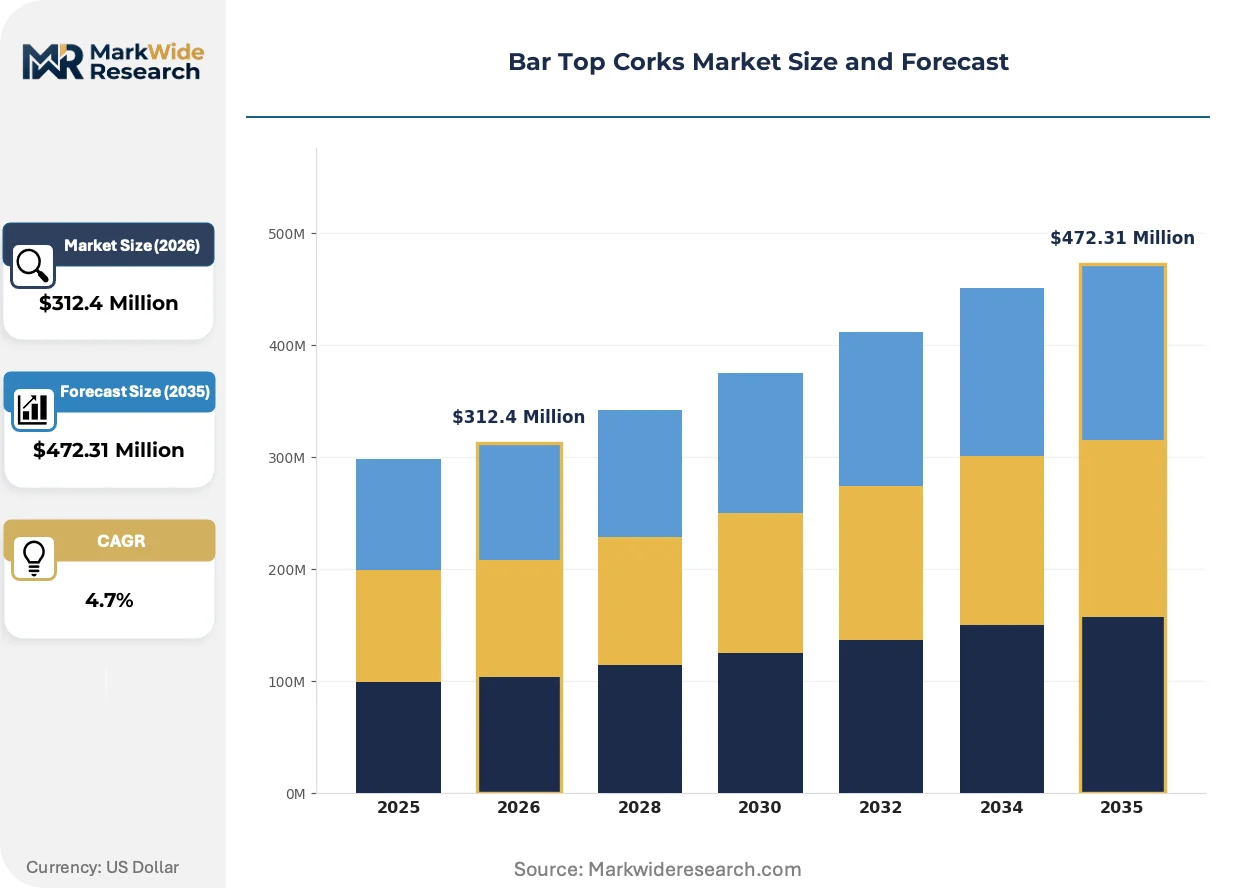
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cork, Synthetic, Plastic, Composite Application: Wine Bottling, Spirits Bottling, Beverage Packaging, Food Preservation End User: Restaurants, Retailers, Distributors, Breweries Size: Standard, Micro, Large, Custom |
| Companies Covered | Corticeira Amorim, WidgetCo, ACIC Cork and Closures, The Cary Company, Berlin Packaging, Tap Group, Bottle Express, Vinolok Closure, Guala Closures Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bar Top Corks Market Evolving Landscape
Material science advances and regulatory pressure on extractable compounds are compressing the performance gap between natural and synthetic bar top corks while reshaping procurement criteria across premium beverage packaging.
Hybrid composite bar top corks are unifying natural cork's tactile authenticity with synthetic consistency by laminating thin bark veneers over extruded polymer cores. Mid-tier wineries in Spain and Italy are adopting these constructions at accelerating pace to eliminate lot-to-lot variability. This unifying architecture is compressing the traditional premium-economy material segmentation into a single intermediate tier.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons are tightening extractable compound limits for all closure materials contacting alcoholic beverages above 15% ABV. Closure manufacturers serving EU export markets must reformulate adhesive binders and surface coatings to comply with migration thresholds. Portuguese natural cork processors are investing in steam-based cleaning protocols to eliminate chemical dependency and secure uninterrupted market access.
Direct-procurement relationships between distilleries and cork forest cooperatives are displacing traditional distributor intermediaries in North American premium spirits. Craft producers in Kentucky and Tennessee are contracting directly with Alentejo harvest associations for certified sustainable supply. This channel restructuring is most visible in bourbon and rye whiskey segments where provenance storytelling commands bottle price premiums.
Bar Top Corks Market Segmentation
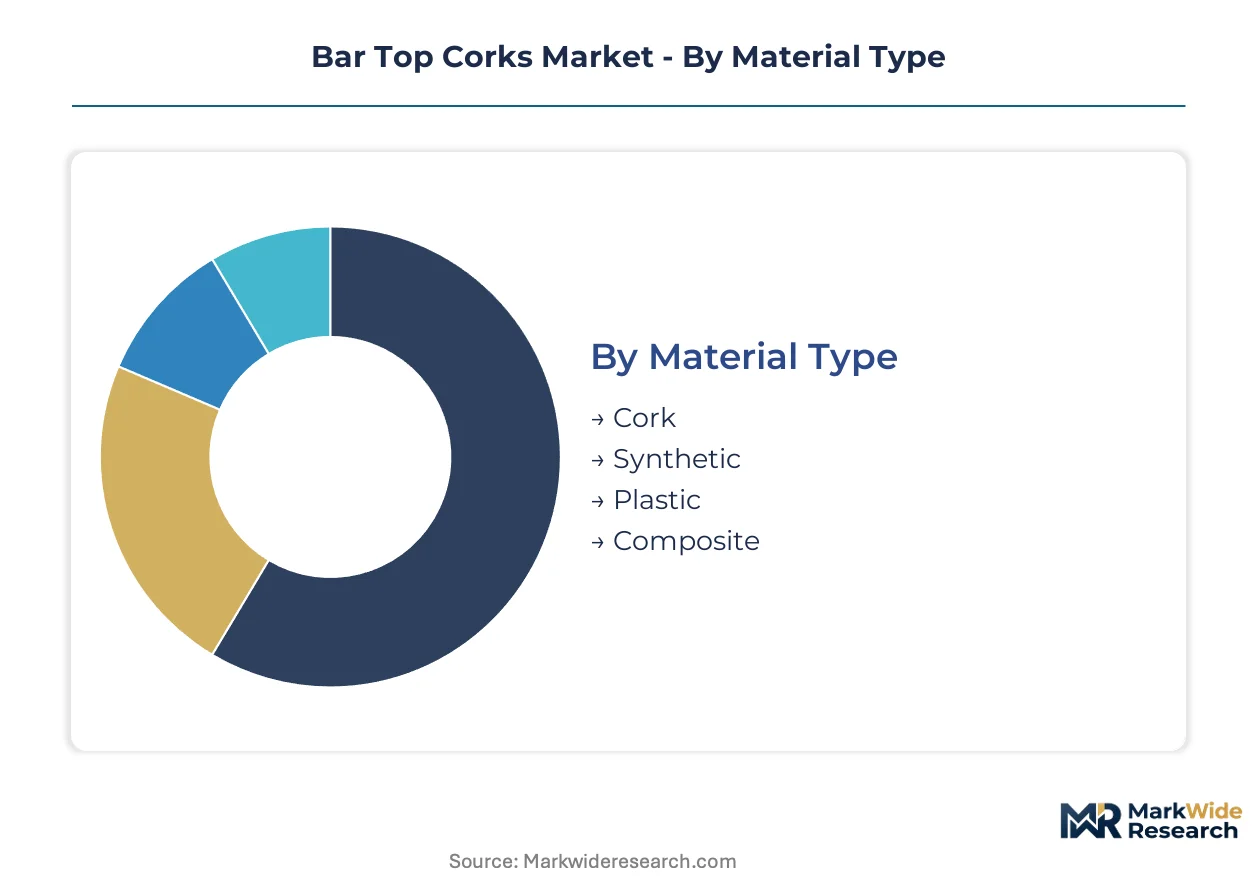
Bar top cork specifications diverge sharply across material platforms and end-use requirements, with procurement decisions increasingly driven by regulatory compliance timelines and provenance signaling rather than unit cost alone. Distilleries and wineries segment their closure sourcing to balance batch consistency, heritage authentication, and capping line compatibility.
Material Type:
Technical specifications around extractable compounds and renewable feedstock certification define competitive positioning across material categories.
- Cork:Harvested Quercus suber bark processed through steam-based cleaning protocols eliminates chemical dependency for EU REACH compliance. Demand concentrates in Portuguese Alentejo supply chains where forest cooperatives control harvest-to-finished-closure capability for premium spirits bottlers seeking heritage positioning.
- Synthetic:Extruded polymer composites formulated without polycyclic aromatic hydrocarbons meet REACH Annex XVII migration thresholds for beverages above 15% ABV. Risk-averse distilleries in Kentucky and Tennessee favor this segment to eliminate natural cork's persistent taint incidence.
- Plastic:Petroleum-derived closures face pressure under EU F-Gas Regulation renewable feedstock mandates. Cost-sensitive beverage packaging applications in mass-market wine categories sustain residual demand despite sustainability headwinds.
- Composite:Hybrid laminates unifying thin bark veneers over polymer cores compress traditional premium-economy segmentation. Spanish and Italian mid-tier wineries adopt these constructions to eliminate lot-to-lot variability without sacrificing tactile authenticity.
Mature deployment sits with Cork. Newer deployment is concentrated in Composite.
Application:
End-use specifications determine dimensional tolerances, resealability requirements, and brand visibility priorities.
- Wine Bottling:Standard 19-25mm formats dominate volume with heritage terroir signaling driving natural cork preference in appellation-controlled segments. Italian and French producers maintain strict closure provenance documentation for export certification.
- Spirits Bottling:High-proof formulations above 15% ABV demand REACH-compliant surface coatings and adhesive binders. Bourbon and rye whiskey producers in Kentucky contract directly with Portuguese harvest associations for certified sustainable supply.
- Beverage Packaging:Lot consistency requirements favor synthetic alternatives where taint elimination outweighs agricultural authenticity. German craft gin bottlers represent emerging demand concentration.
- Food Preservation:Specialty vessels for oils and preserves require neutral extractable profiles. FDA food-contact substance regulations govern US market access for all material platforms in this segment.
Volume concentration rests with Wine Bottling. Steepest expansion trajectory appears in Spirits Bottling.
End User:
Procurement scale and channel position determine specification authority and inventory holding patterns.
- Restaurants:On-premise operators prioritize resealability for by-the-glass programs and brand visibility for tableside presentation. Direct-procurement relationships with closure manufacturers are displacing distributor intermediaries in premium urban markets.
- Retailers:Private label spirits and wine programs drive specification standardization across supplier bases. Shelf access mandates in France and Germany around biodegradability certification reshape material selection criteria.
- Distributors:Inventory consolidation across multiple producer accounts favors standard 19mm formats compatible with legacy capping equipment. Six-figure capital outlays for custom 25mm micro-batch configurations create procurement friction.
- Breweries:Specialty and barrel-aged beer segments adopt bar top corks for differentiation in craft market positioning. Micro-format specifications extract premium pricing for limited-release bottling runs.
Specification authority concentrates with Restaurants. Procurement standardization dominates among Distributors.
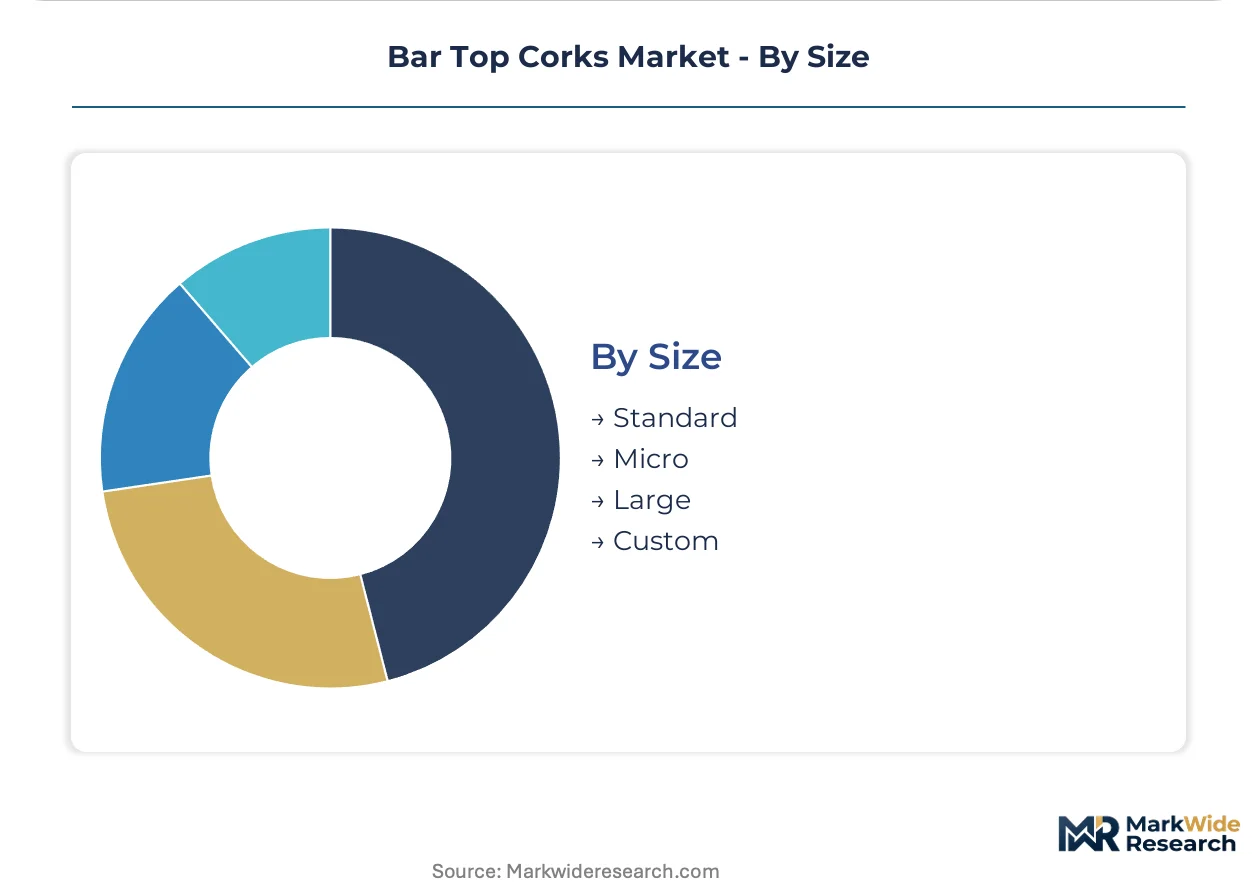
Size:
Dimensional configuration directly determines capping line compatibility and per-unit pricing tiers.
- Standard:19mm diameter specifications align with legacy distillery capping infrastructure across North American beverage accounts. Volume scale supports lowest unit economics for mass-market wine and spirits bottling.
- Micro:Sub-19mm custom dimensions serve craft distilleries seeking bottle differentiation in crowded premium segments. German and US craft producers absorb premium pricing for limited-batch positioning.
- Large:Oversized formats above 25mm accommodate specialty food preservation vessels and magnum wine presentations. Niche demand sustains higher per-unit margins despite limited volume.
- Custom:Non-standard geometries require equipment retrofit capital commitments that filter demand to well-capitalized producers. Digital print convergence with laser-etched surfaces and NFC authentication tags enables anti-counterfeiting applications.
Equipment compatibility anchors Standard. Differentiation value drives Custom.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portuguese cork oak forests in the Alentejo region anchor the raw material base for premium bar top cork production. Harvest-to-finished-closure infrastructure concentrates in this Mediterranean climate zone. Demand patterns diverge sharply across import markets based on regulatory compliance timelines and craft spirits positioning.
United States
Kentucky and Tennessee bourbon distilleries drive natural cork procurement for heritage bottle storytelling. FDA food-contact substance regulations govern extractable compound limits for all closure materials. Direct contracting with Portuguese harvest associations is displacing traditional distributor channels in the American premium spirits segment.
Germany
Craft gin bottlers in Bavaria and Baden-Württemberg represent emerging demand concentration for REACH-compliant closures. The EU F-Gas Regulation pressures reduction of petroleum-based synthetic inputs across German beverage packaging. Berlin-based distributors consolidate inventory across multiple producer accounts for standard format compatibility.
France
Appellation-controlled wine producers in Bordeaux and Burgundy maintain strict closure provenance documentation for export certification. Emerging closed-loop collection mandates in France reshape material selection criteria for retail shelf access. Champagne houses in the Marne valley sustain demand for oversized formats in magnum presentations.
Spain
Mid-tier wineries in La Rioja and Catalonia accelerate adoption of hybrid composite constructions to eliminate lot-to-lot variability. EFSA guidelines on migration thresholds influence adhesive binder reformulation across Spanish closure manufacturing. Barcelona processing clusters handle secondary finishing for cork bar tops destined for European spirits bottlers.
India
Craft gin and single malt whisky bottlers in Maharashtra and Karnataka present first-mover natural cork positioning opportunities. The country's national food safety regulator governs import specifications for alcoholic beverage closures. Mumbai-based distributors are establishing direct procurement relationships with Portuguese forest cooperatives for certified sustainable supply.
Bar Top Corks Market Competitive Landscape
Backward integration into raw material supply dominates the current landscape as manufacturers seek harvest-to-finished-closure control. The vendor base organizes around three strategic archetypes: forest-holding integrated processors, synthetic material specialists, and distribution-centric packaging houses. Portuguese forest cooperatives and extruded polymer fabricators occupy opposing ends of the material spectrum. Competitive moves concentrate on geographic sourcing partnerships and biodegradability certification acquisition.
Among Portuguese-anchored integrated processors, Corticeira Amorim represents the forest-holding archetype with captive cork oak reserves. WidgetCo occupies a position exemplifying synthetic material specialization for risk-averse distilleries. Berlin Packaging sits within the distribution-centric tier, sustaining broad North American beverage account networks without direct manufacturing engagement. These three anchors illustrate how competitive positioning splits across material provenance, technical performance, and channel reach.
| Leading Market Players |
|---|
| Corticeira Amorim |
| WidgetCo |
| ACIC Cork and Closures |
| The Cary Company |
| Berlin Packaging |
| Tap Group |
| Bottle Express |
| Vinolok Closure |
| Guala Closures Group |
| Others |
Value Network & Pricing Analysis
EU REACH chemical compliance standards gate both qualified supply and premium-tier pricing access for bar top cork manufacturers, forcing reformulation investments that separate certified Portuguese natural cork processors from uncertified competitors while compressing margins on synthetic alternatives facing renewable feedstock mandates.
Pricing Analysis
Warranty-backed taint guarantees and unbundled certification premiums define the dominant contract-based long-term offtake structure. Price differentiation rests on FSC chain-of-custody certification grade and volume scale commitments from Kentucky bourbon distilleries. Cost compression in synthetic tiers is intensifying because EU F-Gas Regulation pressures petroleum-derived input costs. Mass-market wine bottlers exhibit highest price sensitivity; heritage spirits producers absorb premiums for provenance documentation.
Supply Chain Analysis
Regional distribution centers in Porto and Lisbon operate hub-and-spoke patterns feeding European spirits bottlers and North American importer consolidation points. Supply concentrates in Portugal, Spain, and Italy for harvest and secondary processing. Raw material flows draw from Quercus suber bark, extruded polymer pellets, and adhesive binder formulations. Single-source vulnerability around Alentejo forest holdings exposes buyers to drought-induced yield fluctuation. Distribution runs through direct-procurement relationships displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bar top cork manufacturing is consolidating around backward-integrated Portuguese processors as REACH compliance timelines and certification costs force smaller synthetic specialists toward exit or acquisition.
For Market Incumbents: Hedge agricultural supply volatility through captive cork forest lease arrangements in Alentejo cooperatives. Accelerate steam-based cleaning protocol deployment to eliminate chemical dependency and secure uninterrupted EU market access against REACH Annex XVII tightening.
For New Entrants and Emerging Players: Launch via direct-to-distillery contracting models targeting Maharashtra and Karnataka craft gin bottlers in India. Penetrate the underdeveloped single malt whisky closure segment through certified sustainable supply partnerships with Mumbai-based distributors seeking Portuguese forest cooperative relationships.
For Investors and Strategic Acquirers: First-mover biodegradability certification acquisition in France and Germany is the leading indicator that material platforms will retain retail shelf access. Target mid-tier composite manufacturers with hybrid laminate capabilities across Spanish and Italian wine markets. Watch for closed-loop collection mandate announcements as the inflection signal triggering consolidation urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cork Forest Holdings | Captive Quercus suber supply insulates Corticeira Amorim against Alentejo drought risk. |
| Steam-Based Cleaning Protocol Deployment | Eliminates chemical dependency for REACH Annex XVII compliance in natural cork processing. |
| Direct-to-Distillery Contracting Model | Kentucky bourbon producers bypass distributor intermediaries for provenance storytelling. |
| Hybrid Composite Laminate Development | Spanish mid-tier wineries adopt bark-veneer-over-polymer-core constructions for consistency. |
| Biodegradability Certification Acquisition | French and German retail shelf access mandates favor certified material platforms. |
Research Methodology
Trade association filings, EU regulatory dossiers, and Portuguese agricultural statistics formed the secondary backbone of this analysis. Primary interviews with closure manufacturing executives, distillery procurement directors, Alentejo forest cooperative managers, and beverage packaging distributors combined with secondary validation. Bottom-up volume estimates triangulated against top-down market sizing across material type and application segments.
Historical trendline analysis of harvest yields, import volumes, and producer capacity utilization informed the analytical framework across the projection horizon. Segmentation dimensions modeled include material platform, end-use application, dimensional configuration, and geographic sourcing cluster. CAGRs derived from fitted growth curves incorporating regulatory compliance timeline impacts and craft spirits expansion trajectories. Industry-specific forecast inputs encompass cork oak bark harvest cycle timing and REACH pre-registration dossier approval rates.
Climate-induced yield fluctuation, regulatory restriction tightening, and synthetic feedstock cost volatility are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Heat Induction Cap Liner Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
Molded Fiber Pulp Cap Market
Caps and Closures
Crown Caps Market
Caps and Closures
Asia Pacific Metal Caps and Closures Market
Caps and Closures
Molded Fiber End Caps Market
Caps and Closures
Crimp-On Spouts Market
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
T-Top Closures Market
Caps and Closures
Fez Caps Market
Caps and Closures
Gamma Seal Lids Market
Caps and Closures
Foamed End Caps Market
Caps and Closures
Global Die Cut Lids Market
Caps and Closures
Thailand Plastic Caps and Closures Market
Caps and Closures
Caps and Closures Market
Caps and Closures
North America Metal Caps and Closures Market