
 Twist Dispensing Closures Market | 2026-2036
Twist Dispensing Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Twist Dispensing Closures Market Analytics
Mono-material polypropylene designs is narrowing the compatibility gap between recycling infrastructure and closure performance. Berry Global Inc. leverages vertical integration across resin compounding and injection molding to control cost structures. Silgan Holdings Inc. anchors North American supply through high-volume contracts with food and beverage bottlers. AptarGroup, Inc. differentiates via precision dosing mechanisms for pharmaceutical applications.
Twist dispensing closures are threaded dispensing systems engineered with specific torque-release profiles, typically molded from polypropylene or polyethylene with internal plug-seal geometries that control viscous and liquid flow rates across variable pressure conditions. Their primary commercial purpose is to combine resealability with controlled product dispensing for consumer convenience and contamination prevention. Plastic closures dominate volume due to cost scalability, while composite formats capture margin pools in pharmaceutical applications where barrier performance commands premium positioning. The Food & Beverage application sustains the largest absolute demand base, though Pharmaceutical represents the fastest structural expansion as regulatory compliance requirements intensify.
FDA 21 CFR regulations govern child-resistant and tamper-evident performance for over-the-counter and prescription packaging in the United States. EMA's MDR framework and REACH chemical restrictions in Europe constrain material selection and migration limits for closures contacting consumable products. Stakeholders must monitor evolving extended producer responsibility mandates and recyclability certification schemes to align product development with downstream waste management infrastructure requirements.
Market Dynamics
Pharmaceutical serialization mandates and extended producer responsibility schemes are compressing design cycles while elevating material traceability requirements across the twist dispensing closure supply base.
Growth Catalysts
- Unit-dose pharmaceutical packaging:FDA 21 CFR child-resistant standards are accelerating format conversion from bulk containers to single-use dispensing systems in over-the-counter and prescription segments.
- REACH chemical restrictions:ECHA migration limits on phthalates and bisphenols are forcing material upgrades that favor polypropylene closures with certified barrier performance.
- Precision molding clusters:Southern Germany's concentration of medical-grade injection facilities is drawing European pharmaceutical brand owners seeking validated supply chains.
Market Restraints
- Propylene feedstock volatility:Crude oil and naphtha price swings compress margin stability for polypropylene-dominant closure producers.
- Tooling lead time concentration:High-cavitation mold fabrication capacity concentrates in Austria and Switzerland, creating bottlenecks for new product qualification.
- Glass vial substitution:Pre-filled syringe formats with integrated Luer locks are capturing share in parenteral drug delivery, displacing threaded closure applications.
Strategic Opportunities
- Indian pharmaceutical export packaging:CDSCO alignment with ICH stability guidelines is opening validated closure demand from European and North American drug sponsors.
- Connected closure integration:Near-field communication chips and printed electronics are converging with tamper-evident designs for cold-chain verification.
- Refill retail channels:Bulk dispensing stations in personal care retail are creating demand for standardized 28-410 thread formats compatible with consumer refill bottles.
Industry Challenges
- Validation engineer scarcity:Pharmaceutical packaging qualification protocols require specialized expertise in extractables-leachables testing that outpaces talent pipeline development.
- ISO 15378 certification timelines:Quality management system audits for primary packaging materials extend new supplier onboarding to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Twist Dispensing Closures Market |
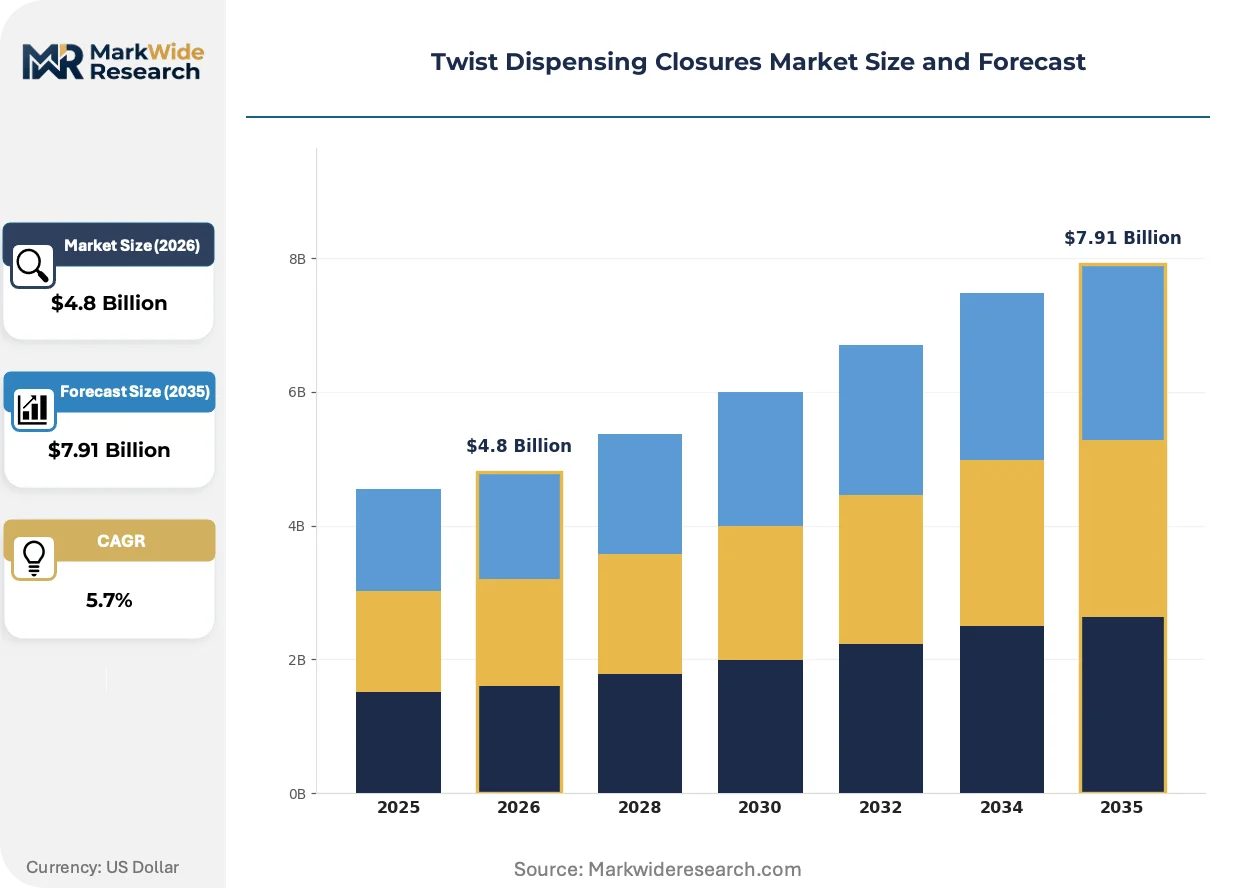
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Glass, Composite Application: Food & Beverage, Personal Care, Pharmaceutical, Household Capacity: Small, Medium, Large, Extra Large Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | O.Berk Company, LLC, Silgan Holdings Inc., Crown Holdings, Inc., Berry Global Inc., AptarGroup, Inc., Ardagh Group S.A., United States Plastic Corporation, Weener Empire Plastics Pvt. Ltd., Mold-Rite Plastics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Twist Dispensing Closures Market Evolving Landscape
Material science advances and regulatory transparency mandates are reconfiguring how closure performance is specified, tested, and communicated through the value chain.
Mono-material polypropylene constructions with integrated living hinges are migrating from food and beverage applications into pharmaceutical dispensing formats. Generic drug packagers in Eastern Europe are adopting these designs to preempt EMA recyclability disclosure requirements. The shift is compressing demand for multi-component assemblies with metal or elastomer inserts.
EMA's Medical Device Regulation framework is reclassifying certain drug-device combination closures as Class IIa medical devices. This reclassification triggers notified body involvement and clinical evaluation requirements that extend time-to-market for novel dosing mechanisms. German and Swiss pharmaceutical contract manufacturers are responding by front-loading regulatory strategy into early design phases.
Brand owner consolidation in personal care is compressing supplier rosters and extending contract durations. Unilever and L'Oréal procurement teams are shifting from spot purchasing to three-year framework agreements with volume commitments and joint sustainability targets. This pattern is most visible in the Netherlands and France, where headquarters proximity enables collaborative packaging development programs.
Twist Dispensing Closures Market Segmentation
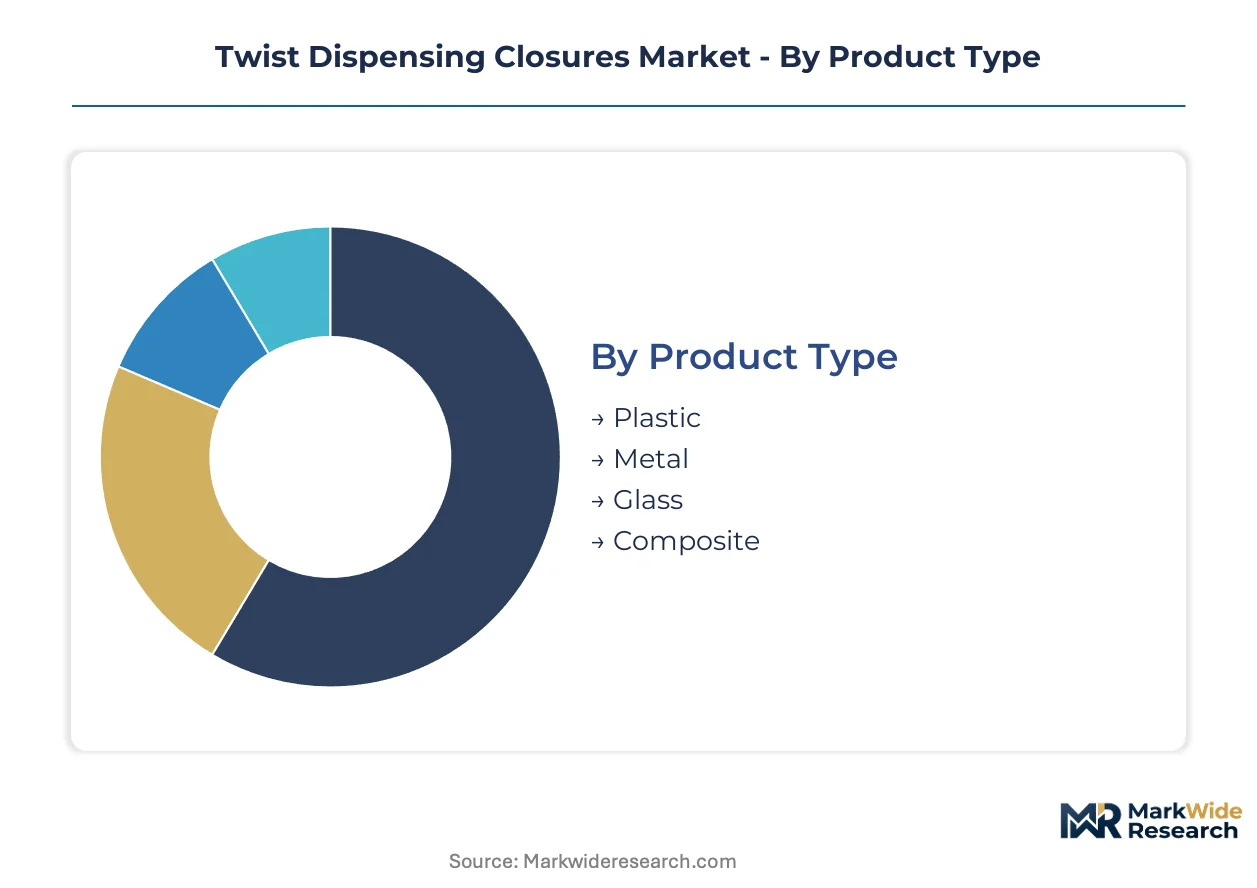
Twist dispensing closures serve divergent performance requirements across material grades and end-use specifications. Segmentation reveals how polypropylene-dominant formats coexist with premium barrier composites in regulated pharmaceutical environments.
Product Type:
Mature commodity formats anchor volume throughput while engineered composites capture margin in compliance-intensive applications.
- Plastic:Polypropylene and polyethylene homopolymers constitute the baseline material platform for cost-scalable injection molding. Demand concentrates in German food and beverage bottlers seeking ISO 15378-aligned supply chains for extended producer responsibility compliance.
- Metal:Aluminum and tinplate closures deliver oxygen barrier performance for essential oil and solvent-based formulations. Swiss pharmaceutical contract manufacturers specify metal-threaded formats for parenteral drug stability under ICH guidelines.
- Glass:Borosilicate and soda-lime threaded closures serve high-temperature sterilization protocols in parenteral packaging.
- Composite:Multi-layer constructions with elastomeric liners command premium positioning in tamper-evident pharmaceutical applications.
Plastic handles the majority of throughput; composite is the fastest mover on share.
Application:
End-use concentration patterns reflect divergent regulatory exposure and convenience-driven format evolution.
- Food & Beverage:Standard 28-410 thread formats dominate condiment, sauce, and beverage dispensing with resealability as the primary functional specification. German retail chains are consolidating supplier rosters around mono-material polypropylene designs for recyclability certification.
- Pharmaceutical:Child-resistant and tamper-evident mechanisms integrate with unit-dose dispensing systems for over-the-counter and prescription segments. FDA 21 CFR compliance requirements are compressing design cycles for generic drug packagers in Eastern Europe.
- Personal Care:Precision dosing mechanisms serve viscosity-variable formulations from shampoos to serums.
- Household:Chemical resistance specifications govern closure selection for cleaning and disinfectant products.
Food & Beverage maintains absolute volume leadership; pharmaceutical is expanding most quickly as serialization mandates intensify.
Capacity:
Format sizing aligns with consumption patterns and retail channel requirements across refill and single-use paradigms.
- Small:Volumes under 50 milliliters serve travel-size personal care and pharmaceutical unit-dose formats. Netherlands-based retailers are standardizing small-format threads for bulk refill station compatibility.
- Medium:100-250 milliliter capacities balance portability with consumption economics for household and personal care applications.
- Large:500 milliliter-plus formats concentrate in food service and institutional dispensing channels.
- Extra Large:Bulk containers exceeding one liter serve commercial and refill retail applications with pump-integrated closure systems.
Medium capacity generates the highest absolute unit demand; extra large is climbing the fastest as refill retail channels expand.
Distribution Channel:
Channel mix reflects procurement centralization trends and sustainability-driven supplier consolidation.
- Online:E-commerce direct fulfillment is gaining traction for specialty pharmaceutical and personal care closures with short lead-time requirements. French brand owners are piloting digital procurement platforms for packaging component sourcing.
- Retail:Brick-and-mortar packaging distributors serve mid-volume food and beverage processors with standardized inventory programs.
- Direct Sales:Account-managed relationships dominate pharmaceutical qualification protocols requiring extractables-leachables documentation.
- Wholesalers:Aggregated distribution networks serve fragmented household and personal care manufacturers in Eastern European markets.
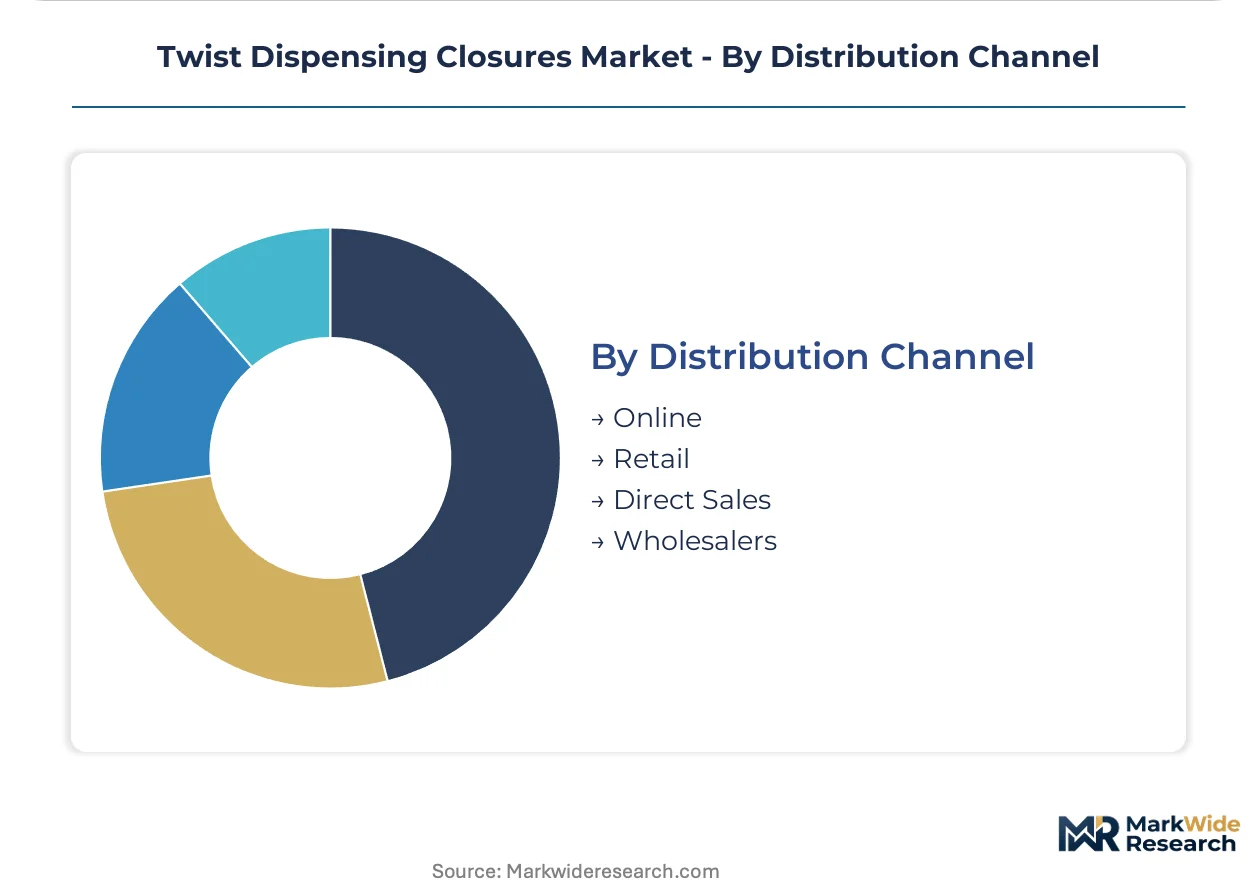
Direct sales commands the highest value per transaction; online is gaining share fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract manufacturers and personal care brand owners concentrate procurement decisions in jurisdictions with validated supply chains and harmonized regulatory frameworks. FDA 21 CFR alignment in North America, EMA MDR implementation in Europe, and CDSCO-ICH convergence in India are reshaping supplier qualification protocols. Regional demand patterns diverge based on serialization mandates, extended producer responsibility schemes, and precision molding infrastructure availability.
United States
Generic drug packagers and over-the-counter brand owners drive unit-dose format conversion. FDA 21 CFR child-resistant closure standards compress design cycles for tamper-evident configurations. New Jersey and Pennsylvania host dense clusters of pharmaceutical packaging converters serving FDA-inspected drug sponsors.
Germany
Precision molding infrastructure draws European pharmaceutical brand owners seeking ISO 15378-validated supply chains. EMA MDR reclassification of certain drug-device closures as Class IIa medical devices extends regulatory timelines. Southern Germany's medical-grade injection facilities anchor continental supply for unit-dose dispensing systems.
Switzerland
Pharmaceutical contract manufacturers specify metal-threaded and barrier composite closures for parenteral stability under ICH guidelines. Swissmedic oversight of primary packaging materials elevates extractables-leachables documentation requirements. Basel-Zurich corridor hosts specialized converters serving Big Pharma parenteral packaging demand.
India
CDSCO alignment with ICH stability guidelines opens validated closure export opportunities to European and North American drug sponsors. Maharashtra and Gujarat pharmaceutical packaging zones are upgrading molding capabilities for serialization-compliant formats. Mumbai-Pune corridor concentrates contract manufacturing demand for oral solid dose and liquid dispensing closures.
France
Personal care brand owner consolidation compresses supplier rosters toward three-year framework agreements with sustainability targets. Unilever and L'Oréal procurement teams prioritize joint packaging development programs. Paris and Lyon headquarters proximity enables collaborative mono-material polypropylene design initiatives.
Twist Dispensing Closures Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. The vendor base separates into consolidated multi-material converters, precision-dosing specialists, and regional injection molding fabricators. Three archetypes dominate: vertically integrated resin-to-closure operators, pharmaceutical-grade validation specialists, and high-volume food and beverage suppliers. Competitive moves concentrate on backward integration into resin compounding and strategic partnerships for serialization-ready format development.
Within the pharmaceutical-grade tier, AptarGroup, Inc. and Berry Global Inc. exemplify divergent strategic positions. Silgan Holdings Inc. anchors high-volume supply relationships with North American bottlers. O.Berk Company, LLC represents the distribution-specialist archetype serving mid-volume processors with standardized inventory programs. These named entities illustrate how competitive positioning fragments across validation intensity, volume scale, and channel control dimensions.
| Leading Market Players |
|---|
| O.Berk Company, LLC |
| Silgan Holdings Inc. |
| Crown Holdings, Inc. |
| Berry Global Inc. |
| AptarGroup, Inc. |
| Ardagh Group S.A. |
| United States Plastic Corporation |
| Weener Empire Plastics Pvt. Ltd. |
| Mold-Rite Plastics, Inc. |
| Others |
Value Network & Pricing Analysis
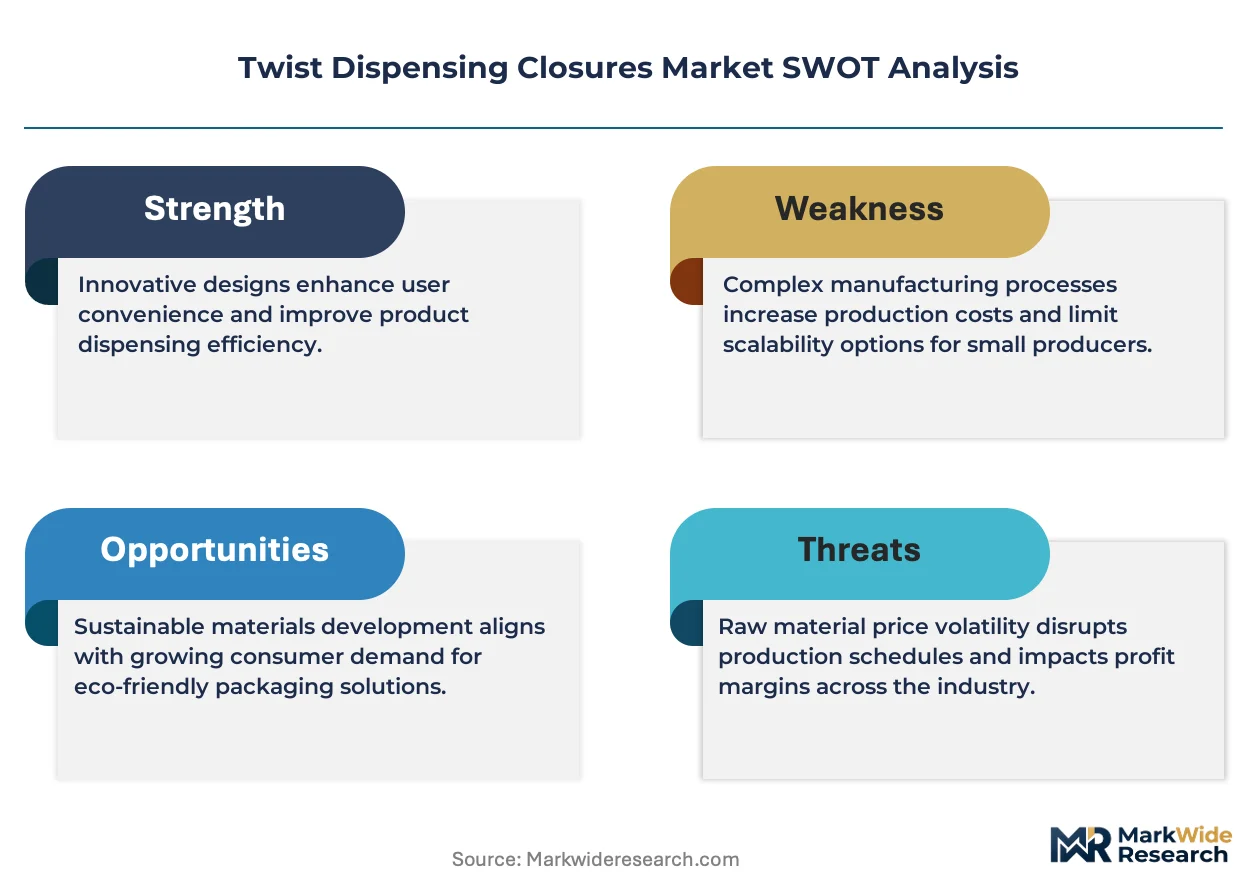
Propylene feedstock volatility compresses margin stability for polypropylene-dominant closure producers while simultaneously widening spreads between commodity-grade and pharmaceutical-validated tiers. This single-source dependency on naphtha-cracker outputs forces converters to index long-term contracts against regional propylene benchmarks, embedding cost-pass-through mechanisms that differentiate pricing power across buyer segments.
Pricing Analysis
Cost-plus contracts with propylene indexation dominate procurement relationships between German precision molders and European pharmaceutical packagers. Price differentiation separates ISO 15378-certified pharmaceutical closures from standard food-grade formats, with barrier composite constructions commanding premiums based on extractables-leachables documentation depth. Pricing pressure stems from REACH-mandated material upgrades that elevate raw material costs without commensurate price recovery in commoditized segments. Generic drug packagers in Eastern Europe exhibit highest price sensitivity, while Swiss parenteral contract manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Tariff exposure between United States and China elevates sourcing risk for metal closure components and specialty resin additives. Supply concentrates in Germany, Switzerland, and Austria, where high-cavitation mold fabrication capacity and medical-grade injection molding clusters anchor continental pharmaceutical packaging supply. Raw material dependencies include polypropylene homopolymer, elastomeric liner compounds, and precision-machined aluminum threads. Distribution runs through direct account-managed relationships for pharmaceutical qualifications, with retail distributors serving mid-volume food and beverage processors through standardized inventory programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates durable defensive moats for validated closure suppliers, as ISO 15378 certification timelines and FDA 21 CFR compliance protocols embed switching costs that protect incumbent positioning against price-based competition.
For Market Incumbents: Pre-empt glass vial substitution in parenteral drug delivery by accelerating connected closure development with integrated NFC chips for cold-chain verification. Backward integration into resin compounding secures margin control against propylene volatility, while capacity expansion in Southern Germany reinforces proximity to pharmaceutical contract manufacturing clusters facing EMA MDR reclassification timelines. For New Entrants and Emerging Players: Indian pharmaceutical export packaging represents the most penetrable entry point, where CDSCO-ICH alignment creates validated closure demand from European and North American drug sponsors underserved by established suppliers. Refill retail channels in personal care offer secondary white-space, with standardized 28-410 thread formats compatible with bulk dispensing stations enabling private-label positioning. A go-to-market strategy anchored in serialization-compliant format development bypasses direct competition with entrenched European molders. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision-dosing specialists with pharmaceutical validation infrastructure over commodity-volume players. Long-term viability hinges on exposure to unit-dose pharmaceutical packaging expansion and connected closure integration trends. Acquisition targets should demonstrate established extractables-leachables testing protocols and active FDA 21 CFR compliance programs. The signal to watch is EMA MDR reclassification implementation velocity, which will accelerate demand for notified body-validated suppliers and compress qualification timelines for unprepared converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply insulates Berry Global from naphtha price volatility and secures formulation control. |
| Connected Closure Development | NFC chip integration with tamper-evident designs enables AptarGroup to capture cold-chain verification demand from biologics sponsors. |
| ISO 15378 Certification Investment | Quality management system accreditation compresses German pharmaceutical supplier onboarding timelines against Austrian competitors. |
| Joint Sustainability Targets | Three-year framework agreements with Unilever and L'Oréal procurement teams lock in volume commitments for mono-material polypropylene formats. |
| Precision Molding Cluster Expansion | Southern Germany medical-grade injection capacity draws European pharmaceutical brand owners seeking validated supply chains. |
Research Methodology
A spread of perspectives from pharmaceutical packaging engineers, regulatory affairs specialists, resin procurement managers, and retail category buyers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 21 CFR guidance documents, EMA MDR implementation notices, REACH chemical restriction updates, and customs trade data for polypropylene closure imports. Bottom-up modeling of unit-dose pharmaceutical packaging conversion rates and top-down reconciliation against extended producer responsibility scheme disclosures ensured analytical coherence.
Demand-supply balance framing anchored the forecast framework across the analysis window. Segmentation dimensions modeled include material grade tier, end-use application, capacity format, and distribution channel, with regional regulatory cluster effects incorporated for pharmaceutical serialization mandates. CAGRs derived from trend extrapolation of unit-dose format adoption, validated against precision molding capacity expansion announcements and pharmaceutical contract manufacturing location decisions.
Practitioners should monitor propylene feedstock price movements, EMA MDR reclassification implementation delays, and glass vial substitution rates in parenteral drug delivery for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
APAC Plastic Caps and Closures Market
Caps and Closures
Steel Ring Pull Caps Market
Caps and Closures
Fixed Length Seals Market
Caps and Closures
Spout Closures Market
Caps and Closures
Italy Plastic Caps and Closures Market
Caps and Closures
Dual Flap Dispensing Closure Market
Caps and Closures
Peelable Lid Stock Market
Caps and Closures
Germany Plastic Caps and Closures Market
Caps and Closures
Aerosol Valves Market
Caps and Closures
Ribbed Phenolic Caps Market
Caps and Closures
Aluminium ROPP Closures Market
Caps and Closures
Plastic Tamper Evident Closures Market
Caps and Closures
Snap Cap Vials Market
Caps and Closures
Middle East and Africa Plastic Caps and Closures Market
Caps and Closures
Flat Valve Caps and Closures Market
Caps and Closures
Elastomeric Closures Market