
 Drum Plugs Market | 2026-2036
Drum Plugs Market Size, Share, and Industry Trends Forecast 2026-2036
Drum Plugs Market Foresight
Skilled polymer tooling technicians is unwinding capacity constraints at several drum plug producers. BASCO leverages its Midwest manufacturing footprint to serve bulk chemical clients with standardized delivery schedules. Greif sustains vertical integration from steel drum production to captive plug supply, locking in fleet customers. Mauser Packaging Solutions anchors European demand through its reusable industrial packaging systems.
Drum plugs are threaded or press-fit closures engineered to seal 55-gallon steel, plastic, or fiber drums against leakage, contamination, and pressure differentials during handling, with typical specifications including two-inch NPS threading and ethylene propylene diene monomer gaskets for chemical resistance. Their primary purpose is securing hazardous and non-hazardous liquids through transport, storage, and dispensing cycles. Leak-proof plugs lead product type demand where caustic and flammable contents require vapor-tight sealing, while vent plugs represent the fastest-growing category as pressure-equalization needs expand in temperature-variable supply chains. Plastic dominates material selection for cost-sensitive food and beverage applications, though metal persists in solvent-heavy chemical environments where thermal tolerance exceeds polymer limits.
EPA hazardous waste manifest rules and OSHA drum handling standards shape U.S. product specifications, while REACH compliance in Europe restricts certain plasticizer chemistries in gasket compounds. FDA food contact material regulations govern drum plug selection for edible oil and ingredient transport in North America. Stakeholders must weigh material certification costs against regional compliance exposure when configuring product portfolios for cross-border chemical and food logistics.
Market Dynamics
EPA hazardous waste manifest rules and OSHA drum handling standards are tightening procurement specifications across chemical logistics, forcing manufacturers toward vapor-tight sealing technologies and certified gasket materials that exceed legacy performance thresholds.
Growth Catalysts
- REACH compliance mandates:ECHA restrictions on plasticizer chemistries in gasket compounds are accelerating demand for EPDM and fluoropolymer alternatives that maintain chemical resistance under thermal cycling.
- Reusable industrial packaging systems:Fleet operators in Germany and the United States are standardizing on captive plug supply models that reduce per-use costs across multi-trip drum rotations.
- Pressure-equalization requirements:Temperature-variable supply chains spanning the US Gulf Coast and Rotterdam chemical corridors are expanding vent plug installations to prevent drum deformation during transit.
Market Restraints
- Steel price volatility:Input cost swings for metal plug components are compressing margins at mid-tier producers serving solvent-heavy chemical environments.
- Polymer certification backlog:FDA food contact material reviews for new gasket compounds are extending qualification timelines for edible oil transport applications.
- Fiber drum substitution:Lightweight composite alternatives are capturing share in non-hazardous liquid segments where thermal tolerance requirements permit polymer-only closures.
Strategic Opportunities
- Indian chemical manufacturing expansion:BIS standards alignment with ISO drum specifications is opening procurement channels for export-qualified plug suppliers serving Mumbai and Gujarat process industries.
- IoT-enabled seal monitoring:Integration of pressure sensors with vent plug architectures is creating predictive maintenance value for hazardous waste transporters.
- EU Green Deal packaging circularity:Reusable closure mandates under revised waste framework directives are favoring modular plug designs compatible with automated drum reconditioning lines.
Industry Challenges
- Polymer tooling technician scarcity:Precision mold maintenance expertise is concentrated at a handful of Midwest and Rhine-Ruhr manufacturing clusters, constraining capacity expansion timelines.
- Multi-jurisdiction certification complexity:Simultaneous EPA, OSHA, and FDA compliance for dual-use chemical-food drum plugs is fragmenting product portfolios and inflating SKU management costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drum Plugs Market |
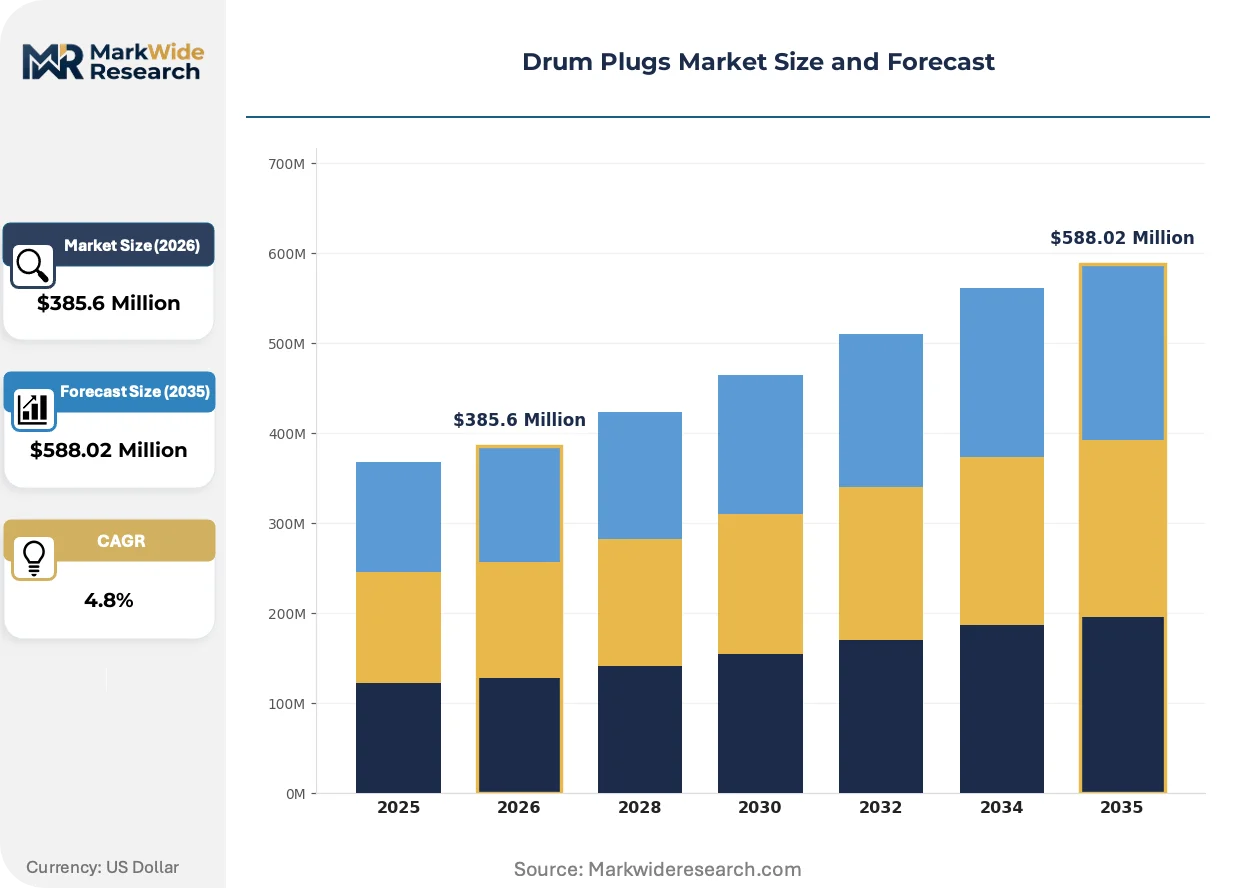
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $588.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Plugs, Leak-Proof Plugs, Vent Plugs, Cap Plugs Material: Plastic, Rubber, Metal, Composite End User: Manufacturing, Chemical, Food & Beverage, Pharmaceutical Application: Transport, Storage, Mixing, Waste Management |
| Companies Covered | BASCO, Technocraft Industries, Greif, Grainger, Ammu Industries, Packco Industries, Mauser Packaging Solutions, Schutz Container Systems, Time Technoplast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drum Plugs Market Shifts & Advancements
Active material substitution and regulatory harmonization pressures are compressing traditional product lifecycles while opening niches for smart closure technologies that bridge compliance and operational efficiency.
Fluoropolymer gasket compounds with enhanced perfluoroalkoxy alkane content are supplanting standard EPDM in high-temperature solvent applications. Specialty chemical transporters operating between Houston and Antwerp are specifying these materials for drums cycling through steam-cleaning protocols. The shift is compressing addressable market share for commodity gasket suppliers while elevating certification barriers for new entrants.
REACH Annex XVII restrictions on persistent organic pollutants are forcing reformulation of legacy plasticizer chemistries used in drum plug seals. Compounders serving European chemical logistics must now validate alternative elastomer packages through ECHA substance evaluation workflows. Food-grade drum applications face parallel pressure from EFSA migration limit updates, creating dual-track compliance costs for cross-border suppliers.
Bulk chemical buyers are consolidating vendor relationships around integrated drum-and-closure service contracts that bundle leakage liability with equipment provision. This model is displacing spot procurement of plugs as separate consumables among Fortune 500 chemical manufacturers. The pattern is most pronounced in German and US Gulf Coast markets where fleet standardization programs prioritize single-source accountability over component-level cost minimization.
Drum Plugs Market Segmentation
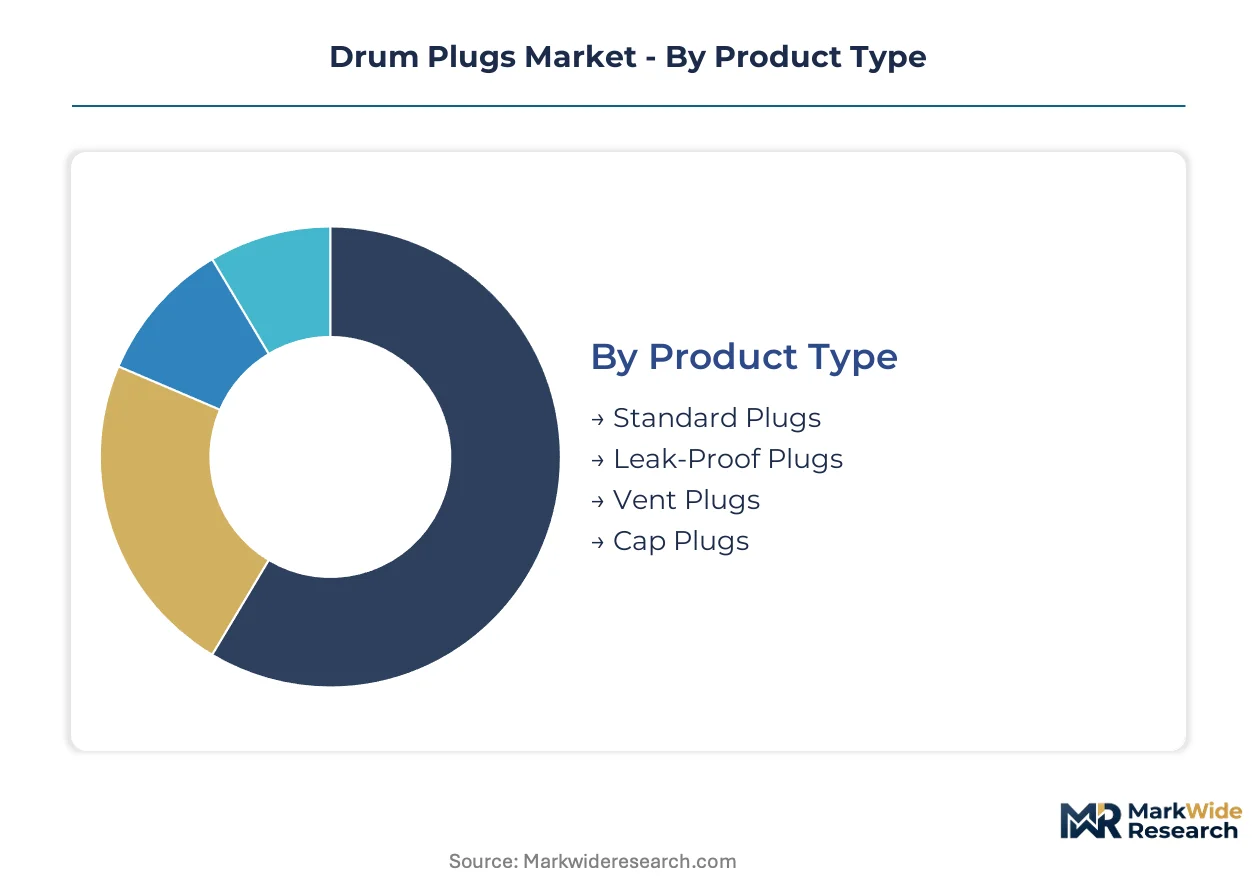
Drum plug procurement patterns diverge sharply between domestic chemical processors and export-oriented logistics operators. Segment-level specification requirements reflect these divergent compliance burdens and operational intensities.
Product Type:
Domestic chemical manufacturers in Germany and the United States favor standardized plug formats with certified gasket materials, while export corridors into India and Brazil drive specialized vent and leak-proof configurations.
- Leak-Proof Plugs:Vapor-tight sealing systems incorporate ethylene propylene diene monomer gaskets rated for caustic and flammable contents. Chemical manufacturers in Texas and Louisiana specify these for EPA hazardous waste manifest compliance during barge and rail transit. REACH Annex XVII restrictions on plasticizer migration are accelerating fluoropolymer gasket adoption for cross-border European chemical logistics.
- Vent Plugs:Pressure-equalization closures prevent drum deformation through temperature-variable supply chains. Rotterdam-Houston chemical corridors install these for multi-modal transits spanning subtropical to temperate zones. Fleet operators standardize on captive vent plug supply to reduce per-use costs across reusable drum rotations.
- Standard Plugs:Basic threaded closures serve non-hazardous liquid applications where thermal cycling remains moderate.
- Cap Plugs:Press-fit temporary seals protect drum threads during cleaning and reconditioning cycles.
Leak-proof plugs command the established base. The steepest expansion runs through vent plugs.
Material:
Cost tier stratification separates commodity polymer selections from certified metal and composite alternatives demanded by solvent-heavy process environments.
- Plastic:Polypropylene and polyethylene formulations dominate food-grade and cost-sensitive chemical applications. FDA food contact material reviews for new gasket compounds extend qualification timelines for edible oil transport, compressing near-term plastic plug availability.
- Metal:Steel and aluminum plugs persist in solvent-heavy chemical environments where thermal tolerance exceeds polymer limits. Input cost swings for metal components compress margins at mid-tier producers serving Gulf Coast petrochemical clusters.
- Rubber:EPDM and fluoropolymer elastomer compounds deliver chemical resistance under thermal cycling for specialty chemical transporters.
- Composite:Hybrid material structures balance weight reduction with structural integrity for automated drum handling systems.
Plastic holds volume leadership. Composite materials are climbing the fastest on lightweighting mandates.
End User:
Customer type concentration clusters around integrated chemical producers with captive fleet operations, while pharmaceutical and food processors drive certification-intensive procurement.
- Chemical:Bulk chemical buyers consolidate vendor relationships around integrated drum-and-closure service contracts that bundle leakage liability with equipment provision. German and US Gulf Coast markets prioritize single-source accountability over component-level cost minimization.
- Food & Beverage:Edible oil and ingredient transporters require FDA food contact material compliance alongside kosher and halal certification for cross-border logistics. EFSA migration limit updates create dual-track compliance costs for European suppliers.
- Manufacturing:Industrial lubricant and coating producers specify standard plug formats for non-hazardous liquid handling.
- Pharmaceutical:Active pharmaceutical ingredient shippers demand validated seal integrity documentation for temperature-controlled supply chains.
Chemical end users command the established base. Pharmaceutical applications are expanding most quickly on serialization and track-and-trace requirements.
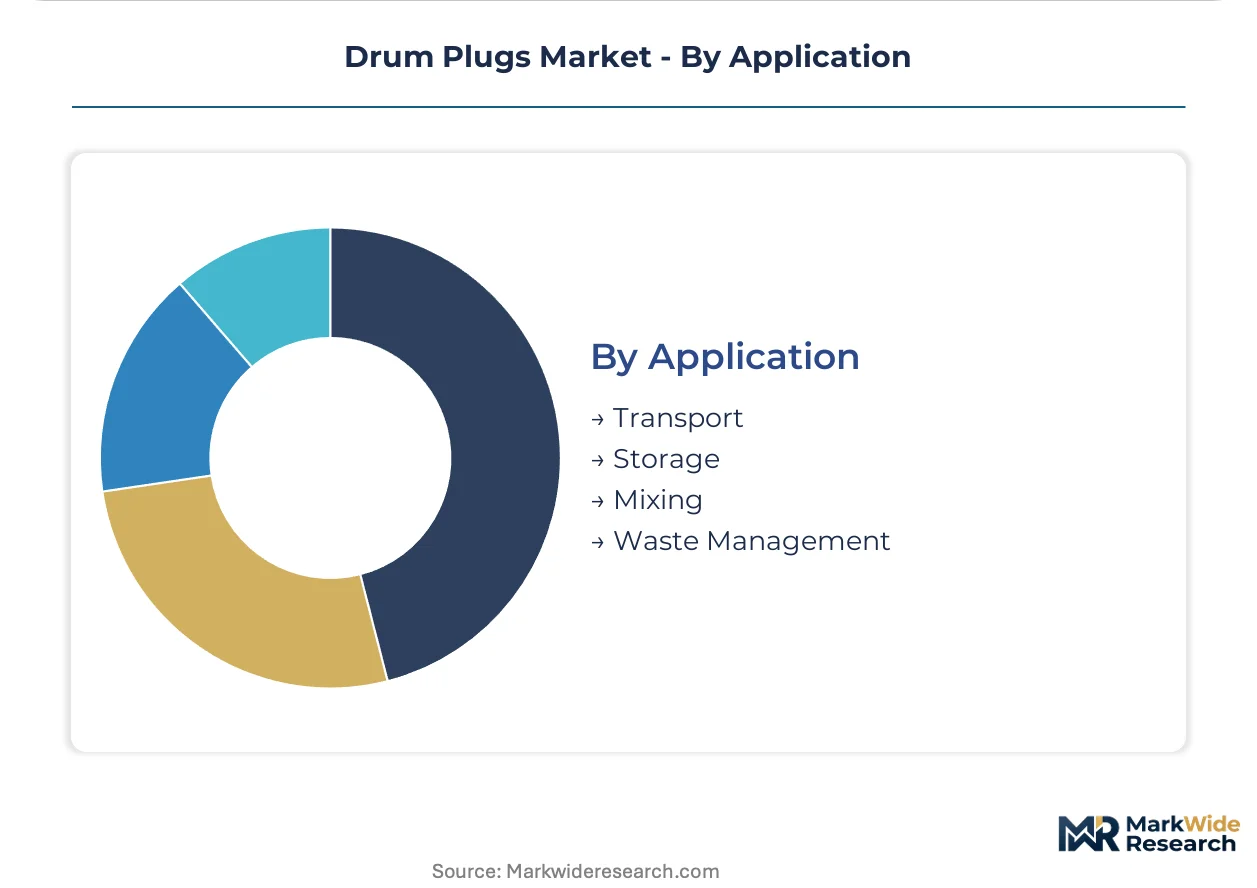
Application:
Volume concentration sits with storage and transport operations, while waste management and mixing applications impose specialized performance specifications.
- Storage:Long-term containment applications specify leak-proof plugs with extended gasket durability for warehouse environments. EPA and OSHA drum handling standards mandate vapor-tight sealing for hazardous material stockpiles.
- Transport:Multi-modal logistics drive vent plug adoption for pressure-equalization across altitude and temperature variations. Temperature-variable supply chains spanning the US Gulf Coast and Rotterdam chemical corridors expand vent plug installations.
- Waste Management:Hazardous waste transporters specify IoT-enabled seal monitoring for predictive maintenance value. EPA hazardous waste manifest rules tighten procurement specifications toward certified gasket materials.
- Mixing:In-drum blending operations require vented closures that permit controlled vapor release during agitation.
Storage commands the established base. Waste management is gaining share fastest on regulatory enforcement intensification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA hazardous waste manifest rules and OSHA drum handling standards in the United States anchor the dominant geography, with chemical logistics operators in Texas and Louisiana driving vapor-tight sealing procurement.
United States
Gulf Coast petrochemical clusters and Midwest drum manufacturing hubs generate concentrated demand for leak-proof and vent plug configurations. EPA hazardous waste manifest compliance mandates vapor-tight sealing for barge and rail transit of caustic contents. Houston and Baton Rouge chemical corridors install pressure-equalization closures for temperature-variable multi-modal supply chains.
Germany
Rhine-Ruhr industrial packaging manufacturers and Bavarian chemical processors sustain standardized plug procurement with certified gasket materials. REACH Annex XVII restrictions on plasticizer chemistries accelerate fluoropolymer alternatives through ECHA substance evaluation workflows. BASF Ludwigshafen and Leverkusen chemical sites consolidate vendor relationships around integrated drum-and-closure service contracts.
India
Mumbai and Gujarat process industries expand drum plug procurement as BIS standards align with ISO drum specifications. The country's national standards body validates alternative elastomer packages for export-qualified suppliers. Ahmedabad and Vadodara chemical manufacturing zones drive specialized vent and leak-proof configurations for domestic and export corridors.
China
Yangtze River Delta drum fabricators and Pearl River Delta chemical logistics operators balance cost-sensitive polymer selections with certified metal alternatives. GB standards for hazardous material handling shape product specifications across Shanghai and Ningbo port zones. Shenzhen and Guangzhou packaging clusters supply standardized closures for food-grade and chemical transport applications.
Netherlands
Rotterdam chemical corridors and Amsterdam logistics hubs anchor European demand for pressure-equalization closures in temperature-variable transits. EU Green Deal packaging circularity mandates under revised waste framework directives favor modular plug designs compatible with automated drum reconditioning lines. Europoort and Moerdijk industrial zones standardize on captive plug supply models for reusable packaging systems.
Drum Plugs Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the drum plug market. Integrated industrial packaging conglomerates with captive steel drum production lock in fleet customers through bundled equipment provision, while specialized polymer fabricators compete on gasket compound certification speed. Mid-tier metal component producers face margin compression from steel price volatility. Dominant competitive moves include backward integration into drum manufacturing and geographic expansion through export-qualified production footprints.
Within the integrated packaging tier, Greif and Mauser Packaging Solutions exemplify archetypes that combine drum production with captive closure supply. BASCO occupies a position among Midwest-based fabricators serving standardized delivery schedules for bulk chemical clients. These three entities represent contrasting strategic positions: Greif anchors vertical control from steel production through closure provision, Mauser Packaging Solutions sits within European reusable systems, and BASCO exemplifies regional manufacturing footprint leverage.
| Leading Market Players |
|---|
| BASCO |
| Technocraft Industries |
| Greif |
| Grainger |
| Ammu Industries |
| Packco Industries |
| Mauser Packaging Solutions |
| Schutz Container Systems |
| Time Technoplast |
| Others |
Supply & Pricing Matrix
Midwest polymer tooling capacity utilization above eighty percent is compressing price floors for standard plug formats while elevating premiums for certified gasket compounds. German and US Gulf Coast chemical buyers absorb higher unit costs through integrated drum-and-closure service contracts that bundle leakage liability.
Pricing Analysis
Price spreads between German REACH-compliant plugs and US Gulf Coast standard formats reflect certification cost differentials of fifteen to twenty percent. Three-tier pricing structure across premium fluoropolymer gaskets, standard EPDM seals, and economy polypropylene closures dominates procurement. Cost compression in metal plug tiers is intensifying because steel price volatility compresses margins at mid-tier producers serving solvent-heavy chemical environments. Food and beverage processors show highest price sensitivity due to FDA qualification timelines, while pharmaceutical buyers accept premium tiers for validated seal documentation.
Supply Chain Analysis
Inventory lead times for fluoropolymer gasket compounds extend qualification cycles by four to six months through ECHA substance evaluation workflows. Manufacturing concentrates in Germany, the United States, and China, with Rhine-Ruhr and Midwest clusters anchoring precision mold maintenance expertise. Raw material sourcing draws from Saudi petrochemical feedstocks for polypropylene, Swedish steel for metal plug bodies, and Japanese fluoropolymer resin for high-temperature gaskets. Single-source vulnerability sits with Midwest polymer tooling technician scarcity constraining capacity expansion. Distribution runs through integrated packaging conglomerates with captive drum production serving fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drum plugs market sits in early-cycle recovery as chemical manufacturing capital expenditure rebounds from regulatory-driven consolidation. EPA enforcement intensification and REACH Annex XVII expansion create replacement demand for certified closure systems.
For Market Incumbents: Consolidate vendor relationships around integrated drum-and-closure service contracts that lock in fleet operators through bundled leakage liability. Deepen captive supply of fluoropolymer gasket compounds to offset steel price volatility compressing metal plug margins. BASCO and Greif demonstrate how Midwest manufacturing footprints and vertical control through steel drum production defend position against polymer-focused entrants.
For New Entrants and Emerging Players: IoT-enabled seal monitoring for hazardous waste transporters represents an under-served service layer where incumbents lack predictive maintenance capabilities. Target Indian chemical manufacturing expansion as BIS standards alignment with ISO specifications opens procurement channels for export-qualified suppliers. Lead with pressure-sensor integration and automated reconditioning compatibility to differentiate from commodity plug producers.
For Investors and Strategic Acquirers: Specialized polymer fabricators with EPDM and fluoropolymer certification speed command scarcity premiums as REACH compliance mandates accelerate material substitution. Long-term viability hinges on circular packaging economics under EU Green Deal directives favoring modular designs. Watch ECHA substance evaluation workflow backlogs as inflection indicator for compounder valuation compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gasket Compounding | Captive EPDM and fluoropolymer supply locks in REACH compliance speed for European chemical logistics. |
| IoT Sensor Integration for Vent Plugs | Pressure monitoring creates predictive maintenance value for EPA-regulated hazardous waste transporters. |
| Modular Plug Design Standardization | Automated drum reconditioning compatibility aligns with EU Green Deal packaging circularity mandates. |
| Indian Export-Qualified Production Footprint | BIS standards alignment opens procurement channels for Mumbai and Gujarat process industries. |
| Long-Term Fleet Service Contracts | Bundled leakage liability displaces spot procurement among Fortune 500 chemical manufacturers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA enforcement databases, ECHA substance evaluation records, and SEC filings from integrated packaging conglomerates. Primary interviews engaged procurement directors at Gulf Coast petrochemical clusters, plant managers at Rhine-Ruhr drum fabricators, and regulatory affairs leads at gasket compounders. Secondary validation drew from customs trade data, OSHA drum handling standard updates, and FDA food contact material review timelines. Bottom-up demand modeling triangulated against top-down chemical logistics expenditure patterns.
Segmentation dimensions modeled include product type, material grade, end-use industry, and application across the projection horizon. CAGRs derive from regression analysis of historical procurement volumes against regulatory enforcement intensity indices. Forecast inputs incorporate steel price volatility coefficients, polymer certification backlog durations, and reusable packaging system adoption curves.
Material uncertainties — steel price swings, ECHA substance evaluation delays, polymer tooling technician availability — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization trajectories and circular packaging mandate implementation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Disc Top Caps Market
Caps and Closures
Latin America Plastic Caps and Closure Market
Caps and Closures
Metal Closures Market
Caps and Closures
Spain Plastic Cap and Closure Market
Caps and Closures
Caps and Closures Market
Caps and Closures
Spigot End Cap Market
Caps and Closures
Mexico Plastic Caps and Closures Market
Caps and Closures
Morocco Plastic Caps and Closures Market
Caps and Closures
Magnetic Closure Box Market
Caps and Closures
Global Aluminum Caps for Packaging Market
Caps and Closures
Twist-Off Metal Caps Market
Caps and Closures
Side Pour Caps Market
Caps and Closures
Linerless Closures Market
Caps and Closures
Continuous Thread Metal Cap Market
Caps and Closures
Humidity Indicator Plugs Market
Caps and Closures
Spout Closures Market