
 Australia and New Zealand Plastic Caps and Closures Market | 2026-2036
Australia and New Zealand Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Australia and New Zealand Plastic Caps and Closures Market Insights
Australian blow-molding capacity is shifting toward tethered-cap configurations ahead of regulatory deadlines. Pact Group Holdings Ltd leverages its integrated recycling infrastructure across Melbourne and Sydney to secure virgin-quality rPET feedstock for closure production. Amcor Plc anchors Australasian supply through its specialized pharmaceutical closure lines, while Berry Global Inc competes aggressively in the dairy and condiments segment with high-speed tamper-evident designs.
Australia and New Zealand plastic caps and closures are threaded or snap-fit sealing devices manufactured from thermoplastic resins, typically injection-molded or compression-molded to tolerances of 0.1–0.3 millimeters, designed to preserve product integrity, enable controlled dispensing, and satisfy child-resistance or tamper-evidence requirements across liquid and semi-solid packaged goods. Screw Caps dominate volume in the Food & Beverage application due to their resealability and compatibility with automated capping lines, though Dispensing Caps command premium positioning in Personal Care where controlled-flow functionality justifies higher unit economics. Polypropylene leads material selection for hot-fill and carbonated applications because of its thermal stability and chemical resistance, while HDPE competes in cost-sensitive household product segments where flexibility and impact strength outweigh clarity requirements.
TGA and Medsafe govern pharmaceutical closure standards across Australia and New Zealand respectively, mandating child-resistant packaging for specified analgesics and psychotropic medicines that directly shapes R&D priorities for local manufacturers. Food Standards Australia New Zealand (FSANZ) and the Australian Packaging Covenant Organisation (APCO) enforce migration limits and recyclability targets that redirect material procurement toward approved resin grades and tethered-cap geometries. Stakeholders must monitor the divergence between Australian state-level container deposit schemes and New Zealand's proposed regulated product stewardship framework, as compliance fragmentation will determine which closure formats achieve scale across the trans-Tasman supply base.
Market Dynamics
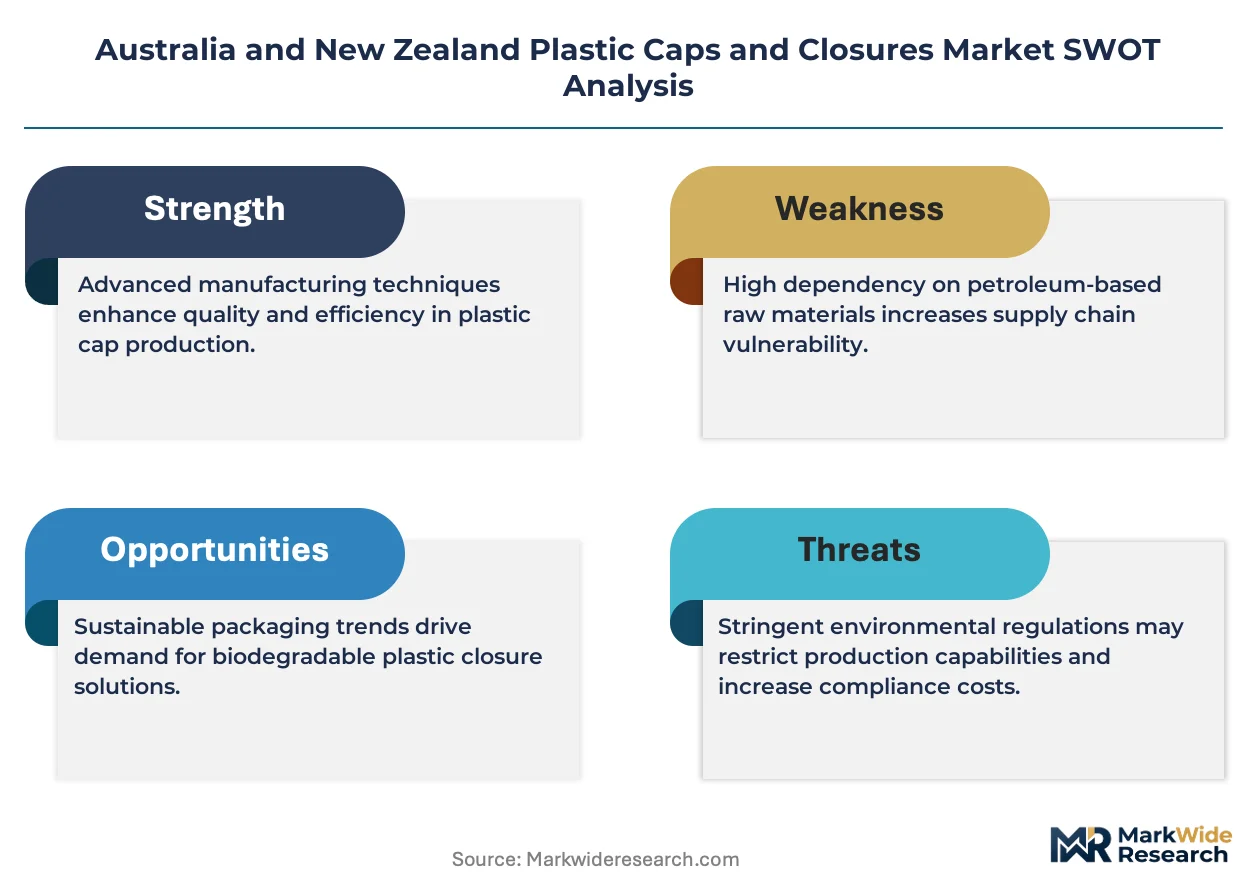
Australia's National Plastics Plan and New Zealand's Plastic Packaging Declaration are forcing closure manufacturers to reconfigure material specifications and tethered-cap geometries ahead of staggered compliance deadlines.
Growth Catalysts
- Tethered-cap mandates:Australia's National Plastics Plan requires attached caps on beverage containers by 2025, redirecting blow-molding investment toward integrated closure-bottle systems.
- Container deposit scheme expansion:Victoria's CDS launch and South Australia's scheme maturation create closed-loop feedstock channels that stabilize rPET supply for Melbourne and Sydney manufacturers.
- Pharmaceutical packaging demand:TGA child-resistance requirements for analgesics and psychotropics sustain specialized closure R&D spending across Australia's southeastern manufacturing corridor.
Market Restraints
- Virgin resin price volatility:Polypropylene feedstock costs fluctuate with Asia-Pacific naphtha markets, compressing margin predictability for high-volume beverage closure producers.
- Recycling infrastructure gaps:New Zealand's limited mechanical reprocessing capacity forces Auckland manufacturers to import rPET flake, inflating landed costs versus Australian competitors.
- Technical substitution limits:HDPE lacks the thermal stability for hot-fill applications, blocking material switching in sauces and ready-to-drink coffee segments.
Strategic Opportunities
- Queensland manufacturing corridor:Underdeveloped closure production relative to beverage bottling concentration creates captive supply potential for Brisbane-Sunshine Coast logistics nodes.
- Dispensing cap premiumization:Personal care brands in Auckland and Sydney seek controlled-flow designs for serums and hair treatments, justifying 40-60% unit price premiums over standard screw caps.
- Regulated product stewardship:New Zealand's proposed framework mandates producer-funded collection, incentivizing lightweighting and mono-material designs that simplify mechanical recycling.
Industry Challenges
- Tooling retooling cycles:Tethered-cap molds require 20-30% longer changeover times than conventional designs, constraining throughput during Australia's seasonal beverage production peaks.
- FSANZ migration testing backlog:Novel resin grades and recycled content blends face extended approval timelines, delaying product launches for condiment and dairy applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia and New Zealand Plastic Caps and Closures Market |
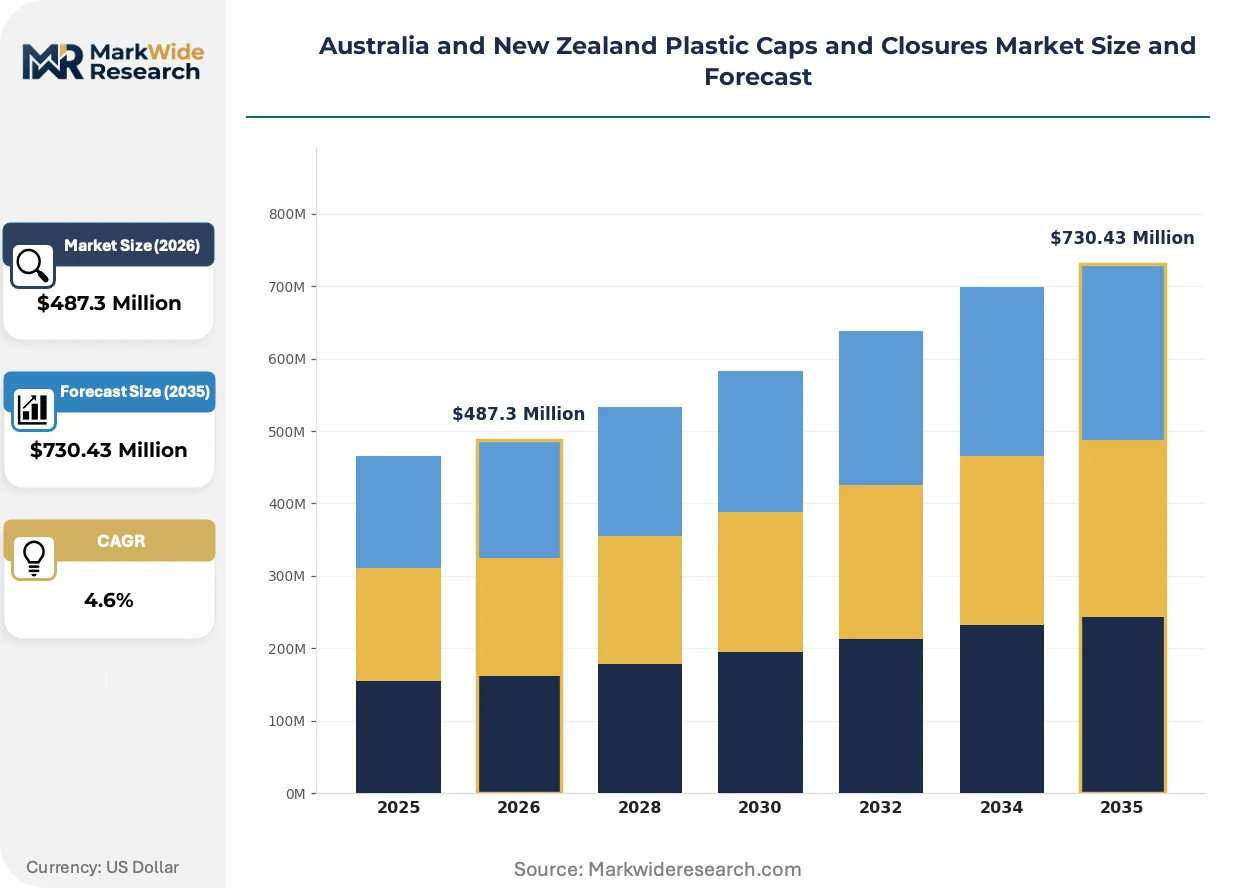
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Snap-On Caps, Sports Caps, Dispensing Caps Material: Polyethylene, Polypropylene, PVC, HDPE Application: Food & Beverage, Personal Care, Pharmaceuticals, Household Products End User: Manufacturers, Retailers, Wholesalers, Distributors |
| Companies Covered | Caprite Australia Pty Ltd, Caps and Closures Pty Ltd, Pact Group Holdings Ltd, Bericap Holding GmbH, Guala Closures SpA, Amcor Plc, Reynolds Group Holdings Limited, Berry Global Inc, Silgan Holdings Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia and New Zealand Plastic Caps and Closures Market Trends and Innovations
Closure engineering across Australia and New Zealand is pivoting from commodity volume toward compliance-integrated functionality, with material traceability and dispensing precision replacing cost-per-thousand as the primary design metric.
Tethered-cap technology is expanding into Australia's beverage supply chain as blow-molding lines retrofit for attached closure geometries. Coca-Cola Europacific Partners and Asahi Beverages are converting Queensland and Victorian facilities ahead of 2025 deadlines. This retrofit wave is expanding into adjacent categories, with condiment and cooking oil brands now specifying tethered designs to preempt future regulatory extension.
FSANZ and APCO are tightening migration limits and recyclability targets that redirect material procurement toward approved resin grades and tethered-cap geometries. Industrial consequence includes mandatory recycled content disclosures on packaging and audit requirements for supply chain traceability. Dairy and pharmaceutical segments are responding fastest, with Melbourne manufacturers pre-qualifying rPET suppliers to secure batch consistency for TGA-submitted products.
Brand procurement teams are consolidating supplier panels from 8-12 vendors to 3-4 strategic partners capable of integrated design, regulatory documentation, and closed-loop recycling. This concentration displaces spot-market purchasing for standard screw caps. The shift is most visible in Australia's southeastern manufacturing corridor, where Pact Group and Amcor capture multi-year supply agreements with beverage and pharmaceutical majors.
Australia and New Zealand Plastic Caps and Closures Market Segmentation
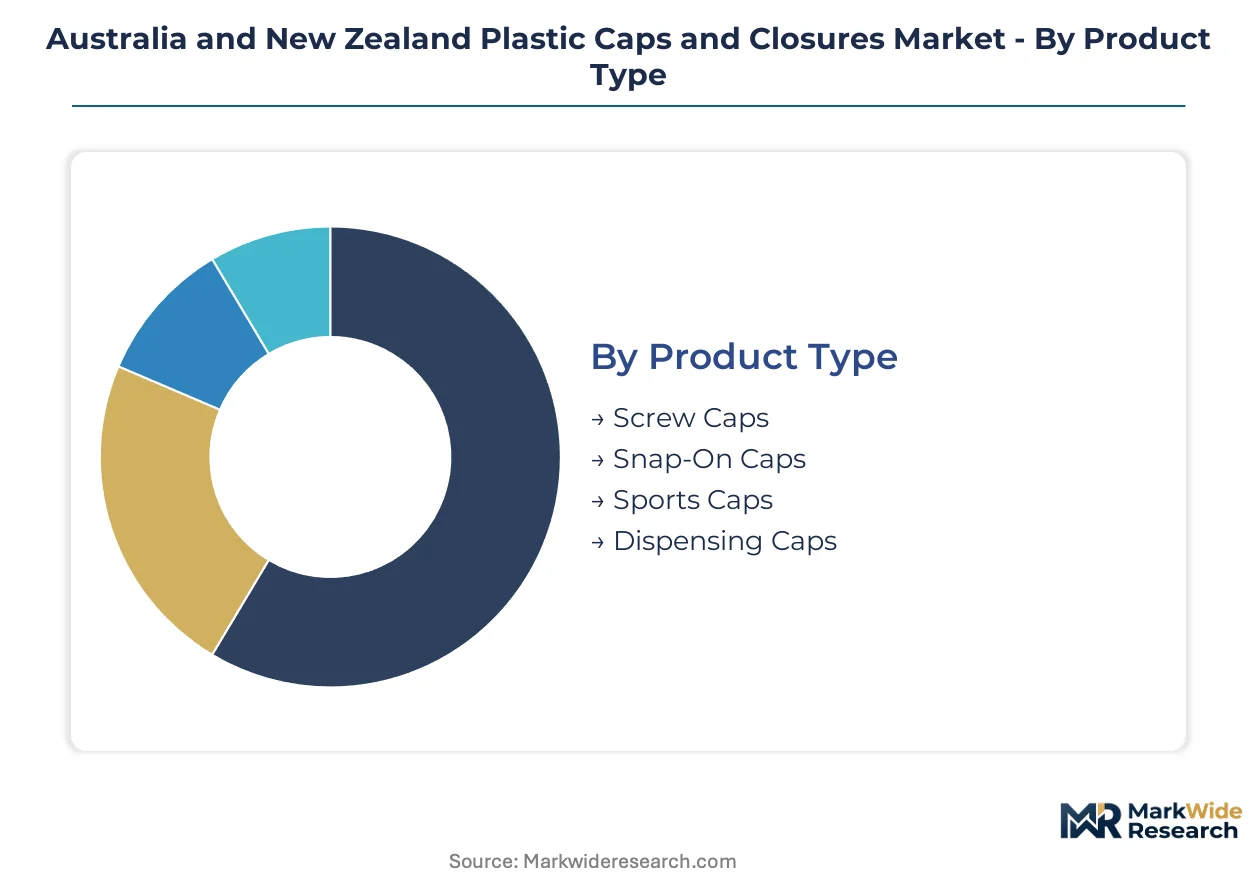
Closure selection across Australia and New Zealand hinges on regulatory certification pathways, with TGA, Medsafe, and FSANZ requirements diverging sharply by end-use. Manufacturers must map segment-specific compliance burdens to resin grades and geometries to avoid approval delays.
Product Type:
TGA child-resistance mandates govern pharmaceutical closures, while FSANZ migration limits apply to food-contact designs, creating divergent certification tracks across screw, snap-on, and dispensing formats.
- Screw Caps:Threaded thermoplastic designs with 0.1–0.3 millimeter tolerances enable automated capping and resealability. Australia's southeastern beverage corridor concentrates demand, with tethered-cap retrofits ahead of National Plastics Plan deadlines compressing conventional screw cap volumes.
- Dispensing Caps:Controlled-flow mechanisms with pump, flip-top, or disc-top actuators command premium positioning. Auckland and Sydney personal care brands drive specification, where serum and hair treatment functionality justifies 40–60% unit price premiums over standard closures.
- Snap-On Caps:Compression-molded designs for single-use dairy and condiment applications. Melbourne manufacturers favor these for high-speed filling lines where thread engagement slows throughput.
- Sports Caps:Push-pull or twist-open mechanisms for active hydration formats. Queensland's beverage bottling concentration sustains regional demand despite tethered-cap transition uncertainty.
Screw Caps sit at the top of the volume ranking, with Dispensing Caps climbing the fastest.
Material:
Hot-fill and carbonated applications concentrate procurement toward thermally stable resins, while cost-sensitive household segments tolerate lower-performance alternatives.
- Polypropylene:Semi-crystalline thermoplastic with 160°C melting point and chemical resistance to acids, bases, and solvents. Australia's ready-to-drink coffee and sauce segments anchor demand, with rPET blending constrained by FSANZ migration testing backlogs.
- HDPE:High-density polyethylene delivers flexibility and impact strength at lower unit cost. New Zealand's limited mechanical reprocessing capacity inflates landed rHDPE costs versus Australian competitors, compressing margin for Auckland household product manufacturers.
- Polyethylene:Linear low-density grades compete in squeeze-tube and flexible pouch applications where closure flexibility matches substrate deformation. Sydney personal care contract packers specify these for travel-size formats.
- PVC:Chlorinated resin with barrier properties for aggressive chemical contents. Declining acceptance across Australian packaging covenants restricts new specification, with existing pharmaceutical applications grandfathered under TGA legacy approvals.
Polypropylene dominates current procurement volumes, with HDPE gaining share fastest in cost-optimized household segments.
Application:
End-use concentration determines margin structure, with pharmaceutical and personal care sustaining premium pricing while food and beverage operates at scale-driven economics.
- Food & Beverage:Screw caps and tethered designs for carbonated soft drinks, juices, and condiments. Victoria's container deposit scheme maturation stabilizes rPET feedstock for Melbourne-Sydney manufacturers.
- Pharmaceuticals:Child-resistant and tamper-evident closures for analgesics, psychotropics, and prescription medicines. TGA requirements sustain specialized R&D spending across Australia's southeastern manufacturing corridor.
- Personal Care:Dispensing caps and premium screw formats for skincare, haircare, and cosmetics. Auckland brand procurement teams consolidate supplier panels to 3–4 strategic partners capable of integrated design and regulatory documentation.
- Household Products:Snap-on and trigger-spray closures for cleaning chemicals and laundry formulations. HDPE cost advantages dominate, though Queensland underpenetration relative to beverage bottling concentration creates captive supply potential.
Food & Beverage commands absolute volume leadership, with Pharmaceuticals expanding most quickly on regulatory specialization premiums.
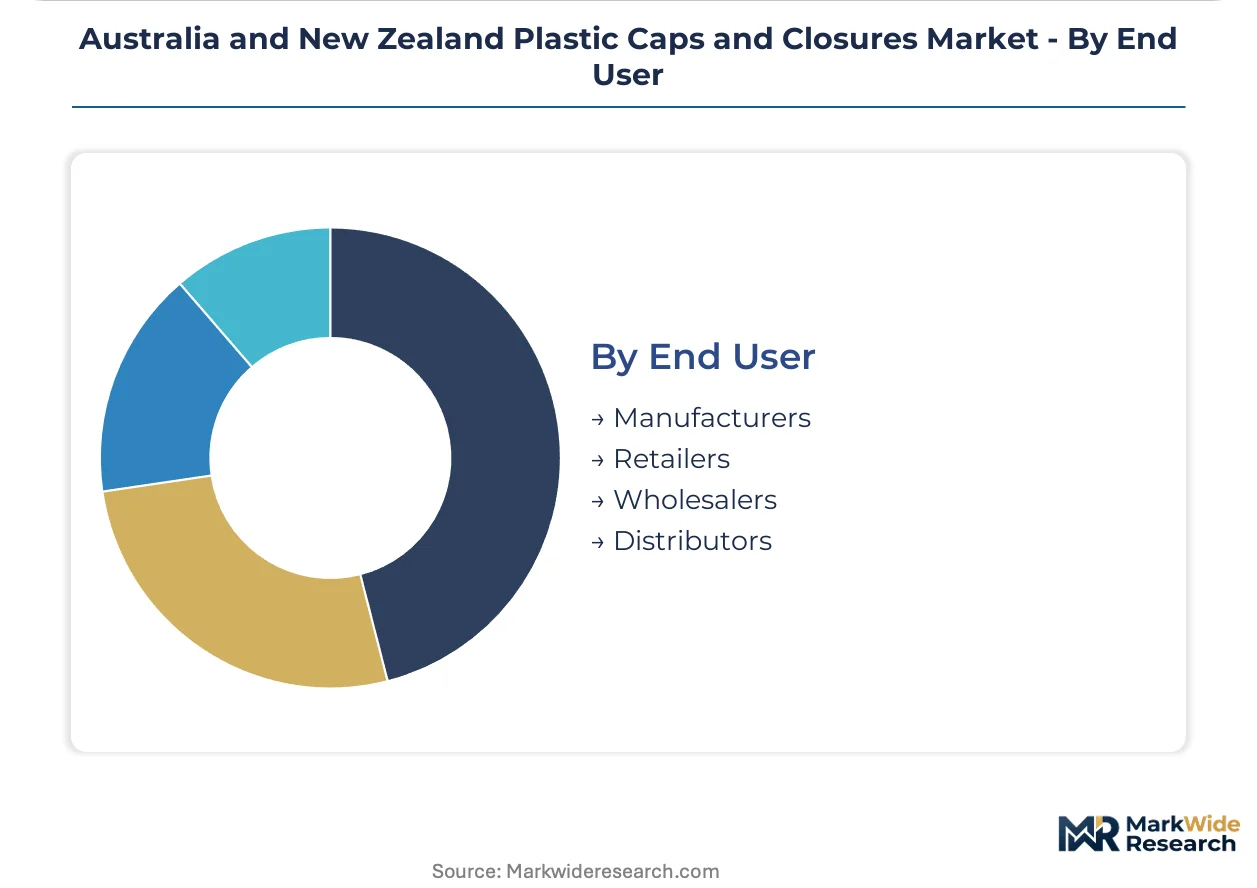
End User:
Channel position determines technical service requirements, with direct manufacturer relationships demanding design integration versus distributor spot purchasing for standardized formats.
- Manufacturers:Beverage, dairy, and pharmaceutical producers with captive filling lines and quality systems. Pact Group and Amcor capture multi-year supply agreements through integrated recycling and regulatory documentation capabilities.
- Retailers:Private label and contract-manufactured goods for supermarket and pharmacy chains. Coles and Woolworths sustainability mandates drive recycled content specifications.
- Wholesalers:Intermediate stocking for regional and independent brand distribution. Spot-market purchasing for standard screw caps faces displacement from strategic supplier consolidation.
- Distributors:Export-focused intermediaries serving Pacific Island and Southeast Asian markets. Trans-Tasman regulatory divergence complicates cross-border closure format standardization.
Manufacturers anchor procurement volume, with Retailers accelerating specification fastest through sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions with mature container deposit schemes and established mechanical reprocessing infrastructure, creating compliance-cost arbitrage between Australian states and across the Tasman.
New South Wales
Sydney's contract packaging cluster drives dispensing cap demand for personal care brands, with premium serum and hair treatment formats commanding substantial unit price premiums. The state's container deposit scheme stabilizes rPET feedstock channels for closure manufacturers. Parramatta's logistics nodes concentrate import-export activity for Pacific Island distribution.
Victoria
Melbourne anchors the southeastern manufacturing corridor with integrated blow-molding and closure production serving beverage and dairy majors. The state's scheme maturation creates closed-loop rPET supply that undercuts Auckland's import-dependent costs. Dandenong's industrial precinct hosts specialized pharmaceutical closure lines meeting TGA child-resistance mandates.
Queensland
Brisbane-Sunshine Coast beverage bottling concentration outpaces local closure production capacity, generating captive supply opportunities for new manufacturing investment. Coca-Cola Europacific Partners and Asahi Beverages operate retrofitting tethered-cap lines ahead of federal deadlines. The underdeveloped supplier base relative to demand concentration attracts strategic facility placement.
South Australia
Adelaide's mature container deposit infrastructure, operational since 1977, delivers the most stable post-consumer feedstock stream nationally. Local reprocessors supply Melbourne and Sydney manufacturers when Victorian capacity tightens during seasonal peaks. The state's regulatory predictability reduces compliance planning uncertainty for multi-site producers.
New Zealand
Auckland's industrial precinct concentrates national demand, though limited mechanical reprocessing capacity forces rPET flake imports at inflated landed costs. Medsafe pharmaceutical standards diverge from TGA requirements, complicating trans-Tasman product standardization. The proposed regulated product stewardship framework will mandate producer-funded collection, reshaping lightweighting incentives.
Australia and New Zealand Plastic Caps and Closures Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue tethered-cap specialization and rPET integration ahead of regulatory deadlines. The market structures around three distinct tiers: integrated packaging conglomerates with captive recycling infrastructure, mid-scale specialists serving pharmaceutical and dairy niches, and regional fabricators competing on logistics proximity. Consolidation pressure intensifies as brand procurement teams reduce supplier panels from 8-12 vendors to 3-4 strategic partners. Capacity expansion and backward integration into reprocessing represent the dominant competitive vectors.
Among Australasian-anchored conglomerates, Pact Group Holdings Ltd exemplifies the integrated archetype through its control of recycling infrastructure across Melbourne and Sydney. Amcor Plc occupies the multinational position with specialized pharmaceutical closure capabilities. Berry Global Inc represents the aggressive mid-tier competitor targeting dairy and condiment segments with high-speed tamper-evident designs. These three anchors illustrate the strategic divergence between recycling-integrated, pharma-specialized, and speed-optimized positioning.
| Leading Market Players |
|---|
| Caprite Australia Pty Ltd |
| Caps and Closures Pty Ltd |
| Pact Group Holdings Ltd |
| Bericap Holding GmbH |
| Guala Closures SpA |
| Amcor Plc |
| Reynolds Group Holdings Limited |
| Berry Global Inc |
| Silgan Holdings Inc |
| Others |
Pricing and Supply Chain Analysis
Tethered-cap certification tiers bifurcate procurement economics across Australia's beverage corridor and New Zealand's import-dependent base, compressing margins for non-compliant suppliers while rewarding integrated recyclers with volume premiums and long-term offtake security.
Pricing Analysis
Direct-to-OEM contract structures dominate high-volume beverage supply, with Melbourne and Sydney manufacturers capturing 15-20 point margin advantages over spot-market distributors through multi-year recycling-integrated agreements. Price differentiation rests on TGA/Medsafe certification grade and rPET batch traceability rather than virgin resin cost alone. Cost compression in commodity screw caps intensifies as Queensland bottlers consolidate supplier panels, while dispensing caps for Auckland personal care brands sustain premium positioning through controlled-flow functionality. Retailer private-label procurement exhibits highest price sensitivity, whereas pharmaceutical majors prioritize batch consistency over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from Coles and Woolworths compel Melbourne manufacturers to qualify alternate rPET suppliers beyond Pact Group's captive infrastructure, stretching qualification timelines. Raw material dependencies center on Asia-Pacific naphtha derivatives for virgin polypropylene and post-consumer flake imports for New Zealand's mechanical reprocessing gap. Single-source vulnerability concentrates in South Australia's mature container deposit infrastructure, where seasonal peak demand forces interstate feedstock diversion. Distribution runs through Dandenong and Parramatta logistics nodes serving trans-Tasman and Pacific Island channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where specification compliance displaces cost-per-thousand as the procurement priority, with tethered-cap mandates and FSANZ migration standards filtering supplier viability toward integrated recyclers and certified pharmaceutical specialists.
For Market Incumbents: To counter supplier panel consolidation by Coles, Woolworths, and Auckland personal care majors, deepen backward integration into mechanical reprocessing infrastructure and secure TGA pre-qualification for rPET batch consistency. Capacity addition in Queensland's underdeveloped closure manufacturing corridor captures captive supply opportunities from Coca-Cola Europacific Partners and Asahi Beverages retrofit programs. For New Entrants and Emerging Players: Launch via toll-manufacturing partnerships with Melbourne pharmaceutical contract packers seeking secondary rPET qualification sources beyond incumbent duopolies. Queensland's Brisbane-Sunshine Coast beverage concentration presents the most penetrable geography, with tethered-cap tooling investment unlocking multi-year supply agreements ahead of federal compliance deadlines. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory documentation capabilities and closed-loop recycling infrastructure concentrate procurement decisions among three to four strategic partners. Five-to-ten year viability favors acquisition targets with Medsafe-TGA dual certification and established container deposit scheme feedstock relationships. The signal to watch is Victoria's scheme maturation triggering interstate rPET arbitrage compression.| Strategic Initiative | Industry Significance |
|---|---|
| Tethered-Cap Manufacturing Retrofit | Queensland bottlers converting lines ahead of National Plastics Plan deadlines secure regulatory-compliant supply positioning. |
| rPET Batch Traceability Investment | Melbourne pharmaceutical manufacturers pre-qualifying suppliers accelerate TGA submission timelines versus competitors. |
| Queensland Manufacturing Corridor Entry | Brisbane-Sunshine Coast captive supply potential addresses underdeveloped closure capacity relative to beverage concentration. |
| Medsafe-TGA Dual Certification | Trans-Tasman standardization capability captures procurement consolidation across Auckland and Sydney brand headquarters. |
| Lightweighting R&D Program | New Zealand's proposed product stewardship framework rewards mono-material designs simplifying mechanical recycling economics. |
Research Methodology
Direct dialogue with blow-molding plant managers, pharmaceutical packaging engineers, retail category buyers, and recycling facility operators grounded qualitative findings, cross-referenced with TGA submission databases, FSANZ migration limit determinations, APCO annual reports, and state-level container deposit scheme operator disclosures. Bottom-up volume estimates from individual manufacturing facility throughput triangulated against top-down resin consumption data from Australian Bureau of Statistics import records and Plastics New Zealand industry surveys.
Bottom-up modeling tracked closure unit shipments by product type, material grade, and end-use application across the projection horizon, with top-down validation against macroeconomic indicators and packaging intensity ratios. Segmentation dimensions incorporated tethered versus conventional geometry, virgin versus recycled content tier, TGA/Medsafe certification status, and geographic manufacturing cluster. CAGRs derived from regression analysis of historical resin pricing volatility, regulatory compliance cost trajectories, and brand procurement consolidation patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated regulatory harmonization or prolonged naphtha price instability. Deviation in New Zealand's product stewardship implementation timeline or Victorian container deposit scheme feedstock availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Low Profile Compact System Closures Market
Caps and Closures
Gable Top Cap and Closures Market
Caps and Closures
Dual Flap Dispensing Closure Market
Caps and Closures
Sleeve Rubber Stoppers Market
Caps and Closures
Elastomeric Closures Market
Caps and Closures
Hinged Dispensing Caps Market
Caps and Closures
Sport Caps and Closures Market
Caps and Closures
Heat Shrink Bands Market
Caps and Closures
United Kingdom Plastic Caps and Closures Market
Caps and Closures
Indonesia Plastic Caps and Closures Market
Caps and Closures
Molded Fiber Pulp Cap Market
Caps and Closures
Crimp-On Spouts Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Side Pour Caps Market
Caps and Closures
Cap Seals Market
Caps and Closures
Vietnam Plastic Caps and Closures Market