
 Hinged Dual Flap Caps Market | 2026-2036
Hinged Dual Flap Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Hinged Dual Flap Caps Market Outlook
Capital-intensity divergence between large-format injection molders and precision closure specialists is bifurcating competitive dynamics in the hinged dual flap caps landscape. Amcor plc leverages integrated resin-to-dispenser capabilities across multiple continents. Silgan Dispensing Systems anchors North American pharmaceutical and personal care channels with dedicated manufacturing infrastructure. AptarGroup, Inc. differentiates through high-speed automation platforms serving regulated drug packaging applications.
Hinged dual flap caps are precision-molded closure devices incorporating two independently articulating cover panels joined by an integral living hinge, typically manufactured through multi-cavity injection molding with polypropylene or polyethylene resins and designed to enable controlled product dispensing while maintaining seal integrity between uses. The pharmaceutical end-user segment leads value generation as tamper-evident and child-resistant design features command premium positioning and compliance-driven specification lock-ins. Plastic product types dominate volume throughput while composite materials represent the fastest-growing category as brand owners pursue sustainability-linked material transitions without sacrificing hinge fatigue performance.
FDA 21 CFR Part 170-199 regulations govern indirect food additive compliance for polymeric closure materials, while the EU MDR and REACH frameworks impose substance restriction and clinical traceability requirements on pharmaceutical dispensing closures. ISO 8317 child-resistant packaging standards create technical barriers that favor suppliers with certified testing laboratories and documented protocol expertise. Stakeholders must monitor evolving state-level extended producer responsibility mandates and bio-based content thresholds that will reshape material qualification workflows and supplier qualification criteria.
Market Dynamics
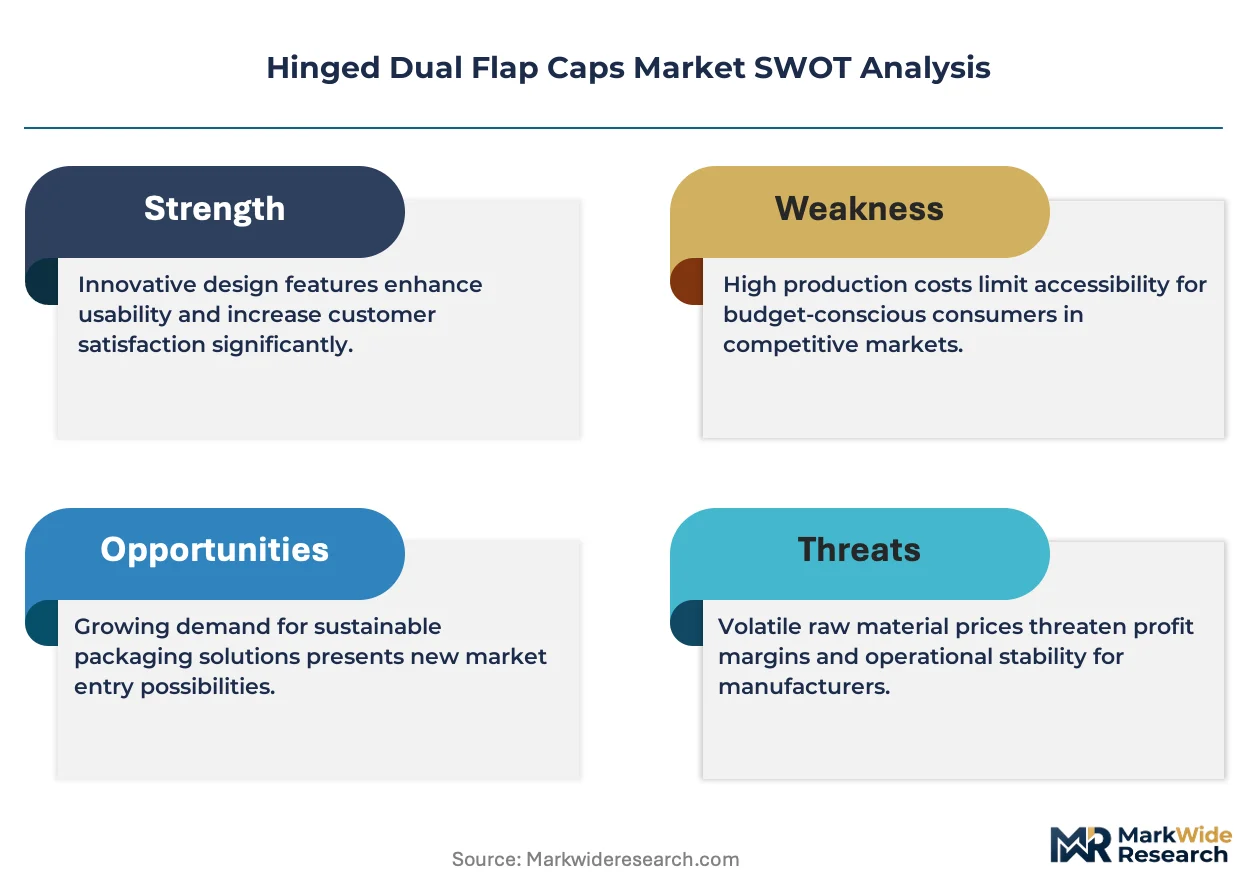
Child-resistant packaging mandates from FDA and EU MDR are compressing specification cycles for pharmaceutical closure suppliers, forcing rapid redesign of living hinge geometries and tamper-evident features to maintain compliance access.
Growth Catalysts
- EU MDR traceability requirements:Pharmaceutical manufacturers must document closure batch records for clinical-grade dispensing systems, locking in qualified suppliers with certified testing protocols.
- Oral solid dose expansion:Tablet and capsule formats require precise moisture barriers that hinged dual flap closures provide through integrated desiccant chambers and multi-point sealing.
- German contract packaging growth:Over-the-counter medicine outsourcing in Baden-Württemberg and Bavaria is expanding dedicated lines that specify child-resistant hinged closures as standard.
Market Restraints
- Polypropylene resin volatility:Feedstock price swings from propylene monomer supply disruptions compress margin predictability for high-volume injection molders serving generic drug packaging.
- Precision closure specialist concentration:Certified ISO 8317 testing capabilities cluster among a handful of European and North American suppliers, creating qualification bottlenecks for new market entrants.
- Living hinge fatigue limits:Standard polyolefin hinges degrade after 500-1000 articulation cycles, restricting reuse applications in institutional dispensing settings.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO's tightening export documentation requirements for oral solid dose formats create demand for pre-qualified child-resistant closure systems among domestic formulators.
- Bio-based polypropylene:Mass balance-certified resins from Neste and SABIC supply chains enable brand owners to meet EU Green Deal content thresholds without sacrificing hinge performance.
- Direct-to-patient pharmacy channels:E-pharmacy fulfillment in Germany and France requires unit-dose packaging with integrated dispensing controls that hinged dual flap designs optimize.
Industry Challenges
- Multi-cavity mold qualification timelines:Validating 32-64 cavity tools for pharmaceutical-grade closures requires 18-24 month FDA submission cycles that delay capacity expansion.
- Living hinge simulation expertise:Finite element analysis of fatigue performance across temperature and humidity ranges demands specialized polymer engineering talent concentrated among aging specialist workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hinged Dual Flap Caps Market |
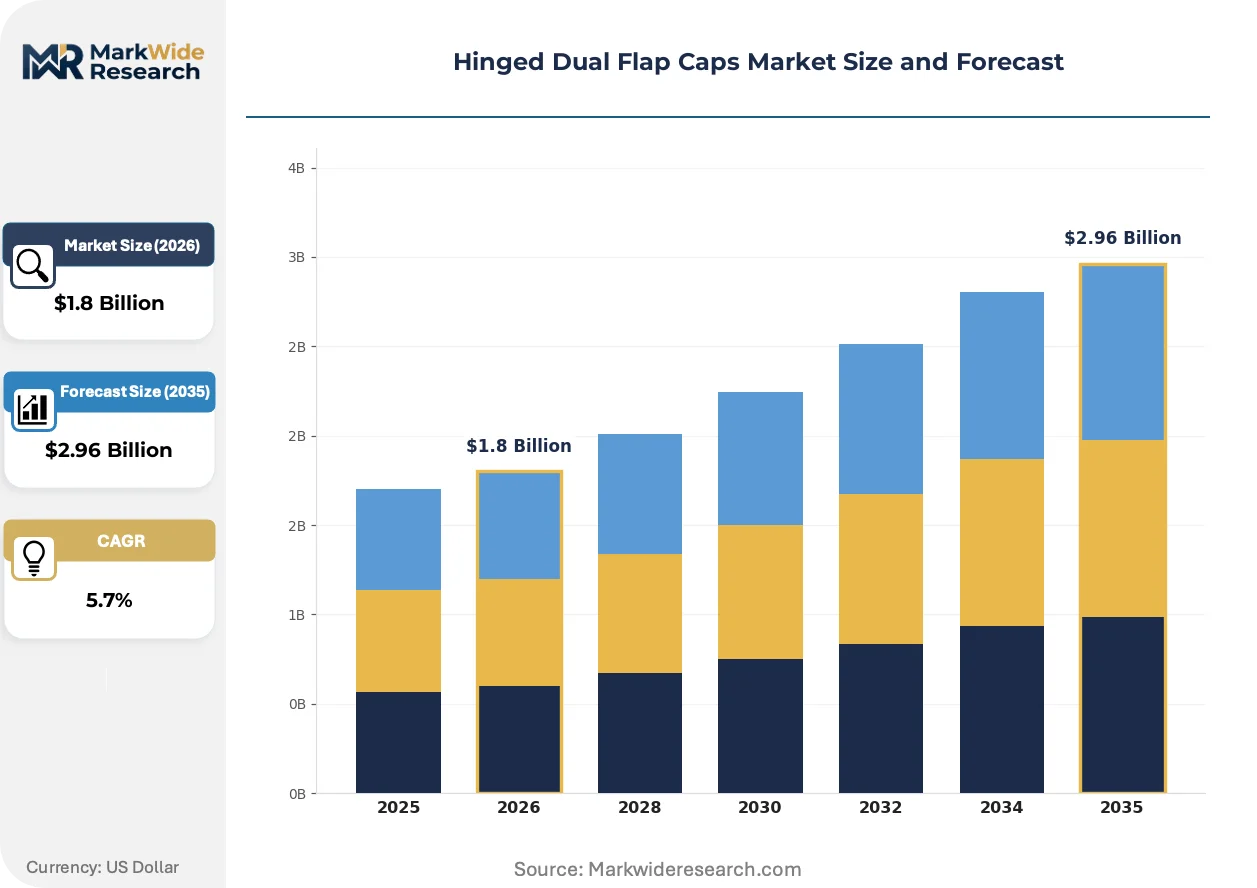
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Glass, Composite Closure Mechanism: Screw Cap, Snap Fit, Push-Pull, Twist Off End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Design Feature: Child Resistant, Tamper Evident, Reusable, Single Use |
| Companies Covered | Amcor plc, Silgan Dispensing Systems, AptarGroup, Inc., United Caps, ALPLA Werke Alwin Lehner GmbH & Co. KG, Berry Global, Inc., Mold-Rite Plastics, Closure Systems International, Silgan Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hinged Dual Flap Caps Market Strategic Shifts
Material science advances and regulatory digitization are reconfiguring how closure suppliers demonstrate compliance and differentiate performance claims in pharmaceutical procurement channels.
Composite hinge materials incorporating glass-fiber reinforced segments alongside flexible polyolefin cores are fragmenting the traditional monolithic polypropylene design paradigm. Medical device manufacturers in Switzerland and Germany are piloting these hybrid structures for insulin pen and inhaler applications where cycle life exceeds 2000 actuations. The technology is fragmenting supplier tiers, separating molders with advanced co-injection capabilities from commodity closure producers.
EU MDR's Unique Device Identification requirements now extend to Class I dispensing closures, compelling suppliers to integrate laser-marked serialization directly into mold designs. Manufacturers serving the European Economic Area must validate mark durability through sterilization cycles and shelf-life aging protocols. German packaging service providers are consolidating supplier bases to partners with in-house marking and verification systems, compressing the qualified vendor pool.
Pharmaceutical procurement teams are unbundling closure supply from primary container contracts, creating discrete sourcing categories for child-resistant dispensing systems. This pattern concentrates volume among buyers with dedicated technical qualification staff in Basel, New Jersey, and Hyderabad. Indian generic drug exporters are adopting this model fastest, separating closure procurement from bottle and blister line decisions to optimize landed cost structures.
Hinged Dual Flap Caps Market Segmentation
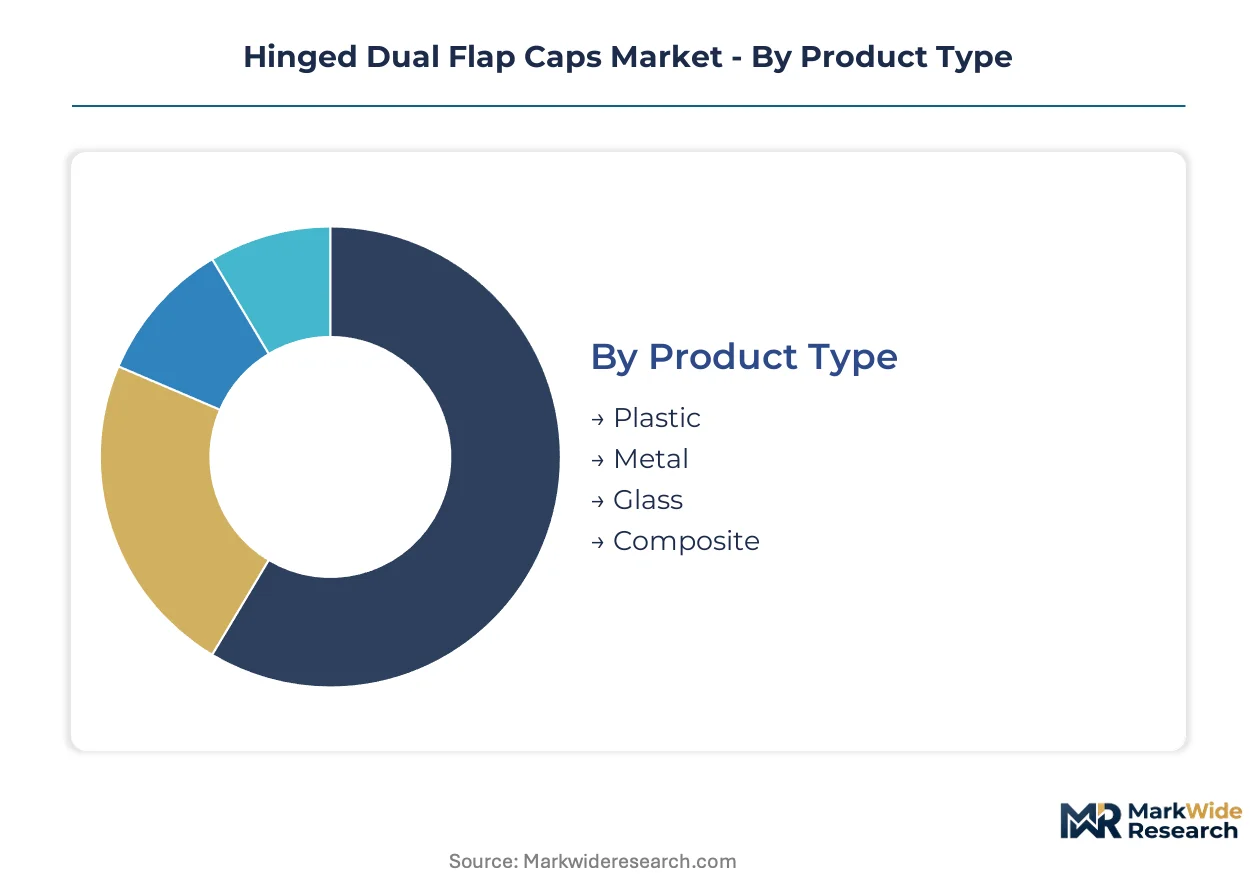
Hinged dual flap caps serve divergent performance requirements across pharmaceutical, food, and personal care channels. Segment boundaries reflect material science capabilities, regulatory compliance tiers, and dispensing precision demands that reshape supplier qualification criteria.
Product Type:
Margin pools concentrate in material grades that balance hinge fatigue performance with regulatory submission pathways.
- Plastic:Polypropylene and polyethylene resins dominate volume through multi-cavity injection molding. Pharmaceutical manufacturers in Germany specify these for oral solid dose formats requiring moisture barriers and child-resistant certification under EU MDR.
- Composite:Hybrid structures pair glass-fiber reinforced segments with flexible polyolefin cores. Swiss medical device manufacturers pilot these for insulin pen applications where cycle life must exceed 2000 actuations, fragmenting supplier tiers between advanced co-injection molders and commodity producers.
- Metal:Aluminum and tinplate variants serve premium cosmetic and specialty food segments requiring barrier properties beyond polymer permeability limits.
- Glass:Borosilicate and soda-lime formulations appear in laboratory reagent and high-purity pharmaceutical applications where chemical inertness overrides mechanical durability concerns.
Plastic holds installed capacity. Composite is rotating up the share rankings.
Closure Mechanism:
Volume throughput clusters around designs that minimize user error in regulated dispensing environments.
- Screw Cap:Threaded engagement provides resealable containment for multi-dose pharmaceutical bottles. FDA 21 CFR Part 170-199 compliance documentation burdens favor established molders with validated cavity-to-cavity consistency.
- Snap Fit:Audible engagement feedback supports child-resistant applications where tactile confirmation of seal integrity matters. German contract packaging services specify these for over-the-counter medicine lines in Baden-Württemberg.
- Push-Pull:Linear actuation suits single-handed dispensing in personal care and household product channels where convenience drives repeat purchase.
- Twist Off:Breakaway torque requirements align with tamper-evident mandates in food packaging where consumer safety signaling precedes reseal functionality.
Screw Cap anchors pharmaceutical procurement. Snap Fit is gaining share fastest in child-resistant applications.
End User:
Specification intensity varies sharply between clinical-grade dispensing and commodity consumer packaging.
- Pharmaceuticals:Oral solid dose formats demand precise moisture control and ISO 8317 child-resistant certification. Indian generic drug exporters now separate closure procurement from primary container contracts to optimize landed cost structures.
- Food & Beverage:Extended shelf-life requirements drive adoption of multi-point sealing configurations in condiment and sauce categories.
- Cosmetics:Premium positioning emphasizes tactile hinge quality and aesthetic surface finishes over functional complexity.
- Household Products:Cost-optimized polypropylene designs serve institutional and retail channels with minimal regulatory documentation burdens.
Pharmaceuticals commands specification premiums. Food & Beverage is expanding volume fastest through condiment innovation.
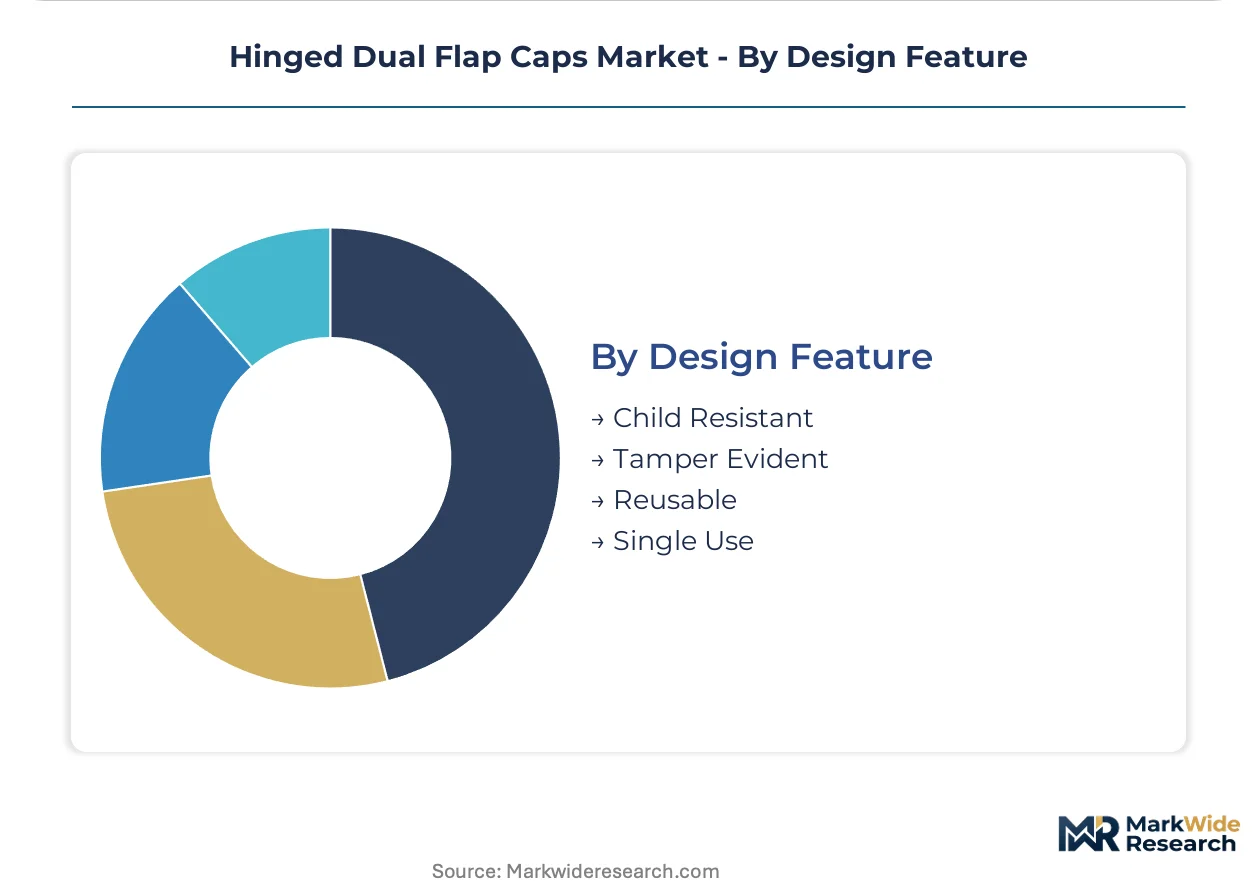
Design Feature:
Compliance mandates and sustainability positioning split development resources across irreversible and circular economy pathways.
- Child Resistant:ISO 8317 testing requirements concentrate supply among European and North American specialists with certified laboratories. CDSCO tightening in India is accelerating pre-qualification demand among domestic formulators.
- Tamper Evident:Breakaway bands and seal integrity indicators serve FDA and EU MDR traceability requirements for clinical-grade dispensing systems.
- Reusable:Living hinge fatigue limits of 500-1000 cycles restrict deployment in institutional settings despite circular economy pressures.
- Single Use:Unit-dose optimization for direct-to-patient pharmacy channels in Germany and France favors disposable designs with integrated dispensing controls.
Child Resistant holds regulatory-driven pricing power. Reusable is climbing the fastest as bio-based material transitions mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity for generic drug packaging, while German and Swiss pharmaceutical manufacturers absorb premium pricing for certified child-resistant systems. This elasticity gap concentrates margin capture in Western European supply chains while volume growth accelerates in cost-optimized Asian markets.
Germany
Contract packaging services for over-the-counter medicines in Baden-Württemberg and Bavaria are expanding dedicated production lines. EU MDR traceability mandates lock in qualified suppliers with ISO 8317 certified testing protocols. Stuttgart and Munich clusters concentrate pharmaceutical formulators specifying hinged dual flap closures as standard configuration.
United States
FDA 21 CFR Part 170-199 compliance documentation burdens favor established molders with validated cavity-to-cavity consistency. New Jersey and Massachusetts pharmaceutical corridors drive specification intensity for oral solid dose formats. FDA child-resistant packaging mandates compress redesign cycles for living hinge geometries.
Switzerland
Medical device manufacturers pilot composite hinge structures for insulin pen applications requiring cycle life beyond 2000 actuations. Swissmedic regulations govern clinical-grade dispensing closure performance. Basel pharmaceutical procurement teams unbundle closure supply from primary container contracts.
India
CDSCO tightening of export documentation requirements for oral solid dose formats creates demand for pre-qualified child-resistant closure systems. Mumbai and Hyderabad generic drug exporters separate closure procurement to optimize landed cost structures. Domestic formulators accelerate pre-qualification timelines.
France
Direct-to-patient pharmacy channels require unit-dose packaging with integrated dispensing controls. ANSM regulations align with EU MDR for Class I dispensing closure serialization. Paris and Lyon e-pharmacy fulfillment networks optimize hinged dual flap designs for last-mile distribution.
Hinged Dual Flap Caps Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure in hinged dual flap caps. Integrated resin-to-dispenser players command multi-continent manufacturing footprints, while precision closure specialists anchor regional pharmaceutical channels with dedicated infrastructure. Three archetypes dominate: full-stack material converters, high-speed automation platform operators, and certified testing protocol specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves as qualification bottlenecks intensify.
Among integrated material converters, Amcor plc exemplifies the resin-to-dispenser archetype spanning multiple continents. Silgan Dispensing Systems occupies a position within North American pharmaceutical and personal care channel specialists. AptarGroup, Inc. represents the high-speed automation platform tier serving regulated drug packaging applications.
| Leading Market Players |
|---|
| Amcor plc |
| Silgan Dispensing Systems |
| AptarGroup, Inc. |
| United Caps |
| ALPLA Werke Alwin Lehner GmbH & Co. KG |
| Berry Global, Inc. |
| Mold-Rite Plastics |
| Closure Systems International |
| Silgan Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month mold qualification timelines for 32-64 cavity pharmaceutical-grade tools concentrate pricing power among established suppliers with validated FDA submission track records, while compressing margin buffers for new entrants facing extended cash conversion cycles. This lead-time asymmetry rewards incumbents with certified ISO 8317 testing infrastructure and locks out speculative capacity additions.
Pricing Analysis
After-sales revenue from technical qualification support and regulatory documentation services drives lifetime value beyond unit margins. Pricing stratifies across premium, standard, and economy tiers based on ISO 8317 certification grade and volume commitment scale. Cost compression in the standard tier intensifies because Indian generic drug exporters separate closure procurement to optimize landed cost structures. Pharmaceutical manufacturers in Germany and Switzerland exhibit lowest price sensitivity, while domestic formulators in India and Southeast Asia prioritize landed cost minimization.
Supply Chain Analysis
Inventory positions and lead-time buffers vary sharply between European precision specialists and Asian volume molders. Supply concentrates in Germany, Switzerland, and the United States for certified pharmaceutical-grade closures, while China and India feed cost-optimized household and generic drug channels. Raw material dependencies center on polypropylene and polyethylene resins, glass-fiber reinforcement compounds, and mass balance-certified bio-based feedstocks. Single-source vulnerability clusters around certified testing laboratory access. Distribution runs through direct pharmaceutical procurement teams in Basel and New Jersey, contract packaging services in Baden-Württemberg, and domestic formulator networks in Hyderabad.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against flip-top and pump dispenser formats that threaten share in personal care and institutional channels. Incumbents must demonstrate irreplaceable value in regulated pharmaceutical applications where compliance documentation creates switching costs.
For Market Incumbents: Fortify qualification moats by embedding ISO 8317 testing capabilities within captive facilities rather than outsourced arrangements. Expand backward integration into resin compounding for bio-based polypropylene grades to capture EU Green Deal content premiums. Lock in multi-year supply agreements with German contract packaging services in Baden-Württemberg and Bavaria before capacity expansion cycles complete.
For New Entrants and Emerging Players: Lead with CDSCO pre-qualification services for Indian generic drug exporters facing tightening export documentation requirements. Target the domestic pharmaceutical formulator segment in Hyderabad and Mumbai where closure procurement unbundling creates discrete sourcing opportunities. Differentiate through rapid mold qualification timelines under 12 months for non-pharmaceutical applications.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underperforming closure divisions lacking pharmaceutical certification depth. Position holdings for a 5-10 year window where EU MDR traceability mandates concentrate volume among qualified suppliers. Monitor FDA submission backlogs as an inflection indicator for qualification bottleneck severity.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 8317 Certification Investment | Creates regulatory barrier against uncertified competitors in EU and US pharmaceutical channels. |
| Bio-Based Polypropylene Transition | Enables EU Green Deal compliance without sacrificing hinge fatigue performance thresholds. |
| Direct-to-Patient Packaging Partnership | Captures e-pharmacy growth in German and French unit-dose fulfillment networks. |
| Composite Hinge Co-Injection Capacity | Accesses Swiss medical device manufacturer demand for 2000+ cycle life applications. |
| CDSCO Pre-Qualification Service Launch | Addresses accelerating demand from Indian generic drug exporters facing documentation tightening. |
Study Parameters
Initial hypotheses were tested against primary input from pharmaceutical packaging procurement managers, injection molding plant engineers, regulatory affairs specialists, and contract packaging operations directors, and refined through secondary validation against FDA 21 CFR Part 170-199 filings, EU MDR technical documentation databases, CDSCO export registration records, and customs trade data for polypropylene closure components. Bottom-up capacity assessments from identified molders were triangulated against top-down pharmaceutical packaging demand models.
Variance decomposition across product type, closure mechanism, end-user segment, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by pharmaceutical oral solid dose expansion rates and personal care dispensing format substitution patterns. Industry-specific inputs included ISO 8317 certification database growth, EU MDR Unique Device Identification implementation timelines, and Indian pharmaceutical export documentation filing velocities.
The analysis sits within stated boundaries; outcomes outside sustained EU MDR enforcement intensity or abrupt polypropylene feedstock supply disruptions would require recalibration. Forecasts reflect documented assumptions regarding certification timeline stability and pharmaceutical outsourcing momentum. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Ribbed Closures Market
Caps and Closures
Spray Caps Market
Caps and Closures
IBC Caps Market
Caps and Closures
Morocco Plastic Caps and Closures Market
Caps and Closures
Europe Plastic Caps and Closures Market
Caps and Closures
Tear Tab Cap Market
Caps and Closures
Global Die Cut Lids Market
Caps and Closures
Middle East and Africa Plastic Caps and Closures Market
Caps and Closures
Flapper Caps Market
Caps and Closures
Snap Cap Vials Market
Caps and Closures
Tear-Tab Lids Market
Caps and Closures
Polypropylene Screw Caps Market
Caps and Closures
Elastomeric Closures Market
Caps and Closures
Crown Closures Market
Caps and Closures
APAC Plastic Caps and Closures Market
Caps and Closures
Flip Top Caps and Closures Market