
 Crown Caps Market | 2026-2036
Crown Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Crown Caps Market Analysis
Subscription-based liner replacement programs for reusable bottle systems is rebalancing how closure suppliers monetize long-term customer relationships. Crown Holdings Inc. leverages its integrated metal-forming operations across multiple continents to sustain cost advantages in high-volume contracts. Silgan Holdings Inc. anchors its competitive position through specialized coating technologies that extend shelf stability for sensitive beverages. Pelliconi & C. SpA differentiates via precision manufacturing of custom-embossed crowns serving premium craft brewers.
A crown cap is a metal closure, typically manufactured from tinplate or aluminum with a polyethylene or PVC liner, that crimps onto glass bottle necks to create a hermetic seal against carbonation loss and microbial ingress; standard crowns require a bottle opener while twist-off variants incorporate threaded geometry for hand removal. The beverage industry end-user segment dominates volume consumption, with carbonated drinks and liquors applications commanding the largest share of metal crown deployment due to pressure-retention requirements and established capping infrastructure. Twist-off caps represent the fastest-growing product type as convenience-oriented packaging gains traction in premium beer and ready-to-drink categories, while ROPP caps occupy a specialized niche in wine and spirits where tamper-evidence regulations command higher per-unit margins.
The FDA governs liner material safety for food-contact applications in the United States, while the EU F-Gas Regulation and REACH framework constrain certain coating chemistries and push manufacturers toward lower-emission production methods. BIS certification requirements in India mandate specific dimensional tolerances and corrosion resistance for imported metal closures, shaping market access for foreign suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and liner material bans to anticipate forced redesign cycles and secure compliant raw material sourcing before regulatory deadlines tighten.
Market Dynamics
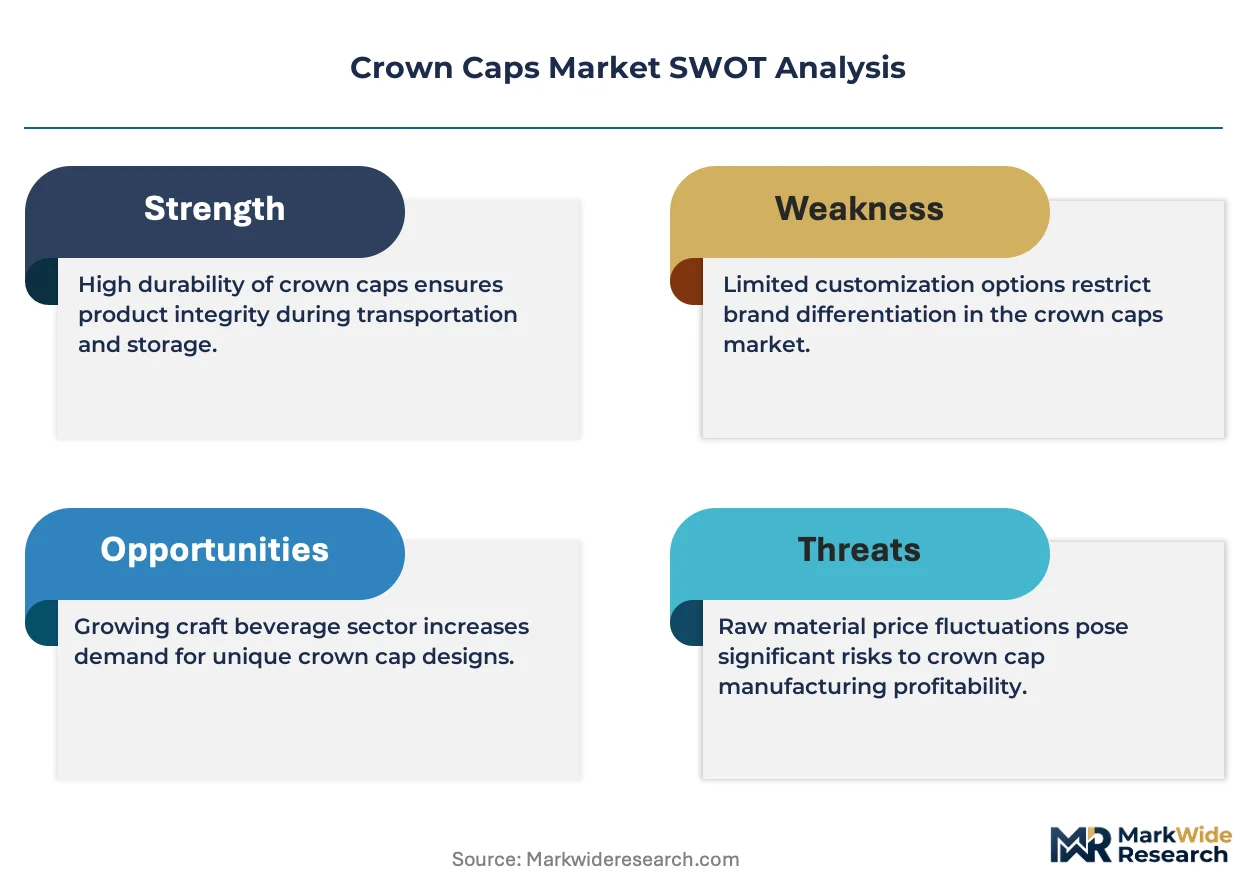
The EU Single-Use Plastics Directive is accelerating material substitution across beverage packaging supply chains, forcing closure manufacturers to reengineer liner chemistries and aluminum-to-plastic ratios ahead of enforcement deadlines.
Growth Catalysts
- Craft brewery expansion:Small-batch brewers in the United States and Germany are specifying custom-embossed twist-off variants to differentiate premium product lines.
- REACH framework compliance:European coating chemistry restrictions are pushing manufacturers toward water-based sealant formulations that reduce volatile organic compound emissions.
- Aluminum sourcing advantages:Secondary smelter capacity in the Middle East is lowering input costs for high-volume crown cap producers serving export markets.
Market Restraints
- Tinplate supply concentration:Three integrated steel mills control two-thirds of food-grade electrolytic tinplate output, creating price volatility vulnerability.
- PVC liner substitution costs:Polyethylene and biopolymer alternatives require retooling crimping equipment and extend qualification timelines.
- Glass bottle demand erosion:Aluminum can adoption in ready-to-drink cocktails is displacing crown-sealed glass in convenience channels.
Strategic Opportunities
- India beverage packaging:BIS certification mandates for imported closures create localized production incentives for foreign suppliers establishing domestic manufacturing.
- Reusable bottle systems:Subscription-based liner replacement programs are creating recurring revenue streams independent of new bottle sales.
- Composite material convergence:Fiber-reinforced thermoplastic crowns combining aluminum shells with bio-based cores address both lightweighting and circularity targets.
Industry Challenges
- Coating chemistry expertise:Formulation chemists capable of balancing corrosion resistance, food-contact safety, and crimp performance remain scarce in Eastern European manufacturing hubs.
- Legacy capping line integration:Twist-off variants require thread-forming mandrel retrofits that disrupt high-speed bottling operations.
- Extended producer responsibility tracking:EU member-state implementation variations complicate compliance documentation for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crown Caps Market |
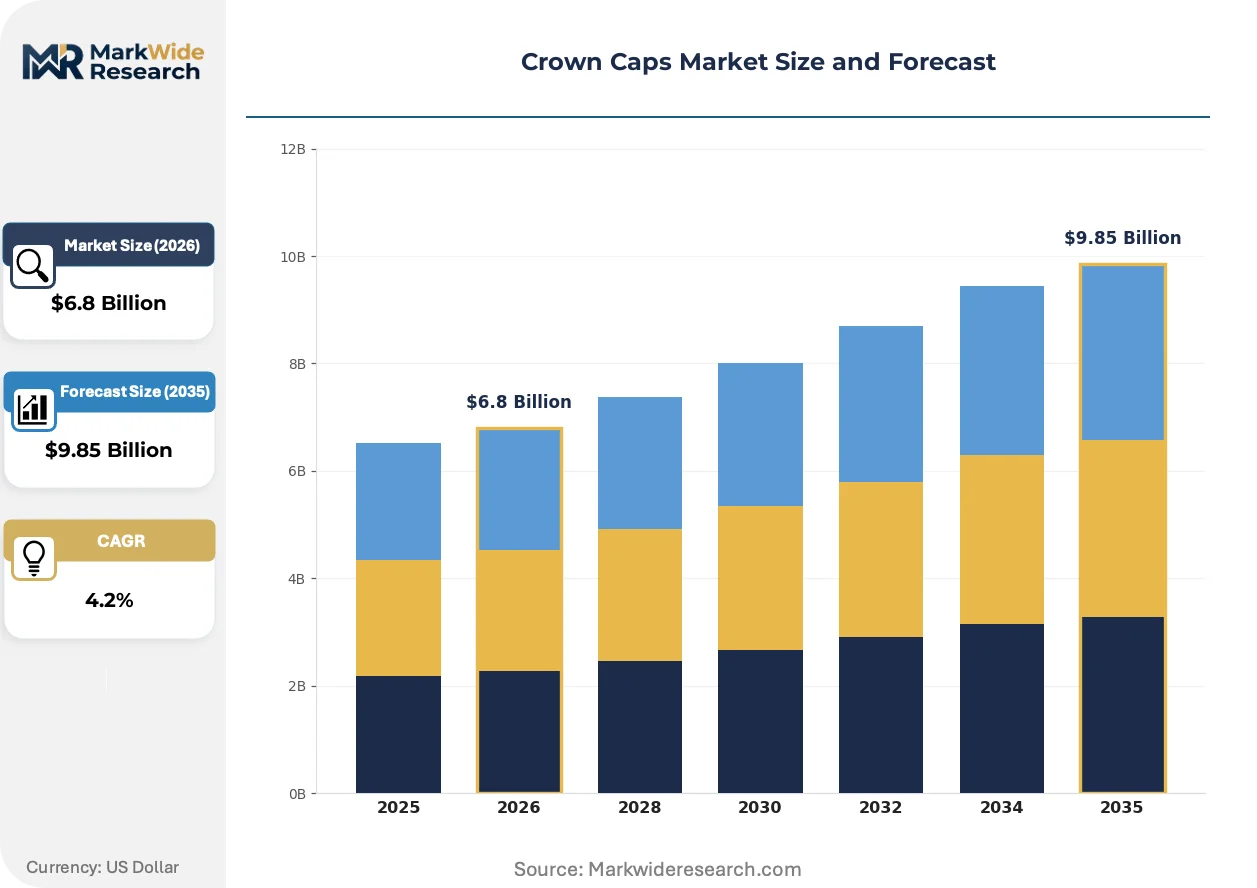
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Crown, Twist-off Caps, Easy-open Caps, ROPP Caps Material: Metal, Plastic, Composite, Aluminum End User: Beverage Industry, Food Packaging, Pharmaceuticals, Personal Care Application: Carbonated Drinks, Bottled Water, Condiments, Liquors |
| Companies Covered | Silgan Holdings Inc., Sonoco Products Company, Crown Holdings Inc., Amcor plc, Closure Systems International, Pelliconi & C. SpA, Guala Closures Group S.p.A., AptarGroup, Inc., Nippon Closures Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crown Caps Market Emerging Trajectories
Digital printing and smart packaging integration are rewriting how closure suppliers capture value beyond the physical seal, while regulatory chemistry constraints and convenience-driven consumer behavior reshape product roadmaps.
Laser-etched QR codes on crown caps are decentralizing authentication and traceability functions from centralized databases to individual package-level verification. Premium spirits producers in Scotland and Kentucky are adopting serialized caps to combat counterfeiting. This technology is decentralizing supply chain transparency investments from brand owners to packaging component suppliers.
The EU F-Gas Regulation is constraining fluoropolymer-based coating chemistries used for oxygen barrier performance. Manufacturers are pivoting toward ceramic-oxide and graphene-doped alternatives that maintain shelf stability. Wine and spirits applications with extended aging requirements face the steepest reformulation timelines.
Direct-to-brewer procurement platforms are compressing traditional distributor intermediation in specialty beer segments. Craft producers in Oregon, Colorado, and Bavaria are sourcing custom crowns through manufacturer-hosted configurators. This channel shift concentrates design authority with smaller-volume buyers who previously relied on standardized catalog offerings.
Crown Caps Market Segmentation
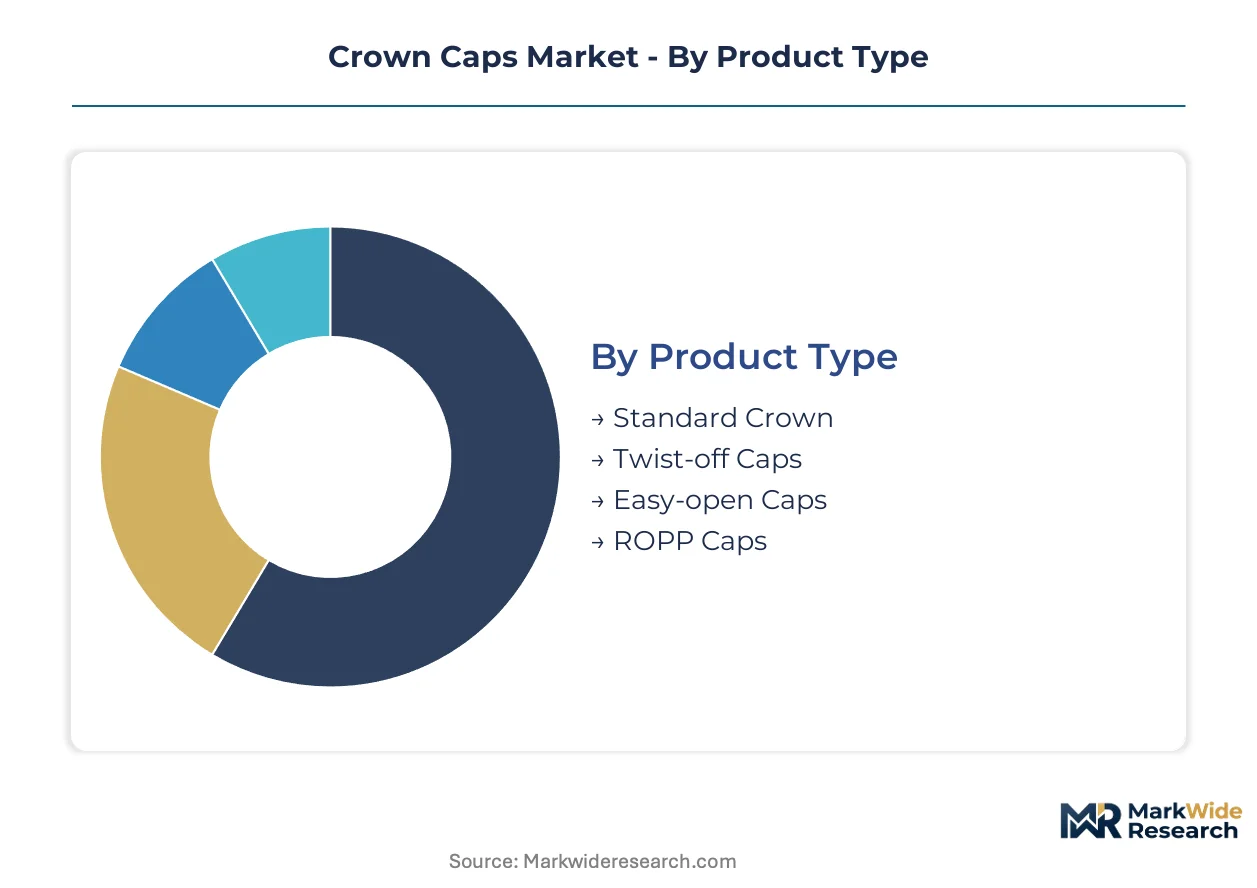
Crown cap specifications vary sharply across end-use applications, with beverage pressure-retention requirements, pharmaceutical tamper-evidence mandates, and food-contact safety protocols each dictating distinct liner chemistries and crimp geometries. Material substitution pressures from EU regulatory frameworks are fragmenting procurement patterns as buyers requalify suppliers against evolving compliance baselines.
Product Type:
Certification burdens cluster around twist-off and ROPP variants, where threaded mandrel compatibility testing and tamper-evidence validation extend qualification timelines versus standardized crown formats.
- Standard Crown:Tinplate or aluminum shells with PVC or polyethylene liners crimp onto glass bottle necks via capping head pressure. German export breweries and Mexican glass bottlers sustain the highest procurement volumes for this format due to established high-speed line infrastructure and minimal retooling costs.
- Twist-off Caps:Aluminum shells incorporate pre-formed threads and breakaway bands for hand removal without tools. United States craft breweries in Oregon and Colorado are driving specification shifts toward custom-embossed twist-off variants as premium differentiation tools, though thread-forming mandrel retrofits disrupt legacy bottling operations.
- Easy-open Caps:Pull-tab mechanisms integrated into crown geometry target accessibility-focused beverage segments. Japanese ready-to-drink cocktail producers represent the primary demand concentration for this specialized format.
- ROPP Caps:Roll-on pilfer-proof aluminum closures with integral tamper-evident bands serve wine and spirits applications where regulatory tamper-evidence requirements command higher per-unit margins. Scottish whisky distillers and Kentucky bourbon producers specify serialized laser-etched variants for counterfeiting protection.
Leading the category by volume: Standard Crown. Growing fastest: Twist-off Caps.
Material:
Cost tiers separate commodity metal inputs from engineered composites, with aluminum commanding premium positioning against tinplate volatility while biopolymer alternatives occupy experimental niches.
- Metal:Electrolytic tinplate and aluminum represent the incumbent volume base, with tinplate supply concentrated among three integrated steel mills creating price volatility exposure. Beverage applications in Germany and Mexico rely on metal crowns for pressure retention and established recycling infrastructure.
- Plastic:Polypropylene and polyethylene variants serve low-pressure applications where weight reduction outweighs barrier performance requirements. Indian condiment packagers specify plastic crowns for cost-sensitive regional brands.
- Composite:Fiber-reinforced thermoplastic cores bonded to aluminum shells address lightweighting targets without sacrificing crimp integrity. European sustainability mandates are accelerating pilot deployments in French and Italian premium water segments.
- Aluminum:Secondary smelter capacity in the Middle East is lowering input costs for high-volume producers, with aluminum crowns gaining share in carbonated soft drinks due to superior oxygen barrier performance versus tinplate alternatives.
Dominating procurement value: Aluminum. Expanding most quickly: Composite.
End User:
Application-driven margin structures concentrate investment in beverage and pharmaceutical segments, where specification complexity and regulatory documentation requirements create supplier stickiness.
- Beverage Industry:Carbonated drinks, beer, and ready-to-drink cocktails command the largest metal crown deployment due to pressure-retention requirements and established capping infrastructure. German brewing exports and United States craft production anchor global demand concentration.
- Food Packaging:Condiment and sauce applications utilize lower-pressure crown formats with modified liner chemistries for acidic content compatibility. Italian tomato paste and Indian pickle packagers represent regional volume centers.
- Pharmaceuticals:Tamper-evident and child-resistant specifications drive specialized ROPP and composite crown adoption. FDA 21 CFR compliance requirements extend qualification timelines for suppliers targeting United States oral liquid formulations.
- Personal Care:Cosmetic and hair care applications prioritize aesthetic customization over functional performance, with direct-to-brand procurement platforms enabling smaller-volume buyers to specify embossed or printed variants.
Commanding volume leadership: Beverage Industry. Steepest expansion trajectory: Pharmaceuticals.
Application:
Geography and channel dynamics fragment demand, with carbonated drinks sustaining high-volume contracts while liquors concentrate premium specification value in regulated spirits markets.
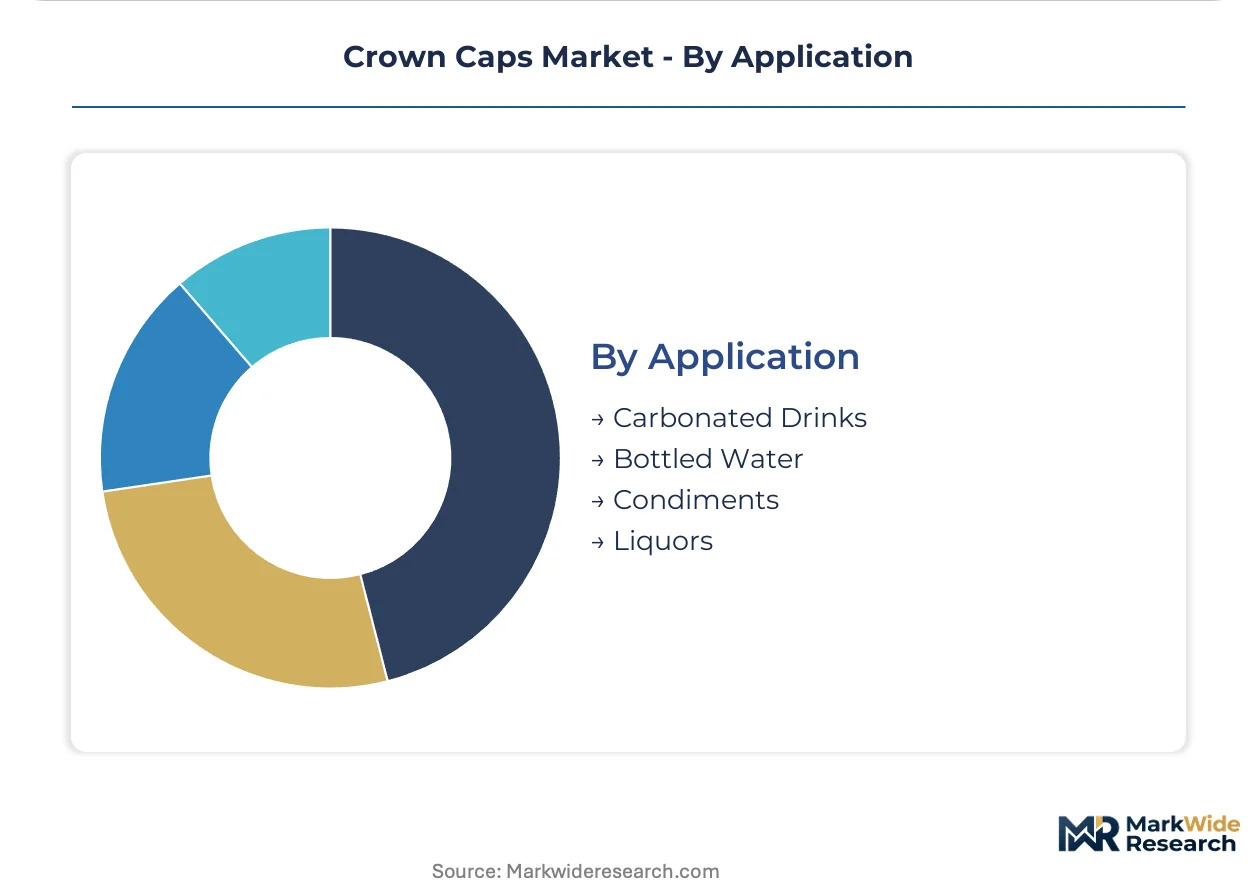
- Carbonated Drinks:Cola, sparkling water, and energy drink applications require maximum pressure retention and hermetic sealing against carbonation loss. Mexican and German bottlers operate the densest concentrations of high-speed capping lines optimized for standard crown formats.
- Bottled Water:Still and lightly carbonated water segments tolerate lower-specification crowns, enabling cost-driven substitution toward plastic and composite alternatives in European sustainability-focused markets.
- Condiments:Ketchup, mustard, and sauce applications face acidic content compatibility requirements that favor specialized liner formulations. Indian and United States regional brands drive procurement fragmentation through direct manufacturer relationships.
- Liquors:Whisky, vodka, and spirit applications combine tamper-evidence mandates with premium aesthetic requirements. Scottish, Kentucky, and Japanese distillers specify serialized or custom-embossed ROPP variants at price points supporting specialized manufacturing investments.
Highest procurement volume: Carbonated Drinks. Gaining share fastest: Liquors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and Mexico where high-speed bottling infrastructure sustains standardized crown procurement, while consumption fragments across craft brewery clusters in Oregon and Colorado demanding custom twist-off variants. The EU F-Gas Regulation and India's BIS certification reshape trade flows and localization incentives.
Germany
Export-oriented brewing industries in Bavaria and North Rhine-Westphalia sustain the densest concentration of high-volume crown cap procurement in Europe. The EU REACH framework constrains coating chemistries, pushing manufacturers toward water-based sealant formulations. Munich and Hamburg anchor specialized supplier networks serving both domestic bottlers and Middle East export markets.
United States
Craft breweries in Oregon, Colorado, and Kentucky specify custom-embossed twist-off variants as premium differentiation tools. FDA liner material safety requirements govern food-contact applications, extending qualification timelines for alternative polymer formulations. The Pacific Northwest brewing cluster is retrofitting legacy capping lines to accommodate threaded mandrel geometries.
India
Regional condiment packagers in Maharashtra and Gujarat drive procurement fragmentation through direct manufacturer relationships. BIS certification mandates for imported closures create localized production incentives for foreign suppliers establishing domestic manufacturing. The Haryana industrial corridor is attracting secondary smelter-linked crown cap fabrication to serve beverage export growth.
Mexico
Carbonated soft drink bottlers operate the highest-speed capping line concentrations optimized for standard aluminum crown formats. NAFTA-origin content rules and USMCA compliance documentation shape cross-border supplier qualification. Mexico City and Monterrey anchor integrated metal-forming operations serving North American beverage contracts.
Japan
Ready-to-drink cocktail producers represent the primary demand concentration for easy-open pull-tab crown variants. METI sustainability guidelines and circular economy targets accelerate pilot deployments of fiber-reinforced thermoplastic composite crowns. The Kansai region maintains specialized coating expertise for oxygen-sensitive beverage applications.
Crown Caps Market Vendor Landscape
Top-tier vendors anchor high-volume beverage contracts, while mid-tier specialists capture premium craft brewery specifications through customization capabilities. The market structures around three strategic archetypes: integrated metal-forming conglomerates with captive aluminum supply, precision coating specialists extending shelf stability, and custom-embossing boutiques serving small-batch brewers. Dominant competitive moves include backward integration into secondary smelter partnerships and geographic expansion via BIS-certified manufacturing in India.
Within the integrated metal-forming tier, Crown Holdings Inc. and Silgan Holdings Inc. exemplify scale-driven positioning through multi-continent production footprints. Pelliconi & C. SpA occupies the precision customization vector, representing the specialist archetype that serves premium craft segments requiring embossed and serialized variants. These three anchors demonstrate how competitive positioning fragments across volume efficiency, coating technology, and design flexibility rather than converging on a single dominant model.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| Sonoco Products Company |
| Crown Holdings Inc. |
| Amcor plc |
| Closure Systems International |
| Pelliconi & C. SpA |
| Guala Closures Group S.p.A. |
| AptarGroup, Inc. |
| Nippon Closures Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
The EU Single-Use Plastics Directive gates both qualified supply and premium-tier pricing access, as manufacturers must reengineer liner chemistries and aluminum-to-plastic ratios to maintain certification eligibility while craft breweries in Oregon and Colorado absorb higher per-unit costs for custom-embossed twist-off variants.
Pricing Analysis
Cost-down pressure on standard crown formats accelerates because tinplate supply concentration among three integrated steel mills amplifies input volatility, while premium-mid-economy pricing differentiation separates serialized ROPP variants for Kentucky bourbon producers from commodity aluminum crowns serving Mexican carbonated soft drink bottlers. Price differentiation traces to REACH-compliant coating certifications and volume scale, with Indian condiment packagers exhibiting highest sensitivity and Scottish whisky distillers least.
Supply Chain Analysis
Formulation chemists capable of balancing corrosion resistance with food-contact safety remain scarce in Eastern European manufacturing hubs, constraining coating capacity expansion even as demand concentrates in Germany, Mexico, and the United States. Raw material flows draw from Middle Eastern secondary aluminum smelters, German electrolytic tinplate mills, and Japanese coating chemical suppliers. Single-source vulnerability in tinplate creates structural risk. Distribution runs through direct-to-brewer procurement platforms and traditional beverage packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive aluminum supply and in-house coating formulation capabilities determine margin capture against raw material volatility.
For Market Incumbents: Hedge tinplate price exposure through long-term offtake agreements with Middle Eastern secondary smelters for aluminum substitution. Consolidate coating chemistry expertise via targeted hiring in German and Japanese technical centers to defend against REACH-driven reformulation delays. Backward integration into liner material production insulates against PVC substitution cost shocks.
For New Entrants and Emerging Players: Craft brewery configurators represent the most penetrable channel partner type, enabling direct specification capture from Oregon and Colorado small-batch producers bypassing traditional distributor intermediation. Target BIS-certified manufacturing in India to serve Maharashtra and Gujarat condiment packagers. White-space exists in serialized laser-etching capabilities for premium spirits authentication.
For Investors and Strategic Acquirers: Closure manufacturer announcements of water-based sealant formulation partnerships is the leading indicator that REACH compliance timelines are compressing and coating chemistry expertise is consolidating. Long-term viability over the coming decade rests on circular-economy positioning and reusable bottle system integration. Acquisition targets should exhibit precision embossing capabilities or composite material pilot programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Secondary Smelter Partnerships | Middle Eastern aluminum capacity secures input cost advantages against tinplate volatility. |
| Water-Based Coating Formulation Investment | REACH-compliant chemistry reduces VOC emissions while maintaining oxygen barrier performance. |
| Direct-to-Brewer Procurement Platform Launch | Crown Holdings and Pelliconi configurators compress distributor margins in craft segments. |
| Composite Material Pilot Deployment | Fiber-reinforced thermoplastic cores address EU circularity targets in French premium water. |
| BIS-Certified Manufacturing Establishment | Localized Indian production bypasses import certification barriers for Maharashtra condiment packagers. |
Methodological Framework
Multi-period observation of liner material substitution rates, REACH compliance announcement velocity, and craft brewery specification shifts anchored the trend analysis, supplemented by interviews with beverage packaging procurement managers, capping line engineers, coating formulation chemists, and secondary smelter commercial officers. Secondary validation drew from EU F-Gas Regulation filings, BIS certification databases, FDA food-contact material registrations, and beverage industry trade association capacity surveys. Bottom-up volume modeling triangulated against top-down macro demand indicators.
Segment-weighting across product type, material composition, end-user industry, and application geography structured the analytical framework throughout the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating aluminum price trajectories and regulatory enforcement timelines. Industry-specific forecast inputs included German brewing export volumes and United States craft brewery formation rates.
Caveats apply where EU member-state implementation variations in extended producer responsibility frameworks could materially shift the outlook, or where glass bottle demand erosion from aluminum can substitution accelerates beyond modeled trajectories. A small set of triggers including F-Gas Regulation amendment timing and Indian BIS certification scope expansion warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Dropper Caps Market
Caps and Closures
Resealable Closures and Spouts Packaging Market
Caps and Closures
Gamma Seal Lids Market
Caps and Closures
Cap Seals Market
Caps and Closures
Smooth Hinge Caps and Closure Market
Caps and Closures
Spain Plastic Cap and Closure Market
Caps and Closures
APAC Plastic Caps and Closures Market
Caps and Closures
United Kingdom Plastic Caps and Closures Market
Caps and Closures
Italy Plastic Caps and Closures Market
Caps and Closures
Caps and Closures Market
Caps and Closures
Brush Caps Market
Caps and Closures
Ring Pull Caps Market
Caps and Closures
United Arab Emirates Plastic Caps and Closures Market
Caps and Closures
Benelux Plastic Caps and Closures Market
Caps and Closures
Cuvette Caps Market
Caps and Closures
Fixed Length Seals Market