
 Cuvette Caps Market | 2026-2036
Cuvette Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Cuvette Caps Market Outlook
Single-use consumable standardization is narrowing the design gap between research-grade and clinical-grade cuvette caps. Thermo Fisher Scientific leverages its integrated life sciences platform to sustain dominance in high-throughput laboratory supply chains. Eppendorf AG anchors its position through precision molding capabilities calibrated to German DIN standards. Greiner Bio-One differentiates via automated production lines serving European diagnostic OEMs.
A cuvette cap is a closure device engineered to seal spectrophotometer cuvettes, typically manufactured from polypropylene or polyethylene with tight dimensional tolerances to prevent optical interference and sample contamination during ultraviolet-visible light analysis. The primary commercial purpose is to maintain sample integrity across biomedical testing, environmental analysis, and chemical quality control workflows. Optical caps command premium positioning due to their zero-birefringence requirements and compatibility with fluorometry applications. Polypropylene material grades represent the volume base given their chemical resistance and autoclave stability, while sealable variants capture growth in regulated clinical settings where chain-of-custody protocols demand tamper-evident closures. Research laboratories remain the largest end-user channel, though clinical laboratories represent the fastest-expanding segment as point-of-care diagnostic networks proliferate.
FDA 21 CFR Part 820 quality system regulations and ISO 13485 medical device standards govern material traceability and biocompatibility certification for cuvette caps entering clinical diagnostic workflows. EPA Good Laboratory Practice standards further shape demand in environmental testing laboratories by mandating contamination-control protocols. REACH compliance in Europe and China's GB standards for laboratory plastics add layered compliance obligations for multinational suppliers. Stakeholders must monitor evolving regulatory convergence between diagnostic device and general laboratory consumable classifications, as reclassification risks could reshape certification costs and competitive barriers.
Market Dynamics
Standardization between research-grade and clinical-grade consumables is compressing design differentiation and forcing suppliers to recalibrate certification investments across dual-use product lines.
Growth Catalysts
- ISO 13485 certification pathways:Medical device quality standards are pulling diagnostic laboratories toward sealable, tamper-evident closure systems that satisfy chain-of-custody protocols.
- Fluorometry expansion:Zero-birefringence optical caps are gaining traction in molecular diagnostics workflows requiring ultraviolet-visible precision.
- China's analytical instrument manufacturing:Dense concentrations of spectrophotometer OEMs in Jiangsu and Zhejiang provinces are generating localized demand for precision-molded polypropylene consumables.
Market Restraints
- Polypropylene resin volatility:Feedstock price swings tied to propylene monomer supply disrupt margin stability for high-volume cap manufacturers.
- German DIN standard concentration:Precision molding capabilities cluster disproportionately in Baden-Württemberg, creating geographic supply vulnerability for European diagnostic OEMs.
- Glass cuvette persistence:Quartz and borosilicate alternatives in high-sensitivity applications limit polypropylene cap attach rates in certain spectrophotometry segments.
Strategic Opportunities
- Point-of-care diagnostic networks:Decentralized clinical testing in the United States is creating demand for single-use, pre-sterilized cap configurations.
- REACH compliance premiumization:European chemical safety documentation requirements are enabling certified suppliers to capture price premiums from risk-averse buyers.
- Automated production integration:Robotic molding and vision inspection convergence is collapsing unit economics for small-batch custom cap orders.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies extend product launch cycles for clinical-grade variants.
- Optical interference tolerance calibration:Tight dimensional control across temperature cycling requires specialized metrology talent scarce outside established polymer clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cuvette Caps Market |
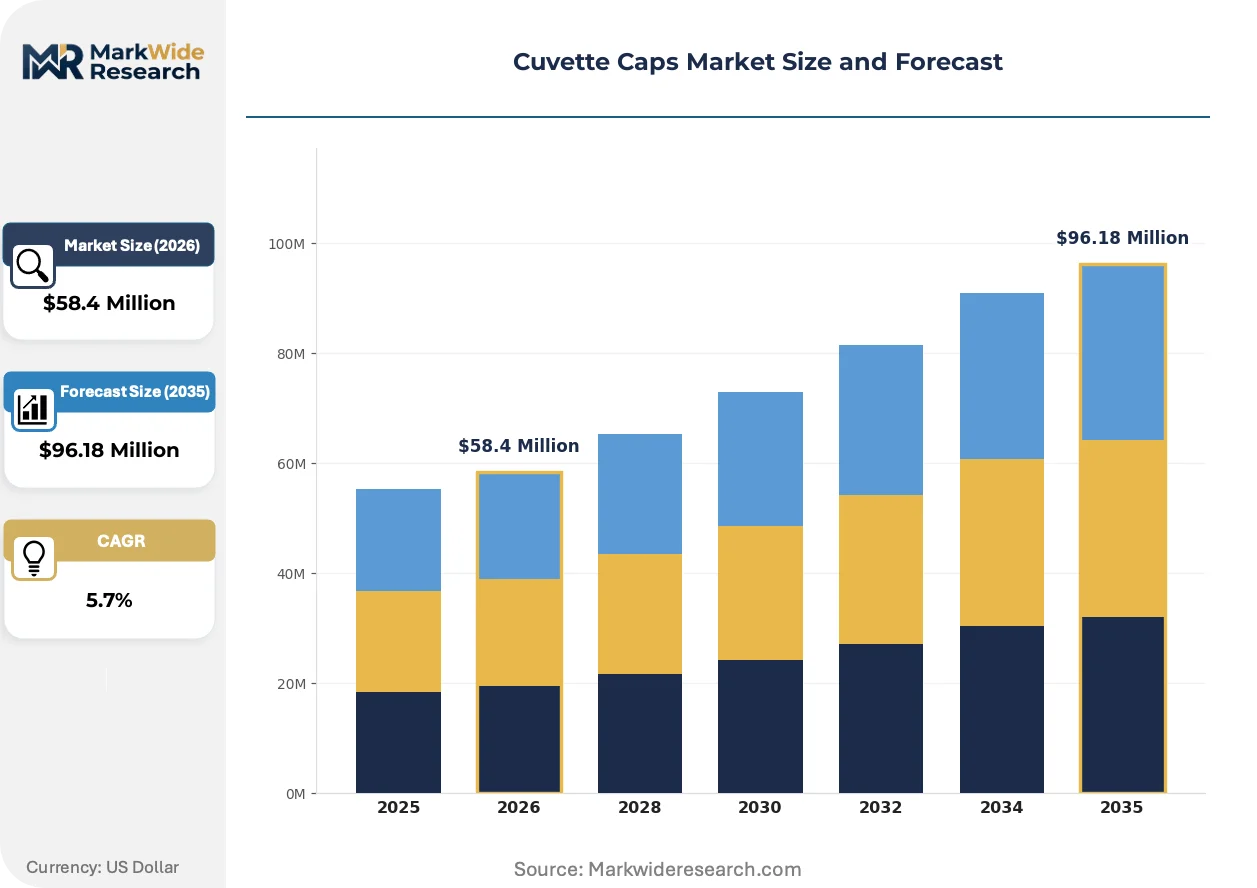
| Market Size in 2026 | $58.4 Million |
| Market Size in 2035 | $96.18 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Caps, Sample Caps, Optical Caps, Sealable Caps Material: Polypropylene, Polyethylene, ABS, PVC End User: Research Laboratories, Clinical Laboratories, Educational Institutions, Quality Control Labs Application: Biomedical Testing, Environmental Analysis, Chemical Testing, Food Safety |
| Companies Covered | Thermo Fisher Scientific, Eppendorf AG, BrandTech Scientific, Greiner Bio-One, Cole-Parmer, Corning Incorporated, Globe Scientific, Heathrow Scientific, DWK Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cuvette Caps Market Strategic Shifts
Material science advances and regulatory convergence are redefining performance thresholds for spectrophotometer consumables, with implications rippling through supplier qualification protocols and buyer specification standards.
Zero-birefringence polypropylene copolymers engineered for fluorometry applications are collapsing the historical performance gap between plastic and quartz closures. Clinical diagnostic laboratories in the United States and Germany are accelerating adoption of these optical-grade materials for high-throughput screening workflows. The technology is collapsing premium pricing power previously held by glass-cuvette incumbent suppliers.
REACH substance restriction expansions in Europe are forcing reformulation of colorants and stabilizers used in laboratory plastics. Manufacturers serving ECHA-registered product categories must now document full material composition down to the additive level. Diagnostic OEMs in France and Switzerland are responding by consolidating supplier bases to pre-qualified vendors with established SCIP database entries.
Consolidated procurement through integrated life sciences distributors is displacing direct manufacturer relationships for mid-volume research laboratories. University and government research facilities in Germany and China are channeling spend through platform distributors offering consolidated SKU coverage. This concentration is most visible in the United States, where Thermo Fisher Scientific and VWR International capture disproportionate cuvette cap volume through bundled consumable contracts.
Cuvette Caps Market Segmentation
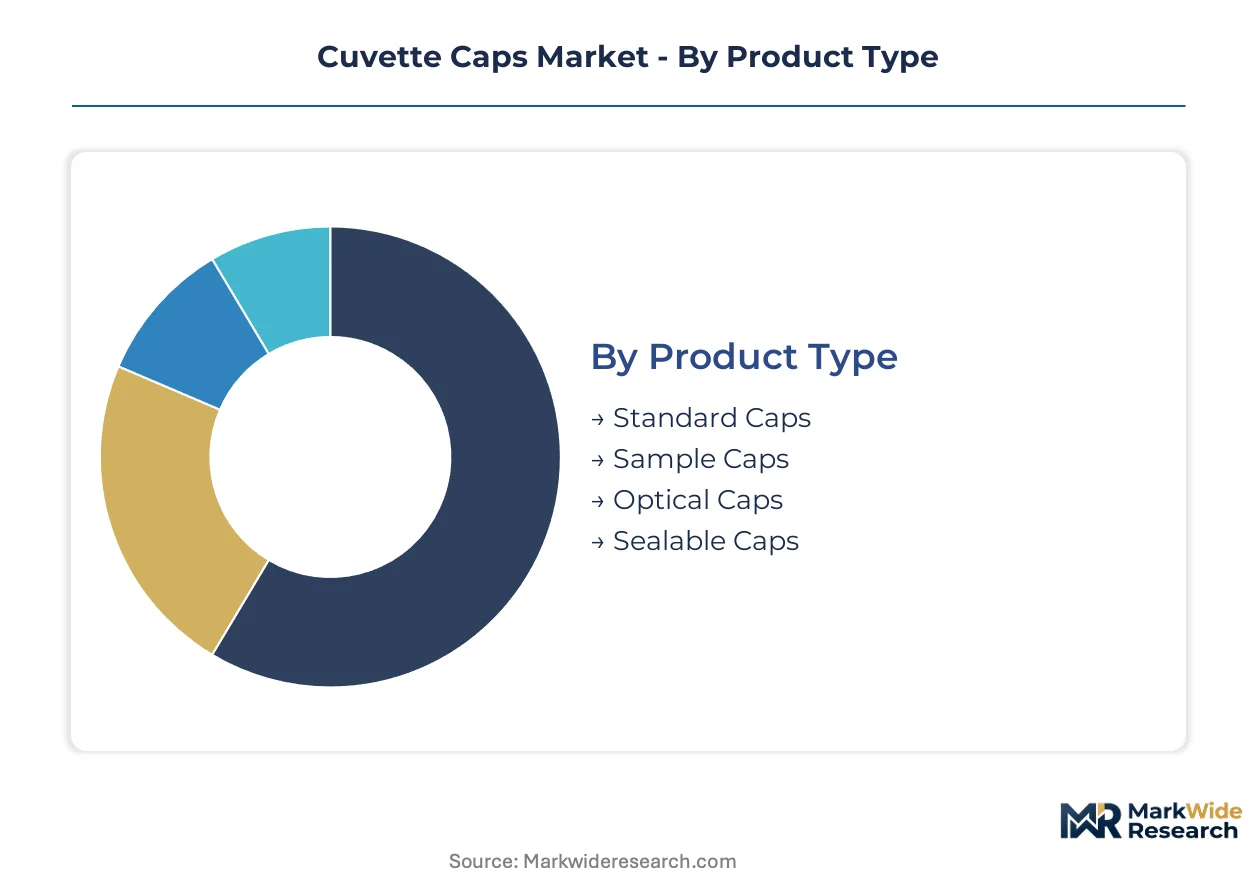
Cuvette cap segmentation reveals how procurement cycles and performance requirements fragment demand across laboratory workflows. Distinct material grades and closure specifications create parallel supply channels serving research, clinical, and industrial end-uses with incompatible certification standards.
Product Type:
Replacement frequencies diverge sharply across this category, with high-throughput screening facilities cycling through caps weekly while specialized optical configurations persist for months in low-volume analytical settings.
- Standard Caps:These general-purpose polypropylene closures serve routine spectrophotometry without specialized optical properties. Research laboratories in Germany and the United States consume the highest volumes, driven by academic procurement cycles that prioritize cost efficiency over performance certification.
- Optical Caps:Engineered from zero-birefringence copolymers to eliminate light scattering in fluorometry applications. Clinical diagnostic networks in the United States are expanding adoption for high-sensitivity molecular assays, though quartz cuvette alternatives constrain attach rates in premium instrument configurations.
- Sample Caps:Intermediate-grade closures balancing chemical resistance with basic optical clarity. Educational institutions represent the core demand channel, with volume concentrated in undergraduate laboratory supply contracts.
- Sealable Caps:Tamper-evident designs incorporating silicone gaskets and snap-lock mechanisms. FDA-regulated clinical laboratories specify these for chain-of-custody protocols, with ISO 13485 certification requirements extending procurement lead times.
Standard caps anchor the volume base while optical caps gain share at the steepest rate.
Material:
Cost tiers stratify sharply across polymer grades, with commodity polypropylene serving price-sensitive bulk purchasers and engineered copolymers capturing premium positioning in regulated diagnostic workflows.
- Polypropylene:Dominant material grade offering autoclave stability and broad chemical resistance. Thermo Fisher Scientific and Eppendorf AG have calibrated precision molding capabilities around this polymer for high-throughput supply chains serving United States and German markets.
- Polyethylene:Lower-cost alternative for single-use applications where thermal cycling demands are minimal. Chinese spectrophotometer OEMs in Jiangsu province specify this grade for bundled consumable packages targeting domestic price competition.
- ABS:Rigid engineering polymer deployed in reusable cap configurations for environmental testing laboratories. EPA Good Laboratory Practice standards favor this material's durability across repeated decontamination protocols.
- PVC:Legacy material grade declining in clinical applications due to plasticizer migration concerns. REACH substance restrictions in Europe have accelerated phase-out timelines, with remaining demand concentrated in non-regulated industrial quality control settings.
Polypropylene commands the installed base while polyethylene expands most quickly in cost-optimized instrument bundles.
End User:
Customer type determines specification intensity, with clinical networks demanding full material traceability while research facilities prioritize availability and price.
- Research Laboratories:Largest demand channel encompassing university, government, and corporate R&D facilities. Procurement through integrated distributors like VWR International dominates, with volume concentrated in the United States and Germany where analytical instrument density is highest.
- Clinical Laboratories:Fastest-expanding segment driven by point-of-care diagnostic network proliferation. FDA 21 CFR Part 820 quality system regulations and ISO 13485 certification requirements create supplier qualification barriers that favor established medical device consumable manufacturers.
- Educational Institutions:Price-sensitive volume channel with standardized specifications and consolidated purchasing through academic supply cooperatives. Demand clusters in undergraduate chemistry and biology laboratory programs.
- Quality Control Labs:Industrial testing facilities serving pharmaceutical, food, and chemical manufacturing. ISO 17025 accreditation requirements shape material documentation demands, with geographic concentration in manufacturing hubs across China and Germany.
Research laboratories anchor the volume base while clinical laboratories climb the fastest.
Application:
Regulatory exposure varies dramatically across use cases, with biomedical and food safety applications subject to stringent material certification while environmental testing operates under less intensive oversight.
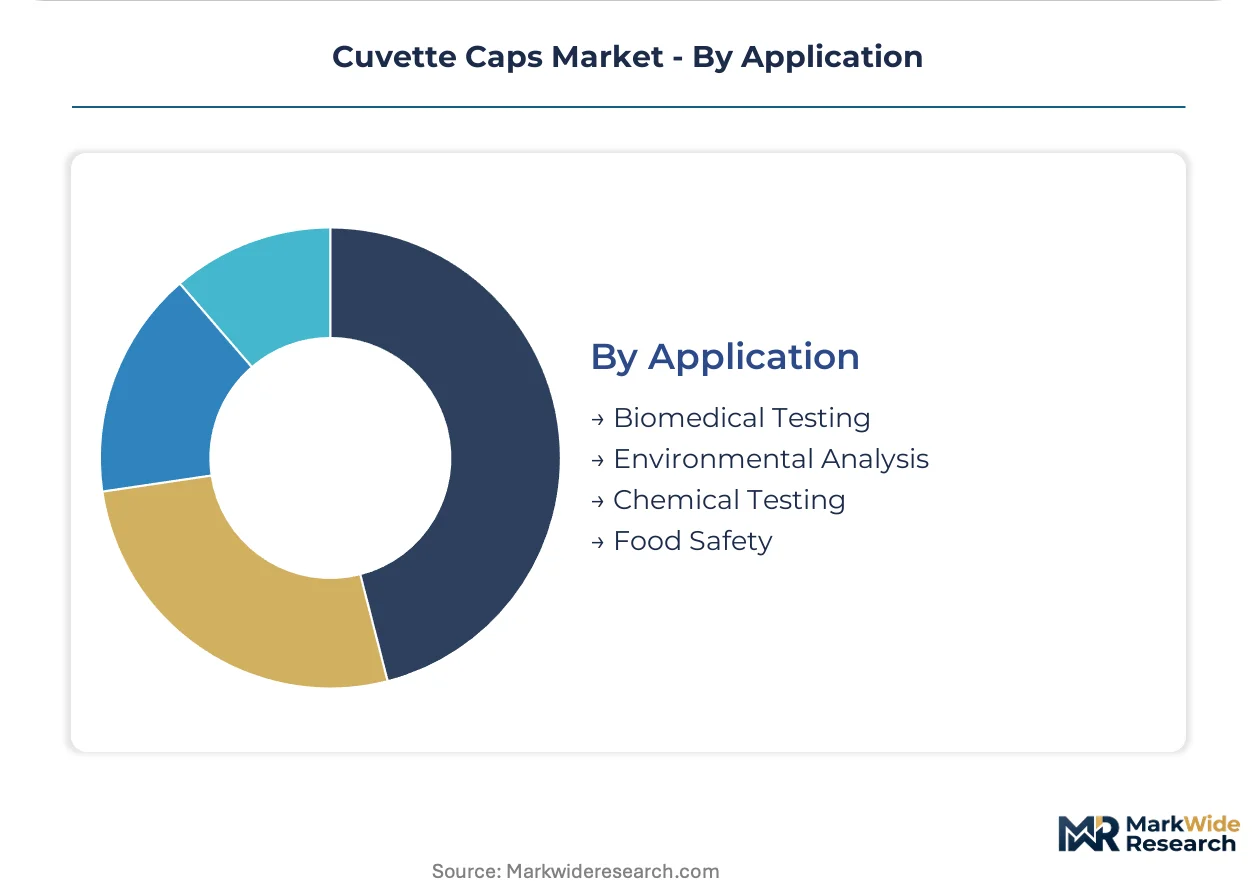
- Biomedical Testing:Highest-specification application requiring ISO 10993 biocompatibility certification and full material traceability. United States clinical diagnostic networks drive demand for sealable, pre-sterilized configurations.
- Environmental Analysis:EPA Good Laboratory Practice standards mandate contamination-control protocols for water and soil testing workflows. Sealable caps with validated closure integrity dominate this segment.
- Chemical Testing:Broad application category spanning pharmaceutical quality control and industrial process monitoring. Chemical resistance specifications vary by solvent exposure profiles, with polypropylene grades serving most routine applications.
- Food Safety:Emerging demand channel driven by pathogen detection and contaminant screening expansion. ISO 22000 food safety management standards are pulling laboratory consumable specifications toward medical-grade material documentation.
Biomedical testing anchors the volume base while food safety gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision molding specialists export optical-grade cuvette caps to United States clinical diagnostic networks, while Chinese polypropylene fabricators supply cost-optimized bundles to domestic spectrophotometer OEMs in Jiangsu and Zhejiang provinces.
United States
FDA-regulated clinical laboratories drive demand for ISO 13485-certified sealable caps as point-of-care diagnostic networks expand across decentralized healthcare systems. EPA Good Laboratory Practice standards mandate contamination-control protocols for environmental testing workflows in water and soil analysis. Boston and San Diego host dense concentrations of molecular diagnostics firms specifying zero-birefringence optical caps for high-throughput screening applications.
Germany
Baden-Württemberg precision molding capabilities anchor European supply chains for DIN-standard cuvette caps serving diagnostic OEMs and research institutions. REACH substance restrictions force reformulation of colorants and stabilizers in laboratory plastics, with full SCIP database documentation now required. Eppendorf AG and Greiner Bio-One maintain automated production lines in the region calibrated to medical device quality standards.
China
Jiangsu and Zhejiang province spectrophotometer manufacturers generate localized demand for polypropylene consumables in bundled instrument packages targeting domestic price competition. GB standards for laboratory plastics impose material traceability requirements on suppliers serving clinical diagnostic workflows. Shanghai and Suzhou host the densest concentrations of analytical instrument OEMs driving precision-molded cap procurement.
Japan
PMDA medical device regulations shape biocompatibility certification requirements for cuvette caps entering clinical diagnostic supply chains. METI industrial policy supports domestic precision polymer manufacturing for high-sensitivity fluorometry applications. Osaka and Nagoya industrial clusters specialize in optical-grade materials for ultraviolet-visible analysis workflows.
Switzerland
Swissmedic medical device standards and ISO 13485 certification requirements create supplier qualification barriers favoring established European consumable manufacturers. Basel pharmaceutical quality control laboratories specify full material documentation for cuvette caps used in drug development workflows. The country's diagnostic OEMs consolidate procurement to pre-qualified vendors with established REACH compliance portfolios.
Cuvette Caps Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply configurations. Thermo Fisher Scientific and VWR International capture disproportionate volume through bundled consumable contracts with university and government research facilities. Three strategic archetypes dominate: integrated life sciences distributors leveraging platform scale, precision molding specialists calibrated to DIN and ISO standards, and automated production operators serving European diagnostic OEMs. Competitive moves center on M&A consolidation of regional distributors and capacity expansion in polypropylene precision molding clusters.
Within the integrated distributor tier, Thermo Fisher Scientific exemplifies channel-control positioning through consolidated SKU coverage. Among German precision specialists, Eppendorf AG occupies a position calibrated to DIN standards and medical device quality systems. Greiner Bio-One represents the automated production archetype serving European diagnostic OEMs with SCIP-registered material documentation. BrandTech Scientific and Cole-Parmer sit within mid-scale specialist positions, while Corning Incorporated anchors diversified materials science positioning across laboratory consumable categories.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Eppendorf AG |
| BrandTech Scientific |
| Greiner Bio-One |
| Cole-Parmer |
| Corning Incorporated |
| Globe Scientific |
| Heathrow Scientific |
| DWK Life Sciences |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp polymer freight corridors shape cost dynamics across European cuvette cap supply chains, with containerized resin movements from Baden-Württemberg molding clusters feeding into distributor consolidation that compresses margin capture for mid-tier suppliers while enabling premium pricing for ISO 13485-certified optical grades.
Pricing Analysis
Zero-birefringence optical caps command substantial premiums over standard polypropylene closures, with sealable clinical-grade variants occupying a mid-tier position. Pricing stratifies across certification intensity, with FDA 21 CFR Part 820 compliance and ISO 13485 medical device quality systems driving tier separation, while volume scale and customization depth further differentiate quotes. Cost compression in standard research-grade caps is intensifying as Chinese polypropylene fabricators enter bundled instrument packages. Educational institutions exhibit the highest price sensitivity, whereas United States clinical diagnostic networks prioritize material traceability over unit cost.
Supply Chain Analysis
German precision molding specialists and Chinese polypropylene fabricators hold dominant contract-manufacturing capacity for cuvette caps, with automated production lines in Baden-Württemberg and Jiangsu province serving distinct tier requirements. Raw material sourcing draws from propylene monomer supply anchored in petrochemical complexes across Germany, China, and the United States, with colorant and stabilizer formulations subject to REACH substance restrictions. Single-source vulnerability concentrates in optical-grade copolymer supply chains calibrated to DIN standards. Distribution runs through integrated life sciences distributors capturing university and government research volume through bundled consumable contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across cuvette cap supply tiers as point-of-care diagnostic network proliferation creates demand niches underserved by incumbent platform distributors.
For Market Incumbents: Pre-empt margin erosion in standard polypropylene caps by securing backward integration into precision molding capacity in Baden-Württemberg or Jiangsu clusters. Accelerate ISO 10993 biocompatibility certification pipelines to defend positioning against emerging medical device consumable specialists targeting FDA-regulated clinical laboratories. For New Entrants and Emerging Players: Build out automated production capabilities serving European diagnostic OEMs with SCIP-registered REACH documentation, capturing share from consolidated procurement channels. Food safety testing laboratories represent the most penetrable end-use segment, with ISO 22000 compliance requirements creating qualification barriers favorable to nimble specialists. Direct manufacturer relationships with mid-volume research facilities bypass distributor concentration. For Investors and Strategic Acquirers: Precision molding specialists with established DIN-standard calibration and medical device quality systems present the most compelling acquisition profile for long-term viability across the projection horizon. Consolidation of regional distributors serving German and Chinese research institutions signals platform control opportunities. Watch for inflection in propylene monomer price volatility as indicator of margin compression risk for commodity-grade producers.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Pathway | Opens FDA-regulated clinical diagnostic supply chains to sealable cap configurations. |
| Automated Production Integration | Collapses unit economics for small-batch custom orders through robotic molding convergence. |
| REACH Compliance Portfolio | Enables price premium capture from risk-averse European diagnostic OEMs requiring SCIP documentation. |
| Point-of-Care Distribution Partnership | Positions pre-sterilized single-use configurations within expanding decentralized United States healthcare networks. |
| Zero-Birefringence Material Development | Displaces quartz cuvette alternatives in high-sensitivity molecular diagnostics workflows. |
Study Parameters
Initial hypotheses were tested against primary input from biomedical laboratory directors, diagnostic OEM procurement managers, polymer molding engineers, and regulatory affairs specialists, and refined through secondary validation against FDA 510(k) filings, ECHA SCIP database entries, ISO certification registries, and customs trade data for laboratory plastics. Bottom-up demand modeling across end-user segments was triangulated with top-down supply capacity assessments from precision molding clusters.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeling spanning product type, material grade, end-user channel, and application intensity. CAGRs were derived from installed base expansion rates and replacement frequency patterns calibrated to spectrophotometer OEM shipment data and clinical laboratory accreditation growth.
Stress conditions across propylene monomer price volatility, REACH substance restriction expansions, and FDA reclassification risks for diagnostic consumables were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of ISO 13485 certification timelines and spectrophotometer OEM bundled consumable contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
APAC Plastic Caps and Closures Market
Caps and Closures
United Kingdom Plastic Caps and Closures Market
Caps and Closures
US Caps and Closure Market
Caps and Closures
Nordic Plastic Caps and Closures Market
Caps and Closures
Pharmaceutical Caps and Closures Market
Caps and Closures
Elastomeric Closures Market
Caps and Closures
Dispensing Spouts Market
Caps and Closures
Crimp Top Cap Market
Caps and Closures
Brush and Dauber Caps Market
Caps and Closures
Shrink Bands Market
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
Gamma Seal Lids Market
Caps and Closures
Sterile Lids Market
Caps and Closures
Peelable Lid Stock Market
Caps and Closures
Germany Plastic Caps and Closures Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market