
 Global Steel Market | 2026-2036
Global Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Steel Market Outlook
Chinese blast furnace operators are restructuring capacity portfolios to comply with stricter emissions ceilings. ArcelorMittal leverages its European electric arc furnace network to sustain low-carbon output positioning. Nippon Steel Corporation anchors premium automotive sheet supply through integrated R&D corridors in Japan and India. HBIS Group competes on scale in long steel for infrastructure, though margin pressure from coking coal volatility persists.
Steel is an iron-carbon alloy containing 0.02% to 2.14% carbon by weight, produced through basic oxygen or electric arc furnace routes and valued for tensile strength, formability, and recyclability across load-bearing and fabrication applications. Flat steel dominates value pools through automotive and appliance-grade coated products, while long steel remains structurally embedded in construction frameworks across emerging economies. Stainless steel commands outsized margins relative to tonnage due to nickel and chromium alloying requirements and specialized end-use certification barriers.
The EU's Carbon Border Adjustment Mechanism, China's MEE emissions standards, and India's BIS quality mandates are collectively raising compliance costs for carbon-intensive integrated mills while advantaging scrap-based and hydrogen-reduced production routes. The US EPA and OSHA frameworks add facility-level environmental and workplace safety obligations that shape greenfield investment location decisions. Stakeholders must monitor regulatory arbitrage opportunities as carbon pricing asymmetries redefine competitive cost structures across producing regions.
Market Dynamics
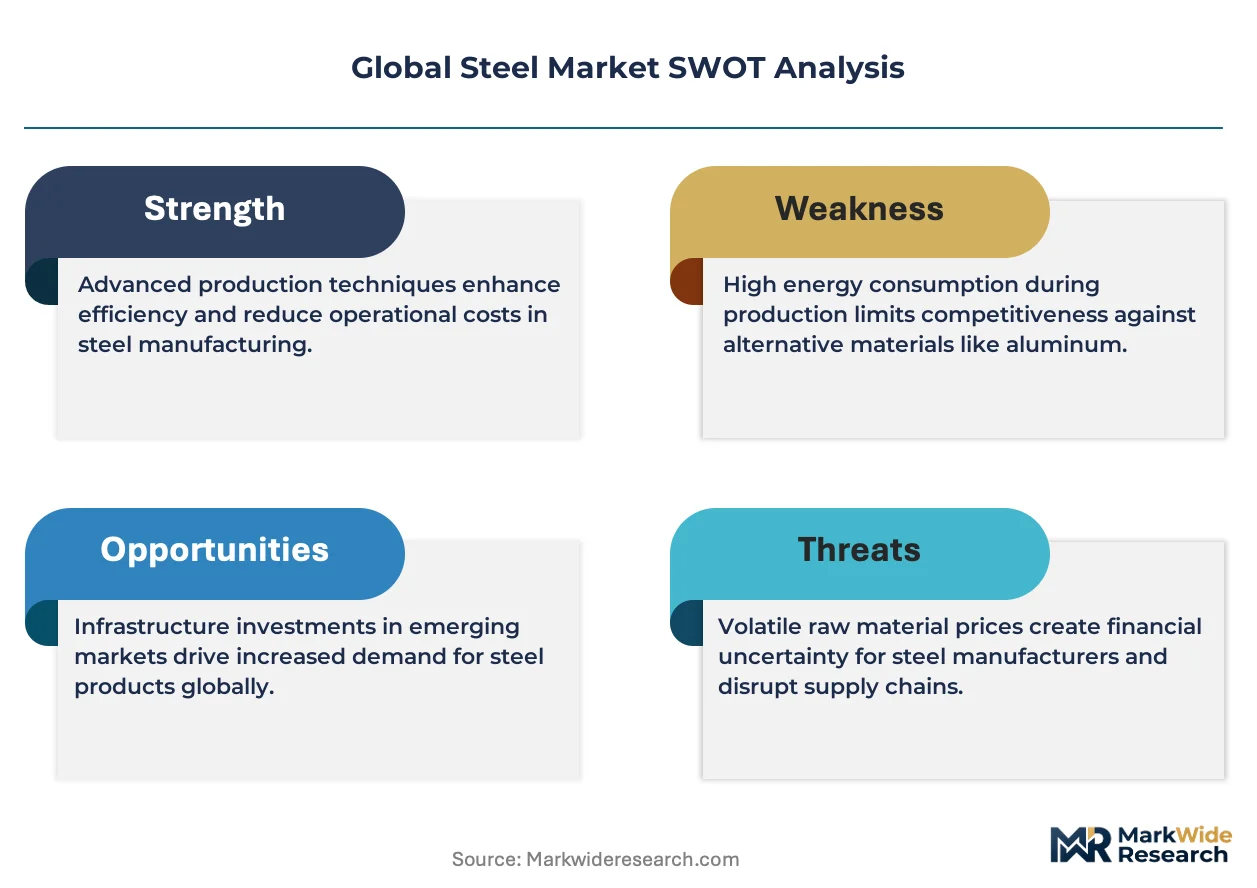
The EU's Carbon Border Adjustment Mechanism and China's MEE emissions standards are forcing integrated blast furnace operators toward electric arc furnace conversion and hydrogen-based direct reduction, fundamentally restructuring capital allocation and competitive cost curves across producing regions.
Growth Catalysts
- India's National Highway Development:The Bharatmala program and urban rail corridors in Mumbai, Delhi, and Bangalore are outpacing domestic flat steel capacity, pulling imports from Japan and South Korea.
- Green Hydrogen Direct Reduction:Pilot projects in Sweden, Germany, and Australia are proving commercial viability of hydrogen-reduced iron, with offtake agreements from automotive OEMs in Stuttgart and Wolfsburg securing premium pricing.
- REACH and RoHS Compliance Mandates:European appliance and automotive manufacturers are specifying low-embodied-carbon steel grades, creating certified supply premiums for mills with verified Scope 3 emissions data.
Market Restraints
- Coking Coal Price Volatility:Australian metallurgical coal spot markets expose integrated Chinese and Indian blast furnace operators to margin compression exceeding 15 percentage points during supply disruptions.
- Scrap Supply Concentration:The US, Turkey, and Russia control 60% of globally traded ferrous scrap, constraining electric arc furnace expansion in scrap-deficient regions like Southeast Asia and the Middle East.
- High-Strength Formability Limits:Third-generation advanced high-strength steels above 1200 MPa face springback and edge-cracking constraints that restrict adoption in complex automotive stampings.
Strategic Opportunities
- Vietnam and Indonesia Infrastructure:Power grid investments and port expansions in Hai Phong, Jakarta, and Surabaya are accelerating demand for long steel products where domestic rebar capacity remains insufficient.
- Automotive Lightweighting Mandates:CAFE standards in the US and CO2 fleet regulations in Brussels are pushing OEMs toward multi-material designs where press-hardened steel competes directly with aluminum in battery enclosure applications.
- Industrial Heat Recovery Integration:Captive power generation from blast furnace gas and coke oven gas is absorbing investment in Taizhou and Tangshan, converting waste heat into electrolytic hydrogen feedstock for direct reduction pilots.
Industry Challenges
- Electric Arc Furnace Metallurgy Expertise:The shift from integrated to scrap-based production requires retraining furnace operators in slag chemistry, residual element control, and nitrogen management that legacy blast furnace workforces lack.
- Scope 3 Certification Complexity:Automotive and construction buyers in Germany and Japan are demanding ISO 14064-compliant carbon accounting across multi-tier supplier networks, creating audit bottlenecks for mills without digitized procurement systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Steel Market |
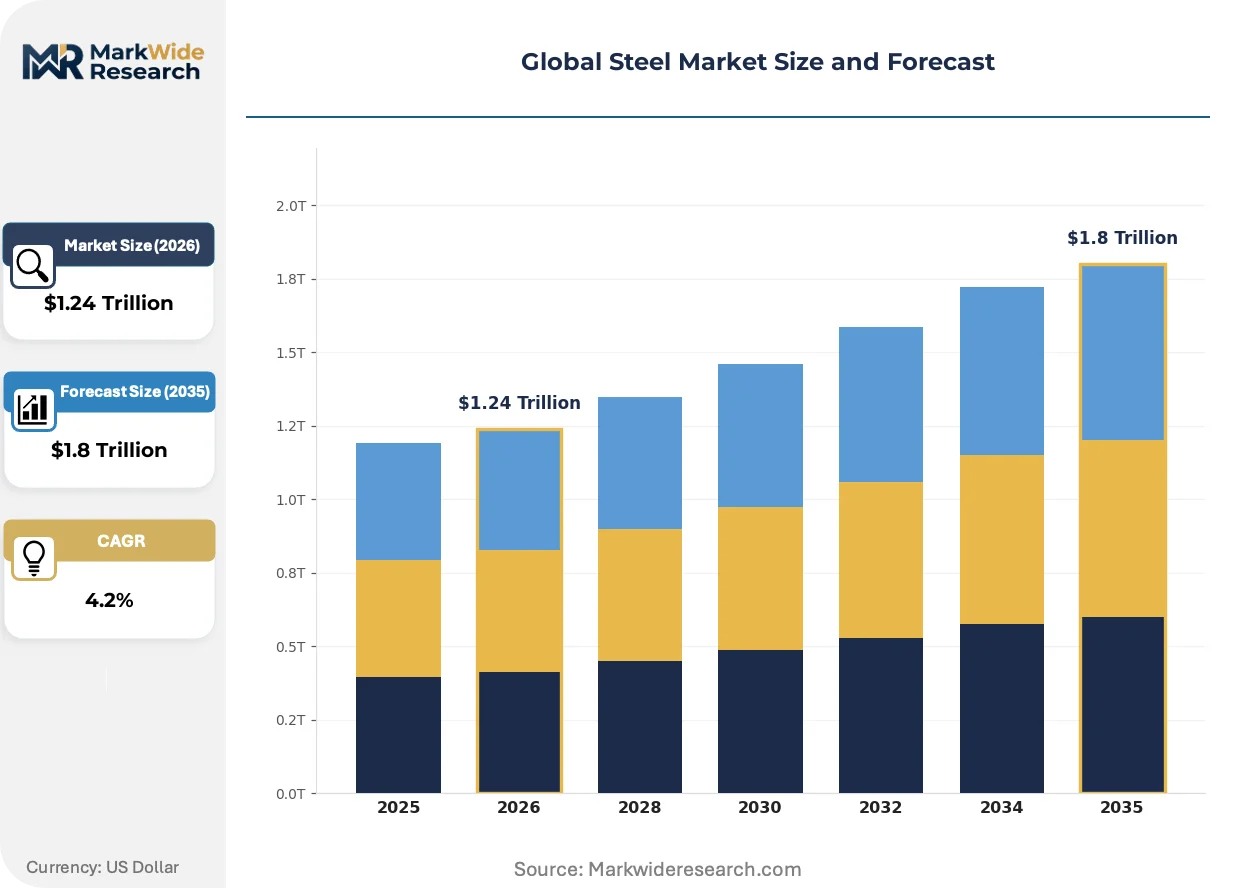
| Market Size in 2026 | $1.24 Trillion |
| Market Size in 2035 | $1.8 Trillion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Steel, Long Steel, Reinforcing Steel, Tool Steel Application: Construction, Automotive, Shipbuilding, Machinery End User: Manufacturers, Contractors, Exporters, Retailers Grade: Carbon Steel, Alloy Steel, Stainless Steel, Others |
| Companies Covered | China Baowu Group, ArcelorMittal, Ansteel Group, Nippon Steel Corporation, HBIS Group, Shagang Group, Jianlong Group, POSCO Holdings, Tata Steel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Steel Market Strategic Shifts
Decarbonization mandates are compressing technology adoption cycles from decades to single-digit years, forcing simultaneous investment in hydrogen infrastructure, scrap processing, and carbon capture across incompatible metallurgical pathways.
Hydrogen-based direct reduction is absorbing capital flows that previously targeted blast furnace relines, with pilot plants in Lulea and Hamburg demonstrating 90% emissions reductions when paired with renewable electrolysis. Automotive stampers in Bavaria and Baden-Wurttemberg are qualifying these grades for body-in-white applications ahead of 2030 fleet CO2 deadlines. The technology is absorbing market share from conventional hot briquetted iron in premium contract negotiations where Scope 3 emissions determine supplier selection.
The EU Carbon Border Adjustment Mechanism phases in reporting requirements during 2026-2034, exposing imported steel to tariffs matching domestic carbon prices. Turkish and Indian exporters to Rotterdam and Antwerp are accelerating electric arc furnace investments to preserve access. Long steel products face the steepest compliance cost escalation due to higher embedded emissions in billet and rebar supply chains.
Automotive OEMs in Stuttgart, Munich, and Detroit are unbundling steel procurement from tier-one stamping contracts, establishing direct mill relationships for certified low-carbon grades. Tier-one suppliers in Ontario and Lower Saxony are responding by consolidating stamping footprints and surrendering material sourcing autonomy. This pattern is most visible in battery enclosure programs where OEMs specify exact chemistries and carbon intensities.
Global Steel Market Segmentation
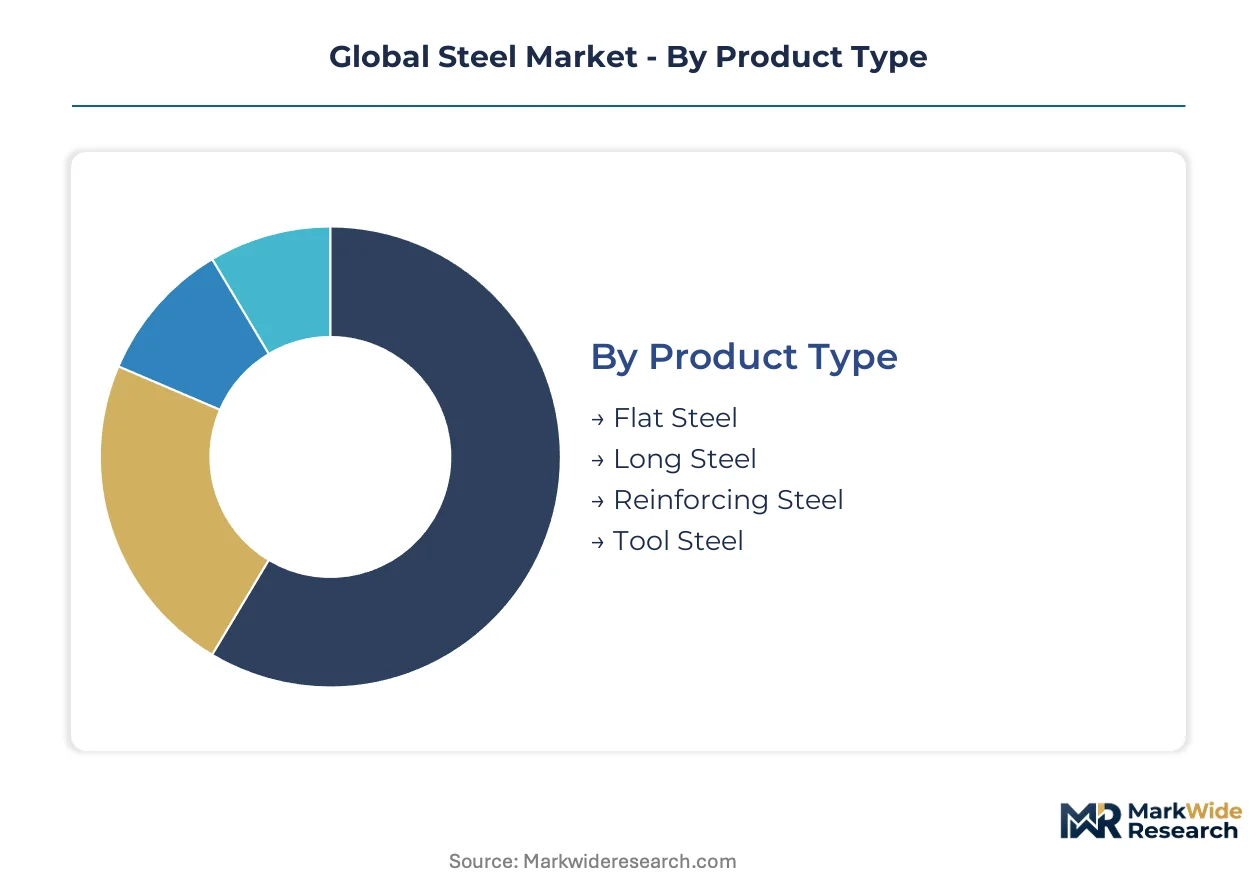
Steel procurement decisions pivot on mechanical specifications, regulatory compliance burdens, and end-use certification requirements. Each segmentation dimension reveals distinct margin pools and competitive barriers that reshape supplier selection criteria across construction, automotive, and industrial fabrication value chains.
Product Type:
Buyers prioritize formability, surface quality, and dimensional tolerance based on downstream processing intensity and final application stress requirements.
- Flat Steel:Hot-rolled and cold-rolled coils and sheets deliver superior surface finish and tight thickness tolerances for automotive body panels and appliance exteriors. Demand concentrates in Stuttgart and Wolfsburg where OEMs specify press-hardened grades for battery enclosures under tightening fleet CO2 mandates.
- Long Steel:Structural sections, rails, and bars provide load-bearing capacity in high-rise frameworks and bridge spans. Consumption accelerates in Mumbai, Delhi, and Bangalore where urban rail corridors and highway viaducts outpace domestic rebar mill capacity.
- Reinforcing Steel:Deformed bars and mesh strengthen concrete infrastructure against tensile failure. Hai Phong and Jakarta port expansions absorb tonnage where seismic-grade specifications exceed local mill certification levels.
- Tool Steel:High-carbon and tungsten-alloyed grades retain hardness under cutting and forming stresses. German automotive stamping toolrooms specify vacuum-degassed grades for die longevity in high-volume production runs.
Volume sits with Flat Steel; growth tilts toward Long Steel.
Application:
End-use specifications determine grade selection, with certification barriers and performance warranties driving supplier consolidation in safety-critical deployments.
- Construction:Structural frameworks, foundation piles, and facade systems demand weldable grades with verified Charpy impact values. India's Bharatmala highway program pulls imported H-beams from Japanese integrated mills.
- Automotive:Body-in-white stampings, chassis components, and crash structures require complex phase microstructures for strength-ductility balance. Bavarian OEMs qualify hydrogen-reduced direct reduction grades ahead of Scope 3 reporting deadlines.
- Shipbuilding:Hull plates, tanker bulkheads, and offshore platform modules specify TMCP-rolled grades for low-temperature toughness. South Korean yards in Ulsan and Geoje consolidate procurement around mills with Lloyd's and DNV certification.
- Machinery:Gear blanks, shaft forgings, and hydraulic cylinder barrels prioritize machinability and fatigue resistance. German mechanical engineering clusters specify quenched-and-tempered grades from integrated producers with in-house heat treatment.
Construction commands current tonnage; automotive exhibits the steepest expansion trajectory as lightweighting mandates intensify.
End User:
Procurement scale and technical sophistication determine contract structures, with large manufacturers extracting carbon accounting commitments unavailable to fragmented buyer pools.
- Manufacturers:Automotive OEMs, appliance producers, and industrial equipment builders specify exact chemistries and certified carbon intensities. Direct mill relationships are displacing tier-one distributor arrangements in battery enclosure programs.
- Contractors:Construction firms and engineering-procurement-construction consortia purchase standard grades through regional distributors with just-in-time delivery guarantees. Working capital constraints favor consignment inventory arrangements.
- Exporters:Trading houses and steel service centers arbitrage regional price differentials and currency movements. Turkish mills leverage scrap-based cost advantages to preserve Rotterdam and Antwerp access under CBAM phase-in.
- Retailers:Hardware chains and metal service centers stock standard sections and merchant bars for small-lot fabrication customers. Inventory turns depend on local construction permit issuance velocity.
Manufacturers anchor value capture; exporters face margin compression from carbon border compliance costs.
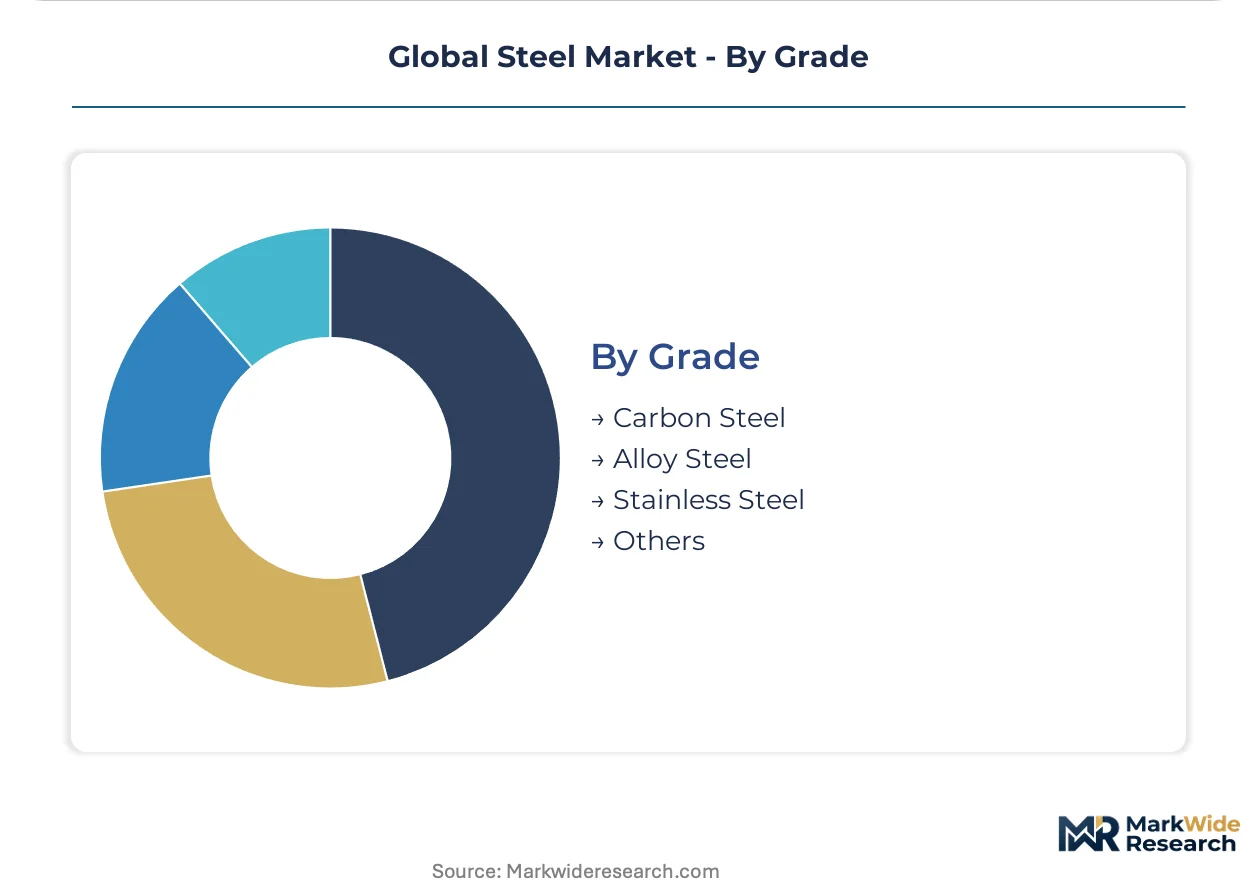
Grade:
Alloying content and processing history determine performance envelopes, with premium grades commanding outsized margins relative to raw material input costs.
- Carbon Steel:Unalloyed grades with carbon content below 2% serve general structural and fabrication applications. Chinese blast furnace operators restructure capacity portfolios to comply with MEE emissions ceilings.
- Alloy Steel:Chromium, molybdenum, and nickel additions enhance hardenability and creep resistance for power generation and aerospace components. German turbine manufacturers specify vacuum-arc-remelted grades for rotating machinery.
- Stainless Steel:Minimum 10.5% chromium content delivers corrosion resistance for chemical processing, medical devices, and food equipment. Nickel price volatility compresses margins for austenitic grades in European appliance applications.
- Others:Electrical steels, weathering grades, and proprietary high-performance alloys serve transformer cores, bridge construction, and extreme-environment applications. Niche tonnage attracts specialist mini-mill operators with dedicated melt shop configurations.
Carbon Steel dominates volume throughput; stainless steel generates the highest margin per shipped ton.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iron ore deposits in Western Australia and coking coal seams in Queensland anchor Asia-Pacific raw material flows. Chinese blast furnace operators source Pilbara fines while Japanese integrated mills depend on Gladstone metallurgical coal exports.
China
Shanghai and Tangshan steel corridors consume seaborne iron ore for blast furnace feedstock. MEE emissions ceilings force capacity consolidation toward electric arc furnace conversion in Taizhou. Hydrogen direct reduction pilots in Hebei province absorb capital previously allocated to relines.
India
Bharatmala highway construction and Mumbai-Delhi-Bangalore urban rail corridors outpace domestic flat steel capacity. BIS quality mandates raise import barriers for non-certified billet and rebar. Jamshedpur and Bhilai integrated complexes anchor automotive sheet supply for OEM qualification programs.
Japan
Kansai and Chubu industrial clusters demand premium automotive grades for export-oriented assembly plants. METI carbon neutrality roadmaps accelerate hydrogen-reduced iron partnerships with Australian miners. Nagoya steel service centers specialize in press-hardened coil processing for hybrid vehicle platforms.
Germany
Ruhr Valley and Bremen electric arc furnace networks supply low-carbon flat products under EU Carbon Border Adjustment Mechanism phase-in. REACH and RoHS compliance mandates from Stuttgart OEMs specify Scope 3-certified grades. Hamburg hosts hydrogen direct reduction pilots with offtake agreements from Wolfsburg automakers.
South Korea
Ulsan and Geoje shipbuilding yards consolidate procurement around TMCP-rolled plate with Lloyd's certification. POSCO's integrated Pohang complex feeds Gwangju automotive stamping clusters for battery enclosure programs. KOSHA workplace safety frameworks shape greenfield investment location decisions alongside carbon intensity targets.
Global Steel Market Competitive Environment
Global majors compete with regional champions across technology licensing and green hydrogen partnerships. The vendor base stratifies into three tiers: Chinese state-owned enterprises with blast furnace scale, European and Japanese integrated mills with electric arc furnace low-carbon positioning, and Indian and Turkish regional champions with scrap-based cost advantages. Strategic moves concentrate on M&A for hydrogen reduction technology access and capacity expansion in India and Southeast Asia.
Among Chinese state-owned producers, China Baowu Group and Ansteel Group occupy positions defined by government-mandated capacity consolidation and emissions compliance restructuring. ArcelorMittal anchors the European low-carbon tier through electric arc furnace network scale, while Nippon Steel Corporation represents Japanese integrated mill positioning in premium automotive sheet supply chains. HBIS Group exemplifies the long steel infrastructure specialist archetype serving domestic construction demand.
| Leading Market Players |
|---|
| China Baowu Group |
| ArcelorMittal |
| Ansteel Group |
| Nippon Steel Corporation |
| HBIS Group |
| Shagang Group |
| Jianlong Group |
| POSCO Holdings |
| Tata Steel Group |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed Chinese producers anchor seaborne iron ore procurement through long-term offtake agreements with Australian miners, creating pricing discipline that resists spot-market volatility while concentrating supply leverage in state-coordinated purchasing pools. This ownership structure compresses margin capture for merchant traders and forces private mills toward scrap-based alternatives or bilateral raw material partnerships.
Pricing Analysis
Carbon-intensity certification bundling separates premium contract tiers from standard merchant grades, with Scope 3-verified hydrogen-reduced iron commanding substantial uplifts in Stuttgart and Wolfsburg automotive negotiations. Price differentiation rests on emissions audit documentation and renewable energy sourcing verification rather than traditional mechanical specifications alone. Cost compression in blast furnace-derived flat products is intensifying because EU Carbon Border Adjustment Mechanism phase-in exposes imported tonnage to tariff equivalence with domestic carbon prices. Tier-one automotive OEMs exhibit lowest price sensitivity, prioritizing supply security and certification compliance over unit cost, while regional construction contractors remain most responsive to spot price movements.
Supply Chain Analysis
Skilled furnace operator shortages in Taizhou and Tangshan constrain electric arc furnace conversion timelines, forcing reliance on legacy blast furnace capacity despite emissions compliance penalties. Raw material flows draw from Western Australian iron ore deposits, Queensland metallurgical coal seams, and concentrated US-Turkish-Russian ferrous scrap pools. Single-source vulnerability pervades seaborne iron ore lanes through the Strait of Malacca, where concentrated shipping routes expose just-in-time blast furnace feedstock deliveries to geopolitical disruption. Distribution runs through integrated mill direct sales for large automotive accounts, with regional service centers and trading houses handling fragmented construction-sector procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Steel Market operates as a cost-of-compliance arena where EU Carbon Border Adjustment Mechanism implementation erects formidable capital barriers, entrenching early movers with certified low-carbon capacity while marginalizing carbon-intensive integrated producers unable to fund conversion.
For Market Incumbents: Anchor defensive positioning through captive hydrogen supply agreements and electric arc furnace network consolidation in Rotterdam-Antwerp corridor markets. Accelerate Scope 3 certification digitization to preempt audit bottlenecks threatening German and Japanese automotive supply relationships. Threat substitution from aluminum battery enclosure solutions demands press-hardened steel R&D investment to preserve lightweighting relevance. For New Entrants and Emerging Players: Capture white-space opportunity in Vietnamese and Indonesian long steel markets where domestic rebar capacity lags power grid and port expansion demand. Target scrap-deficient Southeast Asia through billet import-to-rolling strategies that circumvent ferrous scrap supply concentration. Go-to-market leverage rests on BIS-quality-mandate compliance for Indian infrastructure qualification. For Investors and Strategic Acquirers: Distressed-cycle entries favor European electric arc furnace specialists with verified renewable power sourcing and established automotive OEM direct relationships. Long-term viability over the coming decade hinges on hydrogen reduction technology access and coastal logistics positioning for import-export arbitrage. Watch hydrogen electrolyzer cost curves as inflection signal for direct reduction economics breakeven.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Arc Furnace Conversion | MEE emissions ceilings in China force asset restructuring toward scrap-based production routes. |
| Hydrogen Direct Reduction Partnership | Automotive OEMs in Stuttgart specify hydrogen-reduced iron grades ahead of fleet CO2 deadlines. |
| Scope 3 Certification Digitization | ISO 14064-compliant carbon accounting prevents supplier disqualification from German procurement. |
| Scrap Processing Infrastructure | Turkish mills leverage ferrous scrap cost advantages to preserve Rotterdam access under CBAM. |
| Automotive Sheet Qualification Program | Jamshedpur and Bhilai integrated complexes anchor battery enclosure supply for OEM platforms. |
Study Parameters
Multi-period observation of blast furnace operating rates, electric arc furnace capacity additions, and carbon border compliance cost trajectories anchored the trend analysis, supplemented by interviews with integrated mill procurement directors, electric arc furnace operations managers, automotive OEM platform engineers, and ferrous scrap trading specialists. Secondary validation drew from customs trade databases, SEC filings of listed steel producers, IEA steel sector decarbonization reports, and EU Carbon Border Adjustment Mechanism implementation guidance documents. Bottom-up project pipeline assessment triangulated against top-down macroeconomic demand modeling for construction and automotive end-use.
Segment-weighting across product type, application, end user, and grade dimensions calibrated volume and value distributions throughout the projection horizon. CAGRs derived from elasticity-adjusted demand functions incorporating infrastructure spend correlations, vehicle production forecasts, and regulatory compliance cost pass-through assumptions. Industry-specific inputs included hydrogen direct reduction pilot capacity timelines, scrap availability forecasts by region, and automotive lightweighting content-per-vehicle trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hydrogen electrolyzer cost reduction velocity, carbon pricing policy divergence across producing regions, and coking coal supply disruption frequency. Material deviation in these triggers warrants pause and re-evaluation of capacity expansion and technology investment commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Aluminum Extruded Products Market
Metals
Global Duplex Stainless Steel Market
Metals
Ferro Aluminum Market
Metals
Qatar Metalworking Market
Metals
Rolled Steel Motor Market
Metals
Medium Carbon Steel Market
Metals
Global Copper Sputtering Target Market
Metals
Crude Steel Market
Metals
Metal Injection Molding (Mim) Powders Market
Metals
Global Ultra-Low Alpha Metal Market
Metals
Metallurgical Coal Market
Metals
US and Mexico Stainless Steel Market
Metals
Aluminum Powders Pastes and Flakes Market
Metals
Metal Alloys Market
Metals
Platinum Group Metals Market
Metals
Russia Metal Fabrication Market