
 Titanium Sponge Market | 2026-2036
Titanium Sponge Market Size, Share, and Industry Trends Forecast 2026-2036
Titanium Sponge Market Outlook
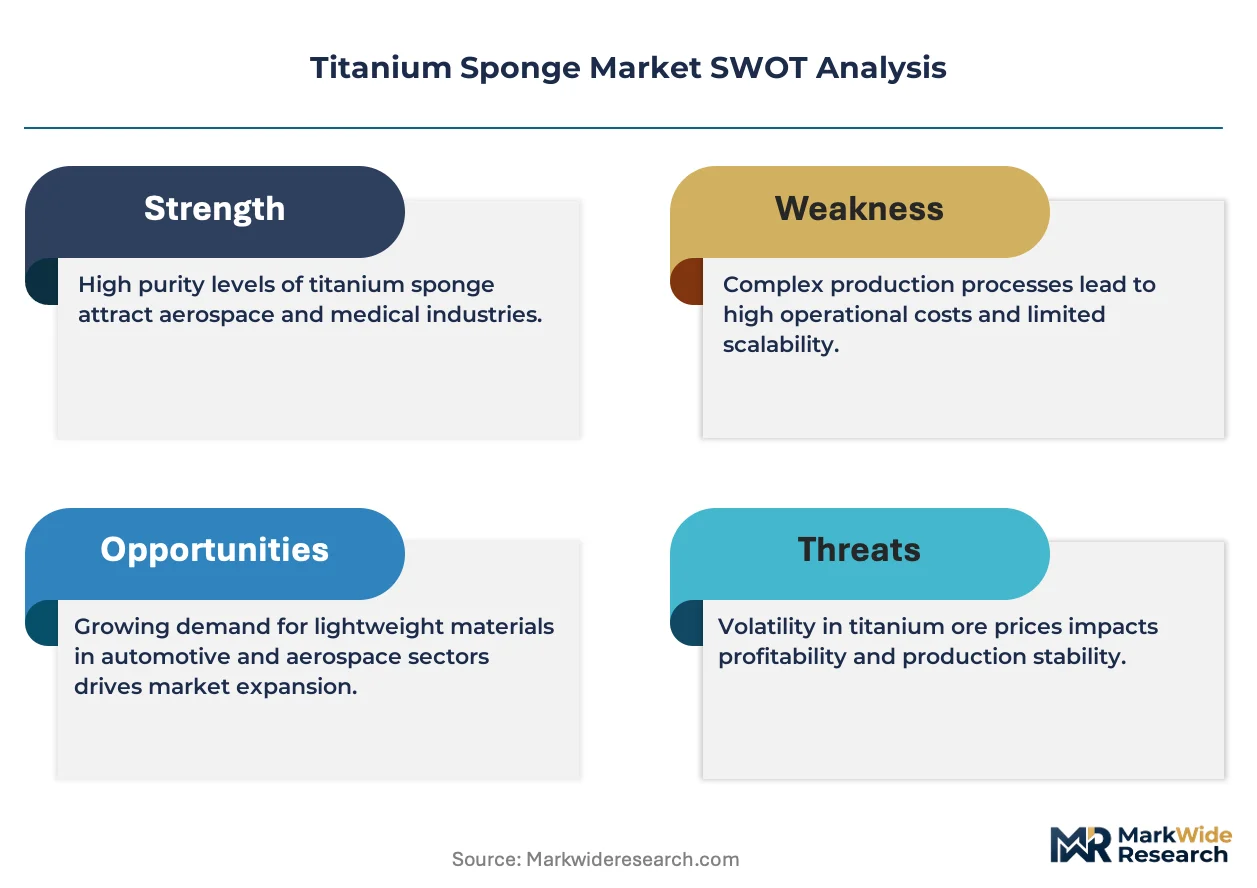
Electrolytic reduction pathways for titanium metal production is fragmenting the traditional Kroll process monopoly across primary supply chains. VSMPO-AVISMA Corporation anchors Russian titanium sponge output through captive ilmenite-to-sponge verticality. Toho Titanium Co., Ltd. dominates high-purity aerospace-grade production with proprietary molten salt technologies. ATI Metals differentiates through integrated forging and rolling downstream from sponge feedstock.
Titanium sponge is a porous, metallic titanium product produced by reducing titanium tetrachloride with magnesium or sodium, typically yielding purity levels from 99.5% to 99.8% Ti and serving as the essential feedstock for mill products and titanium alloys. The Kroll Process still occupies the bulk of commercial output despite energy intensity exceeding 30 kWh per kilogram, while Hunter Process variants sustain niche medical-grade streams where sodium-reduced microstructures command specification premiums. Aerospace Grade product types lead absolute volume due to airframe and engine OEM qualification requirements, though Low-Alpha variants for semiconductor sputtering targets represent the fastest margin pool expansion. Medical Device Producers among end users are concentrating procurement around certified low-oxygen lots for orthopedic implant stock.
Japan's METI enforces JIS H 2151 standards for sponge chemistry and morphology, while China's SAMR administers GB/T 2524 revisions that tighten interstitial element limits for aerospace qualification. The EU REACH framework and ECHA substance evaluations are restricting certain chlorination byproduct classifications, forcing European traders to document full process chain compliance. Stakeholders must monitor electrolytic titanium breakthrough timelines and pre-qualify alternative sponge sources before incumbent process economics shift.
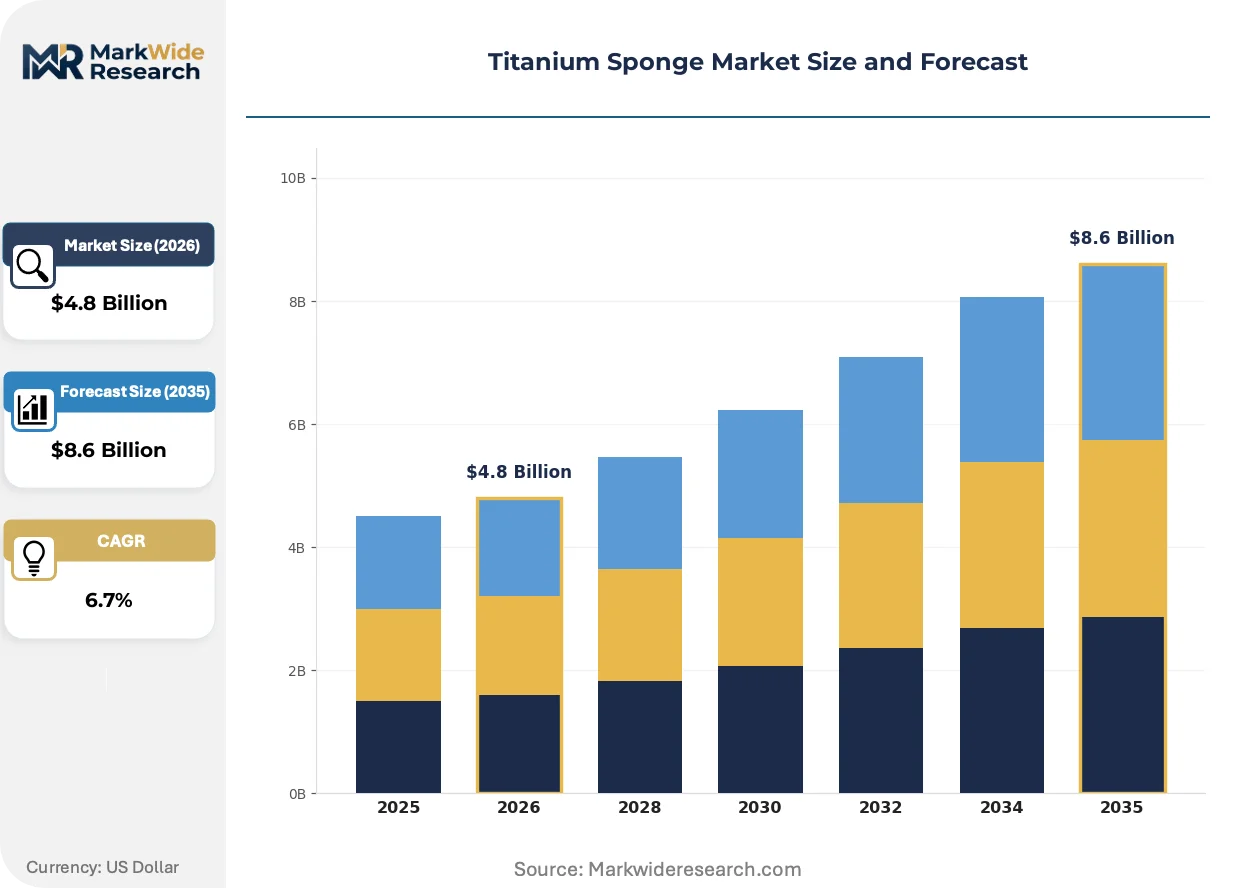
Market Dynamics
Electrolytic reduction technologies are fragmenting the Kroll process monopoly that has governed titanium sponge production for seven decades, forcing incumbent producers to reengineer energy-intensive chlorination and reduction stages while aerospace OEMs accelerate qualification of alternative feedstock sources.
Growth Catalysts
- Aerospace OEM Procurement:Next-generation airframe programs at Boeing and Airbus are expanding titanium alloy specifications, pulling sponge demand toward higher-purity grades with tighter interstitial limits.
- China's Dual Carbon Goals:Beijing's emissions reduction mandates are accelerating electrolytic reduction pilot investments, creating regulatory pressure for process modernization across domestic sponge capacity.
- GB/T 2524 Revisions:China's SAMR has tightened aerospace qualification standards, compelling producers to upgrade morphology control and oxygen content specifications to access civil aviation supply chains.
Market Restraints
- Magnesium Price Volatility:The Kroll process remains dependent on magnesium reductant, exposing margin structures to commodity swings in Chinese magnesium smelter output.
- Russian Supply Concentration:VSMPO-AVISMA's captive ilmenite-to-sponge verticality concentrates aerospace-grade availability in a single geography, amplifying sanctions and logistics disruption exposure.
- Energy Intensity Floor:Commercial electrolytic routes have yet to achieve consistent 99.7%+ purity at scale, trapping volume in thermally intensive reduction methods.
Strategic Opportunities
- Semiconductor Sputtering Targets:Low-alpha titanium sponge for PVD applications commands specification premiums, with Japanese and Korean wafer fabs expanding qualification programs.
- Medical Device Certification:Orthopedic implant producers are consolidating procurement around ASTM F67 and F136 certified lots, creating margin pools for oxygen-controlled sponge segregation.
- EU REACH Compliance Services:European traders lacking full chlorination byproduct documentation face market exclusion, opening advisory and certification revenue streams for process audit specialists.
Industry Challenges
- Molten Salt Electrochemistry Talent:Electrolytic reduction scale-up requires specialized electrochemical engineers familiar with high-temperature chloride systems, a skill set concentrated in Japanese national laboratories and Toho Titanium's Osaka operations.
- Aerospace Qualification Timelines:OEM sponge source approvals require 18-36 month metallurgical validation cycles, compressing competitive response windows for new process entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Titanium Sponge Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Low-Alpha, High-Alpha, Aerospace Grade Application: Aerospace, Medical, Automotive, Industrial End User: Manufacturers, Research Institutions, Aerospace Companies, Medical Device Producers Production Method: Kroll Process, Hunter Process, Calcium Reduction, Others |
| Companies Covered | Pangang Group Vanadium & Titanium Resources Co., Ltd., ATI Metals, Toho Titanium Co., Ltd., Kobe Steel, Ltd., Titanium Metals Corporation, OSAKA Titanium Technologies Co., Ltd., Zunyi Titanium Co., Ltd., Advanced Metallurgical Group N.V., VSMPO-AVISMA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Titanium Sponge Market Strategic Shifts
Process chemistry breakthroughs and end-use specification tightening are converging to reshape competitive positioning across the titanium sponge value chain, with electrolytic routes challenging incumbent thermochemical economics.
Direct electrolytic reduction of titanium dioxide in molten calcium chloride is virtualizing the traditional Kroll process architecture by eliminating chlorination and magnesium reduction stages entirely. Cambridge University spinouts and Japanese consortia are piloting 500-tonne annual cell designs. Aerospace tier-one suppliers are pre-qualifying electrolytic sponge lots for non-critical airframe applications, compressing the timeline for process substitution.
Japan's METI has revised JIS H 2151 morphology standards to accommodate electrolytic sponge microstructures, creating regulatory space for alternative production methods. The revision mandates equivalent hydrogen and nitrogen limits while relaxing grain structure descriptors. Korean and Chinese aerospace qualification bodies are tracking METI precedent, with SAMR indicating potential GB/T 2524 alignment within the current standards cycle.
Long-term offtake contracting is displacing spot market transactions as the dominant procurement mode among aerospace mill product producers. Tier-one titanium alloy forgers are locking three-to-five-year sponge supply agreements with fixed-grade, escalating-price structures. This pattern concentrates most visibly in Japan's Osaka-Hyogo manufacturing cluster, where Toho Titanium and Kobe Steel coordinate qualification-aligned procurement schedules.
Titanium Sponge Market Segmentation
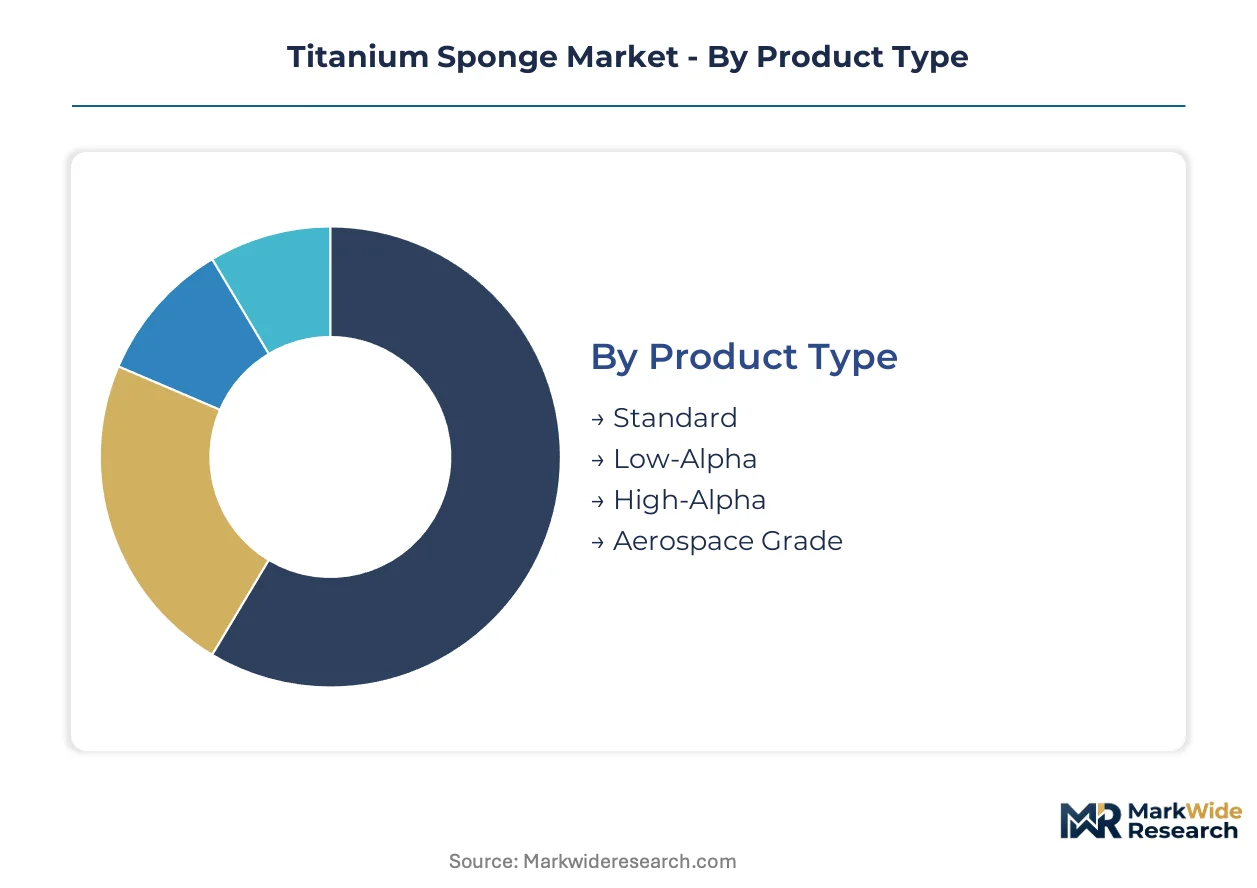
Titanium sponge segmentation reflects divergent purity thresholds across end-use specifications. Aerospace OEMs impose the tightest interstitial limits, while industrial buyers prioritize volume economics over morphology control.
Product Type:
Purity gradients map directly to qualification barriers and margin capture across the use-case spectrum.
- Aerospace Grade:Sponge meeting 99.7%+ titanium content with oxygen below 0.12% and nitrogen under 0.03%. Boeing and Airbus mill product suppliers in Japan's Osaka-Hyogo cluster concentrate procurement here, driven by airframe OEM metallurgical validation cycles.
- Low-Alpha:Ultra-low uranium and thorium content below 10 ppb for semiconductor sputtering target applications. Korean wafer fabs and Japanese PVD equipment makers are expanding qualification programs, drawn by specification premiums in advanced node manufacturing.
- Standard:General-purpose sponge at 99.5-99.6% purity serving industrial chemical and pigment feedstock demand.
- High-Alpha:Elevated alpha-phase stability variants for specialized alloy formulations in defense applications.
The dominant share belongs to Aerospace Grade, while Low-Alpha is closing the gap fastest.
Application:
Cost tier stratification separates qualification-intensive segments from commodity flows.
- Aerospace:Airframe structures and engine components consume the highest-purity sponge grades, with titanium alloy forgers locking long-term offtake agreements to secure metallurgical consistency.
- Medical:Orthopedic implant producers concentrate procurement around ASTM F67 and F136 certified lots, creating margin pools for oxygen-controlled sponge segregation.
- Industrial:Chemical processing equipment and desalination plant fabricators drive volume demand at lower purity specifications.
- Automotive:Exhaust systems and valve train components represent emerging demand from European and Japanese powertrain specialists.
Aerospace commands the premium tier, though Medical is expanding its value contribution most rapidly.
End User:
Customer type determines procurement modality and contract structure across the value chain.
- Manufacturers:Mill product producers and alloy forgers dominate absolute volume, with three-to-five-year fixed-grade supply agreements displacing spot transactions.
- Medical Device Producers:Implant specialists consolidate sourcing around certified low-oxygen lots, with procurement teams embedding directly at sponge producers for lot segregation.
- Aerospace Companies:Tier-one airframe and engine OEMs enforce 18-36 month qualification timelines, compressing competitive response windows for new process entrants.
- Research Institutions:National laboratories and university consortia pilot electrolytic reduction scale-up, accessing small-batch specialty grades for process development.
Manufacturers absorb the largest volume share, yet Medical Device Producers are deepening their supply chain influence fastest.
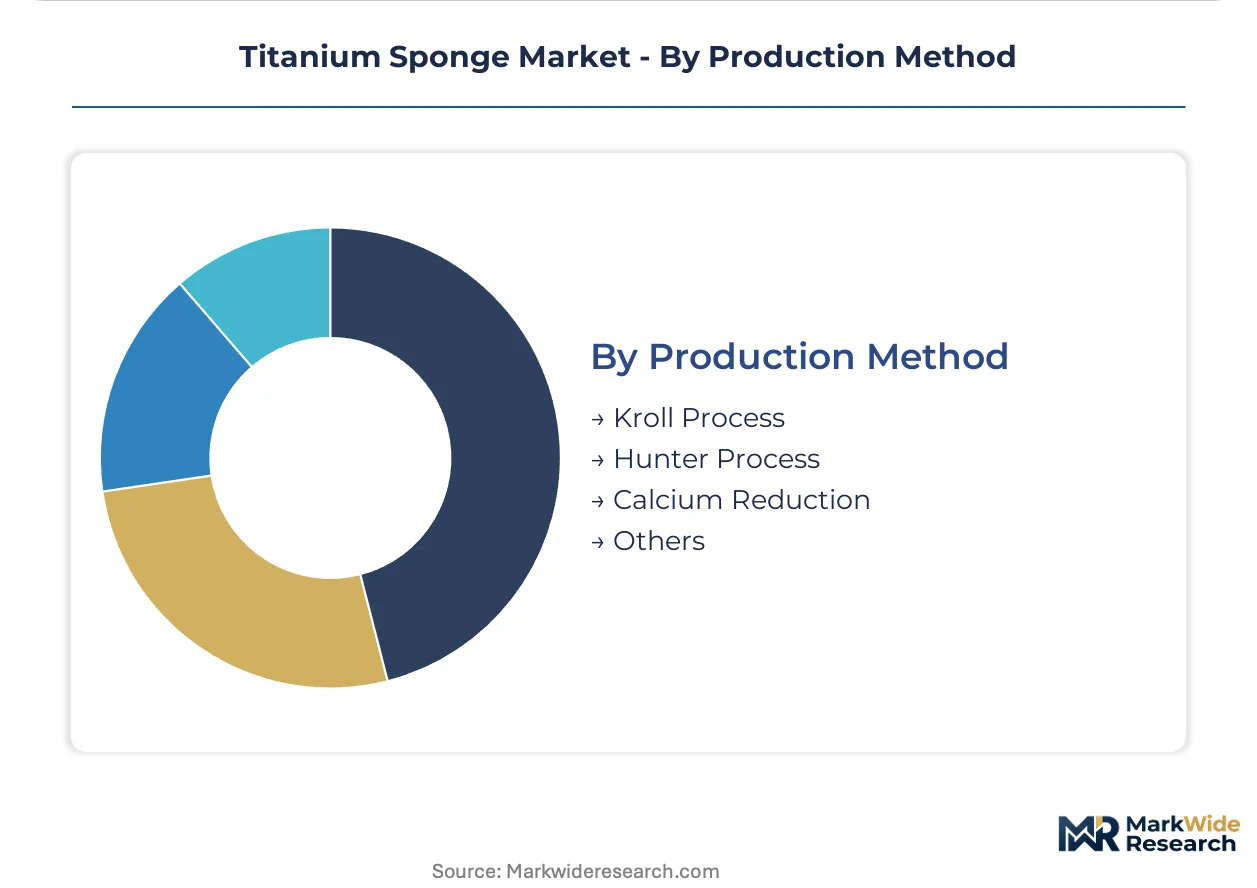
Production Method:
Technology maturity and energy intensity define competitive positioning across process alternatives.
- Kroll Process:Magnesium reduction of titanium tetrachloride remains the commercial standard despite energy intensity exceeding 30 kWh per kilogram, trapping incumbent producers in thermally intensive operations.
- Electrolytic Reduction:Direct electrochemical reduction of titanium dioxide in molten calcium chloride eliminates chlorination stages entirely, with Cambridge University spinouts and Japanese consortia piloting 500-tonne annual cell designs.
- Hunter Process:Sodium reduction variants sustain niche medical-grade streams where sodium-reduced microstructures command specification premiums.
- Calcium Reduction:Emerging thermochemical routes target intermediate purity segments with reduced reductant cost exposure.
Kroll Process capacity retains the dominant installed base, while Electrolytic Reduction is gaining technical credibility fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russian titanium sponge exports through VSMPO-AVISMA Corporation flow primarily to European aerospace tier-one suppliers and US mill product producers, creating a trade corridor now exposed to sanctions-driven supply restructuring.
United States
Boeing and Lockheed Martin airframe programs drive titanium alloy procurement from domestic forgers. FAA certification standards enforce stringent sponge source documentation. ATI Metals anchors integrated production across western Pennsylvania and Texas operations.
Japan
Commercial aviation OEM supply chains concentrate procurement in high-purity aerospace grades. METI administers JIS H 2151 revisions that accommodate electrolytic sponge microstructures. Toho Titanium and Osaka Titanium Technologies coordinate output from the Osaka-Hyogo manufacturing cluster.
China
Commercial aircraft programs at COMAC expand domestic titanium specifications. SAMR enforces GB/T 2524 standards that tighten interstitial element limits for civil aviation qualification. Sichuan and Guizhou provinces host Pangang Group and Zunyi Titanium reduction capacity.
Russia
VSMPO-AVISMA's captive ilmenite-to-sponge verticality supplies aerospace-grade material to European and Asian mill product producers. Export licensing now faces EU and US sanctions complications. The Sverdlovsk region concentration amplifies logistics disruption exposure.
United Kingdom
Rolls-Royce engine component forgers source certified sponge lots for aerofoil and disc applications. ECHA REACH evaluations restrict certain chlorination byproduct classifications. Midlands-based alloy producers are pre-qualifying alternative electrolytic feedstock sources.
Titanium Sponge Market Competitive Environment
On the supply side, the industry is bifurcated between incumbent thermochemical producers and emerging electrolytic technology developers. Consolidation characterizes aerospace-grade supply, where long qualification timelines protect established positions. Three archetypes dominate: integrated miners-to-sponge operators, specialty high-purity refiners, and downstream alloy forgers with captive sponge sourcing. Capacity expansion and strategic partnerships represent the dominant competitive moves, with electrolytic consortia seeking aerospace pre-qualification and incumbent Kroll operators locking long-term offtake agreements.
Among Japanese high-purity specialists, Toho Titanium Co., Ltd. and OSAKA Titanium Technologies Co., Ltd. exemplify the specialty refiner archetype through their concentration in the Osaka-Hyogo cluster. ATI Metals represents the integrated downstream model, spanning sponge feedstock through forging and rolling operations. VSMPO-AVISMA Corporation anchors the captive supply archetype with its Russian ilmenite-to-sponge verticality, though sanctions exposure now challenges this positioning.
| Leading Market Players |
|---|
| Pangang Group Vanadium & Titanium Resources Co., Ltd. |
| ATI Metals |
| Toho Titanium Co., Ltd. |
| Kobe Steel, Ltd. |
| Titanium Metals Corporation |
| OSAKA Titanium Technologies Co., Ltd. |
| Zunyi Titanium Co., Ltd. |
| Advanced Metallurgical Group N.V. |
| VSMPO-AVISMA Corporation |
| Others |
Value Chain & Pricing Dynamics
Russian ilmenite-to-sponge verticality through VSMPO-AVISMA anchors upstream concentration, concentrating aerospace-grade margin capture with Japanese and European mill product producers while exposing downstream buyers to sanctions-driven supply restructuring costs.
Pricing Analysis
Kroll-process legacy pricing dominates current transactions while electrolytic reduction prototypes command development premiums and Hunter-process sodium-reduced streams sustain medical-grade specification premiums. Three-tier pricing structure across premium aerospace-grade, standard industrial-grade, and emerging electrolytic qualification tiers reflects oxygen content thresholds and OEM certification status. Pricing pressure stems from magnesium reductant commodity swings in Chinese smelter output. Industrial chemical buyers exhibit highest price sensitivity, while semiconductor sputtering target specialists accept substantial premiums for low-alpha uranium and thorium limits below 10 ppb.
Supply Chain Analysis
Sanctions exposure between Russia and European aerospace tier-one suppliers dominates supply chain risk assessment, forcing qualification timelines for alternative Japanese and Chinese sponge sources. Geographic supply concentrates in Russia, Japan, and China, with the Osaka-Hyogo manufacturing cluster feeding Boeing and Airbus mill product networks. Raw material dependencies encompass magnesium reductant, chlorine feedstock, and high-purity titanium tetrachloride. Distribution runs through long-term offtake agreements rather than spot markets, with three-to-five-year fixed-grade contracts displacing transactional procurement among aerospace alloy forgers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Titanium sponge demand follows aerospace build-rate cycles, with Boeing and Airbus order backlogs providing visible recovery momentum through next-generation airframe program ramp-ups.
For Market Incumbents: Pre-empt electrolytic reduction qualification by embedding metallurgical validation teams at Cambridge University spinouts and Japanese molten salt consortia before 18-36 month OEM approval windows compress competitive response capacity. Lock long-term magnesium supply agreements to buffer Chinese smelter output volatility. Defend aerospace-grade positioning through JIS H 2151 and GB/T 2524 certification maintenance.
For New Entrants and Emerging Players: European semiconductor sputtering target supply presents the most penetrable white-space, with Korean wafer fabs expanding low-alpha titanium qualification programs absent entrenched incumbent relationships. Target medical device implant producers consolidating procurement around ASTM F67 and F136 certified lots. Lead with oxygen-controlled lot segregation capabilities and direct procurement team embedding.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialty chemical processors holding captive chlorination infrastructure but lacking downstream alloy forging integration. Five-to-ten year viability hinges on electrolytic reduction scale-up timelines and aerospace OEM pre-qualification progress. Monitor METI and SAMR standards alignment on electrolytic sponge microstructure acceptance as inflection signal for process substitution economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolytic Reduction Scale-Up | Cambridge University and Japanese consortia pilot 500-tonne cell designs challenging Kroll process energy intensity. |
| Long-Term Offtake Contracting | Toho Titanium and Kobe Steel coordinate three-to-five-year fixed-grade agreements displacing spot transactions. |
| Backward Integration into Ilmenite | VSMPO-AVISMA's captive mining-to-sponge verticality concentrates supply risk amid sanctions exposure. |
| Medical Device Certification Investment | ASTM F67 and F136 compliance creates margin pools for oxygen-controlled sponge segregation capabilities. |
| EU REACH Compliance Services | ECHA chlorination byproduct restrictions open advisory revenue streams for process audit specialists. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with titanium sponge plant managers, aerospace procurement leads at tier-one alloy forgers, METI standards officials, and medical device implant specialists; and secondary validation through customs trade databases, SEC filings from integrated producers, JIS and GB standards documentation, and ECHA substance evaluation records. Bottom-up capacity assessments across Russian, Japanese, and Chinese production facilities triangulated against top-down aerospace build-rate demand models.
Forecast inputs encompassed grade-tier segmentation by oxygen content thresholds, production method differentiation between Kroll and electrolytic routes, and end-use splits across aerospace, medical, semiconductor, and industrial applications across the analysis window. CAGR derivation incorporated capacity utilization trajectories, OEM qualification timeline probabilities, and magnesium price elasticity effects on Kroll process economics. Energy transition policy intensity and dual carbon goal enforcement timelines fed scenario weightings.
Practitioners should monitor electrolytic reduction purity achievement at commercial scale, sanctions regime evolution affecting Russian export licensing, and SAMR GB/T 2524 revision implementation timing for early signals requiring forecast reassessment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
India Steel Market
Metals
Saudi Arabia Aluminum Market
Metals
Aluminium Forging Market
Metals
Aluminum Hot Rolling Mill Market
Metals
Global Flat Carbon Steel Market
Metals
Aluminum Wire Market
Metals
Prebaked Anodes for Aluminum Market
Metals
Ore Metals Market
Metals
North America Metal Casting Market
Metals
Hafnium Foil Market
Metals
Titanium Mill Products Market
Metals
Bismuth Oxide Market
Metals
Beryllium Copper Billet Market
Metals
Aluminum Plates and Sheet Coils Market
Metals
Titanium Powder Market
Metals
Global Copper Cathode Market