
 Global Mercury Market | 2026-2036
Global Mercury Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mercury Market Intelligence
The buyer base for high-purity virgin mercury is consolidating around a smaller number of specialized chemical and electronics manufacturers. This shift favors suppliers with extensive quality control and documentation capabilities. Merck KGaA leverages its strong position in the laboratory and pharmaceutical chemical supply chain. Avantor Performance Materials competes on the basis of its high-purity material offerings for scientific research. Meanwhile, China Jin Run Industrial Co., Ltd anchors a significant portion of supply for industrial applications in Asia.
Mercury is a heavy, silvery-white liquid metal, unique for its liquid state at standard temperature and pressure. This property, along with its high density and electrical conductivity, underpins its use in specialized industrial processes and scientific instruments. Demand for mercury compounds is growing faster than for elemental mercury, particularly for use as catalysts in chemical manufacturing. The application in traditional measuring instruments like thermometers is declining due to regulatory phase-outs, while use in certain electrical equipment persists under specific exemptions.
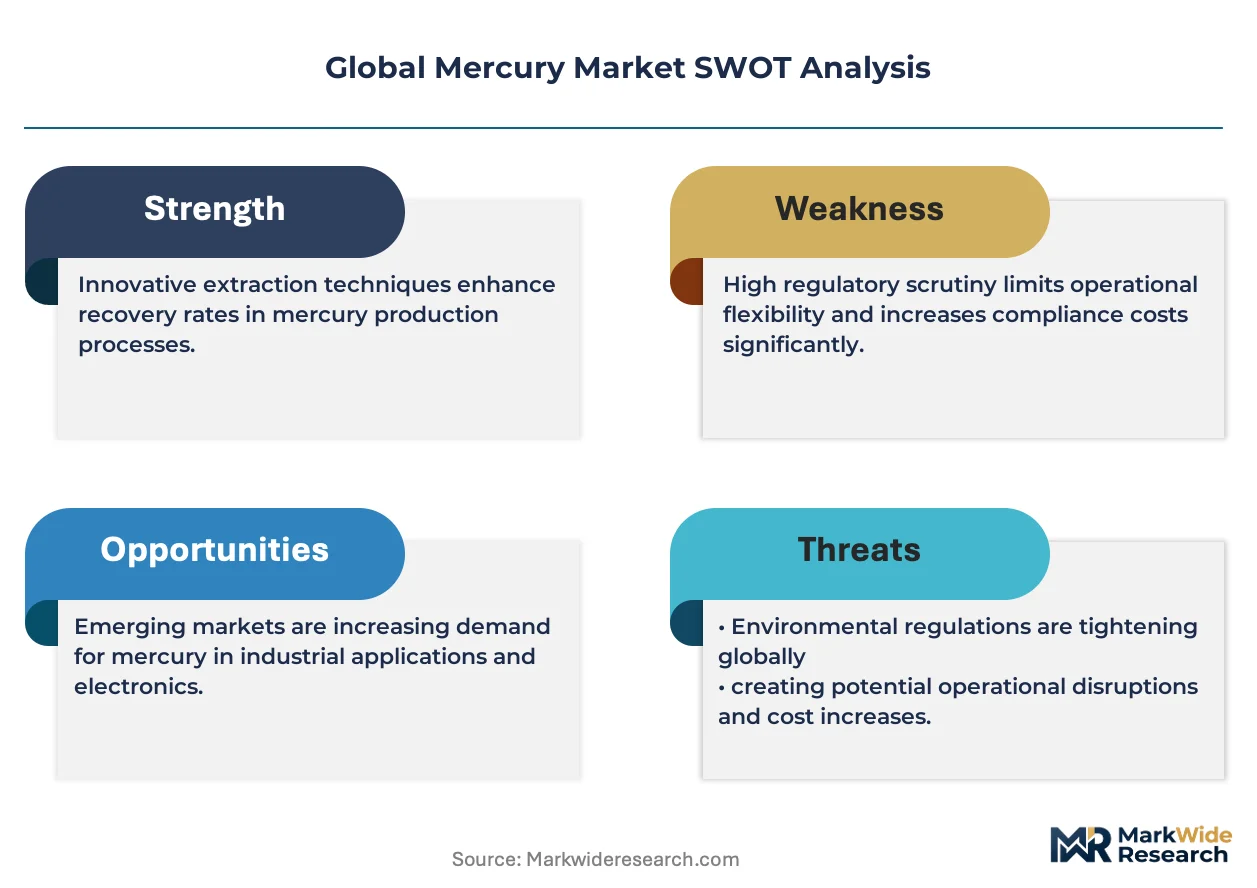
The market operates under stringent international and national regulations, led by the Minamata Convention on Mercury, which aims to phase out many uses. In parallel, bodies like the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) enforce strict controls on trade, use, and disposal. Navigating this complex regulatory landscape to serve legally permissible, high-value applications remains the central strategic challenge for all participants.
Market Dynamics
The central structural force shaping the mercury market is the profound tension between stringent global regulations aiming for phase-out and persistent demand from niche, high-value industrial applications that lack viable substitutes, creating a bifurcated market dynamic.
Growth Catalysts
- Catalysis in Chemical Production:Demand for mercury compounds as catalysts in the manufacturing of specific polymers and chemicals, particularly vinyl chloride monomer in certain regions, continues to provide a foundational demand stream.
- High-Purity Electronics:The requirement for ultra-high purity mercury in specialized electronic components and switches, concentrated in industrial clusters within Germany and Japan, supports a premium market segment.
- Scientific Research:Ongoing use in laboratory-scale research and for calibration of scientific instruments under specific regulatory exemptions sustains a small but stable demand for documented, high-grade material.
Market Restraints
- Regulatory Pressure:The Minamata Convention on Mercury acts as the primary structural restraint, progressively restricting primary mining, international trade, and specific end-use applications across signatory nations.
- Substitution Threats:The development of mercury-free alternatives, such as digital thermometers, gallium-based alloys (galinstan), and alternative catalysts, erodes demand in traditional product categories.
- End-of-Life Liability:Strict regulations from bodies like the US EPA on the disposal and long-term storage of mercury-containing waste and elemental mercury create significant long-term costs and liabilities for users.
Strategic Opportunities
- Advanced Compound Development:Research into novel mercury compounds for highly specific catalytic or reagent use offers a pathway to higher-value, lower-volume applications that may fall outside broad regulatory restrictions.
- Recycling and Purification:Establishing certified, closed-loop recycling and purification infrastructure to serve legally permissible applications creates a defensible service-based business model aligned with circular economy principles.
- Exempted Niche Applications:Focusing on supplying mercury for uses specifically exempted under the Minamata Convention, such as certain analytical standards and research uses, provides a stable, albeit small, market.
Industry Challenges
- Compliance Complexity:Participants face the challenge of navigating a fragmented and evolving regulatory landscape, with national interpretations and enforcement of the Minamata Convention varying significantly between jurisdictions.
- Specialized Logistics:The logistical challenge of transporting, storing, and handling a designated hazardous material requires specialized, certified partners, adding significant cost and complexity to the supply chain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mercury Market |
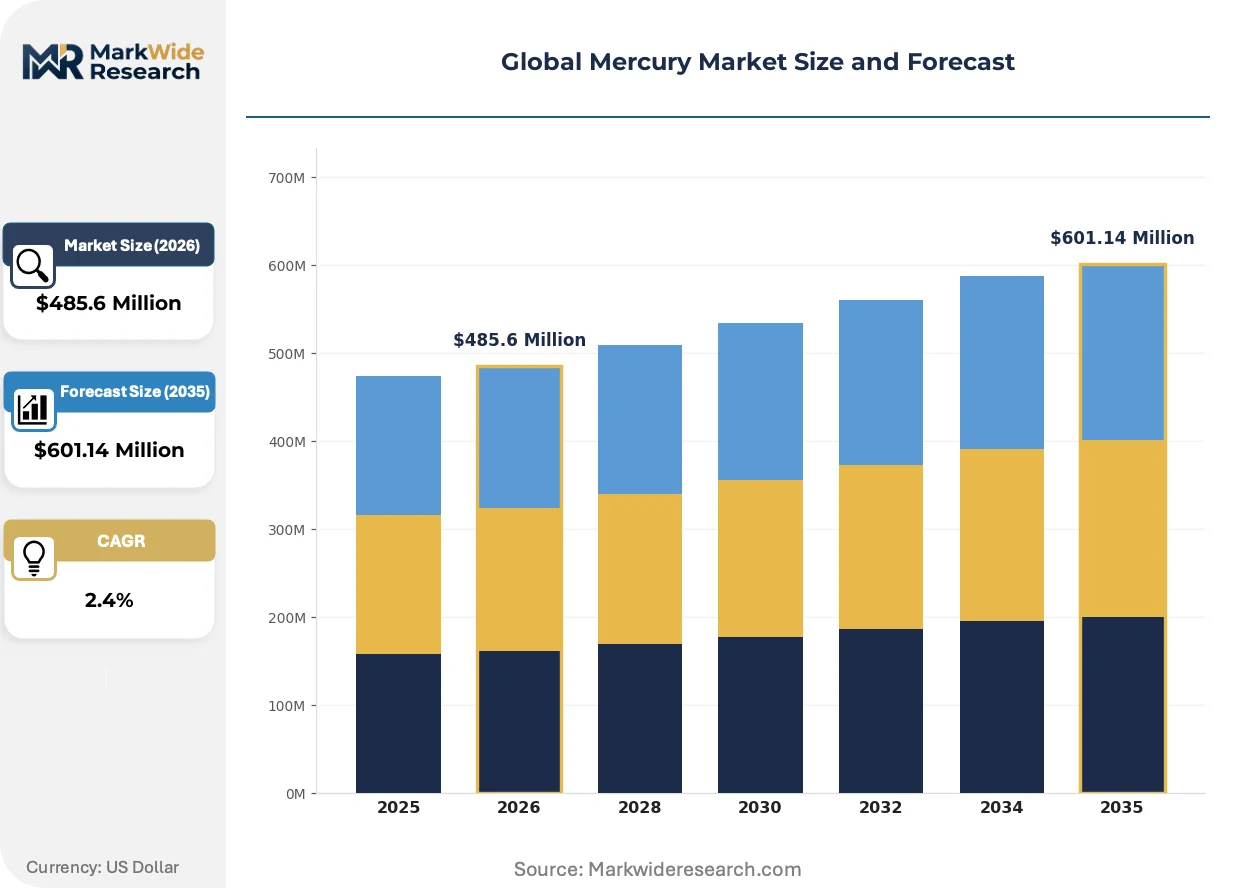
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $601.14 Million |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elemental Mercury, Mercury Compounds, Dental Amalgam, Thermometers, Fluorescent Lamps, Batteries Application: Electrical Equipment, Chemical Manufacturing, Pharmaceuticals, Measuring Instruments, Artwork, Mining End User Industry: Chemical Processing Plants, Pharmaceuticals Production, Scientific Research Facilities, Mining Companies, Art Restoration Studios, Electronics Manufacturers Packaging Type: Glass Bottles, Steel Drums, Plastic Containers, Bulk Tanks, Sealed Ampoules, Cartridge Tubes |
| Companies Covered | Avantor Performance Materials, Albemarle Corporation, China Jin Run Industrial Co., Ltd, Acton Technologies, Inc., ACI Alloys, Aldrett Hermanos, Wake Group, DF Goldsmith Chemical & Metal Corporation, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mercury Market Strategic Shifts & Innovations
The market is defined by a divergence between declining bulk applications and a resilient niche for high-specification material. This split is driven by regulatory enforcement that simultaneously curtails supply while concentrating demand among users with stringent quality and documentation requirements.
Mercury's unique electrical properties ensure its continued use in a small subset of high-reliability electrical components. Manufacturers of specialized industrial and aerospace equipment adopt these components where failure is not an option. The persistent need for this function is electrifying the supply chain for documented, virgin-grade mercury, creating a distinct, high-value segment separate from the broader industrial market.
Global regulatory frameworks are solidifying, forcing major market adjustments. The Minamata Convention's implementation phase is compelling countries to formalize national action plans for reducing and eliminating mercury use. This action, enforced by agencies like the ECHA in Europe, is shutting down informal supply chains and increasing the compliance burden on all industrial users, particularly in the chlor-alkali and vinyl chloride monomer sectors.
Buyer behavior is fundamentally changing, moving away from transactional purchasing. End-users in the electronics and pharmaceutical research sectors now demand complete supply chain transparency and extensive quality documentation, including certificates of origin and purity analysis. This shift disrupts the business model of traditional commodity traders and favors suppliers with robust laboratory and compliance capabilities, a trend most visible in Germany and the United States.
Global Mercury Market Segmentation
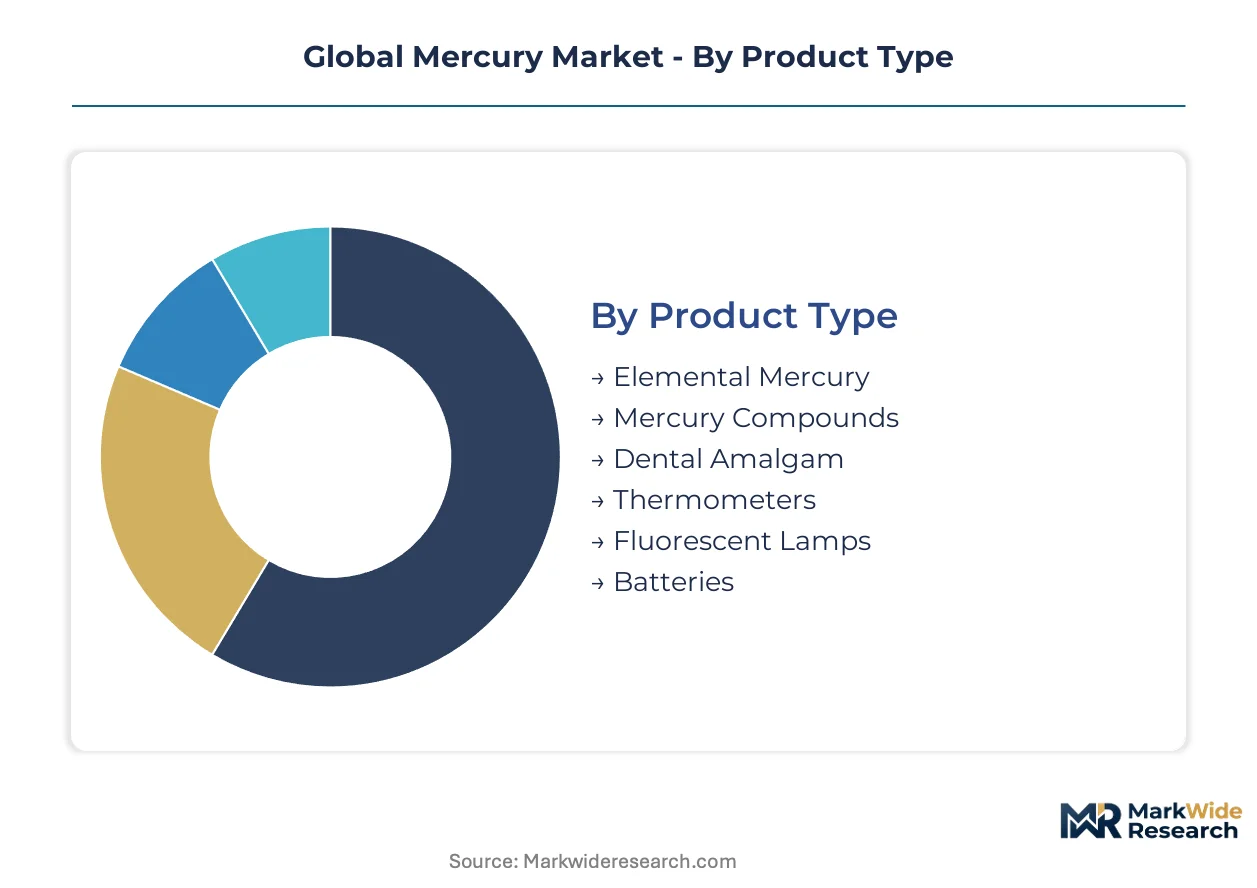
Understanding the segmentation of the global mercury market is crucial for identifying where persistent demand exists despite stringent regulatory pressures. This granular analysis reveals the specific product forms, applications, and end-user industries that continue to require mercury, often for highly specialized functions.
Product Type:
The product type segmentation reflects a spectrum from highly standardized bulk forms to customized, high-purity variants tailored for specific industrial needs.
- Elemental Mercury:This is pure, uncombined mercury metal, a dense, silvery-white liquid at room temperature, valued for its unique electrical conductivity and high density. Demand for high-purity grades is concentrating in specialized electronics manufacturing in Germany and Japan for critical switch components.
- Mercury Compounds:These are chemical substances containing mercury, such as mercury chloride or mercury oxide, often utilized for their catalytic properties in industrial chemical processes. Demand is particularly strong in regions where mercury-based catalysts are still permissible for vinyl chloride monomer production.
- Dental Amalgam:A dental filling material composed of mercury, silver, tin, and copper. Regulatory phase-outs under the Minamata Convention are significantly reducing its use globally.
- Thermometers:Devices using mercury's thermal expansion for temperature measurement, largely phased out due to environmental concerns and the availability of digital alternatives.
- Fluorescent Lamps:Lighting products containing small amounts of mercury vapor for light production, facing declining use due to energy efficiency regulations and LED adoption.
- Batteries:Certain types of batteries historically contained mercury to prevent corrosion, but most have been phased out due to environmental and health impacts.
Leading the category by volume: Elemental Mercury. Growing fastest: Mercury Compounds.
Application:
This category highlights the diverse functional roles mercury plays, ranging from essential industrial processes to highly specialized scientific and artistic uses.
The application segmentation illustrates the varying criticality and regulatory scrutiny applied to different uses of mercury, from high-volume industrial to niche, protected categories.
- Chemical Manufacturing:Mercury compounds serve as catalysts in the production of various chemicals, most notably in the synthesis of vinyl chloride monomer in specific Asian markets. This application remains a foundational demand stream, driving significant volume.
- Electrical Equipment:Mercury's unique electrical properties ensure its continued use in specialized switches, relays, and sensors where reliability and performance are paramount. Manufacturers of industrial and aerospace components in the United States rely on these high-precision parts.
- Pharmaceuticals:Mercury compounds may be used as reagents or in the synthesis of certain pharmaceutical intermediates, though regulatory restrictions have significantly curtailed broad application.
- Measuring Instruments:Applications in barometers, manometers, and other precision instruments persist under specific regulatory exemptions, particularly for calibration.
- Artwork:Mercury has historical use in pigments (e.g., vermilion) and gilding processes, with limited, highly controlled use in restoration projects.
- Mining:Historically used for gold amalgamation, this application is under severe restriction globally due to environmental contamination.
The primary demand driver for this category is catalysis in chemical manufacturing, while specialized electrical equipment applications are expanding most quickly.
End User Industry:
The end-user industry segmentation delineates the specific sectors that procure mercury, reflecting their unique operational needs and regulatory compliance requirements.
This category showcases the distinct operational frameworks and compliance burdens faced by various industries utilizing mercury, from heavy industrial to highly specialized research.
- Chemical Processing Plants:These facilities utilize mercury, primarily in compound form, as a catalyst for large-scale chemical synthesis, particularly in regions with less stringent VCM production regulations. They demand bulk quantities with consistent specifications.
- Electronics Manufacturers:Focused on producing high-reliability components like switches and relays for industrial, automotive, and aerospace sectors, these manufacturers require ultra-high purity elemental mercury. Demand for complete supply chain transparency is high in Germany and the United States.
- Pharmaceuticals Production:Companies in this sector may use mercury compounds for specific synthesis steps or as reagents, adhering to strict purity and handling protocols.
- Scientific Research Facilities:Laboratories and research institutions use mercury for analytical standards, calibration, and experimental setups under specific regulatory exemptions.
- Mining Companies:Historically, artisanal and small-scale gold mining used mercury for amalgamation, an application now largely prohibited and targeted for elimination.
- Art Restoration Studios:Specialized studios may use mercury for historical restoration techniques, operating under strict control and permits due to its hazardous nature.
Compliance requirements heavily influence purchasing decisions within this category, with electronics manufacturers exhibiting the steepest expansion trajectory for high-purity material.
Packaging Type:
The packaging type segmentation highlights the diverse logistical and safety requirements associated with mercury handling, from bulk transport to precision dispensing.
This category reflects the varying scales of mercury use and the critical safety and preservation measures required for its transport and storage, from large industrial volumes to minute, high-purity doses.
- Steel Drums:Robust, sealed containers typically used for the bulk transport and storage of elemental mercury for industrial applications. They are designed for durability and hazardous material containment.
- Sealed Ampoules:Small, hermetically sealed glass vials containing precise, often minute, quantities of high-purity mercury or mercury compounds. These are critical for laboratory research and specialized electronic component manufacturing.
- Glass Bottles:Used for smaller volumes of elemental mercury or various mercury compounds, often for laboratory or specialized industrial use where chemical inertness is required.
- Plastic Containers:Less common for elemental mercury due to potential reactivity, but used for certain mercury compounds or waste, provided material compatibility.
- Bulk Tanks:Large-capacity storage and transport vessels, primarily for elemental mercury in very large industrial operations, requiring specialized handling and infrastructure.
- Cartridge Tubes:Pre-portioned, often encapsulated, units for specific applications like dental amalgam, designed for ease of use and reduced exposure.
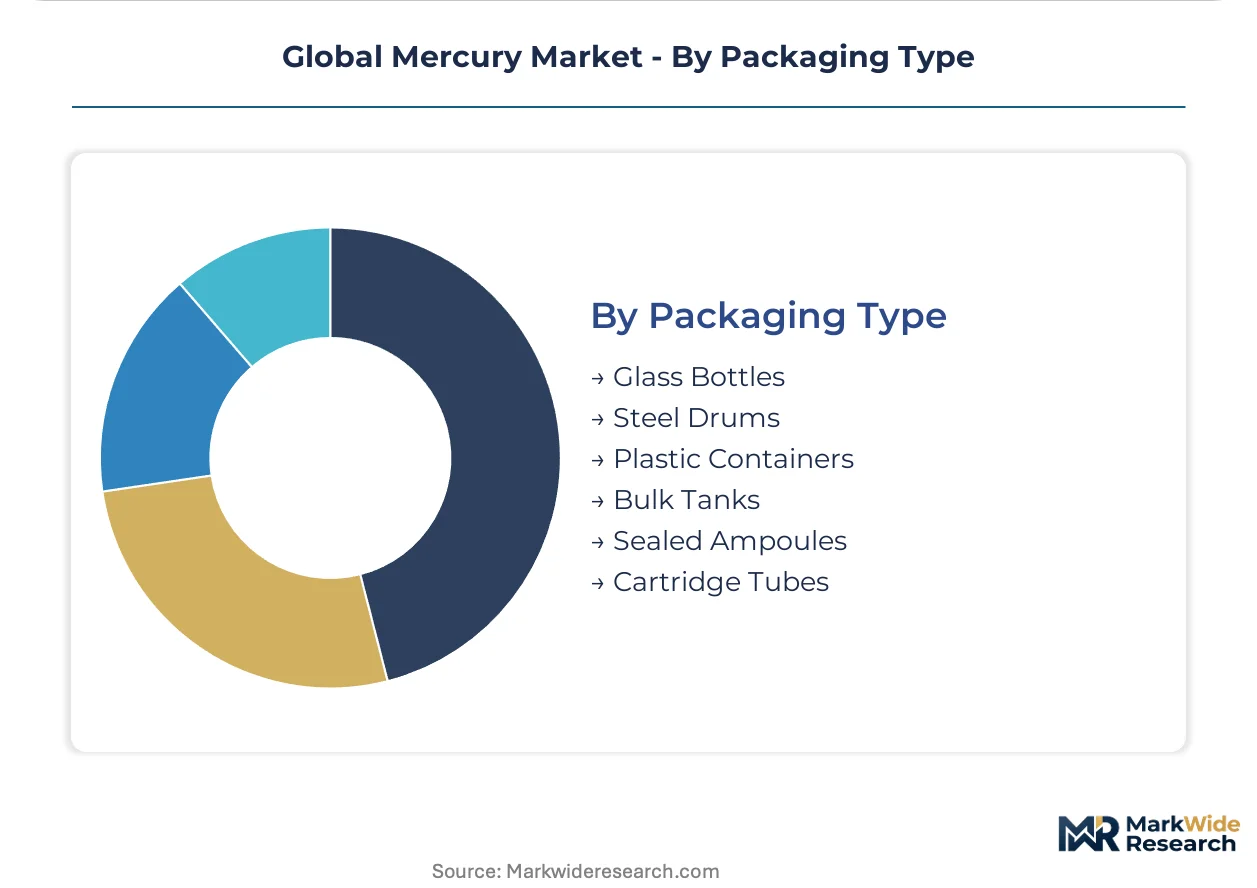
Specialized logistics dictate material handling across these packaging solutions, with sealed ampoules gaining share fastest for high-value applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for mercury, particularly high-purity grades, is concentrating in specialized industrial clusters across key global economies. This shift reflects stringent quality requirements from advanced manufacturing and critical research applications. Regulatory frameworks heavily influence regional market dynamics.
United States
The United States exhibits persistent demand for ultra-high purity elemental mercury in specialized electrical equipment. The US Environmental Protection Agency (EPA) maintains stringent controls on mercury trade and disposal. Electronics manufacturers in Silicon Valley and aerospace component producers demand transparent supply chains for critical components.
Germany
Germany shows strong demand for high-purity mercury in specialized electronics manufacturing and scientific calibration. The European Chemicals Agency (ECHA) rigorously implements the Minamata Convention's use restrictions. Advanced electronics producers in Bavaria and Baden-Württemberg require documented, high-grade material for critical components.
Japan
Japan requires ultra-high purity mercury for critical switch components and advanced scientific research. The Ministry of Economy, Trade and Industry (METI) enforces national mercury reduction plans. Precision electronics manufacturers in the Kanto region prioritize documented, virgin-grade mercury for high-reliability products.
China
China maintains significant demand for mercury compounds, primarily as catalysts in chemical manufacturing. The Ministry of Ecology and Environment (MEE) manages strict controls on industrial mercury use and emissions. Chemical processing plants in the Yangtze River Delta drive volume for mercury-based catalysts in VCM production.
France
France exhibits niche demand for mercury in specialized laboratory research and analytical standards. The French Agency for Food, Environmental and Occupational Health & Safety (ANSES) monitors mercury use under strict exemptions. Research institutions in the Île-de-France region procure high-purity mercury for calibration and experimental setups.
Global Mercury Market Key Industry Players
Asian producers anchor one tier of the mercury market, supplying industrial-grade material for chemical manufacturing. European and North American specialists hold the other tier, focusing on ultra-high purity grades for electronics and research. The market structure is bifurcated, with distinct supply chains serving different quality and volume requirements. Suppliers differentiate through extensive quality control capabilities and comprehensive documentation, crucial for navigating complex regulatory compliance.
Among Asia-based industrial suppliers, China Jin Run Industrial Co., Ltd. exemplifies a major provider for chemical manufacturing applications, particularly in regions with persistent demand for mercury-based catalysts. On the high-purity and research-grade vector, Merck KGaA (Germany) occupies a strong position within the laboratory and pharmaceutical chemical supply chain. Avantor Performance Materials, an American entity, represents a specialist in high-purity material offerings for scientific research. These companies anchor distinct segments of the global mercury market, emphasizing either volume for industrial use or stringent quality for specialized applications demanding extensive documentation.
| Leading Market Players |
|---|
| Avantor Performance Materials |
| Albemarle Corporation |
| China Jin Run Industrial Co., Ltd |
| Acton Technologies, Inc. |
| ACI Alloys |
| Aldrett Hermanos |
| Wake Group |
| DF Goldsmith Chemical & Metal Corporation |
| Merck KGaA |
| Others |
Cost & Logistics Intelligence
The Minamata Convention on Mercury, a global environmental mandate, severely gates qualified mercury supply and restricts access to premium-tier applications. This international agreement creates a unique pricing environment for legally permissible, high-value uses.
Pricing Analysis
Volume-driven industrial applications for mercury compounds typically operate on lower margins, reflecting commodity spot pricing for bulk quantities. High-purity elemental mercury commands premium pricing through transactional sales, driven by stringent quality documentation and certification requirements. Pricing pressure stems from regulatory phase-outs in traditional uses, while specialized applications maintain price stability. Chemical processing plants exhibit higher price sensitivity compared to electronics manufacturers requiring ultra-high purity material.
Supply Chain Analysis
Specialized logistics and freight costs significantly influence the global mercury supply chain, particularly for hazardous material transport. Supply concentration for industrial-grade mercury compounds centers on China, while high-purity elemental material sources from Europe and North America. Raw material dependencies include both primary sources and increasingly, recycled mercury. Regulatory restrictions, particularly the Minamata Convention, pose a structural risk to consistent supply. Distribution runs through direct sales channels for high-purity grades and specialized chemical distributors for industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global mercury market is fundamentally a supply-constrained story, where the progressive shutdown of primary mining capacity under the Minamata Convention props up pricing for legally permissible uses. This creates a unique strategic imperative for participants.
For Market Incumbents: Deepen vertical integration into certified recycling and advanced purification processes to secure compliant feedstock. Invest in robust quality control and supply chain transparency systems to counter the threat of informal supply channels and maintain market legitimacy. Strengthen relationships with specialized industrial clusters in Germany, Japan, and the United States to serve critical electronics and research applications. This approach defends against substitution threats and regulatory shifts.
For New Entrants and Emerging Players: A significant price-point gap exists between commodity-grade mercury and ultra-high purity material, creating market entry opportunities. Target specialized laboratory research and analytical standards, a highly penetrable segment with specific regulatory exemptions. Develop advanced mercury compounds for niche catalytic or reagent uses, offering superior documentation and purity guarantees as a core go-to-market angle. Focus on serving industrial clusters within Germany and the United States.
For Investors and Strategic Acquirers: The successful development of scalable mercury-free catalysts for VCM production is the leading indicator that could significantly alter long-term mercury demand. Long-term viability hinges on persistent demand from irreplaceable, high-value applications such as specialized electronics. Target acquisition profiles include companies with proprietary purification technologies, established certified recycling infrastructure, or strong positions in advanced mercury compound synthesis. Watch for accelerated regulatory enforcement trends in key industrial regions, particularly regarding VCM production.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Chemical processing plants increase output of mercury-based catalysts in Asia. |
| Backward Integration | Electronics manufacturers secure captive supply of ultra-high purity elemental mercury. |
| Green Manufacturing Transition | Suppliers invest in mercury-free production for specific compounds under ECHA guidance. |
| Long-term Supply Agreement | Specialized users secure multi-year contracts for high-grade material with transparent documentation. |
| Joint Venture | Companies partner to develop closed-loop recycling infrastructure for mercury in Europe. |
Research Approach
Trade association reports, customs data, and regulatory agency publications from the US EPA, ECHA, and METI formed the secondary backbone of this study. This was triangulated with primary interviews involving R&D directors, procurement leads from electronics manufacturers, regulatory compliance officers, and chemical plant managers. Our approach combined bottom-up market sizing with top-down validation to ensure data accuracy and coherence.
Historical trendline analysis across the modeling period informed the forecast framework, projecting market evolution over the projection horizon. Segmentation dimensions modeled included product type, application, end-user industry, packaging type, and regional regulatory compliance. Compound Annual Growth Rates were derived from a weighted average of historical growth rates and projected demand drivers. Key forecast inputs included Minamata Convention implementation timelines and advancements in mercury-free alternatives.
Inputs from industry reports, company financial filings, and regulatory databases were available through the study window; gaps in granular end-user consumption data for highly specialized applications introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory enforcement and technological development. Stakeholders should weigh these assumptions against their own operating context, considering risks like unexpected regulatory shifts or faster substitution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
US and Mexico Stainless Steel Market
Metals
Copper Foil Market
Metals
Silver Sulphate Market
Metals
Wear Steel Plate Market
Metals
Electrolytic Iron Market
Metals
Europe Aluminum Extrusion Market
Metals
Europe Aluminium Wire Rod Market
Metals
Global Wire Rods Market
Metals
GCC Aluminium Cans Market
Metals
Monel Alloy Market
Metals
Zirconium Market
Metals
Lithium Foil Market
Metals
Tin Chloride Market
Metals
Platinum Group Metals Market
Metals
Copper Clad Aluminum Wire Market
Metals
North America Iron Casting Market