
 Starch Blended Biodegradable Polymer Market | 2026-2036
Starch Blended Biodegradable Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Starch Blended Biodegradable Polymer Market Intelligence
Modular packaging configurations that separate barrier layers from structural starch cores is realigning procurement criteria for converters and brand owners. BASF SE leverages its polymer compounding infrastructure to supply tailored starch-polyester alloys for flexible film applications. NatureWorks LLC anchors North American supply through its PLA-starch hybrid platform designed for thermoformed food service items. Novamont S.p.A. specializes in Mater-Bi formulations that dominate Italian retail bag specifications through integrated fermentation and polymerization assets.
Starch blended biodegradable polymers combine native or modified starch with synthetic or bio-based polyesters to achieve processability and controlled disintegration in industrial composting environments, typically containing 30-70% starch by weight depending on target mechanical properties and certification requirements. Thermoplastic starch competes primarily on cost in single-use applications where moisture sensitivity remains acceptable, while PHA blends command premium positioning in marine-degradable and agricultural mulch segments where complete biodegradation without industrial infrastructure is essential. Granules constitute the dominant traded form as compounders prefer melt-compounding flexibility, though film demand accelerates fastest as pre-converted roll stock reduces downstream capital barriers for packaging converters.
The EU F-Gas Regulation and REACH restrictions on persistent microplastics shape material eligibility for consumer goods applications across member states, while FDA food contact notifications govern starch-polyester laminates in US food packaging markets. ASTM D6400 and EN 13432 certification divergence creates parallel testing requirements that compounders must navigate for transatlantic product qualification. Stakeholders should monitor industrial composting capacity buildouts in target markets, as certification without accessible end-of-life infrastructure risks greenwashing exposure and regulatory scrutiny.
Market Dynamics
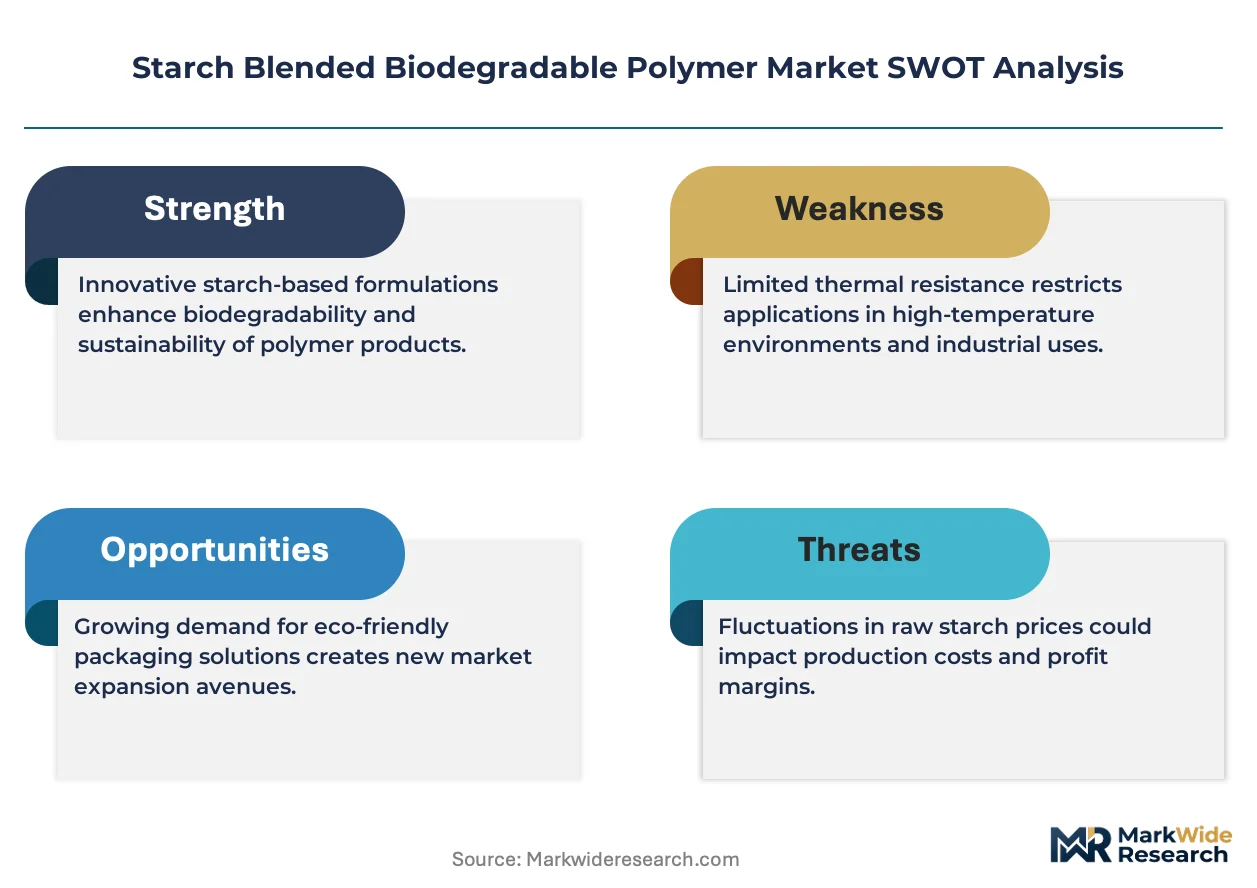
Industrial composting certification divergence between ASTM D6400 and EN 13432 standards is fragmenting product qualification pathways, forcing compounders to maintain dual testing protocols and delaying transatlantic market entry for mid-sized suppliers lacking dedicated regulatory affairs capacity.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory phase-out of conventional plastic cutlery and food containers across member states is pulling forward substitution timelines for certified compostable alternatives in food service packaging.
- California and New York state mandates:Comparable legislation at sub-federal level is creating regulatory momentum that de-risks capital deployment for domestic compounding capacity.
- Industrial composting infrastructure:Facility buildouts in Germany, Italy, and the Netherlands are closing the end-of-life gap that previously undermined certification credibility.
Market Restraints
- Maize and potato starch feedstock volatility:Agricultural commodity price swings transmit directly into compounder margins, with limited hedging instruments available for bio-based polymer producers.
- European compounder concentration:Mater-Bi and similar proprietary formulations dominate Italian retail specifications, creating supply security concerns for converters seeking second-source qualification.
- Moisture sensitivity limitations:Thermoplastic starch performance degradation above 65% relative humidity restricts addressable applications in ambient beverage packaging and extended-shelf-life food formats.
Strategic Opportunities
- PHA-starch hybrid platforms:Convergence of polyhydroxyalkanoate fermentation with thermoplastic starch extrusion is opening marine-degradable segments where industrial composting infrastructure remains absent.
- Pre-converted roll stock distribution:Film converters are bypassing granule resale channels to supply brand owners directly, capturing margin previously held by compounders and reducing downstream capital barriers.
- Agricultural mulch films:Soil-biodegradable certification pathways under EN 13432 and ASTM D5988 are creating premium positioning for starch-PHA blends in specialty crop protection where retrieval costs dominate conventional plastic economics.
Industry Challenges
- Dual certification timeline compression:Parallel ASTM D6400 and EN 13432 testing requirements extend product qualification cycles by 8-14 months, straining R&D budgets and delaying revenue recognition.
- Composting facility acceptance protocols:Operator variability in feedstock tolerance and processing conditions creates batch rejection risk that undermines brand owner confidence in end-of-life claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Starch Blended Biodegradable Polymer Market |
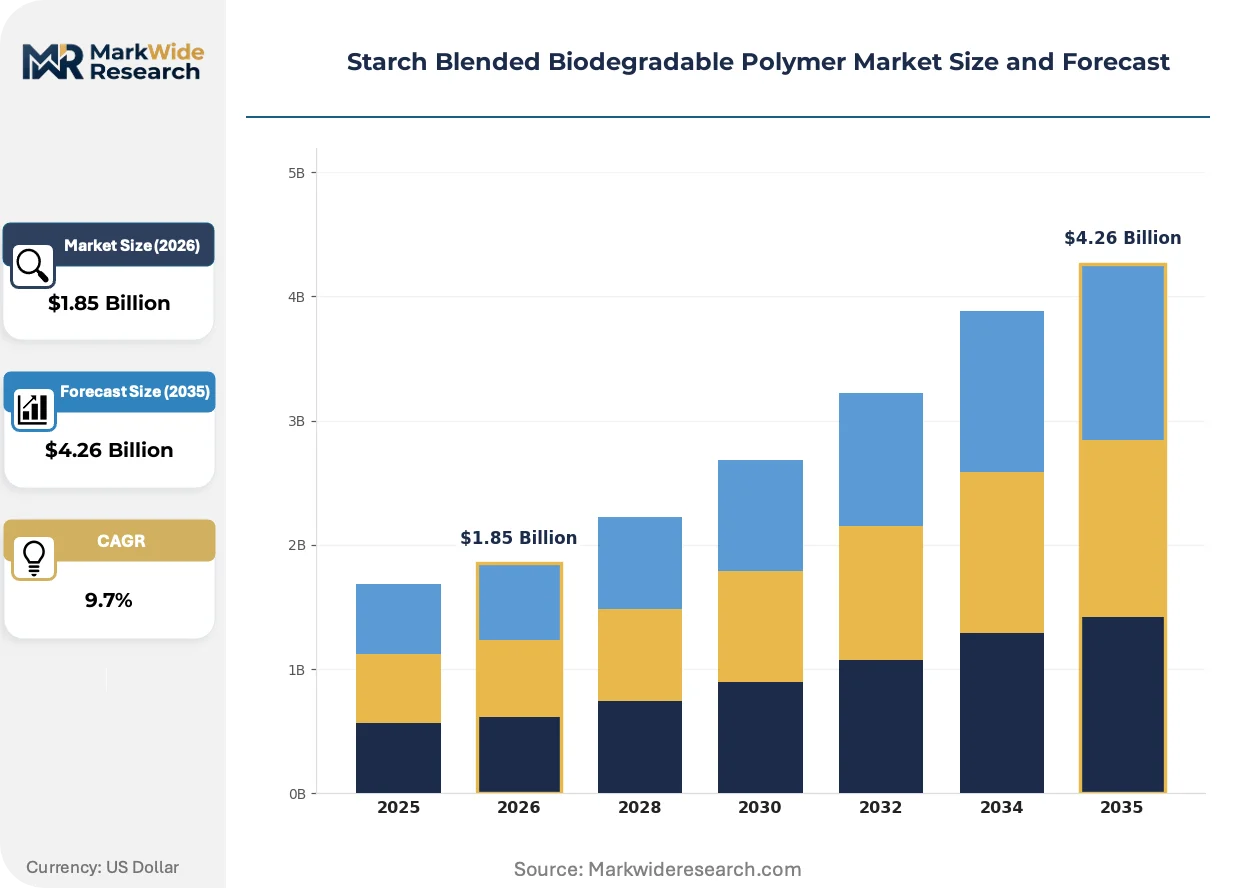
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.26 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch-Based Blends, Thermoplastic Starch, Mater-Bi, PHA Blends End Use Industry: Packing, Agriculture, Consumer Goods, Textiles Form: Granules, Films, Coatings, Moulds Certification: ASTM D6400, EN 13432, ISO 17088, Others |
| Companies Covered | TotalEnergies Corbion, Biome Technologies plc, BASF SE, Cargill Incorporated, PTT Global Chemical, Novamont S.p.A., Danimer Scientific, Plantic Technologies, NatureWorks LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Starch Blended Biodegradable Polymer Market Strategic Shifts & Innovations
Barrier layer separation from structural starch cores is reconfiguring converter procurement criteria, while regulatory pressure on persistent microplastics accelerates material substitution in consumer-facing applications. Three developments are reshaping competitive positioning.
Multilayer coextrusion technology is expanding into high-oxygen-barrier food packaging previously reserved for ethylene-vinyl alcohol laminates. Modified starch outer layers bonded to thin synthetic barrier films achieve shelf-life parity at 40-60% fossil-derived content. European fresh produce packagers are adopting these structures fastest, compressing the addressable market for conventional multilayer films in ready-to-eat salad and prepared fruit segments.
REACH restrictions on microplastics in consumer goods are tightening material eligibility across EU member states. ECHA guidance on polymer biodegradability thresholds is forcing reformulation of starch-polyester ratios to demonstrate disintegration within mandated timeframes. Personal care and home cleaning brands with EU distribution are responding by specifying certified compostable primary packaging, shifting specification power from converters to compounders with established EN 13432 dossiers.
Food packaging chains are consolidating supplier panels around pre-qualified compostable material platforms. Brand owner technical teams now mandate integrated certification documentation from compounders rather than accepting converter-assembled compliance packages. This concentration is most visible in North American quick-service restaurant supply chains, where three approved material specifications now cover 70% of certified compostable food service item procurement volume.
Starch Blended Biodegradable Polymer Market Segmentation
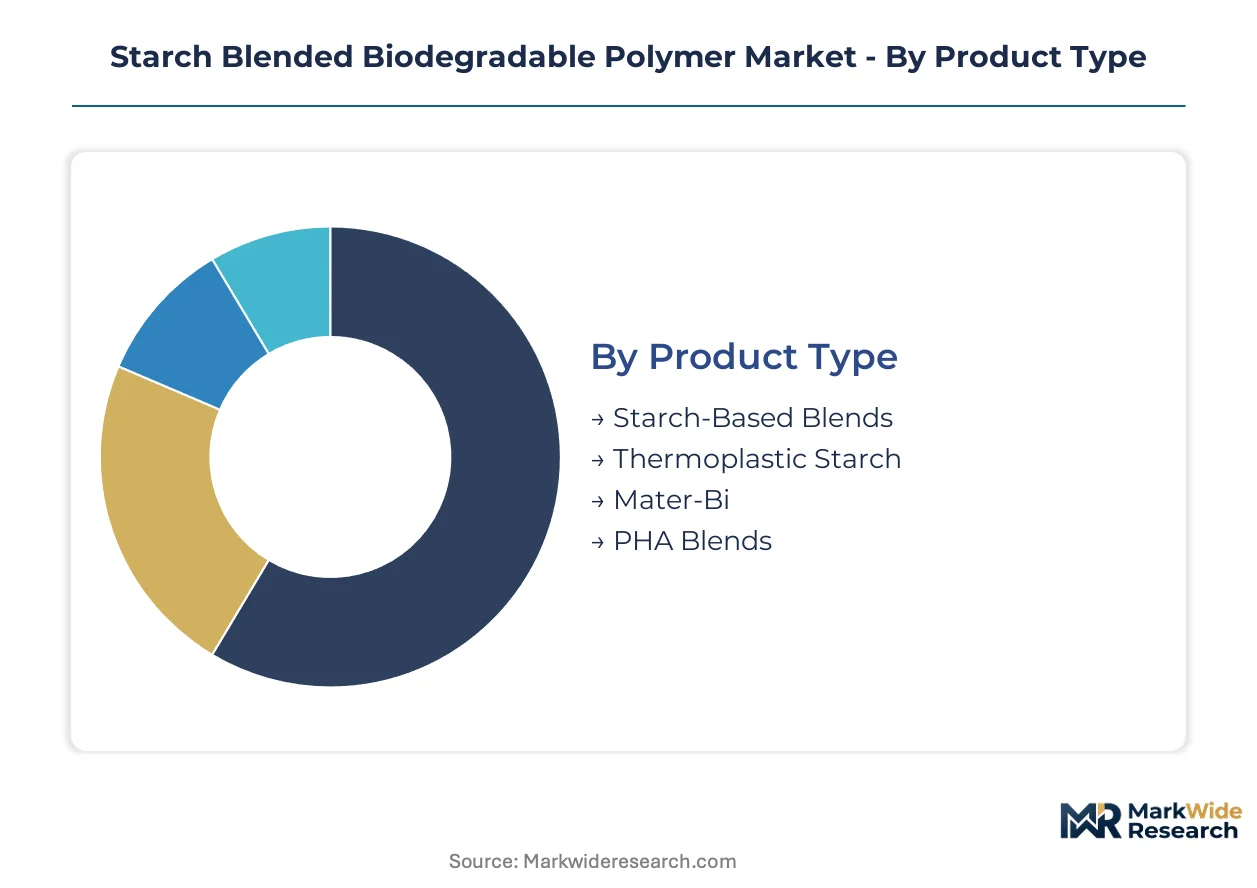
Starch blended biodegradable polymers require precise segmentation to match material specifications with end-of-life infrastructure availability. Certification pathways vary dramatically across product types and geographies, creating procurement complexity for converters navigating dual-standard markets.
Product Type:
Certification burden falls heaviest on PHA blends and Mater-Bi formulations seeking marine-degradable claims, while thermoplastic starch faces lighter documentation for industrial composting-only applications.
- Thermoplastic Starch:Native or modified starch plasticized with glycerol or sorbitol to achieve thermoplasticity, typically comprising 50-70% starch by weight. German fresh produce packaging chains specify this grade for short-shelf-life applications where moisture sensitivity remains manageable and cost minimization dominates procurement criteria.
- PHA Blends:Polyhydroxyalkanoate fermentation products combined with thermoplastic starch to achieve soil and marine biodegradability without industrial composting infrastructure. Italian agricultural mulch film specifications favor these formulations where retrieval economics make conventional plastic uncompetitive.
- Starch-Based Blends:Generic compounding of starch with synthetic aliphatic polyesters for cost-engineered applications.
- Mater-Bi:Proprietary Novamont formulation integrating starch with proprietary polyesters through integrated fermentation assets.
Leading the category by volume: Starch-Based Blends. Expanding most quickly: PHA Blends.
End Use Industry:
Cost tier separation distinguishes premium food contact applications from commodity agricultural deployment where certification depth varies.
- Packing:Food service items, flexible films, and rigid containers requiring FDA food contact notifications in US markets and EFSA compliance in Europe. California quick-service restaurant chains are consolidating supplier panels around three pre-qualified material specifications covering certified compostable cutlery and clamshell containers.
- Agriculture:Mulch films, plant pots, and crop protection applications where soil-biodegradable certification under EN 13432 and ASTM D5988 creates premium positioning. Dutch specialty vegetable growers specify starch-PHA blends where manual plastic retrieval costs exceed material premiums.
- Consumer Goods:Personal care and home cleaning packaging facing REACH microplastic restrictions across EU member states.
- Textiles:Nonwoven applications and fiber production for disposable hygiene products.
Packing commands the largest volume share. Agriculture posts the steepest expansion trajectory as soil-biodegradable certification pathways mature.
Form:
Customer type divergence separates compounder-preferred granules from brand owner-direct film procurement that bypasses traditional distribution channels.
- Granules:Dominant traded form enabling melt-compounding flexibility for converters with extrusion capacity. Compounders in the Netherlands and Germany maintain granule inventory positions to serve mid-sized packaging converters lacking dedicated regulatory affairs capacity for direct certification management.
- Films:Pre-converted roll stock reducing downstream capital barriers for packaging converters entering certified compostable markets. North American fresh produce packagers are adopting multilayer coextruded structures fastest, compressing addressable market for conventional multilayer films in ready-to-eat segments.
- Coatings:Barrier applications for paper and board substrates in food contact.
- Moulds:Thermoformed trays, cups, and structural containers for food service.
Granules lead by volume. Films gain share fastest as direct brand owner procurement concentrates around pre-qualified specifications.
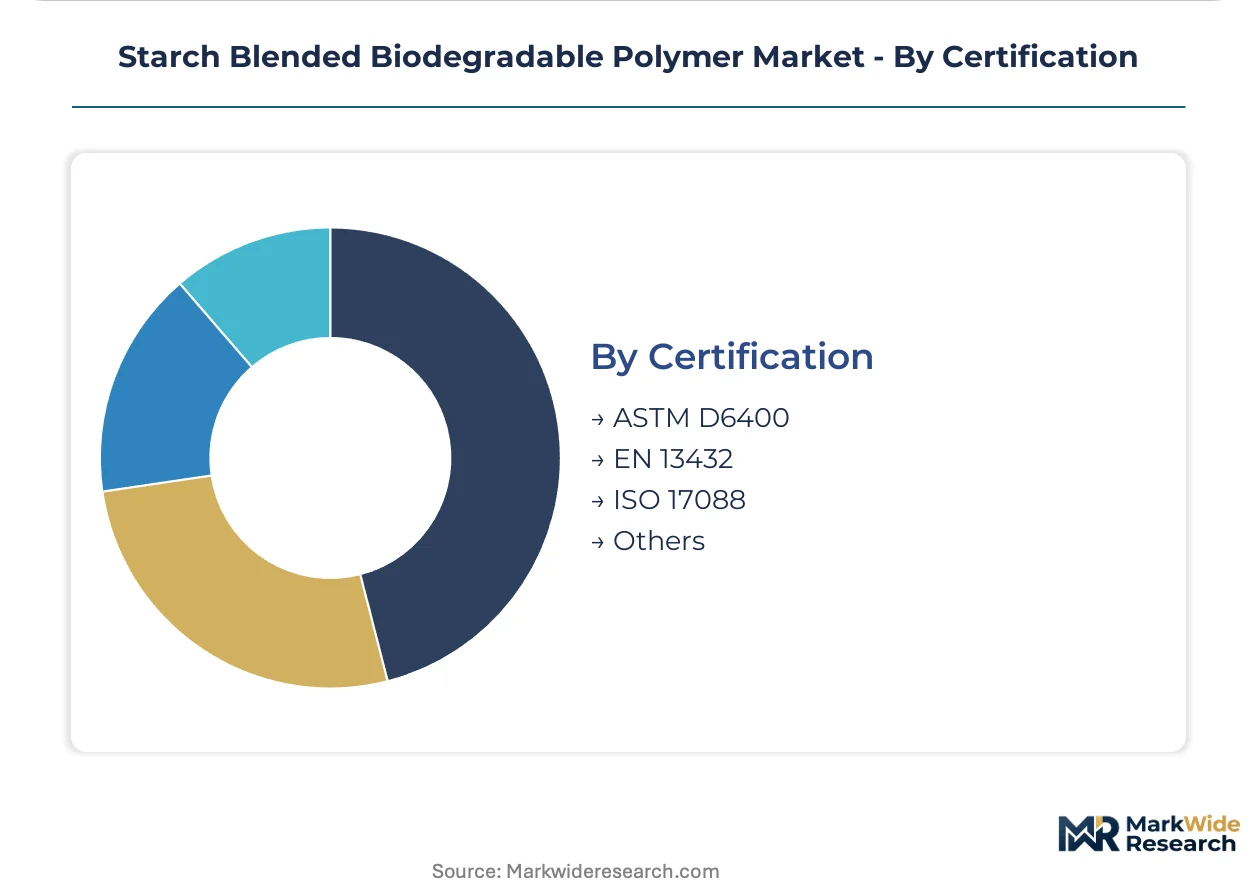
Certification:
Margin structure separates dual-certified products commanding transatlantic premiums from single-standard grades priced for regional deployment.
- ASTM D6400:US industrial composting standard governing disintegration, biodegradation, and ecotoxicity thresholds. FDA food contact notifications accompany this certification for starch-polyester laminates in US food packaging markets, with state-level mandates in California and New York accelerating qualification timelines.
- EN 13432:European equivalent mandating 90% disintegration within 12 weeks and complete biodegradation within 6 months. ECHA guidance on polymer biodegradability thresholds is forcing reformulation of starch-polyester ratios to demonstrate compliance within mandated timeframes.
- ISO 17088:International standard providing harmonized framework for biodegradable plastics specifications.
- Others:Soil-biodegradable, marine-degradable, and home composting certifications addressing niche end-of-life pathways.
EN 13432 holds the largest certified volume base. Dual ASTM D6400 and EN 13432 qualification climbs fastest as compounders invest in parallel testing protocols for transatlantic market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compounders in Italy and the Netherlands produce the majority of certified formulations, while consumption concentrates in Germany, France, and the United States where food packaging chains enforce strict compostable procurement mandates.
United States
California and New York state mandates on single-use plastics are accelerating substitution timelines for certified compostable food service items. The FDA maintains food contact notification requirements for starch-polyester laminates in domestic packaging markets. Quick-service restaurant supply chains in the Midwest and Southeast are consolidating supplier panels around three pre-qualified material specifications.
Germany
Industrial composting infrastructure buildouts in Bavaria and North Rhine-Westphalia are closing end-of-life gaps that previously undermined certification credibility. The EU Single-Use Plastics Directive mandates phase-out of conventional plastic cutlery across all member states. Fresh produce packaging chains in the Rhine-Ruhr metropolitan region specify thermoplastic starch grades for short-shelf-life applications.
Italy
Novamont's integrated fermentation and polymerization assets in Piedmont supply Mater-Bi formulations that dominate domestic retail bag specifications. EN 13432 certification requirements under EU regulation shape material eligibility for consumer goods distribution. Agricultural mulch film demand in Emilia-Romagna favors starch-PHA blends where soil-biodegradable certification creates premium positioning.
Netherlands
Dutch specialty vegetable growers specify starch-PHA blends where manual plastic retrieval costs exceed material premiums. ECHA guidance on polymer biodegradability thresholds is forcing reformulation of starch-polyester ratios for EU market access. Compounders in the Randstad maintain granule inventory positions to serve mid-sized packaging converters lacking dedicated regulatory affairs capacity.
France
REACH restrictions on persistent microplastics in consumer goods are tightening material eligibility for personal care and home cleaning brands with EU distribution. The national packaging waste extended producer responsibility scheme incentivizes certified compostable alternatives in food service applications. Industrial composting facility operators in Île-de-France are standardizing feedstock acceptance protocols to reduce batch rejection risk.
Starch Blended Biodegradable Polymer Market Key Industry Players
The competitive structure tilts toward integrated compounders with captive fermentation assets and established certification dossiers. European suppliers concentrate around proprietary starch-polyester formulations, while North American players emphasize PLA-starch hybrid platforms for thermoformed applications. Two strategic archetypes dominate: vertically integrated specialists controlling fermentation through compounding, and polymer majors leveraging existing resin infrastructure for tailored alloy supply. Capacity expansion and dual-standard certification investment represent the primary competitive moves as compounders navigate parallel ASTM D6400 and EN 13432 testing requirements.
Within the integrated specialist tier, Novamont S.p.A. and NatureWorks LLC exemplify divergent geographic anchoring strategies for compostable polymer supply. BASF SE occupies a position representing polymer major participation through tailored starch-polyester alloys for flexible film converters. These three entities collectively illustrate the certification-driven segmentation separating European industrial composting specialists from North American food service material platforms.
| Leading Market Players |
|---|
| TotalEnergies Corbion |
| Biome Technologies plc |
| BASF SE |
| Cargill Incorporated |
| PTT Global Chemical |
| Novamont S.p.A. |
| Danimer Scientific |
| Plantic Technologies |
| NatureWorks LLC |
| Others |
Cost & Logistics Intelligence
Captive fermentation assets in Novamont's Piedmont complex and NatureWorks' Blair facility anchor both supply security and pricing power for certified compostable formulations, insulating integrated compounders from maize starch feedstock volatility that squeezes margin at non-integrated rivals.
Pricing Analysis
Margin tightening in dual-certified grades reflects parallel ASTM D6400 and EN 13432 testing burdens that extend qualification cycles. Pricing stratifies across premium dual-certified, standard single-standard, and economy industrial-composting-only tiers. Price differentiation rests on certification depth and captive starch supply. Cost-down pressure on thermoplastic starch accelerates because German fresh produce chains prioritize unit economics over barrier performance. Agricultural mulch buyers prove least price-sensitive, accepting premiums for soil-biodegradable certification.
Supply Chain Analysis
Dual-sourcing requirements from California quick-service restaurant chains and Dutch retail consolidators mandate second-source qualification for Mater-Bi and PLA-starch formulations. Supply concentrates in Italy, the Netherlands, and the United States. Raw material dependencies include maize starch, potato starch, and glycerol plasticizers. Commodity price volatility in agricultural feedstocks threatens compounder margins without hedging instruments. Distribution runs through granule resale to converters with extrusion capacity, though pre-converted film roll stock gains share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EN 13432 certification dossiers create barrier-to-entry moats that reward compounders with established regulatory affairs capacity.
For Market Incumbents: Cement dual-standard certification leadership by accelerating parallel ASTM D6400 and EN 13432 testing protocols before mid-sized rivals close capability gaps. Deepen backward integration into fermentation assets to capture margin from volatile maize starch markets. Channel control through pre-converted roll stock distribution defends position against compounder bypass by film converters. For New Entrants and Emerging Players: Marine-degradable PHA-starch hybrid technology offers white-space entry where industrial composting infrastructure remains absent. Target agricultural mulch specifications in Italian and Dutch specialty vegetable segments where soil-biodegradable certification commands premiums. Pursue direct brand owner relationships bypassing established granule distribution channels. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by polymer majors seeking compostable platform assets. Long-term viability favors vertically integrated specialists with captive fermentation and established certification dossiers. Watch industrial composting facility buildout rates in target geographies as inflection indicator for certification credibility.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Parallel ASTM D6400 and EN 13432 testing unlocks transatlantic procurement from California and German food packaging chains. |
| Backward Integration into Fermentation | Captive starch supply insulates compounder margins from agricultural commodity volatility affecting non-integrated rivals. |
| Pre-Converted Film Distribution | Direct roll stock supply to brand owners captures margin held by granule resellers and reduces converter capital barriers. |
| PHA-Starch Hybrid Development | Marine-degradable formulations open segments where industrial composting infrastructure remains undeveloped. |
| Regional Compounding Capacity Expansion | Localized production in Bavaria and North Rhine-Westphalia closes logistics gaps for German fresh produce packaging demand. |
Research Approach
Trade flow databases, EU regulatory filings, and SEC disclosures from listed compounders formed the secondary backbone. Primary interviews with plant managers at starch-polyester compounding facilities, procurement leads at flexible film converters, and regulatory affairs directors at certification bodies validated demand assumptions. Technical R&D directors at integrated fermentation assets provided input on formulation cost structures. Bottom-up and top-down triangulation cross-checked volume estimates against customs data and end-use consumption patterns.
Bottom-up modeling built demand from individual end-use segments across the projection horizon. Segmentation dimensions included product type, certification tier, end-use industry, and regional composting infrastructure maturity. CAGRs derived from regression analysis of historical substitution rates against regulatory mandate timelines. Forecast inputs incorporated industrial composting facility buildout schedules and EU Single-Use Plastics Directive enforcement calendars.
Several conditions sit outside the modeled scope, including home composting certification pathways and marine-degradable standards beyond ASTM D6691. Forecasts assume stable maize starch feedstock availability and continued EU funding for composting infrastructure. Deviation in agricultural commodity price volatility or regulatory enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Global Bioplastic Market
Bioplastics
Automotive Bioplastic Market
Bioplastics
Bio-PET Market
Bioplastics
Global Synthetic and Bio Based Polypropylene Market
Bioplastics
Biodegradable Disposable Tableware Market
Bioplastics
Polylactic Acid (PLA) Straws Market
Bioplastics
Compostable Phone Cases Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market
Bioplastics
Biopolymer Films Market
Bioplastics
Bioplastic Textile Market
Bioplastics
Bio-Based Succinic Acid Derivatives for Plasticizers Market
Bioplastics
Biopolymers Market
Bioplastics
Southeast Asia Bioplastics Market
Bioplastics
Synthetic and Bio-Based PMMA Polymethyl Methacrylate Size Market
Bioplastics
Biodegradable Superabsorbent Materials Market
Bioplastics
Biodegradable Plastics Market