
 Bio-Based Succinic Acid Derivatives for Plasticizers Market | 2026-2036
Bio-Based Succinic Acid Derivatives for Plasticizers Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Succinic Acid Derivatives for Plasticizers Market Insights
Automotive interiors is broadening as a priority end-use vertical for bio-based succinic acid plasticizers, displacing traditional phthalate reliance in cabin trim and seating applications. BASF SE leverages its integrated fermentation and downstream esterification capabilities to supply tier-one automotive compounders. Roquette Frères anchors its position through feedstock security from European agricultural streams. Mitsubishi Chemical Group competes across Asia-Pacific polymer markets with specialized diester and polyester grades.
Bio-based succinic acid derivatives for plasticizers comprise esterified, anhydridated, or hydroxylated compounds derived from fermentative succinic acid, typically exhibiting molecular weights between 300 and 800 g/mol and plasticizing efficiency measured by compatibility with polar polymer matrices. These materials function primarily as internal or external plasticizers, reducing glass transition temperature and enhancing flexibility in polyvinyl chloride and related thermoplastic formulations. Epoxidized esters occupy the dominant product position due to dual functionality as plasticizers and stabilizers against thermal degradation. Flexible PVC represents the fastest-growing application segment as brand owners enforce phthalate-free commitments across consumer-facing goods. Packaging manufacturers command concentrated margin pools within the end-user industry dimension, driven by sustainability scorecards from retail and food-service buyers.
REACH restrictions on Substances of Very High Concern directly constrain ortho-phthalate use in European flexible polymer applications, redirecting formulation demand toward bio-based succinic alternatives. The EPA maintains parallel scrutiny under TSCA Section 6 for high-priority chemical substitutes, while China's GB standards progressively tighten plasticizer migration limits in food-contact and childcare articles. Stakeholders must monitor regulatory harmonization between these frameworks, as divergent approval timelines for novel bio-based substances create asymmetric market access risks that favor producers with multi-jurisdictional registration capabilities.
Market Dynamics
REACH restrictions on phthalate plasticizers are compressing formulation windows for European compounders, forcing immediate substitution toward bio-based succinic acid esters across automotive and packaging supply chains.
Growth Catalysts
- REACH Substances of Very High Concern listings:ECHA's progressive ortho-phthalate restrictions are eliminating incumbent plasticizers from flexible PVC applications, redirecting formulation demand toward bio-based succinic alternatives.
- Flexible PVC automotive interiors:Cabin trim and seating manufacturers are enforcing phthalate-free material commitments, accelerating adoption of succinic acid-derived plasticizers in tier-one supply contracts.
- European agricultural feedstock streams:Dedicated starch and sugar beet supply chains are securing fermentation feedstock for integrated producers, reducing raw material cost volatility versus petrochemical inputs.
Market Restraints
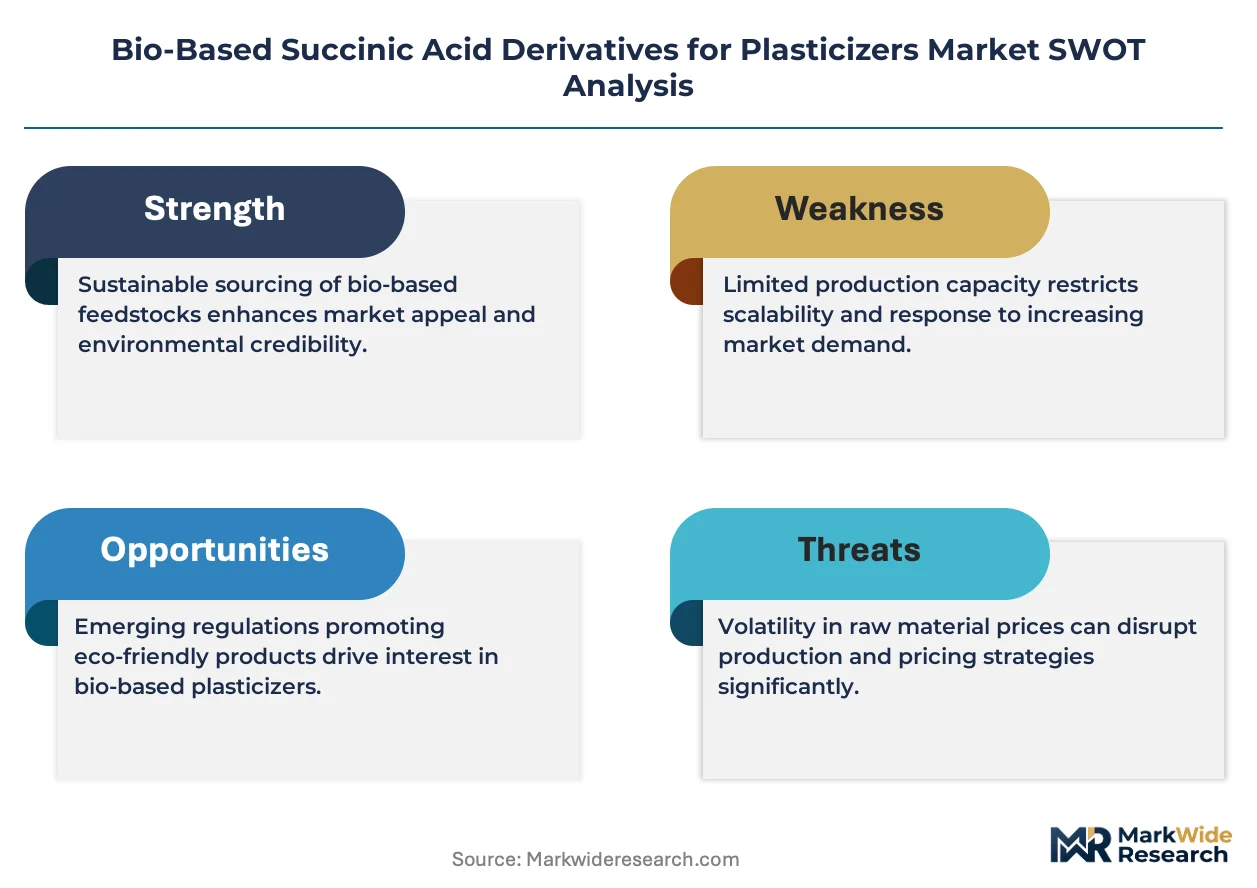
- Fermentation scale-up economics:Capital intensity for commercial-scale bioreactors exceeds comparable petrochemical esterification infrastructure, limiting new entrant participation.
- Enzyme and catalyst supply concentration:Specialized biocatalyst production concentrates among a handful of European and North American suppliers, creating input bottlenecks for derivative manufacturers.
- Performance gaps in high-temperature applications:Bio-based succinic esters exhibit volatility limitations above 180°C processing temperatures, constraining use in certain wire and cable jacketing formulations.
Strategic Opportunities
- China's GB standard tightening:Progressive migration limit reductions in food-contact and childcare articles are opening substitution windows for bio-based alternatives in Asia-Pacific polymer markets.
- Epoxidized ester dual functionality:Products combining plasticization with thermal stabilization are capturing premium positioning in PVC processing where additive reduction delivers compounder cost savings.
- Direct brand-owner contracting:Sustainability scorecards from retail and food-service buyers are enabling bypass of traditional distributor channels for qualified bio-based suppliers.
Industry Challenges
- Multi-jurisdictional registration timelines:Divergent approval pathways between REACH, EPA TSCA Section 6, and China's MEE create asymmetric market access that favors producers with dedicated regulatory affairs capabilities.
- Fermentation contamination control:Maintaining sterile bioreactor conditions at commercial scale demands specialized process engineering talent that remains scarce across the bioplastics sector.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Succinic Acid Derivatives for Plasticizers Market |
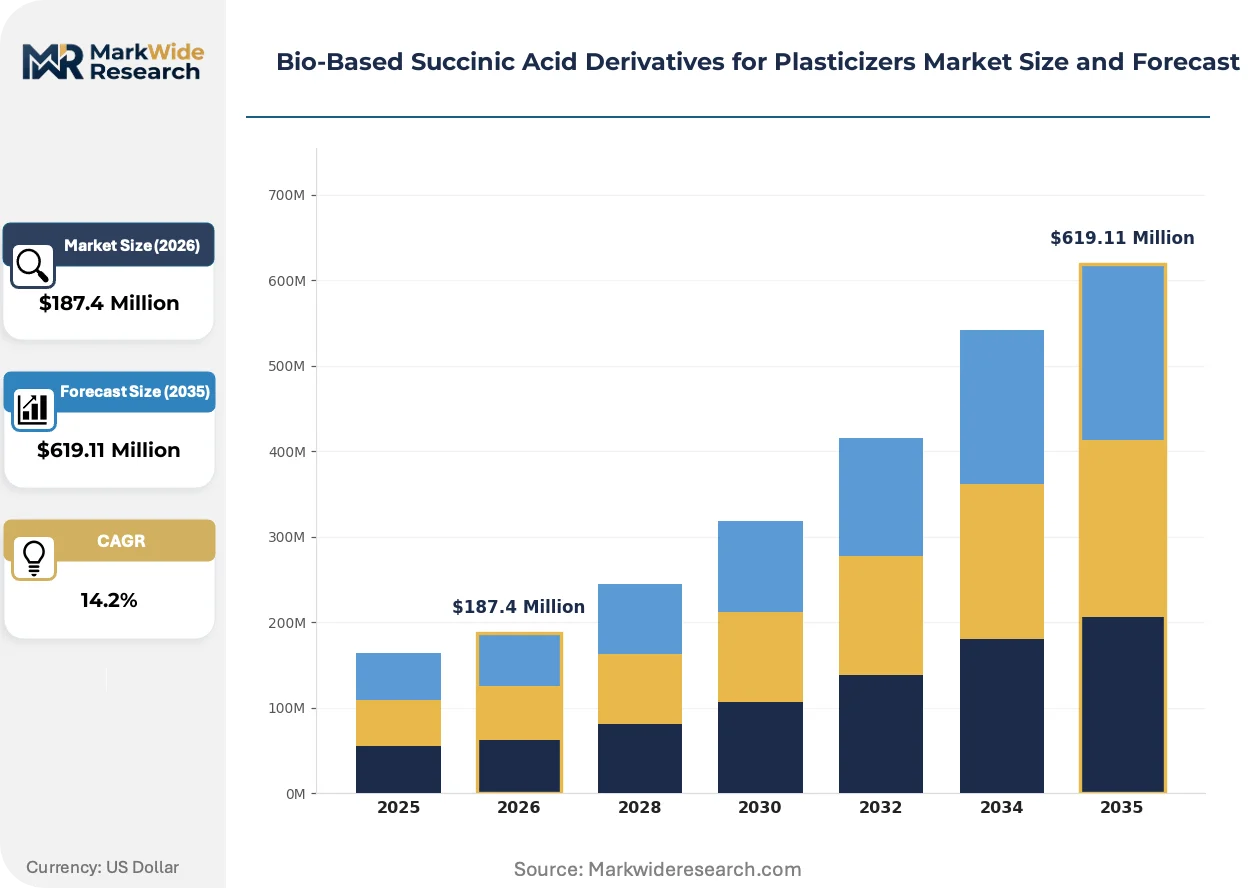
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxidized Esters, Succinic Anhydrides, Diesters, Polyesters, Hydroxylated Derivatives Application: Flexible PVC, Automotive Interiors, Adhesives & Sealants, Coatings, Footwear End User Industry: Packaging Manufacturers, Electrical & Electronics Producers, Consumer Goods, Construction Materials Distribution Channel: Direct Sales, Distributors, Online Platforms, Wholesale Suppliers, Industrial Traders |
| Companies Covered | BASF SE, Roquette Frères, Mitsubishi Chemical Group, DSM-Firmenich, Novamont, Evonik Industries AG, Lanxess, Perstorp Group, UPC Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Succinic Acid Derivatives for Plasticizers Market Trends and Innovations
Process intensification and downstream integration are compressing cost structures for bio-based succinic acid derivatives, while regulatory harmonization efforts are beginning to reduce registration friction across major polymer markets.
Continuous fermentation technology is automating succinic acid production through integrated cell retention and real-time metabolite monitoring systems. German and Dutch compounders are deploying these systems to reduce batch-to-batch variability in ester feedstock quality. The technology is automating quality control overhead that previously required dedicated analytical laboratories at each production site.
REACH Annex XIV authorization requirements are systematically removing di(2-ethylhexyl) phthalate and related ortho-phthalates from flexible polymer formulations. Compounders face sunset date pressures that compress reformulation timelines to 18-24 months for validated alternatives. Automotive interior suppliers in Germany, France, and Italy are responding by locking multi-year supply contracts with bio-based ester producers to secure qualification runway.
Brand-owner sustainability audits are replacing traditional distributor-led specification processes in European and North American packaging markets. Retail and food-service buyers now mandate direct disclosure of biobased content percentages and carbon intensity scores, bypassing compounder intermediaries. This pattern concentrates most visibly in German and Benelux markets where private-label sustainability commitments have advanced furthest.
Bio-Based Succinic Acid Derivatives for Plasticizers Market Segmentation
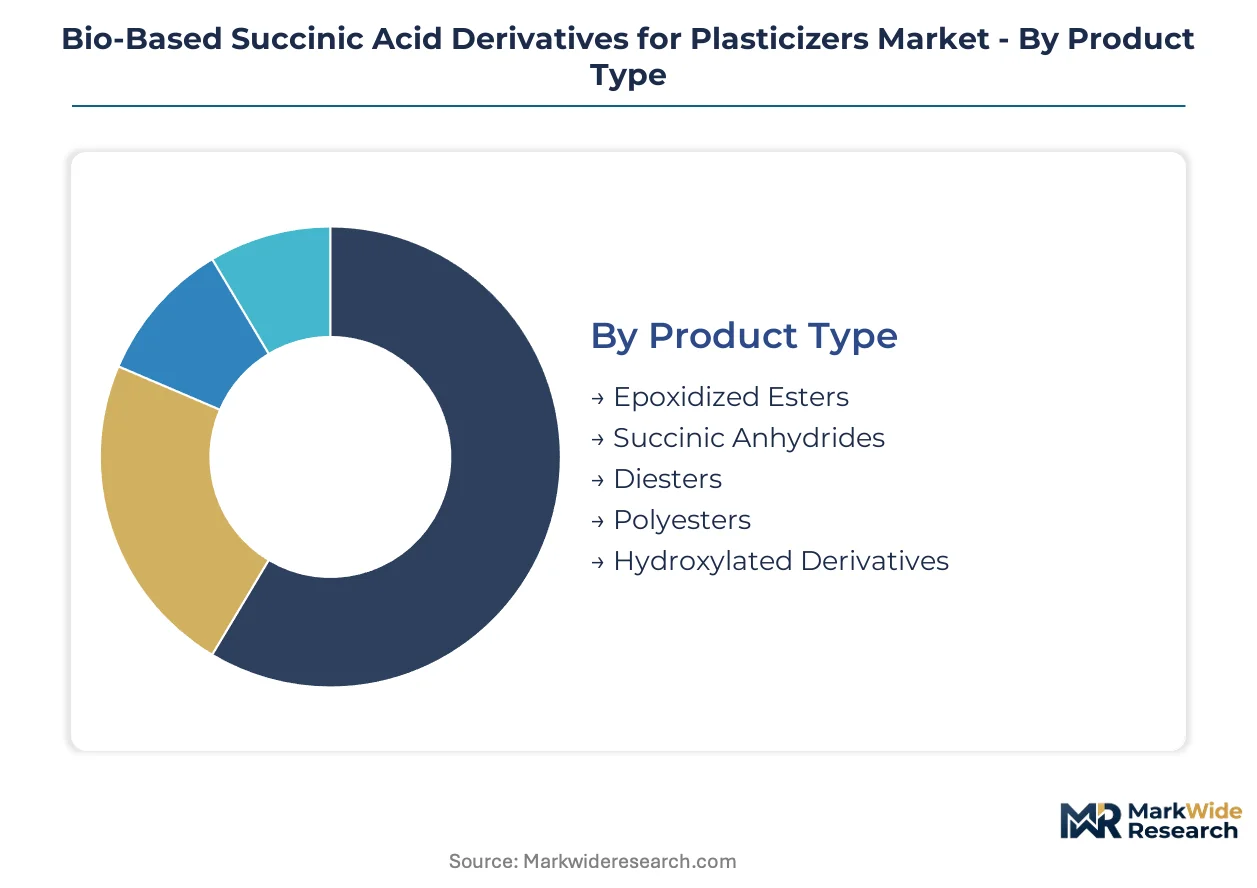
Segmentation in bio-based succinic acid derivatives reveals how formulation requirements, regulatory pressures, and supply chain configurations fragment demand across distinct buyer profiles. Each dimension captures different purchasing logics—from technical specification priorities to channel access patterns.
Product Type:
Buyers differentiate primarily by dual-function requirements versus single-purpose plasticization needs.
- Epoxidized Esters:These compounds combine plasticizing efficiency with thermal stabilization functionality through oxirane ring structures. Demand concentrates in German automotive compounding where PVC processors seek additive reduction to meet cost targets under phthalate-free mandates.
- Succinic Anhydrides:Cyclic anhydride derivatives enable reactive plasticization with polymer matrices through covalent bonding mechanisms. Chinese packaging manufacturers are driving volume for this segment as GB standard migration limits tighten on conventional plasticizers in food-contact applications.
- Diesters:Simple ester structures derived from fermentative succinic acid and linear alcohols provide cost-competitive alternatives to adipate plasticizers.
- Polyesters:Higher molecular weight oligomeric structures offer permanence and low volatility for demanding flexible PVC applications.
- Hydroxylated Derivatives:Terminal hydroxyl functionality enables polyurethane integration and specialty coating plasticization.
Volume sits with Epoxidized Esters; growth tilts toward Succinic Anhydrides.
Application:
Processing temperature tolerance and regulatory exposure determine application selection priorities.
- Flexible PVC:The dominant application segment spans film, sheet, and injection-molded formulations where glass transition depression remains the primary functional requirement. Packaging converters in the United States are expanding procurement of bio-based alternatives as EPA TSCA Section 6 scrutiny intensifies on ortho-phthalate substitutes.
- Automotive Interiors:Cabin trim, seating, and dashboard applications demand low-fogging, low-odor plasticizers with thermal stability above 120°C service temperatures. Tier-one suppliers in Germany and France are locking multi-year supply contracts to secure qualification runway ahead of REACH sunset dates.
- Adhesives & Sealants:Pressure-sensitive and construction adhesive formulations require tack retention and peel strength compatibility.
- Coatings:Film-forming flexibility in waterborne and solvent-borne systems drives hydroxylated derivative demand.
- Footwear:Sole and upper applications prioritize abrasion resistance and cold-flex performance.
Revenue concentrates in Flexible PVC; Automotive Interiors is climbing the fastest.
End User Industry:
Sustainability audit intensity and margin structure differentiate procurement patterns across verticals.
- Packaging Manufacturers:Food-contact film and container producers face the most aggressive sustainability scorecard requirements from retail and food-service brand owners. German and Benelux markets show the most advanced private-label commitments driving direct supplier contracting.
- Electrical & Electronics Producers:Wire and cable jacketing, plus consumer electronics housings, demand high-temperature performance that bio-based esters struggle to meet above 180°C processing thresholds.
- Consumer Goods:Toys, childcare articles, and personal care packaging fall under strict migration limit regulations.
- Construction Materials:Flooring, wall coverings, and roofing membranes prioritize cost position over biobased content certification.
Margin pools concentrate with Packaging Manufacturers; Construction Materials offers the steepest expansion trajectory as building codes evolve.
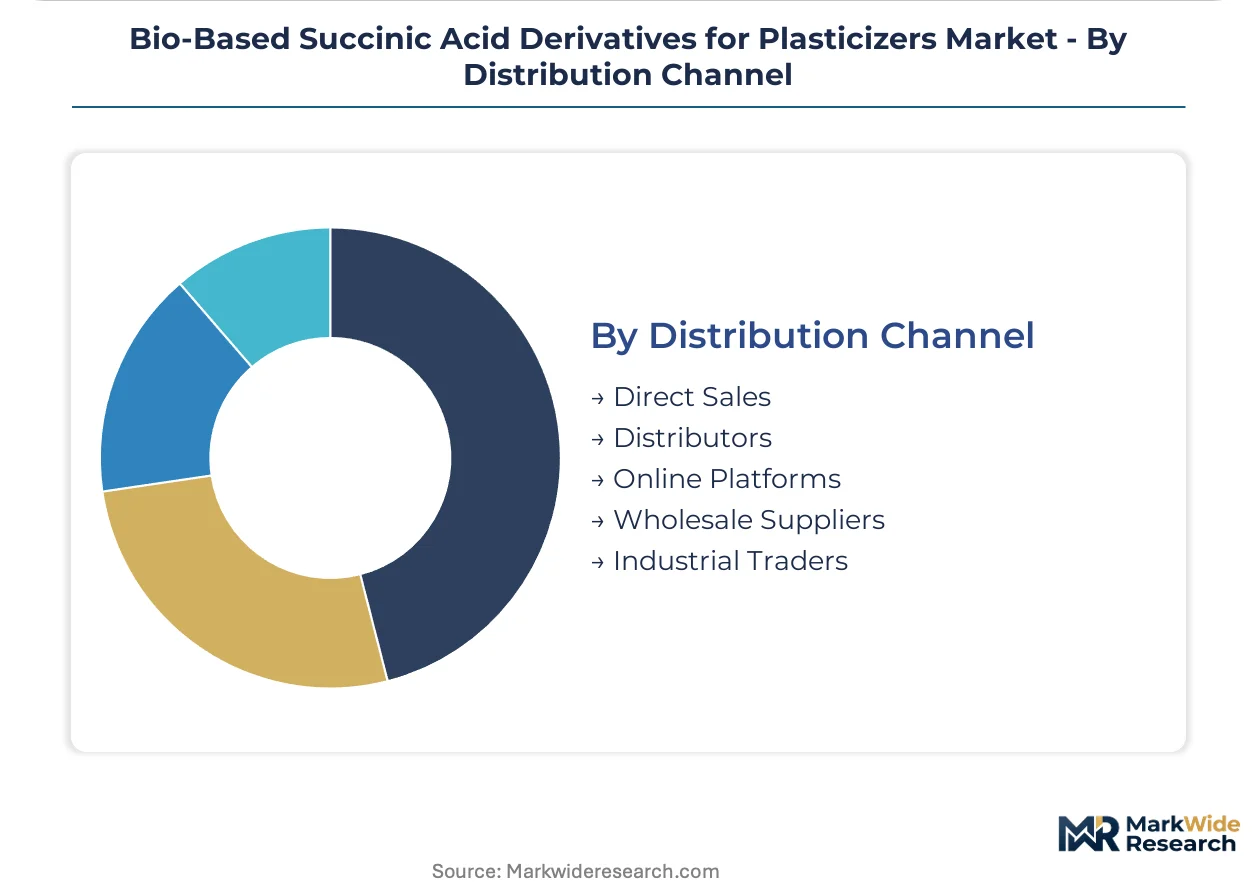
Distribution Channel:
Customer scale and qualification complexity determine channel selection economics.
- Direct Sales:Large polymer compounders and automotive tier-ones negotiate multi-year supply agreements with integrated producers like BASF SE and Roquette Frères. These relationships bypass distributor markups while locking fermentation capacity.
- Distributors:Regional chemical distributors serve mid-size compounders lacking dedicated regulatory affairs capabilities for bio-based substance registration.
- Online Platforms:Digital procurement channels are emerging for standardized diester and polyester grades in lower-volume applications.
- Wholesale Suppliers:Bulk material handlers aggregate demand from small packaging converters.
- Industrial Traders:Spot market liquidity for fermentation-derived esters remains limited due to batch consistency requirements.
Transaction value concentrates in Direct Sales; Online Platforms are gaining share fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical parks in Ludwigshafen, Rotterdam, and Shanghai are concentrating fermentation capacity and downstream esterification infrastructure for bio-based succinic acid derivatives.
Germany
Automotive tier-one suppliers in Baden-Württemberg and Bavaria are locking multi-year supply contracts ahead of REACH sunset dates for ortho-phthalates. ECHA's Annex XIV authorization requirements are systematically eliminating incumbent plasticizers from flexible PVC formulations. The Ludwigshafen chemical cluster anchors integrated production combining agricultural feedstock processing with polymer-grade ester output.
United States
Packaging converters in the Midwest and Southeast are expanding procurement of bio-based alternatives as EPA TSCA Section 6 scrutiny intensifies on phthalate substitutes. The EPA maintains parallel regulatory pressure to European REACH frameworks. Gulf Coast petrochemical corridors are retrofitting fermentation assets to capture migrating demand from restricted conventional plasticizers.
China
GB standard migration limit reductions in food-contact and childcare articles are opening substitution windows across Pearl River Delta manufacturing zones. The Ministry of Ecology and Environment progressively tightens enforcement through updated compliance protocols. Yangtze River Delta polymer compounders are qualifying succinic anhydride derivatives for export-oriented packaging supply chains.
Netherlands
Rotterdam port logistics and Antwerp chemical corridor integration are securing feedstock flows for European bio-based plasticizer production. EU Green Deal bioeconomy funding is accelerating capital deployment into fermentation scale-up projects. Dutch compounders are leveraging direct EU market access to serve German automotive supply chains with qualified ester grades.
France
Roquette Frères anchors production through dedicated starch and sugar beet supply chains in northern agricultural regions. EFSA food-contact approvals for bio-based esters are streamlining market access against conventional alternatives. Paris-based brand owners are enforcing sustainability scorecards that bypass traditional distributor channels for qualified suppliers.
Bio-Based Succinic Acid Derivatives for Plasticizers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated fermentation-to-ester producers commanding premium positioning against toll-processing compounders. Market structure tilts toward consolidation among multi-jurisdictional registrants capable of navigating REACH, EPA TSCA, and China MEE approval pathways simultaneously. Three archetypes dominate: agricultural-integrated fermentation specialists, petrochemical majors with bioplastics diversification units, and regional esterification houses dependent on third-party succinic acid feedstock. Competitive moves concentrate on backward integration into captive fermentation capacity and strategic partnerships with automotive OEMs for qualification runway.
Among European agricultural-integrated producers, BASF SE and Roquette Frères exemplify the fermentation-to-derivative model, while Mitsubishi Chemical Group occupies a position representing Asia-Pacific polymer market specialization. These three entities anchor the competitive landscape through distinct geographic and supply chain configurations rather than overlapping territorial contestation.
| Leading Market Players |
|---|
| BASF SE |
| Roquette Frères |
| Mitsubishi Chemical Group |
| DSM-Firmenich |
| Novamont |
| Evonik Industries AG |
| Lanxess |
| Perstorp Group |
| UPC Technology Corporation |
| Others |
Pricing and Supply Chain Analysis
REACH Annex XIV sunset dates for ortho-phthalates gate qualified supply access and premium-tier pricing power for fermentation-derived ester producers serving German automotive compounders. Buyers without multi-year qualification runway face compressed formulation windows and elevated spot pricing for approved bio-based alternatives.
Pricing Analysis
Lead-time-driven pricing stratification rewards contract commitments with 12-18 month offtake agreements, while spot inventory trades at substantial discounts due to batch consistency risks. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered epoxidized esters from unregistered diester grades and toll-processed commodity alternatives. Cost compression in standard-tier diesters is intensifying because Roquette Frères and BASF SE have expanded fermentation capacity. Small packaging converters in Southern Europe exhibit the highest price sensitivity, whereas German tier-one automotive suppliers prioritize qualification security over unit economics.
Supply Chain Analysis
Logistics and freight costs from Rotterdam-Antwerp chemical corridors to German compounding sites add 8-12% to delivered ester prices, favoring integrated producers with captive rail and barge terminals. Supply concentrates in Germany, the Netherlands, and France where agricultural feedstock processing anchors fermentation capacity. Raw material flows draw from European starch and sugar beet streams, specialized biocatalyst enzymes, and C4-C8 linear alcohol feedstocks. Single-source vulnerability concentrates in biocatalyst supply where European enzyme houses control commercial-scale production. Distribution runs through direct sales relationships for large compounders and regional chemical distributors for mid-tier buyers lacking regulatory affairs capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous fermentation technology is displacing batch bioreactor systems, compressing capital intensity and enabling cost-competitive scale against petrochemical esterification.
For Market Incumbents: Hedge against phthalate substitution completion by locking multi-year supply contracts with automotive OEMs before REACH sunset dates eliminate incumbent plasticizers entirely. Prioritize backward integration into captive enzyme production to reduce biocatalyst supply concentration risk. Expand fermentation capacity in the Ludwigshafen-Rotterdam corridor to capture migrating demand from restricted conventional plasticizers. For New Entrants and Emerging Players: The mid-tier price-point gap between premium epoxidized esters and economy diester grades offers white-space entry for hybrid polyester structures with partial thermal stabilization. Target Chinese packaging manufacturers facing GB standard migration limit tightening as the most penetrable geography. Pursue toll-processing partnerships with established fermentation houses to bypass capital-intensive bioreactor construction. For Investors and Strategic Acquirers: ECHA authorization timeline acceleration for bio-based substances is the leading indicator that multi-jurisdictional registration capabilities will command acquisition premiums. Long-term viability favors integrated fermentation-to-derivative producers with established automotive qualification runway. Watch for Ministry of Ecology and Environment enforcement protocol updates in China as the signal for Asia-Pacific substitution window expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive succinic acid supply reduces feedstock cost volatility for ester producers. |
| Long-term Supply Agreement with Automotive OEM | Multi-year contracts secure qualification runway ahead of REACH sunset dates. |
| Joint Venture with Biocatalyst Supplier | Enzyme production partnerships mitigate single-source supply concentration risk. |
| Green Manufacturing Transition | Agricultural feedstock processing aligns with EU Green Deal bioeconomy funding. |
| Capacity Expansion in Yangtze River Delta | Chinese production footprint captures GB standard-driven substitution demand. |
Research Methodology
Document review covered ECHA authorization databases, EPA TSCA Section 6 dockets, Chinese GB standard migration limit protocols, and customs trade flows for succinic acid derivatives, complemented by interviews with polymer compounders, automotive tier-one procurement directors, fermentation plant managers, and regulatory affairs specialists at bio-based chemical producers. Secondary validation drew from SEC 10-K filings of listed chemical companies, Cefic plastics industry reports, and EU Green Deal bioeconomy funding disclosures. Bottom-up demand modeling triangulated against top-down market sizing from production capacity announcements.
Segment-level projections across product type, application, and end-user industry dimensions were generated through elasticity-adjusted substitution modeling over the projection horizon. CAGRs were derived from phthalate displacement rates under REACH and parallel regulatory frameworks, weighted by automotive and packaging sector procurement cycle timing. Forecast inputs incorporated fermentation yield improvements from continuous bioreactor technology and enzyme cost curves from supplier concentration analysis.
Underlying measurement precision varies by segment; flexible PVC and automotive interior applications carry tighter precision than adhesives and coatings due to more concentrated buyer identification. Forecasts reflect assumptions about regulatory harmonization timelines and fermentation scale-up economics that could revise if ECHA accelerates authorization schedules or biocatalyst supply disruptions persist. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
North America Polylactic Acid (PLA) Market
Bioplastics
Biobased Biodegradable Plastics Market
Bioplastics
Asia-Pacific Bio Plasticizers Market
Bioplastics
Biodegradable Plastics Market
Bioplastics
Automotive Bioplastic Market
Bioplastics
US Bioplastics Market
Bioplastics
Bioplastic Textile Market
Bioplastics
Biopolymers Market
Bioplastics
Global Bio-Polylactic Acid (PLA) Market
Bioplastics
Polylactic Acid (PLA) Straws Market
Bioplastics
China Bioplastics Market
Bioplastics
Biodegradable Disposable Tableware Market
Bioplastics
Compostable Phone Cases Market
Bioplastics
Brazil Bioplastics Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Starch Blended Biodegradable Polymer Market