
 Biodegradable Superabsorbent Materials Market | 2026-2036
Biodegradable Superabsorbent Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Superabsorbent Materials Market Intelligence
Specialty chemical producers' expansion into bio-based polymers is restructuring the supply landscape for biodegradable superabsorbent materials. BASF SE leverages its extensive chemical synthesis expertise to develop novel starch-based and cellulose-based polymers. Meanwhile, Evonik Industries AG specializes in high-performance materials for hygiene applications. Nippon Shokubai Co., Ltd. competes through its large-scale production capacity and established distribution networks in Asia.
Biodegradable superabsorbent materials are polymers capable of absorbing and retaining extremely large amounts of a liquid relative to their own mass. Unlike conventional polyacrylates, these materials, often derived from polysaccharides like starch or cellulose, are designed to decompose through microbial action into water, carbon dioxide, and biomass. Starch-based and cellulose-based products currently dominate the market due to cost-effectiveness and raw material availability. While hygiene products constitute the largest application segment, agricultural enhancers represent the fastest-growing category, valued for improving soil water retention.
Regulatory frameworks like the EU's REACH regulation, the US EPA's Safer Choice program, and China's GB standards for disposable hygiene products are critical. These mandates govern chemical safety, biodegradability claims, and market access, compelling manufacturers to substitute traditional superabsorbent polymers. Future competitiveness will hinge on securing stable supply chains for bio-based feedstocks and achieving cost parity with petroleum-based alternatives.
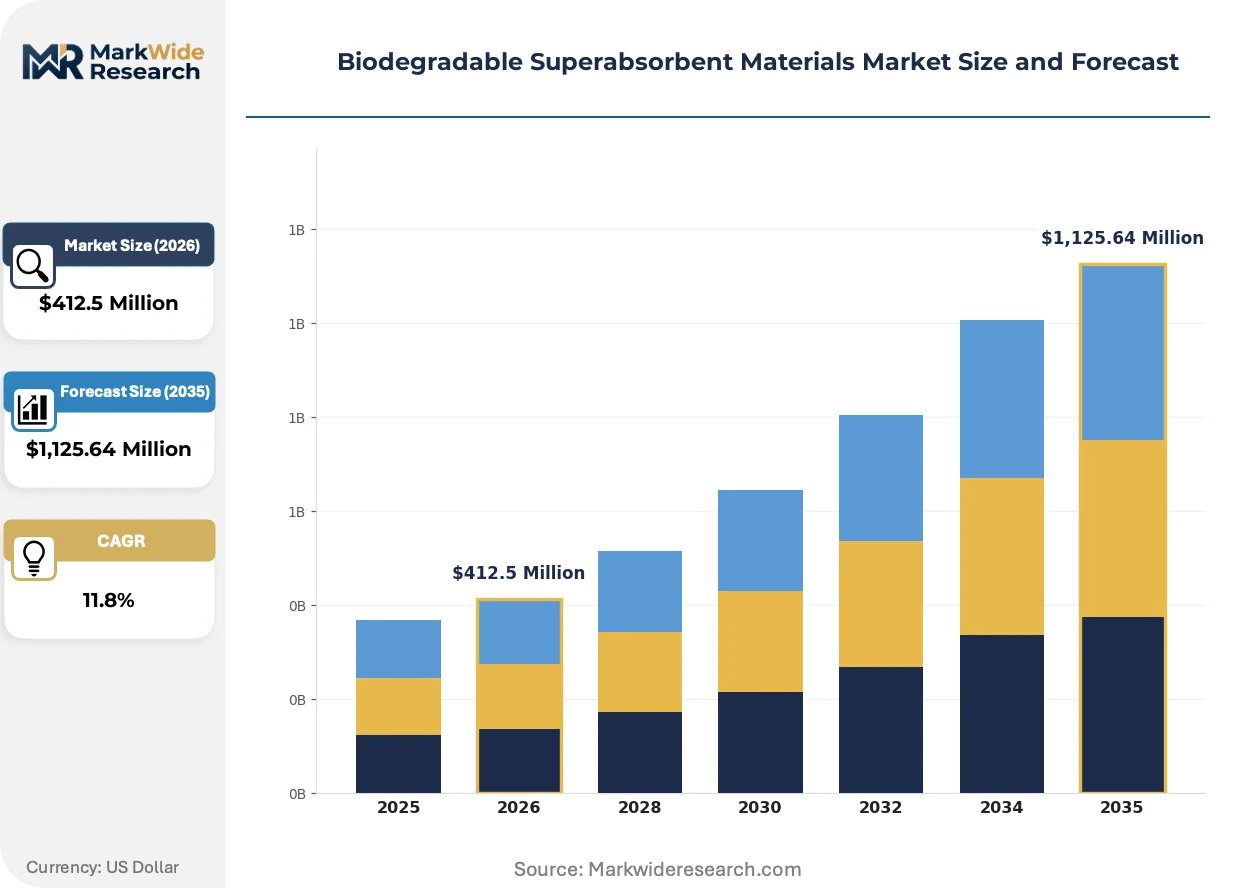
Market Dynamics
The fundamental market dynamic is the regulatory-driven substitution of petroleum-based superabsorbent polymers. Mandates targeting single-use plastics, particularly in Europe, are compelling personal care and agricultural product manufacturers to seek viable, biodegradable alternatives derived from renewable feedstocks.
Growth Catalysts
- Regulatory Mandates:The EU Green Deal and its associated directives on single-use plastics directly incentivize the switch from conventional polyacrylates to biodegradable alternatives in disposable goods.
- Consumer Goods Sector Demand:Major manufacturers of diapers, adult incontinence products, and sanitary napkins are actively reformulating products to meet consumer preferences for sustainable and "green" materials.
- Agricultural Sector Expansion:Use as a soil amendment to improve water retention is a critical catalyst, especially in regions facing water scarcity, opening a high-growth application beyond hygiene.
Market Restraints
- Cost Disparity:The production cost for starch-based and cellulose-based superabsorbents remains higher than for mass-produced synthetic polyacrylates, challenging price-sensitive applications.
- Performance Limitations:Certain biodegradable polymers exhibit lower absorption capacity and retention under load compared to their petroleum-based counterparts, limiting use in high-performance applications.
- Feedstock Supply Volatility:Reliance on agricultural inputs like corn starch and cellulose creates exposure to price fluctuations and supply chain disruptions driven by weather, crop yields, and food market competition.
Strategic Opportunities
- Medical and Healthcare Applications:Development of biodegradable superabsorbents for high-value uses like advanced wound dressings and disposable surgical pads presents a significant opportunity.
- Hybrid Material Development:Formulating polymers that blend bio-based materials with recycled synthetics can provide a cost-effective, transitional solution for manufacturers hesitant to fully switch.
- Emerging Market Penetration:Expanding into markets like India and Brazil, where a growing middle class is increasing demand for hygiene products, offers substantial volume growth potential.
Industry Challenges
- Production Line Adaptation:Integrating new biodegradable materials into existing high-speed converting machinery for hygiene products often requires costly modifications and extensive process re-validation.
- Standardization and Labeling:The lack of harmonized global standards for biodegradability testing and certification, such as those from ISO, leads to market confusion and complicates international trade.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Superabsorbent Materials Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,125.64 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch-Based, Cellulose-Based, Chitosan-Based, Polyvinyl Alcohol-Based Application: Hygiene Products, Agricultural Enhancers, Water Retention Systems, Packaging Absorbents End User: Personal Care Manufacturers, Crop Producers, Environmental Agencies, Packaging Companies Form: Powder, Granules, Films, Fibers, Sheets |
| Companies Covered | Itaconix Corporation, Evonik Industries AG, LG Chem, Ecovia Renewables, Qingdao Soco New Material Co., Ltd., BASF SE, Archer Daniels Midland Company, ZymoChem Inc., Nippon Shokubai Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Superabsorbent Materials Market Strategic Shifts & Innovations
Material science innovation is converging with stringent environmental policies. This dynamic compels producers to re-evaluate polymer chemistry, feedstock sourcing, and end-of-life performance to meet new market demands for sustainable absorbents, particularly within the personal care sector.
AI-powered material informatics platforms are accelerating polymer discovery. Chemical producers adopt these tools to simulate the properties of novel starch and cellulose derivatives, predicting absorbency and decomposition rates. This process is automating the traditionally lengthy R&D cycle, enabling faster iteration and reducing the time to market for next-generation materials.
The US EPA's Safer Choice program is influencing material selection for consumer products sold in North America. This standard helps consumers identify products with safer chemical ingredients, pressuring manufacturers to substitute potentially harmful substances in superabsorbent polymers. The hygiene product segment is most affected, using the certification to build brand trust.
A shift toward certification-driven sourcing is evident among large consumer goods companies. Procurement decisions for personal care components now often mandate proof of biodegradability from bodies like TÜV Austria or DIN CERTCO. This trend is most prominent in the European Union, where retail brands use these eco-labels as a key marketing differentiator.
Biodegradable Superabsorbent Materials Market Segmentation
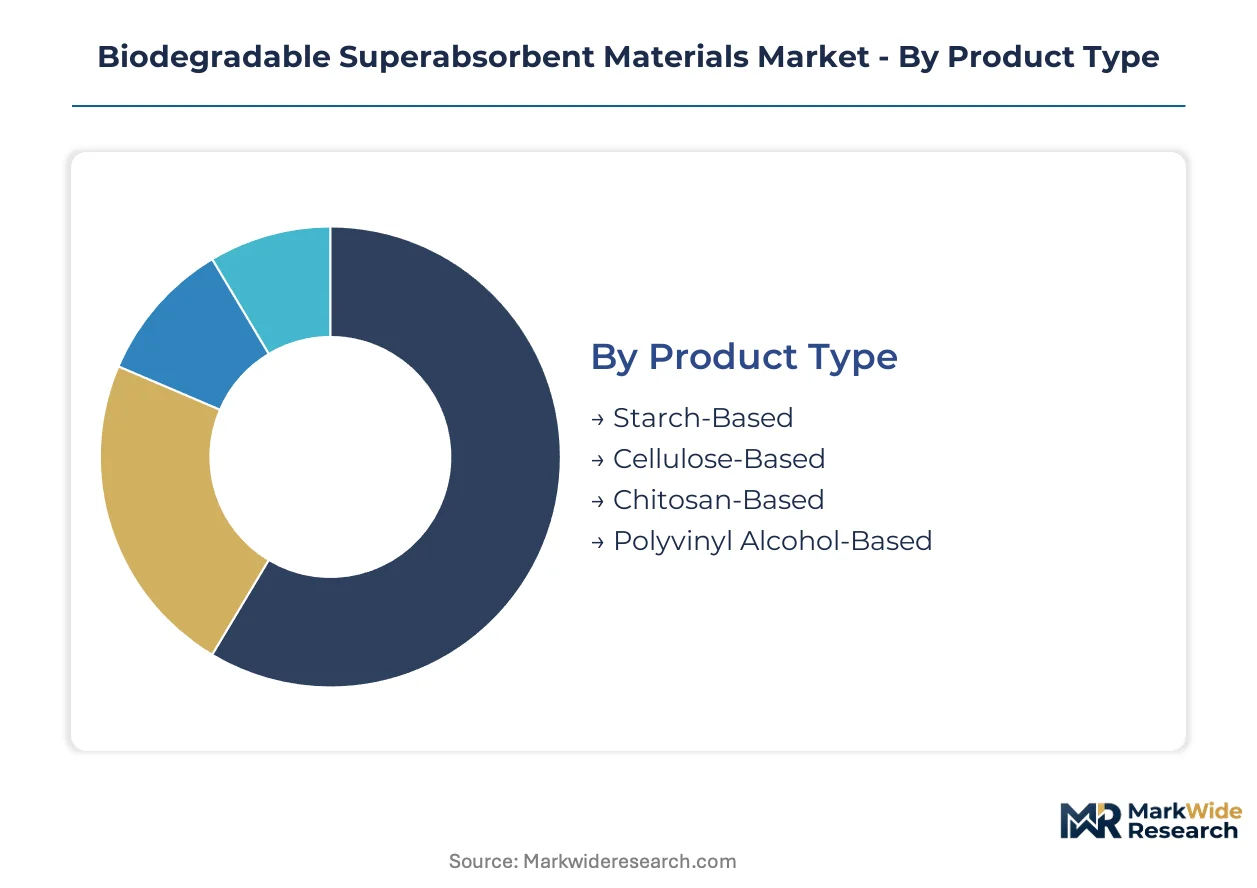
Market segmentation provides a granular view of the biodegradable superabsorbent materials industry, revealing distinct product characteristics, application areas, and end-user requirements. Understanding these segments helps identify specific growth opportunities and address unique market demands for sustainable absorbent solutions.
Product Type:
Material science advancements define the distinct product types within biodegradable superabsorbent materials.
- Starch-Based:These polymers are derived from natural starch, offering high biodegradability and broad availability. Demand concentrates in hygiene products, driven by cost-effectiveness and renewable sourcing.
- Cellulose-Based:Composed of cellulose derivatives, these materials provide robust absorbency and mechanical strength. Personal care manufacturers utilize them for diapers and sanitary napkins, seeking sustainable alternatives.
- Chitosan-Based:Chitosan-based materials, derived from chitin, offer antimicrobial properties alongside absorbency, finding use in specialized medical applications.
- Polyvinyl Alcohol-Based:Polyvinyl alcohol-based polymers are synthetic yet biodegradable, offering tunable properties for specific industrial absorbent applications.
Mature deployment sits with Starch-Based. Newer deployment is concentrated in Polyvinyl Alcohol-Based.
Application:
The diverse utility of biodegradable superabsorbent materials drives their adoption across various end-use sectors.
- Hygiene Products:This segment includes diapers, adult incontinence products, and sanitary napkins, requiring high absorption and retention. Demand is concentrating in European countries due to stringent regulations on single-use plastics.
- Agricultural Enhancers:Used as soil amendments, these materials improve water retention and nutrient delivery in agricultural settings. Crop producers in arid regions are increasing their usage to combat water scarcity.
- Water Retention Systems:Industrial and landscaping projects use water retention systems to manage water resources, particularly in green infrastructure development.
- Packaging Absorbents:Packaging companies integrate these absorbents into food packaging to control moisture and extend product shelf life.
Hygiene Products currently represent the largest volume application. Agricultural Enhancers exhibit the fastest-growing trajectory.
End User:
Different customer types drive demand for biodegradable superabsorbent materials based on their specific operational and regulatory needs.
- Personal Care Manufacturers:These companies integrate biodegradable superabsorbents into disposable hygiene items like diapers and sanitary pads. Regulatory frameworks like the EU Green Deal compel these manufacturers to reformulate products.
- Crop Producers:Farmers and agricultural enterprises utilize these materials to enhance soil water retention and reduce irrigation requirements. Regions facing water scarcity, such as parts of India and Brazil, are increasing adoption.
- Environmental Agencies:Government and non-profit environmental agencies promote and sometimes mandate the use of sustainable materials in various applications.
- Packaging Companies:Businesses involved in product packaging incorporate absorbents to protect goods from moisture damage during storage and transit.
Personal Care Manufacturers exert significant market influence through their large volume procurement. Crop Producers are expanding their material procurement for sustainable farming practices.
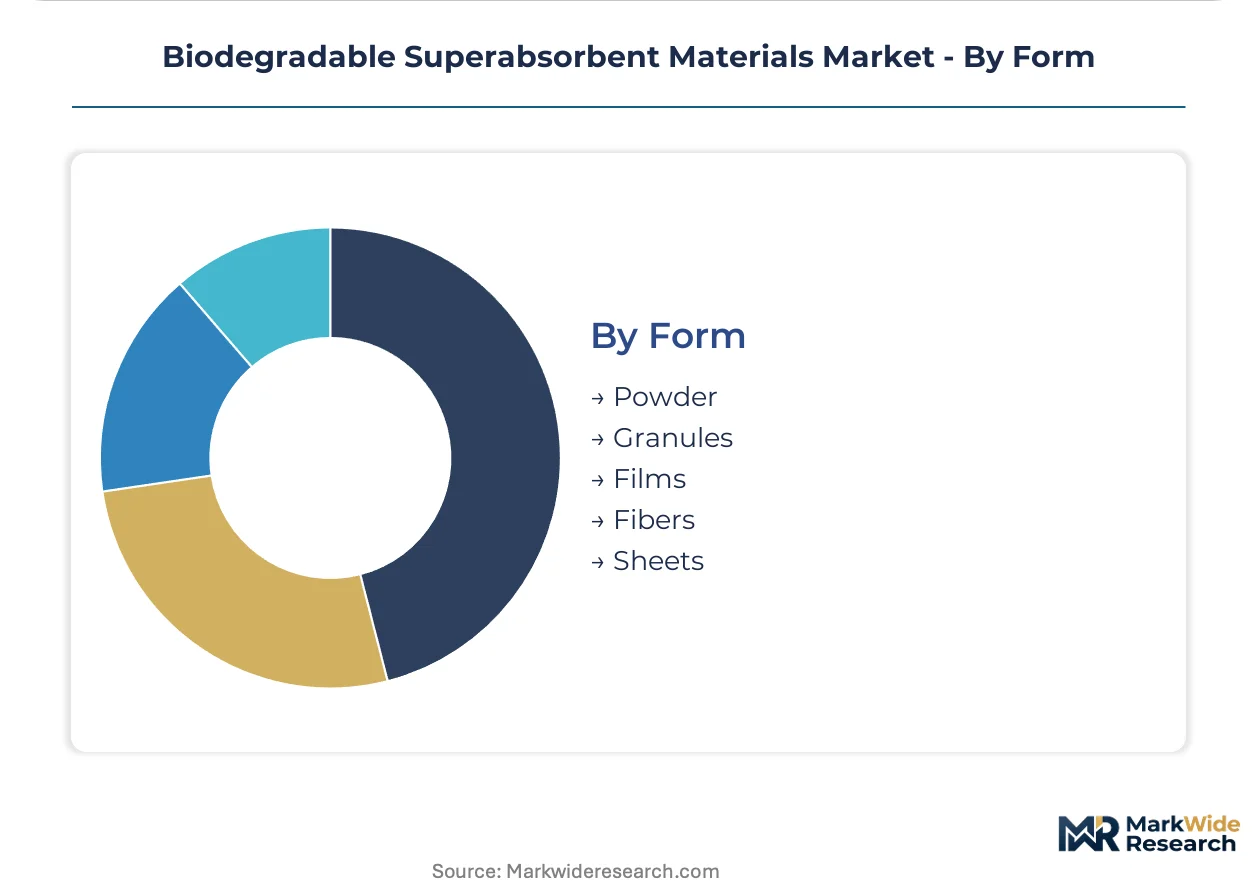
Form:
The physical form of biodegradable superabsorbent materials dictates their ease of integration and application performance.
- Powder:Powdered forms offer high surface area for rapid absorption and are easily blended into various matrices. Hygiene product manufacturers prefer this form for efficient dispersion in absorbent cores.
- Granules:Granular materials provide controlled release and are less prone to dusting, making them suitable for agricultural applications. Crop producers use granules for uniform soil distribution.
- Films:Biodegradable superabsorbent films offer flexible and thin absorbent layers for specialized packaging or medical applications.
- Fibers:Superabsorbent fibers can be woven or non-woven into textiles, providing enhanced liquid management in medical dressings or apparel.
- Sheets:Pre-formed sheets simplify integration into existing manufacturing processes, particularly for certain hygiene or packaging inserts.
Powder forms offer the most versatile integration into existing manufacturing lines. Films and Fibers enable novel product designs requiring flexible absorption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, with its vast agricultural resources, anchors the feedstock supply for bio-based superabsorbent materials. Demand for these innovative polymers is expanding across diverse applications, particularly in personal care and agriculture. This market's trajectory is heavily influenced by regional environmental policies and consumer preferences for sustainable products.
United States
Consumer goods manufacturers seek biodegradable solutions for diapers and adult incontinence products in the US market. The US EPA's Safer Choice program guides material selection, favoring chemicals with reduced environmental impact. Chemical producers in the Midwest, leveraging corn starch availability, are developing novel bio-based polymer formulations.
Germany
European demand for biodegradable superabsorbents is concentrating in Germany, driven by stringent environmental standards. The EU Green Deal and REACH regulation compel personal care brands to reformulate products. Chemical parks in Ludwigshafen and Marl are centers for R&D and production of advanced starch-based and cellulose-based polymers.
China
China presents a large consumer market for disposable hygiene products, alongside a significant agricultural sector. GB standards for disposable hygiene products are evolving, influencing material choices for manufacturers. The Yangtze River Delta region is a key hub for polymer manufacturing and distribution, serving both domestic and export markets.
India
Growing middle-class consumption drives demand for sustainable hygiene products in India. Agricultural enhancers are also gaining traction, particularly in regions facing water scarcity. Government initiatives supporting sustainable farming practices and BIS standards for consumer goods are shaping procurement decisions across the country.
Brazil
Brazil's substantial agricultural sector creates demand for soil amendments that improve water retention. The country's expanding hygiene product market also seeks more sustainable alternatives. ANVISA regulations for personal care items influence product development, with São Paulo state hosting significant chemical production and consumer goods manufacturing facilities.
Biodegradable Superabsorbent Materials Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue high-performance bio-based polymers. The market structure exhibits a tiered consolidation, with large chemical conglomerates competing alongside specialized bio-material innovators. Dominant competitive moves include capacity expansion to meet rising demand and strategic R&D investment in novel polymer chemistries.
At the scale-driven end, BASF SE and Evonik Industries AG exemplify large chemical producers with extensive R&D capabilities in bio-based polymers. Nippon Shokubai Co., Ltd. also occupies a significant position, leveraging its established production capacity and distribution networks in Asia. These companies anchor the supply of both starch-based and cellulose-based superabsorbents for global markets.
| Leading Market Players |
|---|
| Itaconix Corporation |
| Evonik Industries AG |
| LG Chem |
| Ecovia Renewables |
| Qingdao Soco New Material Co., Ltd. |
| BASF SE |
| Archer Daniels Midland Company |
| ZymoChem Inc. |
| Nippon Shokubai Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Chemical synthesis expertise, concentrated in specific industrial clusters like Germany's chemical parks, influences the cost structure of bio-based polymers, creating differentials between high-performance and commodity-grade materials. This labor cost variance impacts pricing tiers for personal care and agricultural applications.
Pricing Analysis
Warranty and service bundling primarily applies to specialized industrial absorbent formulations, not high-volume hygiene products. Transactional per-unit pricing dominates for starch-based and cellulose-based superabsorbents. Price differentiation stems from certification levels, such as TÜV Austria approval, and the material's absorption capacity under load. Pricing softness reflects cost disparity with conventional polyacrylates, particularly for price-sensitive personal care manufacturers. High-value medical applications exhibit lower price sensitivity.
Supply Chain Analysis
Regional distribution centers and a hub-and-spoke model characterize the movement of superabsorbent materials from production sites to end-users. Geographic supply concentration includes the United States for bio-based feedstocks and Germany for advanced polymer R&D and manufacturing. The supply chain draws from agricultural inputs like corn starch and cellulose. Feedstock supply volatility, influenced by weather and crop yields, presents a structural risk. Distribution runs through direct sales channels to large personal care manufacturers and specialized chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A critical bottleneck in bio-based polymer production capacity currently constrains market expansion, reinforcing pricing power for established manufacturers. This supply limitation underpins the need for strategic investment.
For Market Incumbents: Acquire specialized bio-material processing technologies to enhance in-house production capabilities for advanced starch and cellulose derivatives. Incumbents should invest in R&D for novel polymer chemistries to overcome performance limitations against petroleum-based counterparts. Securing long-term supply agreements for bio-based feedstocks in regions like the US will mitigate feedstock supply volatility. This strategy defends market position against emerging entrants and regulatory shifts favoring sustainable materials.
For New Entrants and Emerging Players: Price-point gaps exist between premium bio-based polymers and cost-effective synthetic alternatives. New entrants should target agricultural enhancers in arid regions like India and Brazil, which are less sensitive to initial cost disparities. Develop hybrid material solutions blending bio-based components with recycled synthetics to offer a transitional, cost-effective option. A go-to-market angle focusing on transparent eco-labeling and performance validation can build early brand trust.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized bio-material innovators given accelerating regulatory-driven substitution of conventional polymers. Long-term viability hinges on companies capable of scaling bio-based production and securing diverse feedstock sources. Acquisition targets should include firms with proprietary synthesis expertise or established supply chains for renewable inputs. Watch for harmonized global standards for biodegradability testing, which will unlock broader market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Augmenting production lines for bio-based polymers supports growing demand from personal care manufacturers. |
| Backward Integration | Securing direct control over bio-based feedstock sources reduces supply chain volatility for producers. |
| Green Manufacturing Transition | Implementing sustainable production processes meets EU Green Deal requirements for chemical companies. |
| Strategic Partnership | Collaborating with personal care brands accelerates product reformulation and market penetration in Europe. |
| Sustainability Repositioning | Emphasizing eco-labels like TÜV Austria certification builds consumer trust in disposable hygiene products. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews were conducted with R&D directors from chemical producers, procurement leads from personal care manufacturers, sustainability officers, and agricultural specialists. This approach combined qualitative insights with quantitative data validation. Bottom-up and top-down triangulation ensured comprehensive market sizing and segmentation across all product types.
Data-stream reconciliation across historical market trends and future demand projections informed the forecast framework. The analytical framework modeled segmentation dimensions including product type, application, end-user, form, and regional regulatory environments over the projection horizon. Compound annual growth rates were derived from a synthesis of historical performance and anticipated market drivers. Bio-based feedstock availability and regulatory implementation timelines served as key forecast inputs.
Inputs from industry reports, company disclosures, and government statistics were available through the study window; gaps in emerging market consumption data introduce uncertainty. Forecasts reflect assumptions regarding regulatory enforcement and technological advancements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Biocomposite Materials Market
Bioplastics
Bio-Degradable Polymers Market
Bioplastics
Cellulose Plastics Market
Bioplastics
Global Bio-Polylactic Acid (PLA) Market
Bioplastics
North America Bioplastics Market
Bioplastics
Southeast Asia Bio-PET Market
Bioplastics
US Bioplastics Market
Bioplastics
Biopolymers Market
Bioplastics
Global Synthetic and Bio Based Polypropylene Market
Bioplastics
Middle East Biodegradable Plastics Market
Bioplastics
Canada Bioplastics Market
Bioplastics
Bio-PET Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Global Bioplastic Market
Bioplastics
Bio-Polyamide, Specialty Polyamide and Precursors Market
Bioplastics
North America Polylactic Acid (PLA) Market