
 Global Bioplastic Market | 2026-2036
Global Bioplastic Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bioplastic Market Foresight
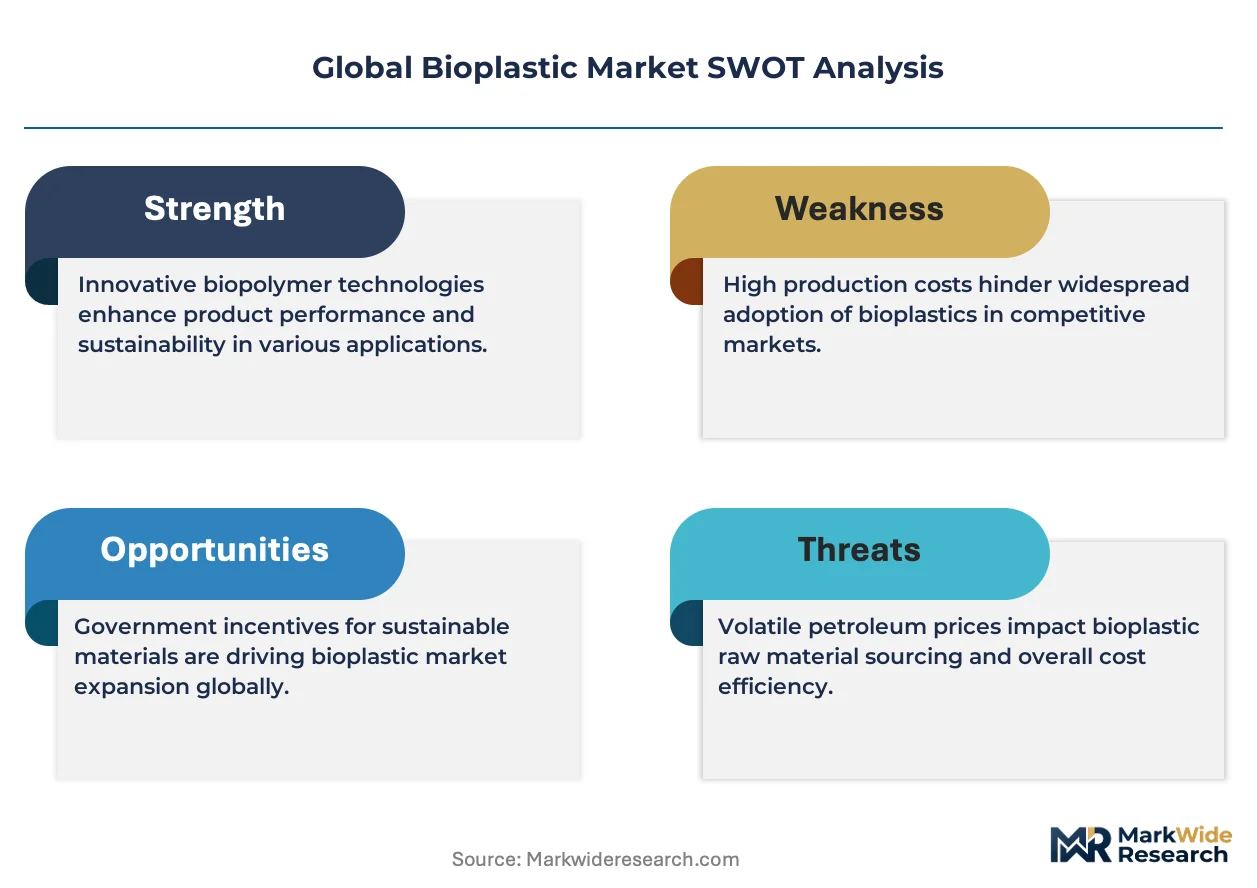
Specialty resin distribution is fragmenting as regional compounders bypass traditional petrochemical distributors to source PLA and PHA directly from producers. NatureWorks LLC leverages its Blair, Nebraska fermentation complex to sustain captive lactic acid supply for Ingeo-branded resin output. BASF SE anchors European biopolymer availability through its Ecoflex and Ecovio product lines, while TotalEnergies Corbion competes on Luminy PLA purity grades aimed at high-heat food service applications.
Bioplastics comprise polymers derived from renewable biomass sources such as corn starch, sugarcane, or cellulose, with ASTM D6866 certifying biobased carbon content through radiocarbon analysis; these materials serve as drop-in or compostable alternatives to conventional plastics in packaging, agriculture, and durable goods. PLA dominates current volume due to mature fermentation infrastructure and cost-competitive feedstock access, while PHA represents the fastest-expanding product type because marine biodegradability commands premium positioning in single-use foodware. Packaging applications concentrate the largest margin pool, though automotive components are gaining structural importance as OEMs pursue interior trim weight reduction with bio-based polyamides.
The EU Green Deal and REACH framework mandate recyclability and biobased content thresholds for plastics placed on European markets, while the U.S. FDA and USDA BioPreferred program shape food-contact approval pathways and federal procurement preferences respectively. Japan's METI has established JIS standards for biodegradable plastics that constrain export market access for uncertified producers. Stakeholders must monitor evolving composting infrastructure gaps between resin certification and actual industrial processing capacity.
Market Dynamics
The EU F-Gas Regulation and REACH framework are compressing petrochemical polymer availability while industrial composting infrastructure gaps create supply-demand mismatches across member states.
Growth Catalysts
- EU Green Deal packaging mandates:The European Commission's Single-Use Plastics Directive bans select conventional items, redirecting food service procurement toward certified compostable alternatives.
- Sugarcane feedstock expansion:Brazilian and Thai agricultural processors are securing long-term supply agreements with fermentation-based resin producers.
- Automotive lightweighting targets:OEM interior trim specifications now incorporate bio-based polyamides to meet fleet emissions standards in Germany and Japan.
Market Restraints
- Industrial composting capacity deficits:ASTM D6400-certified resins require facilities operating above 55°C, yet fewer than 200 municipal sites across the United States meet this threshold.
- Lactic acid feedstock competition:Corn starch pricing volatility ties PLA production costs to agricultural commodity swings and ethanol policy.
- Performance gaps in high-barrier applications:Oxygen transmission rates in PLA films exceed multilayer EVOH structures, limiting adoption in extended-shelf-life food packaging.
Strategic Opportunities
- Marine biodegradable foodware:PHA's ocean-degradability certification opens premium positioning in coastal tourism economies and island jurisdictions with landfill constraints.
- USDA BioPreferred federal procurement:The program's mandatory purchasing minimums for designated product categories create institutional demand anchors.
- Agricultural mulch film replacement:Soil-biodegradable standards under EN 13432 enable mechanized collection cost avoidance for specialty crop operations.
Industry Challenges
- Certification timeline compression:FDA food-contact notification reviews for novel biopolymer additives currently extend 18-24 months, delaying commercial launches.
- Composting infrastructure misalignment:Home composting claims on consumer packaging conflict with actual biodegradation rates in ambient-temperature backyard piles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bioplastic Market |
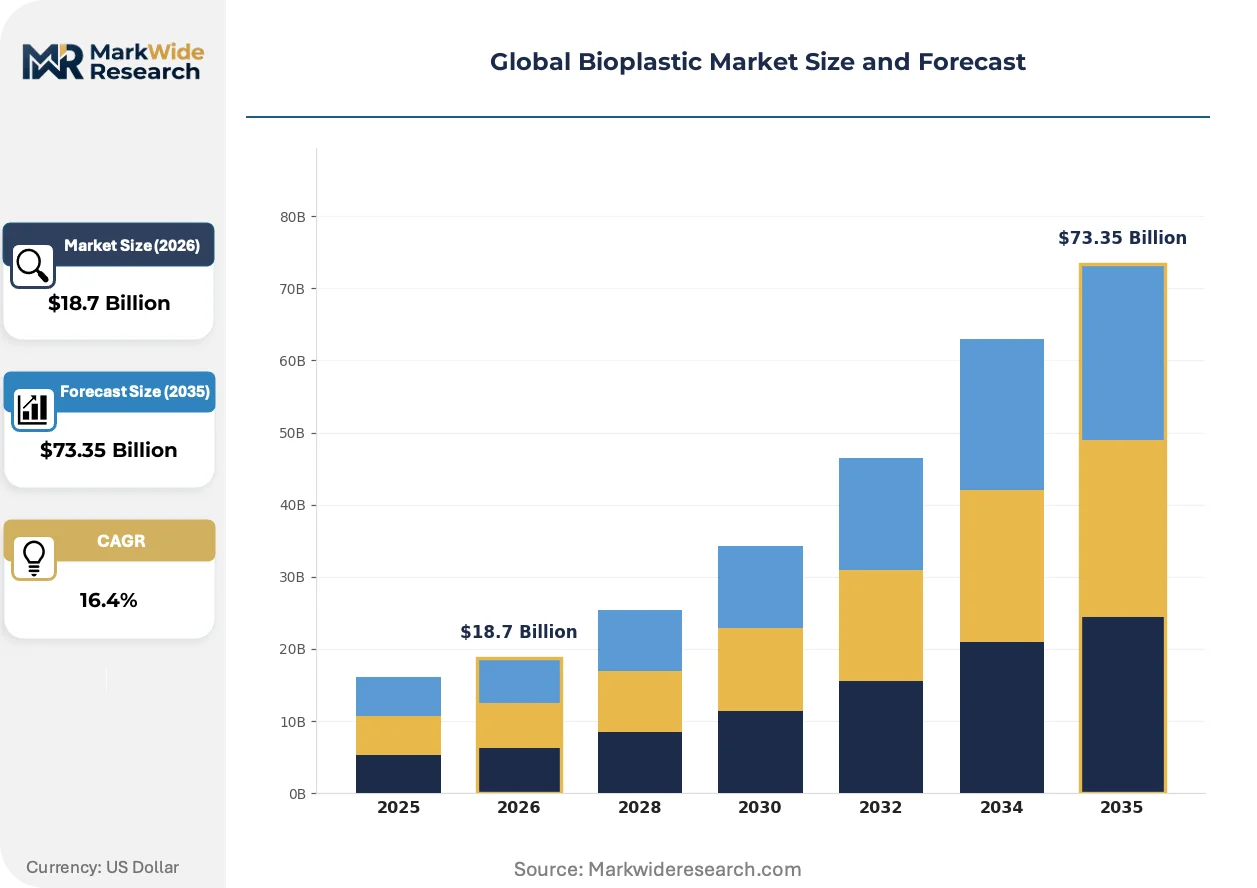
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PHA, Starch Blends, Cellulose-Based, Bio-Polyamides, Bio-Polyethylene Application: Packaging, Agriculture Films, Consumer Goods, Textile Fibers, Automotive Components, Electronic Encapsulation End User: Food & Beverage Manufacturers, Textile Producers, Agriculture Equipment Makers, Consumer Electronics OEMs, Construction Firms, Personal Care Brands Form: Films, Sheets, Pellets, Granules, Fibers, Injection Molded Products |
| Companies Covered | NatureWorks LLC, BASF SE, TotalEnergies Corbion, Braskem, Novamont S.p.A., Danimer Scientific, Eastman Chemical Company, Mitsubishi Chemical Group Corporation, Kuraray Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bioplastic Market Shifts & Advancements
Digital traceability platforms and fermentation process analytics are restructuring how resin producers verify biobased content claims and optimize yield curves.
Blockchain-enabled supply chain verification is digitizing carbon accounting for biomass sourcing. Major food retailers in France and the Netherlands now require batch-level radiocarbon test documentation. This transparency infrastructure is compressing audit costs while exposing uncertified competitors to procurement exclusion.
Japan's METI has tightened JIS K 6953 testing protocols for biodegradable plastics, forcing export-oriented producers to retest existing formulations. The revised standard mandates marine biodegradation documentation for products labeled "ocean-friendly." Southeast Asian compounders are responding by establishing Tokyo-accredited laboratory partnerships.
Brand-owner sustainability scorecards now weight end-of-life disposal pathways above recycled content percentages. Unilever and Nestlé procurement teams in the United Kingdom and Germany have shifted tender evaluation criteria toward industrial compostability certification. This preference rotation disadvantages mechanical recycling-dependent suppliers without composting infrastructure access.
Global Bioplastic Market Segmentation
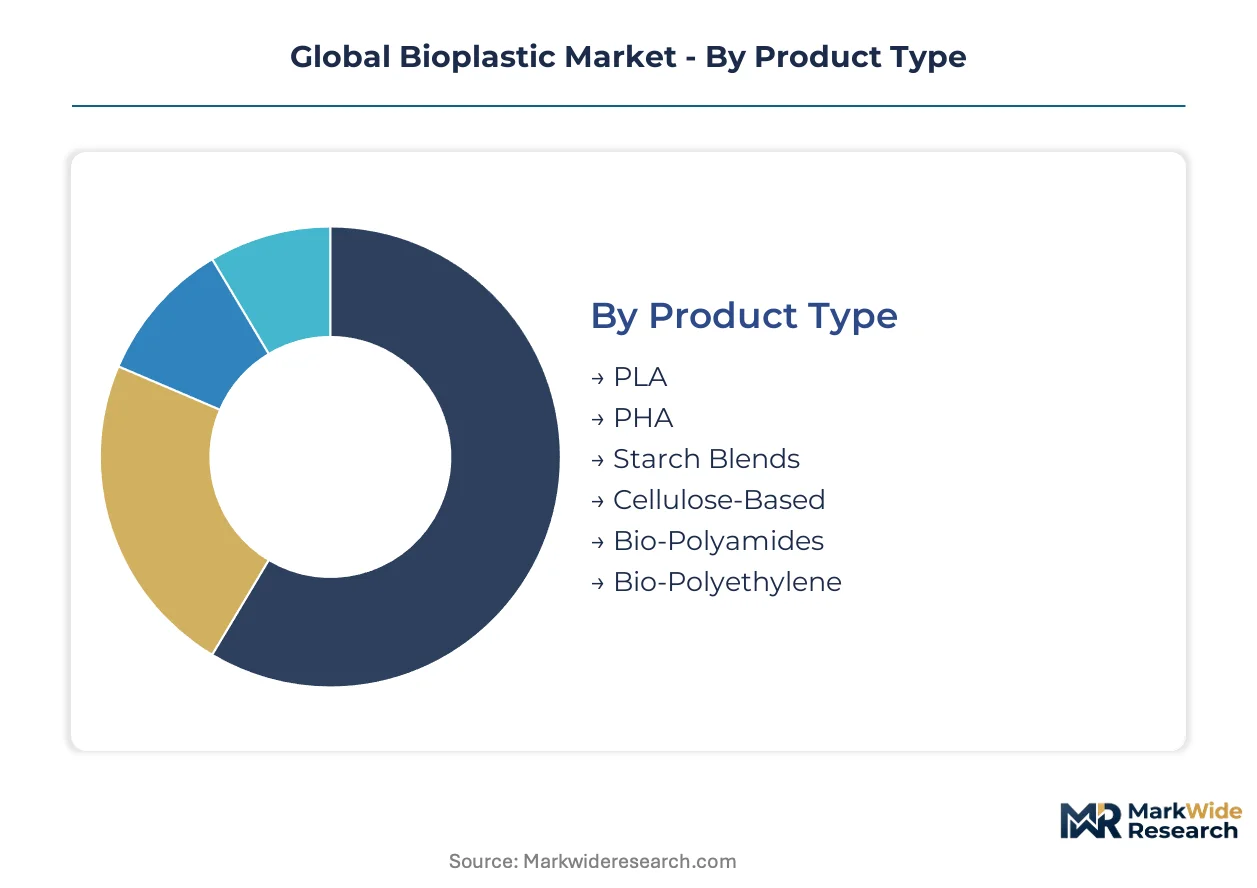
Bioplastic market segmentation reveals distinct technical requirements across product chemistry, processing form, and end-use durability demands. Each dimension carries specific certification burdens and supply chain configurations that determine commercial viability.
Product Type:
After-sales service intensity varies sharply across resin chemistries, with fermentation-based materials requiring technical support for moisture-sensitive processing parameters.
- PLA:Polylactic acid relies on lactic acid fermentation from corn starch or sugarcane feedstock, delivering crystalline clarity suitable for thermoformed food containers. German food service distributors specify Ingeo-grade resin for certified compostable cutlery and cold beverage cups under EU Single-Use Plastics Directive compliance timelines.
- PHA:Polyhydroxyalkanoates accumulate intracellularly in bacterial cultures, producing marine-biodegradable polymers without industrial composting infrastructure. Coastal municipalities in Thailand and island jurisdictions across Indonesia prioritize PHA foodware to address landfill capacity constraints and ocean plastic leakage.
- Starch Blends:Thermoplastic starch compounds with synthetic polymers balance biodegradation rates with mechanical performance for agricultural mulch films.
- Cellulose-Based:Regenerated cellulose from wood pulp serves high-barrier flexible packaging through acetate and cellophane derivatives.
- Bio-Polyamides:Castor oil-derived PA11 and PA610 deliver heat resistance and dimensional stability for under-hood automotive components.
- Bio-Polyethylene:Drop-in replacement polymerized from bio-ethanol maintains identical processing characteristics to fossil-based PE for film blowing operations.
PLA holds the largest share; momentum sits with PHA.
Application:
Cost tier differentiation separates commodity packaging volumes from specialty durable goods commanding formulation premiums.
- Packaging:Flexible films, rigid trays, and foam protective structures dominate bioplastic consumption, with French retailers mandating batch-level radiocarbon documentation for private-label food packaging. ASTM D6400 and EN 13432 certification requirements filter supplier qualification to resin producers with accredited laboratory partnerships.
- Agriculture Films:Soil-biodegradable mulch and tunnel films eliminate retrieval labor costs for specialty crop operations in Spain and Italy, where EN 13432-compliant formulations degrade within a single growing season without mechanical collection.
- Consumer Goods:Disposable cutlery, straws, and cosmetic applicators leverage compostability claims for brand differentiation in regulated markets.
- Textile Fibers:PLA and bio-polyester filaments target moisture-wicking activewear with lower fossil content than conventional synthetic textiles.
- Automotive Components:Interior trim panels and structural brackets incorporate bio-based polyamides to satisfy OEM weight reduction targets under fleet emissions standards.
- Electronic Encapsulation:Bio-epoxy and cellulose-derived substrates serve circuit board protection with halogen-free flame retardancy specifications.
Packaging commands the dominant volume position; agriculture films are expanding most quickly on regulatory tailwinds.
End User:
Customer type segmentation aligns procurement sophistication with technical service requirements, from multinational food brands to dispersed agricultural operations.
- Food & Beverage Manufacturers:Nestlé and Unilever procurement teams in the United Kingdom and Germany have reweighted tender criteria toward industrial compostability certification, disadvantaging mechanical recycling-dependent suppliers without composting infrastructure access. Extended-shelf-life product lines remain constrained by PLA oxygen transmission limitations.
- Textile Producers:Fiber spinners in Japan face METI-mandated JIS K 6953 testing protocol updates requiring marine biodegradation documentation for export market access.
- Agriculture Equipment Makers:Mulch film applicator manufacturers specify soil-biodegradable materials compatible with existing laying machinery.
- Consumer Electronics OEMs:Device assemblers specify bio-based encapsulants for sustainability scorecard compliance without thermal performance compromise.
- Construction Firms:Insulation and geotextile applications demand multi-decade durability conflicting with biodegradation timelines.
- Personal Care Brands:Cosmetic packaging converters prioritize aesthetic clarity and fragrance barrier properties in bioplastic tube and jar formats.
Food and beverage manufacturers anchor procurement volumes; personal care brands are gaining share fastest on premium positioning.
Form:
Supply concentration clusters around pellet and granule intermediates serving downstream converters with established extrusion and molding infrastructure.
- Films:Blown and cast film structures serve flexible food packaging and agricultural mulch with gauge tolerances dictating barrier performance and mechanical integrity during field installation.
- Sheets:Thermoformable sheet extrusions target clamshell containers and blister packs with crystallinity control for heat resistance.
- Pellets:Standardized resin pellets constitute the primary distribution format for injection molding and extrusion compounders, with moisture content specifications critical for hydrolysis-prone PLA grades.
- Granules:Larger particle size intermediates suit bulk handling systems in continuous film production lines.
- Fibers:Melt-spun filaments and staple fibers serve nonwoven applications and textile weaving with denier and tenacity specifications matching petrochemical polyester.
- Injection Molded Products:Finished parts including cutlery, cosmetic containers, and automotive clips bypass converter intermediation for direct OEM supply.
Pellets hold the largest share; injection molded products are climbing the fastest on vertical integration trends among brand owners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal packaging mandates and the Single-Use Plastics Directive are redirecting procurement toward certified compostable alternatives across major economies. Industrial composting infrastructure expansion lags resin certification in most jurisdictions, creating supply-demand mismatches.
Germany
Automotive lightweighting targets and flexible packaging demand anchor biopolymer consumption in Europe's largest economy. The EU F-Gas Regulation and REACH framework compress petrochemical polymer availability while mandating recyclability thresholds. Industrial converters in North Rhine-Westphalia and Bavaria are scaling PLA and bio-polyamide processing capacity for automotive interior trim and food service applications.
United States
Federal procurement through the USDA BioPreferred program creates institutional demand anchors for designated bioplastic product categories. FDA food-contact notification pathways shape resin approval timelines for packaging applications. NatureWorks LLC operates its Blair, Nebraska fermentation complex to sustain captive lactic acid supply for Ingeo-branded PLA output serving thermoformed food containers.
Thailand
Sugarcane feedstock expansion secures long-term supply agreements with fermentation-based resin producers serving export markets. Coastal municipalities prioritize PHA foodware to address landfill capacity constraints and ocean plastic leakage. Bangkok-based compounders are establishing Tokyo-accredited laboratory partnerships to meet Japan's tightened JIS K 6953 testing protocols.
Japan
METI-mandated JIS standards for biodegradable plastics constrain export market access for uncertified producers. Revised K 6953 protocols now require marine biodegradation documentation for products labeled ocean-friendly. Automotive OEMs in the Nagoya and Osaka industrial corridors specify bio-based polyamides for interior trim weight reduction under fleet emissions standards.
France
Major food retailers mandate batch-level radiocarbon test documentation for private-label food packaging procurement. The EU Single-Use Plastics Directive bans select conventional items, redirecting food service procurement toward certified compostable alternatives. Unilever and Nestlé procurement teams have reweighted tender criteria toward industrial compostability certification in the Paris basin.
Global Bioplastic Market Competitive Landscape
On the supply side, the industry is consolidating around fermentation-based resin producers with captive feedstock integration and petrochemical conglomerates diversifying into biopolymer portfolios. Strategic archetypes include agricultural-integrated fermentation specialists, petrochemical-backed biopolymer divisions, and marine-biodegradable technology developers. Dominant competitive moves encompass backward integration into lactic acid supply and strategic partnerships with industrial composting operators to close end-of-life infrastructure gaps.
Within the agricultural-integrated tier, NatureWorks LLC exemplifies captive supply chain control through its Nebraska fermentation complex. BASF SE anchors European biopolymer availability through its Ecoflex and Ecovio product lines, representing the petrochemical diversification archetype. TotalEnergies Corbion occupies a position competing on PLA purity grades for high-heat food service applications.
| Leading Market Players |
|---|
| NatureWorks LLC |
| BASF SE |
| TotalEnergies Corbion |
| Braskem |
| Novamont S.p.A. |
| Danimer Scientific |
| Eastman Chemical Company |
| Mitsubishi Chemical Group Corporation |
| Kuraray Co., Ltd |
| Others |
Supply & Pricing Matrix
North Rhine-Westphalia's converter cluster expansion is compressing spot resin premiums as captive lactic acid supply from Blair, Nebraska feeds volume commitments to German automotive and food service buyers. This geographic bifurcation between fermentation capacity and compounding demand creates arbitrage windows that compounders exploit through long-term offtake structures.
Pricing Analysis
Certification level creates the primary spread between ASTM D6400 and EN 13432 grades versus uncertified commodity bioplastics. Three-tier pricing structure across premium certified, standard industrial, and economy non-certified levels dominates contract negotiations. Cost compression in standard grades is intensifying because Brazilian sugarcane feedstock volatility transmits directly to PLA resin quotations. Food and beverage manufacturers exhibit highest price sensitivity due to thin packaging margins, while automotive OEMs absorb premiums for bio-polyamide heat resistance specifications.
Supply Chain Analysis
Extended payment terms from Thai sugarcane processors to fermentation-based resin producers are restructuring working capital requirements across Southeast Asian supply nodes. Raw material flows draw from corn starch in the United States, sugarcane in Brazil and Thailand, and castor oil derivatives in India. Single-source vulnerability concentrates around lactic acid fermentation trains with multi-year commissioning timelines. Distribution runs through regional compounders in Germany, Thailand, and the United States who pelletize resin for downstream extrusion and molding operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for moisture-sensitive PLA processing support are expanding faster than base resin volumes as converters demand on-site parameter optimization. This service-attach layer offers margin protection independent of commodity resin cyclicality.
For Market Incumbents: Pre-empt PHA capacity shortages by securing bacterial fermentation partnerships before marine-biodegradable certification becomes mandatory for coastal procurement. Anchor backward integration into lactic acid supply through long-term agricultural offtake agreements in Nebraska or Thailand. Defend position by embedding technical service teams at major German automotive Tier 1 suppliers to lock in bio-polyamide specifications.
For New Entrants and Emerging Players: Pursue agricultural mulch film segments in Spain and Italy where EN 13432 compliance eliminates mechanical retrieval costs and incumbent penetration remains shallow. Target coastal tourism economies in Indonesia and Thailand with PHA foodware positioned for ocean-degradability premiums. Establish Tokyo-accredited laboratory partnerships to satisfy Japan's tightened JIS K 6953 protocols as a go-to-market prerequisite.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation specialists with captive feedstock integration over petrochemical diversification plays. Five-to-ten year viability hinges on industrial composting infrastructure buildout keeping pace with resin certification expansion. Target acquisition archetypes include bacterial culture technology developers and regional compounders with accredited laboratory partnerships. Monitor FDA food-contact notification queue lengths as inflection signal for commercial launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactic Acid Supply | Captive feedstock from Blair, Nebraska or Thai sugarcane processors insulates margin from agricultural commodity swings. |
| Marine Biodegradability Certification Investment | JIS K 6953 and ASTM D6691 compliance unlocks premium positioning in Indonesia's island jurisdictions and Japan's coastal municipalities. |
| Industrial Composting Infrastructure Partnership | Collaboration with municipal facility operators in Germany and France closes end-of-life gaps threatening EN 13432 credibility. |
| Automotive OEM Specification Embedding | Technical service presence at BMW and Volkswagen Tier 1 suppliers locks in bio-polyamide content for interior trim applications. |
| Blockchain-Enabled Supply Chain Verification | Batch-level radiocarbon documentation satisfies French retailer procurement mandates from Carrefour and Casino. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with biopolymer plant managers, automotive OEM procurement leads, food packaging converters, agricultural film distributors, and technical R&D directors at fermentation facilities. Secondary validation drew from EU ECHA substance registrations, USDA BioPreferred product listings, FDA food-contact notification databases, and ASTM certification records. Bottom-up resin volume estimates from individual production facilities were triangulated against top-down demand projections from end-use sector consumption models.
Calibration against historical price realizations and capacity utilization rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, processing form factor, end-use durability requirements, and regional regulatory cluster. CAGRs were derived from slope analysis of fitted trend lines applied to certified resin volume growth trajectories. Industry-specific forecast inputs incorporated EU Single-Use Plastics Directive implementation timelines and automotive fleet emissions standard stringency curves.
Sensitivities concentrate around composting infrastructure deployment rates and agricultural feedstock price volatility. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and certification standard harmonization. Macroeconomic contraction, regulatory rollback, or breakthrough petrochemical recycling technologies would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Bio-Degradable Polymers Market
Bioplastics
Asia-Pacific Bio Plasticizers Market
Bioplastics
Biobased Biodegradable Plastics Market
Bioplastics
US Bioplastics Market
Bioplastics
Bio-PET Market
Bioplastics
Europe Bioplastics Market
Bioplastics
Global Bio-Plasticizers Market
Bioplastics
Biopolymers Market
Bioplastics
Asia-Pacific Polylactic Acid (PLA) Market
Bioplastics
North America Bioplastics Market
Bioplastics
Global Synthetic and Bio Based Biodegradable Plastics Market
Bioplastics
Starch-Based Bioplastics Market
Bioplastics
Middle East Biodegradable Plastics Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market
Bioplastics
Bio-Based Succinic Acid Derivatives for Plasticizers Market
Bioplastics
North America Polylactic Acid (PLA) Market