
 Compostable Phone Cases Market | 2026-2036
Compostable Phone Cases Market Size, Share, and Industry Trends Forecast 2026-2036
Compostable Phone Cases Market Insights
Eco-conscious consumer segments within smartphone accessories is expanding as sustainability preferences reshape purchasing patterns across retail channels. Pela Case leverages its early-mover position in biopolymer formulation to anchor premium positioning in North American direct-to-consumer channels. CASETiFY competes through customizable design platforms that integrate compostable materials without sacrificing aesthetic differentiation. A Good Company specializes in transparent supply chain storytelling that sustains brand loyalty among climate-activated buyers.
Compostable phone cases are protective enclosures engineered from biodegradable polymers such as PLA, PHA, or PBAT blends, designed to decompose in industrial composting environments within specified timeframes while meeting drop-test durability standards for consumer electronics. The material type dimension shows PLA formulations dominating current production volumes due to cost-competitive feedstock availability, while PHA variants capture emerging interest from buyers prioritizing marine biodegradability certifications. Online retail channels command the fastest growth trajectory as direct-to-consumer brands bypass traditional wholesale markups, though brick-and-mortar presence in electronics specialty stores retains importance for tactile purchase validation among hesitant switchers.
The EU Green Deal and REACH chemical safety frameworks in Europe mandate phased reduction of petroleum-based plastics in consumer goods, directly elevating compostable alternatives in regulatory compliance strategies. FDA food-contact safety standards and state-level extended producer responsibility laws in the US create parallel compliance pathways that manufacturers must navigate for market access. Stakeholders should monitor composting infrastructure maturity in target markets, as industrial facility availability remains the critical variable separating theoretical biodegradability claims from actual end-of-life performance.
Market Dynamics
EU REACH chemical safety mandates and the EU Green Deal's single-use plastic phase-outs are compressing petroleum-based polymer viability while redirecting procurement toward certified compostable feedstocks.
Growth Catalysts
- REACH compliance deadlines:European manufacturers face binding reduction targets for petroleum-derived plastics in consumer goods, forcing formulation switches to PLA and PHA blends.
- Gen Z purchasing concentration:Berlin and Hamburg retail clusters demonstrate sustained premium willingness for circular economy accessories among climate-activated demographics.
- Industrial composting infrastructure:Facility expansion across Germany, France, and the Netherlands validates end-of-life claims and closes the biodegradability loop.
Market Restraints
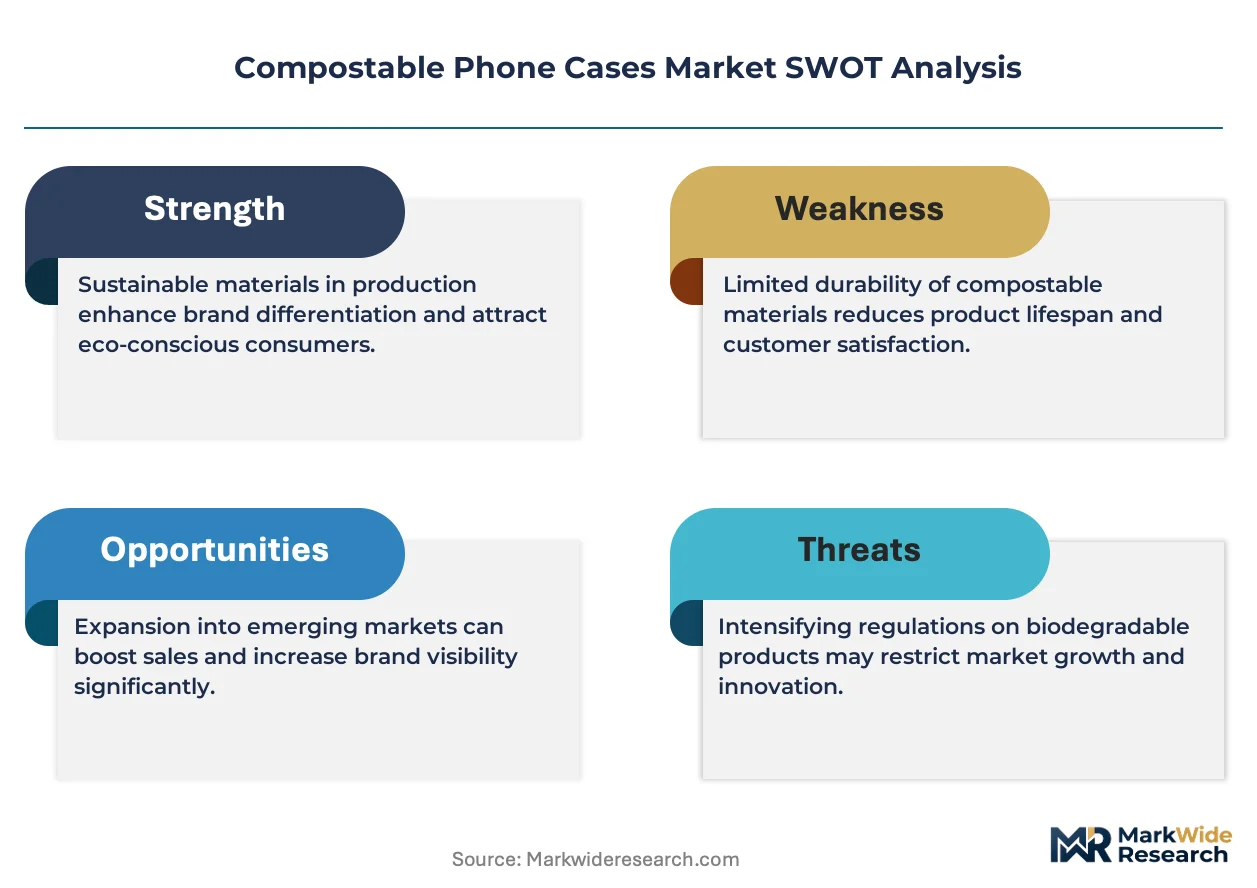
- Feedstock cost volatility:Corn and sugarcane prices for PLA production fluctuate with agricultural commodity cycles, compressing margin stability for mid-tier producers.
- Certification timeline friction:ASTM D6400 and EN 13432 industrial composting certifications require 12-18 month validation periods, delaying product launches.
- Silicone substitute threat:Conventional silicone cases retain durability advantages and lower unit economics, capturing price-sensitive switchers.
Strategic Opportunities
- US state-level EPR laws:California and New York extended producer responsibility frameworks create compliance-driven demand pull for certified compostable alternatives.
- Marine biodegradability certification:PHA formulations achieving TUV Austria OK biodegradable MARINE status unlock beachside retail and coastal tourism channels.
- Direct-to-consumer platform expansion:Shopify-native brands bypass electronics specialty wholesale markups, capturing full margin on subscription-style case replacement programs.
Industry Challenges
- Biopolymer formulation talent scarcity:Material scientists with simultaneous expertise in drop-test durability and compostability certification command premium compensation, constraining R&D scaling.
- Composting facility geographic mismatch:Industrial composting availability clusters in Northern Europe and coastal US metro areas, leaving Central and Eastern European consumers without end-of-life pathway validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compostable Phone Cases Market |
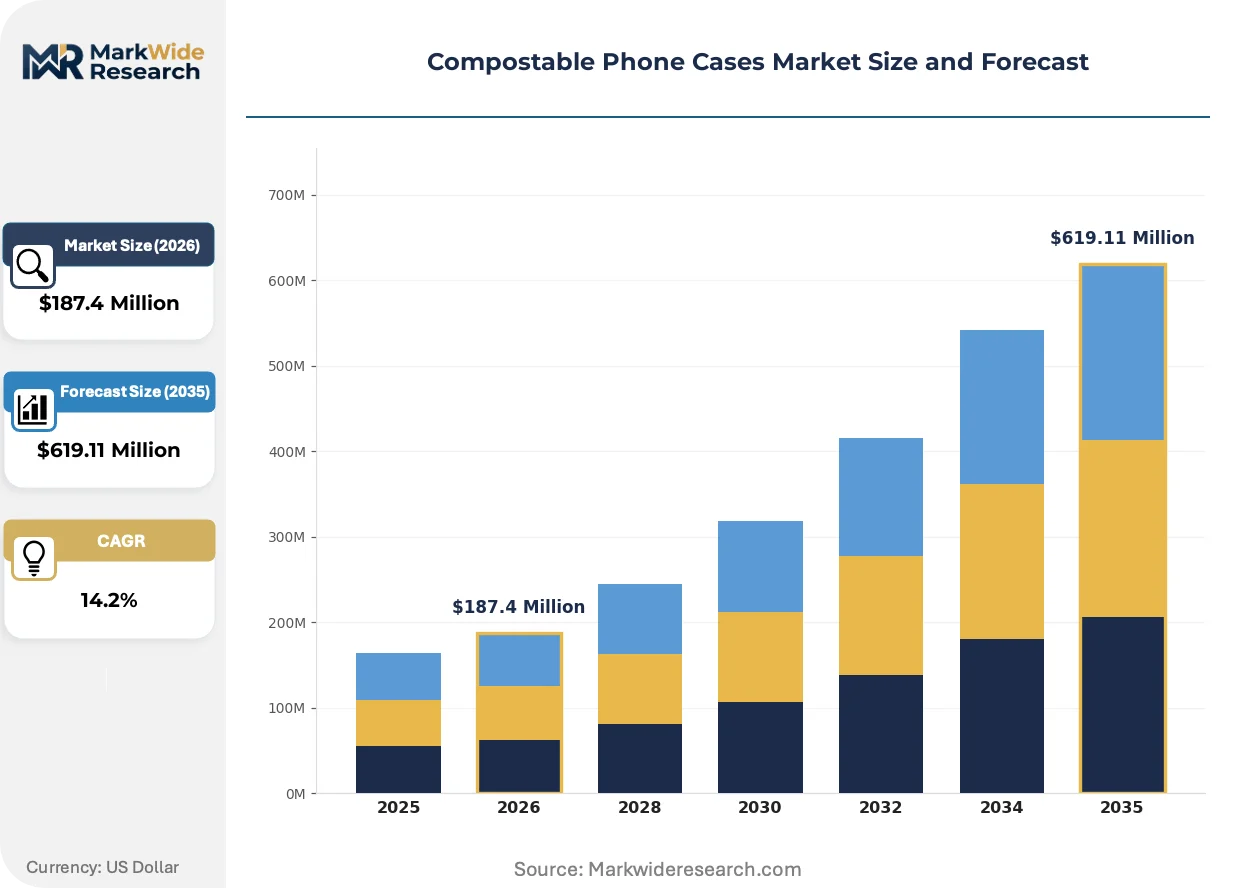
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PLA, PHA, PBAT, Wheat Straw Distribution Channel: Online Retail, Brick-and-Mortar, Direct Sales, E-Commerce End User: Millennials, Eco-Conscious Consumers, Businesses, Students Feature: Biodegradable, Shock-Resistant, Customizable, Lightweight |
| Companies Covered | Reboxed, Casekoo, Pela Case, Empower Impact Ltd, Wave Case, A Good Company, Wild Case, EcoBlvd, CASETiFY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compostable Phone Cases Market Trends and Innovations
Biopolymer formulation science and certification standard evolution are compressing the performance gap between petroleum-based and compostable protective enclosures.
PHA-blend material systems are modularizing protective case architecture by separating impact-absorption layers from outer shell aesthetics. Outdoor recreation buyers and marine-adjacent consumers are adopting these configurations fastest due to saltwater biodegradability credentials. This modularity is compressing SKU complexity for manufacturers while enabling localized material sourcing.
REACH Annex XVII restrictions on microplastic shedding from consumer goods are forcing reformulation of conventional TPU and polycarbonate blends. German chemical manufacturers are accelerating PHA copolymer pilot lines to maintain EU market access. Electronics accessory distributors in Hamburg and Munich are prioritizing inventory shifts ahead of 2027 enforcement milestones.
Subscription-based case replacement programs are displacing one-time purchase patterns among millennial smartphone owners. Direct-to-consumer channels capture these buyers through Instagram-native discovery and unboxing-driven retention mechanics. Berlin-based circular economy startups demonstrate highest conversion rates for annual refresh models tied to composting return logistics.
Compostable Phone Cases Market Segmentation
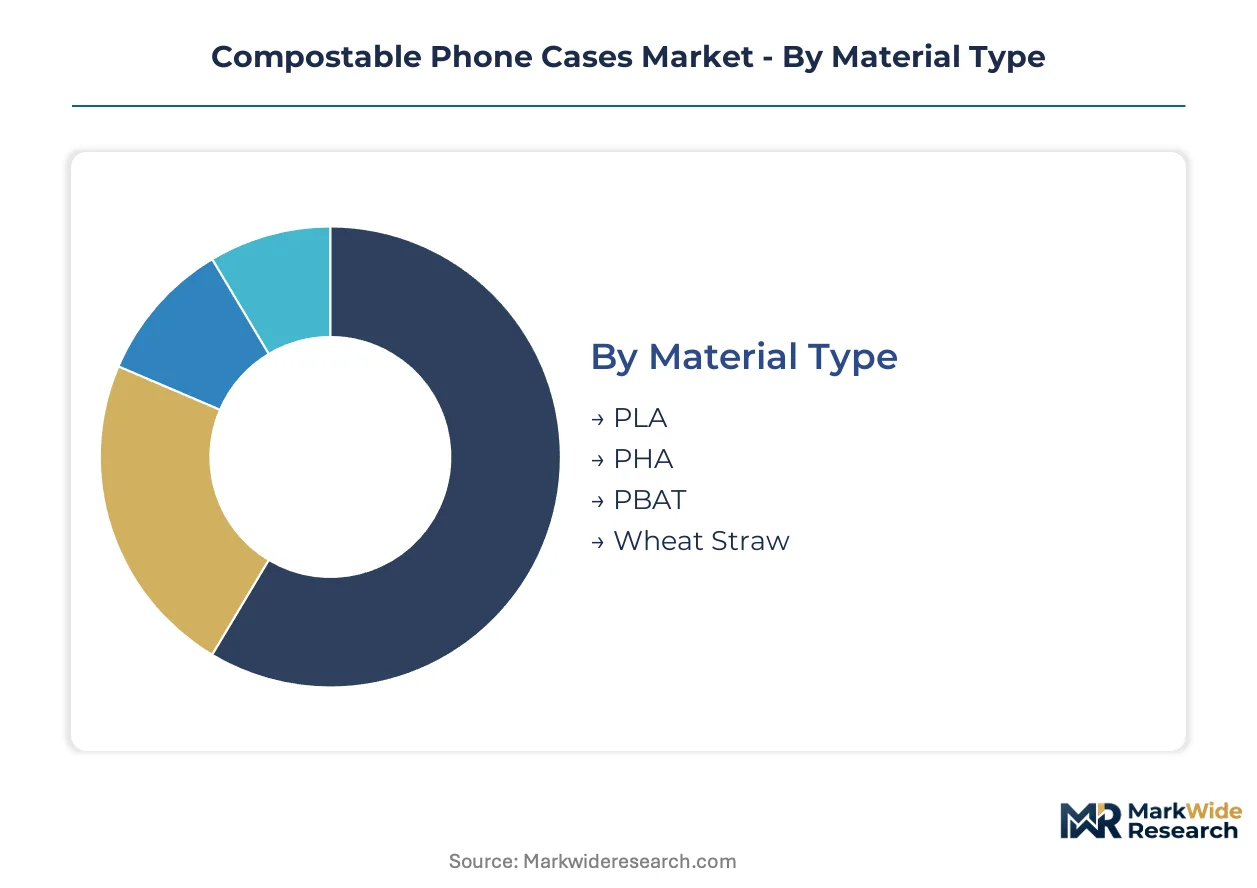
Material specifications and distribution channel economics determine margin capture and end-of-life performance validation in compostable phone cases. Segmentation reveals where biopolymer formulation investments align with purchasing behavior across climate-activated demographics.
Material Type:
Biopolymer chemistry and feedstock sourcing dictate certification pathways, decomposition timelines, and marine biodegradability credentials.
- PLA:Polylactic acid formulations dominate current production volumes through cost-competitive corn and sugarcane feedstock availability. German retailers in Berlin and Hamburg prioritize PLA-based inventory for price-accessible sustainable accessories, though agricultural commodity volatility compresses margin stability for mid-tier producers.
- PHA:Polyhydroxyalkanoate variants capture emerging interest from buyers prioritizing marine biodegradability certifications and saltwater decomposition performance. Coastal tourism channels and beachside retail in the Netherlands and France demonstrate fastest adoption curves for PHA-based protective enclosures.
- PBAT:Aliphatic-aromatic copolyester blends provide flexibility and impact resistance in multi-layer case architectures, commonly combined with PLA in commercial formulations.
- Wheat Straw:Agricultural residue composites offer visual differentiation through natural fiber texture, appealing to transparent supply chain storytellers in direct-to-consumer channels.
PLA leads on scale; PHA leads on momentum.
Distribution Channel:
Channel selection determines customer acquisition economics and tactile purchase validation requirements for hesitant switchers from conventional silicone.
- Online Retail:Direct-to-consumer platforms capture full margin through subscription-style case replacement programs, with Instagram-native discovery driving millennial and Gen Z conversion. Shopify-native brands bypass electronics specialty wholesale markups, concentrating customer relationships in climate-activated urban demographics.
- Brick-and-Mortar:Electronics specialty stores retain importance for tactile validation, with Hamburg and Munich retail clusters demonstrating sustained premium willingness when physical inspection confirms drop-test durability.
- Direct Sales:Manufacturer-owned channels enable circular economy return logistics and composting program integration, particularly effective for annual refresh models.
- E-Commerce:Third-party marketplace presence expands reach to price-comparison shoppers, though margin compression from platform fees challenges premium positioning.
Online Retail captures volume concentration; Direct Sales gains share fastest through subscription mechanics.
End User:
Demographic targeting aligns formulation transparency, design customization, and corporate sustainability procurement requirements.
- Millennials:Smartphone accessory refresh cycles concentrate in this segment, with unboxing-driven retention mechanics and annual replacement programs converting highest lifetime value.
- Eco-Conscious Consumers:Climate-activated buyers demand transparent supply chain storytelling and composting infrastructure validation, prioritizing certified industrial compostability over marine biodegradability claims.
- Businesses:Corporate sustainability procurement mandates drive bulk purchasing for employee device fleets, with EU Green Deal compliance requirements elevating certified compostable alternatives in vendor selection criteria.
- Students:Price-sensitive entry point for sustainable accessories, with campus retail and educational institution partnerships creating volume opportunities at compressed margins.
Millennials anchor revenue concentration; Businesses climb the fastest on compliance-driven procurement.
Feature:
Functional specifications balance environmental performance claims with physical protection standards required for consumer electronics.
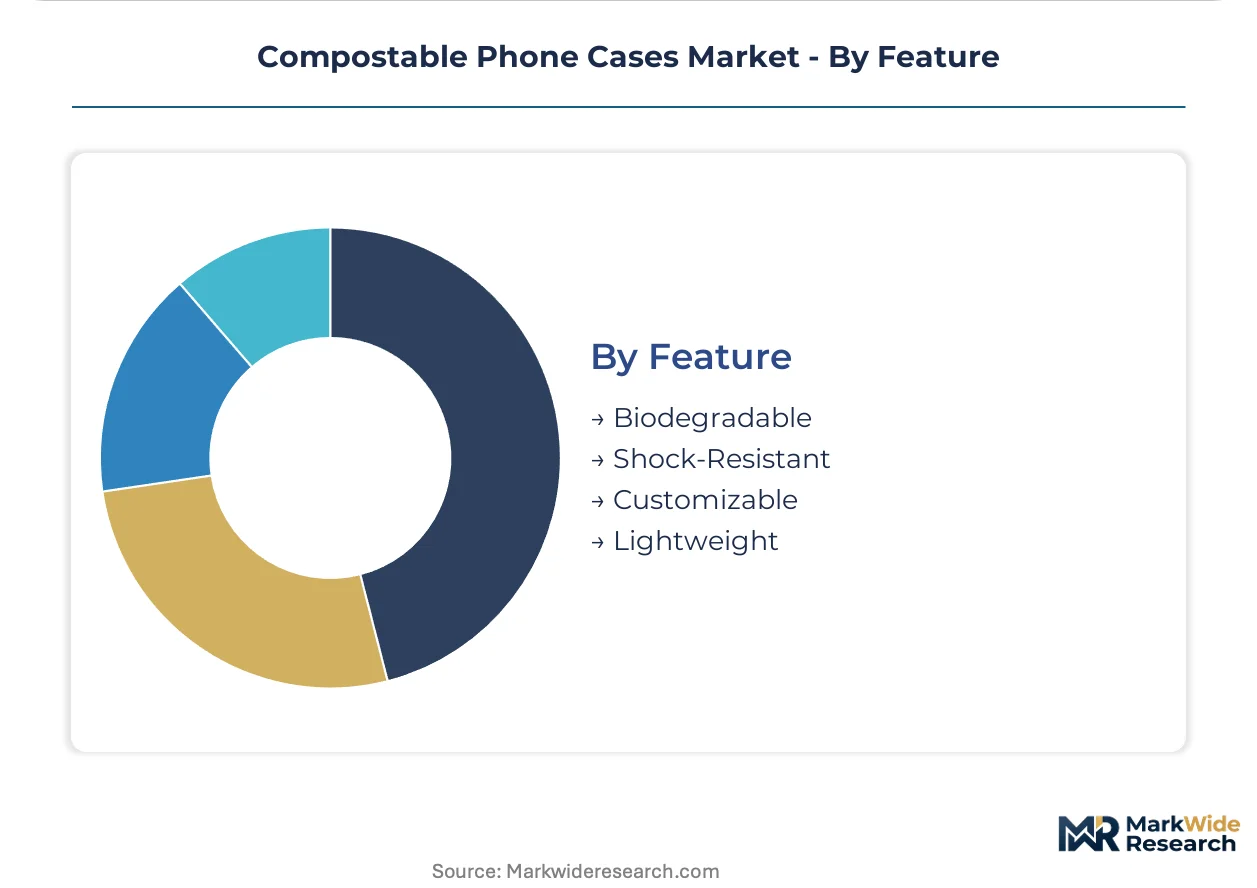
- Biodegradable:Core value proposition requiring ASTM D6400 or EN 13432 certification validation, with industrial composting facility availability determining actual end-of-life performance.
- Shock-Resistant:Drop-test durability standards separate viable compostable alternatives from performance-compromised early formulations, critical for retail acceptance in electronics specialty channels.
- Customizable:Design personalization platforms integrate compostable materials without sacrificing aesthetic differentiation, capturing premium positioning among style-conscious urban consumers.
- Lightweight:Reduced material density appeals to minimal-carry users and outdoor recreation segments, though often traded against impact absorption performance.
Biodegradable features anchor regulatory compliance; Customizable options gain share fastest through direct-to-consumer platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting compostable phone case production toward jurisdictions with mature industrial composting infrastructure and binding plastic-reduction mandates. Manufacturers migrate capacity to capture compliance cost advantages in markets where end-of-life validation closes the biodegradability loop.
United States
California and New York extended producer responsibility laws are creating compliance-driven procurement pull for certified compostable alternatives. EPA guidelines on sustainable materials management and state-level plastic reduction targets are elevating ASTM D6400 certification as a vendor selection criterion. Direct-to-consumer brands cluster in Los Angeles and Brooklyn, leveraging subscription-style replacement programs to capture climate-activated millennial segments.
Germany
Berlin and Hamburg retail clusters demonstrate sustained premium willingness for circular economy accessories among Gen Z demographics. REACH Annex XVII restrictions on microplastic shedding and the EU Green Deal's single-use plastic phase-outs are compressing petroleum-based polymer viability. Chemical manufacturers in North Rhine-Westphalia are accelerating PHA copolymer pilot lines to maintain EU market access ahead of 2027 enforcement milestones.
France
Coastal tourism channels in Provence-Alpes-Côte d'Azur and beachside retail in Nouvelle-Aquitaine demonstrate fastest adoption curves for PHA-based protective enclosures with marine biodegradability credentials. ANSM and ECHA-aligned chemical safety frameworks mandate phased reduction of petroleum-based plastics in consumer goods. Paris-based sustainable fashion distributors are prioritizing inventory shifts toward TUV Austria OK biodegradable MARINE certified alternatives.
Netherlands
Randstad region industrial composting facility expansion validates end-of-life claims and closes the biodegradability loop for climate-activated buyers. Dutch implementation of EU Green Deal procurement standards elevates certified compostable alternatives in vendor selection criteria. Amsterdam circular economy startups demonstrate highest conversion rates for annual refresh models tied to composting return logistics.
United Kingdom
London and Southeast England direct-to-consumer platforms capture full margin through Instagram-native discovery driving millennial conversion. UK alignment with REACH chemical safety frameworks and emerging extended producer responsibility legislation creates parallel compliance pathways. Electronics specialty retail clusters in Manchester and Birmingham retain importance for tactile purchase validation among hesitant switchers from conventional silicone.
Compostable Phone Cases Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents extend biopolymer formulation capabilities across adjacent sustainable accessories. The vendor base clusters around early-mover biopolymer specialists, customizable design platforms, and transparent supply chain storytellers. Three strategic archetypes have crystallized: formulation-science leaders, aesthetic-differentiation platforms, and circular-economy logistics integrators. Capacity expansion in Northern European PHA pilot lines and strategic partnerships with industrial composting operators represent the dominant competitive moves.
Within the formulation-science tier, Pela Case and CASETiFY exemplify divergent positioning strategies. Pela Case occupies a position as a North American direct-to-consumer anchor with early-mover biopolymer expertise. CASETiFY represents the aesthetic-differentiation archetype through customizable design platforms that integrate compostable materials. A Good Company sits within the transparent supply chain storyteller tier, sustaining brand loyalty among climate-activated buyers through verified sourcing narratives.
| Leading Market Players |
|---|
| Reboxed |
| Casekoo |
| Pela Case |
| Empower Impact Ltd |
| Wave Case |
| A Good Company |
| Wild Case |
| EcoBlvd |
| CASETiFY |
| Others |
Pricing and Supply Chain Analysis
Climate-activated millennials purchasing through direct-to-consumer channels anchor pricing power for subscription-style case replacement programs, compressing margins for mid-tier producers dependent on wholesale electronics specialty distribution. Agricultural commodity volatility in corn and sugarcane feedstocks transmits directly into PLA formulation cost structures, while PHA premium positioning reflects marine biodegradability certification scarcity.
Pricing Analysis
Retailer markup layers in electronics specialty channels absorb 35-45 points of gross margin before reaching end consumers, forcing direct-to-consumer brands to capture full value through Shopify-native subscription mechanics. Price differentiation hinges on certification tier—ASTM D6400 and EN 13432 validated products command positioning premiums—and volume scale in annual refresh programs. Cost compression in mid-tier PLA formulations is intensifying because agricultural feedstock volatility outpaces polymer processing efficiency gains. Students and campus retail segments exhibit highest price sensitivity, while corporate sustainability procurement mandates demonstrate lowest elasticity due to compliance-driven vendor selection.
Supply Chain Analysis
Transatlantic freight cost differentials between North American corn belt PLA producers and European compounders in Germany and the Netherlands reshape sourcing economics for brands serving EU regulatory deadlines. Feedstock supply concentrates in United States agricultural regions, Chinese PBAT manufacturing clusters, and emerging Southeast Asian sugarcane processing hubs. Raw material dependencies rest on corn starch for PLA, microbial fermentation feedstocks for PHA, and adipic acid derivatives for PBAT flexibility modifiers. Single-source vulnerability in certified industrial composting facility access creates geographic supply chain risk, particularly for Central and Eastern European market penetration. Distribution runs through direct-to-consumer platforms capturing subscription renewal economics, with electronics specialty wholesale retaining tactile validation importance for hesitant silicone switchers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The compostable phone cases market reads as a late-cycle quality story where marine biodegradability certification and industrial composting return logistics separate viable competitors from commodity-positioned alternatives. Demand is consolidating toward premium PHA formulations with TUV Austria OK biodegradable MARINE status as coastal tourism channels expand.
For Market Incumbents: Acquire industrial composting facility partnerships or captive logistics networks to close end-of-life validation loops ahead of 2027 REACH Annex XVII enforcement milestones. Secure backward integration into PHA copolymer pilot capacity in North Rhine-Westphalia to defend formulation-science positioning against silicone substitute threats. Channel control through direct-to-consumer platform retention mechanics represents the critical lever for margin defense against mid-tier PLA competitors. For New Entrants and Emerging Players: Modular biopolymer architecture enabling impact-absorption layer separation from aesthetic shells offers technology-first entry against incumbent integrated designs. White-space concentration in Central and Eastern European markets lacking industrial composting infrastructure validation presents geographic expansion opportunity. Campus retail partnerships with educational institution sustainability offices provide the most penetrable volume channel at compressed but defensible margins. For Investors and Strategic Acquirers: Sustainable fashion conglomerates with circular economy mandates are the most active acquirer in this space, targeting formulation-science capabilities and composting logistics integration. Long-term viability hinges on industrial composting infrastructure maturation across target geographies rather than material innovation alone. The signal to monitor is state-level extended producer responsibility law passage in US coastal markets, which would trigger compliance-driven demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| PHA Copolymer Capacity Expansion | North Rhine-Westphalia pilot lines secure EU market access ahead of REACH enforcement milestones. |
| Direct-to-Consumer Platform Migration | Shopify-native subscription mechanics capture full margin from climate-activated millennial segments. |
| Marine Biodegradability Certification | TUV Austria OK biodegradable MARINE status unlocks coastal tourism and beachside retail channels. |
| Industrial Composting Partnership | Randstad region facility integration validates end-of-life claims for Amsterdam circular economy startups. |
| Corporate Fleet Procurement Program | EU Green Deal compliance requirements elevate certified alternatives in vendor selection criteria. |
Research Methodology
Multiple input streams—primary interviews with biopolymer formulation scientists, direct-to-consumer brand operators, and electronics specialty retail buyers; secondary validation through ECHA REACH registration databases, EU Green Deal procurement disclosures, and ASTM certification registries; plus customs and trade flow data for PLA and PHA feedstock movements—were reconciled through bottom-up and top-down triangulation. Conversations with circular economy logistics providers and industrial composting facility operators supplemented material science perspectives. SEC filings from disclosed sustainable accessories competitors and Nielsen retail audit data for smartphone accessory channels provided demand-side calibration.
Historical volume trajectories were cross-referenced against expert panel inputs from German chemical manufacturers and Dutch circular economy startups to anchor projection assumptions. The analytical framework segments across material type, distribution channel, end user demographic, and functional feature specifications throughout the forecast period. CAGRs were derived from elasticity-adjusted adoption curves reflecting regulatory deadline proximity and composting infrastructure maturity by geography. Industry-specific inputs include REACH Annex XVII enforcement timeline phasing and state-level extended producer responsibility legislative tracking.
The model holds under sustained EU regulatory compression and industrial composting facility expansion; deviation in agricultural commodity price spikes or marine biodegradability certification timeline delays would shift volume trajectories toward conventional silicone substitutes. Stakeholders should weight assumptions against their own operating context and regional composting infrastructure access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Starch-Based Plastics Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Biodegradable Plastics Market
Bioplastics
Asia-Pacific Polylactic Acid (PLA) Market
Bioplastics
Bio-Based Polyolefins Market
Bioplastics
Global Bio-Plasticizers Market
Bioplastics
Bio-Polyamide, Specialty Polyamide and Precursors Market
Bioplastics
North America Polylactic Acid (PLA) Market
Bioplastics
Middle East Biodegradable Plastics Market
Bioplastics
Biopolymer Films Market
Bioplastics
Biocomposite Materials Market
Bioplastics
Bio-Based Succinic Acid Derivatives for Plasticizers Market
Bioplastics
Cellulose Plastics Market
Bioplastics
Biodegradable Disposable Tableware Market
Bioplastics
Automotive Bioplastic Market
Bioplastics
Global Bioplastic Market