
 Bio-PET Market | 2026-2036
Bio-PET Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-PET Market Analysis
Subscription-grade carbon accounting and chain-of-custody software is rebalancing what resin producers sell, bundling compliance documentation with every metric ton. Braskem leverages its Brazilian ethanol feedstock position to anchor long-term supply contracts with European bottlers. Toray Industries, Inc. sustains R&D intensity in high-performance fiber grades that command premium positioning in Japanese automotive programs. Indorama Ventures Public Company Limited dominates bottle-grade volume through integrated PET recycling and bio-based expansion across Southeast Asian manufacturing hubs.
Bio-PET (polyethylene terephthalate synthesized with bio-based monoethylene glycol) typically contains 30% plant-derived content by mass, with the terephthalic acid portion remaining petroleum-sourced; manufacturers produce it via ethylene oxide hydration from bio-ethanol, yielding resin with identical mechanical and barrier properties to conventional PET for blow-molding and fiber extrusion. The container and bottle category leads current volume as beverage brands pursue visible sustainability credentials, while the textiles application represents the fastest-growing margin pool as athletic apparel brands specify recycled and bio-based fiber blends. Film-grade Bio-PET occupies a narrower niche in premium food packaging where clarity and gas barrier requirements exclude competing biopolymers.
The EU Green Deal and REACH framework restrict fossil-derived content in single-use packaging, while FDA food-contact regulations in the United States govern monomer purity and migration limits for Bio-PET containers. California's recycled-content mandates and Germany's Packaging Act create divergent compliance obligations that favor producers with dual-certified production lines. Stakeholders must monitor feedstock cost volatility between Brazilian sugarcane and European wheat straw pathways as the decisive variable for regional manufacturing economics.
Market Dynamics
Beverage brands in Germany, California, and Japan are locking in decade-long offtake agreements that tie resin pricing to sugarcane ethanol futures, compressing supplier margins and forcing biorefinery operators to hedge feedstock exposure across multiple continents.
Growth Catalysts
- EU Green Deal packaging mandates:Brussels' phased reduction of fossil-derived single-use plastics creates guaranteed offtake volumes for certified bio-based resin producers serving European bottlers.
- California recycled-content thresholds:State-level mandates require beverage containers to incorporate specified percentages of non-virgin material, with bio-based PET qualifying toward compliance totals.
- Automotive lightweighting programs:Japanese and German vehicle manufacturers specify bio-based fiber grades for interior textiles and under-hood applications to meet fleet emissions targets.
Market Restraints
- Brazilian sugarcane price volatility:Ethanol feedstock costs swing with harvest yields and energy market arbitrage, eroding manufacturing margin predictability for European and Asian converters.
- Petrochemical terephthalic acid dependency:The 70% petroleum-derived portion of Bio-PET resin exposes producers to conventional PET price floors during crude oil downturns.
- REACH registration timelines:ECHA's substance evaluation protocols delay new bio-based monomer approvals by 18-36 months, freezing formulation innovation cycles.
Strategic Opportunities
- Indian beverage market penetration:FSSAI food-contact approvals for bio-based packaging remain underdeveloped, creating first-mover positioning for producers establishing local compounding partnerships.
- Textile-to-textile chemical recycling convergence:Integration of bio-based MEG with depolymerization technologies enables fully circular fiber claims for athletic apparel brands.
- German Packaging Act bonus credits:Extended producer responsibility frameworks award preferential fee structures to packaging with verified bio-based content above 30% mass threshold.
Industry Challenges
- Mass-balance certification complexity:ISCC PLUS and RSB chain-of-custody audits require dedicated compliance personnel and documentation systems that smaller compounders struggle to staff.
- Legacy PET extrusion line retrofits:Converting fossil-based bottle production to bio-based feedstock demands screw geometry modifications and drying protocol adjustments that interrupt output during changeover periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-PET Market |
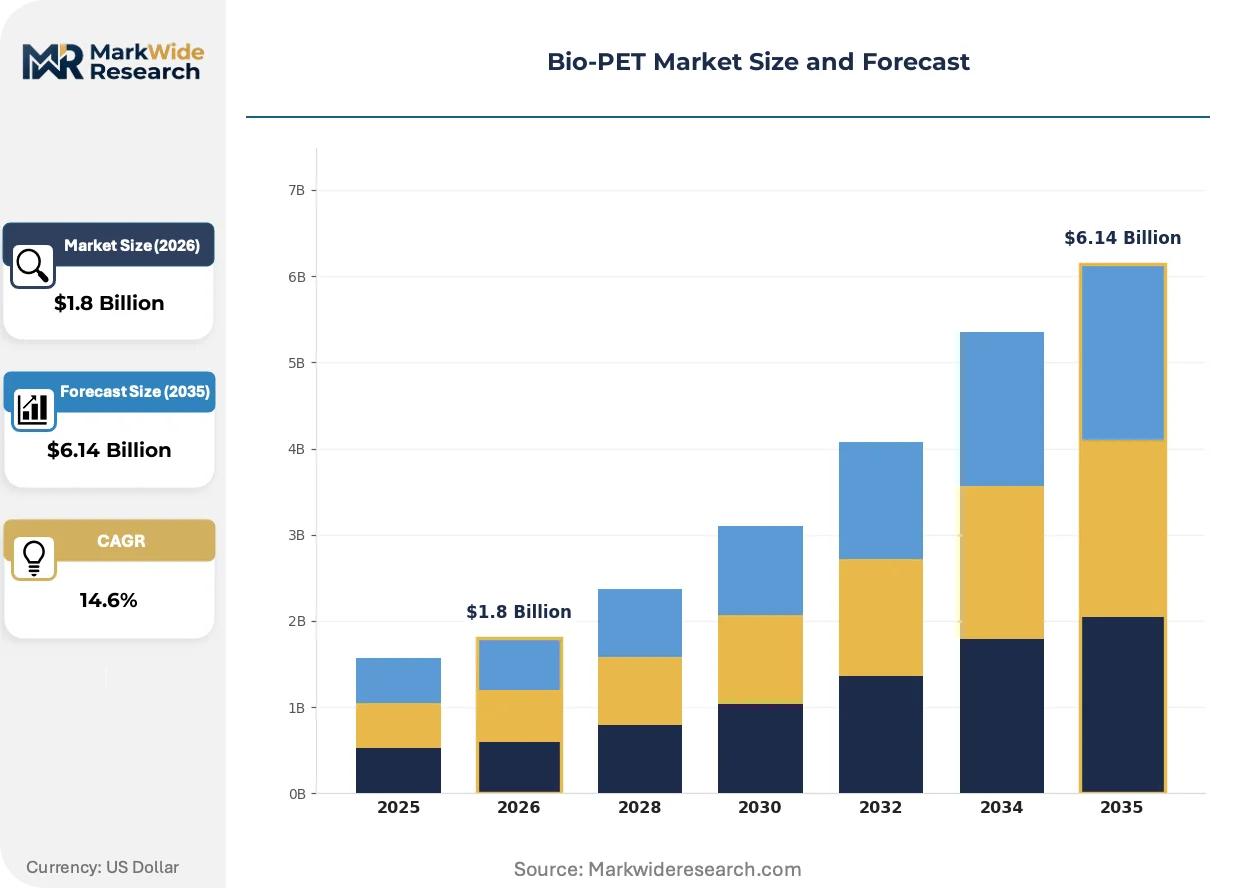
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber, Film, Container, Bottle Application: Food Packaging, Beverage Packaging, Textiles, Automotive Components End User: Healthcare, Food & Beverage, Consumer Goods, Automotive Distribution Channel: Online Retail, Supermarkets, Wholesalers, Direct Sales |
| Companies Covered | Toyota Tsusho Corporation, Braskem, Toray Industries, Inc., DuPont de Nemours, Inc., Mitsubishi Chemical Group, Indorama Ventures Public Company Limited, NatureWorks LLC, M&G Chemicals, TEIJIN LIMITED, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-PET Market Emerging Trajectories
Polymer producers are engineering drop-in bio-based intermediates that eliminate equipment retrofit burdens while regulatory frameworks harden around carbon intensity disclosure requirements.
Second-generation bio-ethylene production from wheat straw and agricultural residues is modularizing upstream supply architecture. Nordic biorefinery operators are deploying enzymatic hydrolysis units at 50,000-tonne annual scales. This distributed processing model is compressing transportation emissions and feedstock aggregation costs for European resin producers.
REACH framework amendments now mandate polymer-level carbon footprint declarations for packaging placed on EU markets. ECHA's SCIP database requirements force brand owners to document bio-based content percentages through tiered supplier certifications. German bottlers are responding by dual-sourcing from Brazilian and European feedstock corridors to satisfy divergent national implementation timelines.
Beverage procurement teams now specify recycled-bio hybrid resins with third-party verified mass balance. This specification shift is displacing virgin fossil PET in premium water and juice segments. Japanese retailers are piloting blockchain-tracked bottle programs that reward consumer return rates with loyalty program credits.
Bio-PET Market Segmentation
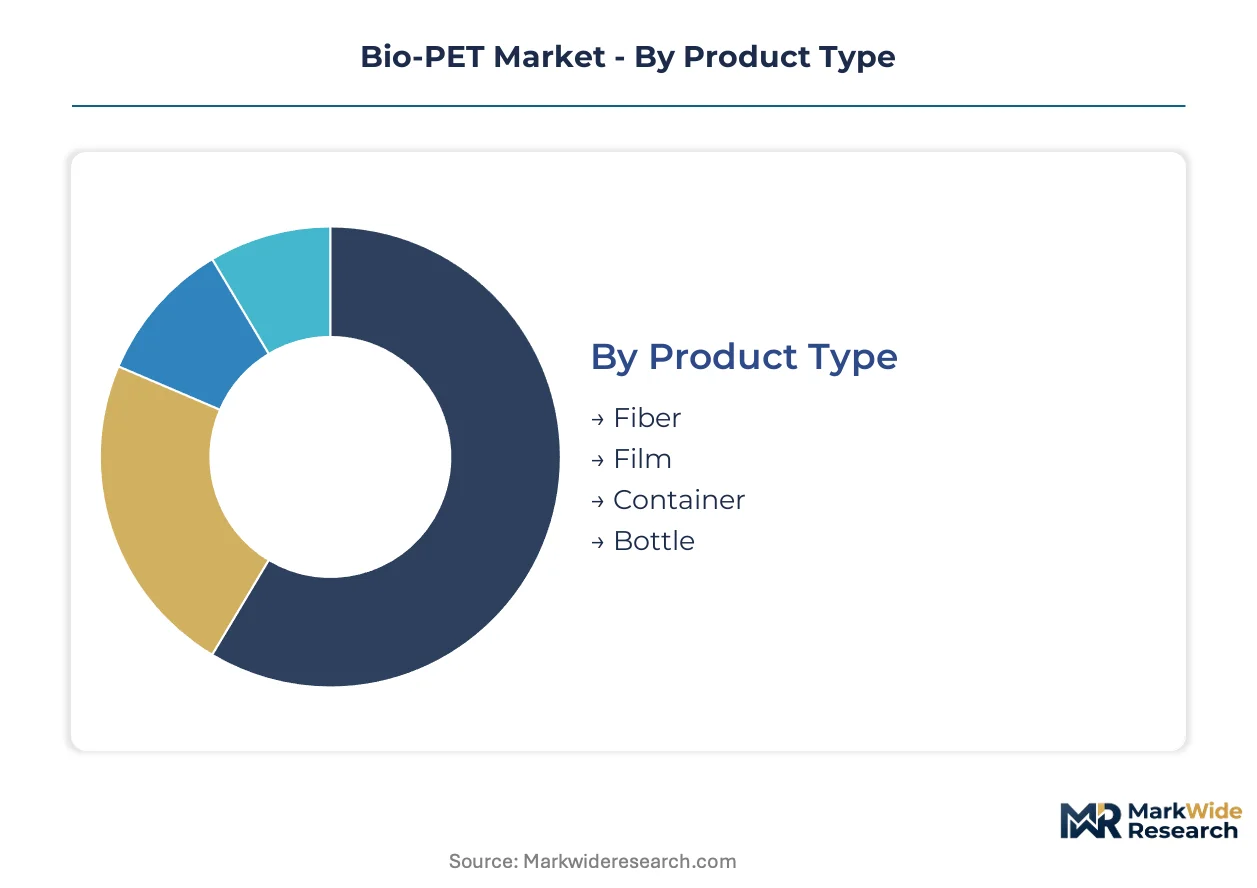
Bio-PET segmentation reveals how certification burdens concentrate in beverage and food-contact applications where FDA and EFSA compliance dominates procurement decisions. Technical specifications diverge sharply between textile-grade fiber and container-grade resin, forcing producers to maintain parallel production lines with distinct quality systems.
Product Type:
FDA food-contact approval requirements and REACH registration timelines create asymmetric compliance costs across product categories, with bottle and container grades bearing the heaviest documentation burdens.
- Bottle:Blow-molding grade resin with identical barrier properties to conventional PET requires ISCC PLUS mass-balance certification for European beverage bottlers. Demand concentrates in Germany and California where state-level mandates accelerate procurement from Brazilian sugarcane and European wheat straw feedstock corridors.
- Fiber:Textile-grade chip engineered for high-tenacity filament spinning serves athletic apparel brands specifying recycled-bio hybrid blends. Japanese automotive programs and European fashion houses drive the steepest specification tightening for carbon intensity disclosure.
- Container:Thermoforming sheet and preform resin for food trays and clamshell packaging faces EFSA migration limit testing that delays new product launches by 12-18 months.
- Film:Biaxially oriented grades for premium food packaging occupy narrow niches where clarity and oxygen barrier requirements exclude competing biopolymers like PLA.
Leading the category by volume: Bottle. Growing fastest: Fiber.
Application:
Cost tier stratification separates premium textile applications from commodity beverage packaging, with automotive components commanding the highest resin prices per kilogram.
- Beverage Packaging:Carbonated soft drink and bottled water segments dominate procurement volumes. German bottlers dual-source from Brazilian and European feedstock corridors to satisfy divergent national implementation timelines under the EU Green Deal.
- Textiles:Athletic apparel brands specify mass-balance certified fiber blends for visible sustainability credentials. Chemical recycling convergence with bio-based MEG enables fully circular fiber claims that command premium positioning.
- Food Packaging:Tray and clamshell applications face slower adoption due to EFSA approval bottlenecks and higher unit economics versus conventional PET.
- Automotive Components:Interior textiles and under-hood applications specified by Japanese and German vehicle manufacturers for fleet emissions compliance represent the smallest volume but highest margin pool.
Highest volume flow: Beverage Packaging. Steepest margin expansion: Automotive Components.
End User:
Customer type determines contract structure, with automotive and healthcare buyers demanding decade-long offtake agreements while consumer goods procurement operates on annual tenders.
- Food & Beverage:Bottling conglomerates and co-packers represent the anchor demand base, locking in sugarcane-ethanol-linked pricing that compresses supplier margins.
- Automotive:Tier-1 seating and interior suppliers specify bio-based fiber grades under direct contract with Japanese and German OEM lightweighting programs.
- Consumer Goods:Personal care and household product brands lag beverage adoption due to less visible sustainability pressure from retail channels.
- Healthcare:Medical device and pharmaceutical packaging applications face the most stringent FDA monomer purity requirements, limiting qualified resin sources.
Dominant procurement scale: Food & Beverage. Longest contract tenors: Automotive.
Distribution Channel:
Supply concentration in direct sales reflects the technical service intensity of Bio-PET qualification, with compounders embedding field engineers at major converter sites.
- Direct Sales:Resin producers maintain dedicated account teams for beverage bottlers and automotive tier-1s, bundling compliance documentation with every metric ton shipped.
- Wholesalers:Regional distributors serve mid-tier converters in Southeast Asian manufacturing hubs where Indorama Ventures dominates bottle-grade volume.
- Supermarkets:Retail procurement of private-label packaged goods creates indirect resin demand through converter specifications.
- Online Retail:E-commerce channels remain negligible for bulk resin transactions but emerging for small-lot specialty grades and sampling programs.
Primary volume pathway: Direct Sales. Fastest channel development: Wholesalers in Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil concentrates bio-ethanol feedstock production while Germany and Japan dominate conversion capacity. European and North American beverage brands source resin from both corridors to satisfy divergent compliance timelines.
Germany
Automotive suppliers and bottling clusters co-locate near biorefinery infrastructure in North Rhine-Westphalia. The Packaging Act awards preferential extended producer responsibility fees to materials exceeding 30% bio-based mass. Cologne and Hamburg host dual-certified production lines serving both domestic bottlers and export markets.
United States
California's recycled-content mandates drive procurement from Brazilian sugarcane corridors by beverage brands seeking compliance credits. FDA food-contact regulations govern monomer purity requirements for resin qualification. Los Angeles and San Francisco bottling hubs lock in decade-long offtake agreements with hedged ethanol-linked pricing.
Brazil
Sugarcane harvest yields and energy market arbitrage swing ethanol feedstock costs for global resin producers. Braskem leverages captive ethanol positions to anchor long-term supply contracts with European converters. São Paulo state biorefineries supply both domestic packaging manufacturers and export-oriented resin operations.
Japan
Vehicle manufacturers specify bio-based fiber grades for interior textiles and under-hood applications to meet fleet emissions targets. METI programs support R&D intensity in high-performance polymer grades. Nagoya and Osaka automotive clusters drive specification tightening for carbon intensity disclosure in supplier contracts.
India
FSSAI food-contact approvals for bio-based packaging remain underdeveloped, creating positioning opportunities for producers establishing local compounding partnerships. Maharashtra and Gujarat manufacturing hubs concentrate textile and packaging converter capacity. Mumbai beverage brands pilot imported resin trials pending domestic certification pathway clarity.
Bio-PET Market Vendor Landscape
Top-tier vendors anchor integrated petrochemical-biorefinery operations, while mid-scale compounders specialize in mass-balance certification services. The vendor base stratifies across feedstock-integrated producers, regional converters with chain-of-custody expertise, and technology licensors of enzymatic hydrolysis platforms. Dominant competitive moves include backward integration into sugarcane ethanol supply and geographic expansion of ISCC PLUS-certified compounding capacity.
Within the feedstock-anchored tier, Braskem and Indorama Ventures Public Company Limited exemplify divergent geographic strategies. Brazilian-origin Braskem represents captive ethanol supply models, while Bangkok-based Indorama Ventures Public Company Limited anchors Southeast Asian bottle-grade volume through integrated recycling and bio-based expansion. Toray Industries, Inc. occupies a position within the Japanese specialty fiber segment.
| Leading Market Players |
|---|
| Toyota Tsusho Corporation |
| Braskem |
| Toray Industries, Inc. |
| DuPont de Nemours, Inc. |
| Mitsubishi Chemical Group |
| Indorama Ventures Public Company Limited |
| NatureWorks LLC |
| M&G Chemicals |
| TEIJIN LIMITED |
| Others |
Supply Flow & Price Mechanics
Decade-long offtake agreements from German and California beverage bottlers force biorefinery operators to hedge feedstock exposure across multiple continents, compressing supplier margins and reshaping how resin producers structure contract pricing.
Pricing Analysis
Margin tightening in standard-grade resin reflects Brazilian sugarcane ethanol price volatility and the 70% petroleum-derived terephthalic acid floor. Three-tier pricing structure across premium certified, standard mass-balance, and economy unverified grades separates ISCC PLUS-certified volumes from generic bio-based claims. Cost-down pressure on European converters accelerates because German Packaging Act bonus credits reward verified bio-based content above 30% mass threshold. Food and beverage procurement teams show highest price sensitivity, while automotive tier-1s accept premium positioning for carbon intensity disclosure.
Supply Chain Analysis
ISCC PLUS and RSB chain-of-custody audits demand dedicated compliance personnel that smaller compounders struggle to staff, creating certification gating. Feedstock production concentrates in Brazil, with conversion capacity clustering in Germany and Japan. Raw material flows draw from sugarcane ethanol corridors, wheat straw enzymatic hydrolysis units, and petroleum-derived terephthalic acid. Single-source vulnerability runs through Brazilian harvest yield swings. Distribution runs through direct sales with embedded field engineers at major converter sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal packaging mandates and REACH registration timelines are forcing consolidation as compliance burdens outstrip smaller compounders' staffing capacity.
For Market Incumbents: Acquire captive ethanol supply positions or enzymatic hydrolysis technology licenses to defend against Brazilian feedstock price volatility. Build ISCC PLUS-certified compounding capacity in Southeast Asian manufacturing hubs where Indorama Ventures currently dominates bottle-grade volume, securing channel control before regional competitors match certification infrastructure. For New Entrants and Emerging Players: Begin with FSSAI food-contact approval partnerships in Maharashtra and Gujarat manufacturing hubs, where Mumbai beverage brands pilot imported resin trials pending domestic certification pathway clarity. Target textile-to-textile chemical recycling convergence as the most penetrable white-space, offering bio-based MEG integration with depolymerization technologies for athletic apparel brands seeking fully circular fiber claims. For Investors and Strategic Acquirers: The window for entry favors feedstock-anchored producers with dual-certified production lines serving divergent EU and US compliance timelines. Long-term viability hinges on backward integration into second-generation agricultural residue processing. Watch ECHA substance evaluation protocol acceleration as the inflection signal for new monomer approval timelines compressing from 36 toward 18 months.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethanol Feedstock | Captive Brazilian sugarcane supply anchors long-term European bottler contracts against price volatility. |
| ISCC PLUS Certification Expansion | Mass-balance documentation bundling with every metric ton satisfies German Packaging Act bonus credit requirements. |
| Enzymatic Hydrolysis Technology Licensing | Nordic biorefinery operators deploy 50,000-tonne wheat straw units, compressing transportation emissions for European resin producers. |
| Textile Chemical Recycling Convergence | Bio-based MEG integration with depolymerization enables fully circular fiber claims for Japanese athletic apparel brands. |
| Southeast Asian Compounding Capacity Buildout | Bangkok-based integrated recycling and bio-based expansion dominates bottle-grade volume across regional manufacturing hubs. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across resin procurement managers at beverage bottlers, technical R&D directors at fiber producers, biorefinery plant managers, and automotive tier-1 seating suppliers. Bottom-up volume modeling triangulated against top-down expenditure analysis from ECHA registration databases and FDA food-contact submission records.
Reconciliation of production volume disclosures, import-export flows, and capacity utilization rates informed analytical framework construction across the analysis window. Segmentation dimensions modeled include product grade tier, end-use application, certification status, and regional feedstock corridor. CAGRs derived from weighted average of historical trajectory and policy-mandated demand floors, with sugarcane ethanol futures curves and REACH amendment timelines as industry-specific forecast inputs.
Underlying measurement precision varies by segment; beverage packaging with established ISCC PLUS certification carries tighter precision than emerging textile chemical recycling applications. Forecasts reflect assumptions about regulatory implementation timelines and feedstock technology maturation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
North America Bioplastics Market
Bioplastics
Europe Bioplastics Market
Bioplastics
US Bioplastics Market
Bioplastics
Polyhydroxyalkanoate (PHA) Market
Bioplastics
Cellulose Bioplastic Market
Bioplastics
Asia-Pacific Bio Plasticizers Market
Bioplastics
Asia-Pacific Lactic Acid Market
Bioplastics
Biodegradable Superabsorbent Materials Market
Bioplastics
Global Bio-Polylactic Acid (PLA) Market
Bioplastics
Biodegradable Disposable Tableware Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Biocomposite Materials Market
Bioplastics
Biodegradable Plastics Market
Bioplastics
North America Polylactic Acid (PLA) Market
Bioplastics
Bio-Based Polyolefins Market
Bioplastics
Biopolymer Films Market