
 Middle East and Africa Polylactic Acid (PLA) Market | 2026-2036
Middle East and Africa Polylactic Acid (PLA) Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Polylactic Acid (PLA) Market Foresight
Saudi petrochemical producers is repositioning biopolymer output toward lactide feedstock integration. Total Corbion PLA leverages European lactide technology partnerships to anchor supply security for African converters. Gulf Biopolymers Industries Ltd. dominates domestic granule formulation while NatureWorks LLC extends brand recognition among Gulf packaging houses.
Polylactic acid is an aliphatic polyester synthesized from fermented plant starch, typically exhibiting a glass transition temperature near 60°C and melting point around 155-170°C, engineered to replace petroleum-derived plastics in thermoformed and extruded applications. Granules command the largest volume share as the foundational feedstock for regional compounders, while 3D printing filaments represent the fastest-growing application segment as Dubai and Cairo additive manufacturing hubs expand technical procurement. Packaging absorbs the dominant share of PLA sheet and film offtake across the Middle East and Africa, though biomedical-grade resins carry the highest margin pools due to purity certification requirements.
Saudi Standards, Metrology and Quality Organization (SASO) bioplastic labeling rules and South Africa's National Regulator for Compulsory Specifications (NRCS) food-contact standards are tightening compliance thresholds for imported PLA grades. The UAE's Ministry of Climate Change and Environment extended producer responsibility frameworks to cover single-use bioplastics, redirecting procurement toward certified compostable resins. Stakeholders must track how Egypt's food safety authority and Nigeria's standards bureau harmonize import testing protocols with Gulf technical regulations.
Market Dynamics
Saudi Arabia's SABIC-led industrial cluster is concentrating regional lactide feedstock demand, while UAE extended producer responsibility rules redirect procurement toward certified compostable resins across Gulf packaging houses.
Growth Catalysts
- Extended Producer Responsibility Frameworks:The UAE's Ministry of Climate Change and Environment mandates single-use bioplastics compliance, redirecting Gulf packaging buyers toward certified PLA grades and scaling procurement volumes.
- Food-Grade Sheet Extrusion Concentration:Saudi industrial clusters anchor regional demand for thermoformed PLA applications as domestic converters expand food-contact packaging capacity.
- Additive Manufacturing Hub Expansion:Dubai and Cairo technical procurement centers are driving filament offtake as regional 3D printing infrastructure matures.
Market Restraints
- Lactide Feedstock Volatility:European lactide technology partnerships create import dependency for African converters, exposing margins to currency and shipping cost fluctuations.
- Technical Performance Limitations:PLA's glass transition temperature near 60°C restricts hot-fill and microwave applications, capping penetration in Gulf food service segments.
- Composting Infrastructure Gaps:Industrial composting facility scarcity across Nigeria and Egypt undermines end-of-life value propositions for certified grades.
Strategic Opportunities
- South African Biomedical-Grade Certification:Purity-driven margin pools in surgical sutures and drug delivery systems remain underexploited by regional compounders.
- Egyptian Import Protocol Harmonization:Alignment between Egypt's food safety authority and Gulf technical regulations would streamline cross-border granule trade.
- Nigerian Standards Bureau Recognition:Early movers securing NRCS-equivalent testing protocols gain preferential access to West African converter networks.
Industry Challenges
- Composting Certification Timeline Compression:SASO bioplastic labeling rules and NRCS food-contact standards impose parallel compliance tracks, stretching quality assurance resources.
- Legacy Petroleum-Polymer Equipment Retrofit:Regional sheet extruders require screw and cooling line modifications to process PLA's distinct rheological profile.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Polylactic Acid (PLA) Market |
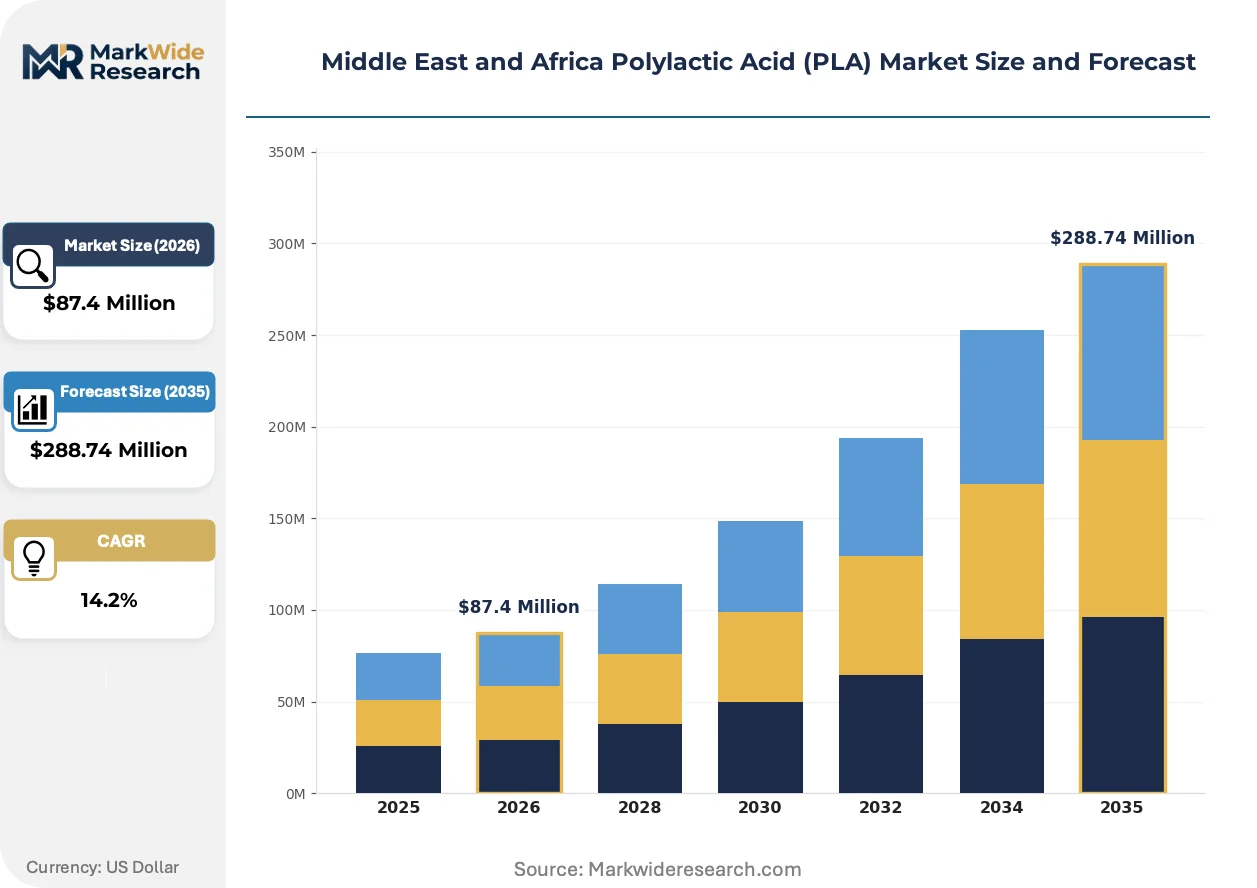
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $288.74 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Filaments, Sheets, Films End User: Packaging, Textiles, Automotive, Consumer Goods Application: 3D Printing, Disposable Tableware, Agricultural Films, Biomedical Distribution Channel: Online Retail, Direct Sales, Distributors, Others |
| Companies Covered | Galactic, Total Corbion PLA, TotalEnergies Corbion, Zhejiang Hisun Biomaterials, Synbra Technology, Gulf Biopolymers Industries Ltd., Futerro, Evonik Industries, NatureWorks LLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Polylactic Acid (PLA) Market Shifts & Advancements
Process intensification and regulatory alignment are compressing development cycles across Middle East and Africa PLA value chains, with automation and certification convergence emerging as dominant vectors.
Continuous lactide polymerization systems are automating reactor throughput optimization and molecular weight distribution control. Saudi petrochemical producers deploy these units to reduce batch-to-batch variation in food-grade granule output. The technology is automating quality assurance labor and accelerating Gulf converter qualification timelines.
SASO bioplastic labeling rules are tightening compositional disclosure requirements for imported PLA grades. Industrial consequence includes mandatory third-party biodegradability certification for products bearing compostable claims. Food-contact sheet extruders in the UAE and Saudi Arabia are responding by pre-qualifying European and Asian suppliers against harmonized test protocols.
Technical procurement from Dubai additive manufacturing hubs is consolidating filament sourcing through certified compounder networks rather than distributed resin traders. This channel compression displaces spot-market granule purchases with annual volume contracts tied to diameter tolerance guarantees. Cairo medical device prototyping centers exhibit the most pronounced preference for certified-origin filament with batch traceability documentation.
Middle East and Africa Polylactic Acid (PLA) Market Segmentation
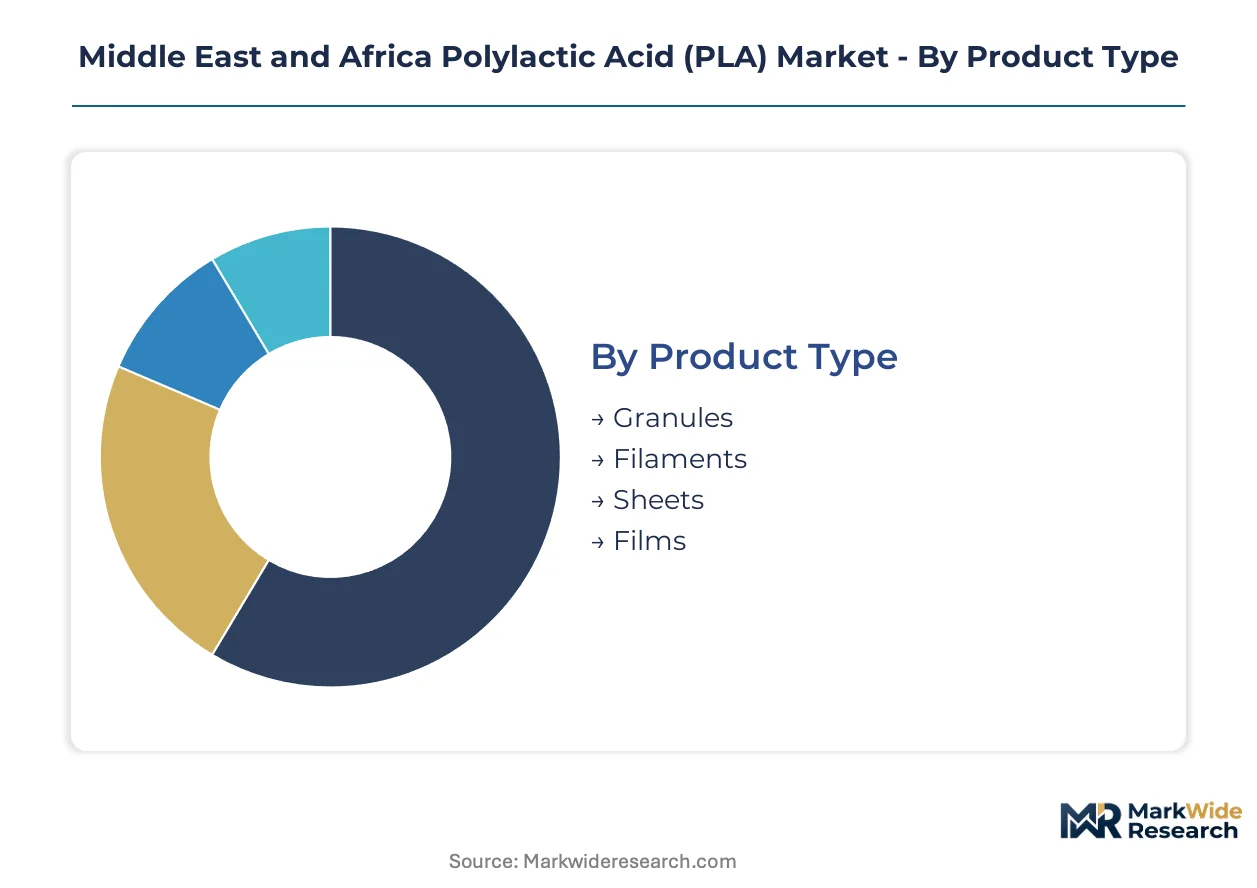
PLA market segmentation in the Middle East and Africa reveals how feedstock form, end-use specifications, and channel economics fragment procurement patterns across the value chain. Each dimension carries distinct margin profiles and regulatory exposure that shape converter sourcing decisions.
Product Type:
Standardization dominates pellet and sheet formats while custom compounding concentrates in filament grades, creating a spectrum from commodity feedstock to engineered specialty.
- Granules:These spherical or cylindrical pellets serve as the foundational feedstock for regional compounders, typically supplied in natural or white base grades requiring downstream color masterbatch addition. Saudi industrial clusters absorb the dominant volume for food-grade sheet extrusion as domestic converters expand thermoforming capacity. SASO bioplastic labeling rules mandate compositional disclosure that favors pre-qualified European suppliers with established certification documentation.
- Filaments:Precision-extruded monofilaments for fused deposition modeling range from 1.75mm to 2.85mm diameter with tight tolerance requirements. Dubai and Cairo additive manufacturing hubs are consolidating procurement through certified compounder networks rather than distributed resin traders, displacing spot-market purchases with annual volume contracts tied to diameter guarantees and batch traceability documentation.
- Sheets:Extruded flat stock for thermoforming applications spans 0.2mm to 3.0mm gauge ranges, supplied in roll or cut formats. UAE packaging converters source primarily from Saudi extrusion facilities to minimize freight exposure.
- Films:Blown or cast thin-gauge material for flexible packaging and agricultural mulch applications. South African converters lead regional demand for certified compostable film grades meeting NRCS food-contact standards.
Most installed capacity flows through granule supply chains. Expansion is steepest in filament formats as additive manufacturing infrastructure matures.
End User:
Volume concentration sits with high-throughput packaging operations while margin capture concentrates in biomedical and technical textile segments.
- Packaging:Thermoformed trays, clamshells, and flexible films for food-contact applications constitute the dominant demand sink. Extended producer responsibility frameworks across Gulf Cooperation Council jurisdictions redirect procurement toward certified compostable grades with mandatory third-party biodegradability certification.
- Biomedical:Surgical sutures, drug delivery systems, and tissue engineering scaffolds require purity certification and batch traceability that command substantial price premiums. South African compounders remain underexposed to this margin pool despite available technical capability.
- Textiles:Fiber applications span nonwoven hygiene products and woven apparel fabrics. Egyptian spinners are piloting PLA staple fiber production for export-oriented garment manufacturing.
- Automotive:Interior trim components and under-hood applications leverage PLA's renewable credentials for corporate sustainability reporting. Volume remains constrained by thermal performance limitations.
- Consumer Goods:Disposable cutlery, cosmetic packaging, and durable housewares. Nigerian distributors are building converter networks around imported granule supply.
Packaging commands the greatest granule offtake. Biomedical applications generate the highest unit margins.
Application:
Functional requirements fragment procurement between disposable single-use formats demanding cost minimization and technical applications requiring performance certification.
- 3D Printing:Fused deposition modeling feedstock demands precise diameter tolerance, consistent melt flow index, and minimal moisture content to prevent print failure. Cairo medical device prototyping centers exhibit pronounced preference for certified-origin filament with comprehensive batch traceability documentation.
- Disposable Tableware:Injection-molded cutlery, cups, and plates for food service replacement of conventional plastics. UAE hospitality sector procurement is scaling fastest under Ministry of Climate Change and Environment mandates.
- Agricultural Films:Mulch films and planting trays requiring soil biodegradability certification. Composting infrastructure gaps across Nigeria and Egypt undermine end-of-life value propositions for certified grades.
- Biomedical:Implantable and non-implantable medical devices subject to national pharmaceutical regulator oversight. South African surgical suture manufacturers represent the most developed regional demand cluster.
Disposable tableware absorbs the greatest volume. 3D printing filament is gaining share fastest among technical applications.
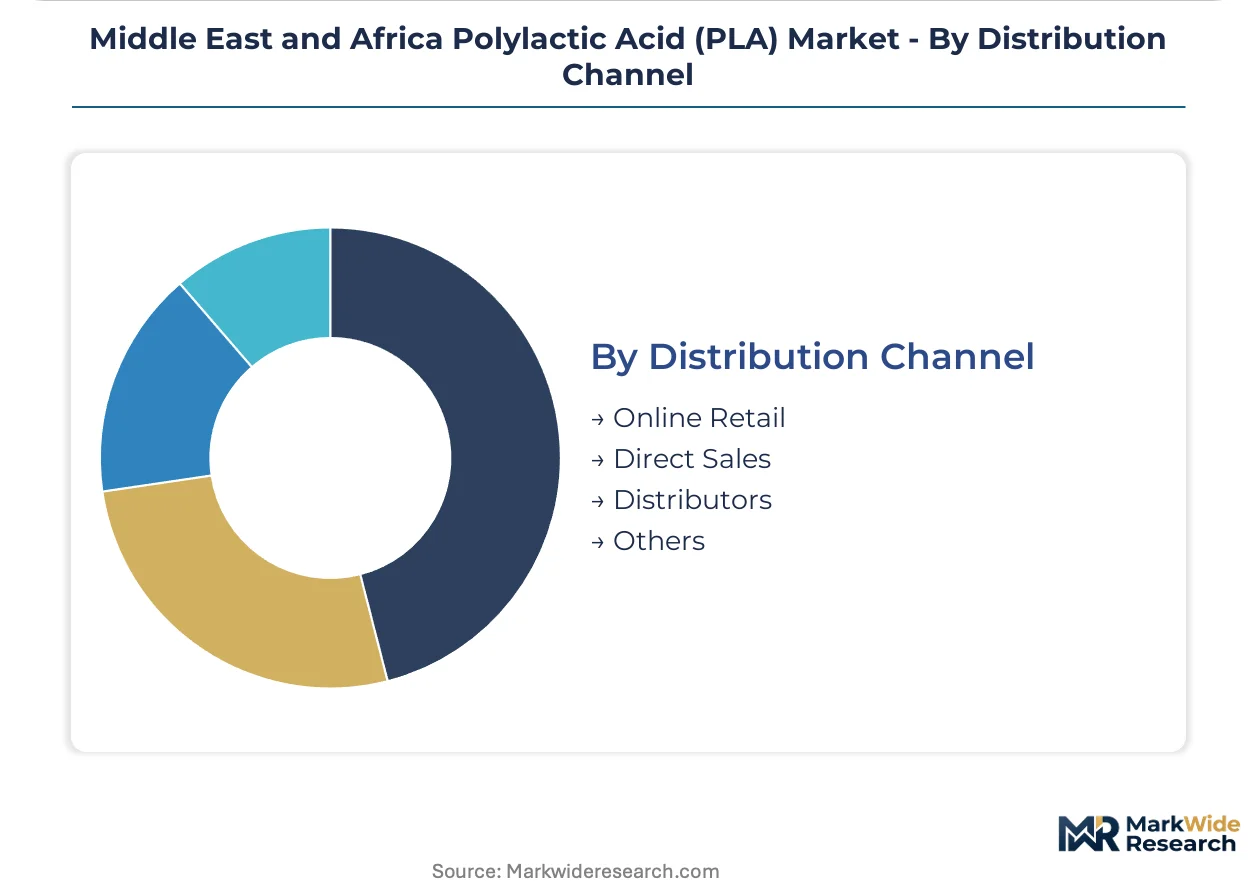
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to compounder infrastructure.
- Direct Sales:Large-volume converters negotiate annual contracts with lactide polymerization facilities for granule supply. Saudi petrochemical producers prioritize direct relationships with Gulf sheet extruders to secure food-grade qualification timelines.
- Distributors:Regional stockists provide technical support, inventory buffering, and local credit terms. West African converter networks rely on Lagos and Casablanca distribution hubs for granule access.
- Online Retail:E-commerce platforms serve small-batch filament purchasers and prototyping centers. Dubai additive manufacturing hubs consolidate through certified compounder portals rather than generic resin marketplaces.
- Others:Agent-mediated procurement and trading house arrangements for spot-market purchases. Currency volatility exposure concentrates in this channel for African converters.
Direct sales capture the greatest granule volume. Distributor networks are expanding fastest to serve underpenetrated sub-Saharan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting PLA procurement flows toward jurisdictions with harmonized certification frameworks. Producers migrate toward Gulf markets where SASO bioplastic labeling rules provide clearer compliance pathways than fragmented African standards regimes.
Saudi Arabia
Food-grade sheet extrusion demand concentrates in SABIC-led industrial clusters around Jubail and Yanbu. SASO bioplastic labeling rules mandate third-party biodegradability certification for compostable claims. Domestic converters are expanding thermoforming capacity to serve UAE packaging houses seeking freight-minimized supply.
United Arab Emirates
Dubai additive manufacturing hubs are consolidating filament procurement through certified compounder networks. The Ministry of Climate Change and Environment extended producer responsibility frameworks to cover single-use bioplastics. Industrial composting infrastructure gaps persist despite certification mandates from Abu Dhabi quality regulators.
South Africa
Biomedical-grade resin demand from surgical suture manufacturers generates the highest regional margin pools. The National Regulator for Compulsory Specifications enforces food-contact standards that pre-qualify European suppliers. Cape Town and Johannesburg compounders remain underexposed to purity-certified medical applications despite available technical capability.
Egypt
Spinners in the Nile Delta region are piloting PLA staple fiber production for export-oriented garment manufacturing. The country's food safety authority maintains import testing protocols that diverge from Gulf technical regulations. Alexandria port logistics create procurement friction for granule shipments destined for Cairo converter networks.
Nigeria
Lagos-based distributors are building converter networks around imported granule supply for disposable cutlery applications. The standards bureau has yet to harmonize NRCS-equivalent testing protocols with West African neighbors. Currency volatility exposure concentrates in agent-mediated procurement channels serving Kano and Ibadan industrial zones.
Middle East and Africa Polylactic Acid (PLA) Market Competitive Landscape
European producers anchor the technology-licensing tier; Gulf-based specialists hold formulation and distribution advantages. Market structure fragments across lactide polymerization facilities, regional compounders, and certified filament distributors. Three archetypes dominate: petrochemical-backed integrators controlling feedstock access, independent compounders serving converter networks, and additive-manufacturing material specialists. Competitive moves center on backward integration into lactide production and pre-qualification against harmonized Gulf certification protocols.
Among European-origin polymer developers, Total Corbion PLA and Futerro exemplify the technology-transfer archetype, licensing lactide polymerization systems to regional partners. Gulf Biopolymers Industries Ltd. occupies a position within the domestic formulation tier, supplying granule feedstock to Saudi sheet extruders. NatureWorks LLC represents the brand-recognition anchor among Gulf packaging houses seeking certified-origin supply with established SASO documentation.
| Leading Market Players |
|---|
| Galactic |
| Total Corbion PLA |
| TotalEnergies Corbion |
| Zhejiang Hisun Biomaterials |
| Synbra Technology |
| Gulf Biopolymers Industries Ltd. |
| Futerro |
| Evonik Industries |
| NatureWorks LLC |
| Others |
Supply & Pricing Matrix
Continuous lactide polymerization automation is compressing batch-to-batch variation costs while simultaneously concentrating formulation expertise among Saudi petrochemical producers with captive reactor capacity. This technology shift rewards integrated producers with pricing power over distributed compounders dependent on imported granule feedstock.
Pricing Analysis
Distributor margins of 12-18% separate spot-market granule traders from direct-contract sheet extruders in Saudi industrial clusters. Three-tier pricing structure across biomedical-grade, food-contact certified, and uncertified base resins reflects SASO documentation burden and purity testing overhead. Cost compression in standard granule tiers is intensifying because European lactide technology partnerships expose African converters to currency and shipping volatility. Small-batch filament purchasers through Dubai additive manufacturing hubs exhibit lowest price sensitivity due to diameter tolerance guarantees and batch traceability requirements.
Supply Chain Analysis
Freight cost differentials of 15-25% advantage Saudi extrusion facilities serving UAE packaging converters over European import alternatives. Supply concentrates in Saudi Arabia, the Netherlands, and Thailand for lactide polymerization feedstock. Raw material dependencies span fermented corn starch, lactic acid fermentation capacity, and polymerization catalyst systems. Single-source vulnerability concentrates in European technology licensing for continuous reactor systems. Distribution runs through direct annual contracts for large-volume Gulf sheet extruders and Lagos-based stockists for West African granule access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where SASO bioplastic labeling rules mandate third-party biodegradability certification, redirecting procurement flows toward pre-qualified suppliers with established documentation.
For Market Incumbents: Extend backward integration into lactide production to secure feedstock cost control against European import dependency. Fortify Gulf converter relationships through pre-qualification against harmonized SASO-NRCS test protocols before Egyptian and Nigerian standards bureaus complete harmonization. Capacity addition in Jubail industrial clusters anchors regional supply security. For New Entrants and Emerging Players: SASO bioplastic labeling rules in Saudi Arabia open a window for certified compounder network expansion serving Dubai additive manufacturing hubs. Target biomedical-grade resin formulation for South African surgical suture manufacturers where purity certification commands substantial premiums. Establish annual volume contracts with diameter tolerance guarantees rather than spot-market filament trading. For Investors and Strategic Acquirers: Roll-up economics work for regional compounder networks because fragmented African converter markets lack integrated formulation capability. Five-to-ten year viability hinges on certification infrastructure investment preceding standards harmonization. Acquisition target archetype: independent compounders with SASO pre-qualification and established Gulf packaging house relationships. Watch for Egyptian food safety authority alignment with Gulf technical regulations as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactide Production | Saudi petrochemical producers secure captive feedstock supply against European import volatility. |
| SASO Pre-qualification Investment | European suppliers accelerate Gulf converter qualification timelines through mandatory third-party certification. |
| Biomedical-grade Certification Pathway | South African compounders capture purity-driven margin pools in surgical suture applications. |
| Direct Sales Channel Expansion | Large-volume converters secure annual contracts bypassing distributor margin layers. |
| Additive Manufacturing Filament Specialization | Dubai hubs consolidate procurement through certified compounder networks with batch traceability. |
Research Methodology
Bottom-up packaging and biomedical modeling reconciled against top-down lactide polymerization capacity tracking forms the analytical core. Primary interviews with Saudi sheet extruder procurement leads, UAE Ministry of Climate Change and Environment regulators, South African surgical suture manufacturing executives, and Lagos-based distribution channel partners combined with secondary validation from SASO technical documentation, NRCS food-contact standards filings, and customs granule import records. Triangulation between converter demand signals and polymerization facility output data anchors volume estimates.
Input-output matrices map lactide feedstock availability through reactor utilization rates to downstream granule, filament, and sheet format offtake across the projection horizon. Segmentation dimensions span product type granularity, end-use certification tier, application functional requirements, and channel economics. CAGRs derive from slope analysis of year-over-year procurement scaling under extended producer responsibility mandates. Industry-specific forecast inputs include Dubai additive manufacturing hub filament demand curves and South African biomedical-grade resin purity premium trajectories.
Revisions become necessary when Egyptian food safety authority harmonization with Gulf technical regulations materializes or when Nigerian standards bureau adopts NRCS-equivalent testing protocols. Forecasts reflect assumptions around SASO labeling rule enforcement continuity and European lactide technology partnership stability. A model refresh is warranted upon material change in industrial composting infrastructure deployment across Nigeria and Egypt.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
US Bioplastics Market
Bioplastics
Biodegradable Superabsorbent Materials Market
Bioplastics
Global Synthetic and Bio Based Polypropylene Market
Bioplastics
Brazil Bioplastics Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Middle East Biodegradable Plastics Market
Bioplastics
Biodegradable Microbeads Market
Bioplastics
Biodegradable Insulated Panel Market
Bioplastics
China Bioplastics Market
Bioplastics
Biocomposite Materials Market
Bioplastics
Automotive Bioplastic Market
Bioplastics
Canada Bioplastics Market
Bioplastics
Synthetic and Bio-Based PMMA Polymethyl Methacrylate Size Market
Bioplastics
Polyhydroxyalkanoate (PHA) Market
Bioplastics
Asia-Pacific Lactic Acid Market
Bioplastics
Asia-Pacific Polylactic Acid (PLA) Market