
 Polylactic Acid (PLA) Straws Market | 2026-2036
Polylactic Acid (PLA) Straws Market Size, Share, and Industry Trends Forecast 2026-2036
Polylactic Acid (PLA) Straws Market Insights
Food-grade crystallinity standards above 40 percent is unwinding legacy commodity positioning across the PLA straw supply base. NatureWorks LLC leverages backward integration into corn-derived lactide feedstock to sustain cost parity against conventional polypropylene. TotalEnergies Corbion anchors European supply through its Thai lactic acid fermentation complex, while CJ Biomaterials competes on marine biodegradability certifications for coastal foodservice chains.
Polylactic acid straws are extruded thermoplastic tubes derived from fermented plant starch, typically exhibiting heat deflection temperatures between 55 and 60 degrees Celsius and industrial compostability under ASTM D6400 or EN 13432 protocols, serving as direct substitutes for polypropylene and polystyrene sipping devices in beverage service. Rigid straws dominate institutional procurement for smoothies and shakes where structural integrity under suction load matters most, while flexible straws with bendable corrugated necks capture quick-service restaurant fountain drink applications. Compostable straws certified for municipal anaerobic digestion command premium placement through wholesale distributors targeting university and corporate cafeteria accounts.
The FDA regulates PLA straws under food contact notification requirements for thermal stability and migration limits, while the EU F-Gas Regulation and Single-Use Plastics Directive jointly constrain competing synthetic alternatives and mandate labeling standards for biodegradability claims. ASTM D6400 and EN 13432 compostability certifications function as de facto market access gates for foodservice distributors in North America and Europe. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and anaerobic digestion infrastructure buildouts to align product specifications with actual end-of-life pathways rather than theoretical compostability.
Market Dynamics
Foodservice distributors are consolidating procurement specifications around crystallinity thresholds above 40 percent, forcing commodity-grade PLA straw producers to upgrade fermentation and extrusion capabilities or exit the supply base entirely.
Growth Catalysts
- EU Single-Use Plastics Directive:The framework mandates labeling standards and eliminates competing petroleum-based alternatives across member states, creating regulatory pull for certified compostable sipping devices.
- Quick-service restaurant chains:Fountain drink programs from Seattle to Miami are specifying marine-biodegradable PLA formulations for coastal metro locations.
- Lactide fermentation technology:Corn-derived feedstock processing is achieving cost parity with polypropylene through backward integration into agricultural supply.
Market Restraints
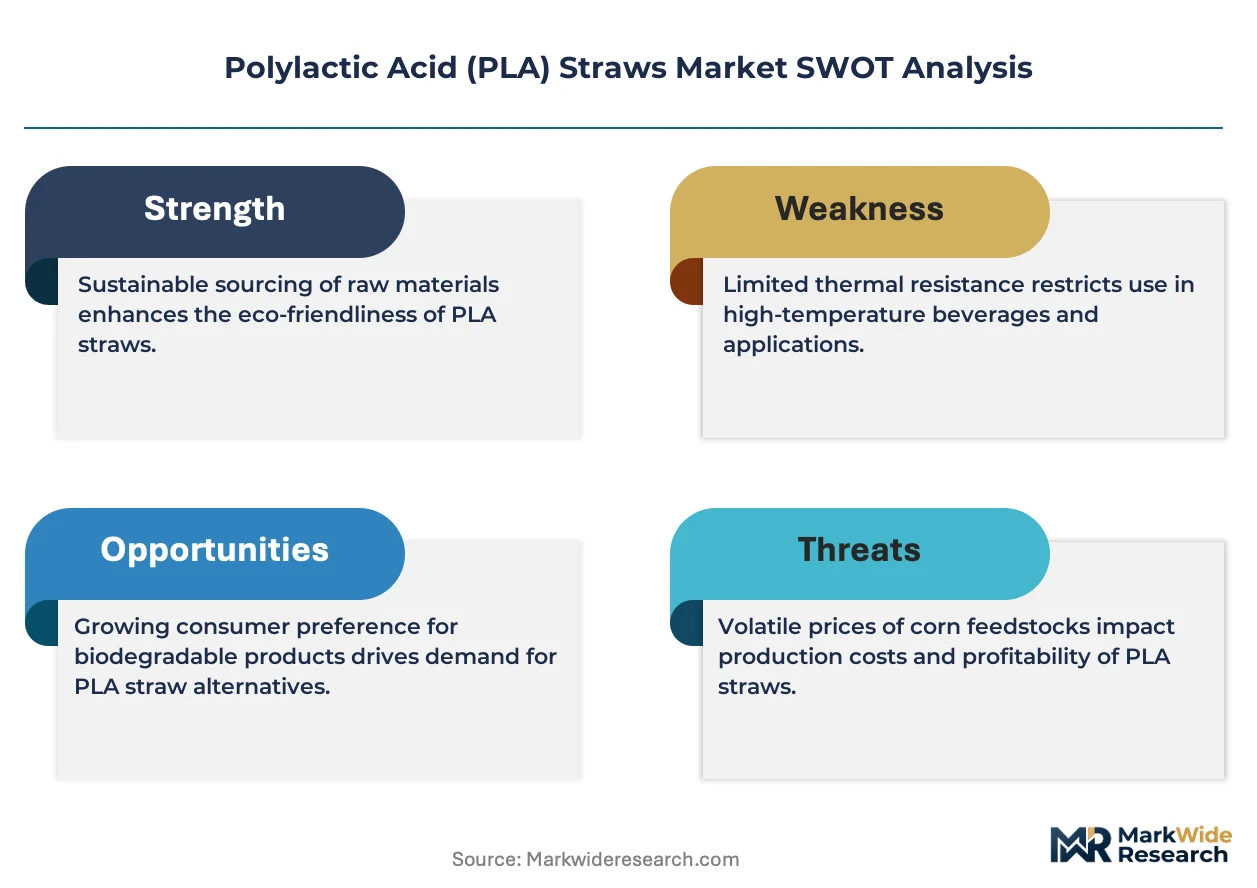
- Heat deflection limitations:PLA straws soften above 60 degrees Celsius, excluding them from hot beverage applications where polystyrene retains structural integrity.
- Thai lactic acid concentration:European supply chains depend on a single fermentation complex for feedstock, creating geographic vulnerability to tropical weather disruptions.
- ASTM D6400 certification costs:Industrial compostability testing and documentation impose fixed compliance burdens that disadvantage smaller extrusion operations.
Strategic Opportunities
- Anaerobic digestion infrastructure:Municipal biogas facility buildouts in Germany and the Netherlands create certified end-of-life pathways for straws meeting EN 13432 standards.
- University cafeteria accounts:Corporate and educational foodservice procurement is consolidating around compostable certification tiers, opening wholesale distributor channels.
- Flexible corrugated neck designs:Bendable straw architectures are capturing fountain drink volumes previously served by polypropylene with fixed geometries.
Industry Challenges
- Extended producer responsibility frameworks:State-level EPR legislation in California and New York requires supply chain documentation that many extruders lack systems to generate.
- Food contact notification timelines:FDA thermal stability and migration limit approvals stretch 18-24 months, delaying formulation innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polylactic Acid (PLA) Straws Market |
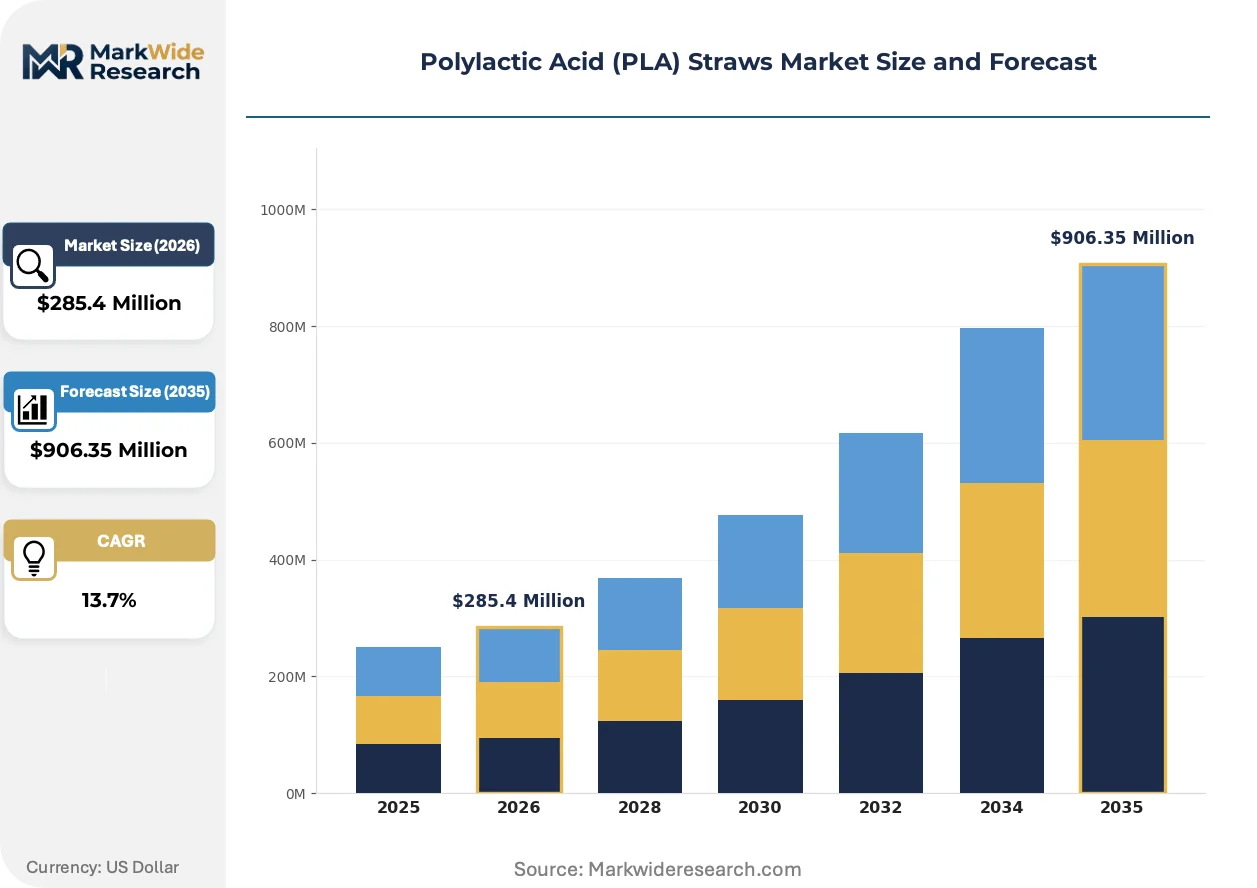
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $906.35 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Straws, Rigid Straws, Biodegradable Straws, Compostable Straws End User: Restaurants, Cafes, Food Trucks, Catering Services Distribution Channel: Online Retailers, Wholesale Distributors, Supermarkets, Specialty Stores Application: Cold Beverages, Hot Beverages, Smoothies, Shakes |
| Companies Covered | Nippon Straw, PT. Strawland, Straw Express, NatureWorks LLC, TotalEnergies Corbion, CJ Biomaterials, PLAMFG, EcoPak, Avani, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polylactic Acid (PLA) Straws Market Trends and Innovations
Extrusion die technology and fermentation control systems are compressing the performance gap between plant-derived and petroleum-based straws while certification requirements fragment the supply base into technical grade tiers.
High-crystallinity PLA formulations are miniaturizing the molecular architecture of fermented plant starch to achieve structural integrity under suction load equivalent to polypropylene. Smoothie chains and institutional foodservice buyers are specifying these grades for thick-beverage applications previously resistant to substitution. The technology is miniaturizing the performance differential between commodity bioplastics and conventional thermoplastics, collapsing the premium positioning of earlier PLA generations.
The EU F-Gas Regulation constrains synthetic fluorinated alternatives in parallel with the Single-Use Plastics Directive, eliminating competing disposable straw chemistries from the European market. Industrial compostability certifications under EN 13432 function as de facto market access requirements for distributors serving university and corporate accounts. Quick-service restaurant procurement teams in France and Germany are rewriting specifications to exclude non-certified alternatives entirely.
University and corporate cafeteria buyers are consolidating purchasing around wholesale distributors holding certified compostable inventory. Foodservice management companies are displacing direct mill relationships with bundled procurement contracts that include end-of-life documentation. This concentration is most visible along the United States coastal corridor from Seattle to Miami, where municipal composting infrastructure supports certified waste streams.
Polylactic Acid (PLA) Straws Market Segmentation
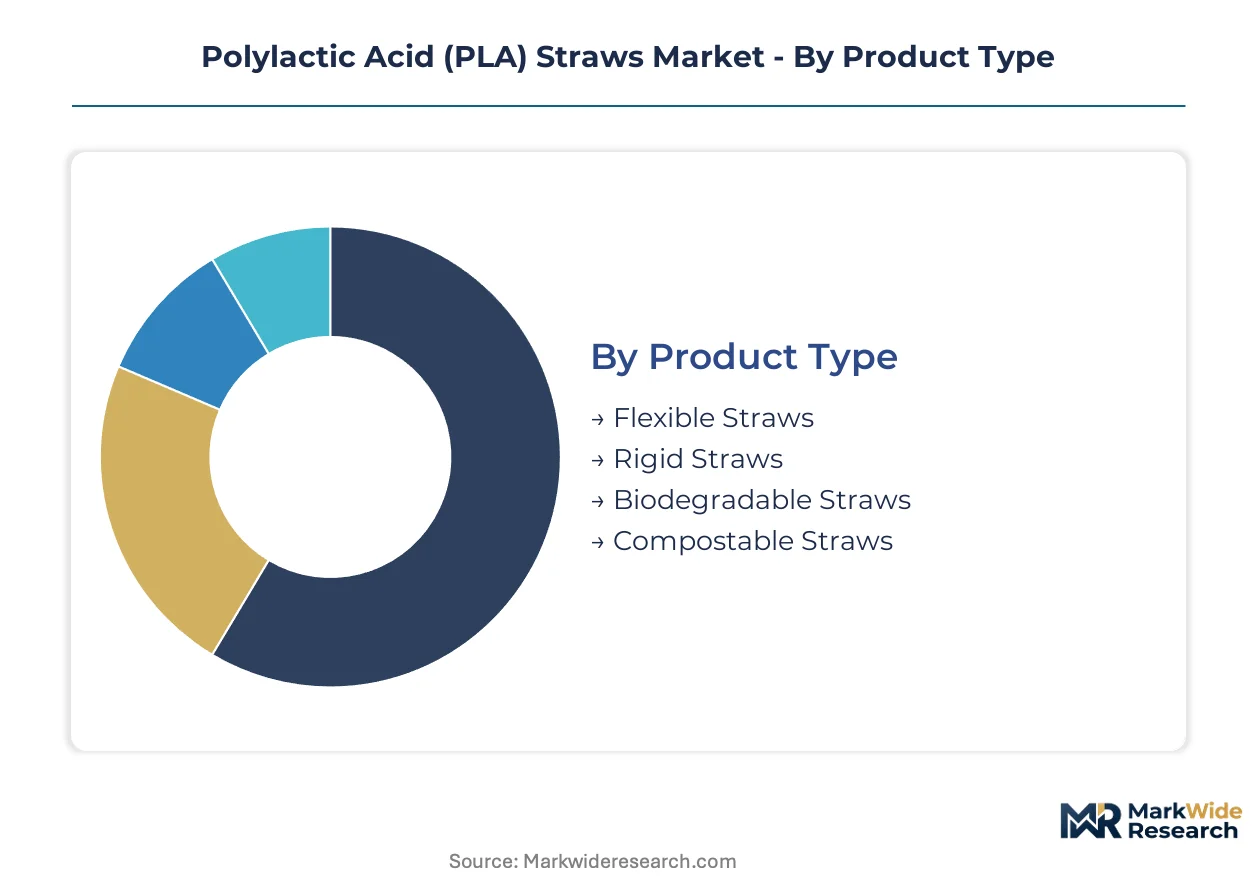
PLA straw procurement fractures across performance requirements, temperature thresholds, and composting infrastructure availability. Foodservice buyers select segments based on structural load demands, beverage viscosity, and end-of-life pathway access rather than material origin alone.
Product Type:
Flexible straws face the most intense substitution pressure from paper alternatives in fountain drink applications, while rigid formulations defend structural performance in thick-beverage service.
- Rigid Straws:Solid-wall extrusions with crystallinity above 40 percent withstand suction loads in smoothie and shake service. Quick-service chains from Seattle to Miami specify these grades for thick-beverage programs where structural collapse triggers customer complaints.
- Flexible Straws:Corrugated neck architectures bend without kinking, capturing fountain drink volumes previously served by polypropylene. Coastal metro procurement teams favor marine-biodegradable certified formulations for ocean-adjacent locations.
- Biodegradable Straws:Unspecified degradation claims without ASTM D6400 or EN 13432 documentation face regulatory exclusion across EU member states and California.
- Compostable Straws:Certified industrial compostability under standardized protocols commands premium placement through university and corporate cafeteria wholesale channels.
Rigid straws retain volume leadership; flexible straws hold the steepest expansion curve.
End User:
Cost tier stratification separates institutional procurement with certified documentation requirements from price-sensitive independent operators.
- Restaurants:Full-service chains specify food-grade crystallinity thresholds and thermal stability documentation under FDA food contact notification protocols. Backward integration into corn-derived lactide feedstock enables cost parity negotiations with petroleum-based alternatives.
- Cafes:Specialty coffee operators balance aesthetic presentation against compostability certification, with cold brew programs driving PLA specification over paper for clarity and mouthfeel.
- Food Trucks:Mobile operators prioritize space-efficient packaging and ambient storage stability over certification tiers due to variable waste stream access.
- Catering Services:Event-based procurement consolidates around disposable convenience with limited visibility into post-consumer composting infrastructure.
Restaurants command the highest certification premiums; food trucks represent the most price-elastic demand pool.
Distribution Channel:
Volume concentration flows through channels with documentation capabilities for extended producer responsibility compliance.
- Wholesale Distributors:Bundled procurement contracts with foodservice management companies displace direct mill relationships. EN 13432 certification tiers separate premium inventory from commodity grades in German and Dutch municipal anaerobic digestion corridors.
- Online Retailers:Direct-to-operator sales accelerate for independent cafes and food trucks seeking small-batch certified inventory without minimum order constraints.
- Supermarkets:Consumer-packaged PLA straw assortments compete with paper and reusable alternatives on retail shelf space.
- Specialty Stores:Eco-focused retail channels emphasize marine biodegradability certifications and transparent supply chain documentation for environmentally segmented consumers.
Wholesale distributors capture institutional volume; online retailers are climbing fastest in independent operator penetration.
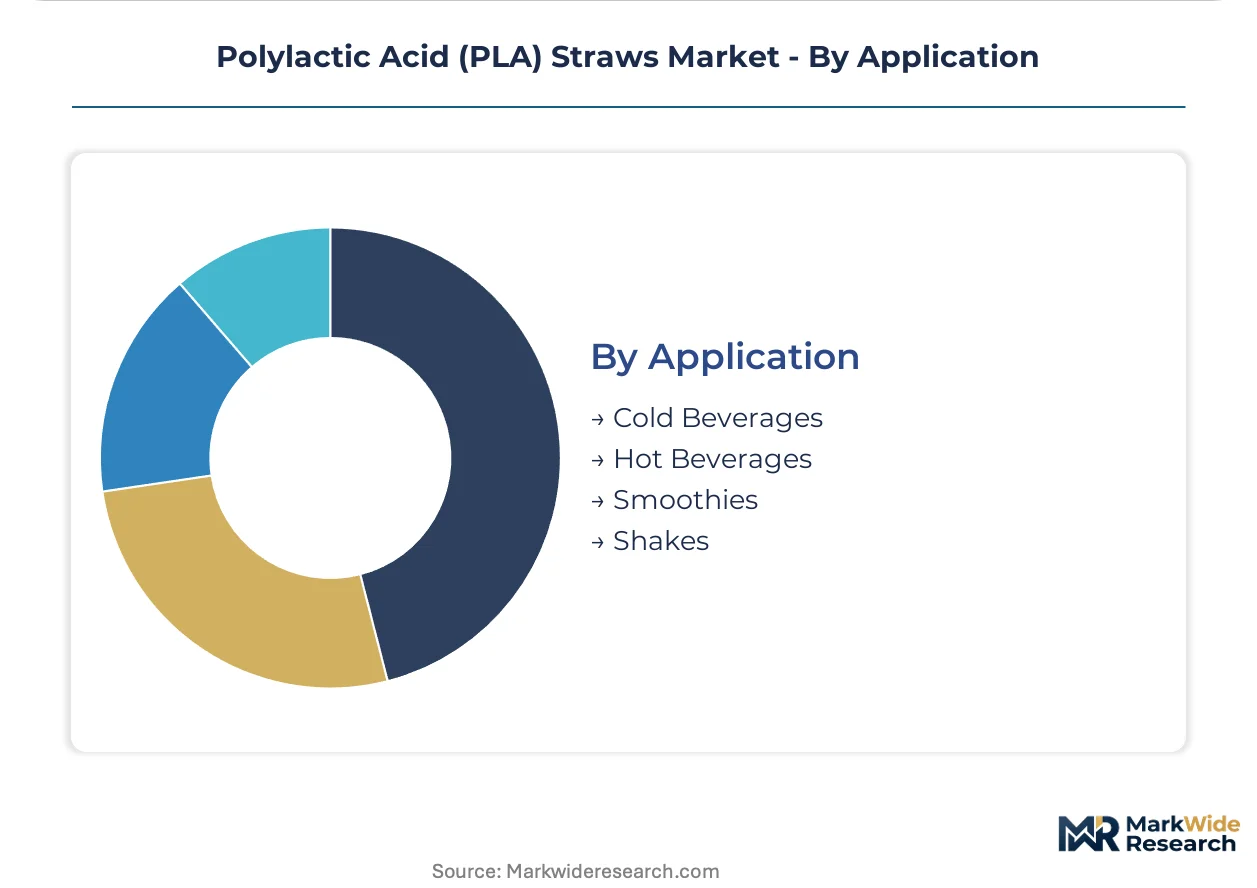
Application:
Temperature exposure creates a hard segmentation boundary where PLA heat deflection limitations exclude hot beverage service entirely.
- Cold Beverages:Fountain drinks, iced coffee, and soft drinks operate well below 55-degree Celsius thresholds, enabling full PLA substitution without performance compromise.
- Smoothies:High-viscosity blends require rigid straw architectures with reinforced wall thickness to prevent collapse under sustained suction load.
- Shakes:Frozen dessert applications demand the highest crystallinity grades to maintain structural integrity in thick, temperature-sensitive formulations.
- Hot Beverages:Temperatures exceeding 60 degrees Celsius soften PLA structures, reserving this segment for polystyrene and paper alternatives until heat-resistant bioplastic formulations achieve cost viability.
Cold beverages dominate unit volume; smoothies are gaining share fastest as crystallinity improvements unlock thick-beverage substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in coastal United States metros exhibit the lowest price elasticity, accepting certification premiums for marine-biodegradable grades, while independent foodservice operators in interior states remain highly price-sensitive to polypropylene alternatives.
United States
Quick-service restaurant chains from Seattle to Miami are specifying crystallinity thresholds above 40 percent for thick-beverage programs. The FDA food contact notification framework governs thermal stability documentation for PLA straws entering interstate commerce. NatureWorks LLC anchors supply through backward integration into corn-derived lactide feedstock from its Blair, Nebraska fermentation complex.
Germany
University and corporate cafeteria procurement is consolidating around EN 13432 certified inventory through wholesale distributors. The EU Single-Use Plastics Directive and F-Gas Regulation jointly eliminate competing petroleum-based alternatives from German foodservice channels. Municipal anaerobic digestion facilities in the Ruhr Valley and Bavaria create verified end-of-life pathways for certified compostable straws.
Thailand
TotalEnergies Corbion operates the lactic acid fermentation complex that anchors European PLA feedstock supply. The country's Board of Investment incentives support bioplastics manufacturing scale-up for export markets. Rayong Province hosts the integrated production corridor serving EU and North American extrusion operations.
Netherlands
Wholesale distributors serving Belgian and German border regions are building certified compostable inventory tiers for university accounts. The Dutch Waste Management Association mandates industrial compostability verification for bioplastics entering municipal organic waste streams. Rotterdam's port logistics cluster handles bulk lactide imports for European compounding operations.
France
Quick-service restaurant procurement teams are rewriting specifications to exclude non-certified alternatives entirely under national implementation of EU directive requirements. ANSM and national environmental agencies enforce labeling standards for biodegradability claims in foodservice packaging. The Paris metropolitan corridor concentrates foodservice management company headquarters driving bundled procurement contracts.
Polylactic Acid (PLA) Straws Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the PLA straw supply base. Fermentation specialists with captive lactide supply command margin structures unavailable to pure-play extrusion operations. The market separates into three strategic archetypes: backward-integrated biopolymer producers, regional extrusion specialists, and private-label converters serving distributor channels. Competitive moves center on capacity expansion in high-crystallinity grades and strategic partnerships with foodservice management companies for bundled procurement contracts.
Within the integrated biopolymer tier, NatureWorks LLC and TotalEnergies Corbion occupy positions that exemplify divergent geographic strategies—one anchored in North American agricultural feedstock, the other in Asian fermentation infrastructure. CJ Biomaterials represents the marine-biodegradable certification specialist archetype competing on coastal foodservice specifications. Regional extrusion players like Nippon Straw and PT. Strawland sit within the distributed manufacturing tier serving proximity-sensitive quick-service restaurant accounts across Asia-Pacific markets.
| Leading Market Players |
|---|
| Nippon Straw |
| PT. Strawland |
| Straw Express |
| NatureWorks LLC |
| TotalEnergies Corbion |
| CJ Biomaterials |
| PLAMFG |
| EcoPak |
| Avani |
| Others |
Pricing and Supply Chain Analysis
Corn-derived lactide displacing petroleum-based polypropylene in quick-service restaurant procurement simultaneously concentrates fermentation capacity in the United States Midwest and Thai coastal corridors while compressing price premiums for certified compostable grades. This substitution dynamic rewards backward-integrated producers with captive agricultural feedstock and penalizes pure-play extruders exposed to spot lactide markets.
Pricing Analysis
After-sales documentation revenue from EN 13432 and ASTM D6400 certification tiers drives lifetime value for wholesale distributors serving university and corporate cafeteria accounts. Three-tier pricing structure across premium, standard, and economy levels separates marine-biodegradable certified inventory from industrial compostable grades and uncertified commodity alternatives. Price differentiation hinges on crystallinity thresholds above 40 percent and thermal stability documentation under FDA food contact notification protocols. Cost compression in commodity grades is intensifying because smaller extrusion operations cannot absorb fixed compliance burdens. Independent food trucks exhibit the highest price sensitivity, while coastal quick-service chains from Seattle to Miami accept certification premiums for marine-biodegradable formulations.
Supply Chain Analysis
Inventory lead times for high-crystallinity PLA straws extend from fermentation through extrusion due to multi-stage quality verification for food-grade certification. Geographic supply concentration centers on Thailand for lactic acid fermentation, the United States for corn-derived lactide processing, and Germany for compounding and distribution to European extrusion operations. Raw material dependencies draw from corn starch feedstock, fermentation catalysts, and extrusion-grade polymer additives. Single-source vulnerability in Thai tropical weather exposure threatens European feedstock security. Distribution runs through wholesale foodservice management companies with bundled procurement contracts displacing direct mill relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through ASTM D6400 and EN 13432 certification requirements creates switching costs that lock in institutional procurement relationships and marginalize uncertified competitors.
For Market Incumbents: Fortify position through backward integration into corn-derived lactide feedstock and capacity expansion in high-crystallinity grades above 40 percent to defend against emerging Asian extrusion specialists with lower cost structures. Certification investment in marine-biodegradable protocols for coastal quick-service restaurant accounts represents the critical lever for margin defense against paper alternative substitution in fountain drink applications. For New Entrants and Emerging Players: Lead with flexible corrugated neck designs targeting independent cafes and food trucks through online retail channels where minimum order constraints exclude incumbent distributor relationships. The most penetrable white-space sits in university cafeteria accounts consolidating around compostable certification tiers, accessible through direct sales bypassing entrenched wholesale foodservice management company contracts. For Investors and Strategic Acquirers: Capital is best deployed toward backward-integrated biopolymer producers with captive fermentation assets rather than pure-play extrusion operations exposed to commodity lactide price volatility. Long-term viability over the projection horizon favors archetypes with demonstrated FDA food contact notification approval timelines and established relationships with quick-service restaurant procurement teams. The signal to watch is state-level extended producer responsibility framework implementation in California and New York, which would accelerate supply base consolidation around documentation-capable players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactide Feedstock | NatureWorks LLC anchors North American supply through captive corn-derived fermentation at its Blair, Nebraska complex. |
| Marine-Biodegradable Certification Investment | CJ Biomaterials captures coastal quick-service restaurant specifications with ocean-degradability protocols for Seattle-to-Miami metro corridors. |
| High-Crystallinity Grade Capacity Expansion | TotalEnergies Corbion's Thai fermentation complex supplies European extruders demanding structural integrity for thick-beverage applications. |
| Wholesale Distributor Partnership Consolidation | Foodservice management companies in Germany and the Netherlands bundle procurement contracts with end-of-life documentation requirements. |
| Flexible Corrugated Neck Design Launch | Bendable straw architectures displace polypropylene in fountain drink volumes previously resistant to plant-based substitution. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA food contact notification filings, EU Single-Use Plastics Directive implementation documents, and ASTM D6400 certification registries. Primary interviews engaged foodservice procurement directors at quick-service restaurant chains, wholesale distributor category managers, extrusion plant engineers, and composting facility operators across the United States coastal corridor and German municipal anaerobic digestion networks. Secondary validation drew from SEC filings of publicly traded biopolymer producers, customs data tracking lactide and PLA resin trade flows, and industry association reports from the Biodegradable Products Institute. Bottom-up volume estimates from extruder capacity and utilization rates triangulate against top-down demand calculations from quick-service restaurant fountain drink program specifications and university cafeteria procurement data.
Segmentation dimensions modeled include product type architecture, crystallinity performance tier, compostability certification status, end-user procurement sophistication, and distribution channel documentation capability across the analysis window. CAGRs derive from elasticity-adjusted demand projections for cold beverage substitution, thick-beverage structural integrity requirements, and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporate FDA food contact notification approval pipeline visibility and municipal anaerobic digestion infrastructure buildout schedules in Germany and the Netherlands.
Forecasts assume regulatory continuity in FDA food contact notification protocols and EU Single-Use Plastics Directive enforcement; material policy shifts such as accelerated extended producer responsibility frameworks or revised thermal stability migration limits would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Global Synthetic and Bio Based Biodegradable Plastics Market
Bioplastics
Biodegradable Plastics Market
Bioplastics
Biodegradable Insulated Panel Market
Bioplastics
Global Synthetic and Bio Based Polypropylene Market
Bioplastics
Cellulose Plastics Market
Bioplastics
Global Bioplastic Composites Market
Bioplastics
Starch-Based Plastics Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Asia-Pacific Lactic Acid Market
Bioplastics
Biocomposite Materials Market
Bioplastics
Biopolymers Market
Bioplastics
Europe Bioplastics Market
Bioplastics
Bioplastics and Biopolymers Market
Bioplastics
Southeast Asia Bio-PET Market
Bioplastics
Biobased Biodegradable Plastics Market
Bioplastics
Asia-Pacific Bio Plasticizers Market