
 Bioplastic Textile Market | 2026-2036
Bioplastic Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Bioplastic Textile Market Analysis
Aftermarket fiber recovery and closed-loop garment processing is reshaping margin distribution across the bioplastic textile value chain. NatureWorks LLC leverages its Iowa-based PLA resin capacity to anchor upstream supply for woven bioplastic applications. BASF SE competes through specialty starch-based polymer formulations engineered for textile-grade tenacity. Teijin Limited extends its position in cellulose-derived filament production, dominating Japan's technical textile segment.
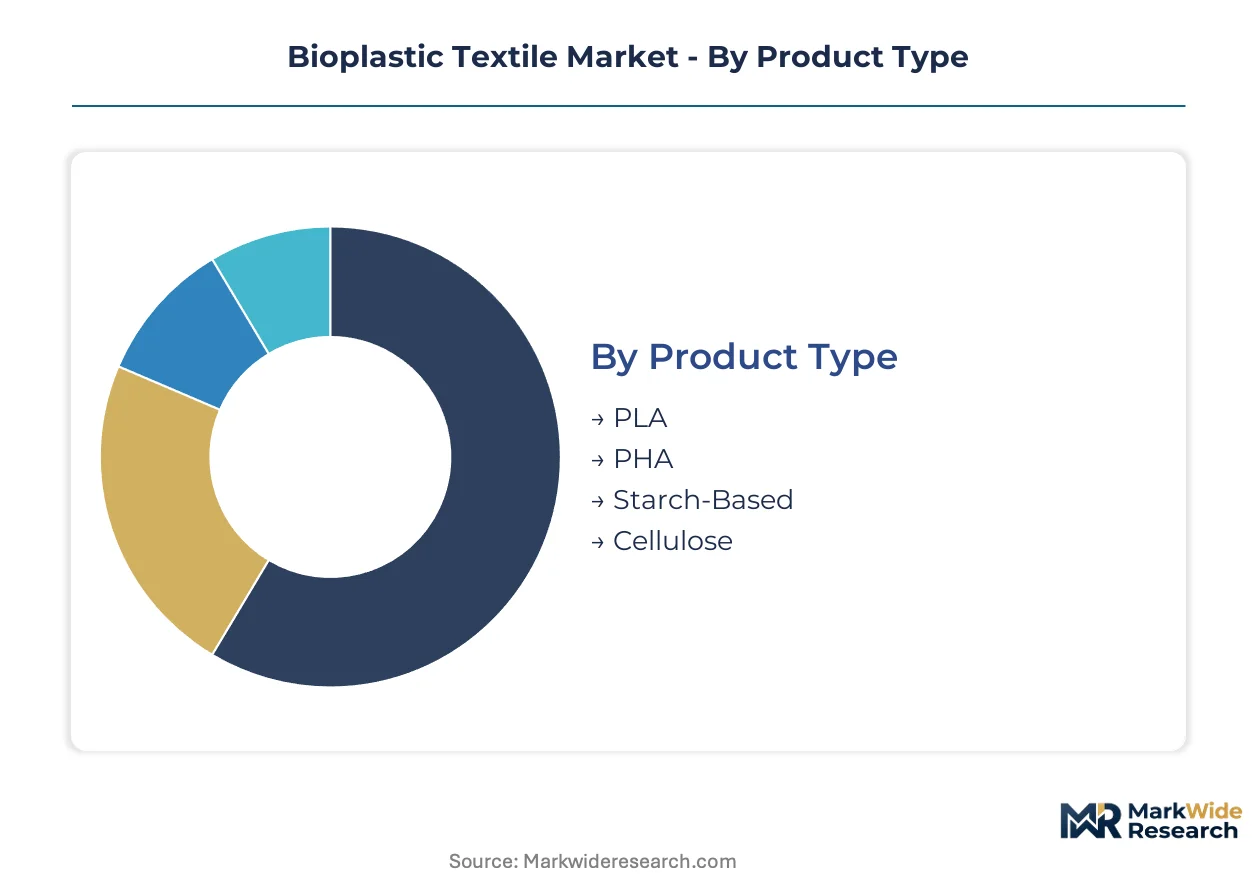
Bioplastic textiles comprise polymers derived from renewable biomass sources—principally polylactic acid, polyhydroxyalkanoates, and regenerated cellulose—processed into fibers meeting 1.5–3.5 decitex fineness specifications for apparel compatibility. These materials substitute petroleum-based polyester and nylon in applications requiring biodegradability or reduced carbon intensity. PLA fiber segments currently occupy the largest production volume share given mature fermentation infrastructure and cost-competitive lactic acid feedstock access. Cellulose-based variants represent the fastest-growing technology category as lyocell and modal processes achieve scale efficiencies. Starch-based formulations remain niche, constrained by moisture sensitivity, though upholstery applications sustain modest expansion.
The EU Green Deal and REACH chemical frameworks restrict microplastic shedding from synthetic textiles, directly stimulating bioplastic fiber substitution in European apparel manufacturing. FDA biocompatibility guidelines and EPA sustainable materials programs shape US market access requirements for medical and consumer textile applications. Stakeholders must monitor feedstock competition from food-grade PLA demand and evolving compostability certification standards across jurisdictions.
Market Dynamics
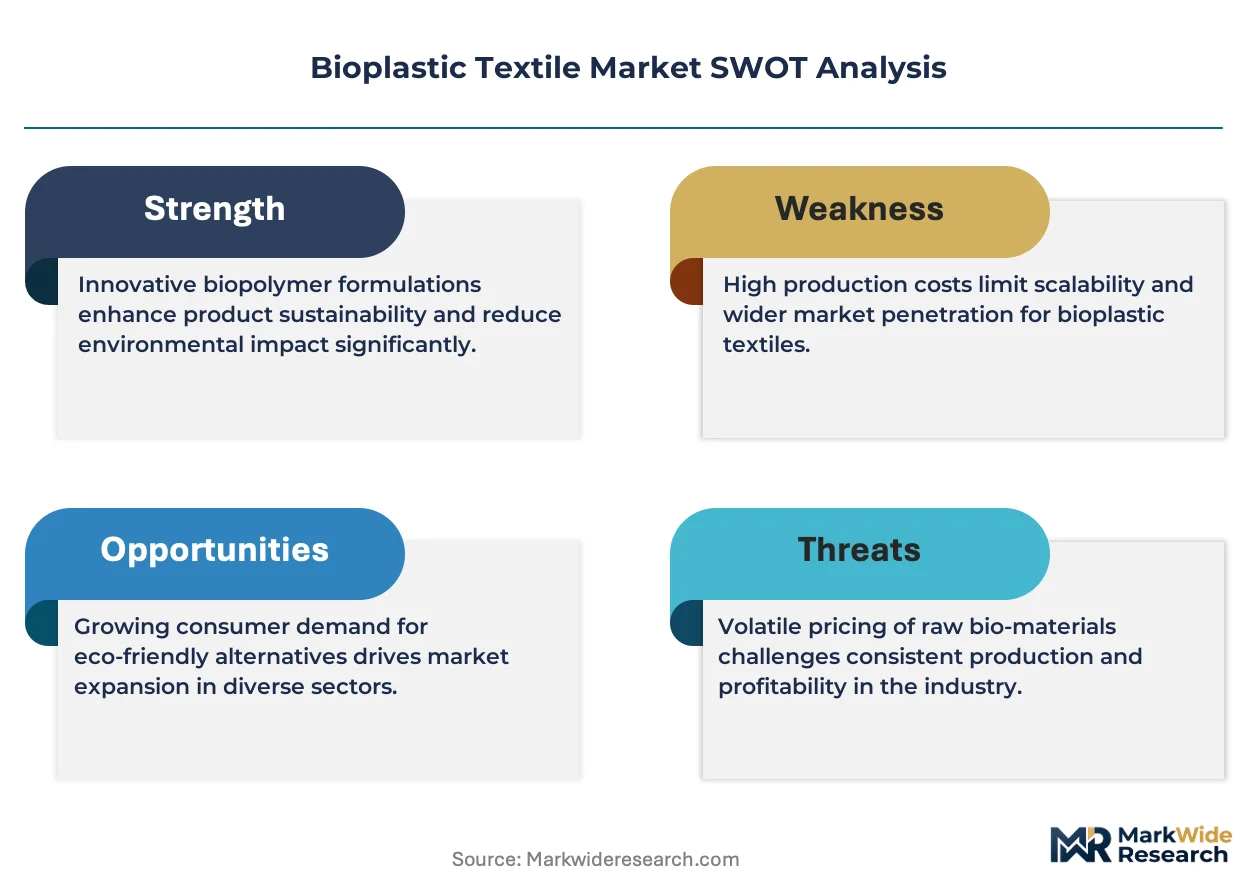
The EU Green Deal's microplastic restrictions and REACH chemical frameworks are forcing immediate substitution of petroleum-based synthetics, redirecting capital toward fermentation-based fiber production and closed-loop garment processing infrastructure.
Growth Catalysts
- REACH microplastic regulations:The EU's synthetic textile shedding limits mandate biodegradable fiber adoption across European apparel manufacturing, accelerating PLA and cellulose-based material procurement.
- Medical textile biocompatibility:FDA guidelines for implantable and patient-contact fabrics expand addressable demand for PHA and PLA fibers in surgical and wound-care applications.
- German chemical-apparel clusters:Co-located R&D facilities in Baden-Württemberg and North Rhine-Westphalia compress development cycles from lab-scale polymer to woven fabric qualification.
Market Restraints
- Lactic acid feedstock competition:Food-grade PLA demand from packaging applications constrains textile-grade resin availability, elevating input costs for fiber producers.
- Moisture sensitivity in starch polymers:Technical limitations restrict starch-based formulations to upholstery and non-apparel applications, capping addressable market expansion.
- Compostability certification fragmentation:Divergent industrial composting standards across Germany, France, and Italy create regulatory friction for cross-border textile distribution.
Strategic Opportunities
- Japan technical textile segment:Underpenetrated demand for cellulose-derived filaments in automotive interiors and industrial filters offers volume expansion beyond apparel.
- Lyocell-modal process convergence:Closed-loop solvent recovery systems reduce production waste and water intensity, enabling cost parity with viscose in Asian markets.
- US sustainable materials programs:EPA procurement preferences for federal uniform and facility textile contracts create a mandated demand channel for certified bioplastic fibers.
Industry Challenges
- Textile-grade tenacity engineering:Talent scarcity in polymer rheology and fiber spinning for bioplastics delays product qualification timelines against established polyester benchmarks.
- Closed-loop garment processing capex:Mechanical and chemical recycling infrastructure for end-of-life bioplastic textiles requires substantial capital deployment with unproven unit economics.
- Multi-jurisdiction compostability testing:Extended certification timelines across EU member states, Japan, and the US compress product launch windows and strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioplastic Textile Market |
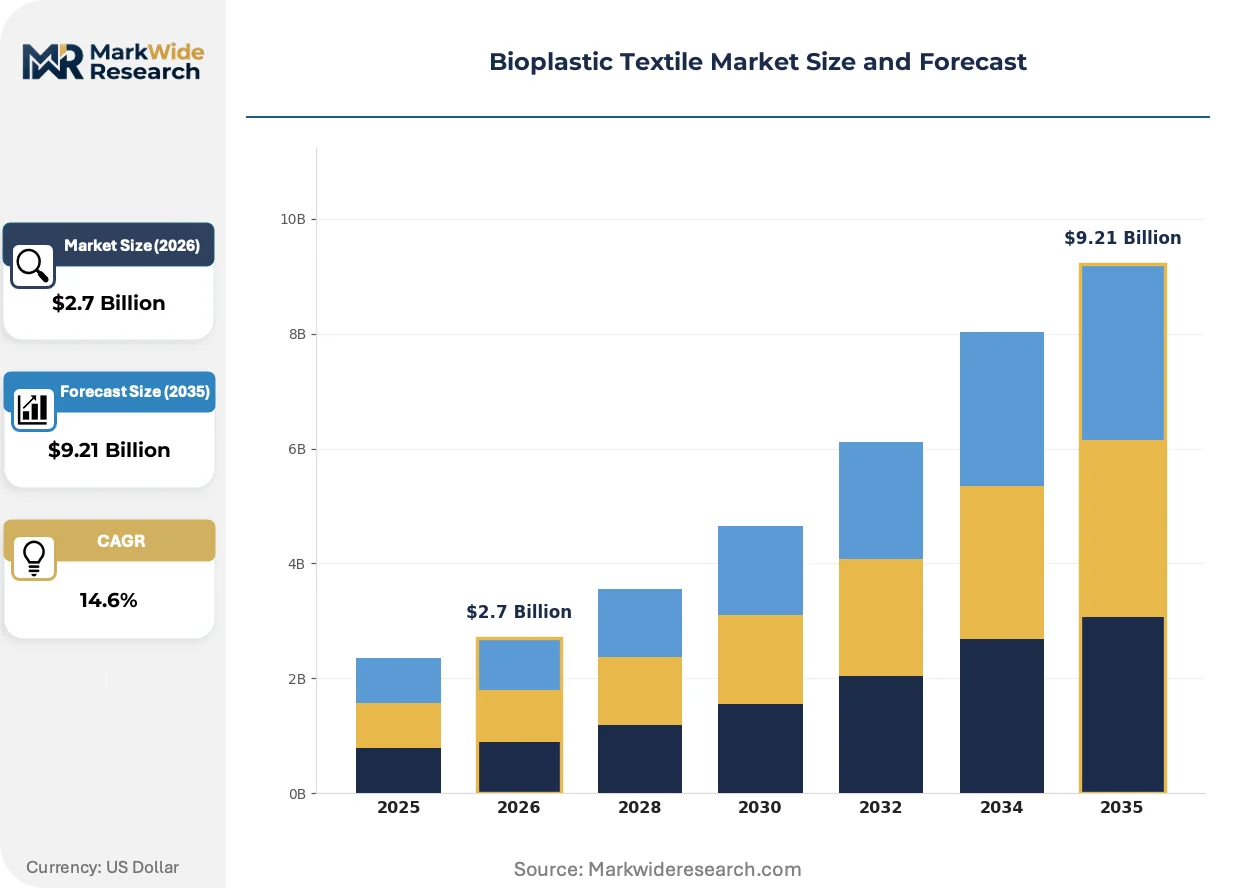
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $9.21 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PHA, Starch-Based, Cellulose End User: Apparel, Upholstery, Automotive Interiors, Packaging Technology: Extrusion, Injection Molding, 3D Printing, Weaving Application: Eco-friendly Textiles, Biodegradable Fabrics, Sustainable Fashion, Nonwoven Materials |
| Companies Covered | NatureWorks LLC, BASF SE, Teijin Limited, DuPont de Nemours Inc, Ercros SA, Gucci, Puma, Adidas, Lacoste, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioplastic Textile Market Emerging Trajectories
Digital process control and solvent recovery systems are compressing production costs for next-generation cellulosic fibers, while regulatory mandates restructure procurement specifications across institutional buyers.
Lyocell production technology is digitizing fiber formation parameters through real-time viscosity monitoring and automated jet-stretch controls. Luxury ready-to-wear houses in Milan and Paris are qualifying these materials for seasonal collections on compressed 12-month development cycles. The technology is digitizing quality assurance protocols, reducing batch-to-batch variation that previously limited high-fashion adoption.
REACH microplastic restrictions and the EU Green Deal textile sustainability requirements are eliminating synthetic fiber options for EU-based apparel brands. Manufacturers in Portugal and Romania are retrofitting spinning lines for PLA and cellulose blends to maintain market access. Technical textile segments in automotive and healthcare face parallel compliance pressure through the EU's Single-Use Plastics Directive extension proposals.
Luxury fashion procurement is consolidating supplier relationships around vertically integrated fiber-to-fabric providers with certified compostability credentials. Brands are bypassing traditional textile traders, contracting directly with polymer producers for exclusive fiber grades. This pattern is most visible in Germany and France, where chemical firms and couture houses co-develop proprietary material specifications under multi-year supply agreements.
Bioplastic Textile Market Segmentation
Bioplastic textile segmentation reveals how polymer chemistry, manufacturing technology, and end-use specifications intersect to determine commercial viability. Each dimension carries distinct margin profiles and regulatory exposure that reshape procurement strategies across apparel, automotive, and technical textile channels.
Product Type:
Mature fermentation infrastructure anchors PLA dominance while emerging polymer platforms scramble for scale.
- PLA:Polylactic acid fibers derive from corn starch fermentation, achieving 1.5–3.5 decitex fineness specifications required for woven apparel applications. German chemical-apparel clusters in Baden-Württemberg concentrate demand for textile-grade PLA resin as REACH microplastic restrictions eliminate polyester alternatives.
- Cellulose:Lyocell and modal processes using closed-loop solvent recovery systems are achieving cost parity with viscose in Asian manufacturing hubs. Luxury ready-to-wear houses in Milan and Paris are qualifying these materials for seasonal collections on compressed development cycles.
- PHA:Marine-biodegradable polyhydroxyalkanoates serve medical textile applications requiring FDA biocompatibility certification for implantable fabrics.
- Starch-Based:Moisture-sensitive formulations remain confined to upholstery and non-apparel segments despite feedstock abundance.
PLA handles the majority of throughput; cellulose is the fastest mover on share.
End User:
Customer-type concentration follows regulatory pressure gradients, with EU-based manufacturing facing the most acute substitution mandates.
- Apparel:EU Green Deal textile sustainability requirements are forcing immediate synthetic fiber substitution across Portuguese and Romanian spinning operations. Brands are contracting directly with polymer producers for exclusive fiber grades with certified compostability credentials.
- Automotive Interiors:Technical textile specifications for seating and panel applications favor cellulose-derived filaments with controlled thermal stability. Japan's automotive supply chain represents underpenetrated demand for these materials beyond traditional apparel channels.
- Upholstery:Starch-based polymer moisture limitations are less constraining in furniture applications, sustaining modest volume expansion.
- Packaging:Nonwoven bioplastic formats for protective wrapping compete directly with food-grade PLA demand, elevating input cost pressure for textile-grade resin allocation.
Apparel commands the dominant revenue share; automotive interiors are expanding most quickly as technical specifications mature.
Technology:
Process selection determines fiber tenacity, surface finish, and compatibility with downstream weaving or knitting equipment.
- Extrusion:Melt-spinning of PLA and PHA pellets into continuous filaments dominates volume production, leveraging existing polyester line retrofits in Portugal and Romania.
- Weaving:Conventional loom processing of bioplastic yarns requires tension calibration adjustments given lower elasticity moduli compared to petroleum-based synthetics.
- Injection Molding:Limited to technical textile components and nonwoven bonding applications rather than continuous fiber production.
- 3D Printing:Additive manufacturing of bioplastic textiles remains experimental, constrained by layer adhesion and surface texture limitations for apparel-grade outputs.
Extrusion maintains the installed base advantage; weaving is climbing the fastest as loom retrofits spread across EU manufacturing.
Application:
Certification requirements and end-of-life processing infrastructure segment addressable demand by biodegradability performance tier.
- Sustainable Fashion:Luxury houses are consolidating supplier relationships around vertically integrated fiber-to-fabric providers, bypassing traditional textile traders for direct polymer producer contracts with multi-year supply agreements.
- Biodegradable Fabrics:Industrial compostability certification fragmentation across Germany, France, and Italy creates regulatory friction for cross-border distribution of certified materials.
- Eco-friendly Textiles:EPA sustainable materials programs for federal uniform and facility textile contracts create mandated demand channels in the US market.
- Nonwoven Materials:Technical segments including surgical and wound-care applications expand addressable demand through FDA biocompatibility guidelines for patient-contact fabrics.
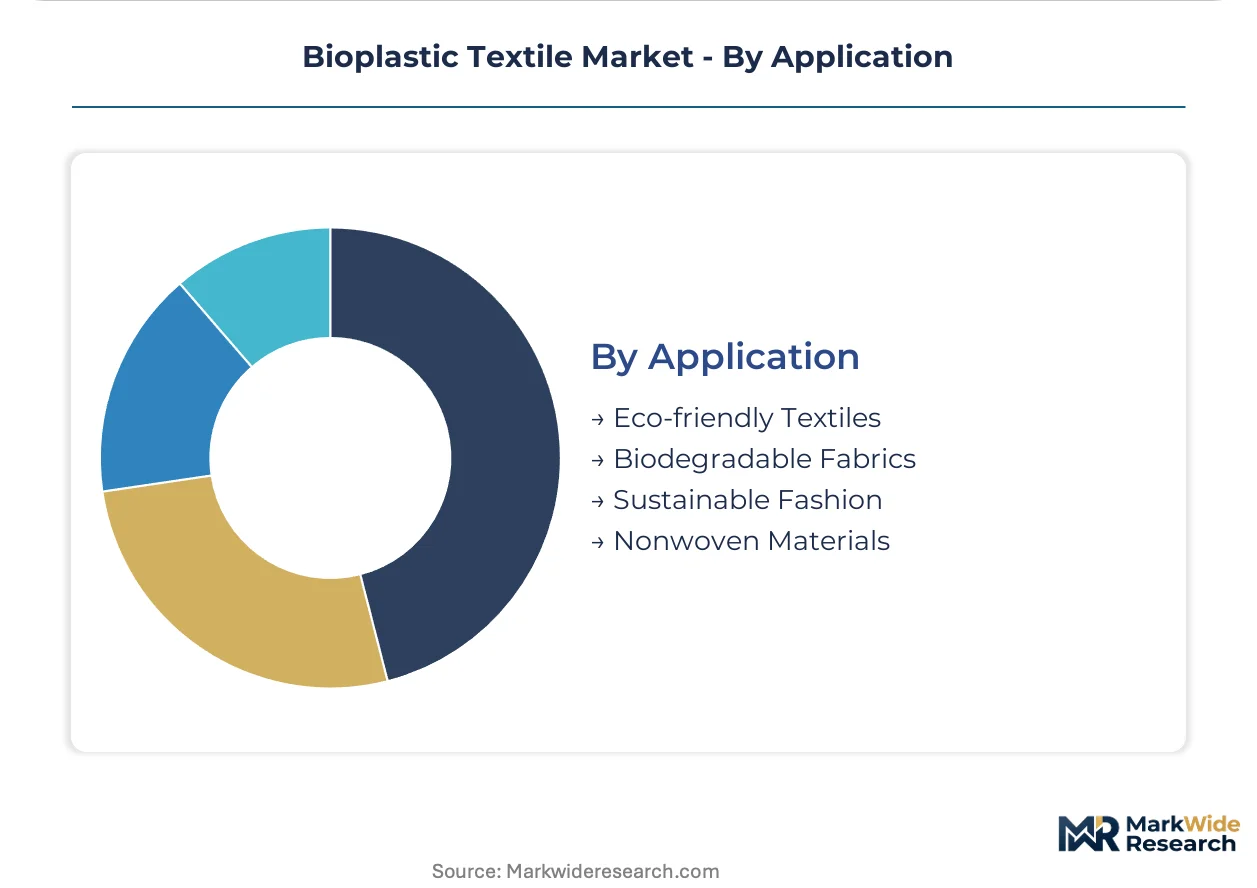
Sustainable fashion captures the premium pricing tier; biodegradable fabrics are gaining share fastest as compostability standards converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan exhibit low price elasticity for certified bioplastic textiles, while apparel manufacturers in Portugal and Romania face acute cost pressure from feedstock competition. Demand concentrates where chemical-apparel clusters co-locate and regulatory mandates eliminate synthetic alternatives.
Germany
REACH microplastic restrictions and EU Green Deal textile sustainability requirements are eliminating polyester options for domestic apparel brands. The country's national chemical regulator enforces strict industrial compostability certification standards for cross-border textile distribution. Baden-Württemberg and North Rhine-Westphalia host co-located R&D facilities where polymer producers and couture houses compress development cycles from lab-scale to woven fabric qualification.
United States
Federal procurement preferences under EPA sustainable materials programs create mandated demand channels for certified bioplastic fibers in uniform and facility textile contracts. FDA biocompatibility guidelines for patient-contact fabrics expand addressable demand for medical textile applications. Iowa-based fermentation infrastructure anchors upstream PLA resin supply for domestic fiber producers serving technical textile segments.
Japan
Automotive interior specifications favor cellulose-derived filaments with controlled thermal stability, generating underpenetrated demand beyond traditional apparel channels. METI standards for industrial compostability align with technical textile performance requirements. The Chubu region around Nagoya concentrates filament production capacity serving automotive supply chains with limited domestic bioplastic fiber competition.
France
Luxury ready-to-wear houses in Paris are qualifying lyocell and modal materials for seasonal collections on compressed development cycles. The EU Green Deal's textile sustainability requirements force immediate synthetic fiber substitution across manufacturing operations. Île-de-France hosts vertically integrated fiber-to-fabric providers with certified compostability credentials serving direct brand contracts.
Italy
Milan-based fashion houses are consolidating supplier relationships around polymer producers for exclusive fiber grades with multi-year supply agreements. Divergent industrial composting standards across EU member states create regulatory friction for certified textile distribution. Lombardy and Piedmont concentrate weaving operations retrofitting spinning lines for PLA and cellulose blends to maintain EU market access.
Bioplastic Textile Market Vendor Landscape
Specialty chemical conglomerates and dedicated biopolymer producers split the market between scale-driven resin supply and application-specific fiber engineering. The structure tilts toward upstream concentration where fermentation infrastructure and lactic acid feedstock access create defensive positions. Three archetypes dominate: integrated chemical-apparel cluster operators, lyocell process technology licensors, and luxury brand captive material development programs. Capacity expansion in Asian solvent-recovery systems and strategic partnerships for compostability certification represent the dominant competitive vectors.
Within the integrated chemical tier, NatureWorks LLC and BASF SE exemplify divergent strategic positions. The Iowa-based limited liability company anchors North American PLA resin capacity for textile-grade applications, while the German societas europaea competes through specialty polymer formulations engineered for tenacity specifications. Teijin Limited occupies a position in cellulose-derived filament production, representing the technical textile specialist archetype with concentration in Japanese automotive and industrial filter segments. These three entities collectively illustrate how geographic feedstock advantages and regulatory proximity to end-use markets determine competitive positioning.
| Leading Market Players |
|---|
| NatureWorks LLC |
| BASF SE |
| Teijin Limited |
| DuPont de Nemours Inc |
| Ercros SA |
| Gucci |
| Puma |
| Adidas |
| Lacoste |
| Others |
Supply Flow & Price Mechanics
Iowa-based PLA resin concentration anchors upstream supply for North American textile-grade fiber production, concentrating margin capture with fermentation infrastructure owners while downstream weaving operations in Portugal and Romania face compressed conversion economics.
Pricing Analysis
Aftermarket fiber recovery and closed-loop garment processing revenue tiers drive lifetime value for integrated producers. Three-tier pricing structure across premium certified-compostable, standard industrial-grade, and economy non-certified levels separates luxury fashion procurement from mass-market apparel. Cost compression in standard-grade PLA fiber is intensifying because food-grade packaging demand constrains lactic acid feedstock allocation. Mass-market apparel manufacturers in Eastern Europe exhibit highest price sensitivity; German chemical-apparel clusters demonstrate lowest elasticity given regulatory substitution mandates.
Supply Chain Analysis
Contract-manufacturing concentration for bioplastic textile conversion rests with Portuguese and Romanian spinning operations retrofitting polyester lines, alongside emerging Thai and Indonesian lyocell solvent-recovery facilities. Feedstock draws from Iowa corn starch fermentation, Thai sugarcane-based lactic acid, and Austrian wood pulp cellulose. Single-source vulnerability in textile-grade PLA resin supply from NatureWorks' Iowa facility creates geographic concentration risk. Distribution runs through vertically integrated fiber-to-fabric providers bypassing traditional textile traders for direct brand contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around luxury fashion houses contracting directly with polymer producers, fragmenting traditional textile trader intermediation and compressing margin pools for undifferentiated converters.
For Market Incumbents: Harden defensive positions by securing captive lactic acid feedstock through backward integration into corn starch processing or long-term offtake agreements with Iowa fermentation facilities. Invest in multi-jurisdiction compostability certification to preempt regulatory fragmentation across Germany, France, and Italy. The priority lever is exclusive fiber grade development with Paris and Milan couture houses under multi-year supply agreements that lock out specialty starch-based polymer competitors. For New Entrants and Emerging Players: Build out white-space presence in Japan's automotive interior technical textile segment, where cellulose-derived filament specifications favor controlled thermal stability and domestic competition remains limited. Target medical textile applications requiring FDA biocompatibility certification for surgical and wound-care fabrics, as PHA fiber penetration sits below apparel substitution rates. A go-to-market angle partnering with Nagoya-area automotive suppliers for seating and panel applications bypasses established apparel channel barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed lyocell process technology licensors holding solvent-recovery system intellectual property but lacking downstream brand relationships. Long-term viability across the analysis window favors acquisition targets with certified compostability credentials and direct luxury house contracts rather than commodity resin producers facing food-grade PLA demand competition. The signal to watch is convergence of industrial composting standards across EU member states, which would eliminate current certification fragmentation friction and re-rate integrated fiber-to-fabric providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Corn starch fermentation capacity in Iowa secures lactic acid allocation against packaging demand competition. |
| Multi-Jurisdiction Certification Investment | REACH-aligned compostability credentials unlock cross-border distribution for German chemical-apparel clusters. |
| Direct Brand Contracting | Paris and Milan luxury houses bypass textile traders for exclusive fiber grades with proprietary specifications. |
| Lyocell Process Licensing | Closed-loop solvent recovery systems achieve cost parity with viscose in Thai and Indonesian manufacturing hubs. |
| Technical Textile Segment Expansion | Nagoya automotive supply chains generate underpenetrated demand for cellulose-derived filaments beyond apparel. |
Methodological Framework
A spread of perspectives from polymer plant managers, luxury brand procurement directors, Portuguese spinning line operators, and German chemical R&D leads converged on the working assumptions driving this analysis. Primary interviews with downstream OEM textile buyers and distribution channel partners were validated against customs and trade data, SEC filings from specialty chemical conglomerates, EU ECHA regulatory submissions, and fiber production capacity disclosures. Bottom-up volume modeling from individual facility outputs and top-down demand segmentation from end-use applications were triangulated to constrain forecast variance.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning polymer chemistry, manufacturing technology, end-use specifications, and regional regulatory clusters. CAGRs were derived from fitted growth curves against historical substitution rates and policy mandate timelines. Industry-specific forecast inputs included REACH microplastic restriction implementation schedules and FDA biocompatibility guideline evolution for patient-contact fabrics.
Stress conditions across lactic acid feedstock price volatility, compostability certification timeline extensions, and luxury fashion procurement cycle compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding policy implementation fidelity and fermentation infrastructure expansion rates. Quarterly review of EU Green Deal textile sustainability requirement enforcement actions and NatureWorks capacity utilization disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Compostable Phone Cases Market
Bioplastics
Canada Bioplastics Market
Bioplastics
Global Bioplastic Market
Bioplastics
Global Bioplastic Composites Market
Bioplastics
Biodegradable Microbeads Market
Bioplastics
Synthetic and Bio-Based PMMA Polymethyl Methacrylate Size Market
Bioplastics
Global Bio-Plasticizers Market
Bioplastics
Brazil Bioplastics Market
Bioplastics
Bio-Based Succinic Acid Derivatives for Plasticizers Market
Bioplastics
Bio-Based Polyolefins Market
Bioplastics
Southeast Asia Bioplastics Market
Bioplastics
US Bioplastics Market
Bioplastics
Cellulose Plastics Market
Bioplastics
Polyhydroxyalkanoate (PHA) Market
Bioplastics
Global Bioresorbable (Resorbable) Polymers Market
Bioplastics
Biodegradable Disposable Tableware Market