
 Cetostearyl Alcohol Market | 2026-2036
Cetostearyl Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Cetostearyl Alcohol Market Analytics
Specialty chemical distribution is tilting toward direct manufacturer-formulator relationships in the cetostearyl alcohol trade. BASF SE leverages its integrated oleochemical network to sustain bulk supply contracts across European pharmaceutical compounders. Croda International PLC anchors its position through lipid-specialist R&D facilities in the United Kingdom. VVF LLC competes on price through high-volume manufacturing scale at its Indian operations.
Cetostearyl alcohol is a fatty alcohol blend, typically comprising cetyl alcohol and stearyl alcohol in varying ratios, produced via catalytic hydrogenation of vegetable-derived fatty acids or petroleum-based feedstocks; it functions primarily as a non-ionic surfactant, emulsion stabilizer, and viscosity-building agent in topical formulations and industrial preparations. Pharmaceutical-grade material commands premium positioning due to compendial compliance burdens under USP and EP monographs, while cosmetic-grade supply faces margin compression from clean-label substitution pressures. The emulsifier application segment leads volume consumption across personal care and topical drug categories, with thickener demand accelerating in silicone-free hair conditioning formulations.
REACH registration requirements and ECHA substance evaluation protocols constrain import pathways into European Union formulations, while FDA compliance with USP-NF monographs governs pharmaceutical-grade market access in the United States. India's CDSCO and BIS standards increasingly influence specification benchmarks for regional generic drug manufacturers sourcing cetostearyl alcohol for ointment bases. Stakeholders must monitor pharmacopeial harmonization initiatives and feedstock origin certification requirements as dual pressures from regulatory stringency and sustainability auditing reshape supplier qualification criteria.
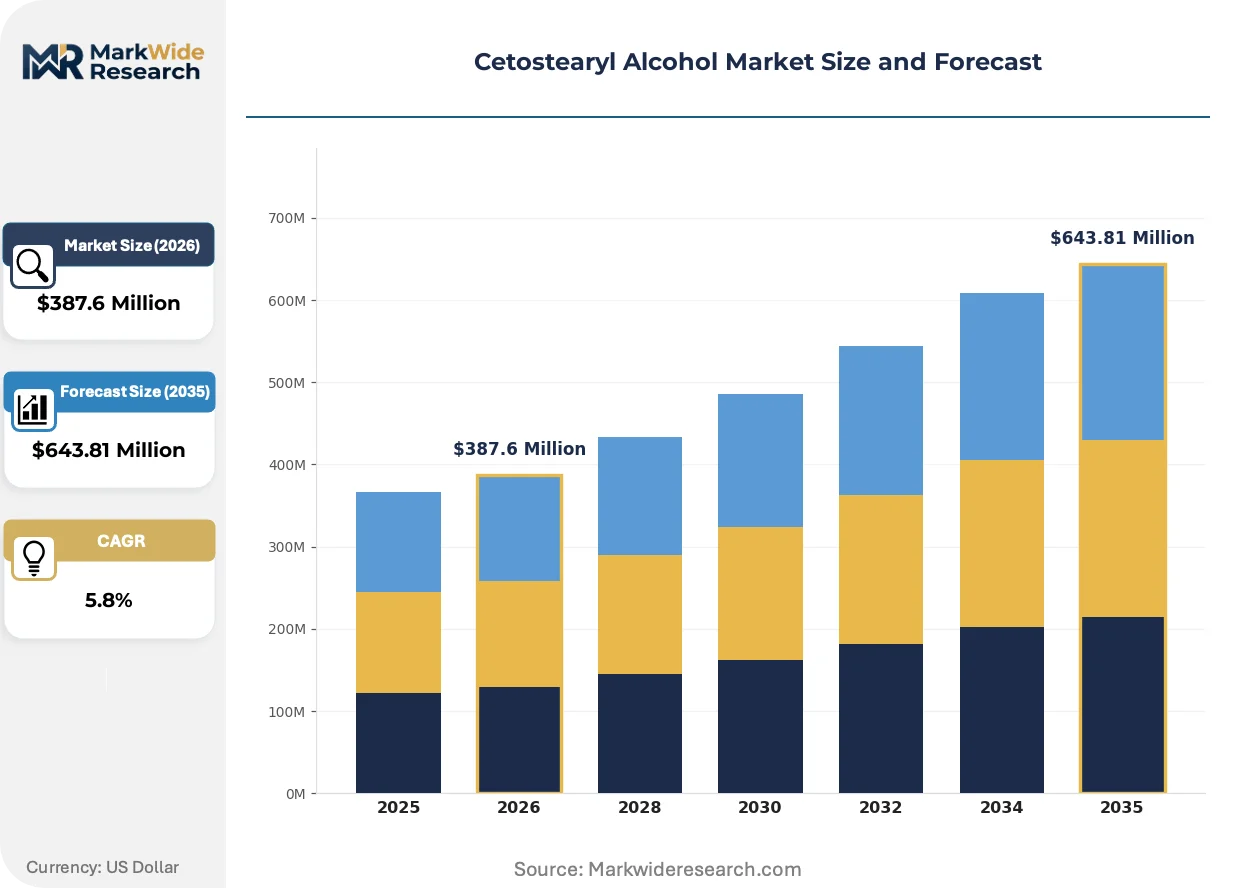
Market Dynamics
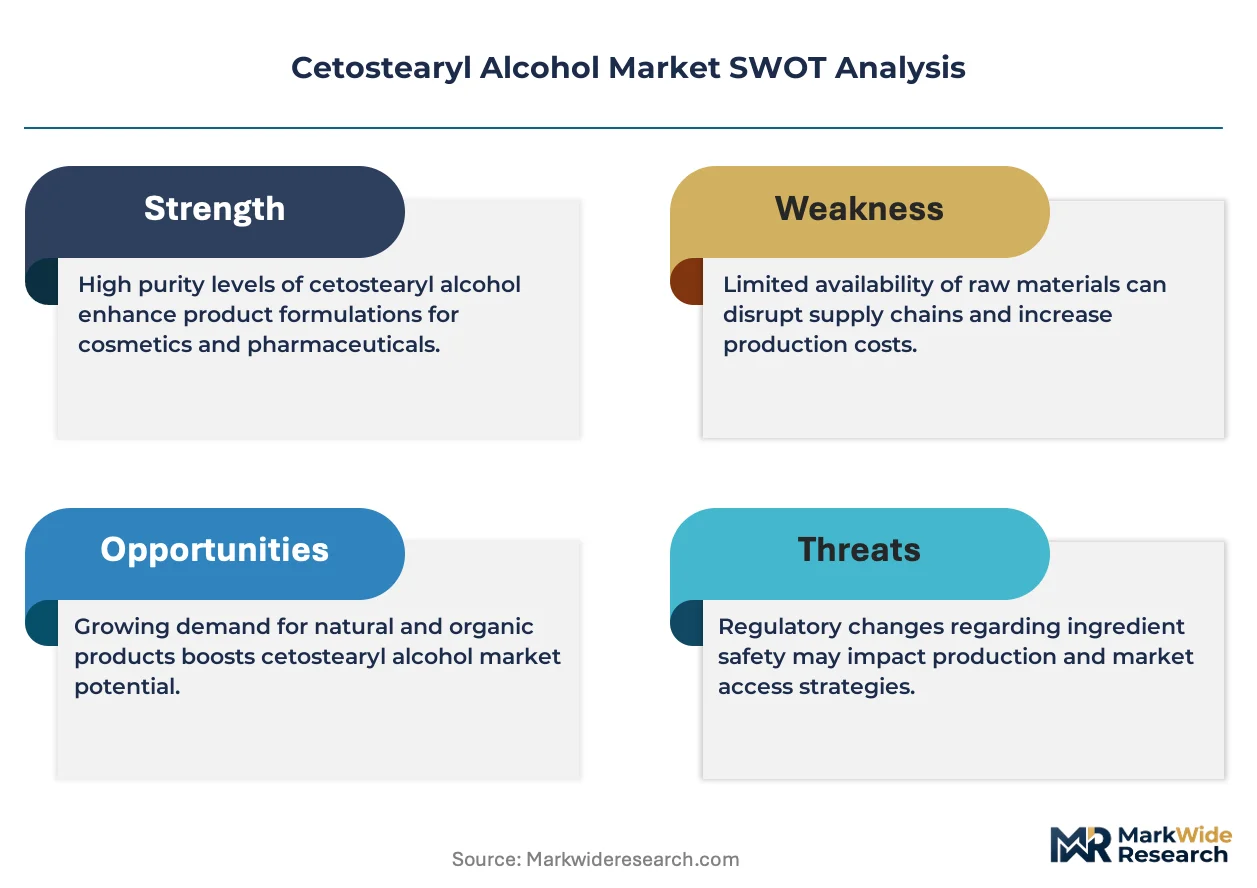
Pharmaceutical-grade specification tightening under USP and EP monographs is compressing supplier qualification windows, forcing formulators to consolidate procurement around integrated oleochemical producers with captive hydrogenation capacity and documented feedstock traceability.
Growth Catalysts
- REACH substance evaluation protocols:ECHA's updated dossier requirements for fatty alcohol derivatives are eliminating marginal importers, concentrating volume among registered EU-based manufacturers with full toxicological datasets.
- Topical drug manufacturing clusters in India:CDSCO's harmonization with ICH Q3C residual solvent guidelines is accelerating specification upgrades across generic ointment producers in Hyderabad and Ahmedabad.
- Silicone-free hair conditioning formulations:Clean-label substitution in Western European personal care is displacing dimethicone with cetostearyl alcohol-thickened cationic emulsions.
Market Restraints
- Palm kernel and coconut oil feedstock volatility:Weather-driven supply interruptions in Southeast Asia transmit directly to fatty alcohol contract pricing, compressing margin predictability for non-integrated formulators.
- Single-source hydrogenation catalyst dependencies:Noble metal supply concentration in South African and Russian mining operations creates input vulnerability for mid-scale European producers.
- Petrochemical-derived synthetic fatty alcohol cost floors:Crude-linked ethylene oligomerization routes set price ceilings that constrain natural-origin premium capture during energy price spikes.
Strategic Opportunities
- CDSCO-BIS convergence in Indian states:Maharashtra and Gujarat pharmacopeia updates are opening qualification pathways for pharmaceutical-grade suppliers with documented USP compliance histories.
- Solid lipid nanoparticle drug delivery systems:Cetostearyl alcohol's compatibility with hot-melt extrusion processes is enabling penetration into controlled-release topical therapies.
- Direct manufacturer-formulator distribution channels:Specialty chemical distributors are losing intermediation power as large personal care compounders establish annual volume contracts with oleochemical integrated producers.
Industry Challenges
- Pharmacopeial harmonization timeline compression:Simultaneous USP, EP, and JP revision cycles are stretching regulatory affairs teams at mid-scale suppliers attempting multi-territory filings.
- Legacy batch record system integration:Electronic batch record adoption for EU GMP Annex 11 compliance is requiring capital deployment that disadvantages family-owned European fatty alcohol processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cetostearyl Alcohol Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetic Grade, Pharmaceutical Grade, Industrial Grade, Food Grade Application: Emulsifier, Thickener, Stabilizer, Surfactant End User: Personal Care, Pharmaceuticals, Food Industry, Chemical Manufacturing Packaging Type: Bags, Drums, Totes, Bulk |
| Companies Covered | Clariant International Ltd., VVF LLC, Croda International PLC, Nouryon, Oleon NV, BASF SE, Stepan Company, Berg + Schmidt GmbH & Co. KG, Kao Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cetostearyl Alcohol Market Evolving Landscape
Digital process analytical technology deployment is virtualizing quality control checkpoints across hydrogenation and distillation trains, compressing release timelines for pharmaceutical-grade batches while tightening specification bands.
Continuous catalytic hydrogenation technology is virtualizing batch-to-batch variability in vegetable fatty acid reduction, enabling real-time alkane chain length distribution adjustment. BASF and Croda have retrofitted German and UK facilities with inline NIR spectroscopy loops. This virtualization of quality assurance is displacing traditional offline laboratory release protocols for high-volume pharmaceutical contracts.
REACH registration dossier updates under ECHA's 2024-2026 substance evaluation work program are mandating enhanced terrestrial toxicity data for fatty alcohols with chain lengths above C16. German and Dutch formulators face reformulation pressure where cetostearyl alcohol fractions trigger new hazard classification thresholds. The personal care segment is responding with accelerated supplier audits and contingency stockpiling ahead of potential authorization list inclusions.
Formulator procurement patterns are compressing supplier rosters as direct manufacturer relationships displace specialty chemical distribution tiers. Large European pharmaceutical compounders now negotiate eighteen-month rolling contracts with integrated oleochemical producers, bypassing regional distributors entirely. This concentration is most visible in German topical generic manufacturing, where three buyers now account for the majority of pharmaceutical-grade volume.
Cetostearyl Alcohol Market Segmentation
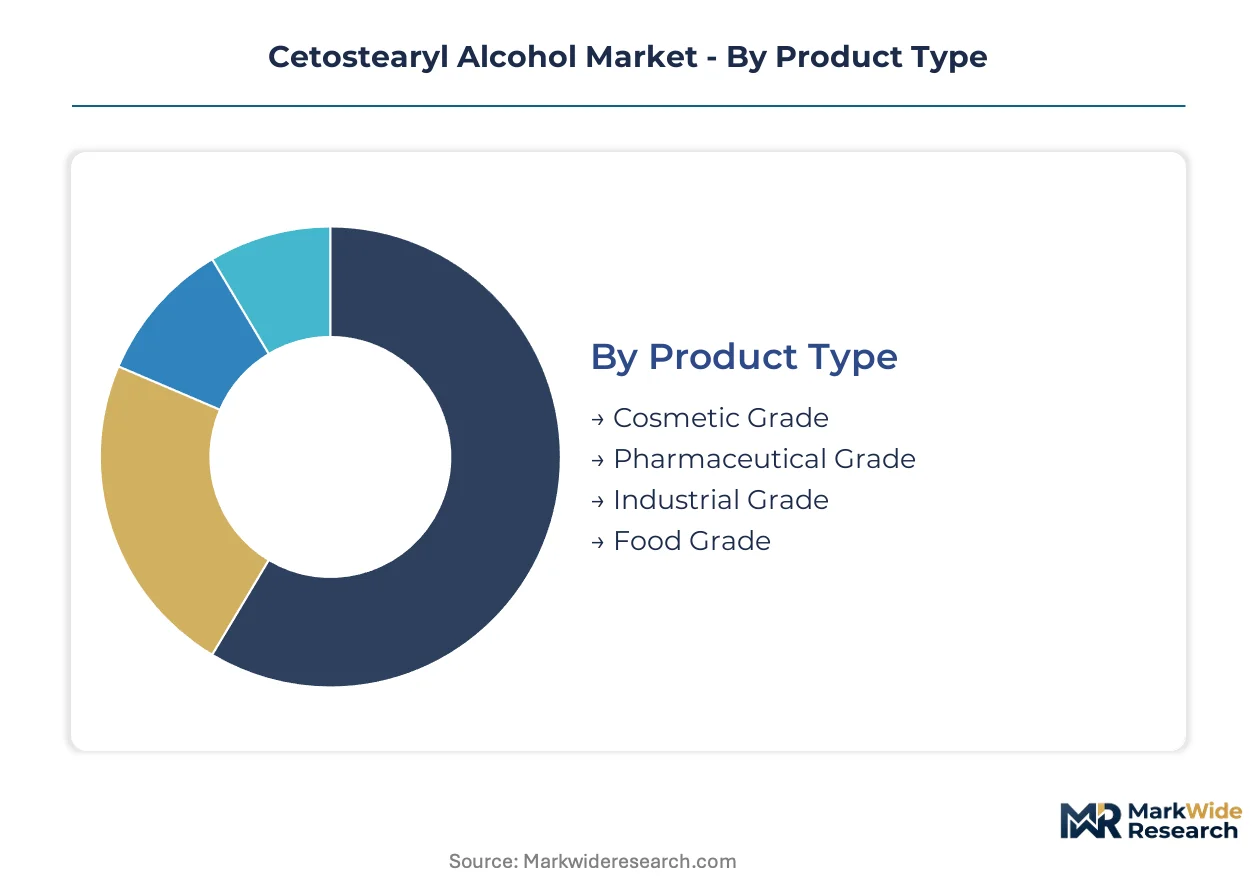
Segmentation in cetostearyl alcohol procurement reveals how specification tiers, application requirements, and end-user compliance burdens fragment supply relationships. Formulators select grades based on compendial burden, while packaging and logistics configurations respond to hydrogenation facility proximity and batch release protocols.
Product Type:
Use-case spectrum spans topical drug compounding requiring USP-NF traceability through industrial metalworking fluids accepting petroleum-derived feedstocks.
- Pharmaceutical Grade:USP-NF and EP monograph compliance mandates documented vegetable feedstock provenance and residual solvent testing under ICH Q3C. CDSCO's harmonization with international standards in Hyderabad and Ahmedabad manufacturing clusters is accelerating specification upgrades among Indian generic ointment producers.
- Cosmetic Grade:REACH-registered supply with restricted substance declarations serves European personal care formulators facing clean-label substitution pressures. Silicone-free hair conditioning formulations in Western Europe are displacing dimethicone with cetostearyl alcohol-thickened cationic emulsions, tightening viscosity specification bands.
- Industrial Grade:Metalworking lubricant and textile auxiliary applications accept broader alkane chain distribution variance.
- Food Grade:FSSAI and FDA food additive compliance governs confectionery coating and anti-foam applications.
Established volume favors pharmaceutical grade; emerging adoption favors cosmetic grade.
Application:
Functional role determines hydrogenation catalyst selection and distillation cut precision, with emulsion stability requirements commanding premium positioning.
- Emulsifier:Primary non-ionic surfactant function in ointment bases and skin creams requires narrow C16-C18 chain length distribution for stable oil-water interfaces. Topical drug manufacturing clusters in India and China are consolidating procurement around integrated oleochemical producers with captive hydrogenation capacity.
- Thickener:Viscosity-building in silicone-free hair conditioners leverages cationic compatibility without quaternary ammonium interference. German and UK personal care compounders are retrofitting formulation lines for cetostearyl alcohol-thickened systems.
- Stabilizer:Freeze-thaw resistance in pharmaceutical emulsions demands consistent hydroxyl value ranges.
- Surfactant:Industrial cleaning and agrochemical dispersion applications tolerate broader specification windows.
Emulsifier captures the dominant value share; thickener is climbing the fastest as clean-label substitution accelerates.
End User:
Customer type dictates audit intensity, with pharmaceutical compounders imposing supplier qualification protocols that exclude non-integrated distributors.
- Personal Care:European formulators under REACH substance evaluation protocols are eliminating marginal importers, concentrating volume among registered manufacturers with full toxicological datasets. Direct manufacturer-formulator contracts now bypass specialty chemical distribution tiers.
- Pharmaceuticals:USP-NF monograph compliance and EU GMP Annex 11 electronic batch record requirements stretch regulatory affairs capacity at mid-scale suppliers. Simultaneous USP, EP, and JP revision cycles are compressing multi-territory filing timelines.
- Food Industry:Anti-caking and coating applications in processed foods face FSSAI specification convergence with Codex Alimentarius.
- Chemical Manufacturing:Derivative production for ethoxylates and sulfates accepts industrial-grade material with broader quality tolerances.
Pharmaceuticals anchor premium pricing; personal care is gaining share fastest through clean-label reformulation cycles.
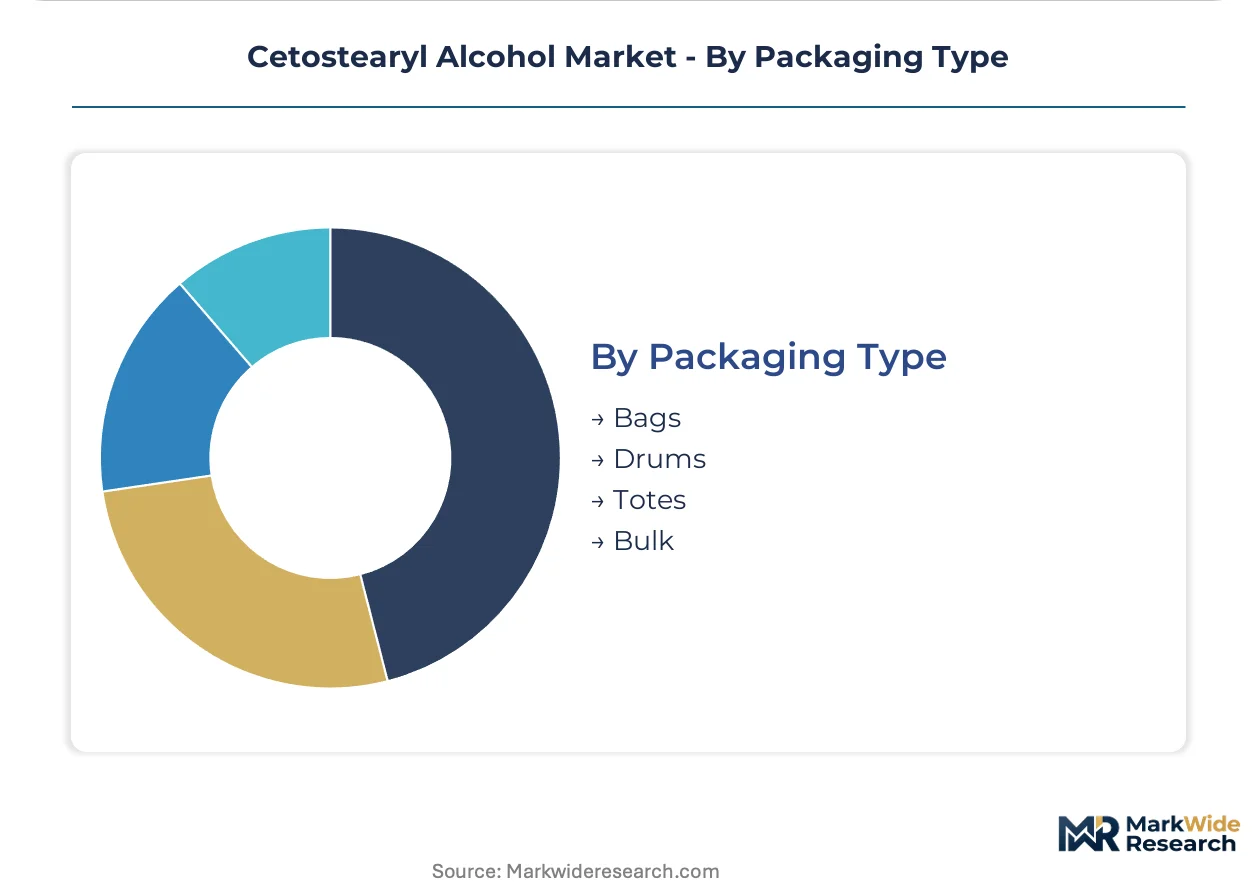
Packaging Type:
Logistics configuration reflects order scale, hydrogenation facility proximity, and contamination risk tolerance across supply chain tiers.
- Bulk:Tanker delivery from integrated oleochemical producers to large European pharmaceutical compounders supports eighteen-month rolling contracts. BASF's Ludwigshafen hydrogenation trains and Croda's UK lipid facilities dispatch bulk shipments to German topical generic manufacturers.
- Drums:Stainless steel containment for pharmaceutical-grade material enables lot traceability and tamper-evident sealing for mid-scale compounders.
- Totes:Intermediate bulk containers serve regional personal care formulators with moderate volume requirements and multi-product formulation lines.
- Bags:Multi-layer laminate packaging protects cosmetic-grade material from moisture ingress in tropical storage conditions.
Bulk dominates pharmaceutical procurement; drums retain position in mid-scale compounder supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk terminals anchor European fatty alcohol distribution, with dedicated hydrogenation feedstock pipelines feeding Ludwigshafen and Geleen manufacturing clusters. This infrastructure underwrites the region's pharmaceutical-grade supply security.
Germany
Topical generic drug manufacturing in North Rhine-Westphalia drives pharmaceutical-grade procurement consolidation. ECHA's 2024-2026 substance evaluation work program for C16-C18 fatty alcohols is forcing reformulation audits among personal care compounders. BASF's Ludwigshafen hydrogenation trains dispatch bulk tanker shipments directly to three major pharmaceutical compounders, bypassing distribution intermediaries entirely.
India
Hyderabad and Ahmedabad ointment manufacturing clusters are scaling pharmaceutical-grade material procurement as export volumes to regulated markets expand. CDSCO's harmonization with ICH Q3C residual solvent guidelines is accelerating specification upgrades across generic drug producers. VVF LLC's Mumbai-area manufacturing complex supplies high-volume contracts to domestic formulators competing on FDA-inspected facility approvals.
China
Domestic surfactant production scaling in Jiangsu and Zhejiang provinces is absorbing regional hydrogenation capacity. NMPA's updated pharmacopeia alignment with USP-NF monographs is tightening import substitution requirements for topical drug manufacturers. Yangtze River Delta oleochemical processors are retrofitting continuous hydrogenation lines to meet pharmaceutical-grade alkane distribution tolerances.
United States
Silicone-free hair conditioning formulation demand in New Jersey and California personal care hubs is displacing dimethicone with cetostearyl alcohol-thickened systems. FDA compliance with USP-NF monographs governs pharmaceutical-grade market access, with electronic batch record requirements under 21 CFR Part 11 stretching supplier qualification timelines. Stepan Company's Illinois and Georgia facilities anchor mid-Atlantic and Southeast supply chains.
United Kingdom
Croda International PLC's East Yorkshire lipid-specialist R&D facilities sustain European pharmaceutical compounder relationships through documented vegetable feedstock provenance. REACH registration dossier maintenance costs are eliminating marginal importers from the UK personal care supply base. Continuous catalytic hydrogenation retrofits at Humberside manufacturing sites enable real-time alkane chain length distribution adjustment for high-volume contracts.
Cetostearyl Alcohol Market Competitive Landscape
On the supply side, the industry is consolidating around integrated oleochemical producers with captive hydrogenation capacity and documented feedstock traceability. Three strategic archetypes dominate: European diversified chemical majors with lipid-specialist divisions, Asian scale-driven manufacturers competing on volume, and mid-tier regional processors facing margin compression from regulatory compliance burdens. Competitive moves center on direct manufacturer-formulator contract structures and continuous hydrogenation technology licensing.
Among European-based integrated producers, BASF SE and Croda International PLC exemplify the diversified-major archetype with dedicated oleochemical networks and pharmaceutical-grade certification depth. VVF LLC represents the Asian scale-competitor model, leveraging Indian manufacturing concentration to serve regional generic drug clusters. These three anchors demonstrate how feedstock integration and regulatory dossier completeness now determine qualification viability for high-specification contracts.
| Leading Market Players |
|---|
| Clariant International Ltd. |
| VVF LLC |
| Croda International PLC |
| Nouryon |
| Oleon NV |
| BASF SE |
| Stepan Company |
| Berg + Schmidt GmbH & Co. KG |
| Kao Corporation |
| Others |
Value Network & Pricing Analysis
Single-source hydrogenation catalyst dependencies in South African and Russian mining operations determine both tiered pricing spreads across pharmaceutical, cosmetic, and industrial grades and the elongated supply chain configurations that favor integrated oleochemical producers with captive reduction capacity.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade contracts commanding compendial compliance premiums from cosmetic-grade spot purchases facing clean-label substitution pressure. Price differentiation rests on USP-NF certification depth and eighteen-month rolling contract scale. Cost compression in cosmetic-grade supply is intensifying because REACH-registered importers face margin squeeze from direct manufacturer-formulator relationships. Mid-scale compounders exhibit highest price sensitivity; integrated pharmaceutical buyers with captive hydrogenation partners show lowest.
Supply Chain Analysis
Upstream palm kernel and coconut oil feedstock channels draw from Malaysian, Indonesian, and Philippine plantation networks. Vegetable fatty acid supply feeds German, Indian, and Chinese hydrogenation trains. Tariff exposure on noble metal catalyst imports from Russian mining operations creates input vulnerability for European mid-scale producers. Distribution runs through direct bulk tanker contracts from Ludwigshafen and Geleen manufacturing clusters to large pharmaceutical compounders, bypassing specialty chemical intermediaries entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among three major German topical generic manufacturers, fragmenting supplier rosters and forcing qualification consolidation around integrated oleochemical producers with documented feedstock traceability.
For Market Incumbents: Insulate pharmaceutical-grade positioning through backward integration into vegetable fatty acid hydrogenation and continuous catalytic retrofitting of European facilities. Lock in eighteen-month rolling contracts with CDSCO-inspected Indian generic producers before specification upgrades close qualification windows. Channel control through direct bulk tanker distribution eliminates distributor margin leakage.
For New Entrants and Emerging Players: Establish a beachhead in cosmetic-grade silicone-free hair conditioning formulations where clean-label substitution creates specification upgrade demand without USP-NF compliance burden. Target Maharashtra and Gujarat personal care compounders facing REACH substance evaluation pressure with documented vegetable feedstock provenance. Go-to-market angle: lipid-specialist technical service partnerships displacing commodity distributors.
For Investors and Strategic Acquirers: The market sits at a specification-tightening phase that favors integrated oleochemical producers with captive hydrogenation and regulatory dossier completeness. Long-term viability favors backward-integrated assets with NMPA and CDSCO qualification pathways. Signal to watch: CDSCO-BIS convergence timeline accelerating import substitution requirements for pharmaceutical-grade supply.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Hydrogenation | Captive vegetable fatty acid reduction secures margin control against palm oil volatility. |
| Continuous Catalytic Hydrogenation Retrofit | Inline NIR spectroscopy at BASF and Croda facilities compresses pharmaceutical batch release timelines. |
| Long-term Supply Agreement with CDSCO-Inspected Facilities | Eighteen-month rolling contracts lock in volume ahead of Indian pharmacopeia upgrades. |
| Regulatory Dossier Investment for REACH Registration | Full toxicological datasets eliminate marginal importers under ECHA substance evaluation protocols. |
| Direct Manufacturer-Formulator Distribution Channel | Bypassing specialty chemical distributors captures intermediation margin in German pharmaceutical procurement. |
Research Methodology
A spread of perspectives from hydrogenation plant managers, pharmaceutical procurement leads at topical generic manufacturers, lipid-specialist R&D directors, and REACH regulatory consultants converged on the working assumptions. Primary fieldwork combined with secondary validation from customs trade data, CDSCO filing records, ECHA registration dossiers, and SEC filings of listed oleochemical producers. Bottom-up grade-tier and application-segment modeling triangulated against top-down regional production cluster analysis.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions spanned pharmaceutical-cosmetic-industrial grade tiers, emulsifier-thickener-stabilizer applications, and regional hydrogenation hub proximity. CAGRs derived from volume trajectory modeling against capacity expansion announcements and feedstock cost pass-through elasticity. Industry-specific inputs included ICH Q3C residual solvent guideline adoption timelines and clean-label substitution rates in Western European personal care.
Stress conditions across palm kernel oil price volatility, noble metal catalyst supply interruption, and REACH authorization list inclusion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization pace and feedstock origin certification penetration. Cross-checking against ECHA substance evaluation work program updates and CDSCO inspection facility approvals is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Coagulant Market
Chemicals
N-Acetyl D-Neuraminic Acid Market
Chemicals
Bakers Ammonia Market
Chemicals
Potassium Hydrogen Fluoride Market
Chemicals
Imaging Chemicals and Materials Market
Chemicals
Peracetic Acid Market
Chemicals
Methylamines Market
Chemicals
China Amines Market
Chemicals
Potassium Fluoride Market
Chemicals
SLS and LABSA Market
Chemicals
Asia-Pacific Surface Treatment Chemicals Market
Chemicals
Acrylic Acids and Esters Market
Chemicals
Global Cresols Market
Chemicals
Phosgene Market
Chemicals
Europe Biguanide Market
Chemicals
Selenium Sulfide Market