
 Biopolymers Market | 2026-2036
Biopolymers Market Size, Share, and Industry Trends Forecast 2026-2036
Biopolymers Market Analysis
Thailand is narrowing the cost gap between fermentation-derived PLA and petroleum-based resins through expanded cane-sugar feedstock access. Braskem leverages its Brazilian ethanol infrastructure to anchor global bio-polyethylene capacity. NatureWorks sustains North American PLA leadership through continuous starch-to-lactide process refinement. BASF competes across multiple chemistries with integrated research platforms in Ludwigshafen.
Biopolymers comprise macromolecules synthesized from renewable biomass sources such as starch, cellulose, lactic acid, or chitosan, typically exhibiting biodegradability or bio-based carbon content exceeding 20 percent by mass according to ASTM D6866 testing protocols. These materials primarily serve as functional substitutes for conventional plastics in applications requiring controlled end-of-life degradation or reduced fossil-carbon intensity. Polylactic acid currently commands the deepest processing infrastructure and widest thermoforming compatibility among commercial grades. Starch-based compounds occupy the most cost-accessible tier for short-use disposable applications despite moisture-sensitivity constraints. Cellulose-derived variants lead in film and coating segments where gas-barrier performance determines specification compliance.
The EPA regulates biopolymer manufacturing emissions under Clean Air Act Title V permitting, while the EU F-Gas Regulation and REACH restrict residual solvent content in imported grades. FDA food-contact notifications govern PLA and starch-based materials entering United States packaging supply chains, creating multi-jurisdictional compliance burdens for exporters. Stakeholders must monitor evolving compostability certification standards across municipal waste systems before committing capital to downstream processing assets.
Market Dynamics
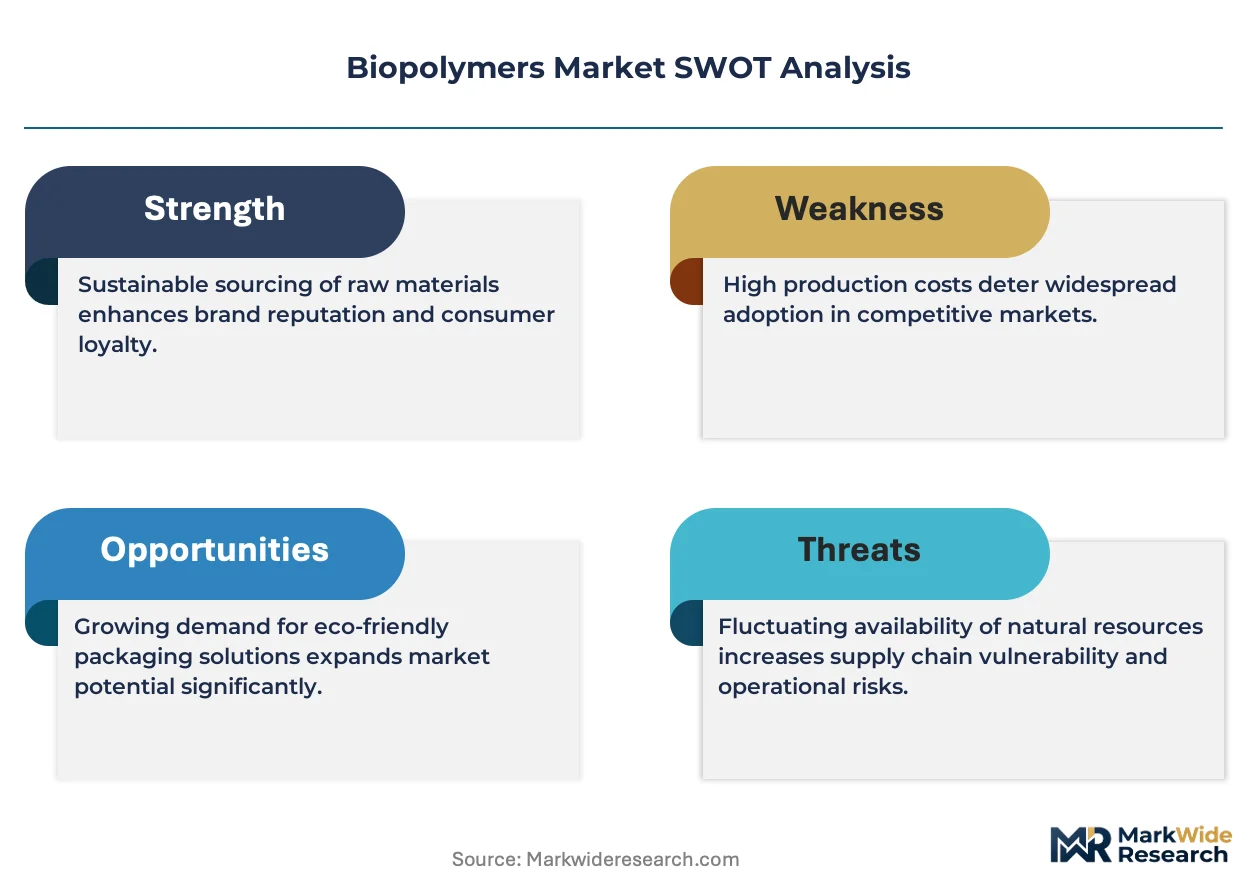
EU Green Deal mandates and REACH compliance deadlines are compressing substitution timelines for fossil-based plastics, forcing packaging converters and automotive suppliers to requalify entire material streams before 2035 regulatory cliffs.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases in foam applications are redirecting insulation manufacturers toward bio-based polyurethane precursors.
- Starch-to-lactide refining:Continuous process improvements at NatureWorks and Thai fermentation facilities are expanding PLA thermoforming compatibility into high-temperature food service.
- Japan METI bioeconomy targets:National mandates for 25 percent bio-based plastics by 2030 are concentrating injection-molding demand in Osaka and Nagoya automotive clusters.
Market Restraints
- Cane-sugar price volatility:Thai and Brazilian ethanol feedstock costs swing with commodity sugar futures, compressing PLA margin stability against polyethylene terephthalate benchmarks.
- Moisture sensitivity:Starch-based compounds require nitrogen-flushed packaging and climate-controlled warehousing, adding 12-18 percent logistics overhead versus polypropylene equivalents.
- Composting infrastructure gaps:Industrial composting capacity concentrates in Germany, Italy, and select US West Coast municipalities, leaving most regions without end-of-life pathways for certified biodegradable grades.
Strategic Opportunities
- US Inflation Reduction Act:Production tax credits for domestic bio-based chemical manufacturing are attracting greenfield fermentation capacity to the Gulf Coast corridor.
- Medical device packaging:Sterilizable PLA and chitosan barrier films are penetrating surgical kit and pharmaceutical blister applications where ethylene oxide compatibility determines specification.
- Direct-to-brand polymer sales:Bypassing traditional distributor channels, producers like Braskem are establishing captive supply relationships with Unilever and Nestlé procurement teams.
Industry Challenges
- ASTM D6400/D6866 testing backlog:Certification queues at BPI and TÜV Austria stretch 8-14 months, delaying product launches for compostable food service lines.
- Legacy extruder reconfiguration:Converting polypropylene lines to PLA processing requires screw geometry modifications, die temperature zone expansion, and moisture exclusion systems totaling capital commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopolymers Market |
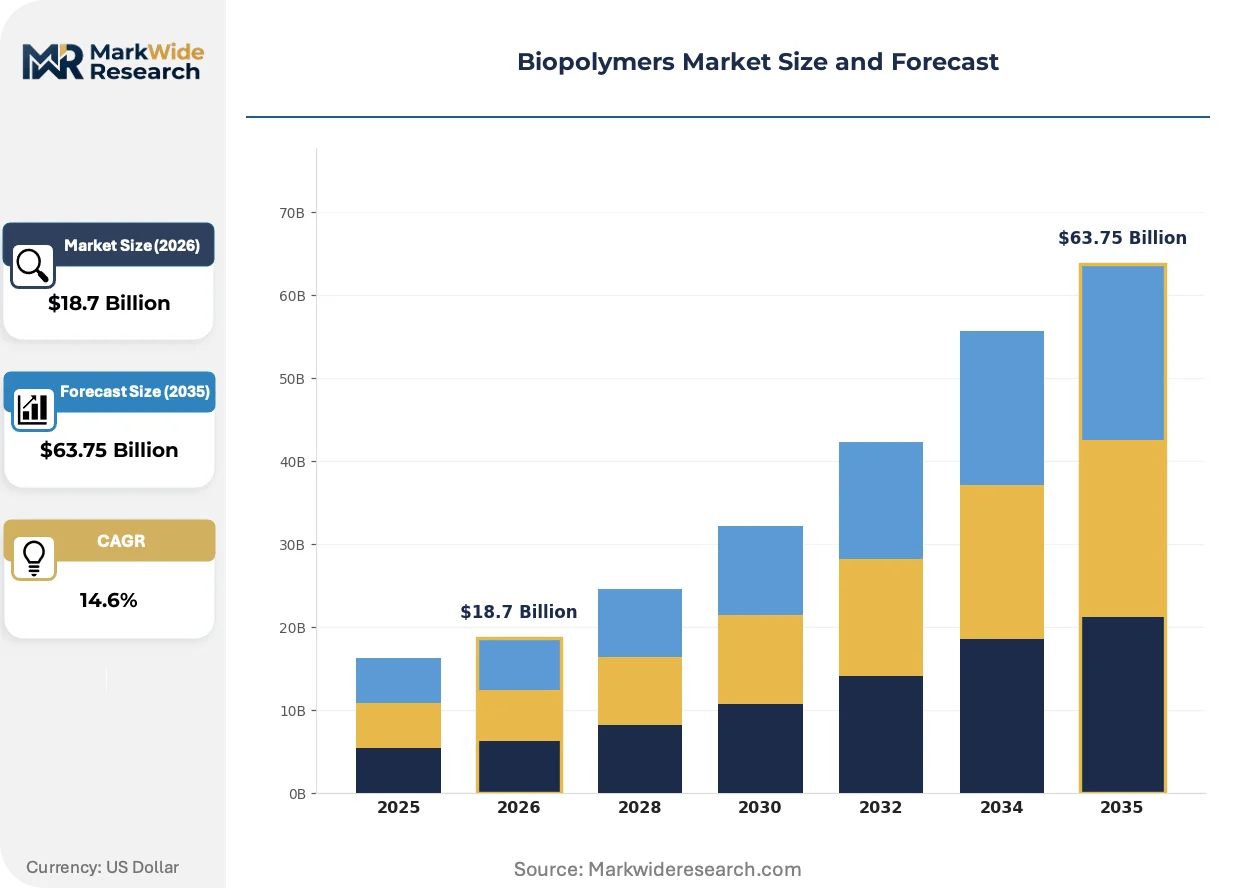
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch-Based, Cellulose-Based, Polylactic Acid, Chitosan Application: Packing, Agriculture, Textiles, Pharmaceuticals End User: Food Industry, Automotive, Consumer Goods, Medical Devices Form: Granules, Films, Coatings, Fibers |
| Companies Covered | Mitsubishi Chemical Corporation, Braskem, NatureWorks, Biome Bioplastics, Total Corbion PLA, BASF, Novamont, Arkema, Corbion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopolymers Market Emerging Trajectories
Digital twin modeling of fermentation bioreactors is compressing strain optimization cycles, while blockchain traceability platforms are hardening bio-based carbon accounting claims against greenwashing scrutiny.
Enzymatic polymerization of polylactic acid is virtualizing traditional metal-catalyzed ring-opening processes, eliminating tin-based residual contaminants that complicate FDA food-contact notifications. Medical device manufacturers and infant formula packaging suppliers are prioritizing these grades for reduced extractables profiles. The technology is virtualizing regulatory approval pathways by collapsing toxicology study timelines from 18 months to under 6 months.
REACH restrictions on microplastics in single-use applications are compelling cosmetic and agricultural film formulators to demonstrate biodegradability within 120 days in marine environments. ECHA enforcement actions against non-compliant importers are accelerating third-party certification investments. German and French personal care brands are responding by specifying cellulose-derived microbead substitutes in rinse-off formulations.
Automotive OEMs are unbundling sustainability specifications from traditional tiered supplier contracts, creating direct polymer qualification programs that bypass compounder intermediaries. BMW and Mercedes-Benz procurement teams in Stuttgart and Munich are establishing bio-based material scorecards separate from price-volume negotiations. This disintermediation is most visible in interior trim and under-hood applications where mass reduction targets intersect with circularity commitments.
Biopolymers Market Segmentation
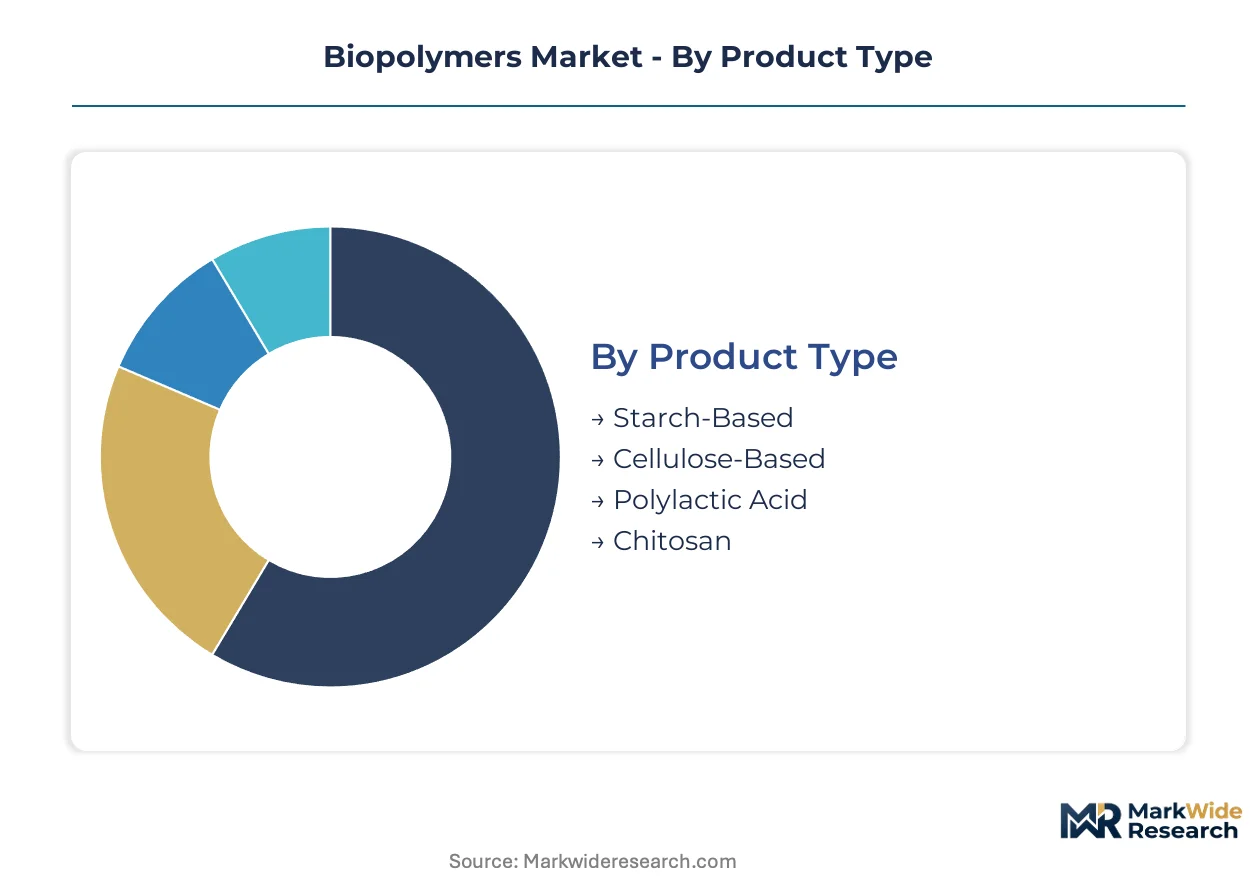
Biopolymer specification varies sharply across product chemistry, processing form, and end-use environment. Each segmentation dimension carries distinct certification requirements and supply chain implications that determine commercial viability.
Product Type:
Material chemistry defines processing temperature windows, barrier performance, and composting pathway compatibility.
- Polylactic Acid:Ring-opening polymerization of lactide monomers yields crystalline thermoplastics with thermoforming temperatures reaching 180°C. Food service packaging converters in Germany and Japan are absorbing expanded PLA volumes as FDA and EU food-contact certifications mature.
- Starch-Based:Thermoplastic starch compounds blended with aliphatic polyesters deliver cost-accessible disposables with 90-day industrial composting certification. Moisture absorption above 15% relative humidity limits deployment to short-use applications with nitrogen-flushed distribution.
- Cellulose-Based:Regenerated cellulose and cellulose esters dominate film and coating segments where oxygen transmission rates below 1 cc/m²/day determine pharmaceutical blister specification.
- Chitosan:Deacetylated chitin from crustacean processing waste provides antimicrobial film properties for medical device packaging and agricultural seed coatings.
Established volume favors starch-based compounds; emerging adoption favors polylactic acid as high-temperature thermoforming compatibility expands.
Application:
Functional requirements across end-use sectors drive chemistry selection and certification investment.
- Packaging:Flexible films, rigid thermoformed trays, and injection-molded containers represent the dominant demand channel. EU Green Deal mandates and Japan METI bioeconomy targets are compressing substitution timelines for fossil-based food contact materials.
- Agriculture:Mulch films, controlled-release coatings, and planting trays require soil biodegradability certification under EN 13432 or ASTM D6400 protocols. Composting infrastructure gaps in most growing regions constrain addressable market development.
- Textiles:PLA staple fibers and cellulose filament yarns serve apparel and nonwoven applications where moisture management and dye affinity determine specification against polyester benchmarks.
- Pharmaceuticals:Sterilizable barrier films and tablet coatings demand extractables profiles compliant with USP Class VI and EP 3.1.3 standards, commanding premium pricing over commodity packaging grades.
Regulatory pressure concentrates investment in packaging; technical performance requirements sustain pharmaceutical margins.
End User:
Procurement sophistication and sustainability disclosure obligations vary sharply across customer categories.
- Food Industry:Processors and quick-service restaurant chains specify compostable serviceware to meet extended producer responsibility mandates. Direct-to-brand polymer sales are bypassing traditional distributor channels as Unilever and Nestlé procurement teams establish captive supply relationships.
- Automotive:Interior trim, under-hood components, and structural panels absorb bio-based polypropylene and polyurethane precursors. BMW and Mercedes-Benz procurement teams in Stuttgart and Munich are unbundling sustainability specifications from traditional tiered supplier contracts.
- Consumer Goods:Personal care brands respond to REACH microplastic restrictions by specifying cellulose-derived microbead substitutes in rinse-off formulations.
- Medical Devices:Surgical kit packaging and pharmaceutical blisters require ethylene oxide sterilization compatibility and reduced extractables profiles, prioritizing enzymatic PLA grades over metal-catalyzed alternatives.
Automotive direct qualification programs are climbing fastest; food industry volume scales through distributor consolidation.
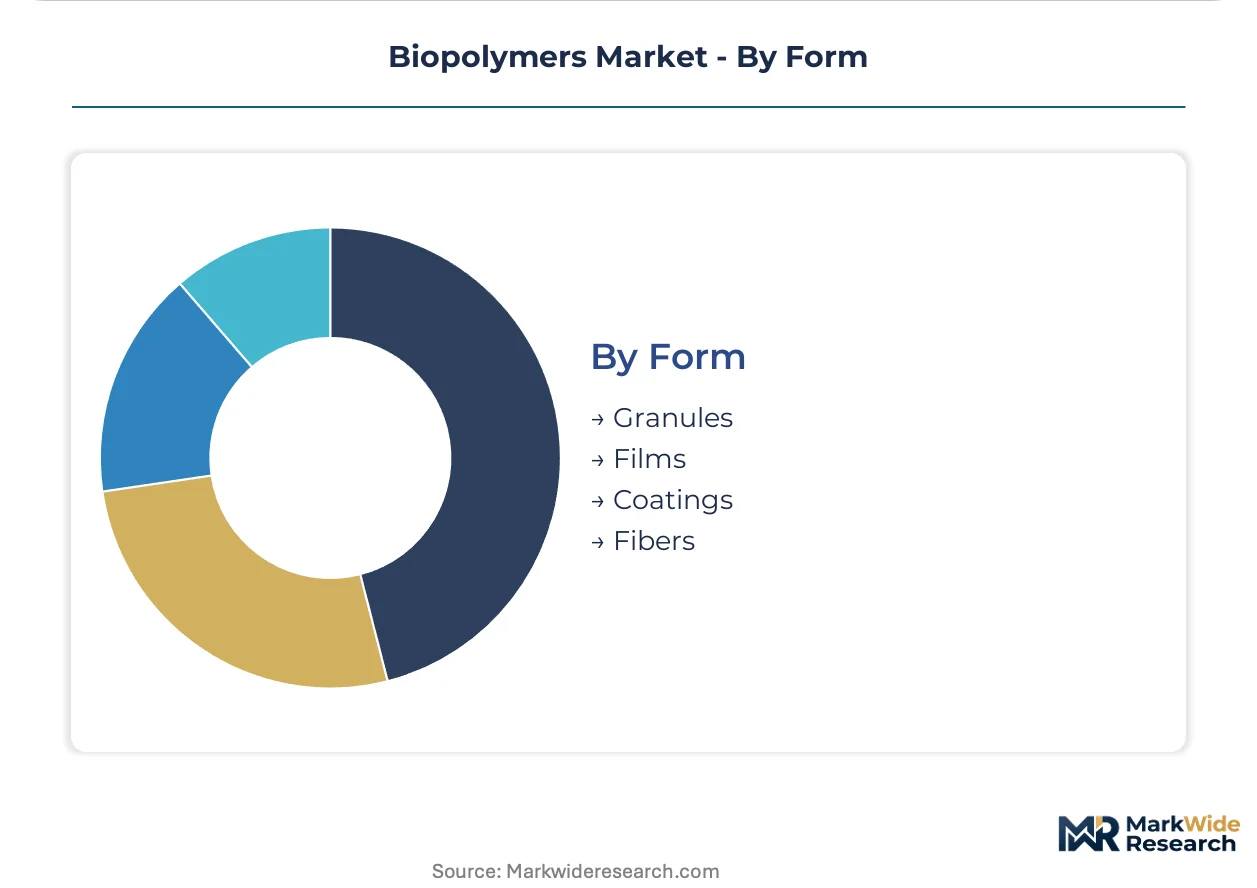
Form:
Processing morphology determines equipment compatibility and downstream conversion economics.
- Films:Cast and blown film extrusion of PLA and cellulose derivatives serves flexible packaging and agricultural mulch applications where gauge uniformity and seal strength determine line speeds.
- Granules:Pelletized compounds enable injection molders and sheet extruders to integrate biopolymers into existing polypropylene and polyethylene processing lines with screw geometry modifications.
- Coatings:Aqueous and solvent-based barrier coatings for paper and board substrates provide grease resistance and moisture vapor transmission control in food service applications.
- Fibers:Melt-spun PLA and solution-spun cellulose filaments target textile and nonwoven markets where tenacity and dye uptake compete with petrochemical polyester.
Granule supply dominates current volume; film capacity expansion is gaining share fastest as packaging substitution accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes biopolymers predominantly for automotive interior applications and industrial packaging, while Thailand and Brazil prioritize fermentation feedstock expansion for export-oriented PLA and bio-polyethylene production.
Germany
Automotive OEMs in Stuttgart and Munich specify bio-based polypropylene for interior trim and under-hood components. EU Green Deal mandates and REACH compliance deadlines compress substitution timelines for fossil-based plastics. The Ludwigshafen chemical cluster anchors integrated research platforms serving packaging converters and tier-one suppliers.
United States
Food processors and quick-service restaurant chains absorb expanded PLA volumes for compostable serviceware. FDA food-contact notifications govern material entry into packaging supply chains. NatureWorks maintains processing leadership through continuous starch-to-lactide refinement at its Nebraska fermentation complex.
Thailand
Expanded cane-sugar feedstock access narrows the cost gap between fermentation-derived PLA and petroleum-based resins. National bioeconomy programs incentivize greenfield fermentation capacity. Bangkok-based processors supply thermoforming-grade material to Japanese and European packaging converters.
Brazil
Sugarcane ethanol infrastructure anchors global bio-polyethylene capacity for export markets. Braskem leverages captive feedstock supply to serve Unilever and Nestlé procurement teams. São Paulo state clusters concentrate polymerization assets and port logistics for Atlantic shipping routes.
Japan
METI bioeconomy targets mandate 25 percent bio-based plastics by 2030, concentrating injection-molding demand in Osaka and Nagoya automotive clusters. Industrial composting infrastructure gaps elsewhere in Asia-Pacific limit end-of-life pathways for certified biodegradable grades. Pharmaceutical blister manufacturers prioritize sterilizable PLA barrier films for surgical kit applications.
Biopolymers Market Vendor Landscape
Capability concentration sits with integrated chemical conglomerates possessing fermentation infrastructure and polymerization expertise; scale advantage sits with regional feedstock-anchored producers leveraging cane-sugar and corn-starch supply chains. The market structures around three tiers: global diversified chemical majors, regional bio-feedstock specialists, and application-focused compounders. Dominant competitive moves include backward integration into fermentation assets and direct-to-brand polymer sales bypassing traditional distribution channels.
Among diversified chemical majors, BASF and Mitsubishi Chemical Corporation exemplify integrated research platforms competing across multiple biopolymer chemistries. Braskem and NatureWorks occupy positions as feedstock-anchored specialists, with the former leveraging Brazilian ethanol infrastructure and the latter sustaining North American PLA leadership through process refinement. Novamont and Total Corbion PLA represent European fermentation-based producers targeting packaging and agricultural film specifications.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| Braskem |
| NatureWorks |
| Biome Bioplastics |
| Total Corbion PLA |
| BASF |
| Novamont |
| Arkema |
| Corbion |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp barge freight corridors transmit cane-sugar cost volatility from Brazilian and Thai ports directly into European PLA landed prices, compressing margin structures for compounders while enabling feedstock-anchored producers to sustain price premiums against petroleum-based benchmarks.
Pricing Analysis
Geographic price spreads between Thai fermentation-derived PLA and Nebraska starch-based grades reflect cane-sugar futures volatility against corn belt input stability. Three-tier pricing structure across pharmaceutical-grade, food-contact certified, and industrial compostable levels separates extractables-compliant medical films from commodity packaging resins. Pricing pressure stems from Brazilian ethanol cost compression as Braskem scales bio-polyethylene output for Nestlé procurement contracts. Food processors exhibit highest price sensitivity due to thin converter margins, while pharmaceutical blister manufacturers absorb premiums for USP Class VI certification.
Supply Chain Analysis
Upstream feedstock concentration in São Paulo state sugarcane belts, Iowa corn belts, and Bangkok cane-sugar corridors anchors global fermentation capacity for lactide and ethylene precursors. Supply chains draw from crustacean processing waste for chitosan, softwood pulp for cellulose esters, and tapioca starch for thermoplastic compounds. Single-source vulnerability concentrates in NatureWorks' Nebraska lactide monopoly and Braskem's Triunfo polymerization complex. Distribution runs through direct-to-brand contracts with Unilever and BMW procurement teams, bypassing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biopolymers sit in early-cycle expansion as EU Green Deal mandates force automotive and packaging converters to requalify material streams before regulatory cliffs eliminate fossil-based alternatives.
For Market Incumbents: Build certification moats by accelerating ASTM D6400 and BPI compostability queues ahead of REACH microplastic enforcement deadlines. Secure backward integration into Thai cane-sugar fermentation assets to buffer Brazilian ethanol price swings. Defend against enzymatic PLA disruptors by locking medical device manufacturers into long-term extractables-compliant supply agreements. For New Entrants and Emerging Players: Southeast Asian industrial composting infrastructure gaps present white-space for soil-biodegradable mulch film formulations targeting agricultural cooperatives without end-of-life pathway access. Japan METI bioeconomy targets concentrate injection-molding demand in Nagoya automotive clusters where direct OEM qualification programs bypass established compounder relationships. Partner with Bangkok-based processors for thermoforming-grade PLA toll manufacturing to circumvent NatureWorks patent thickets. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates spinning non-core biopolymer research platforms amid Ludwigshafen and Tokyo restructuring cycles. Five-to-ten year viability hinges on composting infrastructure buildout velocity rather than production capacity alone. Monitor ECHA enforcement action frequency against non-compliant importers as early signal of certification premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Assets | Captive cane-sugar supply from São Paulo mills locks Braskem's cost position against Thai competitors. |
| Direct-to-Brand Polymer Sales | Unilever procurement teams in Rotterdam bypass distributor markups for bio-polyethylene shrink film contracts. |
| Enzymatic PLA Process Licensing | Elimination of tin-based catalysts collapses FDA toxicology timelines for infant formula packaging suppliers. |
| Composting Infrastructure Joint Ventures | German municipal waste operators partner with Novamont to secure EN 13432 end-of-life pathways. |
| Automotive OEM Qualification Programs | BMW procurement in Stuttgart unbundles sustainability scorecards from traditional tiered supplier contracts. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA food-contact notification databases, ECHA REACH registration filings, EU customs trade records, and NatureWorks patent disclosures. Conversations with fermentation plant managers, automotive tier-one procurement leads, pharmaceutical packaging engineers, and composting facility operators informed capacity and pricing assumptions. Bottom-up volume estimates from Thai and Brazilian export statistics triangulate against top-down substitution models for polyethylene and polypropylene displacement across the analysis window.
Forecast inputs span grade tier differentiation, end-use industry adoption curves, regional regulatory enforcement intensity, and fermentation yield improvement trajectories. Segmentation dimensions modeled include product chemistry, processing form, and end-user procurement sophistication across the projection horizon. CAGRs derive from elasticity-adjusted substitution rates against fossil-based resin price benchmarks, with specific weighting for EU Green Deal compliance deadlines and Japan METI bioeconomy target trajectories.
Practitioners should monitor cane-sugar futures volatility, ECHA microplastic enforcement cadence, and municipal composting capacity buildout announcements for early signals of forecast revision. Cross-checking against ACC and PlasticsEurope production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Global Bio-Polylactic Acid (PLA) Market
Bioplastics
Compostable Phone Cases Market
Bioplastics
Asia-Pacific Lactic Acid Market
Bioplastics
Polylactic Acid (PLA) Straws Market
Bioplastics
Global Bio-Plasticizers Market
Bioplastics
Global Bioplastic Composites Market
Bioplastics
Starch-Based Plastics Market
Bioplastics
Asia-Pacific Bio Plasticizers Market
Bioplastics
Cellulose Plastics Market
Bioplastics
Bio-Based Polyolefins Market
Bioplastics
Biopolymer Films Market
Bioplastics
North America Bioplastics Market
Bioplastics
Biobased Biodegradable Plastics Market
Bioplastics
Polyhydroxyalkanoate (PHA) Market
Bioplastics
Biodegradable Insulated Panel Market
Bioplastics
Cellulose Bioplastic Market