
 Lens Cleaning Product Market | 2026-2036
Lens Cleaning Product Market Size, Share, and Industry Trends Forecast 2026-2036
Lens Cleaning Product Market Foresight
Multi-source procurement for isopropyl alcohol and microfiber substrates is repositioning how lens cleaning product manufacturers secure raw materials. Carl Zeiss leverages its optical heritage to command premium positioning in specialty retail. Kimberly-Clark Worldwide sustains mass-market throughput through supermarket and pharmacy channel dominance. Johnson & Johnson anchors healthcare-grade formulations with sterilization-grade specifications for clinical settings.
Lens cleaning products encompass formulated solutions, impregnated substrates, and gel-based compounds designed to remove particulate matter, oils, and smudges from precision optical surfaces without scratching or leaving residue; typical formulations contain isopropyl alcohol concentrations between 60% and 99%, deionized water, and surfactants balanced for evaporative rate and surface tension. Their primary purpose spans consumer eyewear maintenance, professional photography equipment preservation, medical device optical clarity, and consumer electronics touchscreen functionality. Liquid spray formats lead volume due to refill economics and institutional purchasing patterns, while pre-moistened cloths capture the fastest expansion through travel-size convenience and single-use hygiene preferences. Wipes targeting smartphone screens and VR headsets now command disproportionate margin pools as device manufacturers bundle cleaning kits with premium hardware.
EPA regulations govern volatile organic compound emissions from aerosol spray formulations in the United States, constraining propellant choices and driving water-based alternatives. REACH chemical registration requirements in Europe limit certain surfactants and preservatives, compelling reformulation investments for market access. FDA oversight applies to lens cleaning products marketed with medical device claims or for surgical loupe maintenance. Stakeholders must monitor evolving state-level chemical disclosure mandates and decide whether to maintain regional SKU differentiation or pursue universal formulation compliance.
Market Dynamics
Touchscreen proliferation across smartphones, tablets, and AR/VR headsets is fragmenting demand into specialized substrate formats, forcing manufacturers to retool production lines for pre-moistened wipes while maintaining liquid spray capacity for institutional buyers.
Growth Catalysts
- REACH compliance elevation:Europe's chemical registration requirements are accelerating reformulation toward biodegradable surfactants, opening premium positioning for compliant suppliers.
- Medical device optical maintenance:Surgical loupes and endoscopic equipment require sterilization-grade cleaning protocols, anchoring healthcare procurement at elevated price points.
- Metropolitan electronics retail corridors:Urban concentration of mobile device sales in the United States is concentrating demand for bundled cleaning kits at point-of-purchase.
Market Restraints
- Isopropyl alcohol supply volatility:Pharmaceutical and electronics manufacturing compete for identical feedstock grades, creating input cost spikes during supply disruptions.
- EPA VOC emission constraints:Aerosol propellant restrictions in the United States limit formulation options and increase water-based alternative development costs.
- Microfiber substrate concentration:Asian textile manufacturers control woven substrate supply, exposing converters to freight cost fluctuations and tariff exposure.
Strategic Opportunities
- VR headset ecosystem expansion:Immersive hardware manufacturers bundle cleaning solutions with premium devices, creating captive demand channels.
- EU Green Deal chemical transition:Bio-based solvent incentives reward early movers in plant-derived cleaning compound development.
- Travel-size convenience formats:Single-use impregnated wipes for smartphone screens capture margin pools through airport retail and hospitality distribution.
Industry Challenges
- Formulation chemist talent scarcity:Expertise in surfactant-evaporative rate balancing for optical surfaces is concentrated among legacy optical industry veterans.
- FDA 510(k) pathway complexity:Medical device cleaning claims require sterilization validation timelines that extend product launch cycles.
- Multi-regional SKU proliferation:Divergent chemical disclosure mandates across states and countries fragment inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lens Cleaning Product Market |
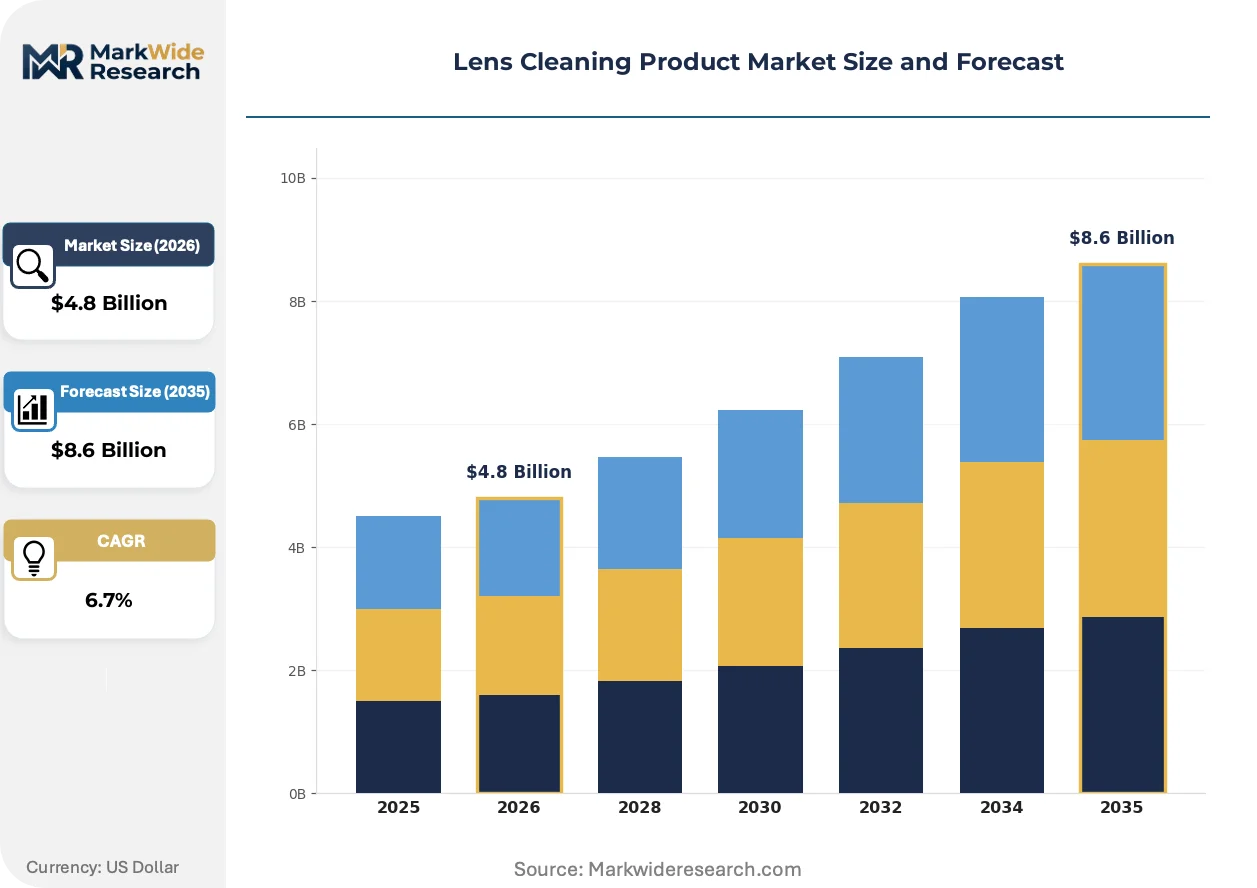
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Spray, Wipes, Pre-Moistened Cloths, Gel Application: Optical Glasses, Camera Lenses, Smartphone Screens, VR Headsets End User: Consumers, Photographers, Healthcare Professionals, Technicians Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | 3M, Bausch + Lomb, Carl Zeiss, Honeywell International, PIP Global, Pyramex, Olympus, Johnson & Johnson, Kimberly-Clark Worldwide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lens Cleaning Product Market Shifts & Advancements
Active coating technologies and sustainable chemistry are compressing traditional formulation paradigms, while procurement patterns shift toward bundled hardware-accessory relationships that reshape margin distribution across the value chain.
Plant-derived solvent systems are integrating into premium formulations to satisfy EU Green Deal chemical transition mandates without sacrificing evaporative performance. European optical equipment manufacturers are piloting these bio-based alternatives in professional photography and medical device maintenance segments. This substitution is integrating sustainability credentials into brand positioning while maintaining optical clarity standards.
REACH chemical registration requirements in Europe are constraining preservative and surfactant choices, compelling manufacturers to redesign formulations around pre-approved substance inventories. The industrial consequence is elevated R&D expenditure for market access compliance. Professional photography equipment preservation products face the steepest reformulation burden given their residue-sensitive performance requirements.
Hardware bundling is displacing standalone accessory purchasing for premium smartphone and VR headset buyers. Device manufacturers now specify cleaning kit inclusion in flagship product packaging, compressing aftermarket retail opportunities. This pattern is most visible in United States metropolitan electronics retail corridors where carrier stores and flagship outlets prioritize complete solution presentations.
Lens Cleaning Product Market Segmentation
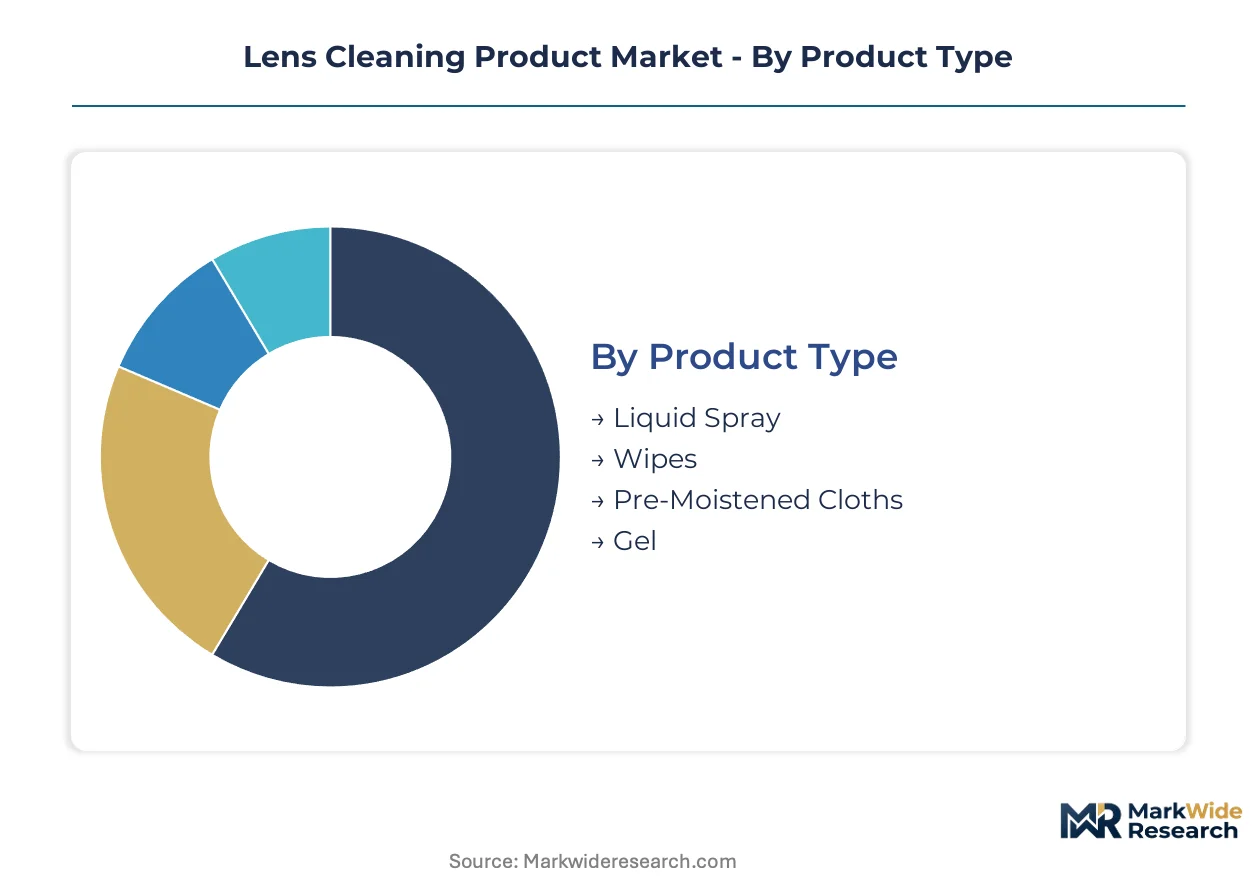
Lens cleaning product manufacturers face divergent capital requirements across format categories, with liquid spray production demanding stainless steel mixing vessels and wipes conversion requiring automated folding and impregnation lines. Segmentation reveals how formulation chemistry, substrate engineering, and packaging specifications reshape investment priorities and margin structures.
Product Type:
Liquid spray formats demand the heaviest upfront capital for bulk formulation tanks and precision filling equipment, while pre-moistened cloth conversion lines require substantial textile handling infrastructure.
- Liquid Spray:Formulated solutions in pump-dispense or aerosol formats carry isopropyl alcohol concentrations between 60% and 99%, balanced with deionized water and surfactants for controlled evaporation. Institutional procurement in United States healthcare systems and European optical laboratories anchors volume demand, though EPA VOC constraints on propellant systems elevate compliance costs for aerosol variants.
- Wipes:Dry substrate products rely on user-applied liquid solutions, minimizing formulation complexity but requiring robust microfiber sourcing relationships. Asian textile manufacturers dominate woven substrate supply, exposing converters to freight volatility and tariff exposure on imported materials.
- Pre-Moistened Cloths:Single-use impregnated formats capture travel retail and hospitality distribution with margin premiums.
- Gel:Viscous compounds target precision optical maintenance with residue-sensitive performance requirements.
Liquid spray absorbs the bulk of installed capacity; pre-moistened cloths are expanding most quickly.
Application:
Application segmentation tracks how device proliferation fragments demand into specialized substrate formats, with smartphone and VR hardware bundling reshaping procurement patterns.
- Optical Glasses:Consumer eyewear maintenance represents the foundational demand pool, with prescription lens coatings requiring pH-neutral formulations that preserve anti-reflective layers. Mass-market retail through pharmacies and supermarkets in Germany and France sustains volume, though private-label competition compresses branded margins.
- Camera Lenses:Professional photography equipment preservation demands residue-free performance with stringent evaporative specifications. REACH chemical registration requirements impose the steepest reformulation burden here, as European professionals reject any surfactant residue that degrades optical clarity.
- Smartphone Screens:Touch-interface cleaning concentrates in metropolitan United States electronics retail corridors where carrier stores bundle cleaning kits at point-of-purchase.
- VR Headsets:Immersive hardware manufacturers specify cleaning solution inclusion in flagship packaging, creating captive demand channels.
Optical glasses absorb the bulk of installed capacity; VR headsets are climbing the fastest.
End User:
End user categories stratify by sterilization-grade requirements and price sensitivity, with healthcare procurement commanding premium positioning through validation protocols.
- Consumers:Mass-market purchasers prioritize convenience formats and retail accessibility over technical specifications. Supermarket and pharmacy channel dominance by Kimberly-Clark Worldwide and comparable operators sustains throughput at economy price points.
- Photographers:Professional equipment owners demand residue-sensitive formulations with documented evaporative performance. This segment tolerates premium pricing for heritage optical brands that leverage technical credibility.
- Healthcare Professionals:Surgical loupe and endoscopic equipment maintenance requires FDA 510(k) pathway compliance for sterilization-grade claims, extending product launch timelines but anchoring procurement at elevated price points.
- Technicians:Industrial and laboratory optical maintenance demands bulk formats with institutional purchasing economics.
Consumers absorb the bulk of installed capacity; healthcare professionals are gaining share fastest.
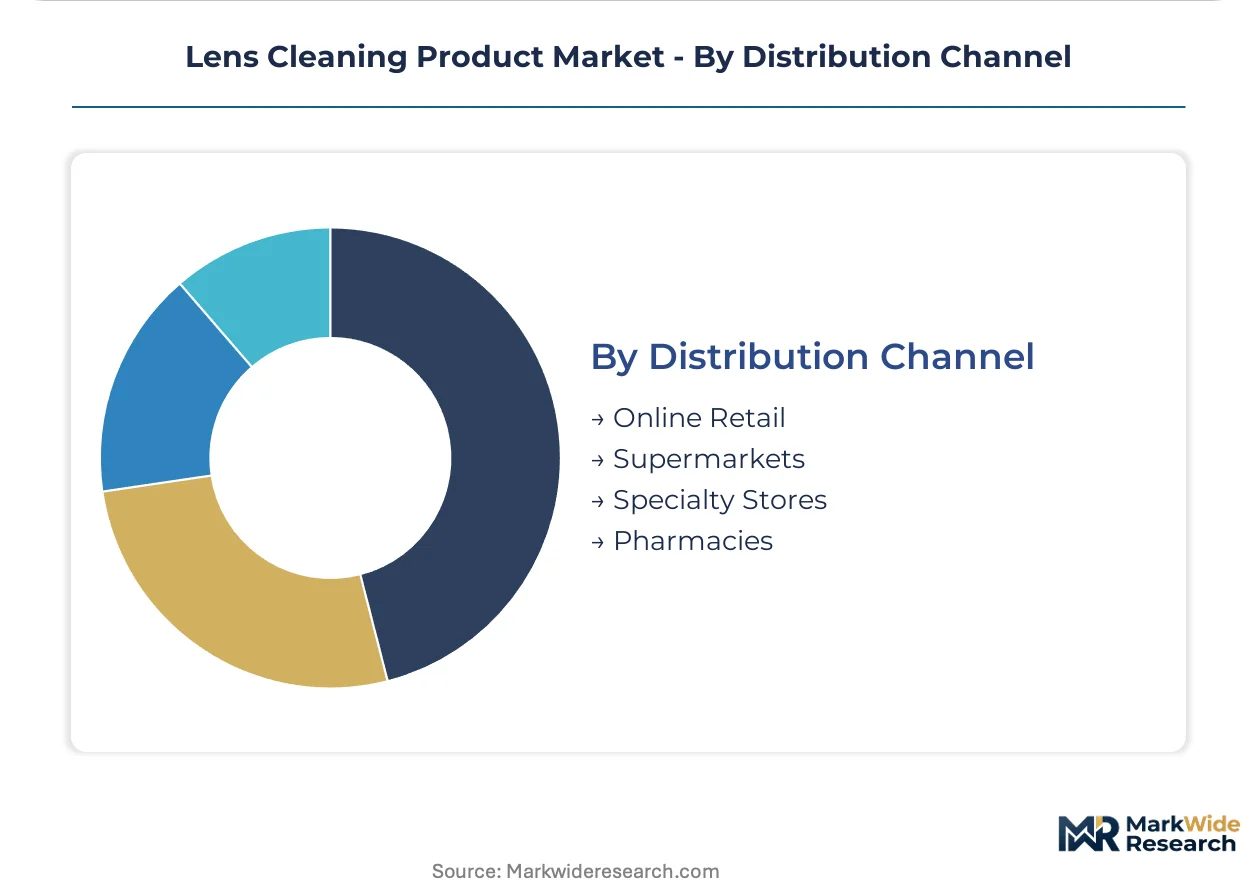
Distribution Channel:
Channel segmentation reflects how hardware bundling displaces standalone accessory purchasing, compressing aftermarket retail opportunities for traditional formats.
- Online Retail:E-commerce platforms aggregate long-tail demand for specialty formulations and bulk institutional purchasing. Amazon and comparable marketplaces enable direct-to-consumer access for premium optical heritage brands that bypass traditional retail markup structures.
- Supermarkets:Mass-market throughput depends on shelf-space negotiations with national pharmacy and grocery chains. This channel favors standardized formulations with universal compliance credentials to minimize regional SKU complexity.
- Specialty Stores:Camera equipment retailers and optical boutiques sustain premium positioning through technical consultation and brand curation.
- Pharmacies:Healthcare-grade formulations with sterilization claims leverage clinical trust and prescription-adjacent purchasing behavior.
Supermarkets absorb the bulk of installed capacity; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smartphone screen cleaning demand concentrates in United States metropolitan electronics retail corridors, while REACH compliance in Europe elevates formulation standards for alcohol-based cleaners.
United States
Touch-interface adoption broadens across smartphones, tablets, and AR/VR headsets, fragmenting demand into specialized substrate formats. EPA regulations govern volatile organic compound emissions from aerosol spray formulations, constraining propellant choices and driving water-based alternatives. Metropolitan electronics retail corridors in New York, Los Angeles, and Chicago concentrate demand for bundled cleaning kits at point-of-purchase.
Germany
Professional photography equipment preservation demands residue-free performance with stringent evaporative specifications. REACH chemical registration requirements impose the steepest reformulation burden, as European professionals reject any surfactant residue that degrades optical clarity. Frankfurt and Munich optical laboratories anchor institutional procurement volume for liquid spray formats.
China
Asian textile manufacturers control woven microfiber substrate supply, exposing converters to freight cost fluctuations and tariff exposure. The country's national chemical regulator maintains standards for industrial solvent formulations used in precision optical maintenance. Shenzhen and Dongguan electronics manufacturing clusters drive captive demand for pre-moistened wipes bundled with smartphone exports.
Japan
Medical device optical maintenance requires sterilization-grade cleaning protocols, anchoring healthcare procurement at elevated price points. METI oversees industrial chemical standards for electronics-grade solvent purity. Tokyo and Osaka surgical equipment supply chains sustain demand for FDA-aligned sterilization-grade formulations.
United Kingdom
Consumer eyewear maintenance through pharmacies and supermarkets sustains mass-market volume, though private-label competition compresses branded margins. The country's chemical disclosure mandates align with REACH frameworks post-regulatory transition. London and Manchester retail corridors concentrate distribution for travel-size convenience formats through airport and hospitality channels.
Lens Cleaning Product Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers retool production lines for pre-moistened wipes while maintaining liquid spray capacity for institutional buyers. The vendor base stratifies across three tiers: optical heritage brands commanding premium positioning, mass-market operators sustaining supermarket throughput, and healthcare-grade specialists anchoring sterilization-validated procurement. Strategic archetypes include formulation chemistry leaders, substrate engineering specialists, and channel-dominant distributors. M&A activity and geographic expansion represent the dominant competitive moves as players secure multi-source procurement for isopropyl alcohol and microfiber substrates.
Within the optical heritage tier, Carl Zeiss leverages technical credibility accumulated across precision instrument manufacturing. Among diversified healthcare conglomerates, Johnson & Johnson and 3M occupy positions spanning consumer, professional, and clinical segments. At the mass-market throughput end, Kimberly-Clark Worldwide exemplifies channel dominance through supermarket and pharmacy negotiations.
| Leading Market Players |
|---|
| 3M |
| Bausch + Lomb |
| Carl Zeiss |
| Honeywell International |
| PIP Global |
| Pyramex |
| Olympus |
| Johnson & Johnson |
| Kimberly-Clark Worldwide |
| Others |
Supply & Pricing Matrix
Captive sourcing of isopropyl alcohol through pharmaceutical-grade refiners anchors both cost predictability and premium pricing power for sterilization-grade formulations, while outsourced microfiber procurement from Asian textile converters exposes margin compression during freight spikes.
Pricing Analysis
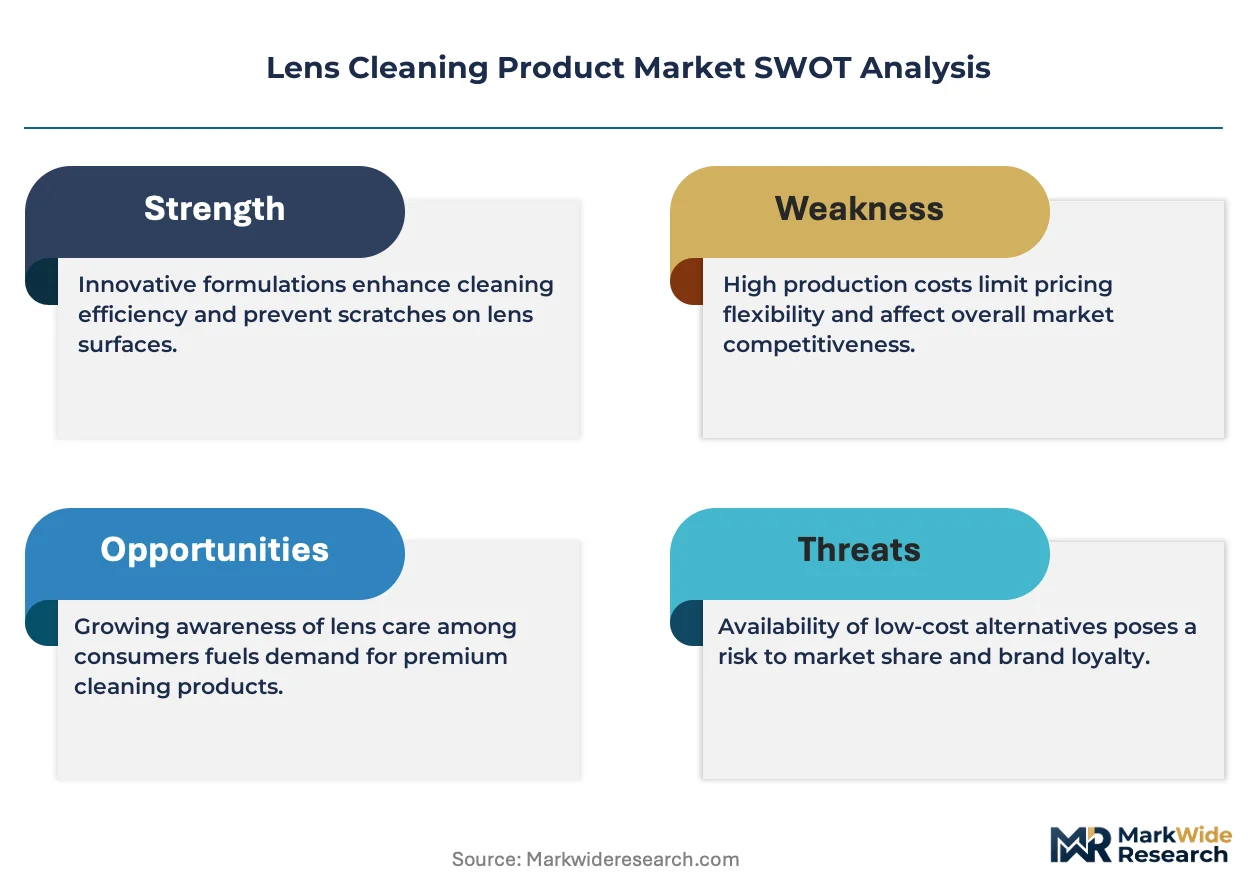
Warranty-backed formulation guarantees separate Carl Zeiss and Johnson & Johnson premium tiers from unbundled economy alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and evaporative performance specifications. Cost compression in the mass-market tier is intensifying because private-label supermarket competition erodes branded shelf space. Healthcare procurement committees show the least price sensitivity due to sterilization validation requirements, while consumer eyewear buyers prioritize convenience formats over technical specifications.
Supply Chain Analysis
REACH and FDA 510(k) qualification gating restricts formulation chemist talent pools to legacy optical industry veterans and sterilization-validated compounders. Isopropyl alcohol feedstock concentrates in United States pharmaceutical corridors, German chemical clusters, and Chinese industrial solvent manufacturers. Microfiber substrates draw from Chinese and Vietnamese textile converters. Single-source vulnerability runs through Asian woven substrate supply. Distribution runs through bundled hardware-accessory relationships at flagship electronics retail and institutional procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Isopropyl alcohol supply constraints from pharmaceutical and electronics manufacturing competition prop pricing resilience across sterilization-grade segments.
For Market Incumbents: Deepen backward integration into pharmaceutical-grade alcohol refining to defend against feedstock competition from vaccine manufacturers. Secure multi-year microfiber substrate offtake agreements with Vietnamese and Chinese textile converters before tariff escalation. Channel control through carrier store exclusivity represents the critical defensive lever against hardware bundling displacement. For New Entrants and Emerging Players: Airport retail distributors offer the most penetrable channel for travel-size pre-moistened wipe formats, where convenience premiums override brand loyalty. Target VR headset accessory bundling agreements with Shenzhen and Dongguan manufacturing clusters before incumbent optical heritage brands establish captive relationships. A direct-to-consumer subscription model for refill liquid sprays bypasses supermarket slotting fee barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in healthcare conglomerate acquisition of sterilization-validated formulation specialists. Five-to-ten year viability hinges on REACH compliance completion timelines and FDA 510(k) clearance portfolios. Watch for EPA VOC rulemaking expansion as the inflection signal accelerating water-based formulation R&D valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alcohol Refining | Captive pharmaceutical-grade feedstock supply insulates margin from vaccine manufacturing demand spikes. |
| REACH-Compliant Formulation Redesign | Pre-approved substance inventories unlock European professional photography and medical device segments. |
| VR Hardware Bundling Partnership | Device manufacturer specification creates captive demand channels displacing aftermarket retail. |
| Travel-Size Wipe Format Expansion | Airport and hospitality distribution captures margin premiums through convenience positioning. |
| Sterilization-Grade Certification Investment | FDA 510(k) pathway completion anchors healthcare procurement at elevated price points. |
Research Methodology
Multi-period observation of isopropyl alcohol spot pricing, REACH registration timelines, and EPA VOC regulatory filings anchored the trend analysis, supplemented by interviews with formulation chemists at optical heritage manufacturers, procurement directors at hospital GPOs, microfiber substrate converters in Vietnam, and category buyers at United States pharmacy chains. Secondary validation drew from ECHA substance inventories, FDA 510(k) clearance databases, SEC 10-K disclosures from diversified healthcare conglomerates, and customs records tracking isopropyl alcohol trade flows. Bottom-up segment sizing triangulated against top-down market value estimates.
Segment-weighting across product type, application, end user, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points and hardware shipment correlations. Forecast inputs incorporated smartphone and VR headset production forecasts, REACH compliance cost curves, and sterilization-grade validation timeline distributions.
Caveats apply where EPA VOC rulemaking expansion, REACH substance restriction updates, or isopropyl alcohol supply disruptions from pharmaceutical manufacturing competition could materially shift the outlook. A model refresh is warranted upon material change in hardware bundling penetration rates or sterilization-grade certification backlog durations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Descaler Market
Cleaning Chemicals
Kitchen Vent Hood and Duct Cleaning Chemicals Market
Cleaning Chemicals
Autonomous Floor Cleaning Machine Detergent and Care Chemicals Market
Cleaning Chemicals
Coating Removal System Market
Cleaning Chemicals
Drain Opener Chemicals Market
Cleaning Chemicals
Fabric Conditioner Market
Cleaning Chemicals
Home Insecticides Market
Cleaning Chemicals
Commercial Cleaning Products Market
Cleaning Chemicals
US Institutional Cleaning Ingredients Market
Cleaning Chemicals
Electrostatic Liquid Cleaner Market
Cleaning Chemicals
Global Metal Cleaning Chemicals Market
Cleaning Chemicals
Dishwashing Liquid Market
Cleaning Chemicals
Dry Cleaning Solvents Market
Cleaning Chemicals
Sponge and Scouring Pads Market
Cleaning Chemicals
Global Antiseptic Products Market
Cleaning Chemicals
US Specialty Cleaners Market