
 Dual Chamber Dispensing Bottles Market | 2026-2036
Dual Chamber Dispensing Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Dual Chamber Dispensing Bottles Market Foresight
Asset-light contract manufacturing is narrowing the capital barrier for mid-tier cosmetic brands seeking dual-chamber formats, allowing private-label entrants to challenge established suppliers. Gerresheimer AG leverages its glass-forming expertise to dominate pharmaceutical-grade dual-chamber vials. AptarGroup, Inc. sustains technology leadership through precision pump mechanisms that integrate with dual-chamber architectures. TekniPlex Healthcare anchors North American supply with vertically controlled polymer compounding for barrier-sensitive applications.
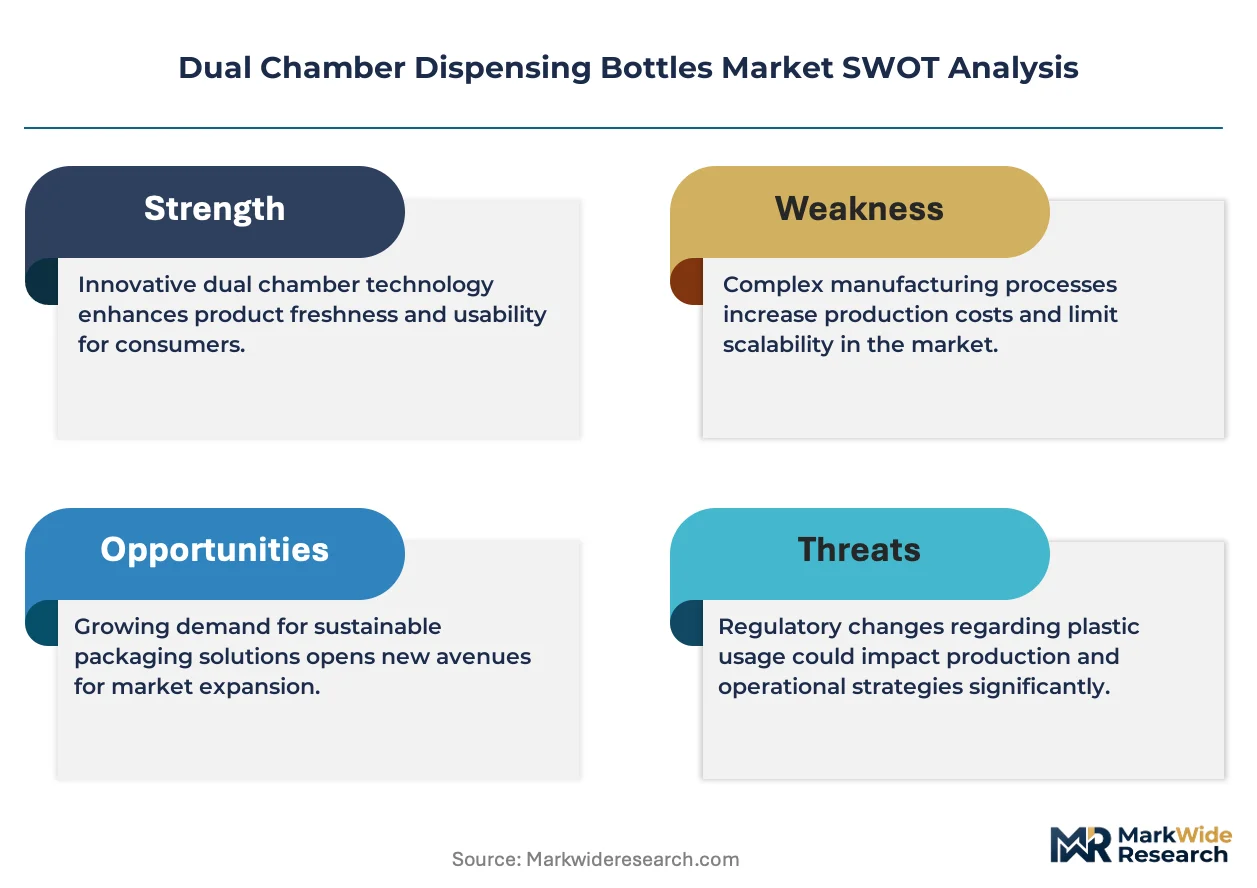
Dual chamber dispensing bottles integrate two isolated reservoirs within a single container body, typically separated by a piston, membrane, or welded partition that permits sequential or simultaneous discharge through a common actuator. Construction employs cyclic olefin polymers, multilayer coextruded plastics, or borosilicate glass to achieve oxygen transmission rates below 0.1 cc per square meter daily, preserving incompatible actives such as vitamin C and retinol in personal care or biologics in parenteral delivery. Plastic bottles lead volume due to cost scalability across 50ml to 500ml formats, though glass bottles command margin pools in pharmaceutical applications requiring USP Type I compliance. Spray bottles represent the fastest-growing application segment as fine-mist dual-chamber systems displace single-compartment alternatives in sun care and wound-cleansing markets.
FDA 21 CFR Part 177 regulates indirect food-contact polymers used in dual-chamber food dispensers, while EMA guidelines on combination products govern drug-device dual-chamber systems marketed in Europe. ISO 15378 extends GMP requirements to primary packaging materials, compelling suppliers to validate barrier integrity across chamber seals. Stakeholders must monitor evolving EPA per- and polyfluoroalkyl substance restrictions, as fluorinated barrier coatings face prospective phaseouts that would force material transitions in high-performance dual-chamber formats.
Market Dynamics
Active-ingredient separation requirements in cosmetics and biologics are forcing material science upgrades across barrier technologies, compressing development timelines for multi-compartment formats while elevating compliance costs for mid-tier suppliers.
Growth Catalysts
- REACH compliance tightening:ECHA's evolving substance restrictions in Europe are accelerating adoption of validated barrier materials that guarantee chamber isolation, pushing manufacturers toward certified polymer suppliers.
- Precision dosing in wound care:Spray bottle formats integrating dual-reservoir architectures are capturing share in clinical cleansing applications where sequential discharge improves therapeutic outcomes.
- Vitamin C and retinol incompatibility:Cosmetic formulators are specifying dual-chamber designs to prevent oxidation-driven degradation, creating specification pull from premium skincare brands.
Market Restraints
- Fluorinated barrier coating phaseout risk:EPA restrictions on per- and polyfluoroalkyl substances threaten high-performance oxygen barrier layers, forcing premature material transitions before alternatives achieve equivalent transmission rates.
- Glass-forming capacity concentration:Pharmaceutical-grade borosilicate supply clusters in Germany and Switzerland, creating geographic concentration risk for USP Type I compliant dual-chamber vials.
- Cyclic olefin polymer cost volatility:Crude-linked feedstock pricing for COC resins compresses margin predictability at volume scale across 50ml to 500ml plastic formats.
Strategic Opportunities
- India cosmetic manufacturing expansion:PLI scheme incentives for packaging localization are opening private-label entry points for dual-chamber formats previously import-dependent.
- Combination product regulatory clarity:EMA guidelines on drug-device dual-chamber systems are creating compliance roadmaps that reward early-mover validation investments in European markets.
- Barrier-sensitive biologics:Cell and gene therapy cold-chain requirements are converging with dual-chamber mixing-at-delivery formats, expanding addressable demand beyond traditional parenteral applications.
Industry Challenges
- ISO 15378 validation timelines:GMP extension to primary packaging materials demands chamber-seal integrity documentation that extends qualification cycles by 12-18 months for new formats.
- Membrane welding precision:Micro-scale partition consistency across high-speed production lines requires capital-intensive laser welding systems that strain mid-cap equipment budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual Chamber Dispensing Bottles Market |
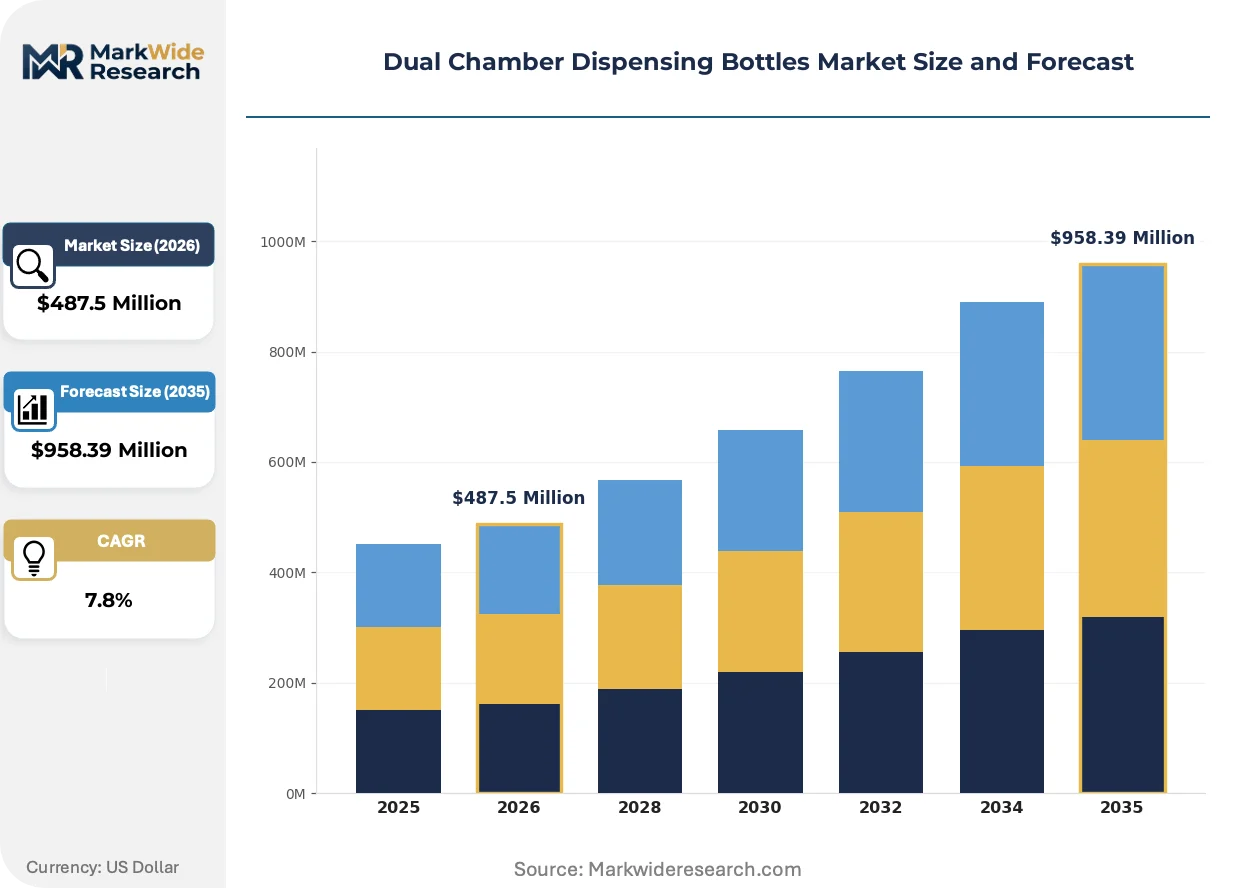
| Market Size in 2026 | $487.5 Million |
| Market Size in 2035 | $958.39 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bottles, Glass Bottles, Metal Bottles, Composite Bottles End User: Pharmaceutical Companies, Cosmetic Manufacturers, Food & Beverage Producers, Household Product Suppliers Capacity: 50ml, 100ml, 200ml, 500ml Application: Liquid Dispensers, Cream Dispensers, Spray Bottles, Gel Dispensers |
| Companies Covered | Gerresheimer AG, TekniPlex Healthcare, AptarGroup, Inc., HCP Packaging, Cospack America Corp., Silgan Holdings Inc., TricorBraun, Albea, Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual Chamber Dispensing Bottles Market Shifts & Advancements
Barrier architecture innovation is compressing the performance gap between polymer and glass formats while regulatory chemistry restrictions are forcing material substitutions ahead of qualification cycles.
Piston-actuated sequential discharge mechanisms are collapsing the complexity premium historically attached to dual-chamber designs. Personal care brands in sun care and serum categories are specifying these systems for consumer-controlled mixing moments. The technology is collapsing price differentiation between premium dual-chamber and conventional single-reservoir formats at volume tiers above 100ml.
EPA per- and polyfluoroalkyl substance restrictions are accelerating fluorinated coating phaseouts in barrier-sensitive applications. Manufacturers serving pharmaceutical and high-performance cosmetic segments face forced transitions to multilayer coextruded alternatives before equivalent oxygen transmission validation completes. North American suppliers with captive polymer compounding capabilities are capturing specification shifts ahead of imported alternatives.
Specification authority is migrating from brand marketing teams to regulatory affairs functions as combination product classifications proliferate. Procurement cycles for dual-chamber pharmaceutical formats now embed 18-24 month qualification protocols that favor incumbent validated suppliers over cost-disruptive entrants. Germany's precision dosing concentration demonstrates this pattern most visibly, where established Gerresheimer relationships command specification lock-in despite 15-20% price premiums.
Dual Chamber Dispensing Bottles Market Segmentation
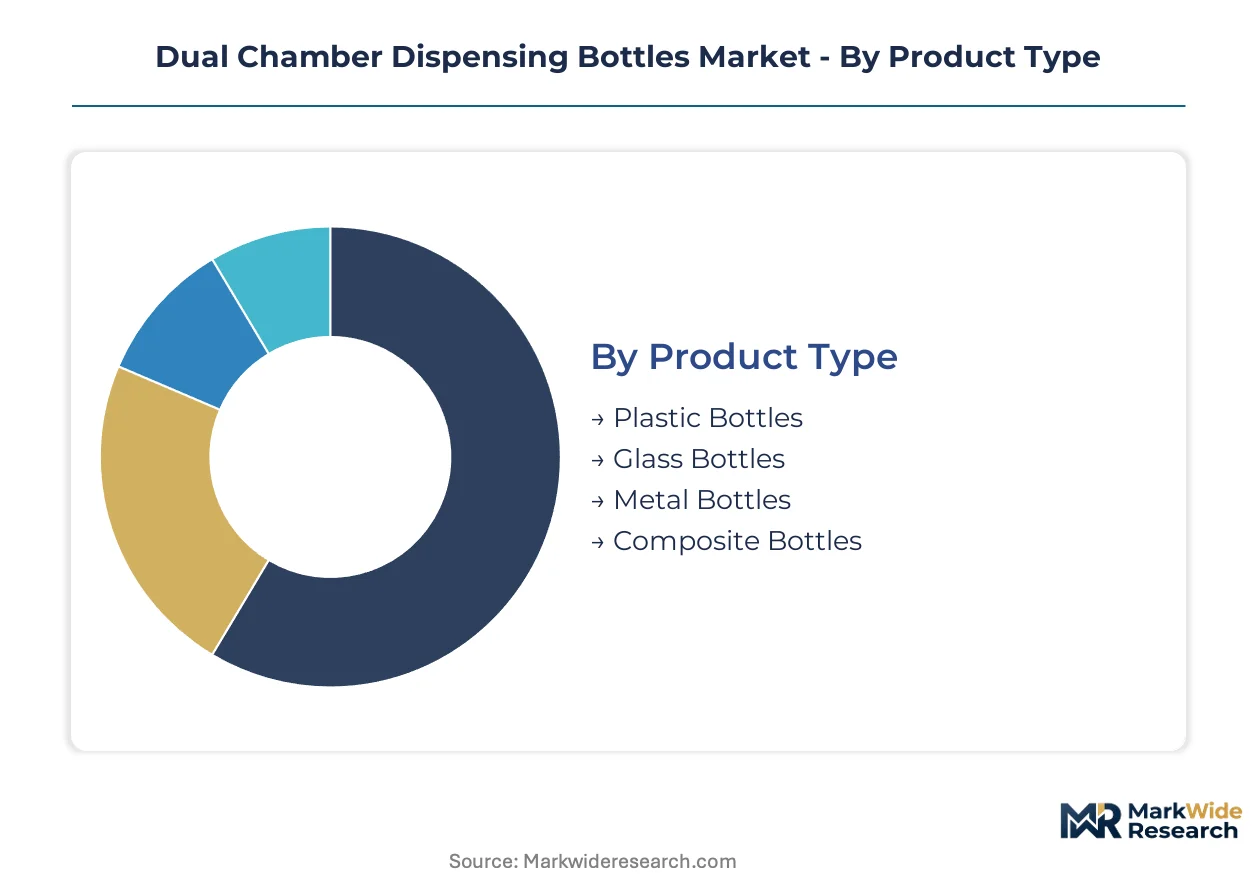
Dual-chamber formats demand material and design specifications that vary sharply across end-use requirements. Segmentation reveals where formulation compatibility, barrier performance, and dosing precision create divergent value pools.
Product Type:
Plastic bottles turn inventory fastest in high-volume personal care, while glass formats cycle slowly through pharmaceutical validation protocols.
- Plastic Bottles:Cyclic olefin polymers and multilayer coextruded plastics dominate construction across 50ml to 500ml formats. Cosmetic manufacturers in Germany specify these for vitamin C and retinol separation where oxygen transmission must stay below 0.1 cc per square meter daily. REACH compliance tightening accelerates adoption of certified polymer suppliers over generic alternatives.
- Glass Bottles:Borosilicate construction achieves USP Type I compliance for parenteral biologics. Supply concentrates in German and Swiss glass-forming clusters, extending lead times for pharmaceutical-grade dual-chamber vials. Gerresheimer relationships command specification lock-in despite price premiums.
- Metal Bottles:Aluminum and stainless steel formats serve niche applications requiring electromagnetic shielding or extreme temperature stability.
- Composite Bottles:Hybrid polymer-metal laminates address barrier-sensitive applications where single-material solutions fail.
Plastic bottles anchor the volume base while glass formats gain share at the steepest rate in pharmaceutical applications.
End User:
Procurement authority varies sharply—cosmetic brands prioritize speed-to-market while pharmaceutical buyers embed 18-24 month qualification cycles.
- Pharmaceutical Companies:ISO 15378 GMP requirements extend to primary packaging materials, demanding chamber-seal integrity documentation. EMA guidelines on combination products govern drug-device dual-chamber systems in Europe. FDA 21 CFR Part 177 regulates indirect food-contact polymers for parenteral delivery formats.
- Cosmetic Manufacturers:Asset-light contract manufacturing narrows capital barriers for mid-tier brands seeking dual-chamber formats. Premium skincare brands in sun care and serum categories specify piston-actuated sequential discharge for consumer-controlled mixing moments.
- Food & Beverage Producers:Dual-reservoir designs separate reactive ingredients until point-of-use in condiment and beverage applications.
- Household Product Suppliers:Industrial cleaning and adhesive formats employ dual-chamber architectures for chemical compatibility.
Cosmetic manufacturers move volume fastest while pharmaceutical qualification protocols stretch development cycles longest.
Capacity:
Format scale determines actuator complexity and barrier investment per unit.
- 50ml:Travel-size and sample formats concentrate in premium cosmetic sampling programs.
- 100ml:Personal care standard enables piston-actuated systems to collapse price differentiation against single-reservoir alternatives.
- 200ml:Mid-scale formats balance dosing precision with production efficiency in clinical wound-cleansing applications.
- 500ml:Institutional and professional formats command highest absolute barrier investment per unit.
100ml formats anchor the volume base while 50ml formats climb fastest in premium sampling segments.
Application:
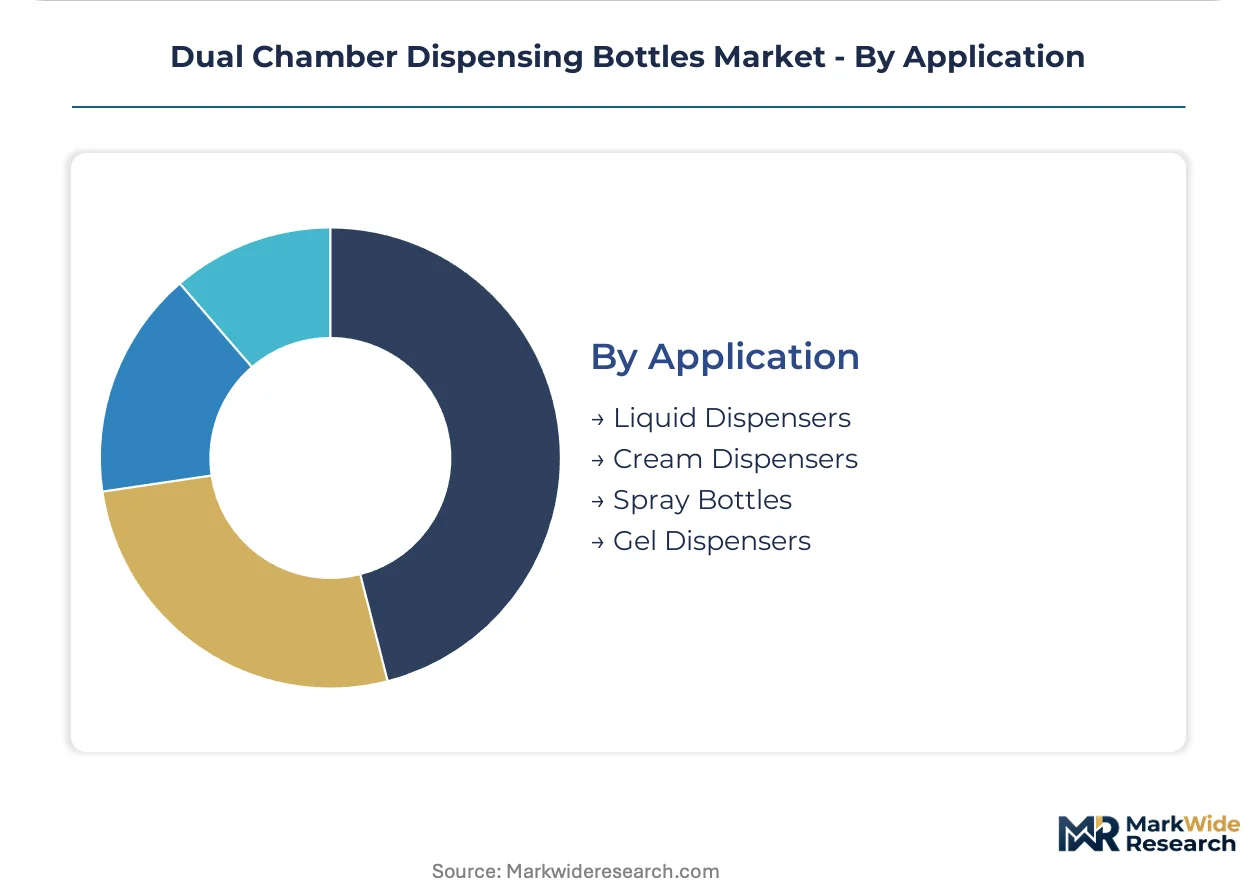
Spray mechanisms demand finest partition precision, while liquid formats tolerate wider manufacturing tolerances.
- Liquid Dispensers:Standard pump-actuated formats serve serum and oil separation in personal care.
- Cream Dispensers:Viscous formulations require wider chamber geometries and reinforced piston seals.
- Spray Bottles:Fine-mist dual-chamber systems displace single-compartment alternatives in sun care and wound-cleansing markets. Precision dosing requirements in clinical applications capture share from conventional formats. EPA per- and polyfluoroalkyl substance restrictions force material transitions in barrier-sensitive spray applications.
- Gel Dispensers:Thixotropic formulations demand specialized actuator geometries to prevent chamber cross-contamination.
Liquid dispensers anchor the volume base while spray bottles expand most quickly in clinical and sun care applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances concentrate dual-chamber dispensing bottle supply in German and Swiss glass-forming clusters, while demand absorption centers on US pharmaceutical hubs and Indian cosmetic manufacturing zones.
Germany
Precision dosing applications in wound care and biologics drive specification pull for borosilicate dual-chamber vials. ECHA's evolving REACH substance restrictions accelerate validated barrier material adoption among certified polymer suppliers. The Mainz-Rhine corridor anchors pharmaceutical-grade glass-forming capacity where Gerresheimer relationships command specification lock-in.
United States
Spray bottle formats in sun care and clinical cleansing capture share from single-compartment alternatives. EPA restrictions on per- and polyfluoroalkyl substances force premature transitions in fluorinated barrier coatings. North American suppliers with captive polymer compounding capabilities in Ohio and Pennsylvania capture specification shifts ahead of imported alternatives.
India
PLI scheme incentives for packaging localization open private-label entry points for dual-chamber formats previously import-dependent. CDSCO guidelines on combination products create compliance roadmaps for drug-device dual-chamber systems. Maharashtra and Gujarat cosmetic manufacturing clusters expand asset-light contract manufacturing capacity for mid-tier brands.
Switzerland
Swissmedic regulations on primary packaging materials for parenteral delivery extend ISO 15378 GMP requirements to chamber-seal integrity documentation. The Basel-Zurich corridor concentrates glass-forming expertise for USP Type I compliant dual-chamber vials serving European biologics markets.
China
NMPA oversight of combination products governs drug-device dual-chamber systems marketed domestically. Yangtze River Delta cosmetic manufacturers specify piston-actuated sequential discharge systems for vitamin C and retinol separation. Multilayer coextruded plastic capacity expands across 50ml to 500ml formats for barrier-sensitive applications.
Dual Chamber Dispensing Bottles Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in barrier materials and precision actuators. The vendor base stratifies across three tiers: validated pharmaceutical-grade suppliers with 18-24 month qualification protocols, mid-cap cosmetic-focused fabricators leveraging asset-light contract manufacturing, and regional private-label entrants capturing PLI-driven localization opportunities. Two competitive moves dominate: backward integration into captive polymer compounding to secure barrier material supply, and technology licensing partnerships to collapse development timelines for multi-compartment formats.
Within the validated pharmaceutical-grade tier, Gerresheimer AG and AptarGroup, Inc. exemplify divergent strategic positions. Gerresheimer leverages glass-forming expertise concentrated in German and Swiss industrial clusters. AptarGroup sustains technology leadership through precision pump mechanism integration. TekniPlex Healthcare anchors North American supply with in-house polymer compounding capabilities for barrier-sensitive applications.
| Leading Market Players |
|---|
| Gerresheimer AG |
| TekniPlex Healthcare |
| AptarGroup, Inc. |
| HCP Packaging |
| Cospack America Corp. |
| Silgan Holdings Inc. |
| TricorBraun |
| Albea |
| Berry Global Inc. |
| Others |
Supply & Pricing Matrix
German and Swiss glass-forming clusters concentrate pharmaceutical-grade borosilicate supply, anchoring margin pools in USP Type I compliant dual-chamber vials where Gerresheimer relationships command specification lock-in despite 15-20% price premiums.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across pharmaceutical qualification cycles. Three-tier pricing structure across premium, standard, and economy levels separates validated suppliers with ISO 15378 documentation from mid-cap cosmetic fabricators and regional private-label entrants. Cost compression in fluorinated barrier coatings is intensifying because EPA per- and polyfluoroalkyl substance restrictions force premature material transitions. Mid-tier cosmetic brands exhibit highest price sensitivity due to asset-light contract manufacturing margins, while pharmaceutical buyers prioritize qualification certainty over unit economics.
Supply Chain Analysis
Extended payment terms from German glass-forming clusters strain working capital for North American distributors serving pharmaceutical hubs. Supply concentrates in Germany, Switzerland, and China for borosilicate vials, cyclic olefin polymers, and multilayer coextruded plastics respectively. Raw material dependencies draw from crude-linked COC resin feedstocks, fluorinated barrier coatings, and USP Type I compliant glass tubing. Single-source vulnerability clusters around German-Swiss pharmaceutical-grade glass-forming capacity. Distribution runs through validated supplier-direct relationships for pharmaceutical tiers and contract manufacturing networks for cosmetic volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chamber-seal validation services and qualification protocol consulting are expanding faster than hardware sales as ISO 15378 GMP extensions stretch pharmaceutical procurement cycles to 18-24 months.
For Market Incumbents: Insulate specification lock-in through captive polymer compounding investments that secure barrier material supply ahead of fluorinated coating phaseouts. Deepen backward integration into cyclic olefin polymer production to cushion crude-linked feedstock volatility. Priority defenses center on laser welding system capacity additions in German industrial clusters where membrane welding precision creates equipment bottlenecks for mid-tier challengers. For New Entrants and Emerging Players: Maharashtra and Gujarat cosmetic manufacturing clusters offer private-label entry points for dual-chamber formats previously import-dependent under India's PLI scheme incentives. White-space targets concentrate in 50ml premium sampling formats for vitamin C and retinol separation where piston-actuated sequential discharge systems collapse price differentiation against single-reservoir alternatives. Go-to-market execution should anchor on asset-light contract manufacturing partnerships with established barrier material suppliers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade dual-chamber vial production as laser welding precision requirements strain mid-cap equipment budgets. Long-term viability favors validated suppliers with 18-24 month qualification protocol relationships over cost-disruptive entrants. Acquisition targets should profile mid-cap cosmetic fabricators with backward integration pathways into captive polymer compounding. Signal to monitor: EPA per- and polyfluoroalkyl substance restriction enforcement timelines forcing material transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive COC resin supply secures margin predictability against crude-linked feedstock volatility. |
| Laser Welding System Capacity Expansion | Micro-scale partition consistency equipment creates bottlenecks that incumbent suppliers can monetize. |
| ISO 15378 Validation Protocol Investment | Chamber-seal integrity documentation extends qualification cycles that favor established relationships. |
| PLI Scheme Localization Partnership | Indian packaging incentives open private-label entry points for import-dependent dual-chamber formats. |
| Fluorinated Coating Alternative Development | Multilayer coextruded barrier R&D captures specification shifts ahead of EPA restriction enforcement. |
Research Methodology
Cross-validation between primary interviews with packaging procurement managers, regulatory affairs leads at cosmetic manufacturers, pharmaceutical GMP compliance officers, and contract manufacturing executives anchors the qualitative findings against secondary validation from ECHA substance restriction databases, FDA 21 CFR Part 177 filings, CDSCO combination product guidelines, and SEC disclosures from listed packaging suppliers. Bottom-up volume modeling triangulates against top-down market sizing across material type and end-use segments.
Calibration against historical COC resin price volatility and pharmaceutical validation timeline data refines projections across the analysis window. Segmentation dimensions include product material, end-user industry, capacity tier, and application format. CAGRs derive from regression analysis of adoption curve penetration in cosmetic active-ingredient separation and pharmaceutical biologics delivery. Industry-specific inputs incorporate REACH compliance cost trajectories and EPA per- and polyfluoroalkyl substance restriction implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in crude oil pricing, euro-dollar exchange rates, or pharmaceutical R&D capital allocation would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and material substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Beveled Bottles Market
Beverage Packaging
Juice Packaging Market
Beverage Packaging
Graduated Sample Bottle Market
Beverage Packaging
Drink Hoses Market
Beverage Packaging
Disposable Tea Flask Market
Beverage Packaging
PET Bottle Market
Beverage Packaging
Europe Beverage Container Market
Beverage Packaging
Tumblers Market
Beverage Packaging
Zippered Bottle Suit Market
Beverage Packaging
Pop-Up Pourer Market
Beverage Packaging
Twin Neck Bottles Market
Beverage Packaging
PET Syrup Bottle Market
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
Ice Transport Buckets Market
Beverage Packaging
Multicomponent Bottle Market
Beverage Packaging
Europe Soft Drinks Packaging Market