
 Europe Flexible Plastic Packaging Market | 2026-2036
Europe Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Flexible Plastic Packaging Market Insights
European converter investments in mono-material extrusion lines is recalibrating competitive dynamics across the continent. Amcor leverages its integrated film-to-pouch network to secure long-term supply contracts with pan-European retailers. Mondi anchors its position through kraft-paper hybrid innovations that reduce plastic dependency in food service applications. Constantia Flexibles specializes in pharmaceutical-grade barrier films that command premium positioning in regulated healthcare channels.
Europe flexible plastic packaging comprises polymer-based films, laminates, and formed containers typically measuring 25 to 250 microns in thickness, engineered to provide moisture, oxygen, and light barrier protection for perishable and sensitive goods. Stand-up pouches and shrink films represent the most dynamic product categories, with pouches displacing rigid containers in sauces and pet food while shrink film gains share in beverage multipacks. Polyethylene and polypropylene dominate material consumption, though bio-based plastics are capturing niche volume in premium personal care and organic food segments where brand owners seek differentiation through certified compostable claims.
REACH, the EU Packaging and Packaging Waste Regulation, and EFSA food contact standards collectively determine material approvals, recyclability targets, and market access conditions for all suppliers operating within Europe. ECHA substance restrictions and forthcoming extended producer responsibility fees are forcing reformulation investments across the value chain. Stakeholders must monitor regulatory implementation timelines and recyclability infrastructure buildout to align capacity decisions with compliance thresholds.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing converters to scrap multi-layer laminates and retool for mono-material extrusion, compressing legacy capacity values while rewarding early movers with recyclability-certified supply contracts.
Growth Catalysts
- REACH substance restrictions:Chemical reformulation mandates are accelerating demand for compliant barrier coatings in pharmaceutical blister films across German and French manufacturing clusters.
- Ready-to-eat meal processors:German food manufacturers are expanding pouch adoption for chilled prepared foods, displacing rigid trays with retort-compatible flexible formats.
- Mono-material extrusion:European converter investments in single-polymer lines are enabling closed-loop recycling claims that unlock premium shelf placement with pan-European retailers.
Market Restraints
- Ethylene feedstock volatility:Crude-linked polyethylene resin costs swing converter margins unpredictably, squeezing mid-tier producers without long-term offtake agreements.
- Barrier performance gaps:Current mono-material structures fail to match aluminum-oxide metallized films for ultra-high oxygen barrier in extended-shelf-life cheese applications.
- Mechanical recycling infrastructure:Sorting capacity shortages in Southern Europe limit actual recyclability rates regardless of packaging design compliance.
Strategic Opportunities
- Pharmaceutical blister films:French and Italian demand for high-barrier pharmaceutical packaging outstrips certified supplier capacity, creating white space for EFSA-compliant film specialists.
- Bio-based polypropylene:ISCC PLUS certified resins are capturing niche volume in premium organic food segments where brand owners seek compostable differentiation.
- Extended producer responsibility fees:Incoming modulated fee structures under the EU Packaging and Packaging Waste Regulation reward lightweight flexible formats versus rigid alternatives.
Industry Challenges
- Mono-material line reconfiguration:Retooling multi-layer coextrusion assets requires 18-24 month commissioning cycles, straining engineering talent pools in extrusion die design.
- EFSA food contact compliance:Novel barrier coating substances face 12-18 month safety evaluation timelines, delaying product launches for innovative film structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Flexible Plastic Packaging Market |
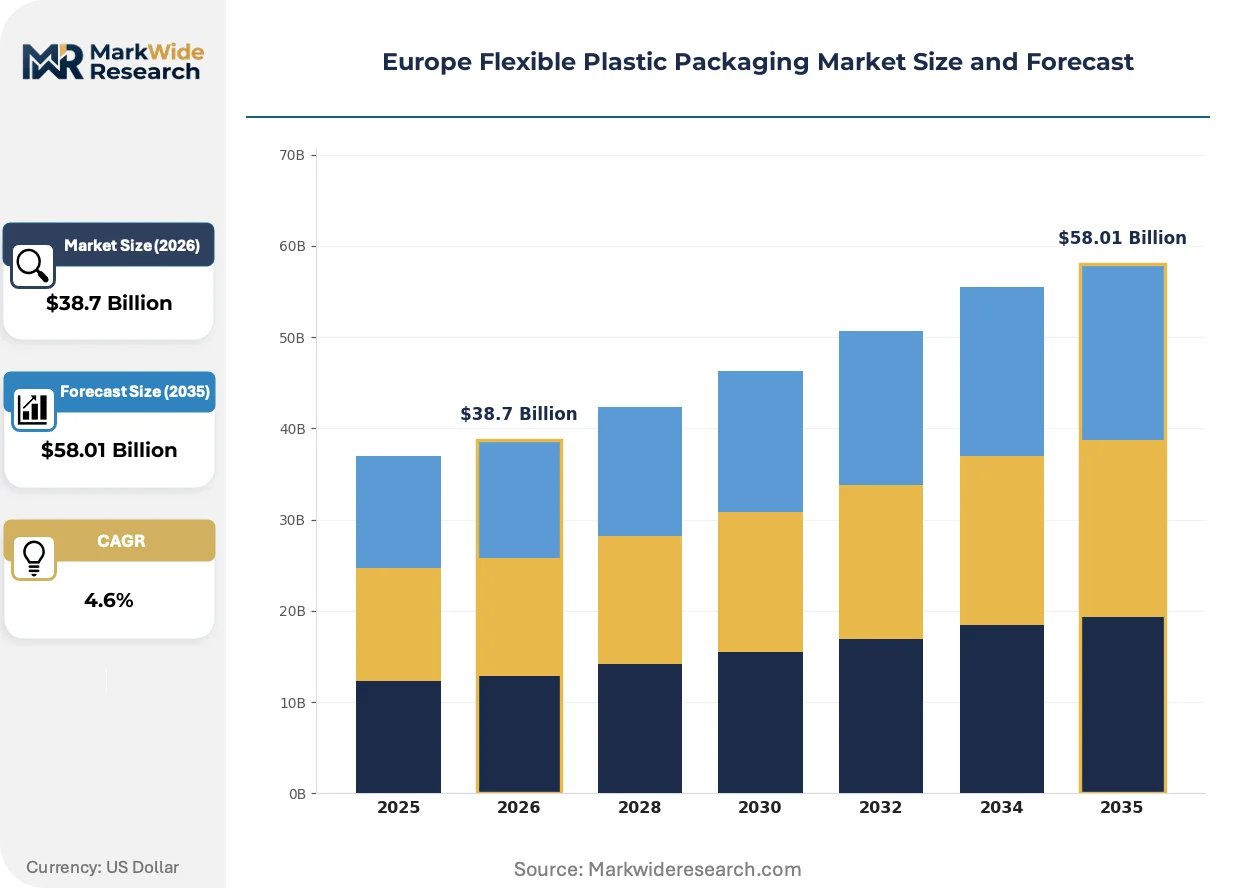
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouch, Flat Pouch, Bags, Shrink Film End User: Food & Beverage, Personal Care, Healthcare, Consumer Goods Material: Polyethylene, Polypropylene, Polyester, Bio-based Plastics Technology: Printing, Laminating, Coating, Sealing |
| Companies Covered | Amcor, Mondi, Sealed Air, Constantia Flexibles, Berry Global, Huhtamäki, Sonoco Products, Coveris, DS Smith, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Flexible Plastic Packaging Market Trends and Innovations
Digital printing and mono-material barrier engineering are collapsing minimum order quantities and recyclability certification timelines simultaneously, compressing the traditional trade-off between customization and circularity.
Digital inkjet printing on flexible films is modularizing short-run production economics for private-label sauces and regional snack brands. Mid-sized converters in Spain and Poland are adopting single-pass UV-LED systems to capture seasonal promotional volumes that rotogravure cannot profitably serve. This technology is modularizing the relationship between order scale and unit cost, enabling batch-size-one production without plate-changeover penalties.
The EU Packaging and Packaging Waste Regulation's recyclability performance grades are mandating design-for-recycling protocols by 2030. Industrial consequence falls heaviest on multi-layer snack and pet food pouches currently incorporating incompatible polymer combinations. German retailers are responding by delisting non-recyclable formats from own-brand portfolios ahead of enforcement deadlines, accelerating supplier qualification for mono-material alternatives.
Retailer consolidation across France, Germany, and the Benelux is concentrating procurement authority within fewer buying desks at Carrefour, Rewe, and Ahold Delhaize. National brand managers are losing negotiation leverage as centralized sustainability teams impose uniform recyclability specifications across private-label and branded supplier bases. This concentration is most visible in beverage multipacks, where shrink film specifications now flow from Brussels-based category directors rather than local country organizations.
Europe Flexible Plastic Packaging Market Segmentation
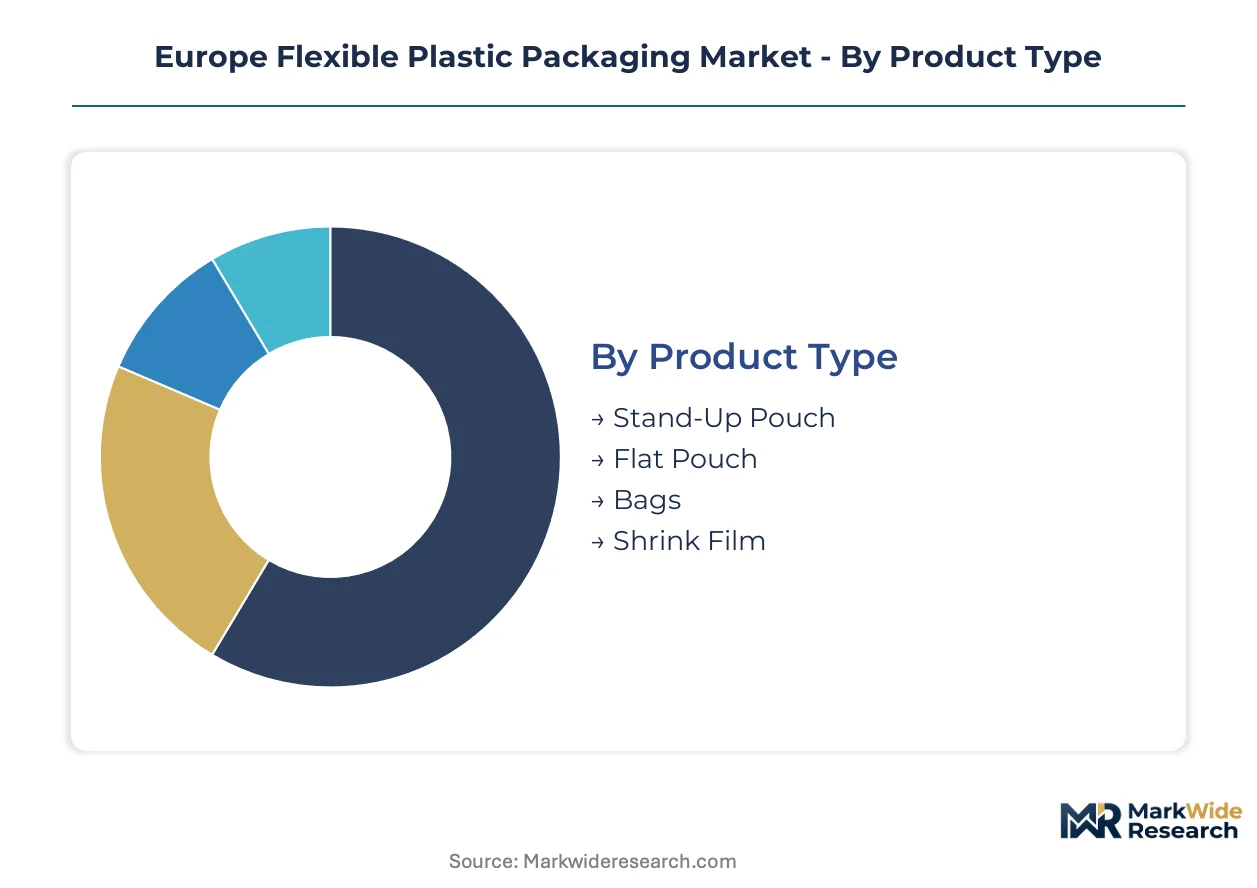
European converters configure production assets around four intersecting dimensions that determine barrier performance, recyclability certification, and compliance with EFSA food contact standards. Each segmentation axis carries distinct margin profiles and regulatory exposure.
Product Type:
Volume concentrates in commodity formats while premium positioning shifts toward convenience-driven structures with enhanced shelf appeal.
- Stand-Up Pouch:Multi-layer laminates with resealable zipper closures and bottom gusset construction. German ready-to-eat meal processors are displacing rigid trays with retort-compatible pouches that withstand 121°C sterilization cycles. REACH-compliant adhesive systems remain a formulation bottleneck.
- Shrink Film:Biaxially oriented polyethylene terephthalate or polyethylene structures engineered for 40-70% shrinkage ratios. Beverage multipack demand in France and Benelux is concentrating procurement authority within Carrefour and Ahold Delhaize sustainability teams. Mono-material specifications are displacing PVC alternatives.
- Flat Pouch:Three-side-seal configurations dominate pharmaceutical sachet applications.
- Bags:Gusseted and pillow formats serve bulk dry goods with lower barrier requirements.
Today's leader: Shrink Film. Tomorrow's challenger: Stand-Up Pouch.
End User:
Application-driven specifications split the market between high-volume food service and regulated healthcare channels with divergent compliance timelines.
- Food & Beverage:Moisture and oxygen barrier films for perishable goods with 25-250 micron thickness ranges. Italian pasta brands and Spanish olive oil packagers are adopting digital-printed flexible formats for seasonal promotional runs. EFSA safety evaluations for novel coating substances extend qualification cycles.
- Healthcare:Pharmaceutical-grade barrier films requiring EMA compliance for blister packs and sachet applications. French and Italian demand for high-oxygen-barrier structures outstrips certified supplier capacity. Aluminum-oxide metallized films retain dominance in extended-shelf-life applications.
- Personal Care:Premium organic segments are capturing bio-based plastic volumes with ISCC PLUS certification claims.
- Consumer Goods:Durable goods packaging prioritizes cost efficiency over barrier performance.
Food & Beverage commands current volume leadership. Healthcare offers the steepest expansion trajectory as regulatory barriers limit supplier entry.
Material:
Feedstock selection determines recyclability certification eligibility and exposure to ethylene price volatility.
- Polyethylene:Linear low-density and high-density grades dominate shrink film and pouch applications. Crude-linked resin costs swing converter margins unpredictably, squeezing mid-tier producers without long-term offtake agreements. Mechanical recycling infrastructure in Southern Europe constrains actual circularity rates.
- Polypropylene:Cast and oriented films serve retort and high-temperature applications. Bio-based polypropylene with ISCC PLUS certification is capturing niche volume in premium organic food segments.
- Polyester:Biaxially oriented polyethylene terephthalate provides clarity and printability for label and lidding applications.
- Bio-based Plastics:PLA and certified compostable resins serve brand owners seeking differentiation through EU Packaging and Packaging Waste Regulation alignment.
Polyethylene retains installed capacity dominance. Polypropylene is gaining share fastest through mono-material recyclability positioning.
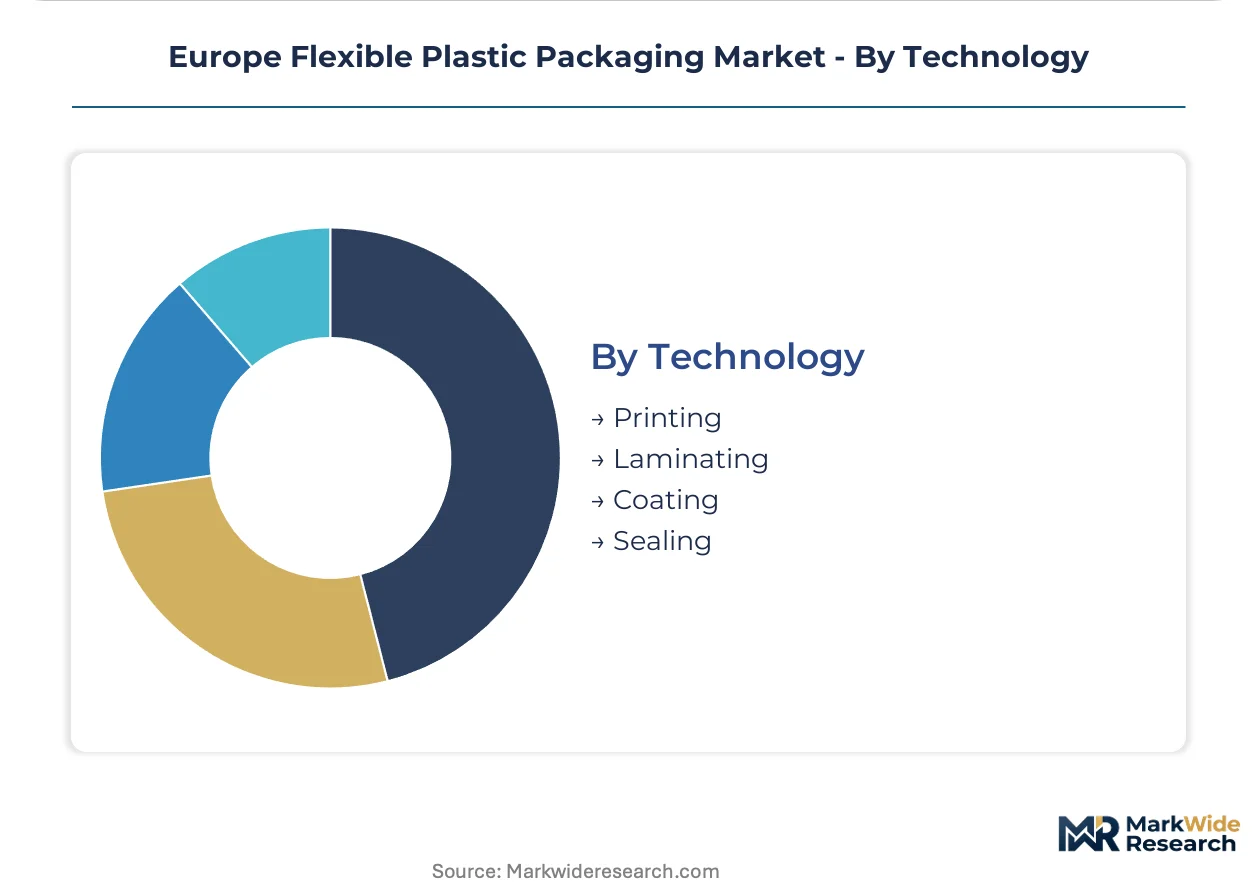
Technology:
Process selection shapes minimum order economics and barrier performance capabilities.
- Printing:Digital inkjet systems modularize short-run production for private-label sauces and regional snack brands. Mid-sized Spanish and Polish converters deploy single-pass UV-LED configurations to capture seasonal volumes.
- Laminating:Solvent-free and water-based adhesive systems are displacing solvent-borne alternatives under ECHA substance restrictions.
- Coating:Barrier coatings face 12-18 month EFSA safety evaluation timelines.
- Sealing:Heat-seal layer engineering determines line speed and package integrity.
Printing technology anchors customization economics. Laminating processes are restructuring around REACH compliance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing flexible packaging capacity across Europe as producers seek jurisdictions with favorable EPR fee structures and established mechanical recycling infrastructure. The EU Packaging and Packaging Waste Regulation's modulated fee schedules create compliance-cost gaps between member states with advanced circularity systems and those still building sorting capacity.
Germany
Dual Systems Deutschland's EPR fee differentials reward lightweight flexible formats over rigid alternatives, accelerating pouch adoption in Berlin-Brandenburg ready-to-eat meal processing clusters. REACH substance restrictions force chemical reformulation investments in barrier coatings. Bavarian converter networks around Munich are retooling multi-layer assets for mono-material extrusion to secure recyclability certification.
France
ANSM pharmaceutical packaging standards drive demand for high-barrier blister films in Île-de-France healthcare manufacturing corridors. Extended producer responsibility modulations under the EU Packaging and Packaging Waste Regulation favor certified recyclable structures. Lyon-based film specialists are expanding capacity to capture premium positioning in regulated medical device channels.
Italy
Emilia-Romagna food processors are displacing rigid containers with retort-compatible pouches for pasta sauce and olive oil applications. EFSA food contact compliance timelines for novel barrier coatings extend qualification cycles. Milan-Turin industrial clusters concentrate pharmaceutical-grade film production for export to French and German healthcare markets.
Spain
Catalonian mid-sized converters deploy digital inkjet systems to capture seasonal promotional volumes from private-label sauce brands. Mechanical recycling infrastructure gaps in Southern Europe limit actual circularity rates regardless of packaging design compliance. Barcelona-area sustainability teams at pan-European retailers are imposing uniform recyclability specifications on supplier bases.
Poland
Warsaw-Kraków converter networks adopt single-pass UV-LED printing configurations to serve regional snack brand short-run requirements. Lower EPR fee structures attract capacity migration from Western European jurisdictions with stricter modulated schedules. Polish extrusion lines are qualifying for recyclability certification to supply German retail private-label programs.
Europe Flexible Plastic Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based certification and digital-printing service models to bypass legacy asset constraints. The vendor base stratifies across integrated film-to-pouch networks, specialty converters with pharmaceutical-grade barrier expertise, and regional mid-tier players competing on short-run flexibility. Three archetypes dominate: pan-European scale operators with retailer-direct relationships, healthcare-focused specialists commanding EMA-compliant premium positioning, and technology-led challengers modularizing production economics through digital infrastructure. Consolidation pressure and mono-material line reconfiguration are the dominant competitive vectors reshaping capacity ownership.
Among integrated packaging networks, Amcor anchors the scale-driven tier through its film-to-pouch infrastructure securing long-term supply contracts with pan-European retailers. Mondi represents the sustainability-transition archetype through kraft-paper hybrid innovations reducing plastic dependency in food service applications. Constantia Flexibles exemplifies the regulated-channel specialist position, occupying premium positioning in pharmaceutical-grade barrier films where EFSA and EMA compliance create certification barriers to entry.
| Leading Market Players |
|---|
| Amcor |
| Mondi |
| Sealed Air |
| Constantia Flexibles |
| Berry Global |
| Huhtamäki |
| Sonoco Products |
| Coveris |
| DS Smith |
| Others |
Pricing and Supply Chain Analysis
Retailer consolidation across Germany, France, and the Benelux is compressing procurement authority into fewer sustainability desks, forcing converters to absorb reformulation costs for mono-material compliance while competing for long-term supply contracts with pan-European retail networks.
Pricing Analysis
Distributor margins in pharmaceutical-grade barrier films run 15-20 points above commodity pouch structures due to EMA certification requirements and extended qualification timelines. Three-tier pricing structure across premium certified-recyclable, standard compliant-grade, and economy non-certified levels separates Amcor and Constantia Flexibles from mid-tier Polish and Spanish converters. Cost compression in standard-grade polyethylene films is intensifying because ethylene feedstock volatility squeezes converters without long-term resin offtake agreements. Private-label buyers at Ahold Delhaize and Rewe exhibit highest price sensitivity, while pharmaceutical OEMs in Lyon and Milan accept premiums for EFSA-compliant barrier coatings.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from German ready-to-eat meal processors and French pharmaceutical manufacturers, bypassing distributor markups for volumes above threshold commitments. Raw material supply concentrates in Belgium, the Netherlands, and Germany for polyethylene resin, with biaxially oriented film production clustering in Bavaria and northern Italy. Converter networks draw from crude-linked ethylene feedstocks, specialized barrier coating chemicals, and ISCC PLUS certified bio-based polypropylene. Single-source vulnerability in aluminum-oxide metallized film supply from Austrian and German specialists creates chokepoint exposure for ultra-high-barrier pharmaceutical applications. Distribution runs through pan-European logistics hubs in Rotterdam and Antwerp, with secondary routing to southern European markets facing sorting infrastructure gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation's 2030 recyclability mandates are compounding demand for certified mono-material structures, creating structural advantage for converters with early-mover extrusion investments.
For Market Incumbents: Deploy mono-material line reconfiguration as the primary defensive lever. Amcor and Mondi should accelerate Bavarian and Polish extrusion capacity additions to capture retailer delisting timelines ahead of enforcement deadlines. Certification investment in EFSA-compliant barrier coatings protects pharmaceutical positioning against emerging bio-based film specialists. Channel control through direct retailer sustainability team relationships limits margin erosion from procurement concentration. For New Entrants and Emerging Players: Capture white space in ISCC PLUS certified bio-based polypropylene for premium organic food segments where brand owners seek compostable differentiation. Target mid-sized French and Italian pharmaceutical converters lacking in-house barrier coating capabilities. Underpenetrated digital printing services for seasonal promotional runs in Spain and Poland offer lowest competitive density. Go-to-market angle should emphasize batch-size-one production economics through single-pass UV-LED infrastructure without legacy rotogravure overhead. For Investors and Strategic Acquirers: Asymmetric upside sits with healthcare-focused specialists commanding EMA-compliant premium positioning in regulated channels. Long-term viability favors converters with integrated film-to-pouch networks and established retailer-direct relationships over asset-light trading houses. Acquisition target archetype: mid-tier Italian or French pharmaceutical film specialists with certified capacity and pending EFSA approvals. Signal to watch is German retailer delisting announcements for non-recyclable multi-layer formats, which will accelerate supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Extrusion Line Investment | Retooling multi-layer assets for recyclability certification unlocks Rewe and Carrefour supply contracts ahead of regulatory deadlines. |
| EFSA Barrier Coating Certification | Novel coating substance approvals extend pharmaceutical qualification cycles, creating moats against unapproved competitors. |
| Digital Printing Infrastructure Deployment | Single-pass UV-LED systems in Spain and Poland capture seasonal promotional volumes from private-label sauce brands. |
| ISCC PLUS Bio-Based Resin Sourcing | Certified polypropylene supply agreements enable premium positioning in organic food segments seeking compostable claims. |
| Retailer Sustainability Team Partnership | Direct relationships with Brussels-based category directors at Ahold Delhaize secure long-term specification influence. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged extrusion plant managers, sustainability procurement leads at pan-European retailers, pharmaceutical packaging engineers, and EFSA regulatory consultants. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation documents, ECHA substance restriction databases, Cefic plastics industry reports, and customs trade data for polyethylene and polypropylene resin flows. Bottom-up capacity modeling across German, French, Italian, Spanish, and Polish converter networks was triangulated against top-down demand estimates from food processor and pharmaceutical OEM procurement disclosures.
Historical reference periods anchored the projection horizon to pre-regulatory announcement baselines, capturing the inflection from multi-layer laminate dominance toward mono-material adoption. Segmentation dimensions modeled include product type, end-user industry, material grade, and technology platform across the analysis window. CAGRs were derived from capacity buildout timelines, retailer delisting schedules, and EFSA approval pipeline velocities. Industry-specific forecast inputs incorporated ethylene feedstock price correlation models and mechanical recycling infrastructure buildout assumptions for southern European markets.
Feedstock price volatility, EFSA evaluation timeline extensions, and mechanical recycling capacity shortfalls are the dominant revision risks to base-case projections. Forecasts reflect assumptions about regulatory enforcement consistency and retailer compliance pacing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Europe, Middle East and Africa (EMEA) Flexible Packaging Market
Flexible Packaging
Germany Flexible Plastic Packaging Market
Flexible Packaging
GCC Shrink Sleeves Market
Flexible Packaging
Egypt Flexible Plastic Packaging Market
Flexible Packaging
Flexible Packaging Paper Market
Flexible Packaging
Confectionery Flexible Packaging Market
Flexible Packaging
Flexible Intermediate Bulk Container Market
Flexible Packaging
APAC Flexible Packaging Market
Flexible Packaging
Indonesia Flexible Plastic Packaging Market
Flexible Packaging
Flexible Containers Market
Flexible Packaging
Flexible Film Market
Flexible Packaging
Nigeria Flexible Plastic Packaging Market
Flexible Packaging
France Flexible Plastic Packaging Market
Flexible Packaging
Global Flexible Plastic Packaging Market
Flexible Packaging
Canada Flexible Plastic Packaging Market
Flexible Packaging
Flexible Bottle Market