
 Foam Pouch Market | 2026-2036
Foam Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Pouch Market Foresight
North American foam sheet producers is shifting capacity toward pouch conversion to capture higher-margin protective packaging demand. Sealed Air Corporation leverages its Instapak technology heritage to dominate inflatable foam pouch systems. Pregis LLC anchors regional fulfillment center supply through direct-to-warehouse distribution networks. Ranpak competes with paper-based alternatives while extending into hybrid foam-paper protective formats for electronics shippers.
A foam pouch is a flexible protective enclosure fabricated from closed-cell or open-cell polymer foams, typically measuring 1/8 to 1/2 inch in thickness, engineered to absorb shock and prevent surface abrasion during transit. Polyethylene foam pouches lead volume due to their moisture resistance and cost efficiency in electronics protection applications. Polyurethane foam pouches occupy premium medical packaging segments where biocompatibility and sterilization compatibility command higher unit economics. Direct sales channels control the largest revenue share as medical device companies and electronics manufacturers negotiate multi-year supply agreements with specified performance thresholds.
EPA guidelines on volatile organic compound emissions from foam manufacturing shape material formulation decisions across US production facilities. REACH restrictions on isocyanates and blowing agents constrain polyurethane foam pouch formulations in Europe, while China's GB standards mandate recyclability labeling that influences export-oriented manufacturers. Stakeholders must monitor evolving extended producer responsibility frameworks that will determine which foam chemistries retain market access across major economies.
Market Dynamics
REACH compliance in Europe is compressing polyurethane foam formulations while e-commerce fulfillment velocity in China pulls polyethylene capacity toward pouch conversion. Material substitution pressure and regulatory fragmentation now determine which chemistries retain commercial viability across major economies.
Growth Catalysts
- E-commerce fulfillment velocity:Electronics manufacturers in China and the United States are standardizing foam pouch specifications for automated packing lines. Direct-to-consumer shipping volumes mandate shock absorption performance thresholds that rigid alternatives cannot meet.
- REACH material restrictions:European isocyanate constraints are accelerating bio-based polyurethane development. Reformulation investments by compounders create first-mover certification advantages for compliant pouch suppliers.
- Medical device sterilization demand:Biocompatible foam chemistries command premium positioning in surgical kit packaging. Gamma and ethylene oxide sterilization compatibility requirements exclude commodity polyethylene from this segment.
Market Restraints
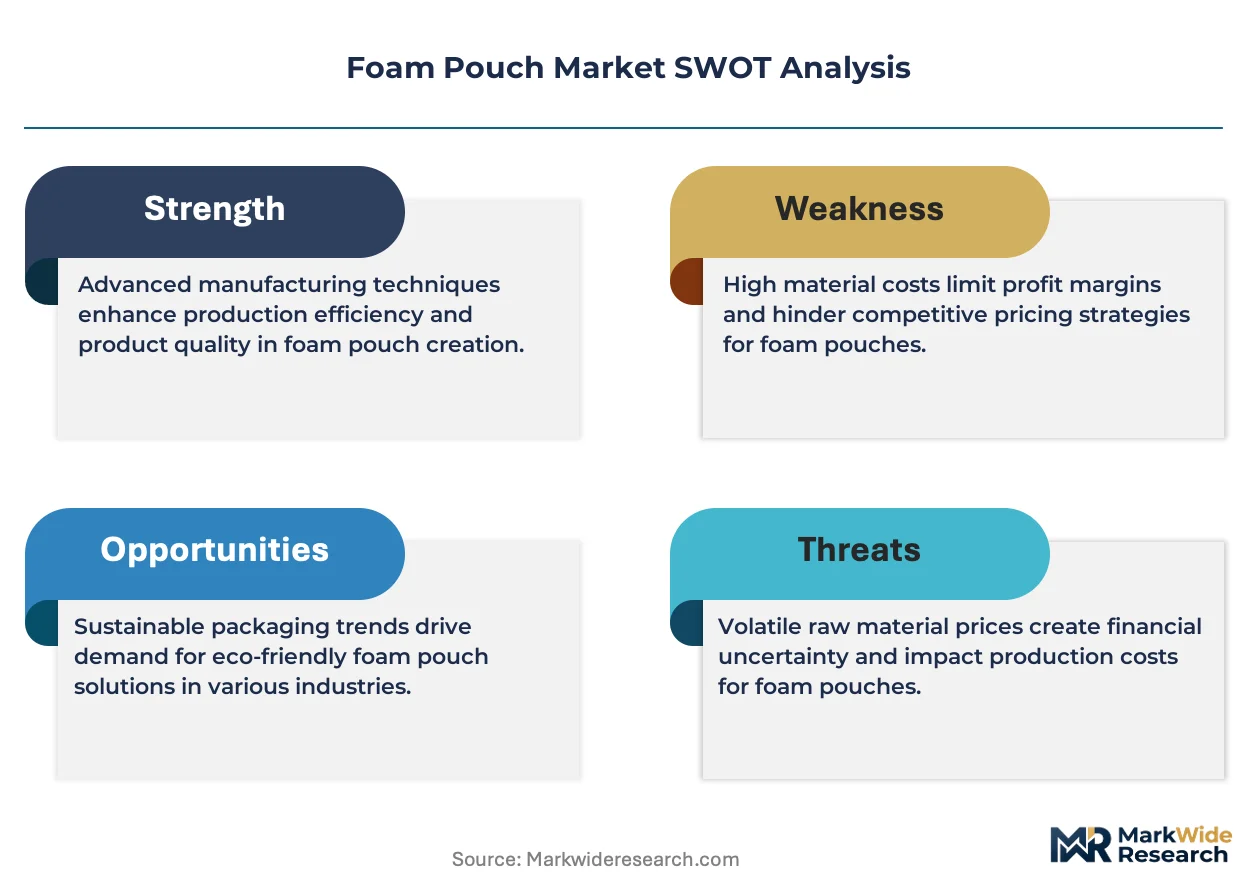
- Petrochemical input volatility:Ethylene and propylene feedstock price swings compress polyethylene foam margins. Integrated producers with captive monomer supply capture margin that merchant compounders cannot access.
- China supply concentration:Domestic foam sheet capacity expansion outpaces demand absorption, exporting price pressure to North American and European converters. Regional trade remedy investigations threaten supply chain reconfiguration costs.
- Paper-based substitution:Ranpak and corrugated molded pulp competitors capture sustainability-sensitive electronics shippers. Hybrid foam-paper formats fragment protective packaging procurement decisions.
Strategic Opportunities
- India domestic manufacturing:PLI scheme incentives for electronics assembly create localized foam pouch demand. Import substitution mandates favor domestic converters over Southeast Asian suppliers.
- Recyclability certification:EU Green Deal extended producer responsibility frameworks reward mono-material pouch designs. How2Recycle and OPRL labeling adoption differentiates suppliers in European retail channels.
- Active packaging convergence:Desiccant-integrated and anti-static foam laminates address moisture-sensitive semiconductor shipments. Multi-functional pouch architectures capture value from adjacent humidity control markets.
Industry Challenges
- Reformulation technical debt:Legacy polyurethane systems require complete process revalidation to meet REACH-compliant blowing agent transitions. Medical device customers demand 18-month stability documentation that delays new chemistry commercialization.
- Automation integration friction:Pouch dimension tolerances must tighten to ±2mm for robotic pick-and-place compatibility. Retrofitting existing converting lines demands capital outlays that mid-tier producers cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Pouch Market |
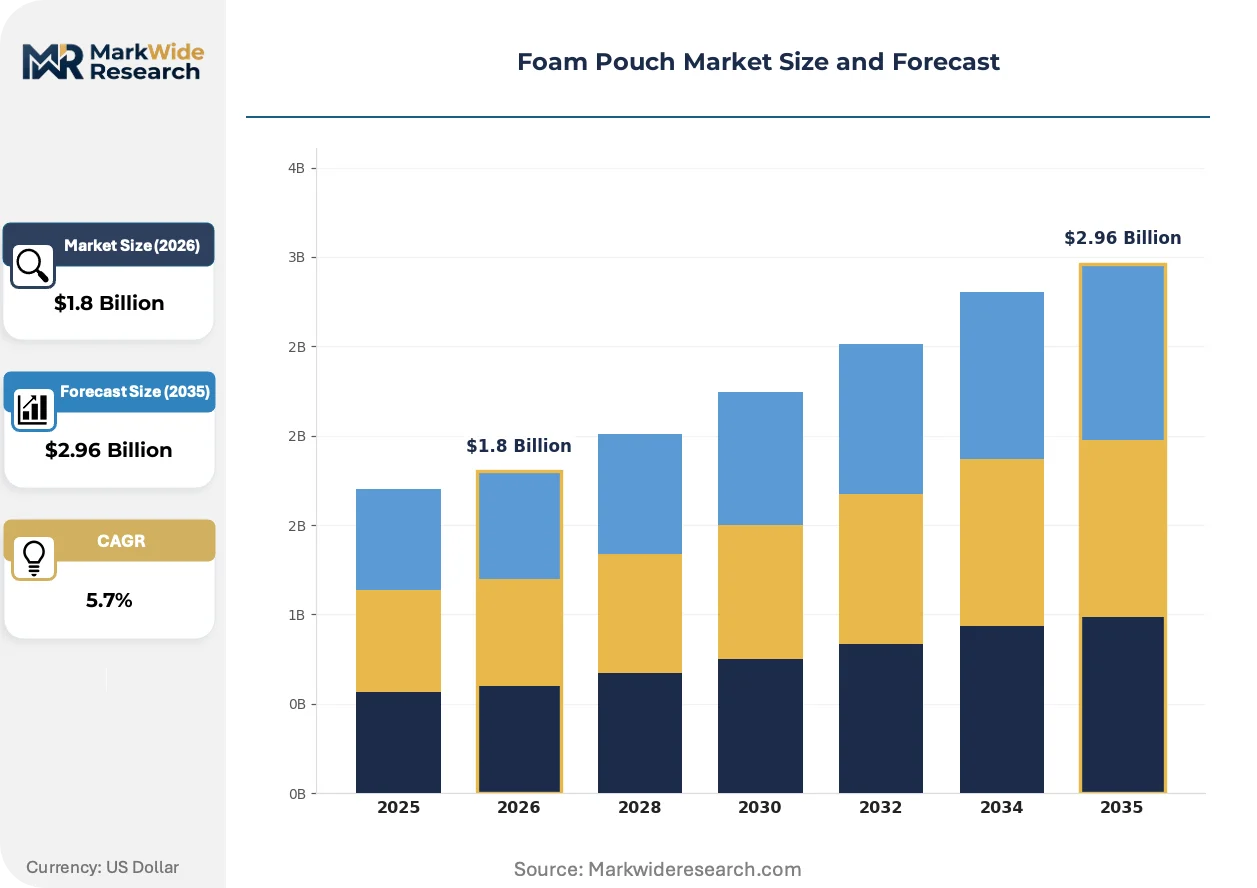
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Foam Pouches, Polyurethane Foam Pouches, Eva Foam Pouches, Neoprene Foam Pouches Application: Electronics Protection, Food Packaging, Medical Packaging, Cosmetic Packaging End User: Electronics Manufacturers, Food Processors, Medical Device Companies, Beauty Product Brands Distribution Channel: Direct Sales, E-commerce Platforms, Distributors, Wholesalers |
| Companies Covered | Sealed Air Corporation, Pregis LLC, 3A Manufacturing, Avery Dennison, Berry Global Inc., Smurfit Kappa Group Plc, International Plastics Inc., FP International, Ranpak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Pouch Market Shifts & Advancements
Material science advances and regulatory chemistry constraints are converging to reshape foam pouch specifications. Three developments are compressing legacy formulation advantages while creating openings for compliant alternatives.
Plant-derived polyethylene foam is absorbing capital from compounders seeking to decouple from fossil feedstock exposure. Major electronics assemblers in Germany and South Korea are piloting bio-based pouches for consumer device shipments. This chemistry is absorbing price premiums that petroleum-based alternatives cannot command in sustainability-audited supply chains.
EPA volatile organic compound emission guidelines are tightening blowing agent specifications for US foam manufacturing facilities. Facilities in Texas and Ohio are retrofitting extrusion lines to capture and recycle pentane emissions. Medical packaging producers face the steepest compliance costs, as their low-volume, high-SKU production profiles resist emission control equipment amortization.
Consolidated electronics manufacturers are unbundling protective packaging procurement from primary logistics contracts. Direct supply agreements with foam pouch converters now specify performance-based acceptance criteria rather than brand mandates. This pattern is most visible in Shenzhen and Chengdu, where contract manufacturers negotiate multi-year foam supply agreements independent of their 3PL relationships.
Foam Pouch Market Segmentation
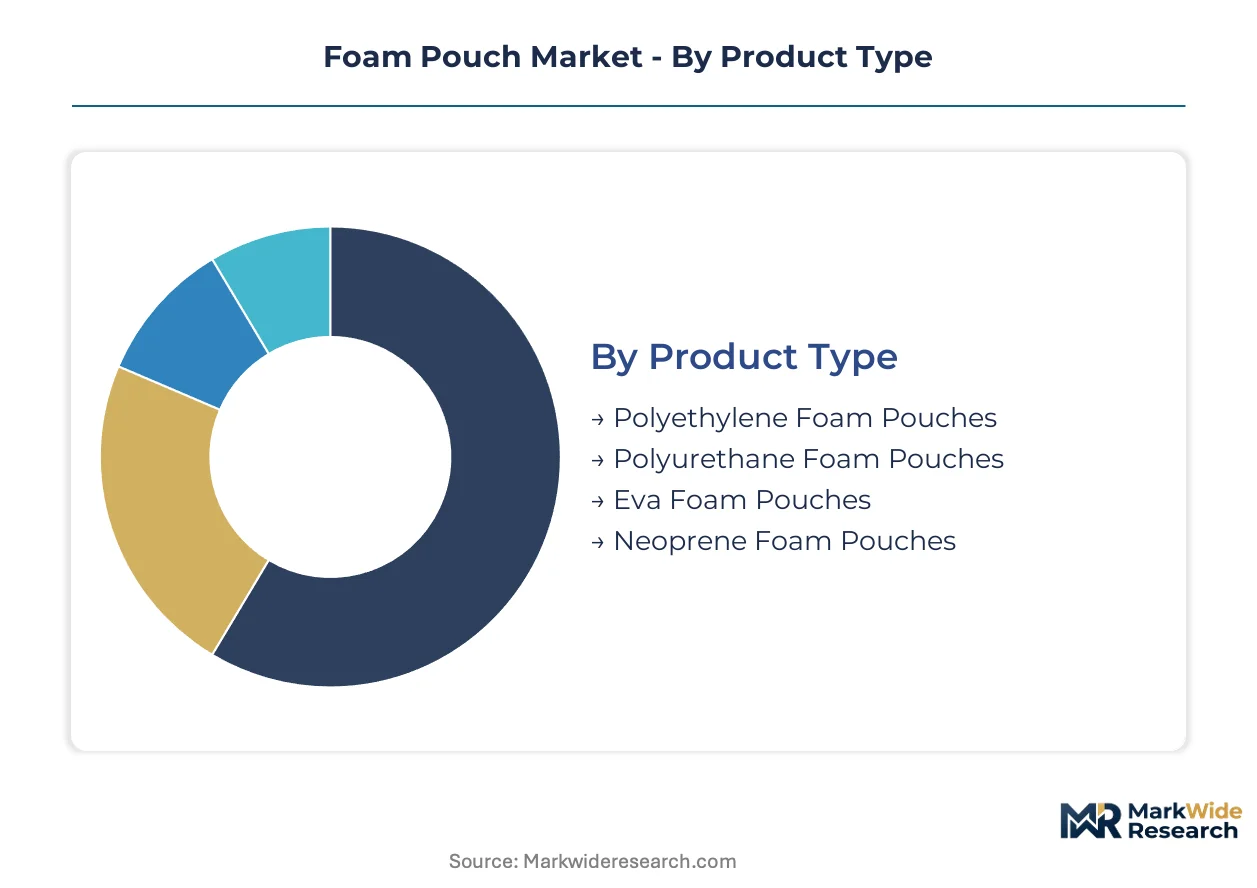
Foam pouch segmentation reveals divergent capital requirements across chemistries and channels. Polyurethane medical-grade lines demand sterile cleanroom investment, while polyethylene extrusion for electronics runs on commodity equipment. Understanding these investment thresholds explains why capacity concentrates among integrated compounders rather than merchant converters.
Product Type:
Capital intensity varies sharply by chemistry, with medical-grade polyurethane requiring 3-4x the upfront investment of commodity polyethylene extrusion lines.
- Polyethylene Foam Pouches:Extruded closed-cell structures dominate volume through moisture resistance and cost efficiency. Electronics manufacturers in China and the United States standardize these specifications for automated fulfillment lines where shock absorption thresholds exclude rigid alternatives.
- Polyurethane Foam Pouches:Open-cell formulations command premium positioning in surgical kit packaging. Gamma and ethylene oxide sterilization compatibility requirements under EU MDR exclude commodity alternatives from this segment.
- Eva Foam Pouches:Ethylene-vinyl acetate copolymers deliver enhanced elasticity for irregular-shaped cosmetic containers.
- Neoprene Foam Pouches:Chloroprene-based chemistry serves niche industrial applications requiring chemical resistance and thermal stability.
Most installed capacity flows through polyethylene foam pouch production. Expansion is steepest in polyurethane formulations as REACH-compliant bio-based alternatives capture medical certification.
Application:
Application segmentation tracks divergent performance specifications, with medical sterilization demands imposing the tightest material constraints.
- Electronics Protection:Anti-static and shock-absorbing specifications dominate procurement from semiconductor and consumer device manufacturers. E-commerce fulfillment velocity in China and the United States mandates performance thresholds that paper-based alternatives cannot meet.
- Medical Packaging:Biocompatibility, sterilization compatibility, and stability documentation requirements create formulation barriers. FDA and EMA device regulations enforce 18-month stability validation that delays new chemistry commercialization.
- Food Packaging:FDA and EFSA compliance for indirect food contact limits acceptable foam chemistries.
- Cosmetic Packaging:Premium unboxing experiences drive demand for soft-touch surface finishes in luxury beauty segments.
Electronics protection absorbs the largest volume share. Medical packaging climbs fastest as surgical kit standardization expands foam pouch adoption.
End User:
End user concentration determines contract structure, with medical device companies negotiating multi-year supply agreements that electronics manufacturers rarely match.
- Electronics Manufacturers:Contract manufacturers in Shenzhen and Chengdu unbundle protective packaging from 3PL relationships to negotiate direct foam supply agreements with performance-based acceptance criteria.
- Medical Device Companies:Surgical kit assemblers demand lot traceability and sterilization validation that commodity converters cannot supply. EU MDR and FDA quality system regulations enforce supplier qualification protocols.
- Food Processors:Temperature-controlled supply chain requirements limit foam pouch adoption to premium chilled categories.
- Beauty Product Brands:Sustainability-audited supply chains in Germany and South Korea pilot bio-based alternatives for premium positioning.
Electronics manufacturers represent the largest addressable base. Medical device companies deliver the highest contract value per customer.
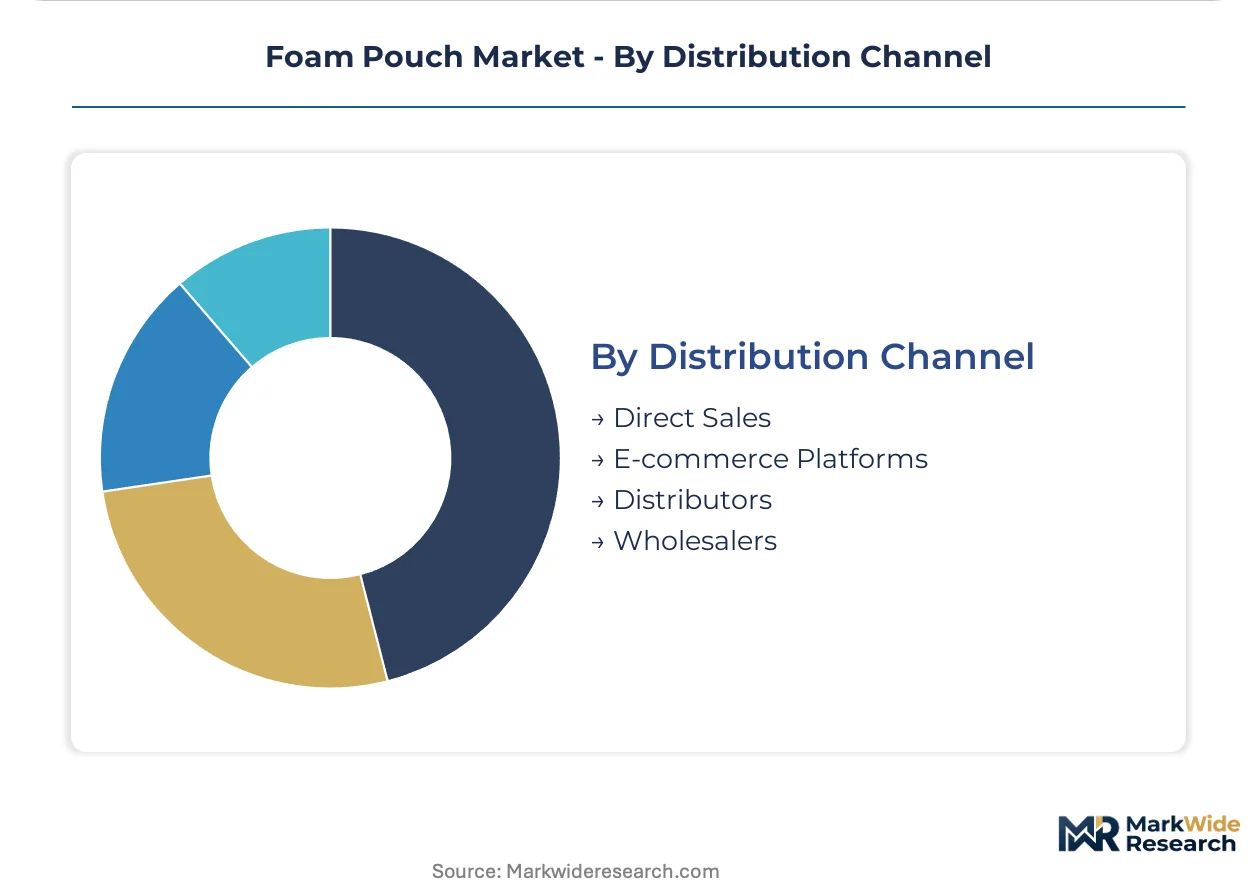
Distribution Channel:
Channel segmentation reflects customer scale and specification complexity, with direct sales capturing the most technically demanding accounts.
- Direct Sales:Multi-year supply agreements with specified performance thresholds dominate medical and electronics procurement. Sealed Air and Pregis anchor regional fulfillment center supply through direct-to-warehouse distribution networks.
- Distributors:Regional converters serve mid-tier food and cosmetic processors through inventory-managed relationships.
- E-commerce Platforms:Alibaba and Amazon Business channels capture spot demand from small-batch cosmetic and specialty food producers.
- Wholesalers:Commodity polyethylene pouches flow through packaging wholesalers to fragmented industrial end users.
Direct sales channels control the largest revenue share. E-commerce platforms gain traction fastest among small-batch cosmetic and specialty food entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting foam pouch production toward jurisdictions with lower compliance costs, while REACH restrictions in Europe and EPA guidelines in the United States compress margins for legacy polyurethane formulations. Manufacturers are relocating capacity to exploit these cost-of-compliance gaps.
United States
Electronics fulfillment centers in Texas and Ohio drive polyethylene pouch demand for automated packing lines. EPA volatile organic compound emission guidelines force extrusion line retrofits to capture pentane emissions. Dallas-Fort Worth logistics corridors concentrate pouch distribution networks serving e-commerce shippers.
China
Domestic packaging consumption outpaces other manufacturing economies as contract manufacturers in Shenzhen and Chengdu unbundle protective packaging from 3PL relationships. GB standards mandate recyclability labeling that shapes export-oriented manufacturer decisions. Yangtze River Delta electronics clusters absorb the largest regional foam pouch volumes.
Germany
Medical device sterilization demand pulls REACH-compliant bio-based polyurethane development. EMA device regulations and EU MDR enforce 18-month stability validation for new chemistries. Stuttgart and Munich surgical kit assemblers negotiate multi-year supply agreements with specified performance thresholds.
India
PLI scheme incentives for electronics assembly create localized foam pouch demand as import substitution mandates favor domestic converters. BIS standards influence material specifications for food contact applications. Maharashtra and Gujarat industrial corridors attract capacity expansion from Southeast Asian suppliers.
South Korea
Semiconductor manufacturers pilot anti-static foam laminates for moisture-sensitive chip shipments. MFDS regulations govern medical packaging materials while consumer electronics assemblers test bio-based alternatives. Seoul Capital Area and Busan-Ulsan production clusters anchor regional supply.
Foam Pouch Market Competitive Landscape
United States producers anchor one tier; European and Asian specialists hold differentiated positions in medical-grade and electronics-focused segments. Market structure concentrates among integrated compounders with captive monomer supply, while mid-tier merchant converters face margin compression from feedstock volatility. Three archetypes dominate: diversified packaging conglomerates with fulfillment center networks, medical-grade polyurethane specialists with cleanroom certification, and regional extrusion houses serving commodity electronics protection. Capacity expansion and backward integration into monomer production represent the dominant competitive moves as producers defend margin position.
Within the diversified packaging tier, Sealed Air Corporation and Pregis LLC exemplify scale-driven fulfillment center anchoring. Among material science specialists, 3A Manufacturing occupies a position representing medical-grade certification capabilities. Ranpak sits within the sustainability-focused archetype as paper-based alternatives fragment procurement decisions for electronics shippers. These three company anchors illustrate how competitive positioning diverges across chemistry, certification, and channel access dimensions.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Pregis LLC |
| 3A Manufacturing |
| Avery Dennison |
| Berry Global Inc. |
| Smurfit Kappa Group Plc |
| International Plastics Inc. |
| FP International |
| Ranpak |
| Others |
Supply & Pricing Matrix
EU Green Deal extended producer responsibility frameworks gate qualified supply access and premium-tier pricing power for mono-material pouch designs that carry How2Recycle and OPRL certification. REACH-compliant bio-based polyurethane formulations command price premiums that legacy chemistries cannot access in sustainability-audited European retail channels.
Pricing Analysis
Direct-to-warehouse distribution discounts anchor contract-based long-term offtake structures for electronics fulfillment centers negotiating multi-year supply agreements. Certification grade under EU MDR and volume scale separate premium medical-grade polyurethane from standard polyethylene electronics protection, with economy tiers exposed to commodity spot volatility. Pricing pressure stems from ethylene and propylene feedstock swings that compress merchant compounder margins against integrated producers with captive monomer supply. Mid-tier food and cosmetic processors through distributors exhibit highest price sensitivity, while surgical kit assemblers demonstrate lowest sensitivity due to sterilization validation requirements.
Supply Chain Analysis
Workforce availability constraints in Texas and Ohio extrusion corridors limit pentane emission retrofit velocity for EPA-compliant foam manufacturing facilities. Supply concentrates in China, the United States, and Germany, with Yangtze River Delta electronics clusters and Dallas-Fort Worth logistics corridors anchoring regional distribution. Raw material dependencies center on ethylene and propylene monomers, isocyanate formulations, and blowing agents constrained by REACH restrictions. Single-source vulnerability in Chinese foam sheet capacity expansion exports price pressure to North American and European converters. Distribution runs through direct-to-warehouse networks for large electronics manufacturers and regional distributors for fragmented industrial end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foam pouch demand functions as a stable compounder anchored by e-commerce fulfillment velocity that standardizes protective packaging specifications across automated packing lines.
For Market Incumbents: Deploy backward integration into captive monomer production to defend margin position against feedstock volatility that compresses merchant compounder returns. Sealed Air and Pregis should deepen cleanroom certification investment for medical-grade polyurethane lines as EU MDR enforcement tightens supplier qualification protocols. Capacity addition in India leverages PLI scheme incentives while insulating against China supply concentration risks from trade remedy investigations. For New Entrants and Emerging Players: Capture India's domestic electronics assembly demand where import substitution mandates favor local converters over established Southeast Asian suppliers. White-space exists in REACH-compliant bio-based polyurethane development for German and South Korean sustainability-audited supply chains. Ranpak's paper-based substitution threat creates openings for hybrid foam-paper format specialists serving electronics shippers with mixed-material procurement preferences. For Investors and Strategic Acquirers: Roll-up economics work for regional extrusion houses with established electronics fulfillment center relationships because contract manufacturers in Shenzhen and Chengdu are unbundling protective packaging from 3PL agreements. Medical-grade polyurethane specialists with EMA sterilization validation offer longest-dated viability given 18-month stability documentation barriers that delay new chemistry commercialization. Watch for EPA emission guideline enforcement acceleration as the inflection signal that forces mid-tier producer consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Integrated producers with captive ethylene supply capture margin compression that merchant compounders cannot access. |
| REACH-Compliant Bio-Based Formulation Development | First-mover certification advantages for European medical packaging create pricing power in sterilization-compatible segments. |
| Direct-to-Warehouse Distribution Expansion | Pregis and Sealed Air anchor regional fulfillment center supply through performance-based multi-year agreements. |
| India Capacity Buildout | PLI scheme incentives for electronics assembly localize demand and satisfy import substitution mandates. |
| Hybrid Foam-Paper Format Introduction | Ranpak competes with paper-based alternatives while capturing sustainability-sensitive electronics shipper procurement. |
Research Methodology
Multiple input streams — primary interviews with foam compounder technical directors, electronics manufacturer procurement leads, and medical device packaging engineers; secondary validation through ECHA REACH substance databases, EPA emission guideline filings, and customs trade flow records — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against expert panel input across chemistry type, application segment, end-user concentration, and distribution channel dimensions. CAGRs were derived from segmented demand modeling incorporating e-commerce fulfillment velocity indices, sterilization compatibility certification timelines, and regional regulatory enforcement intensity throughout the forecast period.
Feedstock price volatility, REACH substance restriction expansion, and automation integration capital requirements are the dominant revision risks to projection assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Global Pouches Packaging Market
Pouch
Aluminium Bags and Pouches Market
Pouch
Wrap-Around Packers Market
Pouch
Dual-Chamber Pouches Market
Pouch
Horizontal Premade Pouch Packing Machine Market
Pouch
Zipper Pouch Market
Pouch
Vietnam Pouch Packaging Market
Pouch
Thailand Pouch Packaging Market
Pouch
Open Mouth Sacks Market
Pouch
Inverted Pouch Market
Pouch
Stand-Up Pouches Market
Pouch
Pillow Pouch Packaging Market
Pouch
North America Stand-Up Pouch Packaging Market
Pouch
Vacuum Chamber Pouches Market
Pouch
Bio PE Pouches Market
Pouch
Digital Printed Pouch Market