
 France Pouch Packaging Market | 2026-2036
France Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
France Pouch Packaging Market Insights
Aftermarket recycling infrastructure revenue is reconfiguring value capture across the France pouch packaging value chain. Amcor PLC leverages its European flexible film network to supply mono-material polyethylene pouches compliant with emerging French sorting requirements. Mondi PLC anchors its position through integrated kraft paper and barrier film operations serving Paris-area food exporters. Constantia Flexibles GmbH specializes in pharmaceutical-grade pouches with aluminum barrier layers for the Lyon life sciences corridor.
France pouch packaging denotes flexible containers formed from laminated films or single-substrate webs, typically sealed on three or four sides with optional fitments, spouts, or zip-lock closures, engineered to protect contents from moisture, oxygen, and mechanical damage during distribution and shelf life. Stand-up pouches occupy the largest volume share due to their retail shelf visibility and pallet efficiency, while spouted pouches represent the fastest-growing product type as French baby food and beverage brands replace rigid bottles. Plastic laminates still dominate material tonnage, though compostable films are gaining structural attention as French retailers impose private-label sustainability specifications ahead of regulatory deadlines.
ANSM enforces pharmaceutical packaging integrity standards that dictate barrier performance and child-resistance testing for drug-containing pouches distributed in France. The EU Green Deal and France's national anti-waste law (AGEC) are accelerating demand for recyclable mono-material structures by penalizing complex multi-layer films in extended producer responsibility schemes. Stakeholders must monitor how rapidly French sorting facilities upgrade near-infrared detection capabilities, as this infrastructure investment timeline will determine which material platforms achieve circular economy certification and preferential shelf placement.
Market Dynamics
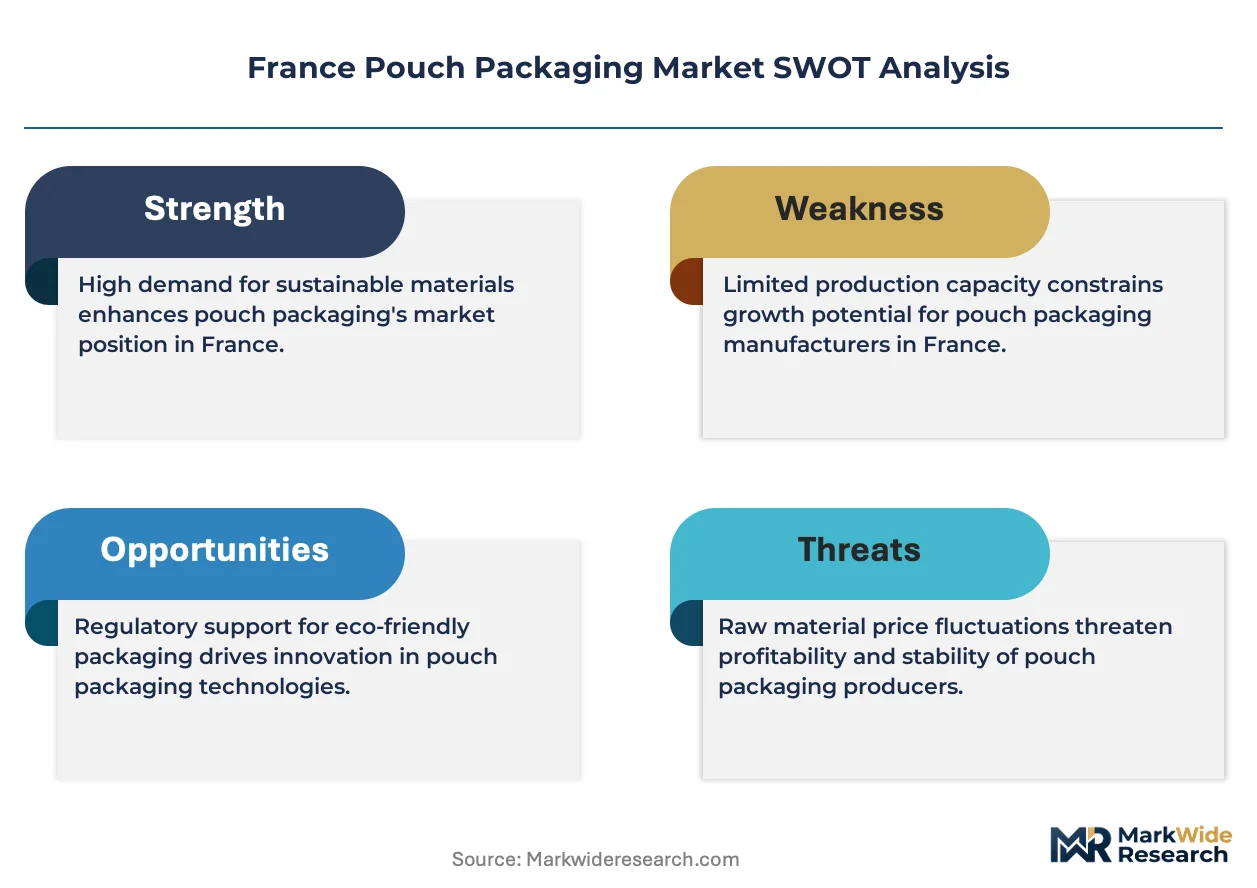
The France pouch packaging market is pivoting around regulatory-driven material substitution, as the EU Packaging and Packaging Waste Regulation (PPWR) forces converters to abandon multi-layer laminates in favor of detectable mono-material structures compatible with existing French sorting infrastructure.
Growth Catalysts
- AGEC Law Enforcement:France's national anti-waste law penalizes non-recyclable packaging through extended producer responsibility fees, pushing food brands toward certified mono-material polyethylene pouches.
- Ready-to-Eal Meal Proliferation:French food processors are adopting retort pouches for ambient-stable prepared dishes, eliminating refrigerated supply chain costs.
- Near-Infrared Detection Upgrades:Sorting facilities in Île-de-France are installing advanced optical sorters capable of identifying mono-material streams, validating circular economy claims.
Market Restraints
- Aluminum Barrier Dependency:Pharmaceutical pouches for the Lyon life sciences corridor require aluminum oxide layers that complicate mechanical recycling streams.
- Compostable Film Cost Premium:Polylactic acid and cellulose-based substrates trade at multiples above conventional polyethylene, constraining adoption in private-label retail.
- Converter Consolidation:European flexible packaging supply concentrates among integrated film producers, limiting bargaining power for mid-size French brand owners.
Strategic Opportunities
- Spouted Pouch Conversion:Baby food and beverage brands in Brittany and Normandy are replacing rigid bottles with flexible spouted formats, opening equipment and substrate supply contracts.
- Pharmaceutical Cold-Chain Expansion:ANSM guidelines for temperature-sensitive biologics create demand for insulated pouch configurations with phase-change materials.
- Retail Private-Label Specifications:Carrefour and E.Leclerc sustainability mandates ahead of 2030 PPWR deadlines favor early-mover converters with certified recyclable platforms.
Industry Challenges
- Barrier Performance Trade-offs:Mono-material polyethylene structures struggle to match the oxygen transmission rates of legacy nylon-aluminum laminates for premium sauce applications.
- Sorting Infrastructure Asynchrony:French regional waste management authorities operate divergent detection capabilities, creating patchwork certification requirements that fragment national scale economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Pouch Packaging Market |
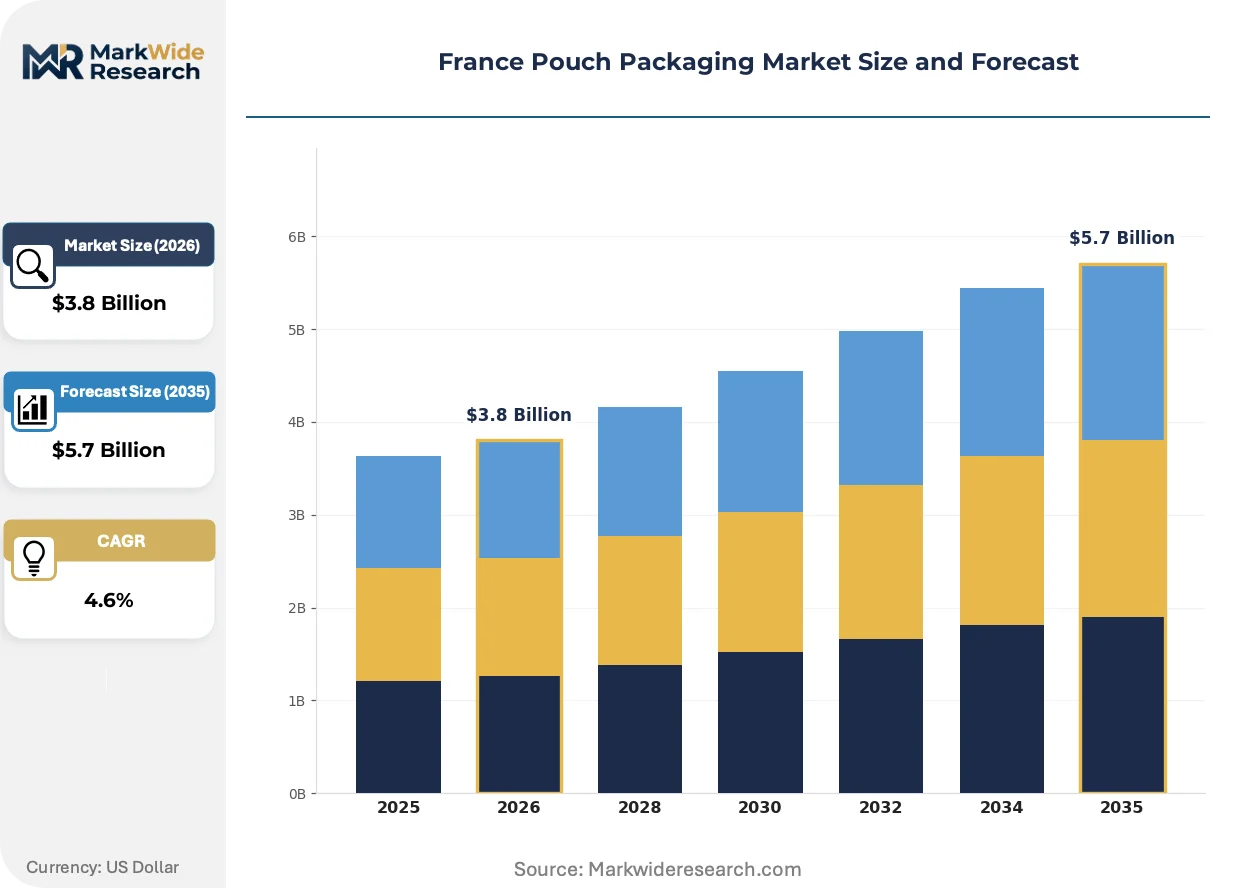
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Gusseted Pouches, Spouted Pouches Material: Plastic, Paper, Aluminum, Compostable Films End User: Food & Beverages, Personal Care, Pharmaceuticals, Home Care Packaging Feature: Reclosable, Child-Resistant, Moisture-Resistant, Leak-Resistant |
| Companies Covered | Amcor PLC, Mondi PLC, Sonoco Products Company, Constantia Flexibles GmbH, DELTASACS, Coveris Management GmbH, BERNHARDT Packaging & Process, Huhtamaki Oyj, Sudpack, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Pouch Packaging Market Trends and Innovations
Digital printing and smart packaging integration are compressing batch economics and traceability costs for French converters, while regulatory deadlines force simultaneous material reinvention.
Digital inkjet printing is virtualizing pre-press and plate-making steps for short-run pouches. Regional sauce and condiment brands in Provence-Alpes-Côte d'Azur are adopting this technology for seasonal and limited-edition SKUs. The elimination of cylinder inventory is virtualizing minimum order quantities and collapsing lead times from weeks to days.
The EU Green Deal's packaging recyclability mandates are restructuring material specifications across French supply chains. PPWR thresholds for recyclability by design are disqualifying conventional multi-layer films from extended producer responsibility bonus schemes. Pharmaceutical and food exporters in the Paris basin are accelerating qualification of mono-material alternatives to maintain preferential shelf placement.
Brand owners are consolidating supplier relationships around converters with integrated recycling partnerships. Procurement teams at major French retailers are demanding mass-balance certifications and post-consumer recycled content guarantees as standard contract terms. This concentration is most visible in Île-de-France, where logistics proximity to sorting and reprocessing hubs enables closed-loop pilot programs with quantitative sustainability reporting.
France Pouch Packaging Market Segmentation
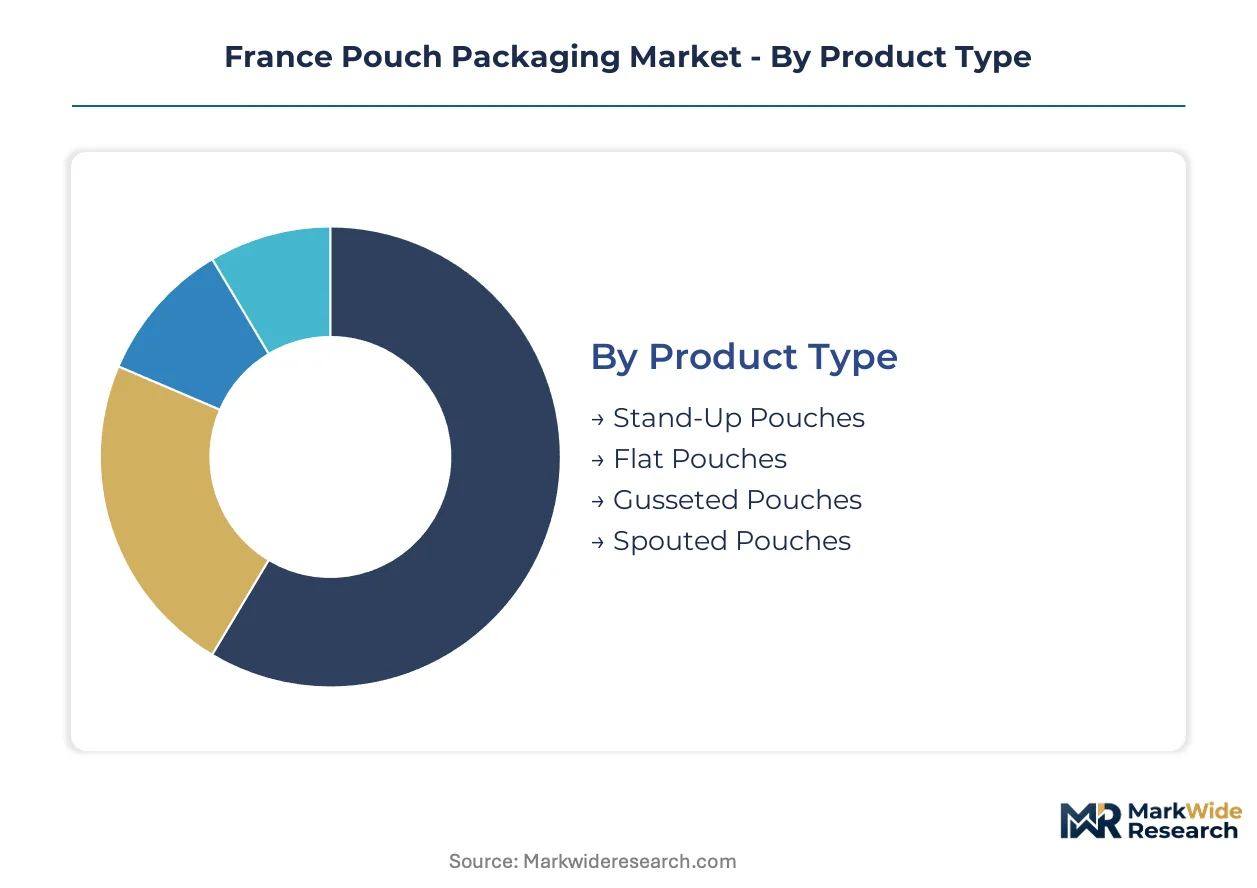
Segmentation in the France pouch packaging market reveals how regulatory pressure and end-use specialization are fragmenting demand across incompatible material platforms. Each dimension exposes distinct investment requirements and margin structures that converters must navigate simultaneously.
Product Type:
Volume concentration varies sharply by shelf presence and handling ergonomics across French retail formats.
- Stand-Up Pouches:Self-supporting bottom gusset construction enables vertical retail display without secondary corrugate. French hypermarkets in Île-de-France prioritize this format for premium sauces and ambient-ready meals where shelf visibility drives velocity. Pallet cube efficiency and reduced shipping weight versus rigid alternatives reinforce adoption among Paris-based exporters.
- Spouted Pouches:Integrated fitment systems replace rigid bottles for controlled dispensing. Brittany baby food processors and Normandy beverage brands are converting filling lines to capture material cost savings and e-commerce shipping advantages. ANSM child-resistance specifications for pharmaceutical applications add compliance complexity but open higher-margin contract opportunities.
- Flat Pouches:Three-side-seal construction dominates single-serve condiment and sample sachet production for French hospitality distributors.
- Gusseted Pouches:Side-fold expansion accommodates bulk dry goods for Provence-Alpes-Côte d'Azur specialty food cooperatives.
Stand-Up Pouches holds installed capacity. Spouted Pouches is rotating up the share rankings.
Material:
Application temperature and barrier requirements dictate substrate selection, with recyclability certification now a gatekeeping criterion.
- Plastic:Multi-layer polyethylene and polypropylene laminates deliver moisture and oxygen barriers at unit economics that private-label retail demands. The AGEC law's extended producer responsibility penalties are forcing rapid migration to mono-material polyethylene structures detectable by Île-de-France optical sorters.
- Compostable Films:Polylactic acid and cellulose-based substrates address Carrefour and E.Leclerc sustainability specifications ahead of regulatory deadlines. Industrial composting infrastructure gaps in rural French regions constrain geographic rollout despite brand owner interest.
- Paper:Kraft-paper-barrier-film laminations serve Paris-area organic food exporters targeting German and Benelux markets with fiber-preferred packaging mandates.
- Aluminum:Metallized and foil-laminate structures maintain pharmaceutical integrity for Lyon life sciences corridor biologics requiring complete light and oxygen exclusion.
Plastic dominates current throughput. Compostable Films is climbing the fastest as retail procurement specifications harden.
End User:
Customer type determines regulatory exposure, batch size economics, and barrier performance thresholds.
- Food & Beverages:Retort-stable pouches for ambient-ready meals and premium sauces absorb the largest material tonnage. French processors are eliminating refrigerated supply chain costs through aseptic filling and high-barrier laminates that match shelf life expectations of traditional canning.
- Pharmaceuticals:ANSM-enforced child-resistance and tamper-evidence standards govern pouch design for over-the-counter and prescription drug distribution. The Lyon pharmaceutical cluster generates specialized demand for aluminum-oxide barrier layers and cold-chain phase-change configurations.
- Personal Care:Sample sachets and travel-size pouches for French cosmetics brands prioritize print quality and tear propagation control over extended shelf barriers.
- Home Care:Concentrate and refill pouches for cleaning products emphasize chemical resistance and spout durability through repeated dispensing cycles.
Food & Beverages commands the deepest converter relationships. Pharmaceuticals is gaining share fastest on regulatory barrier requirements.
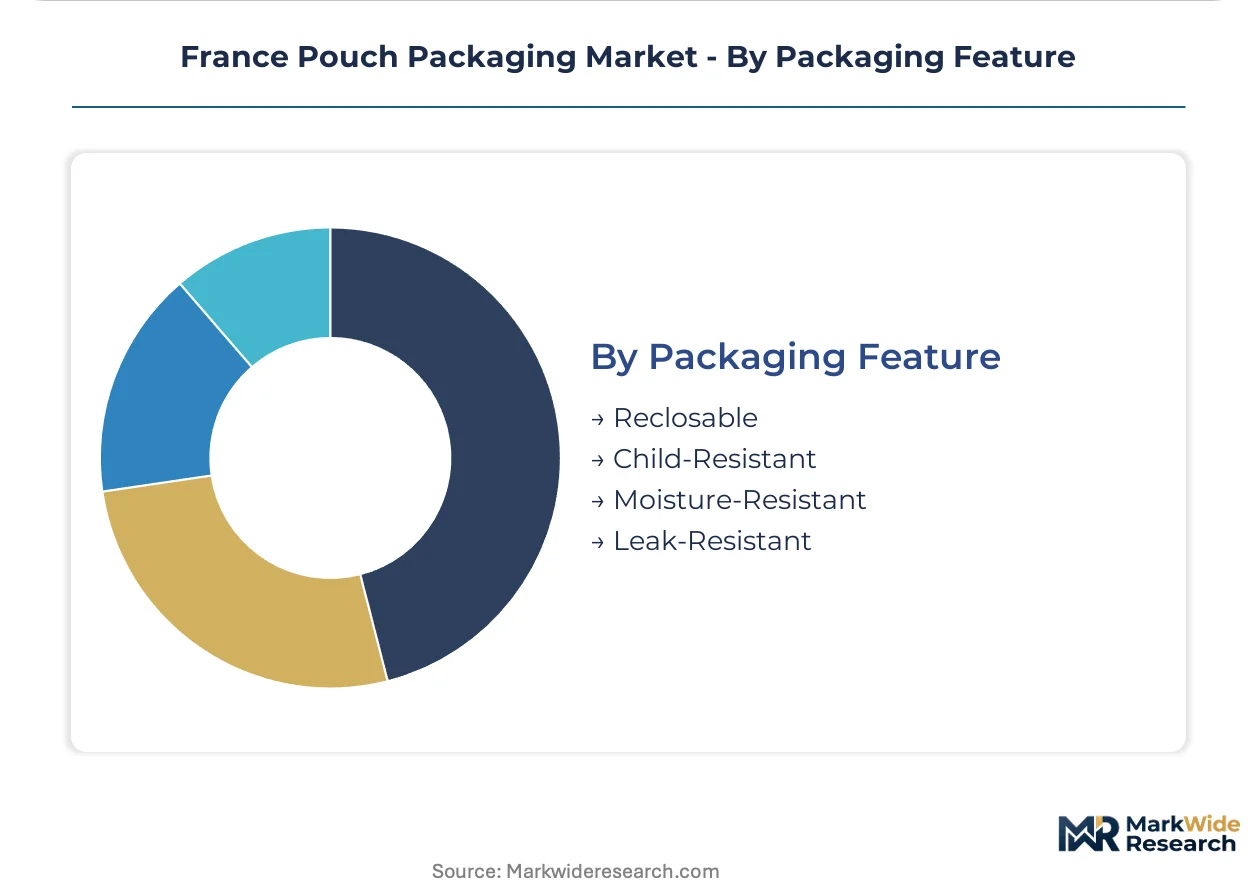
Packaging Feature:
Margin tier differentiation separates commodity formats from value-added configurations with certification overhead.
- Reclosable:Zip-lock and press-to-close mechanisms extend product life across multiple use occasions. French household penetration of larger-format pouches for snacks and frozen produce depends on reliable reclosure performance through freezer-thaw cycles.
- Child-Resistant:Senior-friendly yet child-deterrent opening mechanisms are mandatory for pharmaceutical and certain home care applications under ANSM and EU safety directives. Testing protocol costs create entry barriers for smaller converters.
- Moisture-Resistant:High-barrier laminates with desiccant integration protect hygroscopic contents in humid distribution environments.
- Leak-Resistant:Seal integrity specifications for liquid and semi-liquid contents are tightening as e-commerce shipment replaces controlled retail handling.
Reclosable maintains the broadest installed base. Child-Resistant is rotating up the share rankings on regulatory expansion into adjacent categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's pouch packaging consumption pattern diverges from neighboring economies through its heavier weighting toward premium food exports and pharmaceutical cold-chain logistics rather than commodity retail formats.
Île-de-France
Paris-based brand headquarters and hypermarket distribution networks drive demand for stand-up pouches with high retail shelf visibility. The EU Green Deal's recyclability mandates are accelerating qualification of mono-material polyethylene structures among exporters targeting German and Benelux markets. Logistics hubs in the Paris basin enable closed-loop pilot programs with quantitative sustainability reporting for major retailers.
Auvergne-Rhône-Alpes
The Lyon pharmaceutical corridor generates specialized demand for aluminum-barrier pouches with child-resistance features under ANSM enforcement. Biologics cold-chain expansion is creating demand for insulated pouch configurations with phase-change materials. Local converters are integrating desiccant and temperature-indicator technologies to meet temperature-sensitive drug distribution requirements.
Provence-Alpes-Côte d'Azur
Regional sauce and condiment brands are adopting digital inkjet printing for seasonal and limited-edition SKUs. The elimination of cylinder inventory is collapsing lead times from weeks to days for short-run specialty food packaging. Industrial composting infrastructure gaps in rural hinterlands constrain geographic rollout of compostable film alternatives despite brand owner interest.
Brittany and Normandy
Baby food processors and beverage brands are converting filling lines from rigid bottles to flexible spouted formats. E-commerce shipping advantages and material cost savings are driving equipment and substrate supply contracts across the northwestern coastal region. ANSM child-resistance specifications for pharmaceutical applications add compliance complexity but open higher-margin contract opportunities for specialized converters.
Hauts-de-France
Proximity to Belgian and Dutch sorting infrastructure influences material platform selection for cross-border supply chains. The AGEC law's extended producer responsibility penalties are pushing food brands toward certified mono-material structures detectable by advanced optical sorters. Regional waste management authorities are upgrading near-infrared detection capabilities to validate circular economy claims for national scale economics.
France Pouch Packaging Market Competitive Landscape
Capability concentration sits with integrated film producers possessing in-house recycling partnerships; scale advantage sits with diversified packaging conglomerates with pan-European distribution networks. The market structure tilts toward consolidation as procurement teams at major retailers demand mass-balance certifications and post-consumer recycled content guarantees as standard contract terms. Three archetypes dominate: integrated film-to-pouch converters, pharmaceutical-grade barrier specialists, and digital-print-enabled short-run service providers. Competitive moves center on M&A to secure recycling infrastructure access and strategic partnerships with sorting facility operators to validate circular economy claims.
Among European-based integrated producers, Amcor PLC, Mondi PLC, and Constantia Flexibles GmbH occupy positions that exemplify the capability-scale spectrum. Amcor represents the diversified conglomerate archetype with pan-European flexible film networks supplying mono-material polyethylene platforms. Mondi anchors the integrated paper-film hybrid segment through kraft paper and barrier film operations serving export-oriented food processors. Constantia Flexibles sits within the specialized barrier tier, with its GmbH structure indicating German-origin engineering focused on pharmaceutical-grade aluminum barrier configurations for regulated life sciences applications.
| Leading Market Players |
|---|
| Amcor PLC |
| Mondi PLC |
| Sonoco Products Company |
| Constantia Flexibles GmbH |
| DELTASACS |
| Coveris Management GmbH |
| BERNHARDT Packaging & Process |
| Huhtamaki Oyj |
| Sudpack |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in European flexible film extrusion is pressuring converters to absorb resin cost volatility rather than pass through to French brand owners, compressing margins while accelerating consolidation toward integrated producers with captive polymer supply.
Pricing Analysis
Long-term offtake agreements dominate procurement between major French retailers and integrated converters, locking in volume commitments against price stability guarantees that insulate buyers from polyethylene resin volatility. Pricing stratifies across certified recyclable platforms, pharmaceutical-grade barrier configurations, and commodity multi-layer laminates, with AGEC compliance premiums widening spreads. Cost compression in standard polyethylene pouches is intensifying because mid-size converters lack scale to qualify for mass-balance certification bonuses. Private-label retail buyers exhibit highest price sensitivity, while Lyon pharmaceutical corridors accept substantial premiums for ANSM-validated child-resistance and aluminum-barrier performance.
Supply Chain Analysis
Tariff exposure between EU member states and post-Brexit UK sorting infrastructure dominates cross-border supply chain risk for French exporters targeting British retail compliance. Raw material sourcing draws from German polymer producers, Benelux resin distributors, and domestic Île-de-France reprocessing hubs, with mechanical recycling feedstock availability tethered to near-infrared detection upgrade timelines. Single-source vulnerability concentrates in pharmaceutical-grade aluminum oxide deposition equipment held by a limited supplier base. Distribution runs through Paris-basin logistics clusters serving hypermarket networks, with closed-loop pilot programs validating circular economy claims through quantitative sustainability reporting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified mono-material platform development outpaces available converter capacity, creating a bottleneck where certification-ready supply commands premium positioning ahead of PPWR enforcement deadlines.
For Market Incumbents: Insulate margin position through backward integration into mechanical recycling infrastructure and polymer compounding operations, securing captive feedstock for post-consumer recycled content guarantees. Accelerate qualification of detectable mono-material polyethylene structures with Île-de-France sorting facilities to validate circular economy claims before competitor capacity comes online. Prioritize equipment upgrades for spouted pouch formats serving Brittany baby food and Normandy beverage conversions. For New Entrants and Emerging Players: Pursue digital-print-enabled short-run service provision for Provence-Alpes-Côte d'Azur specialty food brands, where seasonal SKU proliferation and collapsed lead times create service gaps incumbent converters cannot address. Target pharmaceutical cold-chain expansion in Auvergne-Rhône-Alpes, where ANSM temperature-sensitive biologics guidelines generate insulated pouch demand absent established local supply. Lead with equipment-as-a-service models that reduce capital barriers for mid-size French brand owners. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because extended producer responsibility fee structures and recyclability certification requirements are restructuring value capture toward integrated producers with validated sorting partnerships. Acquisition targets should display in-house film extrusion, established retailer sustainability certifications, and geographic proximity to Île-de-France or Hauts-de-France sorting infrastructure. Monitor French regional waste management authority capital expenditure disclosures as the signal for which material platforms achieve circular economy validation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Infrastructure | Captures mass-balance certification premiums under AGEC extended producer responsibility schemes. |
| Mono-Material Platform Qualification | Validates circular economy claims with Île-de-France optical sorting facility partnerships. |
| Spouted Pouch Equipment Conversion | Secures contracts with Brittany baby food processors replacing rigid bottle formats. |
| Digital Printing Capability Deployment | Collapses lead times for Provence-Alpes-Côte d'Azur seasonal specialty food SKUs. |
| Pharmaceutical Cold-Chain Configuration | Addresses ANSM biologics temperature requirements through phase-change material integration. |
Research Methodology
Cross-validation between converter production data and French retailer procurement specifications anchors the qualitative findings, combining primary interviews with flexible packaging plant managers, sustainability officers at major retail chains, polymer procurement leads, and regulatory compliance directors with secondary validation from EU Packaging and Packaging Waste Regulation draft texts, ANSM pharmaceutical packaging guidelines, AGEC implementation decrees, and extended producer responsibility fee schedules. Bottom-up capacity assessments across Île-de-France, Auvergne-Rhône-Alpes, and Hauts-de-France production facilities triangulate against top-down consumption estimates derived from French food processor export statistics and pharmaceutical distribution volumes.
Calibration against historical material substitution patterns in comparable EU regulatory transitions informs the projection framework across product type, material platform, end-use sector, and regional demand cluster dimensions throughout the forecast period. CAGRs derive from segment-level growth rate differentials applied to base-year value estimates, with pharmaceutical cold-chain expansion and spouted pouch conversion rates serving as primary demand elasticity inputs alongside sorting infrastructure investment timelines.
Sensitivities concentrate around French regional waste management authority detection capability upgrade schedules and PPWR final recyclability threshold determinations, either of which could accelerate or delay mono-material platform adoption materially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Benelux Pouch Packaging Market
Pouch
Japan Pouch Packaging Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
Horizontal Premade Pouch Packing Machine Market
Pouch
Spouted Pouches Market
Pouch
Slider Pouches Market
Pouch
Argentina Pouch Packaging Market
Pouch
Saudi Arabia Pouch Packaging Market
Pouch
Aluminum Foil Zipper Pouch Market
Pouch
Monodose Packs Market
Pouch
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market
Pouch
Self-Seal Pouches Market
Pouch
Feminine Care Pouch Film Market
Pouch
Aluminium Bags and Pouches Market
Pouch
Vacuum Chamber Pouches Market
Pouch
Kraft Pouch Market