
 Latin America Pouch Packaging Market | 2026-2036
Latin America Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Pouch Packaging Market Insights
Brazilian flexible packaging converters are repositioning capacity toward high-barrier pouches for protein and dairy applications. Amcor Group GmbH leverages its regional film extrusion network to supply multilayer structures across São Paulo and Minas Gerais food corridors. Mondi Group anchors European-origin paper-based pouch technology into Latin American markets, competing with conventional plastic formats. Gualapack SpA dominates spouted pouch production for children's food and beverage segments, specializing in aseptic filling compatibility.
Latin America pouch packaging comprises flexible, sealed containers fabricated from plastic films, paper laminates, aluminum foils, or composite structures, typically ranging from 50 milliliters to 5 liters in fill volume, designed for product protection, shelf-life extension, and consumer convenience through resealable or dispense features. Stand-up pouches command the largest share of regional value due to their shelf presence and material efficiency in logistics, while spout pouches represent the fastest-growing configuration as beverage and baby food brands adopt pourable formats. Plastic remains the dominant material substrate, though composite structures are capturing margin pools where extended oxygen and moisture barriers justify premium positioning.
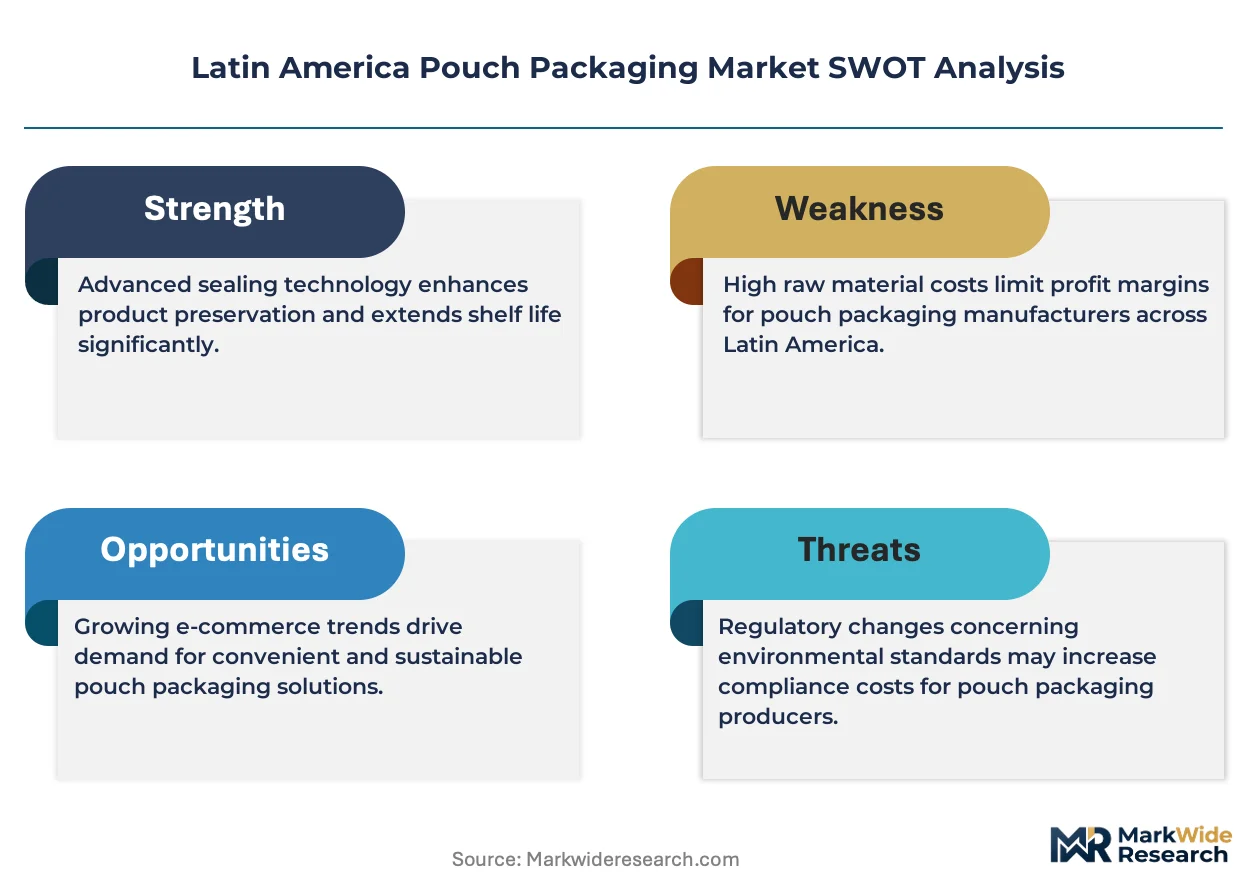
Brazil's ANVISA mandates sanitary barriers for pharmaceutical and nutritional pouch formats, while Mexico's SEMARNAT enforces extended producer responsibility rules that reshape material selection across the supply chain. Chile's REP law for packaging recovery creates compliance-driven demand for mono-material and recyclable pouch designs. Stakeholders must monitor how evolving EPR frameworks across the region interact with food safety standards to determine viable material pathways and investment timing.
Market Dynamics
Latin American pouch packaging markets are restructuring around extended producer responsibility mandates that force converters to redesign multilayer films into mono-material formats compatible with mechanical recycling infrastructure. This regulatory pressure is compressing legacy supply chains while creating first-mover advantages for converters with in-house polymer compounding capabilities.
Growth Catalysts
- SEMARNAT packaging recovery rules:Mexico's extended producer responsibility framework mandates minimum recycled content thresholds, pulling converters toward recyclable pouch designs and certified circular material sourcing.
- Stand-up pouch adoption in Brazilian retail:Major supermarket chains are replacing rigid containers with flexible formats to reduce logistics cube and shelf-space costs, concentrating demand among São Paulo and Minas Gerais food processors.
- Aseptic spout technology:Cold-chain-independent shelf-stable formats enable baby food and dairy brands to penetrate inland distribution networks previously unreachable with refrigerated alternatives.
Market Restraints
- Ethylene and propylene feedstock volatility:Petrochemical price swings in Brazilian and Argentine resin markets compress converter margins and destabilize contract pricing for multilayer structures.
- Recycling infrastructure gaps:Limited mechanical recycling capacity across Colombia, Peru, and Chile forces brands to export post-industrial scrap or stockpile waste, raising compliance costs under national recovery laws.
- Aluminum foil substitution ceiling:High-barrier applications in pharmaceutical and retort segments remain locked into metalized laminates that conflict with mono-material recyclability targets.
Strategic Opportunities
- Colombian Andean corridor penetration:Bogotá and Medellín processed food clusters show underdeveloped pouch conversion capacity relative to regional consumption growth, creating greenfield entry points for equipped converters.
- Chile REP law compliance services:Packaging recovery obligations generate demand for design-for-recycling consulting, material certification, and waste traceability systems adjacent to core manufacturing.
- Paper-barrier hybrid convergence:Fiber-based substrates combined with thin biopolymer seal layers capture premium positioning in European-export-oriented Brazilian meat and coffee brands seeking plastic reduction credentials.
Industry Challenges
- Multilayer delamination technician scarcity:Converter workforce pools lack depth in adhesive lamination and coextrusion troubleshooting, extending commissioning timelines for new high-barrier lines.
- ANVISA sanitary barrier certification delays:Pharmaceutical and nutritional pouch formats face extended approval timelines for oxygen and moisture barrier claims, freezing product launches.
- Legacy gravure-to-digital prepress migration:Short-run customization demand strains converters with sunk investment in cylinder-based printing, forcing parallel equipment maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Pouch Packaging Market |
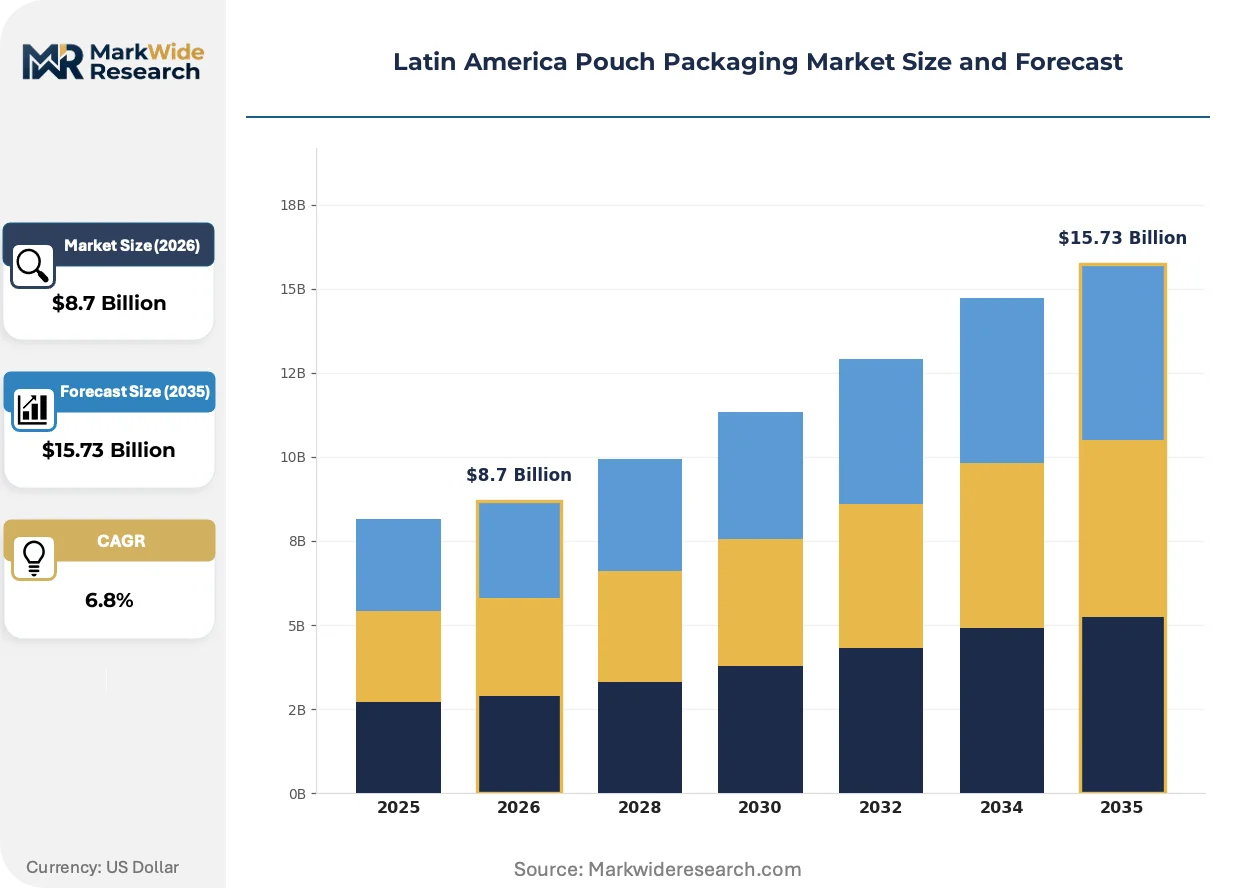
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Pouches, Stand-Up Pouches, Zip Pouches, Spout Pouches Material: Plastic, Paper, Aluminum, Composites End User: Food & Beverage, Healthcare, Personal Care, Household Products Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Stores |
| Companies Covered | Amcor Group GmbH, Mondi Group, Constantia Flexibles Group GmbH, SIG Group AG, Gualapack SpA, Sealed Air Corporation, Sonoco Products Company, Huhtamaki Oyj, ProAmpac Intermediate Inc, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Pouch Packaging Market Trends and Innovations
Digital printing and smart packaging integration are compressing minimum order quantities while enabling traceability compliance. These technologies intersect with regulatory pressure for material transparency and consumer-facing sustainability claims.
Digital flexographic and inkjet printing systems are automating make-ready and color-matching workflows that previously required manual cylinder changes. Mid-sized Brazilian condiment and sauce brands are adopting these platforms for seasonal and private-label runs. This automation is compressing economic order quantities from hundreds of thousands to tens of thousands of units, fragmenting production schedules and rewarding agile converters.
Chile's REP law for packaging recovery is mandating eco-modulated fees that penalize non-recyclable formats. Brand owners are responding by specifying mono-material polyethylene or polypropylene structures with compatible closures and labels. Dairy and beverage segments in Santiago and Valparaíso are most affected, with converters accelerating heat-seal layer reformulation to maintain barrier performance.
Retail buyer consolidation across Mexican supermarket chains is compressing supplier bases and unbundling packaging specification decisions from finished goods procurement. Category managers now direct pouch format selection based on shelf-impact metrics and waste reduction targets. This concentration is most visible in central Mexico's packaged fresh produce and ready-to-eat meal segments, where national chains are displacing regional distributors.
Latin America Pouch Packaging Market Segmentation
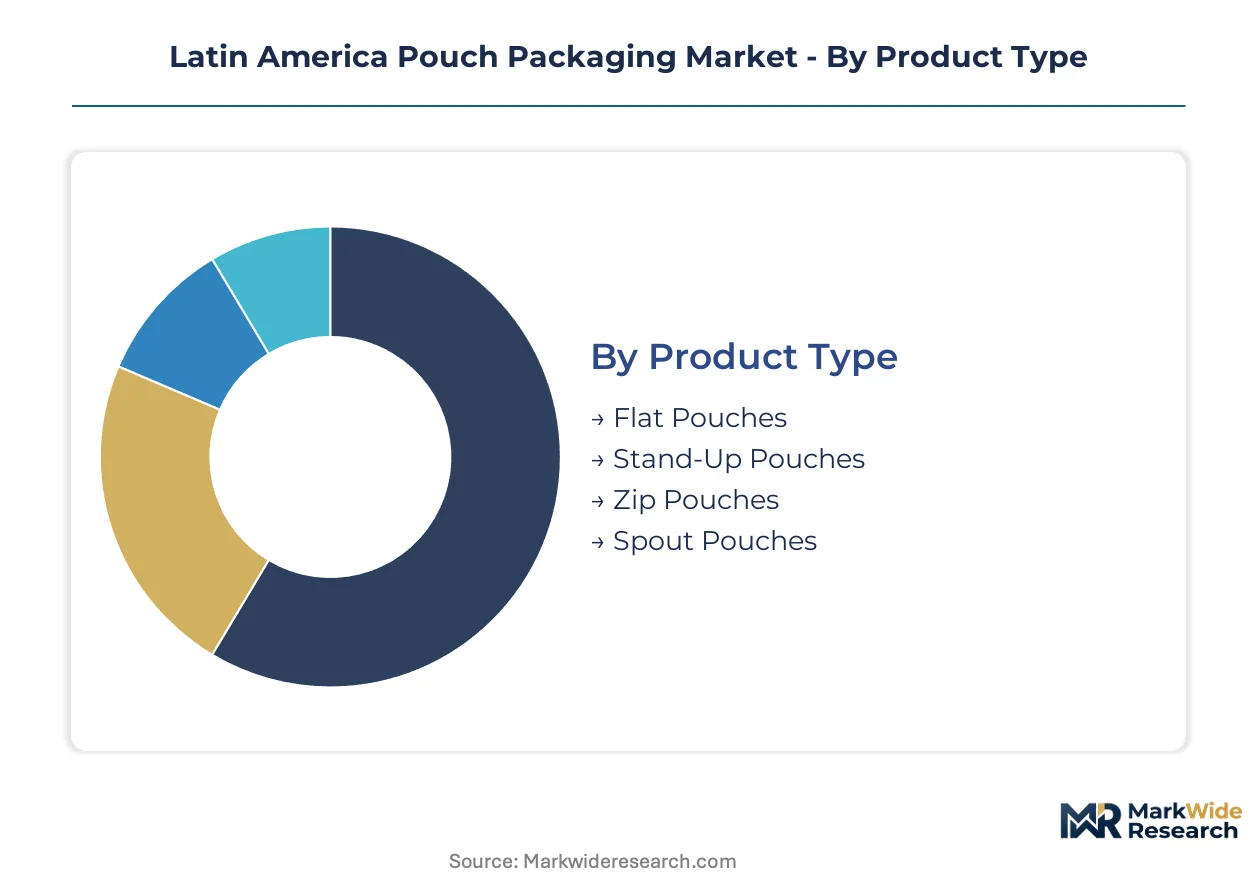
Pouch packaging procurement in Latin America fragments across technical specifications, material compliance regimes, and channel access requirements. ANVISA, SEMARNAT, and Chile's REP law each impose distinct certification burdens that reshape segment viability and converter investment priorities.
Product Type:
ANVISA mandates sanitary barrier validation for pharmaceutical and nutritional formats, while SEMARNAT's recovery rules favor designs compatible with mechanical recycling infrastructure.
- Stand-Up Pouches:Self-supporting structures with gusseted bases maximize shelf presence in Brazilian retail. São Paulo supermarket chains specify these formats for sauces and ready-to-eat meals to reduce logistics cube and stocking labor.
- Spout Pouches:Integrated dispensing closures enable pourable baby food and dairy applications without refrigeration dependency. Aseptic filling compatibility allows brands to penetrate inland distribution networks across Minas Gerais and northeastern Brazil.
- Flat Pouches:Two-dimensional sealed envelopes serve single-serve condiments and sample sachets where material minimization outweighs shelf visibility requirements.
- Zip Pouches:Reclosable interlocking strips extend product usability across multiple consumption occasions for dried fruits, nuts, and coffee in Colombian retail.
Stand-Up Pouches sits at the top of the volume ranking, with Spout Pouches climbing the fastest.
Material:
Raw material selection determines compliance pathways under Mexico's extended producer responsibility framework and Chile's eco-modulated fee structures.
- Plastic:Polyethylene and polypropylene substrates dominate regional production due to established extrusion infrastructure. Mono-material structures are gaining preference as SEMARNAT mandates minimum recycled content thresholds.
- Composites:Multilayer laminates combining plastic films with aluminum oxide or ethylene vinyl alcohol deliver oxygen barriers for retort applications. These structures face redesign pressure as mechanical recycling targets harden.
- Paper:Fiber-based substrates with biopolymer seal layers serve European-export-oriented Brazilian meat and coffee brands seeking plastic reduction credentials.
- Aluminum:Foil laminates maintain dominance in pharmaceutical blister packs and high-barrier retort pouches where metalized layers conflict with mono-material recyclability mandates.
Plastic commands the largest installed base, though Composites face the steepest regulatory headwinds.
End User:
Customer segment requirements diverge sharply on barrier performance, sterilization compatibility, and labeling real estate for regulatory disclosure.
- Food & Beverage:Processed meat, dairy, and sauce processors in Brazil and Mexico drive volume demand. Shelf-stable formats with aseptic filling compatibility unlock inland distribution previously constrained by cold chain gaps.
- Healthcare:Pharmaceutical and nutritional pouch formats require ANVISA sanitary barrier certification with extended approval timelines for oxygen and moisture claims. Nutritional supplements and single-dose medications concentrate demand.
- Personal Care:Cosmetic and hygiene brands specify pouches for travel-size and refill applications where portability and dispensing precision matter.
- Household Products:Cleaning concentrates and detergent pods utilize high-strength films with child-resistant closure options.
Food & Beverage anchors absolute volume, with Healthcare expanding most quickly on regulatory premiumization.
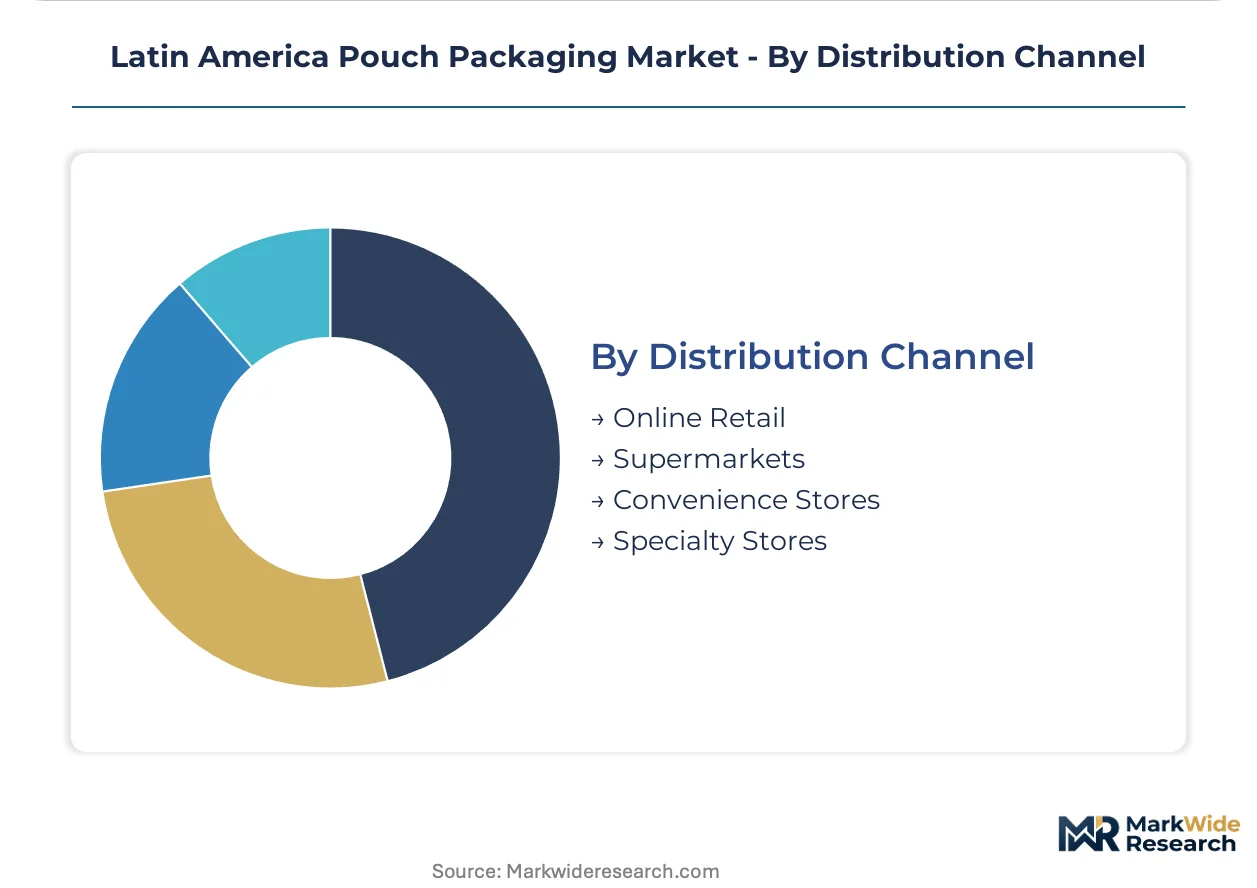
Distribution Channel:
Channel selection determines order quantity economics, lead time tolerance, and customization requirements for private-label penetration.
- Supermarkets:Central Mexico's packaged fresh produce and ready-to-eat meal segments concentrate specification power with category managers who direct format selection based on shelf-impact metrics and waste reduction targets.
- Convenience Stores:Small-format retail in Colombian Andean corridors favors single-serve and impulse-oriented pouch sizes with immediate consumption positioning.
- Online Retail:E-commerce channels demand damage-resistant structures with optimized cube efficiency for last-mile logistics, compressing economic order quantities through digital printing enablement.
- Specialty Stores:Premium and organic product positioning in Santiago and Valparaíso requires certified recyclable or compostable material credentials.
Supermarkets retain the deepest volume concentration, with Online Retail gaining share fastest on fulfillment infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting pouch conversion investments toward jurisdictions with clearer compliance pathways. Brazil and Mexico absorb the majority of capital deployment due to established EPR frameworks, while Chile's stringent recovery mandates push premium pricing for certified recyclable formats.
Brazil
ANVISA sanitary barrier requirements for pharmaceutical and nutritional pouches extend certification timelines, freezing some product launches. São Paulo and Minas Gerais food corridors anchor regional demand as major supermarket chains displace rigid containers with flexible formats. São Paulo-based converters are repositioning capacity toward high-barrier pouches for protein and dairy applications.
Mexico
SEMARNAT's extended producer responsibility framework mandates minimum recycled content thresholds, pulling converters toward mono-material designs. Central Mexico's packaged fresh produce and ready-to-eat meal segments concentrate specification power with category managers. Mexico City Metro processors face compressed supplier bases as retail buyer consolidation unbundles packaging decisions from finished goods procurement.
Chile
The REP law for packaging recovery imposes eco-modulated fees that penalize non-recyclable formats, accelerating demand for mono-material polyethylene structures. Santiago and Valparaíso dairy and beverage segments are most affected by heat-seal layer reformulation requirements. Specialty stores in these metros now require certified recyclable credentials for premium positioning.
Colombia
Andean corridor consumption growth outpaces local pouch conversion capacity, creating greenfield entry points for equipped converters. Bogotá and Medellín processed food clusters show particular underdevelopment relative to regional demand. Zip pouches for dried fruits, nuts, and coffee are gaining traction in Colombian retail as reclosable formats extend product usability.
Argentina
Ethylene and propylene feedstock volatility in Argentine resin markets compresses converter margins and destabilizes contract pricing. Buenos Aires and Córdoba industrial zones face particular pressure from petrochemical price swings. Limited mechanical recycling infrastructure forces brands to export post-industrial scrap or stockpile waste, raising compliance costs.
Latin America Pouch Packaging Market Competitive Landscape
European producers anchor one tier with paper-based and sustainable material expertise; Latin American specialists hold regional distribution and regulatory navigation capabilities. The vendor base stratifies across multinational film extruders, regional flexible packaging converters, and niche spouted pouch fabricators. Three archetypes dominate: integrated resin-to-pouch converters with compounding capabilities, mid-sized agile players serving seasonal and private-label runs, and technology licensors supplying aseptic filling compatibility. Capacity expansion and portfolio diversification toward mono-material recyclable formats represent the dominant competitive moves.
Within the multinational tier, Amcor Group GmbH and Mondi Group occupy positions that exemplify divergent material strategies. Amcor leverages regional film extrusion networks to supply multilayer structures across Brazilian food corridors, representing the integrated resin-to-pouch archetype. Mondi anchors European-origin paper-based pouch technology into Latin American markets, competing with conventional plastic formats through fiber-based substrate positioning. Gualapack SpA sits within the specialist fabricator tier, dominating spouted pouch production segments through aseptic filling compatibility focus.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Mondi Group |
| Constantia Flexibles Group GmbH |
| SIG Group AG |
| Gualapack SpA |
| Sealed Air Corporation |
| Sonoco Products Company |
| Huhtamaki Oyj |
| ProAmpac Intermediate Inc |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between ANVISA-validated pharmaceutical pouches and commodity food-grade formats manifests in both pricing power and resin sourcing configurations across Brazil and Mexico. Premium tiers command captive polyethylene supply chains from São Paulo extruders while standard tiers absorb spot-market volatility from Argentine petrochemical corridors.
Pricing Analysis
Distributor margin layering compresses final landed costs by 15-20 points for converters selling through regional packaging distributors versus direct-to-processor contracts. Three-tier pricing structure across premium, standard, and economy levels reflects barrier performance certification, with SEMARNAT-compliant mono-material formats capturing mid-tier positioning. Pricing pressure stems from ethylene feedstock volatility in Brazilian resin markets, forcing contract renegotiations quarterly. Small-format beverage processors in Colombia show highest price sensitivity, while pharmaceutical multinationals in São Paulo tolerate premium positioning for sanitary barrier validation.
Supply Chain Analysis
Polyethylene resin supply rests on Brazilian and Argentine petrochemical complexes, with specialty coextrusion equipment anchored in German and Italian engineering centers. High-barrier film substrates draw from São Paulo and Minas Gerais extrusion corridors, while spout and closure components rely on Chinese injection molding specialists. Single-source vulnerability concentrates in aseptic filling technology licensors, where European equipment providers control regional installation capacity. Distribution runs through São Paulo-based master distributors serving food processors across Brazil's southeast corridor, with direct mill relationships reserved for multinational FMCG accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between Chile's stringent REP law compliance costs and Colombia's underdeveloped conversion capacity, with SEMARNAT's recycled content mandates creating a $40-60 per ton cost spread for certified material sourcing.
For Market Incumbents: Deploy compounding-in-house capabilities to capture margin pools as SEMARNAT thresholds harden, insulating against resin price volatility through backward integration into São Paulo extrusion assets. Consolidate position in high-barrier pharmaceutical formats before ANVISA approval timelines lengthen further, locking in nutritional brand relationships with dedicated aseptic filling lines. For New Entrants and Emerging Players: Digital printing platforms offer a technology-first wedge into mid-sized Brazilian condiment brands seeking seasonal run flexibility without cylinder investment. Target Bogotá and Medellín processed food clusters where local pouch conversion capacity lags consumption growth by 30-40 percent, entering through private-label partnerships with Andean supermarket chains. For Investors and Strategic Acquirers: Asymmetric upside sits with mono-material compounding specialists holding SEMARNAT certification ahead of recycled content mandate enforcement, particularly those with captive supply agreements to Mexico City Metro processors. Acquisition focus should center on mid-tier converters with installed coextrusion lines and underutilized pharmaceutical barrier expertise. Watch ANVISA approval queue length as inflection signal for pharmaceutical format premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Conversion Investment | SEMARNAT compliance deadlines force film structure redesigns across Mexico's central corridor processors. |
| Aseptic Filling Technology Licensing | European equipment providers control penetration into Brazil's northeastern dairy distribution networks. |
| Digital Printing Platform Deployment | São Paulo converters compress minimum order quantities for seasonal sauce brand private-label runs. |
| Andean Corridor Greenfield Capacity | Bogotá food processors currently export pouch requirements to Brazilian converters with 3-week lead times. |
| REP Law Compliance Service Bundling | Chilean specialty stores now require certified recyclable credentials from Santiago-based dairy brands. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with flexible packaging plant managers, SEMARNAT compliance officers, supermarket category buyers, and pharmaceutical regulatory affairs leads with secondary validation from ANVISA filing databases, Brazilian customs trade records, SEC filings of exposed multinationals, and Chilean Ministry of Environment REP law implementation reports. Bottom-up capacity assessments across São Paulo and Minas Gerais extrusion corridors were triangulated against top-down consumption estimates derived from food processor procurement disclosures.
Historical reference periods anchored the forecast window to pre-pandemic baseline capacity utilization and post-regulatory-shift pricing regimes across the modeling period. Segmentation modeling incorporated product type, material compliance tier, end-use industry, and regional regulatory cluster dimensions. CAGRs were derived from slope analysis of normalized capacity expansion rates against consumption growth trajectories, with specific inputs including ethylene price volatility indices and ANVISA approval queue velocity.
The model holds under stable EPR enforcement timelines and resin supply continuity; deviation in SEMARNAT mandate acceleration or Argentine petrochemical export restrictions would shift capacity investment patterns. Forecasts reflect documented assumptions regarding mechanical recycling infrastructure buildout rates. A small set of named triggers—ANVISA certification delays, Chilean eco-modulated fee recalibration, and Colombian Andean corridor consumption acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
OPP Pouches Market
Pouch
Liquid Pouch Packaging Market
Pouch
Foam Pouch Market
Pouch
United States Retort Pouches Market
Pouch
Spout and Non-Spout Liquid Pouch Packaging Market
Pouch
Doyen Style Pouches Market
Pouch
Italy Pouch Packaging Market
Pouch
Global Anti Static Bubble Pouch Market
Pouch
Aluminum Pouches Market
Pouch
Spouted Pouches Market
Pouch
Morocco Pouch Packaging Market
Pouch
PCR Pouches Market
Pouch
Asia-Pacific Retort Pouch Market
Pouch
Stand-Up Pouches Market
Pouch
Pouch Dispensing Fitment Market
Pouch
United States Pouch Packaging Market