
 Kraft Block Bottom Pouch Market | 2026-2036
Kraft Block Bottom Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Kraft Block Bottom Pouch Market Foresight
E-commerce fulfillment channels is rewriting procurement patterns for protective food-grade packaging. Mondi Group leverages integrated pulp-to-pouch manufacturing across Central European mills to sustain cost discipline. Smurfit Kappa Group anchors its position through corrugated-kraft hybrid formats that compete with rigid alternatives. WestRock Company differentiates via coated natural kraft substrates that dominate premium private-label contracts in North America.
A Kraft Block Bottom Pouch is a self-standing flexible package constructed from multi-ply kraft paper with gusseted side folds and a flat base, typically incorporating heat-sealable inner layers and barrier coatings to achieve oxygen transmission rates below 5 cc/m²/day for dry goods preservation. Plastic laminated material leads volume share due to cost-efficient moisture barrier performance, while biodegradable segments register the fastest growth as compostability certifications become mandatory for quick-service restaurant supply contracts. Medium-sized pouches occupy the core demand band for retail shelf sets, though extra large formats are gaining traction in institutional foodservice channels where dispensing efficiency outweighs unit economics.
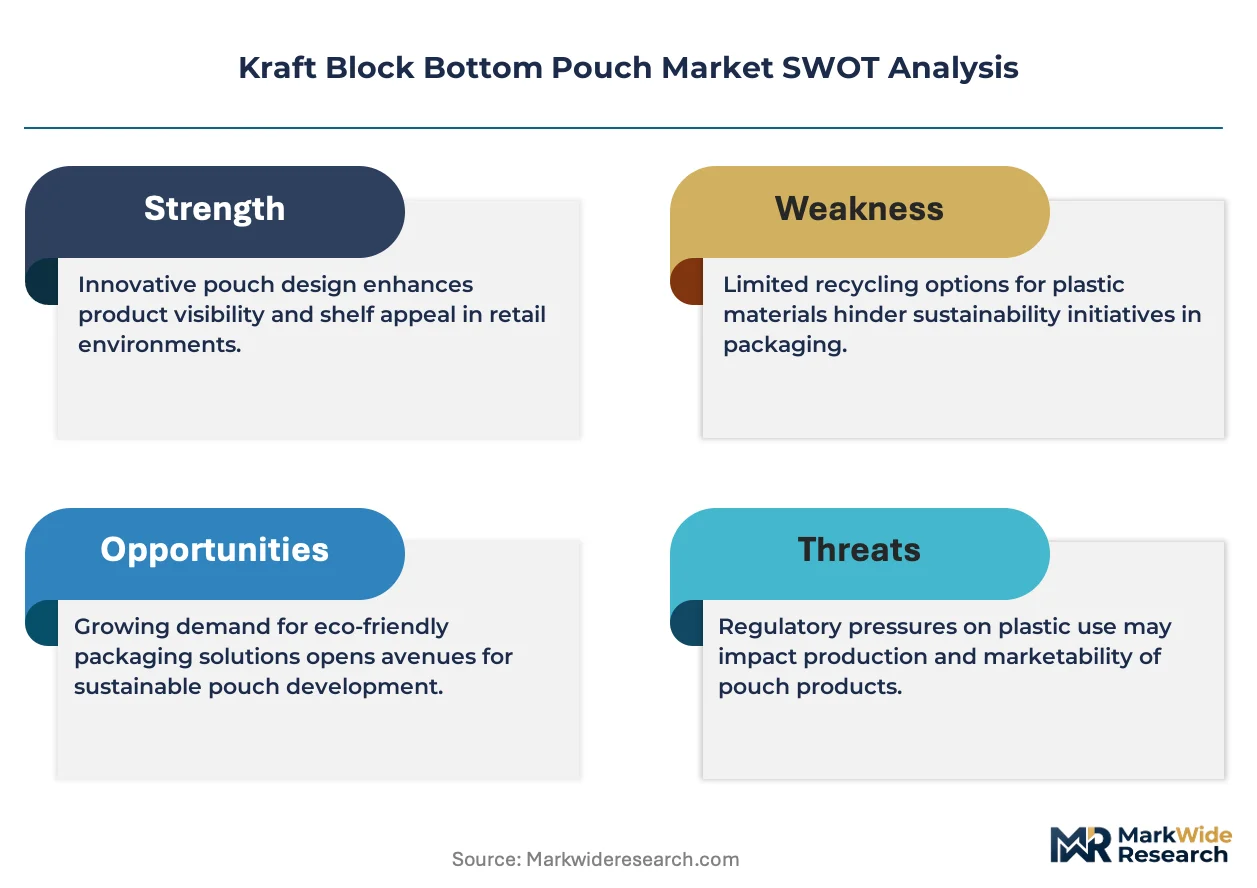
FDA food contact substance regulations govern migration limits for kraft-polymer laminates in US distribution, while EU REACH compliance restricts certain adhesive chemistries in pouch construction. EFSA guidelines on recycled fiber content in food-contact materials are tightening purity standards for European converters. Stakeholders must monitor how evolving extended producer responsibility schemes in France and Germany reshape cost allocation between brand owners and packaging suppliers.
Market Dynamics
EU PPWR recyclability mandates are forcing converters to reengineer multi-ply laminates, compressing lead times for certified substrate sourcing across Central European supply chains.
Growth Catalysts
- Specialty Coffee Roasters:Artisan brands in Germany and Italy are specifying block bottom pouches for shelf differentiation in premium retail sets, pulling demand away from conventional flat pouches.
- EU Green Deal Packaging Targets:Mandatory recycled content thresholds in food-contact materials are accelerating converter investment in fiber-recovery infrastructure.
- Heat-Seal Barrier Coatings:Solvent-free aqueous coatings with oxygen transmission rates below 5 cc/m²/day are displacing conventional extrusion laminates in dry goods applications.
Market Restraints
- Pulp Price Volatility:Kraft linerboard input costs swing with Nordic softwood pulp auction cycles, squeezing converter margins on fixed-price annual contracts.
- Adhesive Chemistry Constraints:EU REACH restrictions on specific polyurethane chemistries limit bonding options for high-barrier pouch constructions.
- Rigid Container Substitution:Glass jars and metal tins retain preference in gift-packaging segments where perceived premiumness outweighs logistics efficiency.
Strategic Opportunities
- Quick-Service Restaurant Supply:Compostability certifications are becoming mandatory in French and German QSR procurement specifications, opening volume contracts for biodegradable pouch formats.
- Institutional Foodservice Channels:Extra-large dispensing formats are gaining traction in Scandinavian hospital and university catering systems where portion-control efficiency dominates unit economics.
- Corrugated-Kraft Hybrid Innovation:Integration of micro-flute corrugated bases with kraft flexible sidewalls creates structural integrity for e-commerce shipment without secondary boxing.
Industry Challenges
- Migration Testing Bottlenecks:FDA food contact substance notification timelines stretch 180-300 days, delaying North American product launches for European converters.
- Recycled Fiber Purity Standards:EFSA tightening of food-contact recycled content specifications requires capital-intensive sorting and deinking upgrades at paper mills.
- Extended Producer Responsibility Cost Allocation:French and German EPR scheme revisions are shifting end-of-life fees upstream from municipalities to brand owners and their packaging suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kraft Block Bottom Pouch Market |
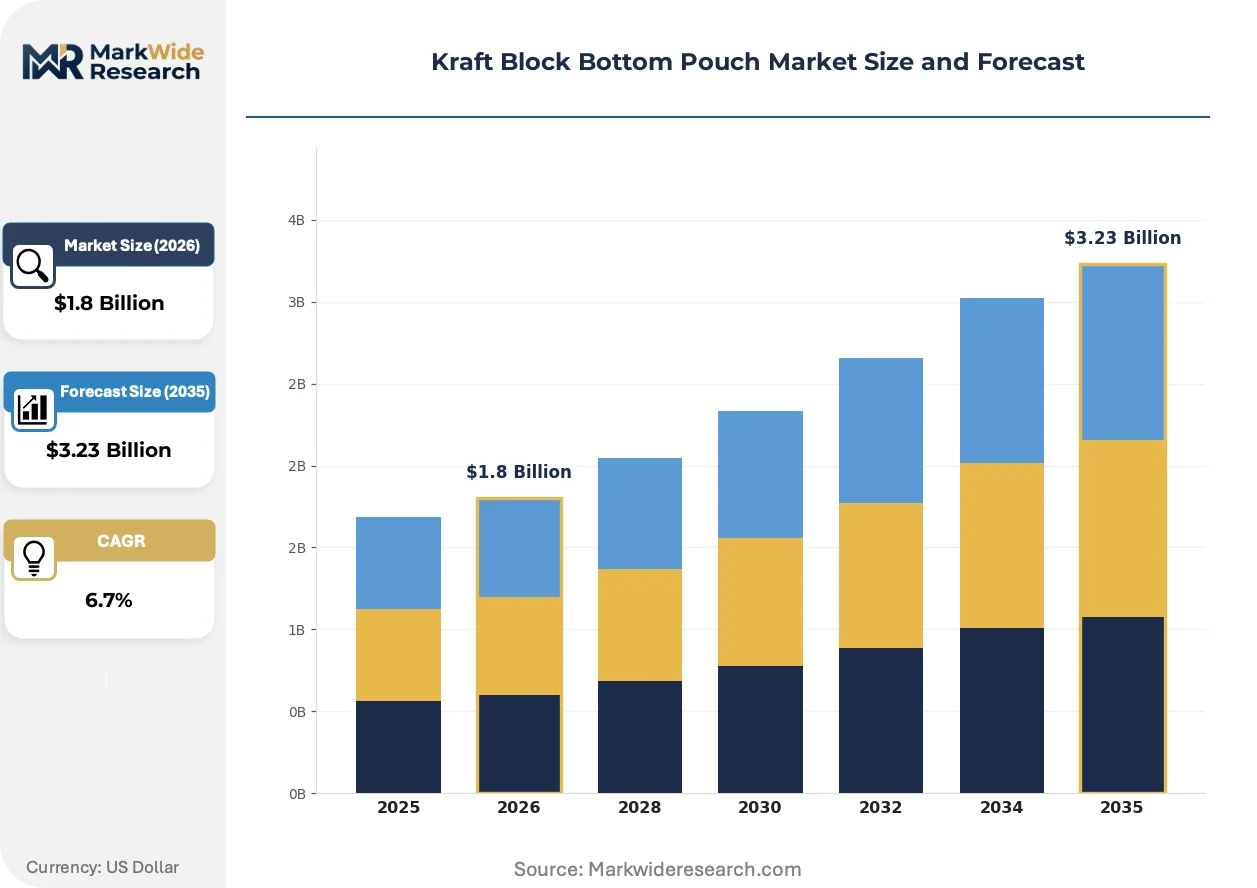
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Kraft Paper, Plastic Laminated, Aluminum Foil, Biodegradable Size: Small, Medium, Large, Extra Large Closure Type: Zip Lock, Heat Seal, Velcro, Tying End User: Food Industry, Beverage Sector, Cosmetics, Pharmaceuticals |
| Companies Covered | Mondi Group, Smurfit Kappa Group, WestRock Company, Amcor Plc, International Paper Co., Sealed Air Corporation, Novolex Holdings, BillerudKorsnäs AB, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kraft Block Bottom Pouch Market Shifts & Advancements
Digital printing integration is collapsing minimum order quantities for customized pouch runs, while regulatory chemistry restrictions and channel-specific procurement mandates are rewriting converter capability requirements.
Water-based high-definition flexography is digitizing artwork versioning for regional private-label programs. German discount retailers are adopting this technology for seasonal promotional cycles with 48-hour turnaround requirements. The technology is digitizing prepress workflows and compressing traditional cylinder engraving lead times from weeks to hours.
EU PPWR revisions mandate design-for-recyclability criteria effective across all member states, prohibiting multi-material laminates that cannot be mechanically separated. This forces converters to specify mono-material or fiber-dominant constructions with compatible heat-seal layers. Specialty coffee roasters in Italy and the Netherlands are responding fastest, locking in supply contracts with certified recyclable substrate suppliers.
Direct-to-retailer procurement platforms are disintermediating traditional distributor networks for mid-sized pouch volumes. Scandinavian food brands are consolidating supplier relationships through centralized sustainability scorecard systems that rate carbon footprint, recyclability, and ethical sourcing. This concentration is most visible in Denmark and Sweden, where retail cooperative buying power enforces uniform packaging standards across private-label portfolios.
Kraft Block Bottom Pouch Market Segmentation
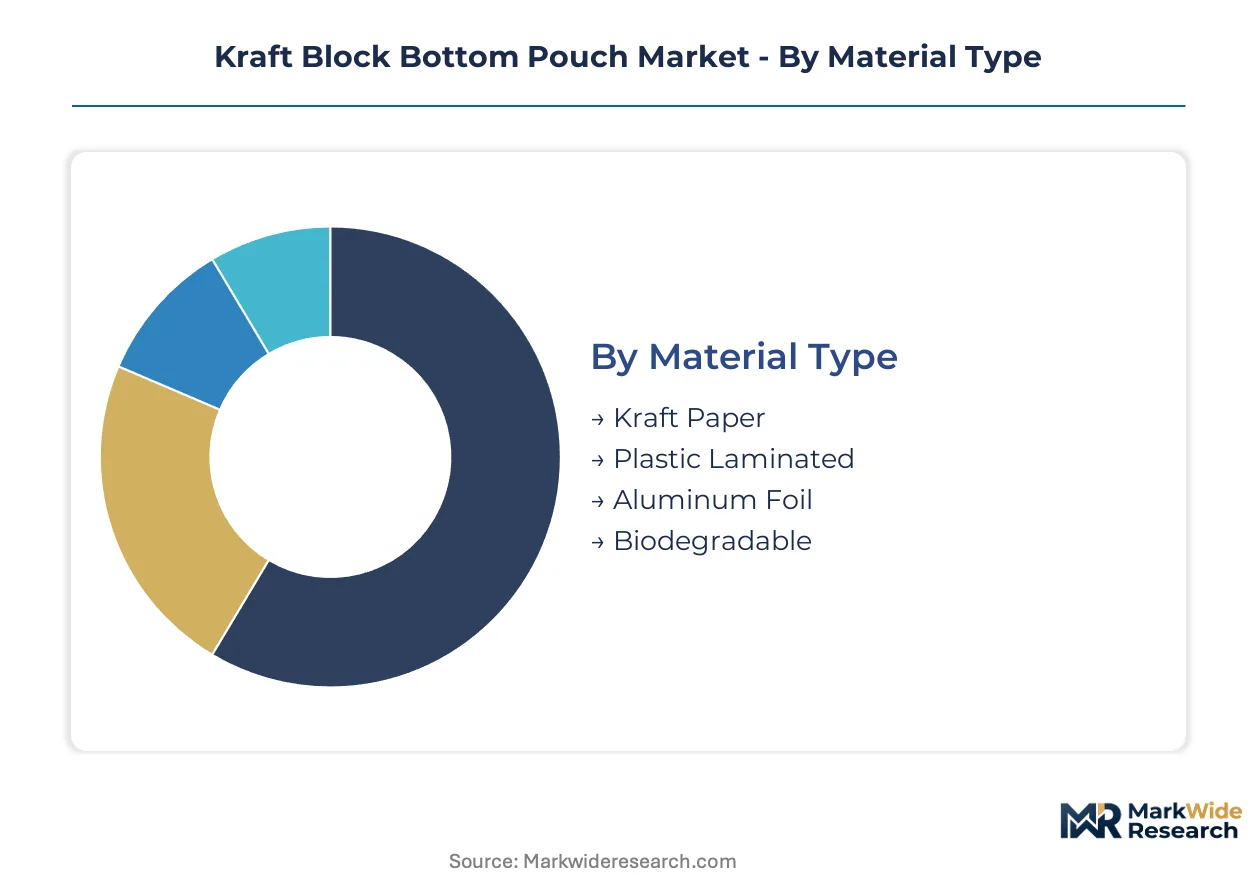
Segmentation in the Kraft Block Bottom Pouch Market reflects divergent performance requirements across material science, dimensional specifications, closure mechanics, and end-use compliance regimes. Each dimension carries distinct regulatory footprints and procurement criteria that reshape converter capability investments.
Material Type:
Cost tier differentiation separates commodity substrates from certified sustainable alternatives, with barrier performance and recyclability mandates driving specification divergence.
- Plastic Laminated:Multi-ply constructions combining kraft outer layers with polyethylene or polypropylene barrier films achieve oxygen transmission rates below 5 cc/m²/day. German discount retailers specify this format for private-label dry goods where moisture protection outweighs end-of-life recyclability concerns.
- Biodegradable:Compostable films derived from polylactic acid or cellulose acetate replace conventional polymers in heat-seal layers. French and German quick-service restaurant procurement mandates are accelerating volume commitments for certified industrially compostable formats.
- Kraft Paper:Uncoated or minimally treated natural fiber substrates serve non-barrier applications where breathability benefits dry bulk commodities.
- Aluminum Foil:Metallized or laminate-integrated foil layers deliver ultra-high barrier performance for oxygen-sensitive pharmaceuticals and specialty coffee.
Plastic laminated holds installed capacity. Biodegradable is rotating up the share rankings.
Size:
Application use cases dictate dimensional requirements, with retail shelf economics and institutional dispensing efficiency pulling specification in opposite directions.
- Medium:Standard retail-facing formats dominate supermarket shelf sets for coffee, nuts, and dried fruits. Italian specialty roasters specify this footprint for premium positioning alongside rigid tin alternatives.
- Extra Large:Institutional dispensing formats serve Scandinavian hospital and university catering systems where portion-control efficiency dominates procurement calculations. The format reduces labor costs in high-volume foodservice environments.
- Small:Single-serve and sample-size configurations target hospitality amenity programs and direct-to-consumer subscription boxes.
- Large:Club-store and bulk retail formats balance unit economics with household consumption rates for commodity dry goods.
Medium maintains retail dominance. Extra large is climbing the fastest in foodservice channel penetration.
Closure Type:
Customer convenience expectations and resealability requirements segment closure technology adoption across retail and institutional channels.
- Heat Seal:Permanent hermetic seals protect product integrity through extended distribution cycles. Solvent-free aqueous coating technologies are displacing conventional extrusion laminates in European converter specifications.
- Zip Lock:Mechanical interlocking tracks enable consumer resealability for multi-use dry goods. German coffee brands specify this feature for premium positioning in supermarket premium tiers.
- Tying:Traditional twist-tie or wire-tie closures persist in artisan bakery and specialty food segments where craft aesthetic overrides functional convenience.
- Velcro:Hook-and-loop fastening systems serve reusable container applications and industrial ingredient dispensing where frequent access is required.
Heat seal commands food-contact safety compliance. Zip lock is gaining share fastest in retail premium tiers.
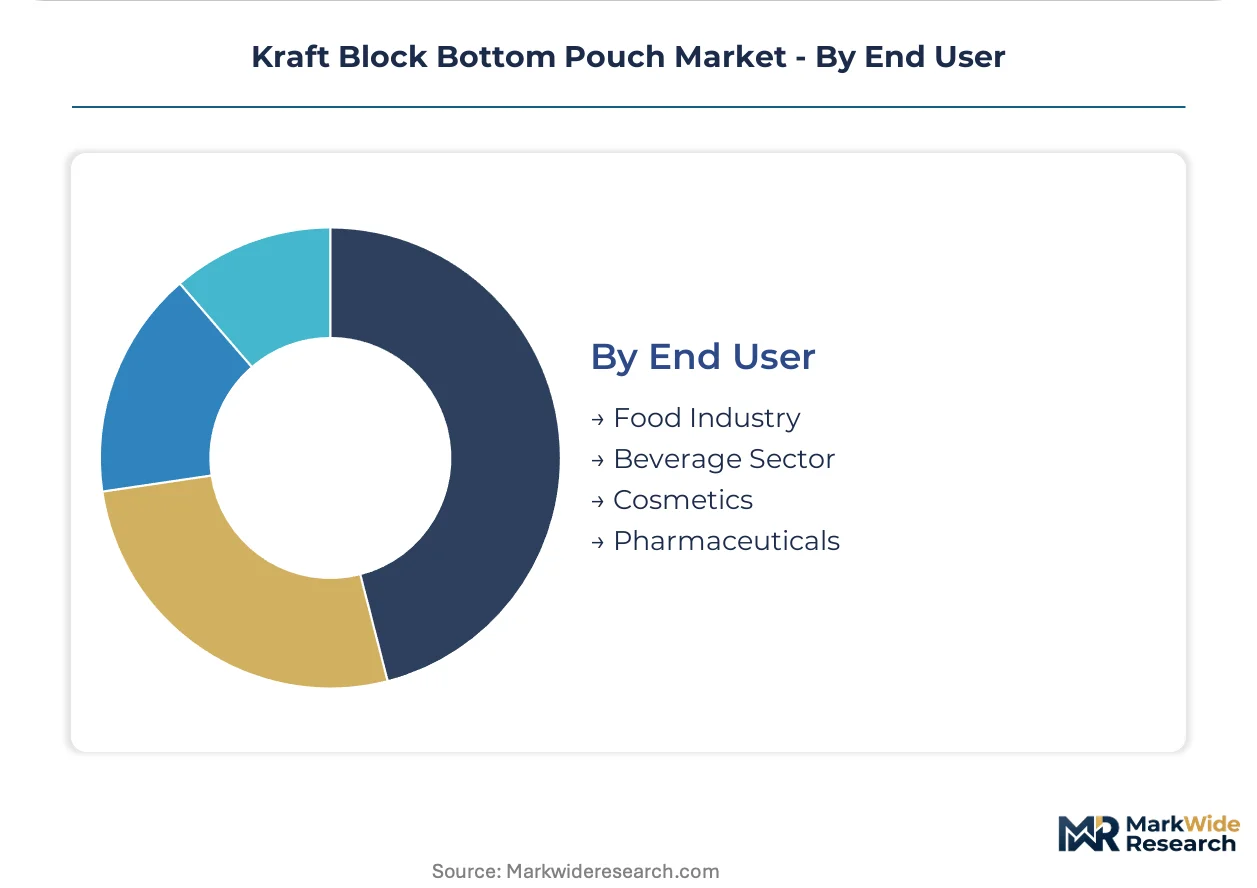
End User:
Regulatory compliance intensity and barrier performance requirements segment demand across food-contact, cosmetic, and pharmaceutical applications.
- Food Industry:Dry goods preservation drives oxygen and moisture barrier specifications. EFSA tightening of recycled fiber purity standards is forcing capital upgrades at European paper mills serving this segment.
- Pharmaceuticals:Migration testing and child-resistance requirements govern pouch construction. FDA food contact substance notification timelines stretch 180-300 days for European converters entering US distribution.
- Beverage Sector:Powdered drink mixes and specialty tea applications require aroma barrier performance alongside moisture protection.
- Cosmetics:Natural and organic positioning aligns with kraft aesthetic preferences for bath salts, botanicals, and solid personal care products.
Food industry anchors volume demand. Pharmaceuticals is expanding most quickly on regulatory compliance premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Packaging and Packaging Waste Regulation revisions are tightening recyclability mandates across member states, concentrating converter investment in Germany, France, and Italy where retail sustainability benchmarks exceed regional norms.
Germany
Specialty coffee roasters in Berlin and Hamburg are accelerating procurement of certified recyclable block bottom pouches for premium shelf differentiation. The national EPR scheme revisions are shifting end-of-life fees upstream from municipalities to brand owners and packaging suppliers. Bavarian paper mills are upgrading fiber-recovery infrastructure to meet EFSA tightening of recycled content purity standards.
France
Quick-service restaurant procurement mandates are making compostability certifications mandatory for pouch supply contracts in the Paris basin. ANSM oversight of food-contact materials is converging with EU REACH restrictions on specific adhesive chemistries. Lyon-based converters are reengineering multi-ply laminates to meet design-for-recyclability criteria ahead of PPWR enforcement timelines.
Italy
Artisan food brands in Milan and Turin are specifying block bottom pouches to displace conventional flat pouches in retail premium tiers. EFSA guidelines on recycled fiber content are forcing capital-intensive sorting upgrades at domestic paper mills. Emilia-Romagna packaging clusters are locking in supply contracts with certified substrate suppliers for specialty coffee applications.
United States
FDA food contact substance notification timelines stretching 180-300 days are delaying North American product launches for European converters. Private-label contracts in premium retail channels are specifying coated natural kraft substrates for shelf differentiation. Midwestern corrugated-kraft hybrid production is expanding to serve e-commerce fulfillment channels without secondary boxing requirements.
Netherlands
Centralized sustainability scorecard systems in Dutch retail cooperatives are enforcing uniform packaging standards across private-label portfolios. Rotterdam port logistics are anchoring pulp-to-pouch supply chain integration for Central European distribution. Amsterdam-based specialty roasters are adopting digital printing for 48-hour turnaround on seasonal promotional cycles.
Kraft Block Bottom Pouch Market Competitive Landscape
On the supply side, the industry is consolidating around integrated pulp-to-pouch manufacturers and corrugated-kraft hybrid specialists. Tiered competitive positioning separates scale-driven integrated producers from mid-cap substrate converters and regional flexible packaging specialists. Dominant competitive moves include backward integration into captive fiber supply and strategic partnerships with certified compostable film suppliers.
Among integrated European producers, Mondi Group exemplifies the pulp-to-pouch archetype through Central European mill networks. Smurfit Kappa Group occupies a position anchoring corrugated-kraft hybrid innovation against rigid container alternatives. WestRock Company represents the coated natural kraft substrate tier dominating premium private-label contracts in North American distribution.
| Leading Market Players |
|---|
| Mondi Group |
| Smurfit Kappa Group |
| WestRock Company |
| Amcor Plc |
| International Paper Co. |
| Sealed Air Corporation |
| Novolex Holdings |
| BillerudKorsnäs AB |
| ProAmpac |
| Others |
Supply & Pricing Matrix
Nordic softwood pulp auction cycles in Sweden and Finland concentrate upstream cost volatility, compressing margin pools at converter level while shifting pricing power toward integrated pulp-to-pouch manufacturers with captive fiber supply.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts, with annual fixed-price agreements anchoring standard-grade plastic-laminated formats while spot-indexed pricing governs biodegradable certified tiers. Price differentiation hinges on compostability certification grade and customization complexity for digital-printed seasonal runs. Cost compression in commodity kraft linerboard intensifies as Nordic pulp auctions swing on energy input costs. German discount retailers exhibit highest price sensitivity, whereas Italian specialty coffee roasters absorb premiums for coated natural kraft substrates with sub-5 cc/m²/day barrier performance.
Supply Chain Analysis
Upsteam feedstock dependence on Nordic softwood pulp, German adhesive chemical suppliers, and Chinese metallized film producers concentrates geographic supply risk across three distinct regulatory zones. Raw material sourcing draws from bleached kraft linerboard mills, solvent-free aqueous coating formulations, and heat-seal layer polymers. Single-source vulnerability in specialized barrier coating chemistries exposes converters to EU REACH restriction cascades. Distribution runs through Central European converter clusters serving pan-European retail cooperative networks, with Rotterdam port logistics anchoring transatlantic shipments to North American private-label channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment around EU PPWR recyclability mandates and EFSA food-contact purity standards creates substantial switching costs for brand owners locked into certified substrate supply relationships.
For Market Incumbents: Harden supply security through backward integration into Nordic pulp assets or long-term offtake agreements with Bavarian fiber-recovery facilities. Deepen channel control via direct-to-retailer procurement platforms that disintermediate traditional distributor networks. Prioritize certification investment in industrially compostable formats ahead of French and German QSR mandate enforcement timelines. For New Entrants and Emerging Players: Pursue white-space opportunity in Scandinavian institutional foodservice channels where extra-large dispensing formats face limited incumbent specialization. Target quick-service restaurant supply contracts in the Paris basin where compostability certification requirements are newly mandatory and supplier qualification timelines favor agile entrants. Lead with digital printing integration offering 48-hour turnaround on seasonal promotional cycles. For Investors and Strategic Acquirers: Capital is best deployed toward integrated pulp-to-pouch manufacturers with captive Central European mill networks and established EFSA compliance infrastructure. Long-term viability over the medium-term projection horizon rests on fiber-recovery asset ownership and certified recyclable substrate supplier relationships. Monitor French and German EPR scheme revision implementation as inflection indicator for upstream cost allocation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Assets | Captive Nordic softwood supply insulates margin compression from auction cycle volatility. |
| Compostability Certification Investment | French ANSM and German EPR mandates are locking in volume for certified biodegradable formats. |
| Digital Printing Platform Deployment | German discount retailer 48-hour turnaround requirements favor aqueous flexography adopters. |
| Direct-to-Retailer Procurement Channel | Dutch retail cooperative scorecard systems reward supplier consolidation and transparency. |
| Corrugated-Kraft Hybrid Format Development | Micro-flute base integration eliminates secondary boxing for e-commerce fulfillment channels. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with packaging procurement managers at German discount retailers, Italian specialty coffee roasters, French QSR supply chain directors, and Scandinavian institutional foodservice operators; and secondary validation drawing from EU PPWR regulatory filings, EFSA food-contact material guidelines, Nordic pulp auction price indices, and customs trade data for kraft linerboard imports. Bottom-up volume modeling triangulated against top-down converter capacity assessments across Central European mill networks.
Forecast inputs considered material type substitution dynamics, closure technology adoption curves, and end-use regulatory compliance intensity across the projection horizon. Segmentation dimensions modeled include barrier performance tier, dimensional specification band, closure mechanism, and channel-specific procurement mandate cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific inputs incorporated EU Green Deal packaging target implementation schedules and FDA food contact substance notification timeline bottlenecks.
Sensitivities concentrate around EU PPWR enforcement timeline acceleration, Nordic pulp price spike duration, and EPR cost allocation scheme revisions in France and Germany. Forecasts reflect documented assumptions regarding certification adoption rates and converter reengineering lead times. Cross-checking against EFSA recycled fiber purity standard implementation progress is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Brazil Pouch Packaging Market
Pouch
High-Barrier Pouches Market
Pouch
Utility Pouches Market
Pouch
Colombia Pouch Packaging Market
Pouch
Standcap Pouch Market
Pouch
Inverted Pouch Market
Pouch
Asia-Pacific Retort Pouch Market
Pouch
Pillow Pouch Packaging Market
Pouch
Fin Seal Pouches Market
Pouch
Nigeria Pouch Packaging Market
Pouch
Saudi Arabia Pouch Packaging Market
Pouch
Stick Pouches Packaging Market
Pouch
India Pouch Packaging Market
Pouch
Latin America Pouch Packaging Market
Pouch
Wrap-Around Packers Market
Pouch
France Pouch Packaging Market