
 Japan Packaging Design Services Market | 2026-2036
Japan Packaging Design Services Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Packaging Design Services Market Insights
Packaging concept-to-shelf workflow revenue is tilting toward integrated structural and graphic design bundles. Nippon Design Center leverages its heritage in Japanese aesthetic systems to anchor premium food and cosmetics accounts. Dentsu Group Inc. sustains cross-media packaging campaigns that merge physical shelf presence with digital activation. GK Graphics specializes in material-specific engineering for glass and metal substrates, occupying a technical niche that commands higher fees.
Packaging design services encompass the creative and engineering disciplines that develop protective, communicative, and regulatory-compliant enclosures for commercial products, incorporating specifications such as barrier thickness, closure torque tolerance, and print registration accuracy to ensure shelf stability and consumer safety. Structural design and graphic design together form the core revenue base, with structural work commanding premium fees due to its dependency on material science expertise and prototyping iterations. Label design is accelerating fastest among service types as pharmaceutical and electronics end users tighten compliance requirements for multilingual ingredient and safety disclosures.
METI's resource efficiency guidelines and Japan's Plastic Resource Circulation Act together mandate reduced material usage and higher recyclability, forcing brands to redesign existing packaging formats and expand procurement of sustainable design services. JIS standards for packaging safety and child-resistant closures further constrain design freedom, elevating demand for specialists who navigate regulatory verification processes. Stakeholders must monitor how amendments to extended producer responsibility frameworks reshape fee structures for compliance-intensive design categories.
Market Dynamics
Japan's Plastic Resource Circulation Act and METI resource efficiency guidelines are forcing simultaneous material reduction and recyclability upgrades, compressing design iteration cycles and elevating procurement of integrated structural-graphic service bundles.
Growth Catalysts
- Regulatory compliance mandates:Japan's Plastic Resource Circulation Act compels brands to redesign existing packaging formats, expanding procurement of sustainable design services and material engineering expertise.
- Food and beverage shelf differentiation:Premium brands in Tokyo and Osaka are expanding design budgets to secure integrated structural and graphic design bundles that command retail attention.
- Pharmaceutical label complexity:Electronics and pharmaceutical end users are tightening requirements for multilingual ingredient and safety disclosures, accelerating demand for specialized label design services.
Market Restraints
- Specialized talent scarcity:Material science expertise for structural prototyping and JIS compliance verification remains concentrated among a limited pool of Tokyo-based agencies.
- Input cost volatility:Fluctuations in specialty substrate pricing for glass and metal packaging compress margins on fixed-fee design contracts.
- Regulatory friction:Extended producer responsibility framework amendments create uncertainty in fee structures for compliance-intensive design categories.
Strategic Opportunities
- Kansai regional expansion:Osaka and Kyoto manufacturing corridors remain underpenetrated relative to Tokyo's design agency cluster, offering white space for premium structural design commissions.
- Digital-physical convergence:Cross-media packaging campaigns that merge physical shelf presence with digital activation represent an emerging service layer with higher fee potential.
- Export-oriented redesign:Brands targeting EU markets require REACH and CSRD-aligned packaging adaptations, creating regulatory tailwind for compliance-specialized design services.
Industry Challenges
- Prototyping capex intensity:Material-specific engineering for glass and metal substrates demands specialized equipment investments that strain mid-size agency balance sheets.
- JIS certification timelines:Child-resistant closure verification and packaging safety standard compliance extend project delivery schedules, compressing effective billing rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Packaging Design Services Market |
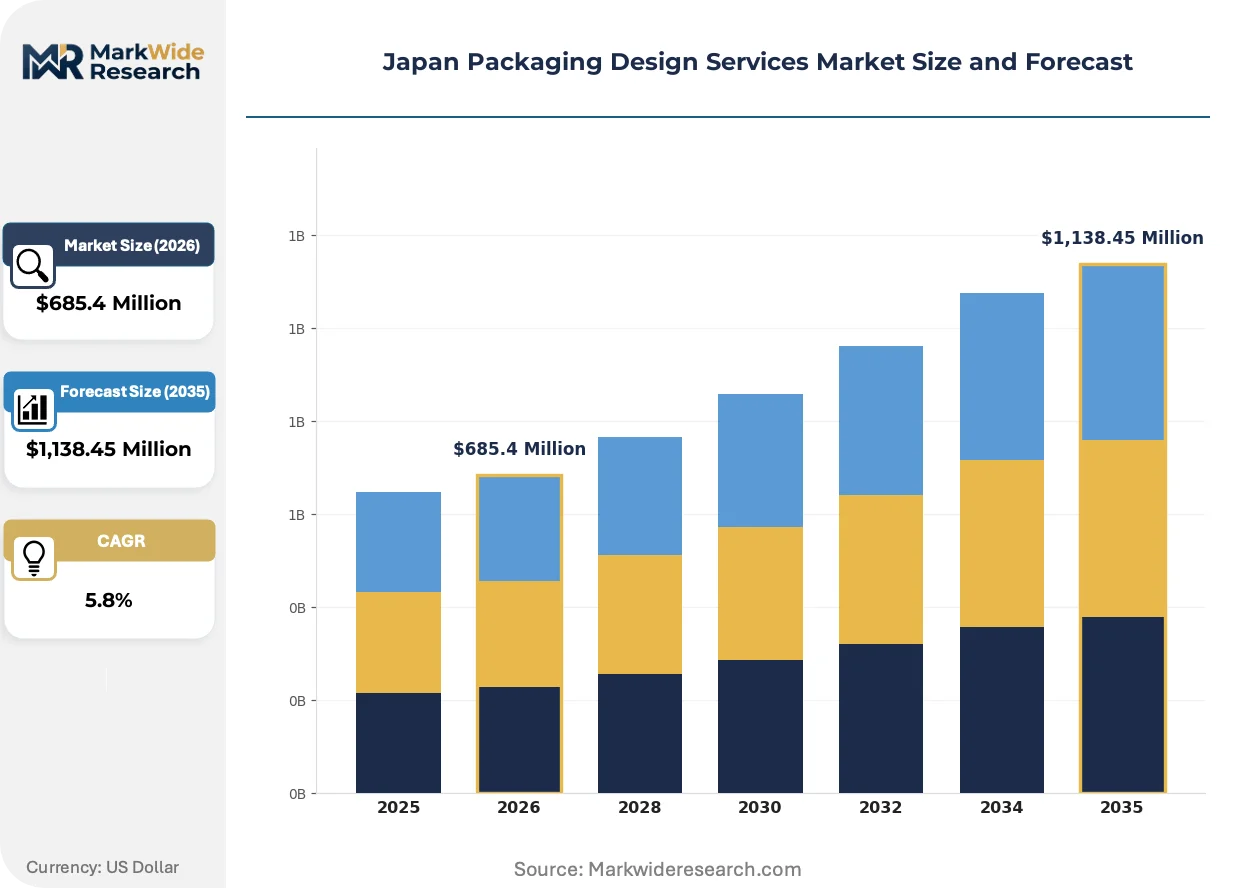
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Label Design, Structural Design, Graphic Design, Prototyping Material Type: Paper, Plastic, Glass, Metal End User: Food & Beverage, Cosmetics, Electronics, Pharmaceuticals Design Complexity: Simple, Moderate, Complex, Custom |
| Companies Covered | Nippon Design Center, Takram Co., Ltd., NOSIGNER, Nendo, CINRA, Inc., Dentsu Group Inc., GK Graphics, Winkreative, Frog Design, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Packaging Design Services Market Trends and Innovations
Digital fabrication workflows and regulatory compliance automation are compressing traditional concept-to-shelf timelines, while sustainability verification requirements are embedding new technical competencies into core service offerings.
Generative design software paired with rapid prototyping hardware is collapsing the traditional gap between structural concept and physical validation. Cosmetic and pharmaceutical brands in Tokyo are adopting these integrated workflows within six-month procurement cycles. The technology is collapsing the premium fee structure that previously rewarded lengthy prototyping iterations, forcing agencies to capture value through faster turnaround guarantees rather than hourly engineering rates.
METI's resource efficiency guidelines and amendments to Japan's Plastic Resource Circulation Act are mandating demonstrable material reduction and recyclability pathways. Industrial consequence includes mandatory redesign of existing packaging formats regardless of brand equity investment. Food and beverage manufacturers are responding by embedding lifecycle assessment specialists directly into design procurement teams, elevating technical validation above aesthetic preference in vendor selection.
Buyers are consolidating vendor relationships around agencies offering integrated structural, graphic, and compliance verification capabilities. The traditional separation of creative and engineering procurement is yielding to single-source accountability for shelf-ready outcomes. Electronics and pharmaceutical verticals in the Kanto region are most visible in this shift, where procurement teams now prioritize JIS certification expertise alongside portfolio quality in RFP evaluation criteria.
Japan Packaging Design Services Market Segmentation
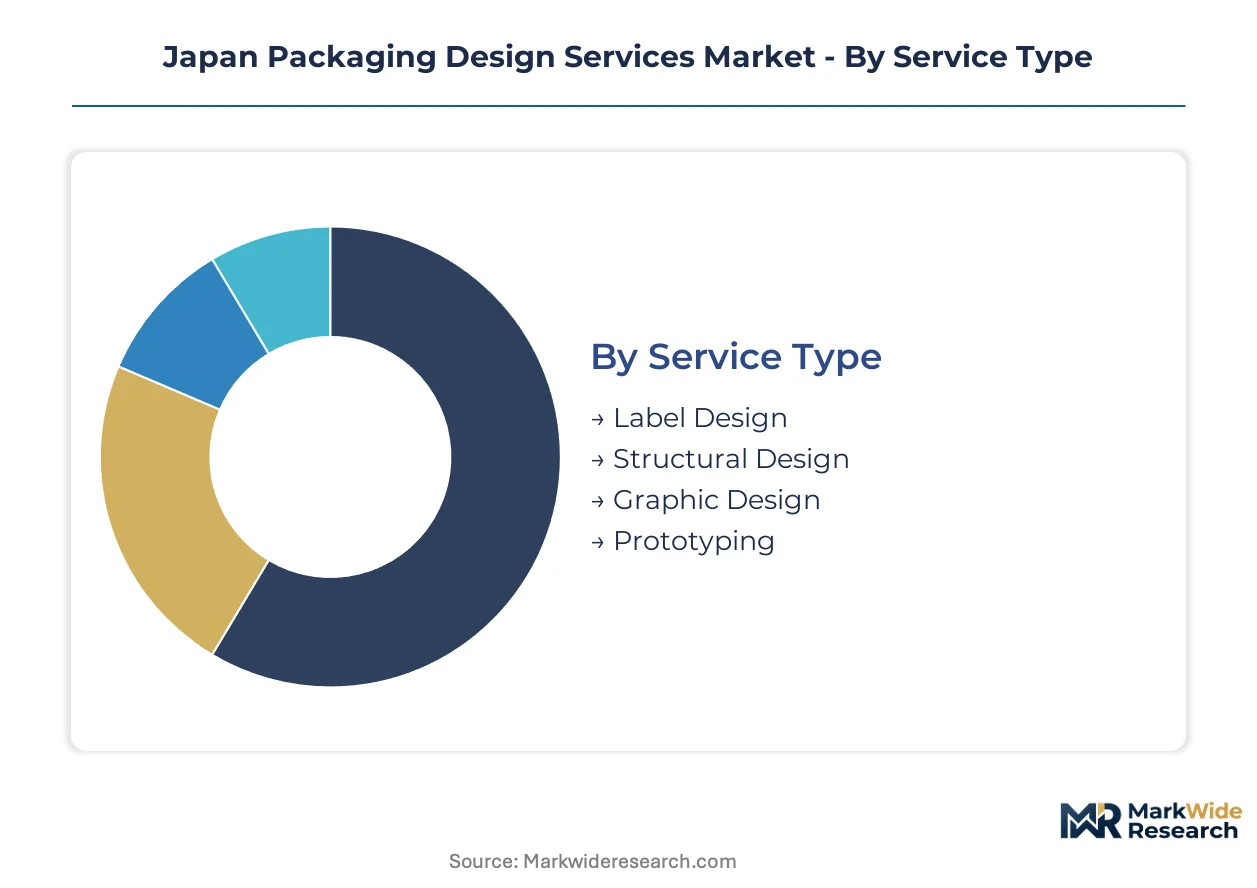
Service bundling and regulatory layering have fragmented procurement patterns across Japan's packaging design market. Vendors now compete on specialized competencies rather than generalist creative output.
Service Type:
End-use requirements span compliance-heavy pharmaceutical labeling through premium cosmetic structural engineering.
- Structural Design:Material science expertise governs barrier thickness specifications, closure torque tolerances, and shelf stability engineering. Tokyo-based food and cosmetics brands commission premium structural work for retail differentiation, though prototyping capex demands strain mid-size agency balance sheets.
- Graphic Design:Visual identity systems integrate print registration accuracy with Japanese aesthetic conventions. Osaka and Kyoto manufacturers are expanding procurement of integrated structural-graphic bundles to compress concept-to-shelf timelines.
- Label Design:Multilingual ingredient disclosures and safety warnings for pharmaceutical and electronics verticals. METI resource efficiency guidelines are forcing material reduction without compromising regulatory readability.
- Prototyping:Physical validation workflows using generative design software and rapid fabrication hardware. Cosmetic brands in Tokyo now demand six-month procurement cycles for integrated prototyping services.
The dominant share belongs to Structural Design, while Label Design is closing the gap fastest.
Material Type:
Cost tiers separate commodity substrates from engineered alternatives requiring specialized design expertise.
- Plastic:Dominant substrate facing forced redesign under Japan's Plastic Resource Circulation Act. Food and beverage manufacturers are embedding lifecycle assessment specialists into procurement teams to navigate recyclability mandates.
- Paper:Accelerating substitution for single-use plastic in retail and foodservice applications. Premium cosmetics brands in Tokyo specify paper-based structural formats for sustainability positioning.
- Glass:Material-specific engineering demands specialized equipment investments that elevate design fees. GK Graphics occupies a technical niche commanding premium rates for glass substrate projects.
- Metal:Barrier performance requirements in pharmaceutical and electronics verticals sustain specialized demand. JIS certification timelines for metal closure systems extend project delivery schedules.
Plastic retains volume leadership, though Paper is expanding most quickly as brands execute regulatory-driven material transitions.
End User:
Customer types range from compliance-driven pharmaceutical procurement to aesthetic-intensive cosmetic brand building.
- Food & Beverage:Shelf differentiation budgets are expanding for integrated design bundles. Premium brands in Tokyo and Osaka prioritize structural innovation for retail attention capture.
- Cosmetics:Japanese aesthetic systems anchor premium account relationships. Nippon Design Center leverages heritage competencies to secure recurring commissions from established beauty houses.
- Electronics:Multilingual safety disclosures and technical documentation requirements tighten label complexity. Kanto region procurement teams prioritize JIS certification expertise in vendor evaluation.
- Pharmaceuticals:Child-resistant closure verification and ingredient transparency mandates elevate regulatory overhead. PMDA compliance pathways extend design iteration cycles and verification costs.
Food & Beverage commands the largest procurement volume, while Pharmaceuticals shows the steepest fee escalation trajectory.
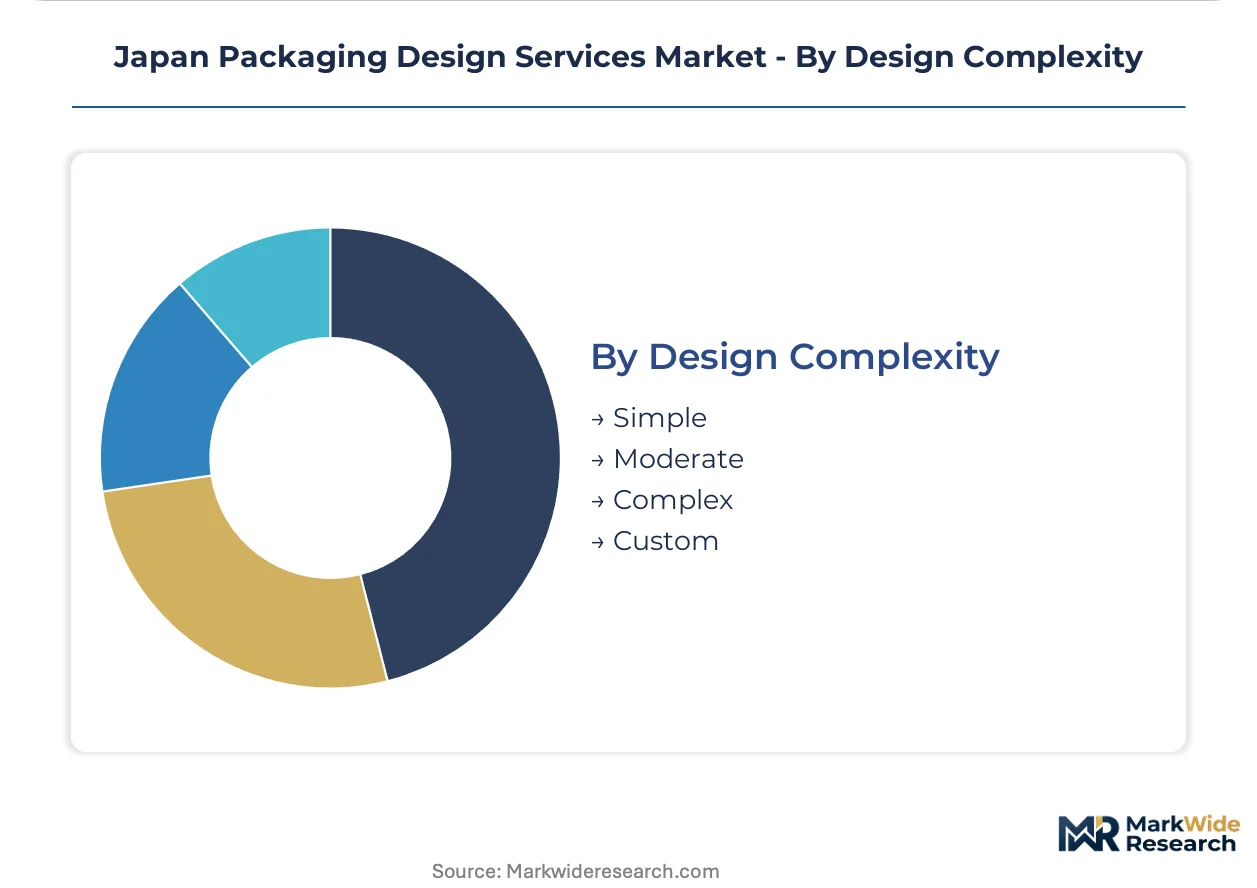
Design Complexity:
Maturity levels correlate with billing structure — standardized formats yield fixed fees, custom engineering commands cost-plus arrangements.
- Complex:Multi-substrate engineering with integrated compliance verification for export markets. Brands targeting EU markets require REACH and CSRD-aligned adaptations creating regulatory tailwinds.
- Custom:Bespoke structural and graphic systems for flagship product launches. Dentsu Group Inc. sustains cross-media campaigns merging physical shelf presence with digital activation at this tier.
- Moderate:Adaptation of proven formats with limited material or regulatory modifications. Mid-market cosmetics and regional food brands concentrate procurement here.
- Simple:Template-based label updates and format refreshes with minimal engineering overhead. Commodity food and beverage producers prioritize cost minimization.
Complex assignments generate the highest absolute fees, while Custom work is gaining share fastest as brands pursue integrated physical-digital campaigns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Osaka and Kyoto manufacturing corridors exhibit higher price elasticity for standardized design services, while Tokyo-based premium food and cosmetics brands absorb premium fees for integrated structural-graphic bundles with minimal negotiation.
Kanto/Tokyo
Tokyo's design agency cluster commands the bulk of premium structural design commissions for food and cosmetics verticals. METI's resource efficiency guidelines force simultaneous material reduction and recyclability upgrades across brand portfolios. Shibuya and Minato wards concentrate integrated prototyping facilities serving six-month procurement cycles for cosmetic houses.
Kansai/Osaka
Osaka manufacturing corridors remain underpenetrated relative to Tokyo, offering white space for premium structural design commissions from regional food producers. Japan's Plastic Resource Circulation Act accelerates demand for sustainable packaging redesigns among mid-market brands. Kyoto's heritage craft traditions attract paper-based structural format development for premium positioning.
Chubu/Nagoya
Automotive and industrial equipment suppliers in Aichi Prefecture generate specialized demand for export-oriented packaging compliance. PMDA-aligned pharmaceutical packaging requirements from Nagoya medical device manufacturers tighten label complexity specifications. Toyota City industrial cluster sources multilingual safety disclosure designs for EU and North American export markets.
Kyushu
Fukuoka's growing electronics assembly base drives procurement of JIS-certified packaging for semiconductor and component shipments. Regional food processors face compressed margins that limit design budget expansion despite regulatory redesign mandates. Oita and Kumamoto prefectures concentrate glass container manufacturing that feeds specialized substrate engineering demand.
Hokkaido
Dairy and seafood processors in Sapporo metropolitan area prioritize shelf stability engineering for cold-chain distribution packaging. Geographic isolation elevates logistics cost sensitivity, constraining premium design service procurement for commodity product lines. Local brands target domestic tourism retail channels with aesthetic-intensive graphic systems leveraging regional identity.
Japan Packaging Design Services Market Competitive Landscape
Capability concentration sits with heritage-rooted aesthetic specialists; scale advantage sits with cross-media campaign integrators. The market structures around three tiers: Tokyo-based premium boutiques commanding structural engineering premiums, integrated agency networks bundling physical-digital activation, and material-specific technical specialists occupying narrow fee niches. Dominant competitive moves include geographic expansion into underpenetrated Kansai manufacturing corridors and portfolio diversification into regulatory compliance automation services.
Within the heritage aesthetic tier, Nippon Design Center anchors premium account relationships through Japanese aesthetic system expertise. Dentsu Group Inc. exemplifies cross-media campaign integration, merging physical shelf presence with digital activation. GK Graphics occupies a technical niche commanding elevated fees for glass and metal substrate engineering. These three represent distinct archetype positions rather than direct substitution competitors.
| Leading Market Players |
|---|
| Nippon Design Center |
| Takram Co., Ltd. |
| NOSIGNER |
| Nendo |
| CINRA, Inc. |
| Dentsu Group Inc. |
| GK Graphics |
| Winkreative |
| Frog Design |
| Others |
Pricing and Supply Chain Analysis
Specialty substrate suppliers in Germany and Japan anchor the upstream cost structure for glass and metal packaging design, concentrating margin capture among Tokyo-based agencies with captive prototyping equipment and JIS certification capabilities. Design fees stratify based on material engineering complexity rather than creative output alone, with structural work commanding premiums that reflect equipment amortization and regulatory verification overhead.
Pricing Analysis
After-sales revenue from lifecycle redesign contracts and compliance retainer agreements drives lifetime value for established agencies. Project-based pricing dominates, with cost-plus arrangements for complex multi-substrate engineering and fixed fees for template-driven label updates. Price differentiation rests on JIS certification tier and prototyping equipment ownership, with certified Tokyo boutiques absorbing minimal negotiation pressure from premium cosmetics brands. Cost compression in mid-market structural design is intensifying because generative design software collapses iteration timelines, eroding hourly engineering rates. Regional food processors in Hokkaido and Kyushu exhibit highest price sensitivity, while Tokyo-based multinational cosmetics houses absorb premium fees with limited procurement friction.
Supply Chain Analysis
Upstream feedstock for specialty packaging substrates draws from Germany, Japan, and select Italian suppliers for premium glass and engineered metal closures. Raw material dependencies include borosilicate glass formulations, aluminum alloy specifications for pharmaceutical closures, and high-barrier coated papers for foodservice transitions. Single-source vulnerability concentrates in precision molding equipment for structural prototyping, where German and Japanese OEMs control lead times. Distribution runs through direct agency-client relationships for premium commissions, with mid-market procurement increasingly consolidating through design-build contractors serving Osaka and Kyoto manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
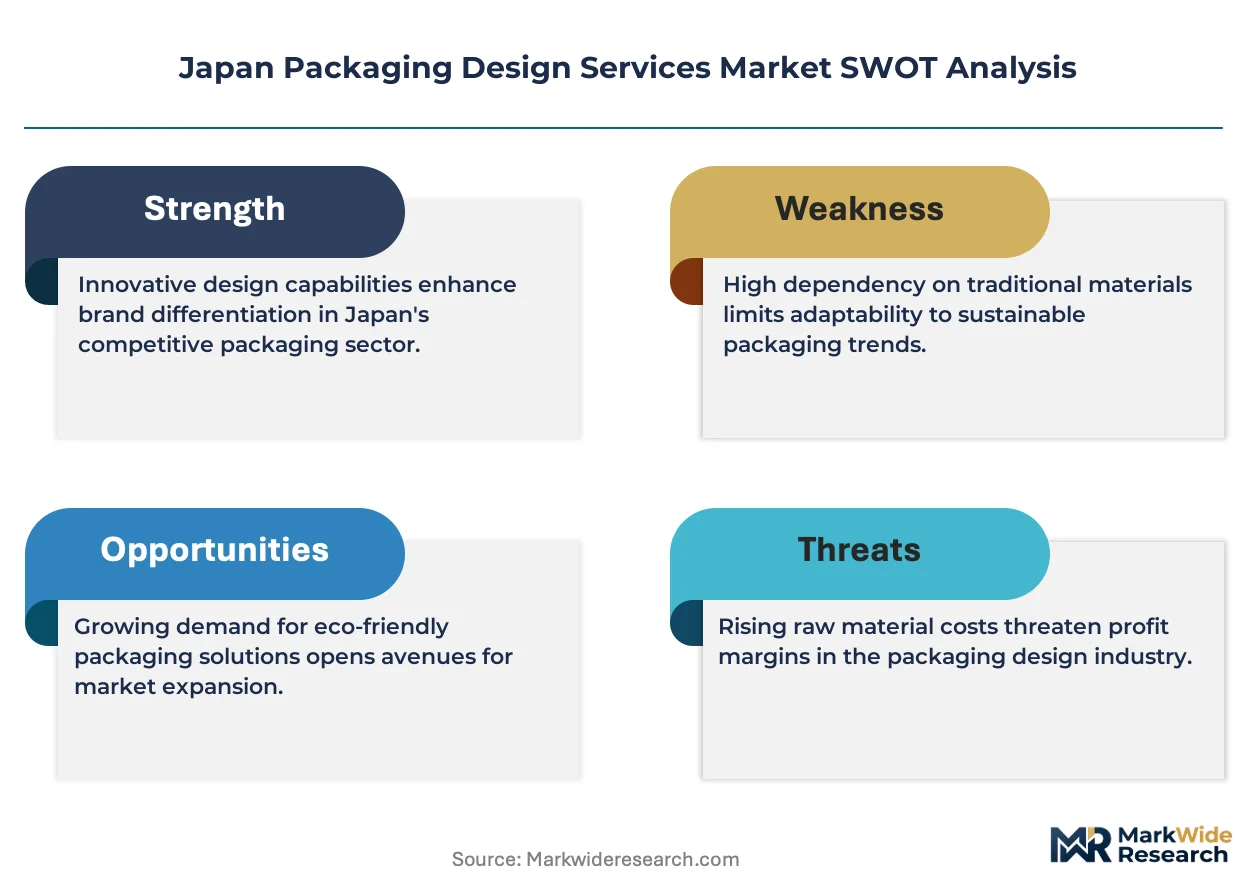
Fragmentation across regulatory complexity tiers and material specialization creates niche opportunities as METI guidelines force simultaneous compliance and sustainability redesigns. Procurement consolidation around integrated service bundles rewards capability breadth over pure creative reputation.
For Market Incumbents: Harden structural engineering moats through captive prototyping equipment investments and JIS certification automation that compresses verification timelines. Consolidate label design capabilities to capture pharmaceutical compliance mandates before specialist boutiques scale. Vertical integration into lifecycle assessment consulting offsets margin pressure from generative design commoditization of basic structural iteration. For New Entrants and Emerging Players: Build out regulatory compliance automation services as a wedge into established food and beverage accounts facing Plastic Resource Circulation Act redesign deadlines. Osaka and Kyoto manufacturing corridors offer underpenetrated white space for premium structural commissions from regional brands. A go-to-market angle anchored in EU REACH and CSRD export packaging expertise captures procurement attention from Nagoya automotive and medical device suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-size agencies with material-specific engineering capabilities in glass or metal substrates and existing JIS certification infrastructure. Long-term viability across the analysis window favors specialists who embed sustainability verification into core workflows rather than pure aesthetic boutiques. The signal to watch is amendment timing to extended producer responsibility frameworks, which will reshape fee structures for compliance-intensive design categories and accelerate procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Automation | Captures METI and PMDA-driven redesign mandates from pharmaceutical and electronics verticals. |
| Material-Specific Engineering Acquisition | Consolidates glass and metal substrate expertise that commands premium structural design fees. |
| Kansai Geographic Expansion | Penetrates Osaka and Kyoto manufacturing corridors with lower competitive density than Tokyo. |
| Digital-Physical Convergence Service Layer | Merges shelf presence with activation campaigns for higher-fee integrated procurement bundles. |
| Sustainability Verification Integration | Embeds lifecycle assessment capabilities that elevate technical validation in vendor selection. |
Research Methodology
The analysis maps structural design, graphic design, label design, and prototyping sub-sectors, each validated through packaging procurement managers at food and cosmetics brands, regulatory affairs leads navigating METI guidelines, and design agency principals. Primary interviews with JIS certification specialists and lifecycle assessment consultants combined with secondary validation from METI policy documents, PMDA packaging safety filings, and customs records tracking specialty substrate imports. Bottom-up service-type revenue builds and top-down end-user spend allocation triangulate market sizing.
Assumption sets held regulatory amendment timelines and generative design adoption curves fixed while varying export demand intensity and Kansai regional penetration rates. Segmentation dimensions modeled include service type, material substrate, end-user vertical, and design complexity tier across the projection horizon. CAGRs derive from regression against historical procurement cycle data and policy-driven redesign mandate schedules, with inputs from electronics export volume trajectories and pharmaceutical labeling regulatory expansion.
Sensitivities concentrate around Plastic Resource Circulation Act enforcement intensity and generative design software commoditization pace. Forecasts reflect documented assumptions about procurement consolidation behavior and sustainability verification embedding timelines. Cross-checking against METI industrial statistics and JIS certification issuance records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
Caps and Closures Market
Packaging
Compostable Food Service Tray Market
Packaging
APAC Glass Bottles/Containers Market
Packaging
Secondary Packaging Market
Packaging
Global Plastic Container Market
Packaging
Morocco Plastic Caps and Closures Market
Packaging
Decal Paper Market
Packaging
Retail E Commerce Packaging Market
Packaging
Global Seam Sealing Tapes Market
Packaging
Hot-Melt Based Packaging Market
Packaging
Beverage Caps and Closures Market
Packaging
Europe Flexible Plastic Packaging Market
Packaging
India BOPP Films Market
Packaging
Thermal Impulse Sealers Market
Packaging
Case Packing Machines Market
Packaging
Global Rigid Bulk Packaging Market