
 Stick Pouches Packaging Market | 2026-2036
Stick Pouches Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Stick Pouches Packaging Market Outlook
EU Packaging and Packaging Waste Regulation is consolidating the cost-of-entry calculus for European stick pouch converters. Amcor plc leverages its multi-layer extrusion network to sustain compliance-led supply contracts across France and Italy. Constantia Flexibles anchors its position through aluminum-laminate specialization for pharmaceutical powders. ProAmpac competes via biodegradable film R&D pipelines targeting German private-label food brands.
Stick pouches are narrow-format flexible packages, typically 10–40 mm in width, formed from laminated films of PET, aluminum, or bio-based polymers through horizontal or vertical form-fill-seal processes, designed for single-serve dispensing of liquids, powders, or gels. The liquid segment dominates current volume due to energy drink and nutraceutical concentrate demand, while biodegradable materials represent the fastest-growing structural category as converters respond to ECHA-enforced sustainability mandates. Heat seal closure types occupy the margin-rich pharmaceutical tier, whereas tear notch designs saturate mature food and household applications.
FDA 21 CFR food contact notifications, EU REACH substance restrictions, and EFSA migration limits collectively shape material selection and laminate architecture for stick pouch suppliers seeking transatlantic market access. Germany's national packaging regulator enforces stricter sorting and recycling quotas than baseline EU directives, forcing imported pouches to meet elevated verification standards. Stakeholders must monitor how ECHA's expanding restriction candidate list and FDA's evolving bio-based polymer guidance interact to determine which laminate technologies retain commercial viability.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing converter margins while forcing laminate architecture redesigns across European supply chains. This single regulatory framework now determines which material technologies retain shelf access and which face phased obsolescence.
Growth Catalysts
- Aluminum-Composite Adoption:Single-serve nutraceutical brands in Germany are expanding orders for aluminum-composite stick packs as oxygen barrier requirements tighten for probiotic and omega-3 formulations.
- REACH Compliance Mandates:ECHA-enforced sustainability directives are accelerating biodegradable film qualification programs as converters race to substitute petroleum-derived sealant layers.
- Southeast Asian Manufacturing:Contract manufacturers serving Japanese cosmetic houses are scaling capacity in Thailand and Vietnam to capture regional beauty concentrate demand.
Market Restraints
- Aluminum Price Volatility:Input cost swings for rolled aluminum foil are destabilizing laminate pricing structures for pharmaceutical powder applications.
- German Sorting Quotas:Stricter recycling verification standards enforced by Germany's national packaging regulator are elevating compliance costs for imported flexible packaging.
- Multi-Layer Recyclability:Technical limitations in separating PET-aluminum-polyethylene laminates are blocking circular economy certification for mainstream stick pouch formats.
Strategic Opportunities
- Indian Nutraceutical Expansion:Underpenetrated single-serve supplement markets in Maharashtra and Gujarat offer white space for portion-controlled powder formats.
- CSRD-Driven Disclosure:The EU Corporate Sustainability Reporting Directive is creating procurement preference for packaging suppliers with verified lifecycle data.
- E-Commerce Sampling Channels:Direct-to-consumer beauty subscription boxes are emerging as a high-margin distribution channel for trial-size gel and serum sticks.
Industry Challenges
- Migration Testing Bottlenecks:EFSA migration limit verification timelines are extending new laminate qualification cycles by eight to fourteen months.
- Legacy Equipment Retrofit Costs:Horizontal form-fill-seal lines require substantial capital expenditure to handle bio-based polymer seal temperatures without compromising throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stick Pouches Packaging Market |
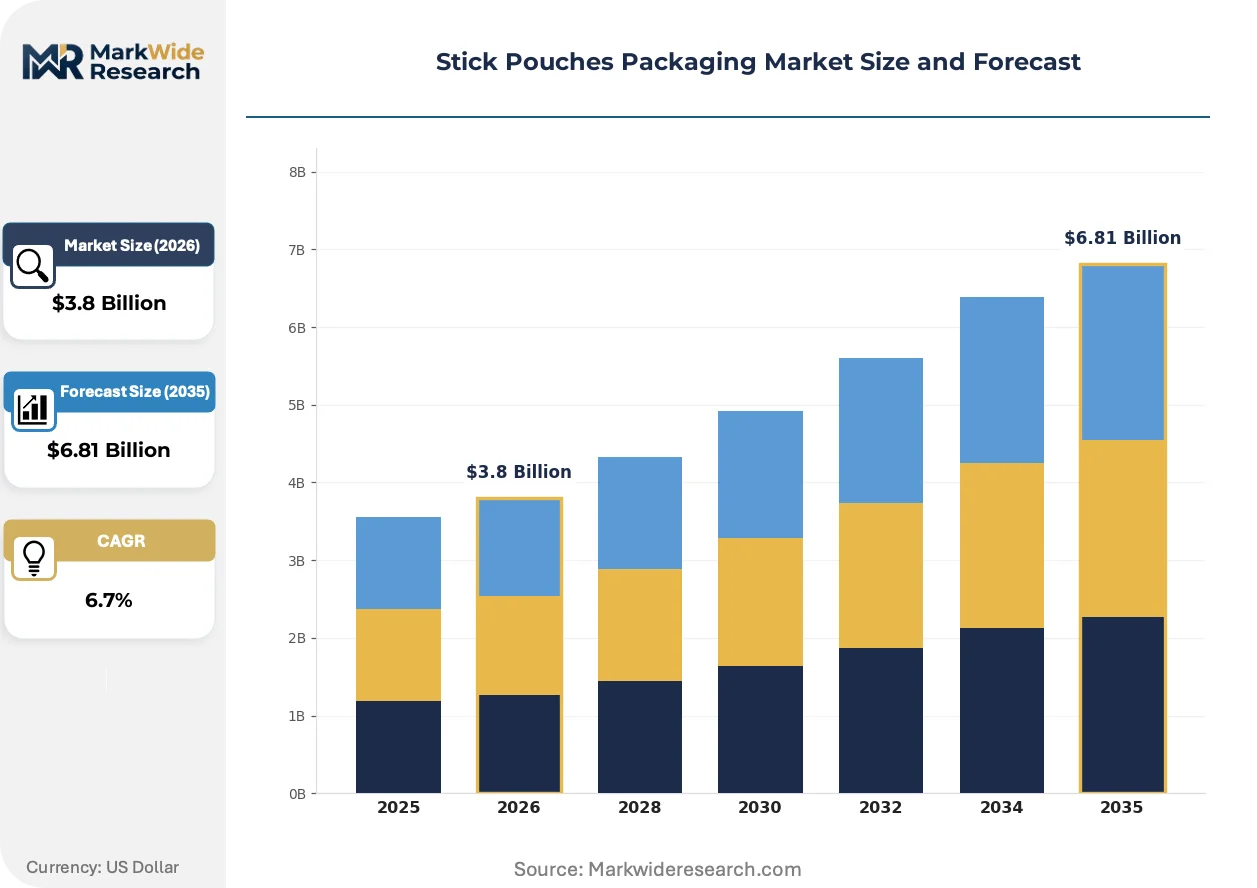
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granules, Gel Closure Type: Zip Lock, Twist Off, Tear Notch, Heat Seal Material: Plastic, Aluminum, Biodegradable, Composite End User: Food, Cosmetics, Pharmaceuticals, Household |
| Companies Covered | Amcor plc, Constantia Flexibles, Glenroy, Inc., ePac Holdings, LLC, Huhtamaki, ProAmpac, Losan Pharma, Catalent, Inc., IMPAK CORPORATION, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stick Pouches Packaging Market Strategic Shifts
Material science advances and regulatory disclosure requirements are converging to reshape competitive positioning across the stick pouch value chain. Three distinct vectors now determine which converters capture premium contract volumes.
Water-based barrier coatings are decentralizing supply chain control over high-performance oxygen and moisture protection. Nutraceutical contract manufacturers in Italy and Spain are qualifying these coatings at pilot scale to reduce aluminum foil dependency. This technology is decentralizing laminate sourcing decisions from traditional petrochemical suppliers to specialty chemical formulators with coating deposition expertise.
REACH substance restrictions are compressing the approved chemical inventory for food-contact laminates across EU member states. The industrial consequence is forced reformulation of adhesive and sealant layers that have served the market for fifteen-plus years. Pharmaceutical powder applications face the steepest compliance burden, with converters in France and Italy accelerating bio-based adhesive trials to maintain EMA-aligned supply contracts.
Boutique cosmetic houses are consolidating purchase volumes with converters offering integrated design-to-delivery services. The traditional specification-bid-award cycle is compressing into collaborative development partnerships with shared mold investment. This pattern is most visible in Tokyo-Osaka corridors where Japanese beauty brands are embedding packaging engineers directly with Southeast Asian contract manufacturers.
Stick Pouches Packaging Market Segmentation
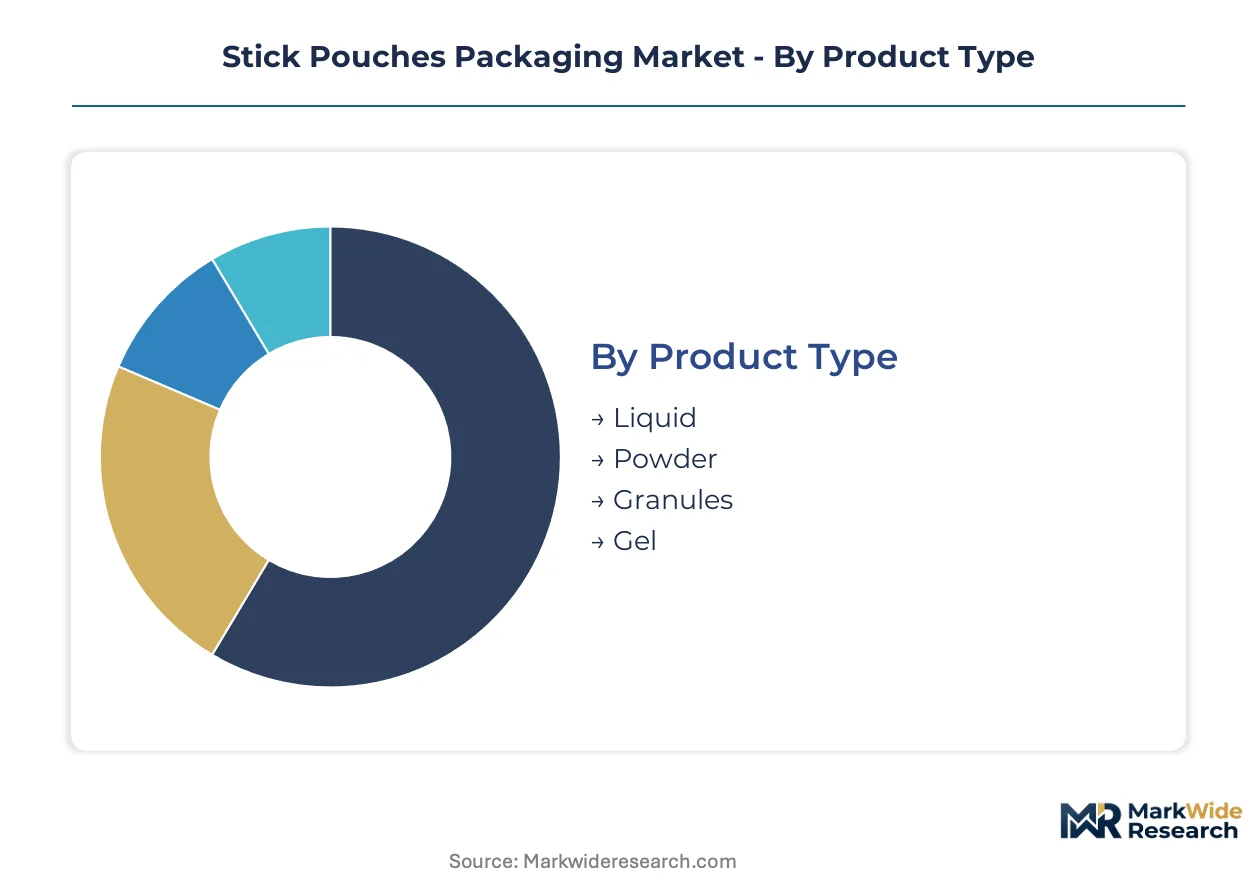
Stick pouch converters configure laminate architecture and sealing mechanisms around the physical state of contents, barrier requirements, and end-use regulatory exposure. Segmentation choices directly determine equipment investment cycles, material qualification timelines, and margin capture potential across pharmaceutical, nutraceutical, and cosmetic supply chains.
Product Type:
Upgrade cycles for form-fill-seal equipment track content viscosity and oxygen sensitivity, with liquid lines requiring the most frequent retrofit investment.
- Liquid:Energy drink concentrates and nutraceutical shots dominate current throughput. German private-label brands are expanding orders for 10–20 ml single-serve formats with extended shelf-life requirements.
- Powder:Probiotic and protein formulations require aluminum-composite barriers against moisture ingress. Southeast Asian contract manufacturers serving Japanese cosmetic houses are scaling dedicated powder lines in Thailand.
- Granules:Instant coffee and soup applications favor wider 30–40 mm formats with tear-notch dispensing. Italian converters maintain specialized granule-handling equipment for Mediterranean food brands.
- Gel:Beauty serums and topical pharmaceutical bases demand precision dosing accuracy. Tokyo-Osaka corridor cosmetic houses are embedding packaging engineers with Vietnamese contract manufacturers for gel stick development.
Liquid sits at the top of the volume ranking, with Gel climbing the fastest.
Closure Type:
Margin capture stratifies sharply by closure complexity, with pharmaceutical and cosmetic applications paying premiums for hermetic integrity.
- Heat Seal:Pharmaceutical powders and sensitive nutraceuticals require hermetic fusion of laminate layers. EMA-aligned supply contracts in France and Italy specify heat seal validation protocols exceeding baseline EU requirements.
- Tear Notch:Mature food and household applications saturate this low-cost design. German sorting quotas under the national packaging regulator are elevating recyclability verification costs for tear-notch laminates.
- Zip Lock:Reclosure functionality targets multi-dose cosmetic and household segments. Spanish converters are piloting bio-based zipper profiles to meet ECHA-enforced sustainability mandates.
- Twist Off:Child-resistant and senior-friendly variants serve OTC pharmaceutical applications. Swissmedic-aligned specifications in Switzerland require torque testing documentation for twist-off stick packs.
Heat Seal commands the premium tier by margin contribution, while Biodegradable materials are gaining share fastest among material categories.
Material:
Regulatory disclosure requirements under CSRD and REACH are compressing the approved chemical inventory for laminate construction.
- Composite:PET-aluminum-polyethylene laminates balance barrier performance with formability. Technical limitations in layer separation are blocking circular economy certification for mainstream formats.
- Biodegradable:Bio-based polymers and compostable sealants represent the steepest expansion trajectory. ECHA restriction candidate list expansion is accelerating converter qualification programs for petroleum-derived layer substitution.
- Aluminum:Rolled foil provides absolute oxygen and light barriers for pharmaceutical applications. Input cost volatility is destabilizing laminate pricing structures for powder formulations.
- Plastic:Mono-material polyethylene and polypropylene variants target improved recyclability. Germany's stricter recycling verification standards are forcing imported plastic-based pouches to meet elevated sorting quotas.
Composite retains the largest installed base, with Biodegradable expanding most quickly.
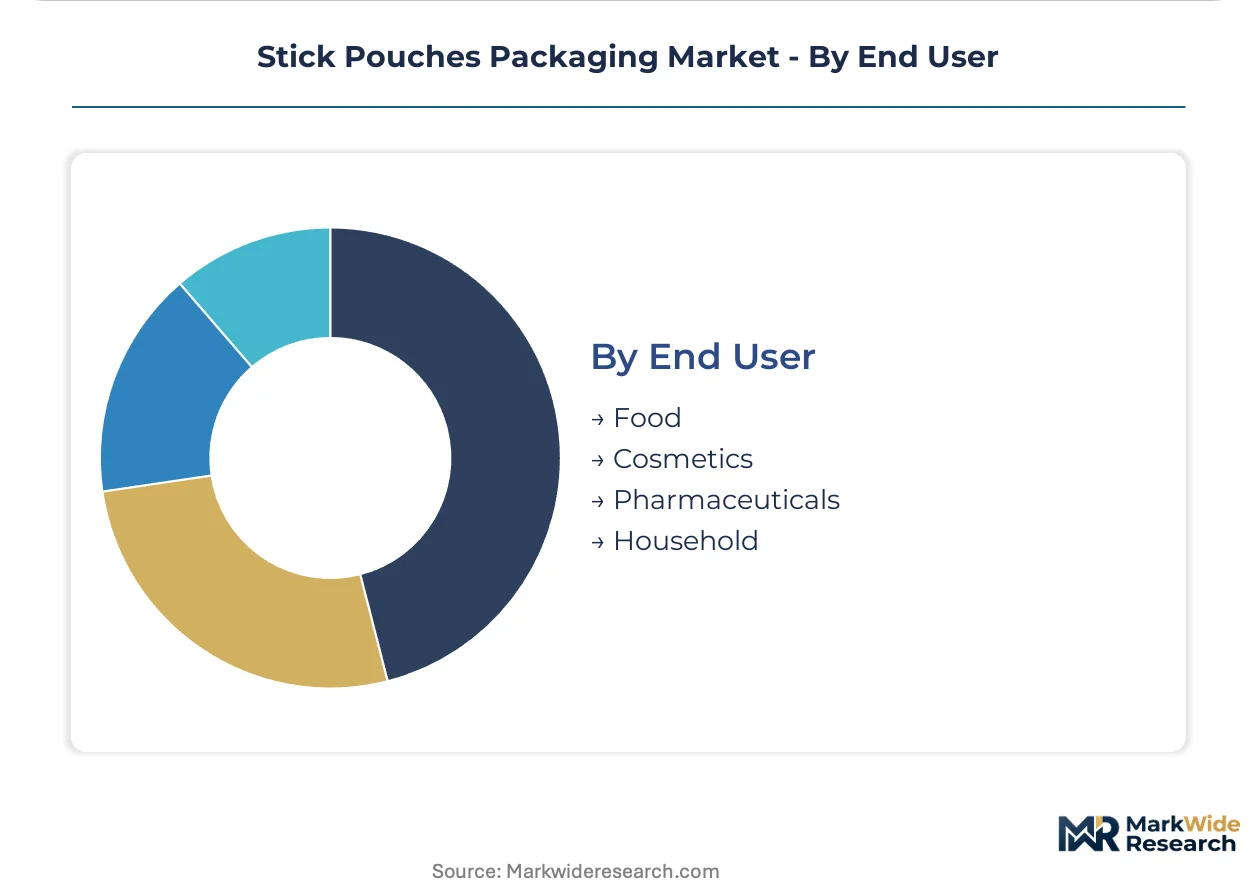
End User:
Procurement patterns diverge by regulatory exposure, with pharmaceutical and cosmetic buyers demanding extensive migration testing documentation.
- Pharmaceuticals:EFSA migration limit verification and EMA alignment dominate material selection. EFSA verification timelines are extending new laminate qualification cycles by eight to fourteen months.
- Cosmetics:Japanese beauty brands are consolidating volumes with converters offering integrated design-to-delivery partnerships. Southeast Asian contract manufacturers are capturing regional beauty concentrate demand through collaborative mold investment.
- Food:Energy drink and supplement concentrates drive liquid stick volume. Italian and Spanish nutraceutical contract manufacturers are qualifying water-based barrier coatings at pilot scale.
- Household:Detergent and cleaning agent applications favor cost-optimized tear-notch formats. Private-label German food brands are sourcing biodegradable alternatives through ProAmpac's R&D pipeline.
Food leads by unit volume, with Cosmetics posting the steepest growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized converter talent clusters in Germany, Japan, and the United States anchor the highest-value stick pouch production networks. These workforce concentrations sustain the technical laminate qualification and regulatory navigation capabilities that pharmaceutical and cosmetic brands demand.
Germany
Single-serve nutraceutical brands in Bavaria and North Rhine-Westphalia are expanding aluminum-composite stick pack orders as oxygen barrier requirements tighten for probiotic formulations. The national packaging regulator enforces stricter sorting and recycling quotas than baseline EU directives, elevating compliance verification costs for imported laminates. Munich-based converters maintain specialized equipment for pharmaceutical powder handling under EMA-aligned protocols.
United States
Energy drink concentrate brands and direct-to-consumer beauty subscription services in California and New York Metro drive liquid and gel stick pouch volume. FDA 21 CFR food contact notifications shape material selection architecture for suppliers seeking transatlantic market access. Chicago-area contract manufacturers serve national nutraceutical distributors with dedicated high-speed form-fill-seal lines.
Japan
Cosmetic houses in the Tokyo-Osaka corridor are consolidating purchase volumes through collaborative development partnerships with shared mold investment. METI standards and PMDA pharmaceutical packaging guidelines govern laminate qualification for beauty concentrate and topical applications. Vietnamese contract manufacturers serving Japanese brands are scaling gel stick capacity in Ho Chi Minh City industrial zones.
Italy
Nutraceutical contract manufacturers in Lombardy and Emilia-Romagna are qualifying water-based barrier coatings at pilot scale to reduce aluminum foil dependency. EFSA migration limit verification timelines extend new laminate qualification cycles by eight to fourteen months for pharmaceutical applications. Bologna-area converters maintain specialized granule-handling equipment for Mediterranean instant coffee and soup brands.
India
Underpenetrated single-serve supplement markets in Maharashtra and Gujarat offer white space for portion-controlled powder formats. FSSAI food safety standards and CDSCO pharmaceutical packaging regulations govern material selection for domestic and export-bound production. Mumbai-Pune industrial corridor converters are installing dedicated stick pouch lines to capture emerging nutraceutical contract manufacturing demand.
Stick Pouches Packaging Market Competitive Environment
The competitive structure tilts toward diversified packaging conglomerates with multi-layer extrusion capabilities and specialized pharmaceutical laminators with EMA-aligned qualification expertise. Tier-one players leverage backward integration into film production to control sealant layer specifications and migration testing documentation. Three archetypes dominate: global flexible packaging houses with regulatory compliance infrastructure, regional pharmaceutical specialists with validated cleanroom production, and emerging bio-based material innovators with compostable sealant pipelines. M&A activity concentrates on acquiring biodegradable film qualification capabilities, while capacity expansion targets Southeast Asian contract manufacturing clusters serving Japanese cosmetic demand.
Within the global flexible packaging tier, Amcor plc and Huhtamaki occupy positions defined by multi-territory extrusion networks and compliance-led supply contract maintenance across France, Italy, and Germany. Constantia Flexibles exemplifies the pharmaceutical-specialist archetype through aluminum-laminate concentration for powder applications requiring EMA validation. ProAmpac represents the sustainability-driven vector with biodegradable film development targeting German private-label food brand procurement preferences under tightening EU Packaging and Packaging Waste Regulation thresholds.
| Leading Market Players |
|---|
| Amcor plc |
| Constantia Flexibles |
| Glenroy, Inc. |
| ePac Holdings, LLC |
| Huhtamaki |
| ProAmpac |
| Losan Pharma |
| Catalent, Inc. |
| IMPAK CORPORATION |
| Others |
Value Chain & Pricing Dynamics
Specialized laminate extrusion technicians in Bavaria and North Rhine-Westphalia command wage premiums that widen spreads between pharmaceutical-grade and commodity stick pouch tiers. Labor-cost differentials between German precision-converter clusters and Southeast Asian contract manufacturing zones directly shape three-tier pricing architectures across the value chain.
Pricing Analysis
Bundled design-to-delivery services versus unbundled laminate-only supply splits the market into divergent pricing logics. Three-tier pricing structure across premium, standard, and economy levels reflects EMA-aligned certification status, volume scale, and migration testing documentation depth. Cost compression in standard-tier aluminum-composite laminates is intensifying because rolled foil input volatility destabilizes converter quoting confidence. Private-label food brands in Germany exhibit highest price sensitivity, while Tokyo-Osaka cosmetic houses prioritize hermetic integrity over unit economics.
Supply Chain Analysis
Workforce availability for qualified form-fill-seal operators concentrates in Germany, Japan, and the United States, anchoring high-value production networks. Raw material dependencies draw from rolled aluminum suppliers, petrochemical sealant producers, and bio-based polymer innovators. Single-source vulnerability in aluminum foil supply from specific rolling mills creates concentration risk for pharmaceutical powder applications. Distribution runs through converter-direct relationships with nutraceutical contract manufacturers, supplemented by regional distributor networks serving fragmented food and household segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU regulatory compliance costs and Southeast Asian manufacturing labor advantages, with German sorting quotas under the national packaging regulator elevating landed costs for imported laminates by compliance verification burdens.
For Market Incumbents: Anticipate REACH substance restriction expansions by accelerating bio-based adhesive qualification programs ahead of ECHA restriction candidate list updates. Backward integration into water-based barrier coating deposition capabilities defends margin position against aluminum price volatility. Prioritize capacity retention in Munich-area pharmaceutical cleanroom facilities where EMA-aligned validation expertise remains scarce.
For New Entrants and Emerging Players: Enter via Maharashtra and Gujarat nutraceutical contract manufacturing corridors where single-serve supplement penetration remains underdeveloped. Target powder-format stick pouches for probiotic and protein formulations requiring oxygen barrier performance. Pursue collaborative mold investment partnerships with Japanese cosmetic houses seeking Vietnamese production alternatives.
For Investors and Strategic Acquirers: Valuations sit cheapest among Italian and Spanish converters with water-based barrier coating pilot programs but limited EMA-aligned pharmaceutical validation. Long-term viability hinges on biodegradability certification pipelines and CSRD-driven procurement preference capture. Watch EFSA migration testing timeline extensions as inflection indicator for laminate qualification bottleneck severity.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Adhesive Qualification | ECHA REACH compliance mandates accelerate petroleum-derived layer substitution programs. |
| Water-Based Barrier Coating Scale-Up | Italian and Spanish nutraceutical contract manufacturers reduce aluminum foil dependency. |
| Southeast Asian Capacity Expansion | Thai and Vietnamese contract manufacturers capture Japanese cosmetic house gel stick demand. |
| EMA-Aligned Validation Investment | Munich-based converters maintain pharmaceutical powder handling certification advantages. |
| CSRD Lifecycle Data Disclosure | EU Corporate Sustainability Reporting Directive creates procurement preference for verified suppliers. |
Study Parameters
Coverage spans Germany, Japan, the United States, Italy, and India, with primary inputs from each territory's converter and contract manufacturing clusters. Research combined interviews with form-fill-seal equipment operators, laminate R&D directors, nutraceutical brand procurement managers, and regulatory affairs specialists with secondary validation from EU Packaging and Packaging Waste Regulation filings, ECHA restriction candidate list updates, FDA 21 CFR food contact notification databases, and FSSAI packaging standard disclosures. Bottom-up capacity and demand estimates triangulated against top-down macroeconomic drivers.
Rate-of-change decomposition across the analysis window segmented volume and value trajectories by product type, material category, closure mechanism, and end-use regulatory exposure. CAGRs derived from equipment installation pipelines, laminate qualification timelines, and contract manufacturing capacity announcements. Forecast inputs incorporated EFSA migration testing bottleneck durations and bio-based polymer seal temperature performance curves.
Inputs from converter financial disclosures and regulatory filing databases were available through the study window; gaps in real-time aluminum foil contract pricing and bio-based adhesive qualification success rates introduce uncertainty bands around laminate cost projections. Forecasts reflect documented assumptions regarding REACH enforcement intensity and CSRD disclosure adoption velocity. Material deviation in ECHA restriction candidate list expansion timing or FDA bio-based polymer guidance revision warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Wrap-Around Packers Market
Pouch
United States Pouch Packaging Market
Pouch
Spain Pouch Packaging Market
Pouch
Inflatable Pouches Market
Pouch
Cold Seal Lamination Pouch Market
Pouch
Egypt Pouch Packaging Market
Pouch
Ziplock Products Market
Pouch
Liquid Pouch Packaging Market
Pouch
Nigeria Pouch Packaging Market
Pouch
Telemetry Pouch Market
Pouch
Pouch-Bowl Packaging Market
Pouch
Global Pouches Packaging Market
Pouch
Rice Paper Stand Up Pouch Market
Pouch
United States Retort Pouches Market
Pouch
Bio PE Pouches Market
Pouch
GCC Retort Pouches Market