
 Collateral Ligament Stabilizer System Market | 2026-2036
Collateral Ligament Stabilizer System Market Size, Share, and Industry Trends Forecast 2026-2036
Collateral Ligament Stabilizer System Market Analysis
Buyer concentration across hospital procurement networks is rebalancing as integrated delivery networks consolidate purchasing authority while ambulatory surgery centers fragment into specialized buyers. Ossur leverages its Nordic manufacturing base to sustain premium positioning in ligament bracing. Stryker Corporation anchors its presence through orthopedic suite bundling. Arthrex specializes in arthroscopy-adjacent stabilization products that compete for surgeon preference.
Collateral ligament stabilizer systems are orthopedic devices engineered to restrict varus or valgus knee motion through mechanical bracing, typically employing hinge mechanisms with adjustable flexion-extension stops and composite shells molded from carbon fiber or thermoplastic polymers. These systems serve primary commercial purpose in post-injury mechanical protection and surgical reconstruction recovery, restoring joint stability while permitting controlled range-of-motion exercise. Braces incorporating adjustable hinge designs command the dominant margin pool due to customization premiums, while 3D-printed patient-specific supports represent the fastest-expanding technology segment as digital workflows reduce fabrication lead times. Compression technology applications in soft supports occupy mature volume positions with thinner margin profiles.
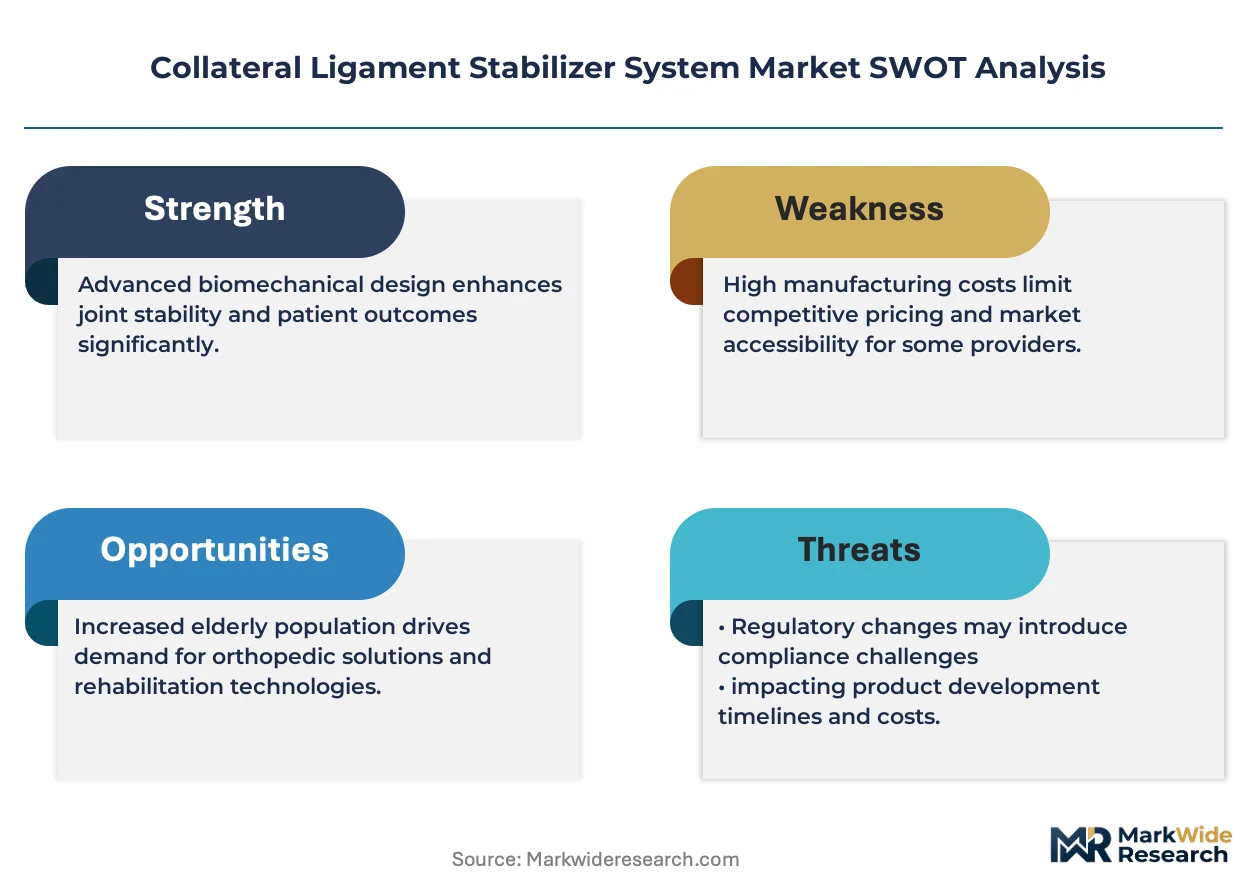
FDA 510(k) clearance pathways and EMA Medical Device Regulation conformity assessments govern market access, with both frameworks intensifying clinical evidence requirements for mechanical testing validation and biocompatibility screening under ISO 10993 protocols. These regulatory structures elevate R&D barriers for entrants while rewarding incumbents with established quality management systems and predicate device libraries. Stakeholders must monitor how evolving software-as-medical-device classifications affect smart-brace innovations with embedded sensor feedback loops.
Market Dynamics
Digital manufacturing workflows are compressing fabrication cycles for patient-specific collateral ligament stabilizers, forcing incumbent brace manufacturers to reconfigure production infrastructure or cede premium segments to point-of-care fabrication networks.
Growth Catalysts
- ISO 10993 biocompatibility protocols:Harmonized screening standards across FDA and EMA jurisdictions accelerate multi-market product launches for composite shell manufacturers.
- Professional sports medicine programs:Franchise medical directors demand hinge-mechanism braces with telemetric feedback, expanding addressable volume for sensor-integrated systems.
- Carbon fiber thermoplastic molding:Advanced polymer processing yields 40% weight reduction in functional braces, improving patient compliance during extended rehabilitation protocols.
Market Restraints
- Medical-grade polymer feedstock volatility:Carbon fiber and high-performance thermoplastic resin prices fluctuate with aerospace sector demand, compressing margin stability for molded shell producers.
- EMA MDR conformity assessment bottlenecks:Extended notified body review timelines delay European market entry for predicate-device-dependent manufacturers.
- Soft support compression garments:Elastic textile alternatives capture price-sensitive rehabilitation volumes, limiting brace penetration in primary care settings.
Strategic Opportunities
- Ambulatory surgery center expansion:Freestanding orthopedic facilities in the United States require same-day discharge protocols, creating demand for lightweight stabilizers with rapid fitting capability.
- Sensor-orthotic convergence:Embedded gyroscopic and pressure-sensing arrays enable remote monitoring integration with telehealth platforms.
- US FDA breakthrough device designation:Expedited review pathways for AI-enabled brace adjustment systems reward early movers in automated fitting technology.
Industry Challenges
- Biomechanical engineer talent scarcity:Specialized expertise in knee kinematics and orthotic hinge design concentrates in academic medical centers, limiting R&D scaling for mid-tier manufacturers.
- ISO 13485 quality management system certification:Documented process controls and risk management file maintenance demand sustained capital investment before commercial authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collateral Ligament Stabilizer System Market |
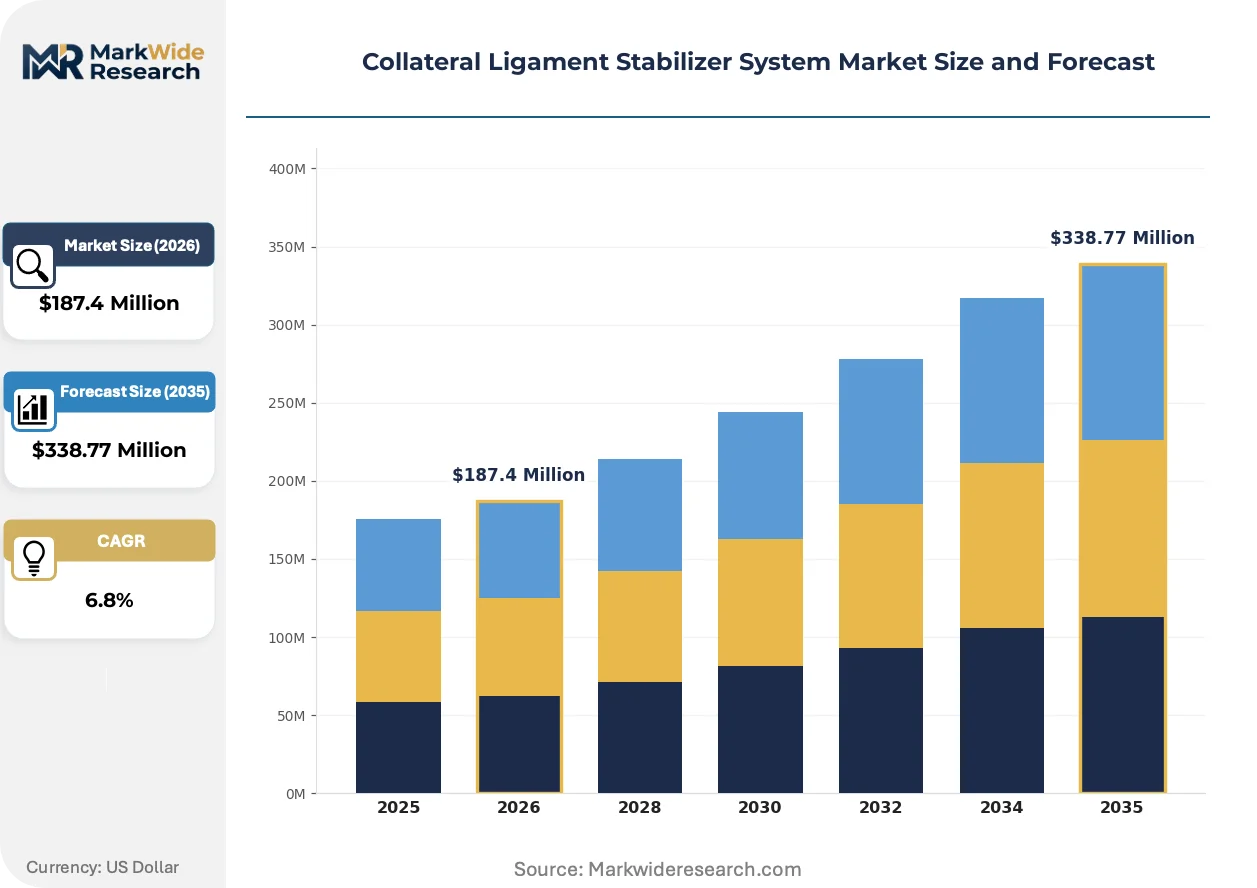
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Braces, Splints, Tapes, Supports Application: Sports Injuries, Rehabilitation, Post-operative Support, Pain Management End User: Clinics, Hospitals, Physiotherapy Centers, Home Care Technology: 3D Printing, Compression Technology, Adjustable Design, Flexible Materials |
| Companies Covered | Ossur, Stryker Corporation, Arthrex, Inc., Medtronic plc, Orthofix Medical, Inc., DePuy Synthes, Enovis Corporation, Smith & Nephew plc, Bauerfeind, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collateral Ligament Stabilizer System Market Emerging Trajectories
Point-of-care manufacturing technologies are redistributing production authority away from centralized fabrication facilities, enabling clinic-level customization while disrupting traditional brace supply relationships.
Additive manufacturing with selective laser sintering of medical-grade nylon is decentralizing production of patient-specific stabilizer shells. Orthopedic clinics in the United States and Germany are installing in-house 3D printing capacity, cutting delivery times from three weeks to 48 hours. This shift compresses inventory carrying costs for traditional distributors while elevating digital design competency requirements among clinical staff.
EMA Medical Device Regulation Article 10 clinical evidence mandates are intensifying post-market surveillance obligations for mechanical brace manufacturers. Companies must now maintain periodic safety update reports and vigilance systems that track device performance across distributed patient populations. Small-to-mid scale manufacturers without established quality infrastructure face exclusion from European procurement networks.
Hospital procurement departments are consolidating orthopedic device purchasing through integrated delivery networks, unbundling brace acquisition from traditional surgeon preference protocols. United States health systems now mandate value-analysis committee review for stabilizer selections above defined price thresholds. This behavioral shift elevates standardization pressure on manufacturers while compressing margins for premium-positioned hinge mechanisms.
Collateral Ligament Stabilizer System Market Segmentation
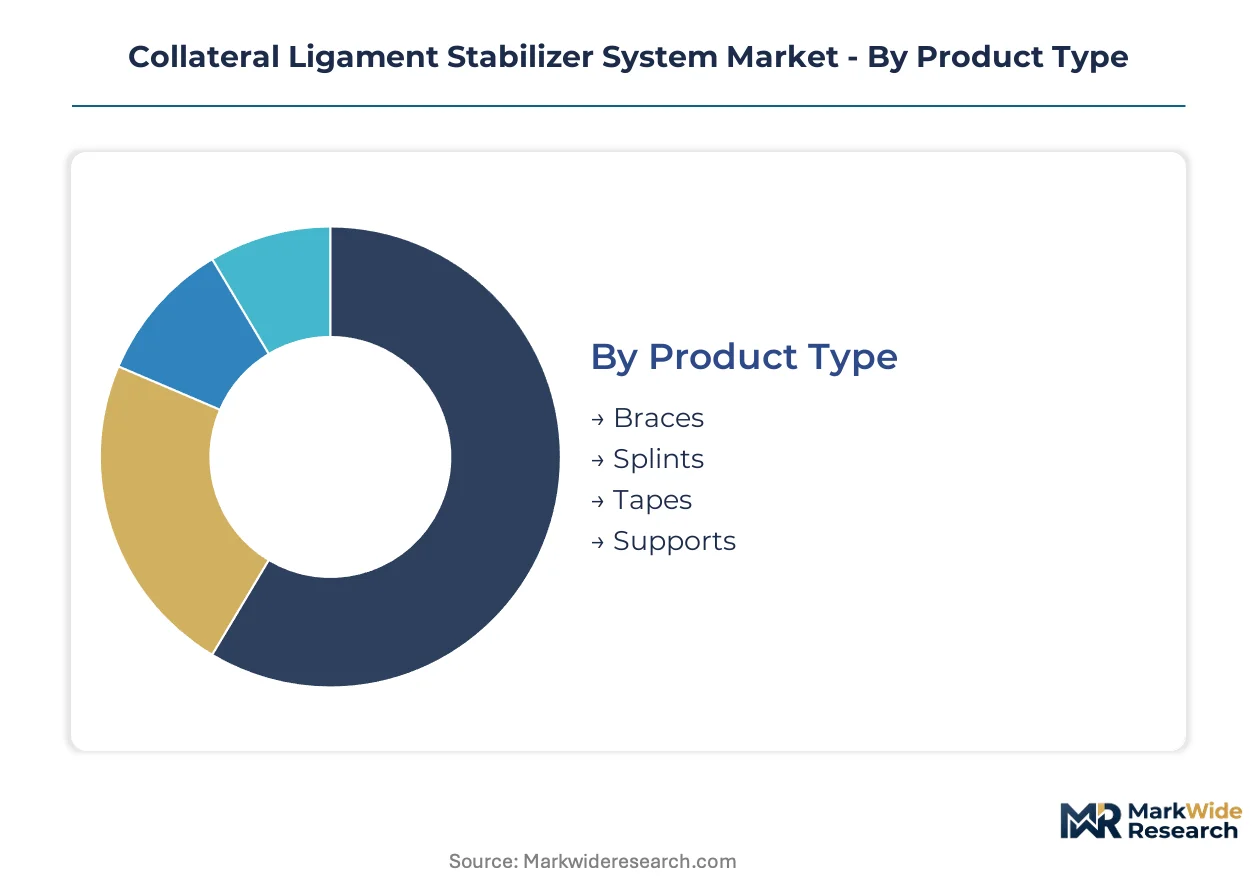
Collateral ligament stabilizer systems fragment across multiple technical and commercial dimensions. Product architecture determines whether devices function as standalone mechanical braces or integrate into broader orthopedic care protocols. Understanding segment boundaries clarifies where manufacturers compete on specification depth versus price accessibility.
Product Type:
Mechanical integration depth varies sharply: hinge-equipped braces operate as standalone therapeutic systems, while tapes and soft supports embed within multimodal treatment regimens.
- Braces:Rigid composite shells with calibrated hinge mechanisms deliver varus-valgus restraint through adjustable flexion-extension stops. Orthopedic centers in the United States prioritize these for post-surgical reconstruction protocols, with procurement committees now mandating value-analysis review above threshold pricing. Volume placements concentrate in braces; the faster expansion belongs to patient-specific configurations enabled by digital fabrication workflows.
- Splints:Semi-rigid thermoplastic constructs immobilize the knee through circumferential molding, typically deployed in acute injury phases before progressive mobilization. German trauma clinics favor splints for same-day discharge pathways in ambulatory settings, though EMA MDR conformity assessments have extended authorization timelines for new polymer formulations.
- Tapes:Elastic adhesive strips provide proprioceptive feedback and mild mechanical support without joint axis control. Australian sports medicine programs integrate taping into pitch-side emergency response, where immediate application precedes formal brace fitting.
- Supports:Soft compression garments with integrated stays offer graduated pressure distribution for chronic instability management. Retail pharmacy channels in Japan dominate distribution, capturing price-sensitive volumes outside reimbursed care pathways.
Revenue pools stratify by mechanical complexity: rigid hinge systems command premium positioning, while elastic alternatives compete on accessibility.
Application:
Clinical setting determines whether stabilizers serve definitive therapeutic roles or adjunctive support functions across the care continuum.
- Sports Injuries:Acute collateral ligament trauma in professional athletics demands rapid-return protocols combining mechanical protection with telemetry-enabled monitoring. Franchise medical directors in North American leagues specify sensor-integrated braces that feed data into athlete management platforms, creating procurement concentration around connected device ecosystems.
- Rehabilitation:Progressive loading protocols require staged mechanical support that transitions from rigid immobilization through dynamic assistance. Physiotherapy networks in the United Kingdom emphasize adjustable designs that permit clinician-controlled range-of-motion progression without device replacement.
- Post-operative Support:Surgical reconstruction recovery mandates biomechanical protection during graft incorporation phases. Hospital procurement consolidation through integrated delivery networks has unbundled brace selection from individual surgeon preference in United States health systems.
- Pain Management:Chronic ligamentous laxity drives demand for low-profile supports that enable daily activity continuation. Home care channels in Canada capture these volumes through direct-to-consumer distribution, bypassing institutional procurement entirely.
Institutional procurement dominates post-operative and sports medicine segments; rehabilitation and pain management applications fragment across provider types.
End User:
Site-of-care economics reshape demand specifications: acute settings prioritize clinical efficacy metrics, while decentralized care emphasizes patient self-management and cost containment.
- Clinics:Orthopedic and sports medicine clinics require rapid-fitting capability with inventory flexibility across multiple injury presentations. Point-of-care 3D printing adoption in German and United States clinic networks is compressing delivery timelines for custom-molded stabilizers.
- Hospitals:Inpatient and surgical settings demand predicate-device-cleared systems with established quality management documentation. FDA 510(k) clearance pathways govern United States hospital procurement, with value-analysis committees increasingly standardizing selections across health system footprints.
- Physiotherapy Centers:Rehabilitation-focused facilities prioritize adjustable mechanisms that support progressive mobilization protocols without device exchange. Australian private practice networks show early adoption of sensor-integrated systems for remote patient monitoring integration.
- Home Care:Patient-directed use emphasizes intuitive application and maintenance without clinical supervision. Japanese retail pharmacy distribution and North American e-commerce channels capture these volumes, with price sensitivity limiting penetration of premium hinge mechanisms.
Hospital and clinic procurement concentrates premium product placements; home care channels expand volume through accessible price positioning.
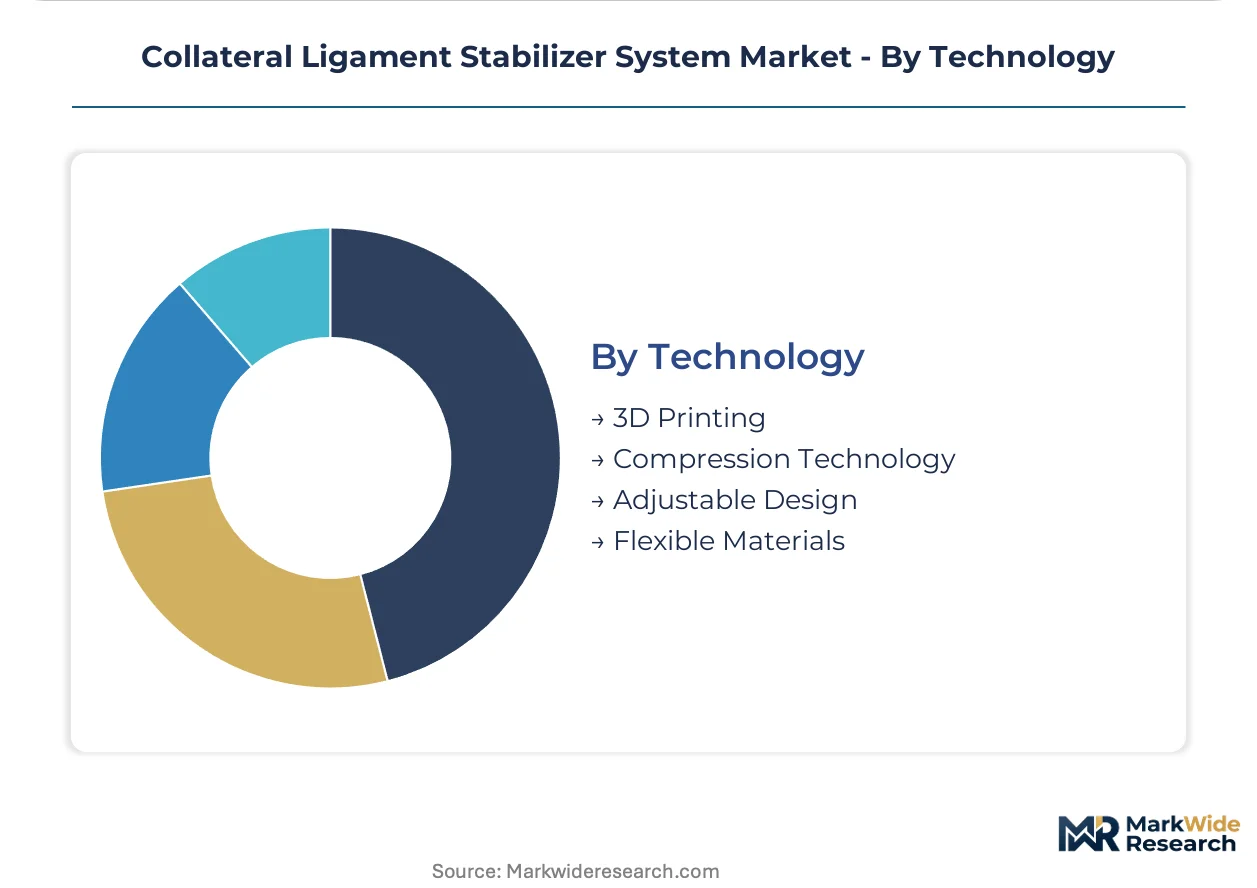
Technology:
Manufacturing methodology determines production scalability, customization depth, and regulatory pathway complexity across the technology portfolio.
- 3D Printing:Selective laser sintering of medical-grade nylon enables patient-specific geometry derived from anatomical scanning. United States and German orthopedic clinics installing in-house fabrication capacity are compressing delivery from weeks to 48 hours, redistributing production authority from centralized manufacturers to point-of-care networks.
- Compression Technology:Knitted elastic textiles with graduated pressure zones provide proprioceptive feedback without mechanical joint control. Mature manufacturing processes in East Asian textile centers yield thin margin profiles, limiting R&D investment in performance differentiation.
- Adjustable Design:Hinge mechanisms with tool-free flexion-extension stop modification accommodate staged rehabilitation progression. Stryker Corporation and Ossur anchor competitive positioning through proprietary hinge geometries protected by predicate device libraries.
- Flexible Materials:Advanced thermoplastic elastomers and carbon fiber composites reduce device mass while maintaining torsional rigidity. Aerospace sector demand volatility for carbon fiber feedstock creates margin pressure for molded shell producers.
Adjustable hinge mechanisms dominate current revenue; additive manufacturing platforms are climbing the fastest as digital workflows mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration for collateral ligament stabilizer systems tilts heavily toward orthopedic centers with embedded sports medicine programs. United States health systems and German clinic networks currently drive the bulk of premium hinge-mechanism demand. Regulatory divergence between FDA 510(k) pathways and EMA MDR assessments is fragmenting go-to-market timelines across jurisdictions.
United States
Integrated delivery networks in Texas and California consolidate brace purchasing through value-analysis committees, unbundling selection from individual surgeon preference. FDA 510(k) clearance predicates govern hospital procurement, with breakthrough device designations accelerating review for sensor-integrated systems. The Cleveland Clinic and Mayo Clinic anchor demand for patient-specific 3D-printed stabilizers with 48-hour fitting capability.
Germany
Ambulatory surgery centers in Bavaria and North Rhine-Westphalia require rapid-discharge protocols that favor lightweight splints with same-day fitting. EMA MDR Article 10 clinical evidence mandates extend conformity assessment timelines for new polymer formulations. Berlin and Munich clinic networks lead European adoption of in-house selective laser sintering for custom-molded shells.
Japan
Retail pharmacy channels in Tokyo and Osaka capture price-sensitive volumes for soft compression supports outside reimbursed care pathways. PMDA regulatory frameworks prioritize biocompatibility documentation under ISO 10993 protocols for imported hinge mechanisms. The Kansai region concentrates domestic manufacturing of knitted elastic textiles with graduated pressure zones.
Australia
Private physiotherapy practices in Sydney and Melbourne integrate sensor-orthotic systems for remote patient monitoring during rehabilitation protocols. TGA conformity assessments align with ISO 13485 quality management requirements for mechanical brace authorization. Sports medicine programs in Queensland drive demand for pitch-side taping applications preceding formal brace fitting.
United Kingdom
NHS procurement frameworks in London and Manchester emphasize adjustable designs supporting staged range-of-motion progression without device exchange. MHRA post-Brexit regulatory pathways maintain alignment with MDR clinical evidence standards for mechanical testing validation. The Midlands region concentrates orthopedic manufacturing supply relationships serving European export markets.
Collateral Ligament Stabilizer System Market Vendor Landscape
United States producers anchor premium-tier positioning through orthopedic suite bundling; Nordic and German specialists hold fabrication expertise in composite molding and hinge calibration. Market structure concentrates around predicate-device libraries that accelerate regulatory clearance, with mid-tier manufacturers facing exclusion from consolidated procurement networks. Three archetypes dominate: diversified orthopedic conglomerates with brace-as-accessory positioning, pure-play stabilization specialists with digital fabrication integration, and textile-centric soft support manufacturers competing on retail accessibility. Competitive moves center on point-of-care manufacturing partnerships and sensor-orthotic technology licensing.
Among diversified orthopedic conglomerates, Stryker Corporation and Ossur occupy positions exemplifying contrasting geographic anchoring strategies. Stryker leverages its United States health system relationships to bundle stabilizer procurement within broader orthopedic device contracts. Ossur represents Nordic manufacturing-based premium positioning sustained through carbon fiber thermoplastic processing capabilities. Arthrex sits within the arthroscopy-adjacent specialization tier, competing for surgeon preference through stabilization products integrated with minimally invasive surgical workflows.
| Leading Market Players |
|---|
| Ossur |
| Stryker Corporation |
| Arthrex, Inc. |
| Medtronic plc |
| Orthofix Medical, Inc. |
| DePuy Synthes |
| Enovis Corporation |
| Smith & Nephew plc |
| Bauerfeind |
| Others |
Supply Flow & Price Mechanics
Integrated delivery network consolidation in United States health systems is compressing brace procurement timelines and mandating value-analysis committee oversight above threshold pricing, forcing manufacturers to absorb certification costs or cede hospital contracts to predicate-device incumbents with established quality documentation.
Pricing Analysis
Volume pools concentrate in soft compression supports with thin margin profiles, while premium pools attach to hinge-equipped braces with sensor integration and patient-specific 3D-printed configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by mechanical complexity and customization depth, with FDA 510(k) clearance tier and carbon fiber shell grade serving as primary differentiation drivers. Pricing pressure stems from aerospace sector demand volatility for carbon fiber feedstock, which compresses molded shell producer margins. Ambulatory surgery centers and home care channels exhibit highest price sensitivity, while orthopedic centers anchor premium positioning.
Supply Chain Analysis
Reverse logistics for brace refurbishment and hinge mechanism recalibration flow through manufacturer-authorized service centers in Germany and the United States, capturing value from post-warranty devices. Production concentrates in China for knitted elastic textiles, Germany for selective laser sintering equipment and medical-grade nylon feedstock, and the United States for carbon fiber thermoplastic molding. Supply chains draw from carbon fiber resin, medical-grade thermoplastic polymers, and embedded sensor arrays. Single-source vulnerability concentrates in aerospace-linked carbon fiber suppliers. Distribution runs through orthopedic clinic networks, hospital procurement committees, and retail pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomechanical engineer talent scarcity concentrates in academic medical centers, creating a supply-constrained environment where manufacturers compete for limited hinge design expertise and fabrication competency, propping pricing for premium-tier patient-specific configurations.
For Market Incumbents: Anchor market position through backward integration into carbon fiber thermoplastic molding capacity and point-of-care 3D printing partnerships that compress delivery timelines. Predicate device libraries accelerate FDA 510(k) clearance pathways, defending against mid-tier manufacturers lacking established quality management systems. ISO 13485 certification investment remains essential for European market access under EMA MDR Article 10 mandates. For New Entrants and Emerging Players: FDA breakthrough device designation for AI-enabled brace adjustment systems opens a window for automated fitting technology specialists to bypass traditional predicate-device dependencies. White-space targets concentrate in sensor-orthotic convergence for remote patient monitoring and ambulatory surgery center lightweight stabilizers with rapid fitting capability. Direct-to-home care channel penetration via e-commerce platforms offers the most penetrable go-to-market angle outside consolidated hospital procurement networks. For Investors and Strategic Acquirers: The window for entry favors pure-play stabilization specialists with digital fabrication integration and established ISO 10993 biocompatibility documentation. Long-term viability hinges on point-of-care manufacturing partnerships that redistribute production authority from centralized facilities to clinic-level networks. Watch EMA MDR conformity assessment timeline compression as the inflection signal for European market re-entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Care 3D Printing Partnership | Cleveland Clinic and Mayo Clinic installations compress delivery from weeks to 48 hours, redistributing production authority. |
| Sensor-Orthotic Technology Licensing | Telemetric feedback integration with athlete management platforms expands addressable volume for professional sports medicine programs. |
| FDA Breakthrough Device Designation Pursuit | Expedited review pathways reward early movers in AI-enabled brace adjustment systems with automated fitting capability. |
| ISO 13485 Quality Management Certification | Documented process controls satisfy EMA MDR clinical evidence mandates for European procurement network access. |
| Carbon Fiber Thermoplastic Backward Integration | In-house polymer processing mitigates aerospace sector demand volatility and protects margin stability for molded shell producers. |
Methodological Framework
Document review covered FDA 510(k) clearance databases, EMA Medical Device Regulation submission records, and ISO 10993 biocompatibility protocol documentation, complemented by interviews with orthopedic surgeons, hospital value-analysis committee members, biomedical engineers specializing in knee kinematics, and sports medicine franchise medical directors. Secondary validation drew from hospital procurement databases, GPO contracts, and CMS Medicare reimbursement schedules. Bottom-up demand modeling across patient-specific configurations, adjustable hinge mechanisms, and compression technology segments triangulated with top-down market sizing from manufacturer revenue disclosures.
Segment-level projections across product architecture, clinical application, end-user site-of-care, and manufacturing technology dimensions fed aggregate market estimates across the projection horizon. CAGRs derived from regression analysis against orthopedic procedure volumes, sports injury incidence rates, and ambulatory surgery center expansion trajectories. Model inputs incorporated carbon fiber feedstock price indices, EMA MDR conformity assessment timeline data, and point-of-care 3D printing adoption curves in United States and German clinic networks.
Caveats apply where EMA MDR notified body capacity constraints, aerospace sector carbon fiber demand spikes, or software-as-medical-device classification rulings could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Endodontic Files Market
Medical Devices
Global Biliary Stents Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Bone-Cutting Technologies Market
Medical Devices
Global Aneurysm Clips Market
Medical Devices
Wearable Insulin Pump Market
Medical Devices
Medical Machine Battery Market
Medical Devices
Next Generation Infusion Pump Market
Medical Devices
Europe Minimally Invasive Surgery Devices Market
Medical Devices
US SNF Based Dialysis Market
Medical Devices
Ligament Augmentation Market
Medical Devices
Global Vein Illuminator Market
Medical Devices
Intraocular Lens (IOL) Market