
 North America Kyphoplasty Market | 2026-2036
North America Kyphoplasty Market Size, Share, and Industry Trends Forecast 2026-2036
North America Kyphoplasty Market Insights
Premium-grade bone cement formulations is reorganizing competitive dynamics in North America. Medtronic leverages its integrated spine platform to sustain leadership across balloon kyphoplasty systems. Stryker Corporation anchors its position through dedicated orthopedic surgical instruments and cement delivery technologies. Globus Medical differentiates via specialized expandable cage and biologics portfolios tailored to vertebral augmentation.
Kyphoplasty denotes a minimally invasive surgical intervention wherein a balloon tamp creates a cavity within a fractured vertebral body, followed by injection of polymethylmethacrylate bone cement to restore height and stabilize the spine. The procedure addresses osteoporotic vertebral compression fractures, pathological fractures from spinal metastases, and traumatic vertebral collapse. Bone cement product lines command the dominant revenue share given consumable repeat purchase cycles, while ambulatory surgery centers represent the fastest-growing end user channel as payors push site-of-care migration. Minimally invasive procedure types capture expanding volumes as surgeons and facilities prioritize reduced hospitalization and faster patient mobilization.
FDA 510(k) clearance requirements govern device commercialization, while CMS reimbursement codes shape procedure economics and site selection across US markets. Health Canada's Medical Devices Directorate maintains parallel licensing standards that manufacturers must satisfy for Canadian market access. Stakeholders must monitor evolving payor policies on inpatient versus outpatient kyphoplasty coverage, as these determinations will dictate capital allocation between hospital and ambulatory surgery center channels.
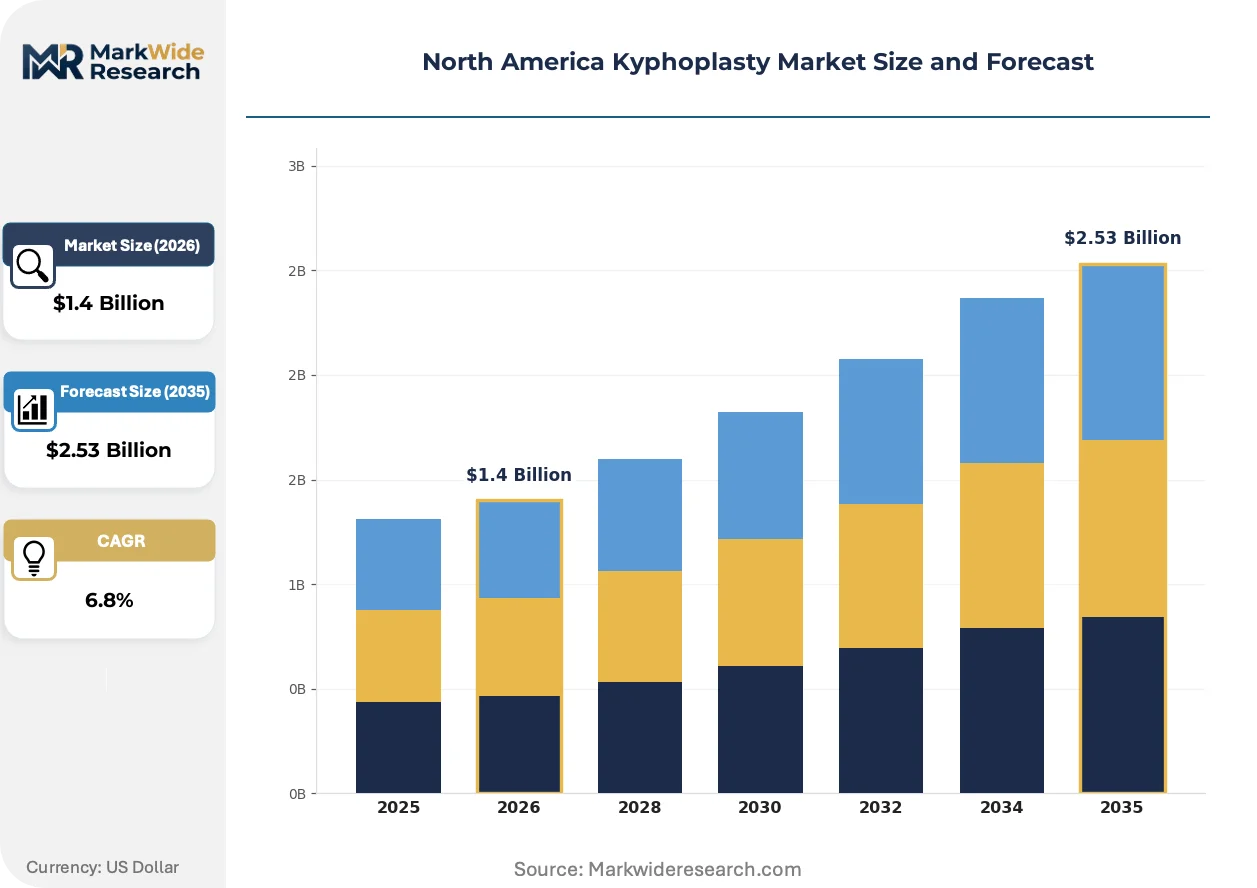
Market Dynamics
Site-of-care migration is compressing procedure economics across the United States and Canada, forcing manufacturers to reconfigure distribution networks around ambulatory surgery centers while defending hospital purchasing contracts.
Growth Catalysts
- Aging demographics:The US Sun Belt states concentrate Medicare-eligible populations with elevated osteoporosis prevalence, generating sustained procedure demand.
- CMS reimbursement codes:Outpatient prospective payment system expansions for kyphoplasty procedures accelerate ASC channel development across US markets.
- Balloon system miniaturization:Next-generation tamp designs reduce access tract trauma, expanding candidacy to frailer patient cohorts previously excluded from intervention.
Market Restraints
- PMMA monomer supply concentration:Three chemical manufacturers control North American methyl methacrylate feedstock, exposing cement producers to input cost volatility.
- Biologics substitution threat:Vertebral augmentation with calcium phosphate cements and demineralized bone matrix products competes for younger trauma cases.
- FDA 510(k) predicate device requirements:Substantial equivalence pathways for novel cement formulations create regulatory friction against breakthrough material introductions.
Strategic Opportunities
- Canadian provincial expansion:Ontario and British Columbia health authorities lag US ASC penetration rates, presenting whitespace for outpatient program development.
- Real-time fluoroscopy integration:Convergence of balloon inflation systems with intraoperative imaging navigation enables single-operator workflow consolidation.
- Health Canada parallel licensing:Medical Devices Directorate streamlined review pathways accelerate product synchronization with US commercial timelines.
Industry Challenges
- Interventional radiology workforce constraints:Fellowship-trained spine interventionists remain concentrated in academic medical centers, limiting ASC staffing scalability.
- Legacy EHR integration complexity:Ambulatory surgery center information systems require custom middleware development to interface with hospital radiology PACS networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Kyphoplasty Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Cement, Surgical Instruments, Inflation Devices, Biologics End User: Hospitals, Ambulatory Surgery Centers, Orthopedic Clinics, Rehabilitation Centers Procedure Type: Unilateral, Bilateral, Minimally Invasive, Traditional Surgical Distribution Channel: Direct Sales, Distributors, Online Sales, Others |
| Companies Covered | Medtronic, Stryker Corporation, DePuy Synthes (Johnson & Johnson), Globus Medical, Merit Medical Systems, Zimmer Biomet, Smith & Nephew, Alphatec Holdings, Benvenue Medical, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Kyphoplasty Market Trends and Innovations
Material science advances and reimbursement engineering are simultaneously reshaping product development priorities and commercial deployment strategies across US and Canadian markets.
Radio-opaque bone cement formulations are fragmenting competitive positioning among polymer suppliers. Barium sulfate loading variations now differentiate premium from standard tiers, with high-contrast variants commanding preference from interventional radiologists performing outpatient procedures under reduced fluoroscopy exposure protocols.
FDA 510(k) clearance pathways for combination products are compressing development timelines for cement-delivery system integrations. The agency's orthopaedic devices division issued revised guidance on balloon kyphoplasty predicate comparisons, prompting manufacturers to consolidate biocompatibility testing across platform families rather than device-by-device submissions.
Direct-to-facility contracting is displacing traditional distributor intermediaries in high-volume ASC clusters. Multi-site surgery center operators in Texas, Florida, and Arizona negotiate master purchase agreements spanning balloon systems, cement kits, and disposable accessories, compressing vendor margins while securing supply continuity guarantees for scheduled procedure blocks.
North America Kyphoplasty Market Segmentation
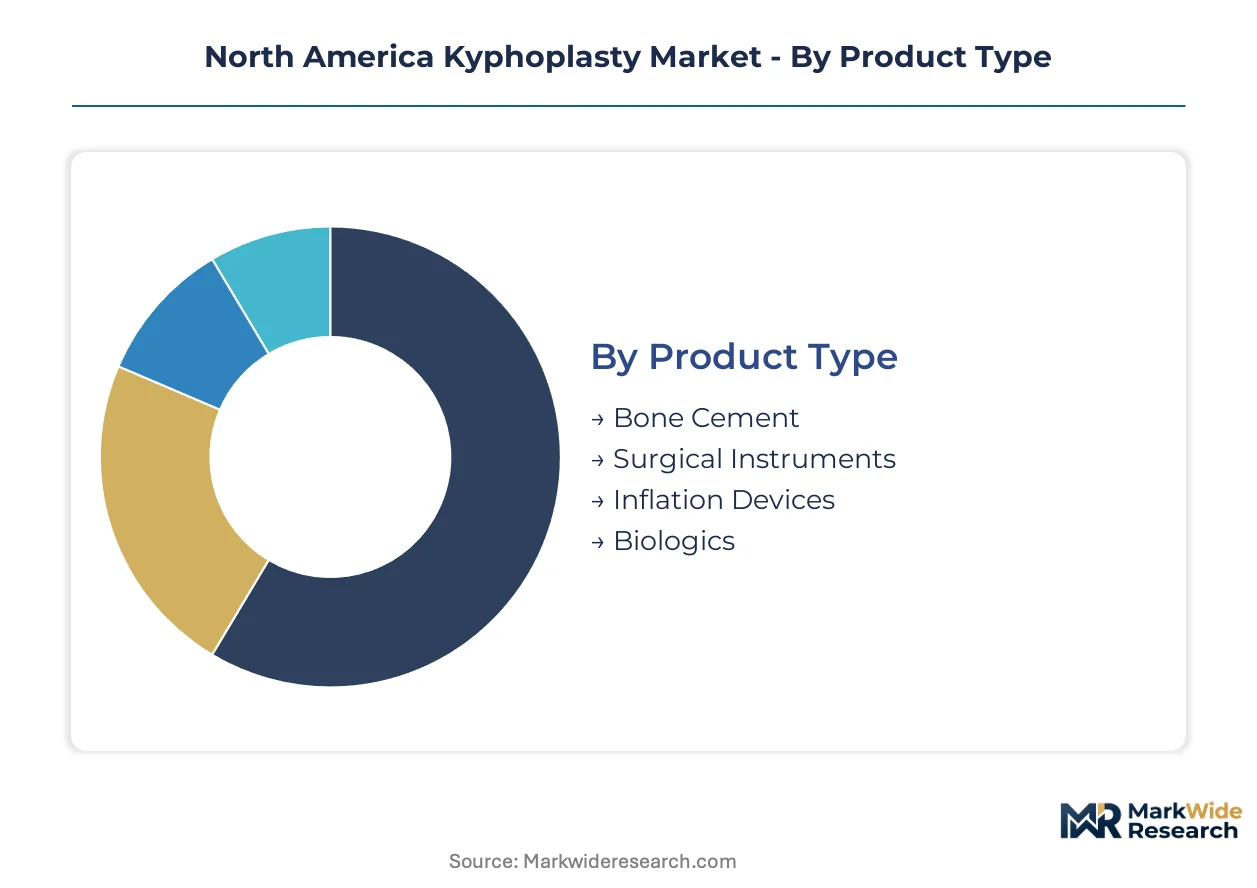
Kyphoplasty market segmentation reveals how site-of-care migration and material substitution pressures reshape procurement patterns across North American healthcare networks. Product categories face divergent competitive threats from biologics and alternative vertebral augmentation technologies.
Product Type:
Biologics substitution pressures concentrate most intensely on bone cement formulations, while surgical instruments defend position through procedure-specific design lock-in.
- Bone Cement:Polymethylmethacrylate-based formulations with barium sulfate radiopacity loading dominate consumable revenue cycles. Arizona and Texas ASC clusters drive demand for high-contrast variants that reduce fluoroscopy exposure during outpatient procedures. FDA 510(k) predicate requirements constrain rapid formulation innovation.
- Surgical Instruments:Specialized curettes, trocars, and cement delivery systems anchor kit economics through reusable sterilizable designs. Canadian hospital purchasing contracts favor instrument durability metrics over disposable convenience, slowing ASC-style conversion in Ontario and British Columbia.
- Inflation Devices:Balloon tamp inflation syringes and pressure monitors complete procedural kits.
- Biologics:Calcium phosphate cements and demineralized bone matrix products target younger trauma populations.
Bone cement retains volume leadership; biologics holds the steepest expansion curve.
End User:
Capital allocation intensity varies sharply across facility types, with ambulatory surgery centers commanding disproportionate vendor attention per procedure slot.
- Hospitals:Academic medical centers and community hospital systems maintain kyphoplasty service lines for complex pathological fracture cases. CMS inpatient prospective payment classifications sustain higher reimbursement for patients with spinal metastases requiring overnight observation. California and Florida hospital networks defend purchasing volume through multi-year balloon system contracts.
- Ambulatory Surgery Centers:Freestanding surgical facilities in Medicare-certified networks capture migrating outpatient volumes. Texas and Arizona multi-site operators negotiate master purchase agreements spanning cement kits, balloon systems, and disposable accessories.
- Orthopedic Clinics:Physician-owned specialty practices perform select kyphoplasty procedures under office-based surgery licenses.
- Rehabilitation Centers:Post-acute facilities coordinate referral pathways for fracture stabilization candidates.
Hospitals retain volume leadership; ambulatory surgery centers gain share fastest.
Procedure Type:
Surgeon training concentration and reimbursement precision determine which approaches expand within constrained interventional radiology workforces.
- Minimally Invasive:Balloon kyphoplasty through percutaneous access tracts prioritizes reduced hospitalization and faster mobilization. US Sun Belt Medicare populations with elevated osteoporosis prevalence generate concentrated demand for outpatient-compatible techniques.
- Bilateral:Two-sided vertebral augmentation addresses multi-level compression fractures in a single anesthetic session.
- Unilateral:Single-access procedures reduce operative time for isolated vertebral body collapse.
- Traditional Surgical:Open vertebral augmentation remains reserved for traumatic burst fractures requiring corpectomy.
Minimally invasive approaches retain volume leadership; bilateral procedures climb the fastest.
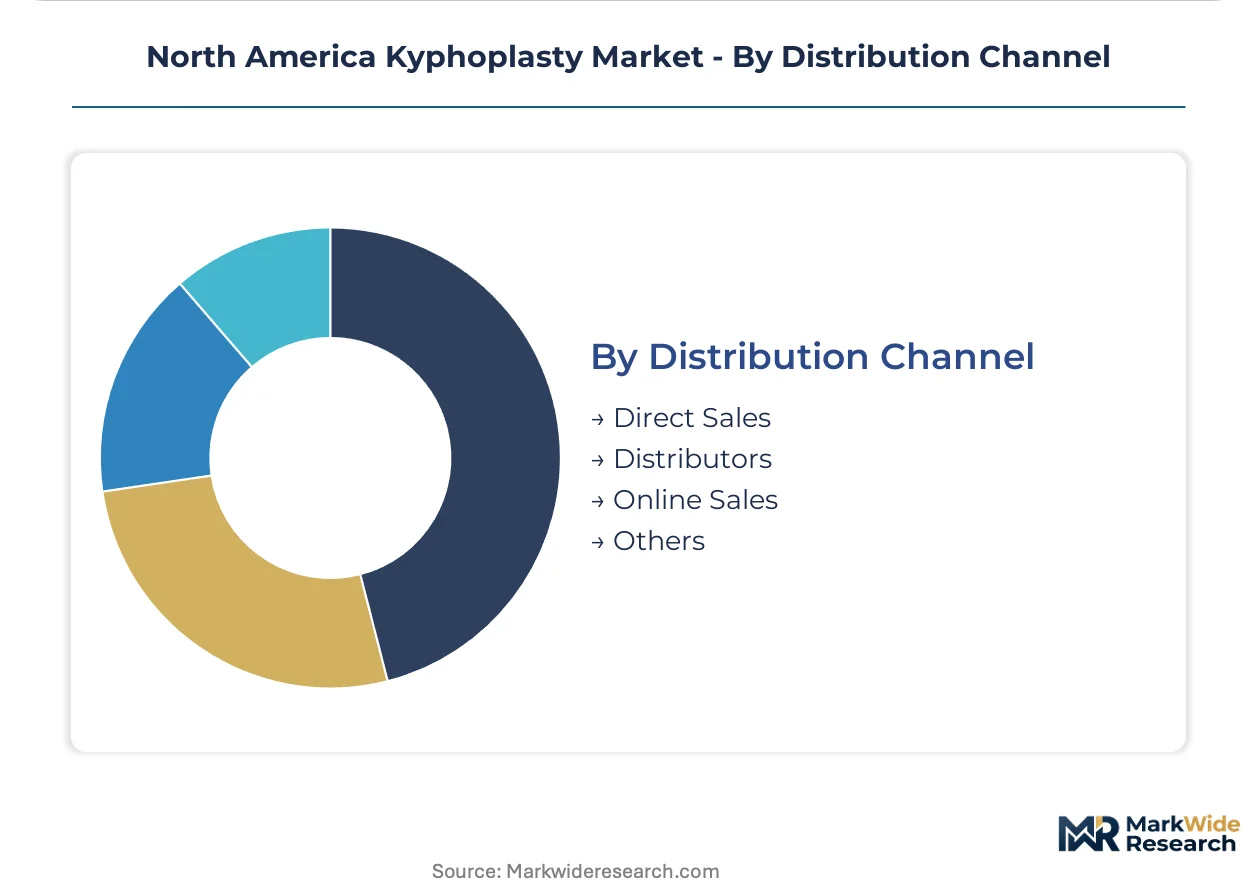
Distribution Channel:
Channel economics fragment according to facility scale and geographic clustering density.
- Direct Sales:Manufacturer field representatives contract directly with high-volume ASC chains and hospital IDNs. Arizona and Texas multi-site operators secure supply continuity guarantees for scheduled procedure blocks.
- Distributors:Regional medical device wholesalers serve low-volume orthopedic clinics and rehabilitation centers.
- Online Sales:E-procurement platforms capture consumable replenishment for established accounts.
- Others:Group purchasing organizations aggregate demand across independent facilities.
Direct sales retains volume leadership; online sales shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of kyphoplasty balloon systems and bone cement delivery platforms clusters around established medical device corridors in the United States. FDA 510(k) clearance pathways and CMS reimbursement engineering concentrate vendor strategic planning within US regulatory orbits.
United States
Medicare-eligible populations in Arizona, Texas, and Florida generate concentrated procedure demand through ambulatory surgery center networks. FDA orthopaedic devices division guidance on predicate device comparisons shapes product development timelines for cement-delivery integrations. Dallas-Fort Worth and Phoenix metropolitan clusters host multi-site ASC operators negotiating master purchase agreements for scheduled kyphoplasty blocks.
Canada
Ontario and British Columbia health authorities maintain hospital-centric purchasing patterns that lag US outpatient migration rates. Health Canada's Medical Devices Directorate licensing standards require parallel regulatory submissions that manufacturers synchronize with US commercial timelines. Toronto and Vancouver academic medical centers concentrate fellowship-trained interventional radiologists performing complex pathological fracture cases.
Mexico
Private hospital networks in Mexico City and Monterrey expand minimally invasive spine service lines for medical tourism and domestic affluent populations. COFEPRIS regulatory pathways for imported medical devices create documentation requirements that favor established multinational suppliers. Guadalajara medical device manufacturing clusters produce disposable surgical instruments for regional distribution.
North America Kyphoplasty Market Competitive Landscape
Concentration sits with diversified spine platform operators and specialized orthopedic surgical instrument manufacturers. The vendor base separates into three functional tiers: integrated hospital supply conglomerates with dedicated spine divisions, mid-scale device specialists with focused vertebral augmentation portfolios, and regional distributors serving low-volume orthopedic clinics. Dominant competitive moves include direct-to-facility contracting with high-volume ASC chains and portfolio diversification into biologics-adjacent bone substitute materials.
Among integrated platform operators, Medtronic and Stryker Corporation exemplify the diversified spine-device archetype. Globus Medical occupies a position within the specialized vertebral augmentation tier. These three entities anchor the competitive structure through contrasting strategic postures: platform breadth versus segment focus.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| DePuy Synthes (Johnson & Johnson) |
| Globus Medical |
| Merit Medical Systems |
| Zimmer Biomet |
| Smith & Nephew |
| Alphatec Holdings |
| Benvenue Medical |
| Others |
Pricing and Supply Chain Analysis
Sixty-day cement kit inventory cycles at Texas ASC clusters concentrate procurement leverage with multi-site operators while squeezing margin buffers for manufacturers tethered to volatile methyl methacrylate feedstock contracts. This lead-time compression simultaneously amplifies buyer pricing power in high-volume corridors and exposes suppliers to input cost pass-through constraints.
Pricing Analysis
FDA 510(k) predicate requirements dictate the pricing tier structure across bone cement and balloon system portfolios, separating premium high-radiopacity formulations from standard barium sulfate loadings. Price differentiation hinges on fluoroscopy reduction certification and kit bundling complexity, with direct-to-facility master agreements in Arizona and Florida compressing list prices for high-volume chains while smaller orthopedic clinics absorb distributor markups. Cost compression in standard-grade cement intensifies as biologics substitution threats erode trauma-case premiums, rendering hospital purchasing committees the least price-sensitive segment due to inpatient reimbursement buffers.
Supply Chain Analysis
The United States and Germany anchor balloon system manufacturing and precision molding for kyphoplasty tamps, while China and India feed specialized polymer components and surgical instrument forgings. Raw material dependencies center on methyl methacrylate monomer from Gulf Coast petrochemical corridors, barium sulfate radiopaque agents, and medical-grade silicone for inflation lumens. Single-source vulnerability concentrates in PMMA feedstock where three North American chemical manufacturers control methyl methacrylate supply, exposing cement producers to input volatility. Distribution runs through manufacturer field representatives for high-volume ASC chains and regional wholesalers for low-volume clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in vertebral augmentation hinge on interoperability between balloon inflation systems and intraoperative imaging navigation, with single-operator workflow consolidation emerging as the decisive ecosystem battleground.
For Market Incumbents: Fortify ASC channel control through captive cement formulation supply and exclusive master purchase agreements spanning Texas and Arizona multi-site operators. Deepen backward integration into methyl methacrylate feedstock through long-term offtake contracts with Gulf Coast chemical manufacturers, neutralizing the PMMA monomer supply concentration threat while locking in margin stability against biologics substitution pressure. For New Entrants and Emerging Players: Real-time fluoroscopy integration gaps in current balloon system offerings create entry vectors for navigation-enabled workflow consolidation targeting understaffed ASCs in Ontario and British Columbia. Penetrate Canadian provincial markets where Health Canada parallel licensing accelerates product synchronization with US timelines, leveraging direct sales models to bypass incumbent distributor relationships in hospital-centric purchasing environments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified orthopedic conglomerates with under-monetized spine device divisions lacking dedicated kyphoplasty platform depth. Long-term viability rests on ASC channel density and biologics-adjacent bone substitute pipelines, with acquisition screens prioritizing firms holding Health Canada licenses and established GPO contracts. Watch Health Canada Medical Devices Directorate review pathway streamlining as the signal indicating accelerated product cycle synchronization and valuation multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Predicate device consolidation accelerates cement-delivery system integrations across platform families. |
| Health Canada Parallel Licensing | Streamlined Medical Devices Directorate reviews synchronize Canadian commercial timelines with US FDA clearances. |
| ASC Master Purchase Agreement | Direct contracting with Texas and Arizona multi-site operators secures scheduled procedure block supply continuity. |
| Real-Time Fluoroscopy Integration | Navigation-enabled balloon inflation systems consolidate single-operator workflows in outpatient settings. |
| Reimbursement Strategy Engineering | CMS outpatient prospective payment system alignment accelerates site-of-care migration from hospitals to ASCs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with interventional radiologists, ASC procurement directors, hospital purchasing committee members, and biomedical engineers at academic medical centers. Secondary validation drew from FDA 510(k) device filings, CMS Medicare reimbursement databases, Health Canada Medical Devices Directorate licensing records, and GPO contract repositories. Bottom-up procedure volume estimates across US Sun Belt states and Canadian provinces were triangulated against top-down manufacturer revenue segment disclosures.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across product type, end user facility category, procedure approach, and distribution channel. CAGRs were derived from procedure migration patterns between hospital inpatient and ASC outpatient settings, incorporating aging demographic trajectories in Medicare-eligible populations and payor site-of-care policy evolution. Industry-specific inputs included methyl methacrylate feedstock pricing volatility indices and Health Canada licensing timeline compression observations.
Underlying assumptions cover stable CMS reimbursement code structures for kyphoplasty procedures, with deviation risk concentrated in biologics substitution acceleration and PMMA monomer supply disruptions. Forecasts reflect these documented conditions and acknowledge regulatory pathway friction, interventional radiology workforce constraints, and legacy EHR integration complexity as factors that could materially revise projections. Recalibration cycles align with material shifts in FDA predicate guidance, Health Canada review streamlining announcements, and CMS site-of-care policy determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Outsourced Orthopedic Manufacturing Market
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
Global Shoulder Replacement Market
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
Orthopedic Trauma Fixation Devices Market
Orthopedic Devices
Spinal Pumps Market
Orthopedic Devices
Spinal Implants and Devices Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
Total Wrist Prosthesis Market
Orthopedic Devices
Orthopedic Fracture Repairing Implants for Osteoporosis Market
Orthopedic Devices
Adult Orthopedic Insole Market
Orthopedic Devices
Orthopedic Artificial Bone Defect Repair Materials Market
Orthopedic Devices
North America Knee Cartilage Repair Market
Orthopedic Devices
Hip Orthosis Market
Orthopedic Devices
Kyphoscoliosis Treatment Market