
 Global Spinal Fusion Devices Market | 2026-2036
Global Spinal Fusion Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Spinal Fusion Devices Market Foresight
CE marking under the EU Medical Device Regulation (MDR) is unwinding competitive access across European markets, forcing smaller manufacturers to consolidate or exit. Medtronic leverages its integrated spine platform to sustain broad portfolio coverage across cervical and lumbar segments. Stryker anchors its position through proprietary navigation and robotics ecosystems that lock in hospital system loyalty. Globus Medical differentiates via aggressive R&D intensity in expandable interbody technologies and patient-specific implant design.
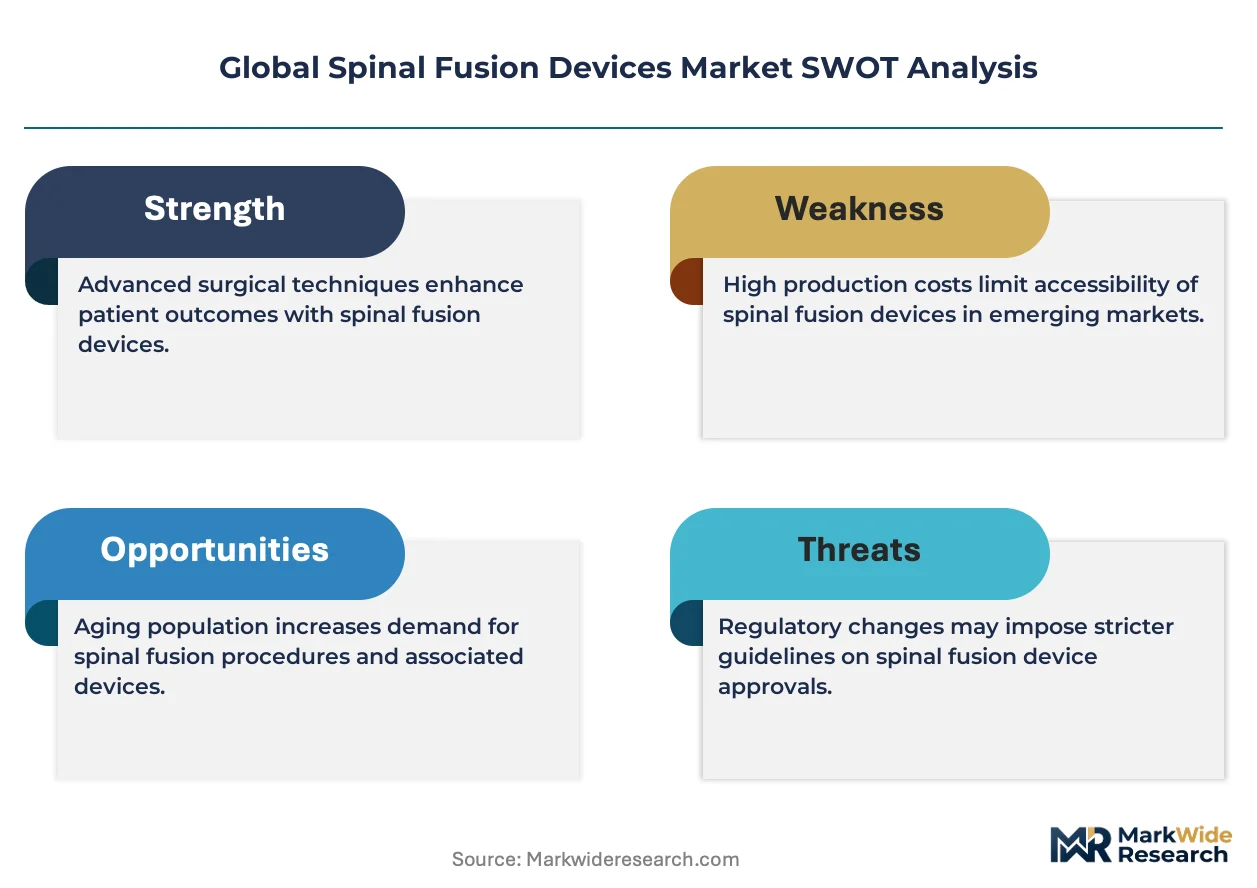
Spinal fusion devices are implantable orthopedic systems—typically comprising titanium or polyetheretherketone interbody cages, pedicle screw-rod constructs, and biologic graft materials—engineered to immobilize vertebral segments and promote osseointegration following decompression or deformity correction. These systems restore spinal stability and alignment in patients with degenerative, traumatic, or neoplastic pathologies where conservative management fails. Pedicle screws and rods capture the largest installed base and command durable replacement revenue streams from revision procedures. Interbody cages, particularly those incorporating porous titanium architectures and demineralized bone matrix, represent the fastest-expanding product category as surgeons pursue higher fusion rates with reduced subsidence. Minimally invasive technology platforms concentrate margin pools through premium pricing tied to reduced hospital length-of-stay metrics and lower complication profiles.
FDA premarket notification and PMA pathways, EU MDR technical documentation requirements, and Japan PMDA foreign manufacturer registration collectively govern market entry and sustain product standardization across major jurisdictions. These frameworks elevate clinical evidence burdens, particularly for novel biologic adjuncts and patient-matched 3D-printed implants, which filters manufacturer participation toward well-capitalized entities with established regulatory infrastructure. Stakeholders must monitor evolving CMS and private payer site-of-service policies, as reimbursement differentials between inpatient and ambulatory settings will determine capital allocation toward enabling technologies and channel infrastructure.
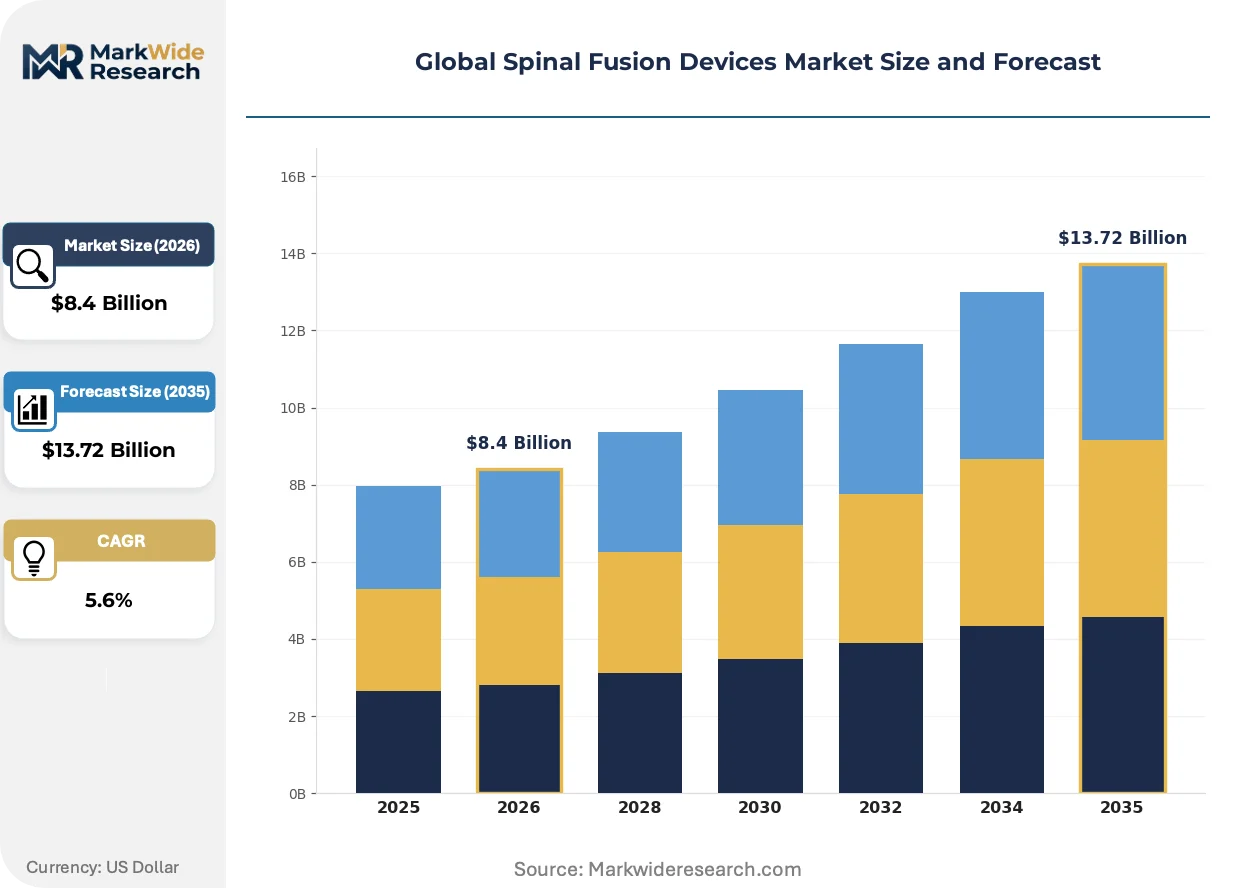
Market Dynamics
Site-of-service migration toward ambulatory surgical centers is compressing traditional hospital revenue capture and forcing device manufacturers to reconfigure channel economics around outpatient reimbursement codes.
Growth Catalysts
- CMS reimbursement parity:Medicare payment adjustments for outpatient spinal fusion procedures are accelerating ASC caseload expansion in the United States.
- Porous titanium architectures:Advanced additive manufacturing techniques are improving osseointegration rates and reducing subsidence-related revision rates.
- Japan's super-aging demographic:PMDA-registered foreign manufacturers are capturing procedural volume growth as degenerative spine conditions concentrate in patients over 75.
Market Restraints
- EU MDR technical documentation:Elevated clinical evidence requirements for Class III implantable devices are extending conformity assessment timelines and compliance costs.
- Titanium powder supply concentration:Plasma atomization feedstock for additive manufacturing concentrates among a limited supplier base, creating input cost volatility.
- Adjacent segment motion disease:Fusion-induced biomechanical stress transfer accelerates adjacent-level degeneration, sustaining non-fusion alternative development.
Strategic Opportunities
- German outpatient surgery expansion:Bundled reimbursement pilots for lumbar fusion in day-clinic settings are creating early-mover positioning for enabling technology providers.
- Navigation-robotics convergence:Integration of intraoperative imaging with autonomous screw placement is compressing operative time and expanding addressable surgeon populations.
- Patient-matched 3D-printed implants:FDA breakthrough device designation pathways are accelerating market access for anatomically customized interbody cages.
Industry Challenges
- Biologics characterization expertise:Demineralized bone matrix and cellular allograft products require specialized regulatory affairs capabilities that outpace talent pool expansion.
- Legacy hospital IT integration:Robotic navigation platforms face interoperability friction with proprietary surgical scheduling and electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Spinal Fusion Devices Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.72 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interbody Cages, Pedicle Screws, Plates & Rods, Bone Grafts, Spinal Fixators Technology: Minimally Invasive, Navigation Systems, Biologics, 3D Printing, Robotic Assistance Application: Degenerative Disc Disease, Spinal Trauma, Tumors, Deformities, Infections End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Orthopedic Centers |
| Companies Covered | Medtronic, Stryker, Zimmer Biomet, Globus Medical, NuVasive, DePuy Synthes, Orthofix Medical, Alphatec Spine, ATEC Spine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Spinal Fusion Devices Market Shifts & Advancements
Digital surgery ecosystems and advanced biomaterials are compressing the gap between intraoperative precision and postoperative biological integration, redefining value capture across the procedural continuum.
Expandable interbody cage technology is miniaturizing delivery profiles while maintaining post-deployment lordotic restoration. Surgeons in high-volume ASC networks are adopting these devices to reduce neural retraction requirements and accelerate patient mobilization. The technology is miniaturizing access corridors from 22mm to sub-15mm working channels, collapsing the boundary between open and minimally invasive procedural categories.
EU MDR post-market surveillance requirements are mandating systematic implant registries and periodic safety update reports for spinal fusion hardware. Manufacturers must now maintain active clinical follow-up infrastructure across notified body jurisdictions, elevating ongoing compliance expenditures. German and French health technology assessment bodies are incorporating these real-world evidence streams into reimbursement determination frameworks.
Hospital system procurement consolidation is centralizing spine device contracting through integrated delivery network preferred vendor arrangements. Independent ASC operators are responding through group purchasing organization aggregation to recover pricing leverage. This concentration dynamic is most pronounced in Texas and Florida metropolitan markets where private equity-backed surgery center roll-ups dominate facility ownership structures.
Global Spinal Fusion Devices Market Segmentation
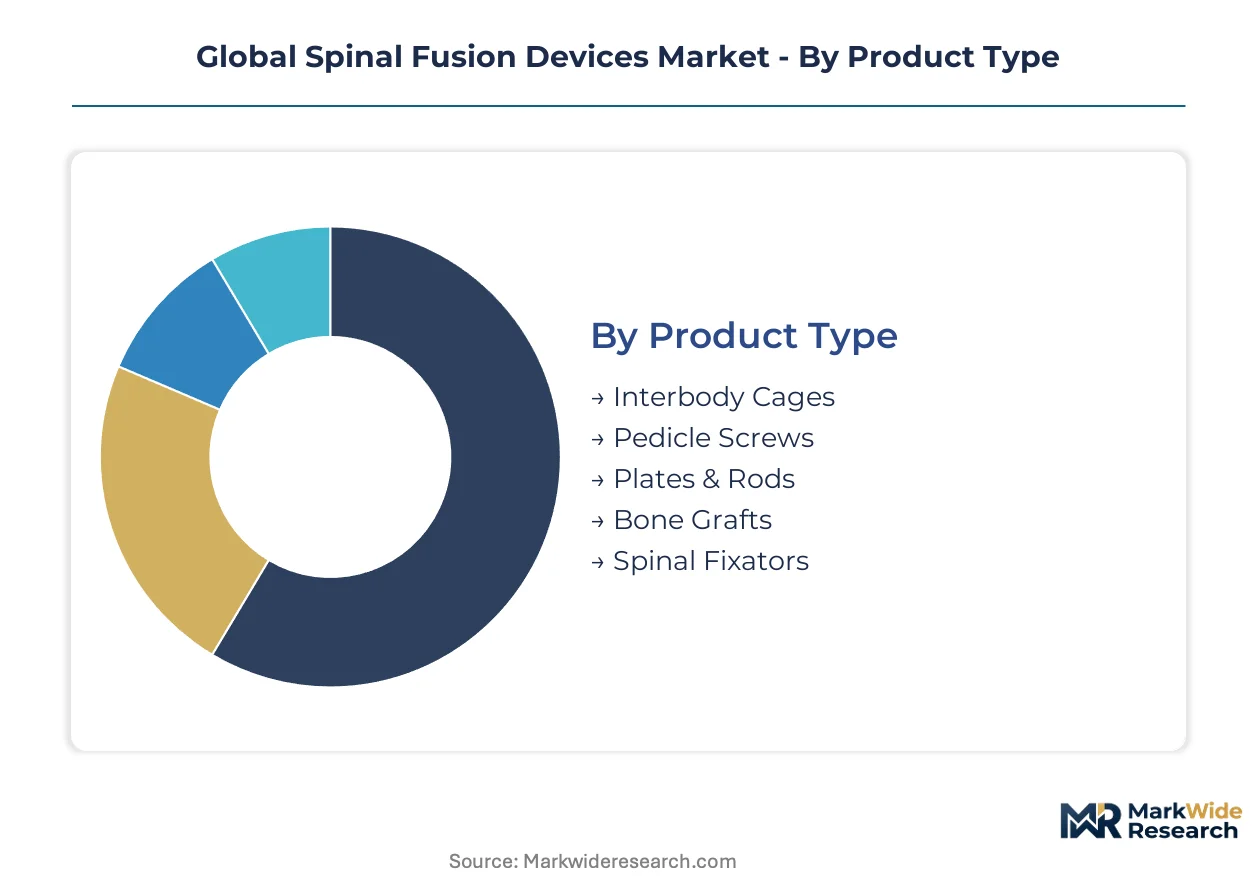
Segmentation in spinal fusion devices reveals how margin pools concentrate in differentiated technology platforms and shift with site-of-service migration. Understanding these divisions exposes where pricing power endures and where commodification pressures mount.
Product Type:
Pedicle screw-rod systems and advanced interbody cages command the deepest margin pools through replacement revenue and premium materials.
- Pedicle Screws:Titanium and cobalt-chrome alloy constructs anchor posterior stabilization constructs. Demand concentrates in high-volume academic medical centers in the United States and Germany where revision caseloads sustain replacement cycles.
- Interbody Cages:Porous titanium and PEEK-OPTIMA polymer cages restore disc height and promote fusion. Surgeons in Japan and ambulatory surgical centers in Texas and Florida are driving adoption of expandable designs that reduce neural retraction.
- Plates & Rods:Anterior cervical and thoracolumbar plating systems stabilize anterior column reconstruction.
- Bone Grafts:Demineralized bone matrix and synthetic ceramic grafts supplement autograft harvest limitations.
- Spinal Fixators:External and temporary internal fixation devices bridge unstable trauma segments.
Pedicle screws hold installed capacity. Interbody cages is rotating up the share rankings.
Technology:
Navigation-robotics convergence and biologics platforms capture outsized value through workflow integration and regulatory moats.
- Minimally Invasive:Tubular retractor systems and percutaneous screw placement reduce paraspinal muscle disruption. German day-clinic pilots and United States ASC networks are expanding addressable volumes through reduced length-of-stay metrics.
- Navigation Systems:Intraoperative CT and fluoroscopy-based tracking enable real-time screw trajectory verification. Hospital systems in Japan and the United States are bundling these platforms into capital equipment contracts that lock in disposable revenue.
- Biologics:Cellular allografts and recombinant bone morphogenetic proteins accelerate fusion biology.
- 3D Printing:Patient-matched titanium implants from EOS and Arcam machines enable anatomical customization.
- Robotic Assistance:Autonomous drilling and screw placement systems compress operative variability.
Navigation systems hold installed capacity. Minimally invasive is rotating up the share rankings.
Application:
Procedure volumes concentrate in degenerative indications where aging demographics and reimbursement clarity align.
- Degenerative Disc Disease:Spondylolisthesis and disc herniation drive lumbar fusion volume. Patients over 65 in Japan, Germany, and the United States are expanding the addressable pool as PMDA and FDA pathways sustain device innovation.
- Spinal Trauma:Burst fractures and ligamentous injury require urgent stabilization. Level I trauma centers in the United States and university hospitals in Germany concentrate high-acuity caseloads.
- Tumors:Metastatic spinal cord compression necessitates corpectomy and anterior column reconstruction.
- Deformities:Adolescent idiopathic scoliosis and adult spinal deformity drive complex multi-level fusions.
- Infections:Discitis and osteomyelitis require debridement and temporary stabilization.
Degenerative disc disease holds installed capacity. Spinal trauma is rotating up the share rankings.
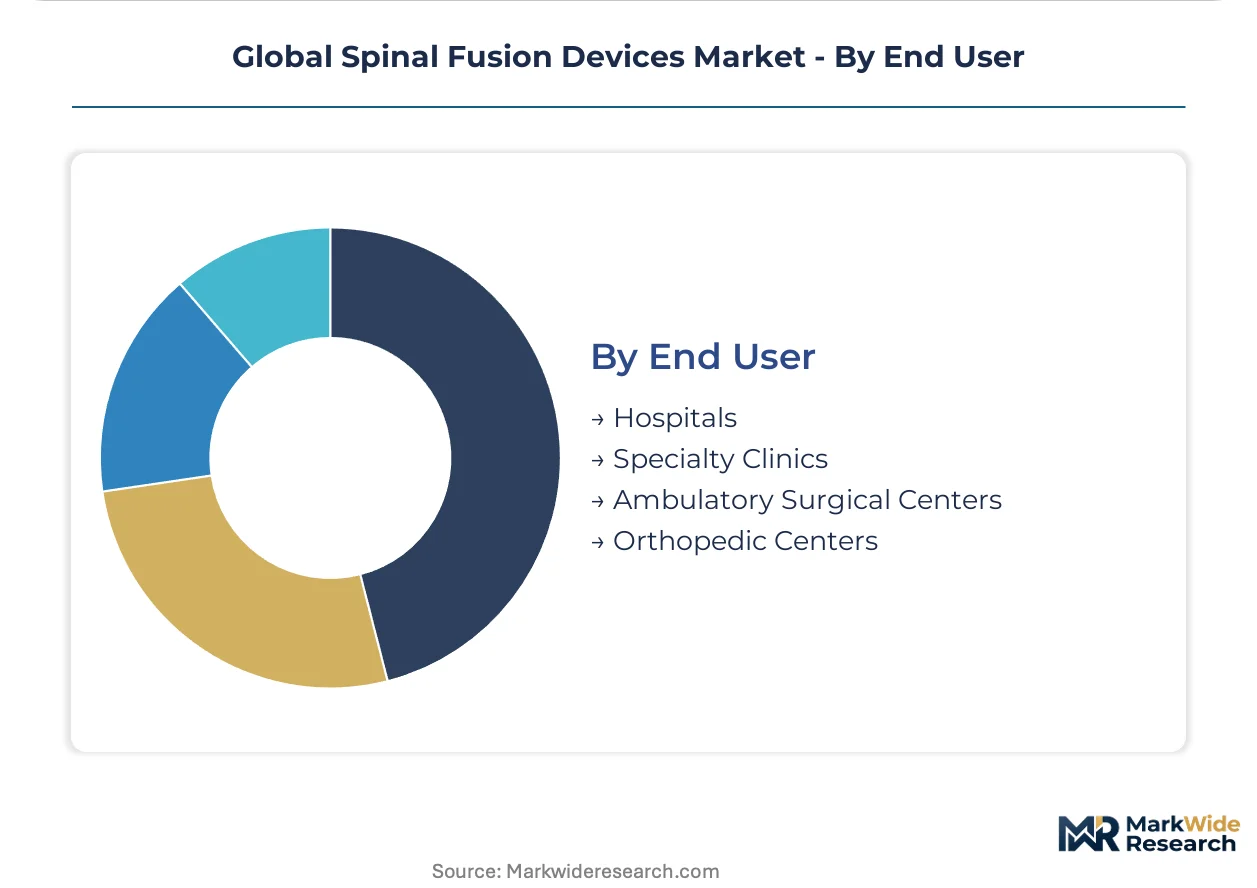
End User:
Site-of-service economics are redistributing volume toward outpatient settings where reimbursement parity enables margin capture.
- Hospitals:Inpatient surgical departments retain complex deformity and trauma cases. Academic medical centers in the United States and Japan maintain high fusion volumes through resident training pipelines and research infrastructure.
- Ambulatory Surgical Centers:Outpatient lumbar and cervical fusions are expanding as CMS reimbursement adjustments align payment with hospital rates. Private equity-backed networks in Texas and Florida are consolidating purchasing power.
- Specialty Clinics:Spine-focused practices integrate diagnostic and interventional capabilities.
- Orthopedic Centers:Multi-specialty groups combine joint and spine service lines.
Hospitals hold installed capacity. Ambulatory surgical centers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket approval pathways and CMS reimbursement parity adjustments are accelerating outpatient migration in the United States. Germany's bundled payment pilots and Japan's PMDA foreign manufacturer registration frameworks are reshaping competitive access across their respective markets.
United States
CMS reimbursement parity for outpatient spinal fusion procedures is expanding ambulatory surgical center caseloads. FDA PMA and 510(k) pathways sustain elevated clinical evidence requirements for novel biologic adjuncts. Private equity-backed surgery center networks in Texas and Florida are consolidating purchasing power through group purchasing organization aggregation.
Germany
Bundled reimbursement pilots for lumbar fusion in day-clinic settings are creating early-mover positioning for enabling technology providers. EU MDR technical documentation requirements and CE marking conformity assessments are extending market access timelines for implantable hardware. The Baden-Württemberg and Bavaria medical technology clusters concentrate notified body infrastructure and orthopedic manufacturing expertise.
Japan
Super-aging demographics are concentrating degenerative spine procedure volumes among patients over 75. PMDA foreign manufacturer registration and quality management system requirements govern market entry for imported implantable devices. Tokyo and Osaka metropolitan areas sustain high-volume academic medical centers with established resident training pipelines.
United Kingdom
NICE technology appraisal frameworks and NHS England specialized commissioning criteria are determining reimbursement access for navigation-robotics platforms. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining UKCA marking pathways. The Oxford-Cambridge-London golden triangle concentrates spine surgery research infrastructure and early-stage device evaluation programs.
China
NMPA Class III medical device registration requirements and provincial centralized procurement initiatives are compressing pricing for standard implant systems. Volume-based procurement pilots in Jiangsu and Zhejiang provinces are consolidating hospital purchasing power. The Yangtze River Delta medical device manufacturing corridor is expanding domestic production capacity for titanium interbody cages.
Global Spinal Fusion Devices Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory infrastructure dimensions. The vendor base concentrates around integrated platform providers with established FDA and EU MDR compliance capabilities. Three archetypes dominate: diversified orthopedic conglomerates with spine divisions, pure-play spine technology specialists, and emerging navigation-robotics platform developers. M&A activity targets expandable interbody technology and patient-matched 3D printing capabilities, while strategic partnerships lock in hospital system loyalty through bundled capital equipment contracts.
Within the diversified orthopedic tier, Medtronic and Stryker exemplify platform breadth across cervical and lumbar segments. Globus Medical occupies a position representing pure-play spine specialization with intensive R&D allocation. These three entities anchor the competitive structure by demonstrating how regulatory infrastructure scale and integrated technology ecosystems determine sustainable market access.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Zimmer Biomet |
| Globus Medical |
| NuVasive |
| DePuy Synthes |
| Orthofix Medical |
| Alphatec Spine |
| ATEC Spine |
| Others |
Supply & Pricing Matrix
Porous titanium additive manufacturing feedstock is displacing conventional machined PEEK interbody cages, simultaneously shifting procurement geography toward plasma atomization specialists in Germany and the United States while compressing per-unit economics for standard implant tiers. This substitution dynamic concentrates margin capture among device manufacturers with backward integration into powder supply agreements, while ASC buyers exploit commoditized legacy PEEK inventory to extract contract concessions.
Pricing Analysis
Certification level (FDA PMA versus 510(k) versus CE MDR Class III) creates the primary spread across implant pricing tiers, with breakthrough-designation expandable cages commanding premium positioning against standard pedicle screw constructs. Three-tier pricing structure across premium, standard, and economy levels stratifies by osseointegration performance data and navigation-robotics bundling. Cost compression in standard PEEK cages is intensifying because Chinese NMPA-registered domestic manufacturers are expanding titanium cage production capacity. Hospital purchasing committees exhibit lowest price sensitivity for navigation-integrated systems, while independent ASC networks in Texas and Florida demonstrate highest sensitivity to interbody cage per-unit costs.
Supply Chain Analysis
Germany and the United States anchor plasma atomization feedstock production for porous titanium architectures, with Japan supplying high-purity cobalt-chrome alloy rod stock for posterior stabilization constructs. The supply chain draws from concentrated titanium powder suppliers, demineralized bone matrix allograft processors, and precision machining subcontractors for screw thread geometries. Single-source vulnerability concentrates in plasma atomization capacity, where limited qualified suppliers create input cost volatility during demand surges. Distribution runs through integrated delivery network preferred vendor arrangements and group purchasing organization aggregation for independent ASC operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spinal fusion devices market sits in early-cycle expansion as CMS reimbursement parity for outpatient procedures accelerates ASC site-of-service migration, creating penetration headroom for enabling technologies that compress operative time and length-of-stay metrics.
For Market Incumbents: Compound platform stickiness through navigation-robotics ecosystem bundling that locks hospital system loyalty, while deepening backward integration into titanium powder supply to defend margin position against emerging domestic Chinese manufacturers. Prioritize EU MDR technical documentation infrastructure investment to sustain CE marking access as smaller competitors exit from compliance cost burdens.
For New Entrants and Emerging Players: Post-market surveillance data analytics services represent an under-served layer where incumbents lack specialized regulatory affairs capabilities for systematic implant registry maintenance. Target German day-clinic bundled reimbursement pilots with patient-matched 3D-printed interbody cage offerings that demonstrate superior lordotic restoration metrics. Deploy direct-to-ASC sales models bypassing traditional hospital contracting channels.
For Investors and Strategic Acquirers: The market sits at a technology-integration phase that favors navigation-robotics platform developers and expandable interbody cage specialists with FDA breakthrough device designations. Over the coming decade, consolidation will concentrate around entities with dual FDA-EU MDR regulatory infrastructure and established hospital system capital equipment contracts. Monitor CMS site-of-service policy adjustments as the primary inflection signal for ASC volume acceleration versus hospital retention.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates market access for patient-matched 3D-printed interbody cages through prioritized review pathways. |
| EU MDR CE Marking Pathway | Sustains competitive access across German and French markets as clinical evidence requirements elevate. |
| Hospital System Partnership | Locks in disposable revenue streams through bundled navigation-robotics capital equipment contracts. |
| Software Companion Development | Integrates intraoperative planning algorithms with robotic screw placement to expand addressable surgeon populations. |
| Reimbursement Strategy | Aligns device value propositions with CMS outpatient parity adjustments and German bundled payment pilots. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across orthopedic surgeons, hospital purchasing committee members, biomedical engineers at academic medical centers, GPO contracts managers, and regulatory affairs leads at notified bodies. Secondary validation drew from FDA 510(k) and PMA filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement contract disclosures. Bottom-up triangulation across implant shipment volumes and top-down reconciliation against procedure reimbursement codes anchored market size estimation.
Across the analysis window, the forecast framework modeled product type segmentation (pedicle screws, interbody cages, biologics), technology platform adoption (minimally invasive, navigation-robotics, 3D printing), application indication prevalence (degenerative disc disease, trauma, deformity), and end-user site-of-service migration (hospitals versus ASCs). CAGRs were derived from procedure volume elasticity to demographic aging curves and reimbursement policy elasticity models, incorporating PMDA foreign manufacturer registration timelines and EU MDR conformity assessment duration assumptions.
Forecasts assume regulatory continuity in FDA PMA pathways, EU MDR CE marking regimes, and CMS outpatient reimbursement parity; material policy shifts in site-of-service payment differentials or biologics classification would require re-modeling. Specific risks include titanium powder supply disruption, adjacent-segment disease litigation accelerating non-fusion alternative adoption, and hospital system procurement consolidation compressing vendor margins. Recalibration cycles align with material shifts in CMS reimbursement policy, EU MDR implementation enforcement, and navigation-robotics platform adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Humeral Implant Market
Orthopedic Devices
Shoulder Arthroplasty Market
Orthopedic Devices
Closed Heel Nursing Shoes Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
Orthopedic Trauma Fixation Devices Market
Orthopedic Devices
Orthopedic Artificial Bone Defect Repair Materials Market
Orthopedic Devices
Orthopedic Joint Reconstruction Market
Orthopedic Devices
Europe Orthopedic Braces and Support Market
Orthopedic Devices
Europe Orthopedic Navigation Systems Market
Orthopedic Devices
Global Shoulder Replacement Market
Orthopedic Devices
Europe Orthopedic Devices Market
Orthopedic Devices
Keyhole Orthopaedic Surgery Market
Orthopedic Devices
Global Patient Positioning Devices Market
Orthopedic Devices
Spine Devices Market
Orthopedic Devices
Orthopedic Insole Manufacturing Thermosealer Market
Orthopedic Devices
Global Orthopedic Bone Cement Market