
 Global Implantable Drug Delivery Market | 2026-2036
Global Implantable Drug Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Implantable Drug Delivery Market Foresight
Remote monitoring and software-defined dosing protocols is repositioning implantable pumps from passive reservoirs to connected therapeutic platforms. Medtronic leverages its neuromodulation infrastructure to dominate programmable infusion systems. Boston Scientific Corporation anchors its portfolio in interventional pain management with catheter-integrated delivery architectures. Abbott Laboratories differentiates through glucose-responsive hormone delivery mechanisms that compete on algorithmic precision rather than hardware alone.
Implantable drug delivery encompasses polymer-encased or titanium-housed devices that release therapeutic agents through osmotic pressure, electrochemical gradients, or biodegradable matrix erosion at specified pharmacokinetic rates, primarily serving chronic disease management where oral or intravenous administration proves inadequate. Biodegradable implants and reservoir-based systems capture expanding margin pools as polymer chemistry advances reduce explantation burdens. Osmotic delivery technology leads in oncology applications where zero-order kinetics maintain plasma concentration windows, while electrochemical platforms represent the fastest-growing segment for neurological disorders requiring patient-triggered bolus capability.
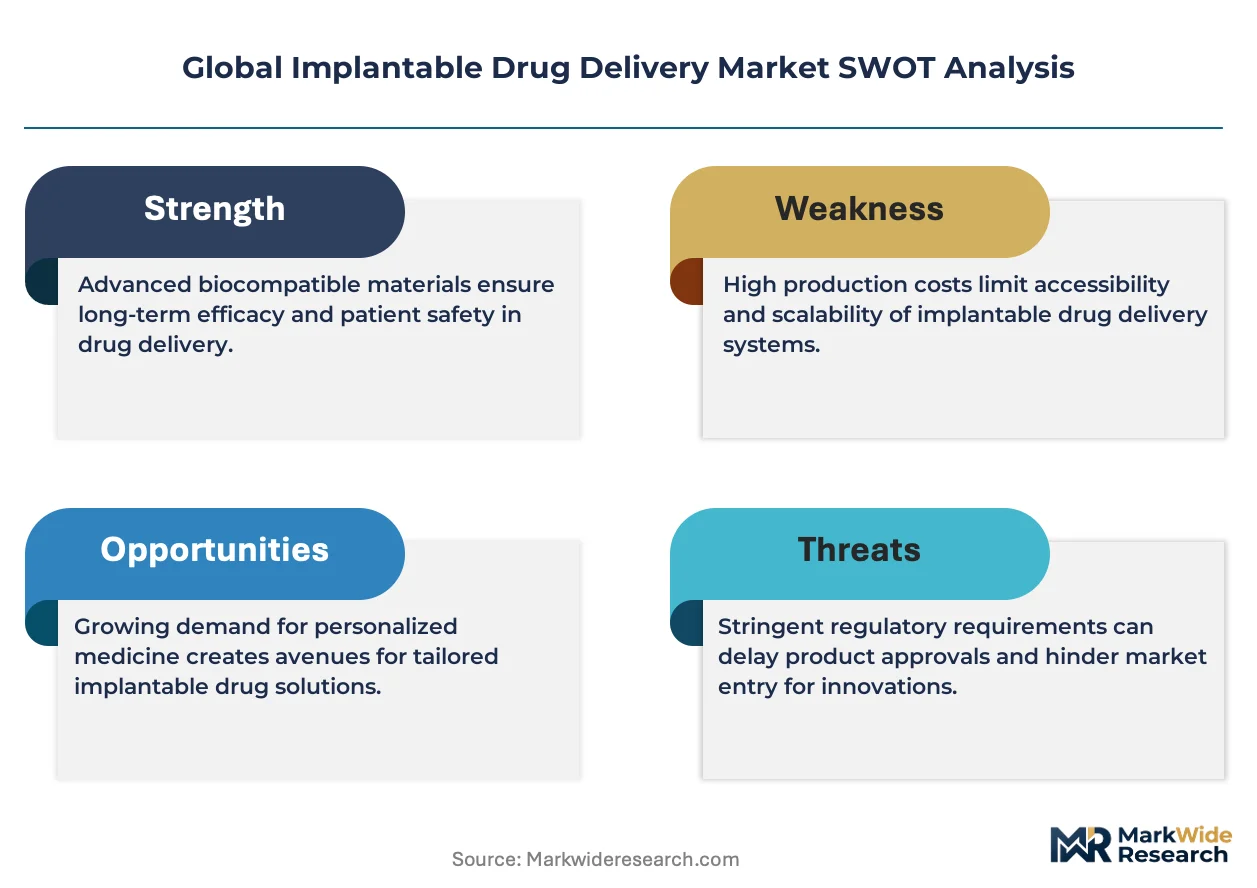
FDA premarket notification and EU MDR technical documentation requirements enforce biocompatibility validation and clinical evidence thresholds that filter out undercapitalized entrants. Japan's PMDA and China's NMPA impose additional localized stability testing protocols, fragmenting approval pathways and favoring multinationals with dedicated regulatory affairs infrastructure in Tokyo, Shanghai, and Munich. Stakeholders must monitor reimbursement coding convergence between implantable devices and companion biologics as payers recalibrate bundled payment frameworks.
Market Dynamics
Connected dosing platforms are compressing the competitive window between hardware manufacturers and algorithm developers, forcing device makers to acquire software capabilities or cede margin to digital-native entrants.
Growth Catalysts
- EU MDR conformity pathways:Streamlined technical documentation for Class III implantables accelerates market entry for polymer-based reservoir systems across Germany, France, and the Netherlands.
- Oncology infusion protocols:Zero-order kinetic requirements in platinum-based chemotherapy regimens pull osmotic pump adoption into hospital outpatient centers.
- Titanium housing advances:Additive manufacturing of patient-specific geometries reduces explantation trauma and extends device lifecycle economics.
Market Restraints
- Biologics stability testing:FDA-mandated shelf-life validation for protein formulations housed in implantable reservoirs extends development timelines by 18-24 months.
- Lithium cell supply:Electrochemical pump manufacturers face input concentration risk from South Korean and Japanese battery suppliers.
- Catheter thrombosis rates:Intrathecal delivery systems carry 12-15% occlusion incidence, limiting addressable patient pools for chronic pain applications.
Strategic Opportunities
- Glucose-responsive algorithms:Closed-loop hormone delivery for Type 1 diabetes patients creates white space beyond conventional insulin pump markets.
- Brazil ANVISA harmonization:Emerging regulatory alignment with FDA PMA standards reduces duplicate clinical trial burdens for Latin American expansion.
- Home infusion migration:Ambulatory surgical centers and specialty pharmacy channels displace hospital-based pump programming services.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 cytotoxicity and sensitization testing for new polymer formulations creates 9-14 month gate delays.
- Electrochemical firmware validation:FDA software-as-medical-device oversight for patient-triggered bolus algorithms demands specialized regulatory engineering talent scarce outside Boston and Minneapolis clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Implantable Drug Delivery Market |
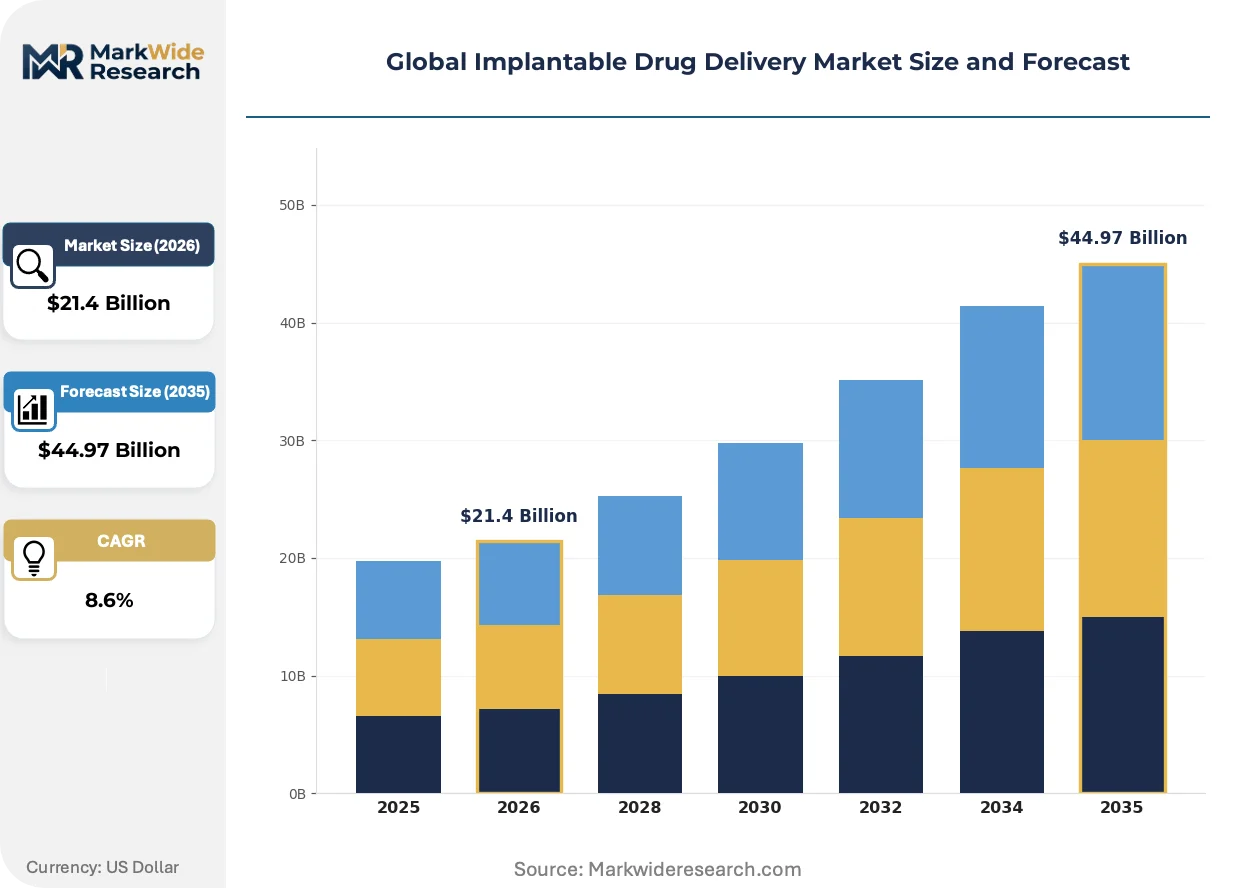
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $44.97 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pumps, Microchips, Port Systems, Implantable Pumps, Biodegradable Implants Application: Oncology Treatment, Pain Management, Hormone Therapy, Neurological Disorders, Cardiovascular Treatments End User: Hospitals, Specialty Clinics, Research Institutes, Ambulatory Surgical Centers, Rehabilitation Centers Delivery Technology: Reservoir-Based, Osmotic, Electrochemical, Osmosis-Driven, Mechanical, Biodegradable Matrix |
| Companies Covered | Medtronic, Johnson & Johnson, Boston Scientific Corporation, Abbott Laboratories, Becton, Dickinson and Company, Baxter International, Pfizer, Merck & Co., Inc., Bausch + Lomb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Implantable Drug Delivery Market Shifts & Advancements
Digital telemetry and predictive analytics are embedding intelligence directly into implantable reservoirs, transforming passive containers into therapeutic systems that communicate patient status and adjust dosing without clinical intervention.
Closed-loop electrochemical pumps is automating glucose-responsive insulin delivery through subcutaneous sensors and algorithmic dose modulation. Pediatric endocrinology units at academic medical centers in the United States and Germany are piloting these systems at triple-digit annual growth rates. This automation is compressing the traditional separation between diagnostic monitoring and therapeutic action into single-platform disease management.
Japan's PMDA has introduced accelerated approval pathways for combination device-drug products that demonstrate real-world performance data through post-market surveillance registries. Manufacturers now face reduced pre-market clinical trial requirements in exchange for mandatory patient outcome tracking. Neurological disorder applications in Osaka and Tokyo metropolitan hospitals are responding with earlier commercial launches and expanded indication-seeking behavior.
Specialty pharmacy networks are consolidating procurement authority for implantable pain management pumps away from individual hospital purchasing committees. Omnicare and similar distributors now negotiate device-biologic bundles directly with manufacturers, compressing price transparency and standardizing service-level agreements. This channel concentration is most visible in United States Medicare Part B reimbursement territories where site-of-care economics favor outpatient infusion centers over inpatient surgical placement.
Global Implantable Drug Delivery Market Segmentation
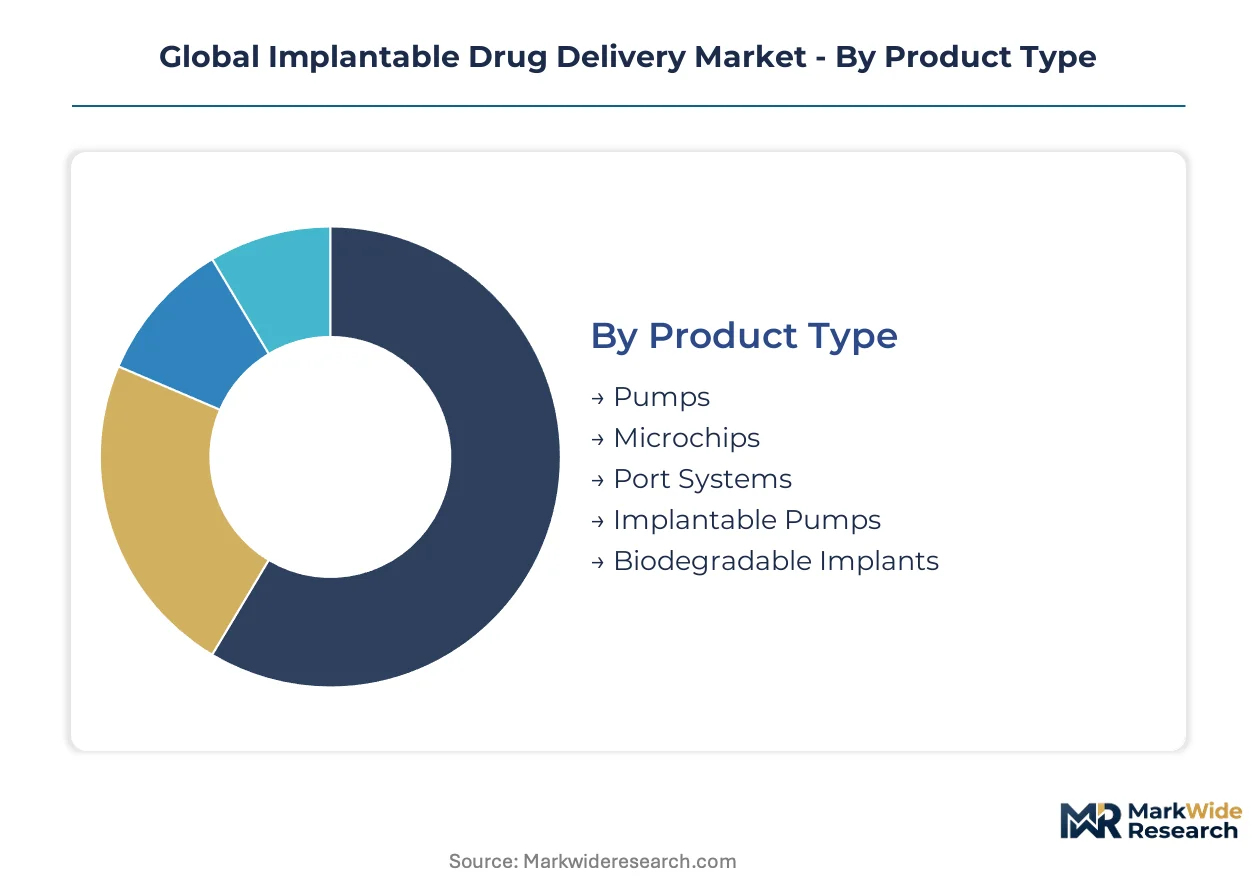
Implantable drug delivery systems fragment across four critical dimensions where buyer priorities diverge sharply. Technology selection determines regulatory pathway complexity, while end-user channel choice dictates service revenue attachment rates and lifecycle economics.
Product Type:
Hospital procurement committees weight explantation burden against refill frequency when selecting hardware platforms.
- Pumps:Titanium or polymer-encased reservoirs with programmable flow rates enable chronic infusion protocols. Demand concentrates in United States academic medical centers where interventional pain management services generate recurring refill revenue.
- Biodegradable Implants:Polymer matrix devices erode at controlled rates, eliminating surgical retrieval. Oncology units in Germany and Japan prioritize these for platinum-based chemotherapy regimens where patient compliance limits oral alternatives.
- Microchips:Silicon-based reservoirs with wireless telemetry enable remote dose adjustment.
- Port Systems:Subcutaneous access devices for intermittent bolus delivery.
- Implantable Pumps:Programmable electrochemical systems with patient-triggered bolus capability.
Pumps lead volumes today; biodegradable implants are gaining share fastest.
Application:
Clinical evidence requirements and reimbursement coding density separate high-investment from opportunistic indication expansion.
- Oncology Treatment:Zero-order kinetic delivery maintains narrow therapeutic windows for cytotoxic agents. Hospital outpatient centers in the United States and Japan drive adoption where bundled payment frameworks reward reduced hospitalization days.
- Pain Management:Intrathecal opioid delivery for refractory chronic pain requires specialized implantation expertise. United States Medicare Part B reimbursement territories concentrate demand where site-of-care economics favor ambulatory surgical placement.
- Hormone Therapy:Testosterone and estrogen depot formulations for endocrine disorders.
- Neurological Disorders:Intraparenchymal delivery for Parkinson's disease and epilepsy.
- Cardiovascular Treatments:Anticoagulant and antiarrhythmic localized delivery systems.
Pain management anchors current revenue; oncology applications are expanding most quickly.
End User:
Capital equipment budgets and biologic procurement authority determine channel power distribution.
- Hospitals:Integrated delivery networks with dedicated interventional radiology and anesthesia departments control high-complexity implantation procedures. Germany's university hospitals and Japan's metropolitan medical centers concentrate purchasing authority for electrochemical pump systems.
- Ambulatory Surgical Centers:Outpatient facilities with streamlined procedural protocols capture migration from inpatient settings. United States specialty pharmacy networks now negotiate device-biologic bundles directly with these centers.
- Specialty Clinics:Pain management and endocrinology focused practices.
- Research Institutes:Academic medical centers conducting combination product trials.
- Rehabilitation Centers:Post-implantation patient monitoring and dose adjustment services.
Hospitals dominate installed base; ambulatory surgical centers show the steepest expansion trajectory.
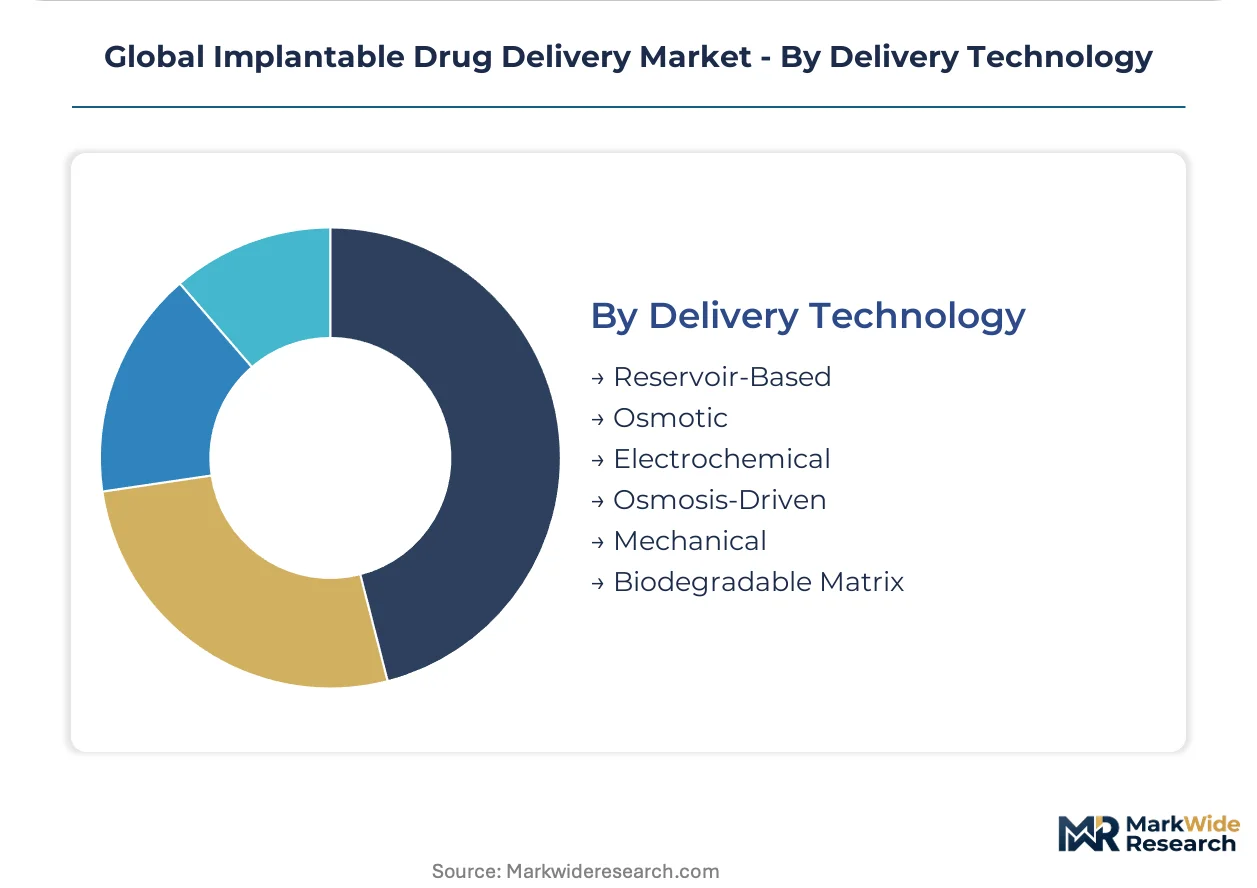
Delivery Technology:
Manufacturing process maturity and raw material supply security separate defendable margin positions from commodity competition.
- Reservoir-Based:Passive diffusion chambers with fixed orifice geometries provide predictable release kinetics. Mature polymer chemistry supply chains in the United States and Netherlands support cost-competitive production for chronic hormone therapy applications.
- Electrochemical:Battery-powered piston or bellows mechanisms enable patient-triggered bolus delivery. South Korean and Japanese lithium cell suppliers create input concentration risk for manufacturers lacking alternative sourcing.
- Osmotic:Semi-permeable membranes generate constant pressure-driven flow.
- Osmosis-Driven:Solute concentration gradients power release without external energy.
- Mechanical:Spring-loaded or gas-pressurized reservoirs for fixed-rate delivery.
- Biodegradable Matrix:Erodible polymer formulations with tunable degradation profiles.
Reservoir-based systems hold volume leadership; electrochemical platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's university hospitals drive osmotic pump adoption for oncology protocols, while Japan's metropolitan medical centers concentrate purchasing authority for electrochemical systems. The United States anchors pain management pump volumes through Medicare Part B reimbursement territories. China's NMPA accelerates combination product reviews. Brazil's ANVISA harmonization reduces duplicate clinical burdens for Latin American expansion.
United States
Academic medical centers in Boston and Minneapolis generate recurring refill revenue from interventional pain management services. FDA premarket notification pathways enforce biocompatibility validation thresholds that filter undercapitalized entrants. Specialty pharmacy networks in Medicare Part B territories now negotiate device-biologic bundles directly with ambulatory surgical centers, compressing price transparency.
Germany
University hospitals in Munich and Heidelberg prioritize biodegradable implants for platinum-based chemotherapy regimens where patient compliance limits oral alternatives. EU MDR technical documentation requirements for Class III implantables accelerate market entry for polymer-based reservoir systems across Bavaria and Baden-Württemberg manufacturing clusters.
Japan
Metropolitan medical centers in Tokyo and Osaka concentrate purchasing authority for programmable electrochemical pumps with patient-triggered bolus capability. PMDA accelerated approval pathways for combination device-drug products reduce pre-market clinical trial requirements in exchange for mandatory post-market surveillance registries.
China
Shanghai and Beijing medical centers pilot glucose-responsive hormone delivery systems at triple-digit annual growth rates. NMPA localized stability testing protocols for implantable reservoirs fragment approval pathways and favor multinationals with dedicated regulatory affairs infrastructure in Pudong and Haidian districts.
Brazil
São Paulo and Rio de Janeiro hospital networks expand adoption of reservoir-based systems for chronic disease management. ANVISA regulatory alignment with FDA PMA standards reduces duplicate clinical trial burdens, enabling faster Latin American market entry for polymer chemistry advances that reduce explantation trauma.
Global Implantable Drug Delivery Market Competitive Landscape
Top-tier vendors anchor programmable infusion and neuromodulation infrastructure, while mid-tier specialists compete on polymer chemistry and catheter-integrated architectures. The vendor base stratifies across three archetypes: diversified medtech conglomerates with neuromodulation divisions, interventional pain management specialists, and glucose-responsive algorithm developers. Competitive moves concentrate on strategic partnerships with specialty pharmacy networks and technology licensing for closed-loop dosing protocols.
Within the diversified medtech tier, Medtronic plc and Boston Scientific Corporation exemplify scale-driven positions anchored in interventional infrastructure. Abbott Laboratories occupies a distinct archetype competing on algorithmic precision rather than hardware alone. Johnson & Johnson and Becton, Dickinson and Company represent legacy healthcare conglomerates with broad device portfolios spanning multiple delivery technology categories.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Becton, Dickinson and Company |
| Baxter International |
| Pfizer |
| Merck & Co., Inc. |
| Bausch + Lomb |
| Others |
Supply & Pricing Matrix
Lithium cell procurement from South Korean and Japanese suppliers cascades through electrochemical pump manufacturing cost structures, compressing margins for device makers lacking alternative sourcing while polymer reservoir systems in the Netherlands and United States maintain pricing stability through mature chemistry supply chains.
Pricing Analysis
Capacity additions in German and Dutch polymer manufacturing clusters are reshaping price floors for reservoir-based implantable systems, enabling three-tier pricing structure across premium, standard, and economy levels differentiated by FDA PMA tier and ISO 10993 certification completeness. Price differentiation stems from biocompatibility validation depth and vertical integration into polymer synthesis. Pricing pressure intensifies in electrochemical segments due to lithium battery input concentration. Academic medical centers in the United States show lowest price sensitivity; ambulatory surgical centers in Medicare Part B territories exhibit highest.
Supply Chain Analysis
ISO 10993 and EU MDR conformity assessment requirements gate supplier qualification, fragmenting component sourcing across United States polymer chemistry specialists, South Korean lithium cell manufacturers, and Japanese precision machining houses. Raw material dependencies center on medical-grade silicone, titanium powder for additive manufacturing, and lithium thionyl chloride cells. Single-source vulnerability concentrates in Japanese battery suppliers. Distribution runs through specialty pharmacy networks and GPO contracts with hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between Japan's PMDA accelerated approval pathways and FDA's extended biologics stability timelines creates geographic cost differentials for combination product developers, rewarding infrastructure placement in Tokyo and Osaka metropolitan clusters.
For Market Incumbents: Extend software-defined dosing capabilities through acquisition of algorithm developers or cede margin to digital-native entrants; deepen in-house production of glucose-responsive control systems to defend against Abbott Laboratories' algorithmic precision positioning. Backward integration into polymer synthesis secures supply continuity against EU MDR documentation delays. For New Entrants and Emerging Players: Enter via Brazil's ANVISA harmonization with FDA PMA standards, exploiting reduced clinical trial duplication burdens for Latin American expansion. Target ambulatory surgical center channels in United States Medicare Part B territories where site-of-care economics favor outpatient pump programming. Lead with biodegradable implant platforms for oncology applications in Germany and Japan. For Investors and Strategic Acquirers: Consolidation pressure builds where electrochemical firmware validation talent concentrates in Boston and Minneapolis clusters, creating acquisition premiums for regulatory engineering capabilities. Mid-tier polymer chemistry specialists with ISO 10993-certified formulations represent priority targets. Watch PMDA post-market surveillance registry performance data as inflection signal for combination product viability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Premarket approval pathways enforce biocompatibility thresholds that filter undercapitalized device entrants. |
| CE Marking Pathway | EU MDR technical documentation accelerates market entry for Class III polymer reservoir systems. |
| Hospital System Partnership | Integrated delivery networks in Boston and Minneapolis generate recurring refill revenue streams. |
| Software Companion Development | Closed-loop algorithms automate glucose-responsive insulin delivery for Type 1 diabetes patients. |
| Reimbursement Strategy | Medicare Part B coding convergence between implantable devices and companion biologics shapes bundled payments. |
Research Methodology
Multiple input streams — primary interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and regulatory affairs leads; secondary validation through FDA 510(k) and PMA filings, EMA submission databases, ClinicalTrials.gov records, and CMS Medicare reimbursement data; plus customs records for polymer and titanium trade flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, application, end user, and delivery technology segmentation dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from modeled adoption curves for electrochemical and osmotic platforms, with cross-referencing to hospital procurement database trends and specialty pharmacy network expansion patterns.
Inputs from FDA, EMA, and PMDA regulatory filing databases were available through the study window; gaps in real-world post-market surveillance performance data introduce uncertainty bands around combination product adoption forecasts. A model refresh is warranted upon material change in EU MDR conformity assessment timelines or lithium cell supply chain restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Sweden Respiratory Devices Market
Medical Devices
Neuromodulation Market
Medical Devices
Endoscope Flushing Pumps Market
Medical Devices
Spinal Stenosis Implant Market
Medical Devices
Middle East and Africa Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Global Artificial Tendons and Ligaments Market
Medical Devices
Lactate Meter Market
Medical Devices
Catheter Introducer Sheaths Market
Medical Devices
Global Obstetrics Devices Market
Medical Devices
Anti-Blue Ray Myopia Lenses Market
Medical Devices
Global Artificial Pancreas Device System Market
Medical Devices
Tubal Obstruction Devices Market
Medical Devices
Global Robotic Nurse Assistant Market
Medical Devices
Veterinary Catheters Market
Medical Devices
Pharma Robots Market
Medical Devices
Male Artificial Urinary Sphincter Market