
 Spectroscopy Software Market | 2026-2036
Spectroscopy Software Market Size, Share, and Industry Trends Forecast 2026-2036
Spectroscopy Software Market Intelligence
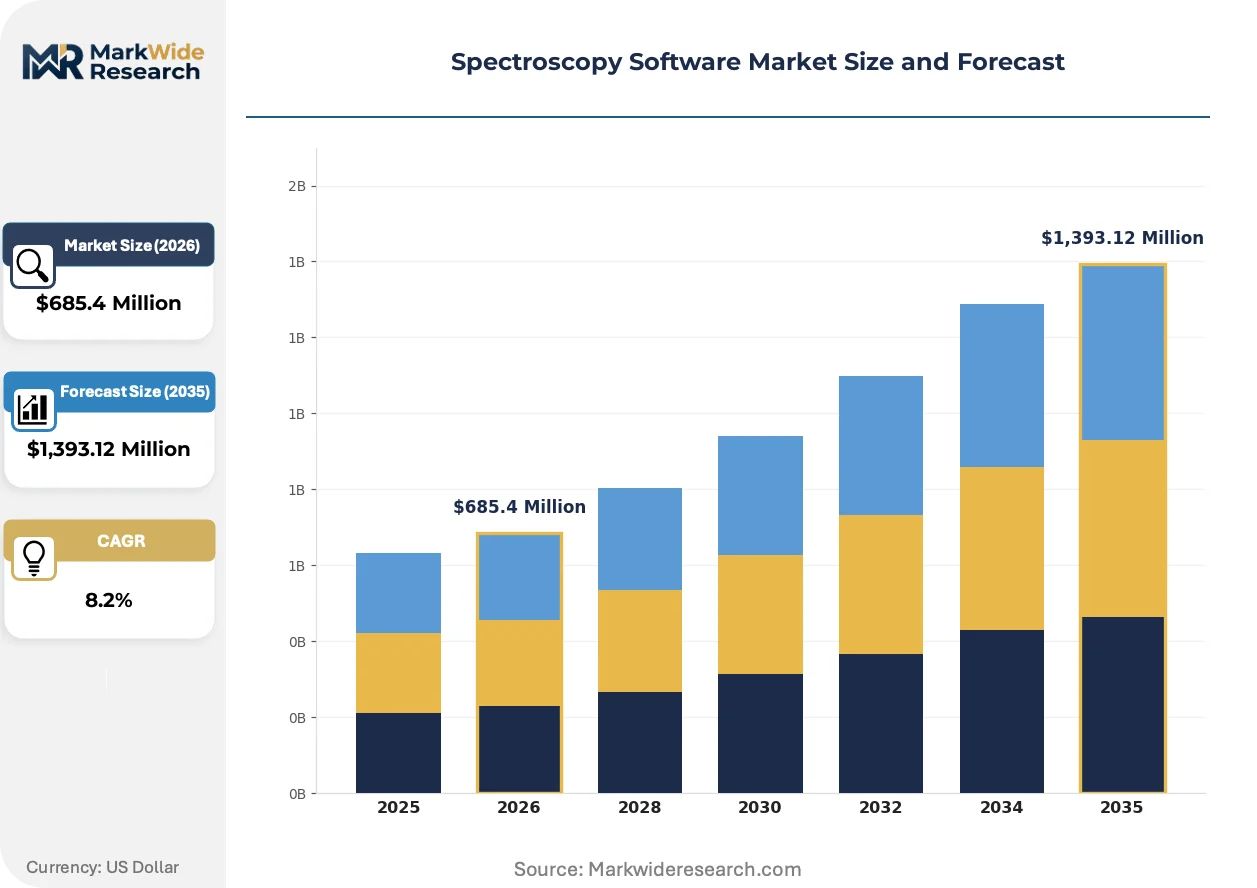
Platform licensing revenue is reshaping competitive economics in spectroscopy software as vendors migrate from perpetual licenses to recurring subscription models. Thermo Fisher Scientific leverages its embedded instrument software ecosystem to sustain high renewal rates across installed bases. Bruker Corporation anchors its position through specialized Raman and mass spectrometry workflow packages that dominate academic research procurement. Genedata AG competes by extending bioinformatics integration capabilities that differentiate its offering in biopharmaceutical customer segments.
Spectroscopy software encompasses computational platforms that control optical and mass spectrometers, process spectral data through deconvolution algorithms, and manage compliance documentation with electronic signature capabilities. These systems execute peak identification, quantitative calibration, and spectral library matching with resolution thresholds typically reaching picometer precision in UV-Vis configurations. UV-Vis and Raman spectroscopy software categories occupy mature margin pools tied to replacement cycles in quality control laboratories, while cloud-based solutions represent the fastest-expanding technology segment as industrial manufacturers seek remote instrument management. Desktop applications retain dominance in academic institutions where data sovereignty concerns limit SaaS migration, though embedded systems are concentrating growth in process analytical technology deployments.
FDA 21 CFR Part 11 validation requirements in the United States and EU GMP Annex 11 guidelines in Europe shape product development roadmaps by mandating audit trails and electronic records for pharmaceutical applications. ISO 17025 accreditation standards for testing laboratories further constrain software architecture choices around data integrity and traceability. Stakeholders must monitor regulatory divergence between FDA electronic submission requirements and emerging EU AI Act provisions governing algorithmic spectral interpretation tools.
Market Dynamics
The migration from perpetual licensing to subscription-based revenue models is restructuring vendor economics and customer procurement patterns across pharmaceutical and industrial analytical laboratories.
Growth Catalysts
- Cloud Platform Adoption:Pharmaceutical quality control laboratories are deploying cloud-based spectroscopy platforms to enable remote instrument management and centralized data repositories.
- FDA 21 CFR Part 11:Compliance mandates in the United States are accelerating validation investments for electronic records and audit trail capabilities in laboratory software procurement.
- Process Analytical Technology:Embedded spectroscopy systems are concentrating deployment in continuous manufacturing environments requiring real-time spectral monitoring.
Market Restraints
- Data Sovereignty Constraints:Academic institutions in Germany and Switzerland limit SaaS migration due to institutional data residency policies and research data protection requirements.
- Validation Cost Burden:FDA and EU GMP Annex 11 compliance documentation requirements impose substantial labor costs on software deployment timelines in pharmaceutical applications.
- Legacy Hardware Interoperability:Decade-old UV-Vis and Raman instruments lack firmware architectures compatible with modern spectral processing algorithms.
Strategic Opportunities
- Biopharmaceutical Bioinformatics Integration:Convergence of mass spectrometry data with proteomics and metabolomics platforms creates workflow differentiation in drug discovery segments.
- EU AI Act Provisions:Emerging algorithmic governance frameworks for spectral interpretation tools establish first-mover advantage for compliant vendors in European pharmaceutical markets.
- India's PLI Scheme:Production-linked incentives for pharmaceutical manufacturing are expanding analytical instrumentation procurement in Mumbai and Hyderabad clusters.
Industry Challenges
- Spectroscopy Data Science Talent:Shortages of computational chemists capable of deploying machine learning for spectral deconvolution constrain algorithm development pipelines.
- ISO 17025 Accreditation Timelines:Testing laboratory certification processes for software validation create 12-18 month procurement delays for quality control departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spectroscopy Software Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Pharmaceuticals, Biotechnology, Environmental Testing, Food & Beverage Product Type: UV-Vis Spectroscopy, Near-Infrared Spectroscopy, Raman Spectroscopy, Mass Spectrometry Technology: Software-as-a-Service, Embedded Systems, Cloud-Based Solutions, Desktop Applications End User: Academic Institutions, Research Laboratories, Industrial Manufacturers, Quality Control Departments |
| Companies Covered | Agilent Technologies Inc., Bruker Corporation, Thermo Fisher Scientific Inc., Shimadzu Corporation, Revvity Inc, Waters Corporation, Genedata AG, Advanced Chemistry Development, Lablicate GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spectroscopy Software Market Strategic Shifts & Innovations
Artificial intelligence integration and regulatory digitization are compressing traditional software development cycles while expanding the addressable market beyond conventional laboratory environments.
Machine learning algorithms for automated peak identification and spectral library matching are rendering obsolete manual interpretation workflows in high-throughput screening laboratories. Contract research organizations in the United States and United Kingdom are adopting these platforms at accelerated procurement cycles. The shift is compressing analytical service delivery timelines from days to hours for pharmaceutical clients.
EU GMP Annex 11 and the emerging EU AI Act are mandating algorithmic transparency and auditability for spectral interpretation tools used in pharmaceutical quality control. Software vendors must now document training data provenance and model decision pathways. German and Swiss pharmaceutical manufacturers are prioritizing vendors with pre-validated compliance architectures to accelerate deployment timelines.
Pharmaceutical buyers are consolidating vendor relationships around integrated instrument-software ecosystems rather than maintaining fragmented point solutions. This pattern concentrates procurement authority within centralized laboratory informatics departments. The behavior is most visible in United States biopharmaceutical headquarters and European Big Pharma manufacturing sites.
Spectroscopy Software Market Segmentation
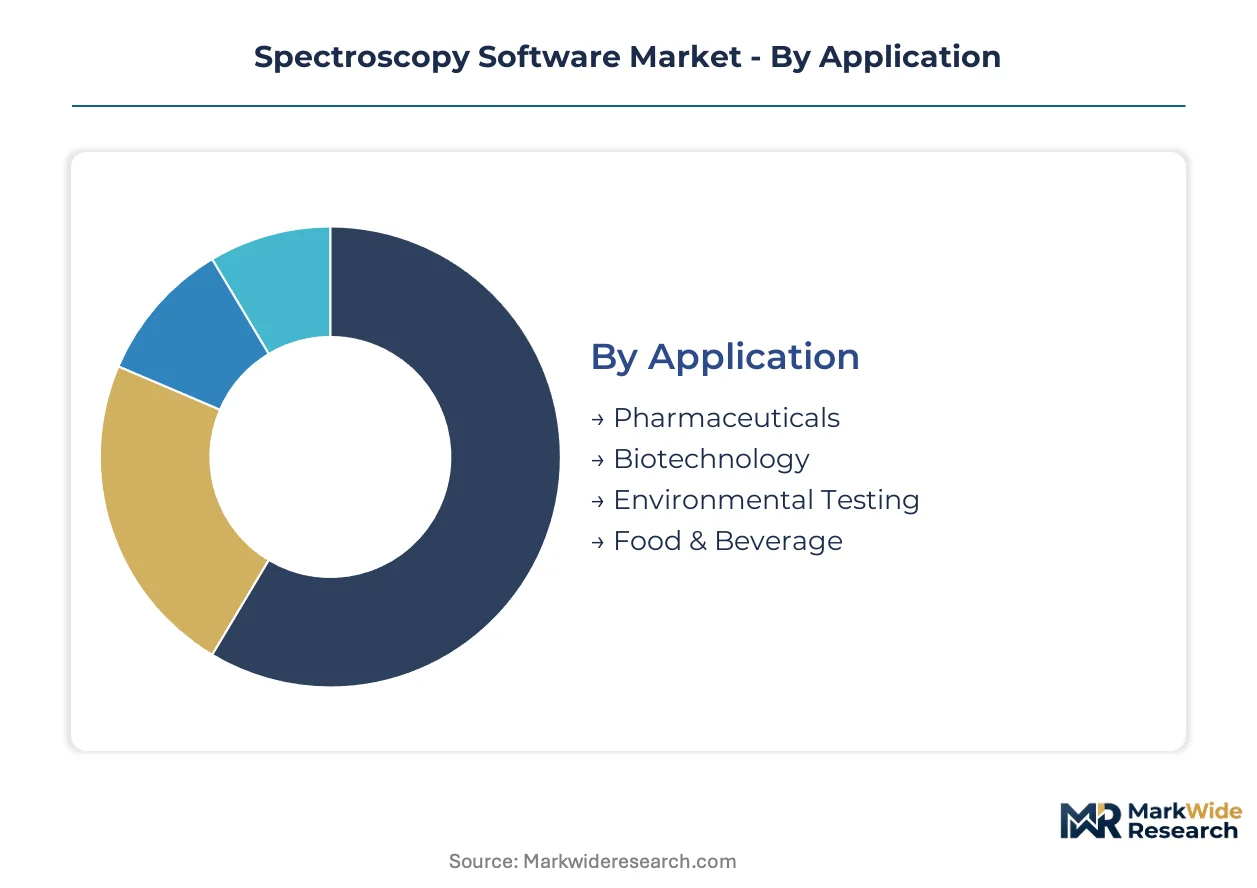
Spectroscopy software segments map directly to distinct procurement budgets, validation requirements, and technology refresh cycles across pharmaceutical, academic, and industrial customer bases. Each category reveals divergent growth velocities and margin profiles that reshape vendor resource allocation.
Application:
Use-case spectrum spans from regulated pharmaceutical quality control to exploratory academic research, with compliance burden and software complexity scaling accordingly.
- Pharmaceuticals:FDA 21 CFR Part 11 mandates dominate software architecture decisions, requiring electronic signatures, audit trails, and validation documentation that extend deployment timelines. Demand concentrates in United States biopharmaceutical headquarters and European Big Pharma manufacturing sites where centralized laboratory informatics departments consolidate vendor relationships.
- Biotechnology:Convergence of mass spectrometry with proteomics and metabolomics platforms drives workflow integration investments in drug discovery segments. Genedata AG competes aggressively here through bioinformatics capabilities that differentiate its offering from instrument-centric vendors.
- Environmental Testing:ISO 17025 accreditation requirements constrain data integrity architectures for testing laboratories.
- Food & Beverage:Quality control departments deploy UV-Vis configurations for routine compositional analysis.
The dominant share belongs to Pharmaceuticals, while Biotechnology is closing the gap fastest.
Product Type:
Technology maturity and replacement cycles create tiered margin pools, with established modalities funding investment in emerging spectral techniques.
- UV-Vis Spectroscopy:Mature software category tied to replacement cycles in quality control laboratories, with picometer precision thresholds standard in modern configurations. Demand concentrates in industrial manufacturers seeking routine compositional analysis with minimal operator training requirements.
- Raman Spectroscopy:Specialized workflow packages dominate academic research procurement, with Bruker Corporation anchoring position through instrument-software bundling. German industrial analytical instrumentation clusters around Munich and Berlin drive regional demand concentration.
- Near-Infrared Spectroscopy:Process analytical technology deployments favor embedded system architectures.
- Mass Spectrometry:Bioinformatics integration requirements elevate software complexity in biopharmaceutical segments.
UV-Vis Spectroscopy commands the largest installed base, though Raman Spectroscopy exhibits the steepest expansion trajectory among research-intensive customers.
Technology:
Delivery model selection reflects organizational data sovereignty policies, IT infrastructure maturity, and regulatory jurisdiction constraints.
- Cloud-Based Solutions:Remote instrument management and centralized data repositories attract pharmaceutical quality control laboratories seeking operational efficiency. Industrial manufacturers in continuous production environments prioritize real-time spectral monitoring capabilities that cloud architectures enable.
- Desktop Applications:Data sovereignty concerns limit SaaS migration in academic institutions, particularly in Germany and Switzerland where institutional data residency policies protect research outputs. These deployments retain dominance where local control over spectral libraries and proprietary algorithms remains non-negotiable.
- Software-as-a-Service:Subscription economics restructure vendor-customer relationships around recurring revenue.
- Embedded Systems:Process analytical technology deployments concentrate growth in manufacturing-integrated configurations.
Desktop Applications maintain the deepest installed base, yet Cloud-Based Solutions are gaining share fastest among industrial manufacturers.
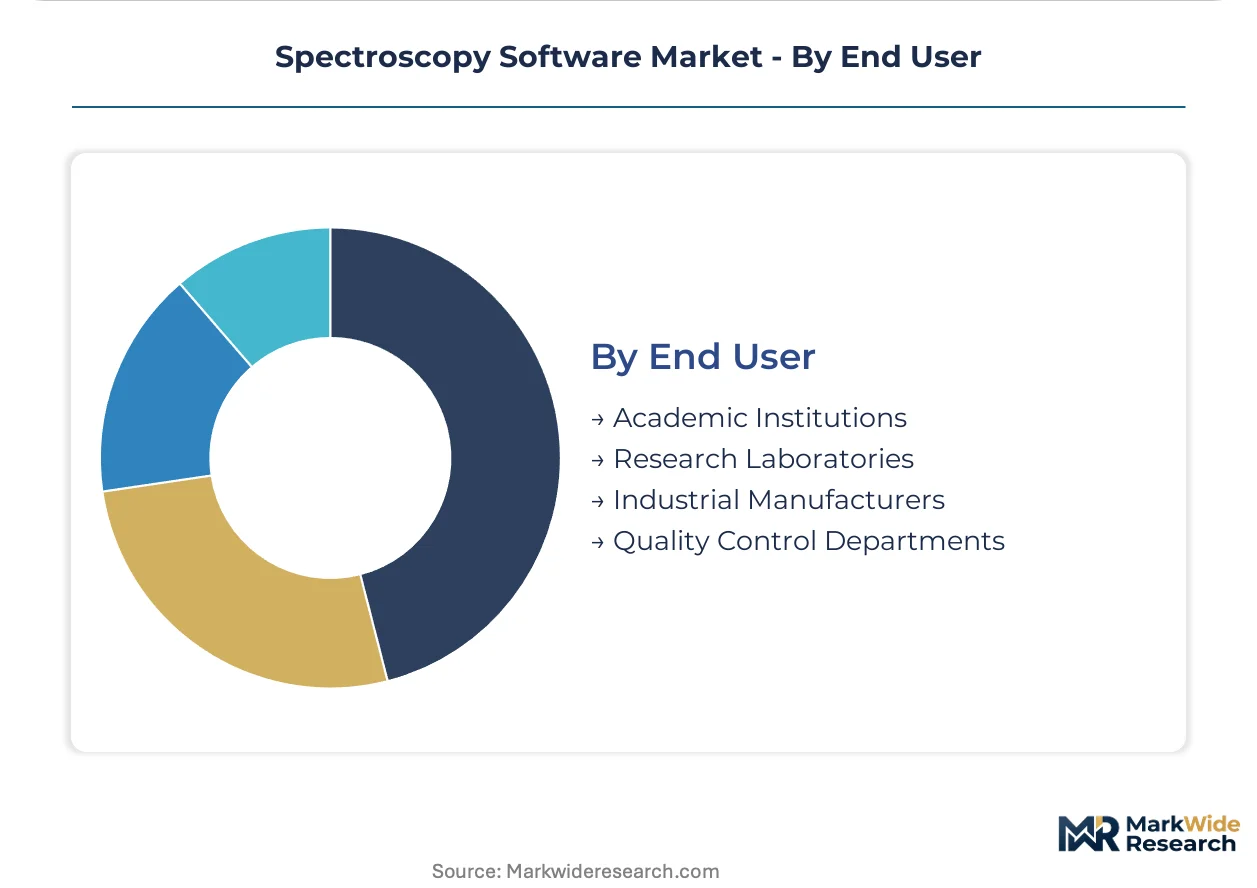
End User:
Organizational type dictates procurement authority, validation burden, and willingness to absorb subscription pricing models.
- Quality Control Departments:Centralized laboratory informatics departments in United States biopharmaceutical headquarters consolidate vendor relationships around integrated instrument-software ecosystems. FDA and EU GMP Annex 11 compliance documentation requirements impose substantial labor costs on deployment timelines.
- Academic Institutions:Data residency policies in Germany and Switzerland limit SaaS migration, preserving demand for perpetual-licensed desktop applications. Research data protection requirements and proprietary spectral library ownership sustain preference for locally-hosted solutions.
- Research Laboratories:High-throughput screening requirements drive machine learning adoption for automated peak identification.
- Industrial Manufacturers:Production-linked incentives in India's pharmaceutical clusters expand analytical instrumentation procurement in Mumbai and Hyderabad.
Quality Control Departments represent the largest revenue pool, while Research Laboratories are expanding procurement most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Academic institutions in Germany and Switzerland resist subscription pricing due to data sovereignty mandates, while pharmaceutical manufacturers in the United States absorb premium validation costs without procurement hesitation.
United States
FDA 21 CFR Part 11 compliance mandates dominate software procurement decisions across biopharmaceutical headquarters. Electronic records and audit trail requirements extend deployment timelines and elevate vendor selection criteria. Quality control laboratories in Greater Boston and the San Francisco Bay Area consolidate vendor relationships around integrated instrument-software ecosystems.
Germany
Industrial analytical instrumentation clusters around Munich and Berlin drive concentrated demand for Raman and mass spectrometry workflow packages. EU GMP Annex 11 guidelines shape product development roadmaps alongside emerging EU AI Act provisions. Academic institutions in Bavaria and Baden-Württemberg limit SaaS migration due to institutional data residency policies protecting research outputs.
Switzerland
Swissmedic regulations and stringent research data protection requirements sustain preference for locally-hosted desktop applications over cloud architectures. Pharmaceutical manufacturers in Basel prioritize vendors with pre-validated compliance architectures to accelerate deployment timelines. The country's precision instrumentation heritage supports premium pricing tolerance for validated spectroscopy platforms.
India
Production-linked incentive schemes for pharmaceutical manufacturing expand analytical instrumentation procurement in Mumbai and Hyderabad clusters. CDSCO compliance documentation requirements are accelerating validation investments as domestic manufacturers target export markets. Contract research organizations in these metro regions adopt machine learning-integrated platforms at compressed procurement cycles.
United Kingdom
Contract research organizations in Cambridge and Oxford are adopting automated peak identification platforms to compress analytical service delivery timelines. MHRA alignment with FDA electronic submission requirements simplifies validation pathways for multinational pharmaceutical clients. Academic institutions in Scotland and Northern England retain data sovereignty concerns that limit cloud migration.
Spectroscopy Software Market Key Industry Players
Capability concentration sits with specialized bioinformatics vendors; scale advantage sits with diversified analytical instrumentation conglomerates. The market structures around three tiers: embedded instrument software ecosystems, standalone workflow specialists, and cloud-native platform entrants. Two dominant competitive moves are reshaping positioning: strategic consolidation around integrated instrument-software bundles, and migration from perpetual licensing to recurring subscription revenue models.
Within the diversified instrumentation tier, Thermo Fisher Scientific Inc. and Bruker Corporation exemplify scale-driven competitive positioning through embedded software ecosystems and specialized Raman workflow packages respectively. Genedata AG occupies a distinct position among bioinformatics specialists, differentiating through proteomics and metabolomics integration capabilities that resonate with biopharmaceutical research segments.
| Leading Market Players |
|---|
| Agilent Technologies Inc. |
| Bruker Corporation |
| Thermo Fisher Scientific Inc. |
| Shimadzu Corporation |
| Revvity Inc |
| Waters Corporation |
| Genedata AG |
| Advanced Chemistry Development |
| Lablicate GmbH |
| Others |
Cost & Logistics Intelligence
Overcapacity in cloud-based spectroscopy platform development is compressing vendor margins while forcing incumbents to bundle validation services at discounted rates. This utilization dynamic simultaneously elevates buyer negotiating power in pharmaceutical procurement and accelerates consolidation among standalone software vendors unable to absorb implementation cost overruns.
Pricing Analysis
After-sales validation and compliance documentation services drive lifetime value differentiation between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels segments by FDA 21 CFR Part 11 certification depth and audit trail granularity. Price differentiation hinges on electronic signature architecture complexity and EU GMP Annex 11 pre-validation status. Pricing pressure stems from India's PLI scheme expanding domestic vendor competition in Mumbai and Hyderabad clusters. Academic institutions in Germany exhibit highest price sensitivity due to constrained public research budgets, while United States biopharmaceutical headquarters absorb premium tiers without procurement hesitation.
Supply Chain Analysis
Supplier-financing facilities extended by German and Swiss analytical instrumentation manufacturers are tightening payment terms for independent software vendors. Component concentration centers on semiconductor fabrication in Taiwan, specialized optical sensor production in Japan, and cloud infrastructure provisioning from United States hyperscalers. Raw material dependencies include high-purity germanium substrates, indium gallium arsenide detectors, and GPU accelerators for machine learning inference. Single-source vulnerability in EUV lithography equipment for chip fabrication poses structural risk to embedded system production. Distribution runs through direct enterprise sales teams for pharmaceutical accounts and academic consortium purchasing agreements for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spectroscopy software market is recovering from a cyclical trough driven by pharmaceutical capital expenditure normalization following pandemic-era laboratory expansion. Replacement cycles for decade-old UV-Vis installations are reactivating quality control procurement pipelines.
For Market Incumbents: Harden embedded instrument-software ecosystem lock-in by extending firmware exclusivity to legacy hardware retrofits. Consolidate validation documentation capabilities in-house to capture compliance service revenue streams. Cloud-native platform entrants threaten subscription pricing power through API-first architectures; vertical integration into proprietary spectral libraries defends margin position.
For New Entrants and Emerging Players: Mid-tier contract research organizations in India and Southeast Asia represent the most penetrable entry point for SaaS-native platforms lacking FDA pre-validation. Academic institutions in Switzerland and Germany constrained by data sovereignty policies offer white-space for locally-hosted desktop alternatives. Go-to-market execution should anchor on compressed implementation timelines versus incumbent validation burdens.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among bioinformatics specialists with proteomics integration capabilities. Long-term viability across the analysis window favors vendors with pre-validated compliance architectures serving pharmaceutical quality control departments. Acquisition target archetype: specialized Raman workflow developers with embedded system expertise. Signal to watch: CDSCO validation investment acceleration among Indian pharmaceutical exporters.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidated instrument-software ecosystems reduce vendor fragmentation in United States biopharmaceutical procurement. |
| Regulatory Pre-Validation | FDA 21 CFR Part 11 pre-certified architectures accelerate deployment timelines for quality control laboratories. |
| Backward Integration | In-house spectral library development captures proprietary algorithm revenue from academic research segments. |
| Geographic Expansion | India's PLI scheme clusters in Mumbai and Hyderabad expand addressable instrumentation procurement pools. |
| Acquisition of Specialist Firm | Bioinformatics integration capabilities differentiate positioning in biopharmaceutical drug discovery workflows. |
Research Approach
Operator-level perspectives from laboratory informatics directors, regulatory affairs leads at pharmaceutical manufacturers, spectroscopy platform engineers, and academic procurement officers anchored the qualitative base. Primary interview findings triangulated against FDA 21 CFR Part 11 guidance documents, EU GMP Annex 11 implementation reports, ISO 17025 accreditation databases, and hyperscaler cloud infrastructure disclosures. Bottom-up segmentation modeling and top-down market sizing converged on value estimates across deployment modes and end-user categories.
Scenario-bracketing around regulatory digitization velocity and pharmaceutical capital expenditure cycles bounded projection uncertainty. Segmentation dimensions spanned application type, product modality, technology delivery model, end-user organizational type, and regional regulatory cluster. CAGRs derived from instrument replacement cycle analysis, cloud migration elasticity estimates, and compliance-driven upgrade propensity scoring. Machine learning algorithm adoption curves and EU AI Act implementation timelines served as industry-specific forecast inputs.
Stress conditions across FDA enforcement intensity, EU algorithmic governance rollout speed, and Indian pharmaceutical export growth were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization and cloud infrastructure cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Global Fixed Zirconia Oxygen Analyzer Market
Analytical Instruments
Africa Digital Thermometer Market
Analytical Instruments
Process Analytical Instrumentation Market
Analytical Instruments
Scanning Electron Microscopes (SEM) Market
Analytical Instruments
Ultraviolet (UV) Analyzer Market
Analytical Instruments
Abbe Refractometers Market
Analytical Instruments
Kinetic Chromogenic Spectrophotometer Market
Analytical Instruments
Seawater Refractometers Market
Analytical Instruments
AFM Probe Market
Analytical Instruments
TDLAS Moisture Analyzers Market
Analytical Instruments
Global Infrared Thermography Market
Analytical Instruments
Portable Chromatography Systems Market
Analytical Instruments
Air Sampling Equipment Market
Analytical Instruments
Gas Analyzer Market
Analytical Instruments
Melt Flow Meter Market
Analytical Instruments
Portable Gas Analyzer Market