
 Seawater Refractometers Market | 2026-2036
Seawater Refractometers Market Size, Share, and Industry Trends Forecast 2026-2036
Seawater Refractometers Market Insights
Commercial aquaculture is restructuring demand patterns across the seawater refractometer landscape as intensive farming operations replace traditional open-water harvesting. Hanna Instruments leverages its digital platform expertise to dominate electronic salinity testing in Southeast Asian shrimp farms. Atago sustains technology leadership through precision optical systems calibrated for brackish water transitions. Red Sea anchors the premium segment with reef-specialized instruments targeting coral propagation facilities.
Seawater refractometers are optical or electronic instruments that measure dissolved salt concentration by detecting the refractive index of water samples, typically calibrated to the Practical Salinity Scale with resolution to 0.1 parts per thousand for laboratory-grade units. Their primary purpose is enabling precise salinity control in living marine systems, industrial desalination, and environmental compliance monitoring. Digital refractometers command the fastest expansion as Bluetooth-enabled handheld units replace analog optics in field-deployed water quality testing. Optical technology retains the largest installed base but faces margin compression from ultrasonic alternatives entering marine research applications. Portable refractometers occupy the highest volume tier among environmental agencies conducting shoreline compliance sweeps.
EPA water quality standards and FDA seafood safety protocols shape instrument specifications for U.S. aquaculture and environmental monitoring end users, while ISO 17025 accreditation requirements drive calibration service demand among research laboratories. The EU Marine Strategy Framework Directive and REACH substance restrictions influence material selection for European-manufactured optical components. Stakeholders must monitor how salinity monitoring gets integrated into broader IoT water quality networks rather than treated as standalone measurement.
Market Dynamics
Bluetooth-enabled handheld refractometers are automating salinity data collection across intensive aquaculture operations, compressing manual sampling cycles from hours to minutes while forcing legacy optical instrument suppliers to retrofit connectivity modules or cede field-deployed testing contracts.
Growth Catalysts
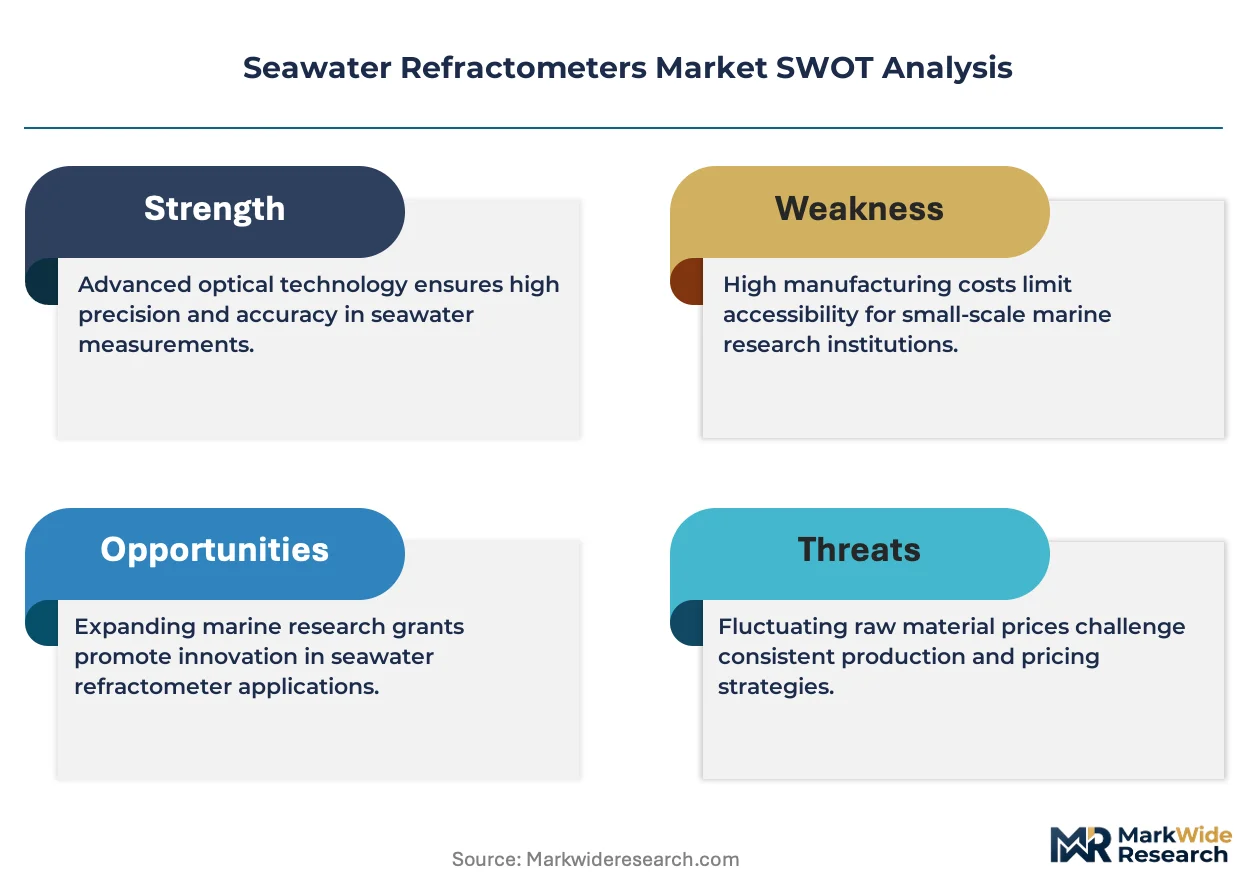
- EPA Water Quality Standards:Tightened dissolved salt monitoring mandates for Gulf shrimp farms and Pacific Northwest salmon hatcheries are mandating precision salinity tracking at 0.1 parts per thousand resolution.
- Intensive Aquaculture Expansion:Stock density increases in Southeast Asian shrimp ponds are elevating mortality risks from salinity fluctuations, accelerating instrument procurement for real-time water chemistry management.
- IoT Integration:Bluetooth-enabled handheld units are replacing analog optics in field-deployed water quality testing, creating network effects as sensors feed centralized monitoring platforms.
Market Restraints
- Optical Component Supply Concentration:Precision glass prism manufacturing clusters in Germany and Japan create vulnerability to regional production disruptions and extended lead times for laboratory-grade calibration standards.
- Ultrasonic Substitution Threat:Marine research laboratories are piloting ultrasonic salinity sensors that eliminate optical fouling issues in high-particulate coastal waters, threatening refractometer incumbency in environmental monitoring.
- REACH Material Restrictions:EU substance limitations on certain optical coatings and housing polymers are forcing reformulation of European-manufactured instruments, extending product development cycles.
Strategic Opportunities
- Coral Propagation Facilities:Reef-specialized instruments targeting premium-priced coral propagation operations in Florida and Queensland offer margin expansion beyond commodity aquaculture pricing.
- ISO 17025 Calibration Services:Accreditation requirements for research laboratories are creating recurring revenue streams for instrument vendors capable of delivering certified calibration protocols.
- Desalination Plant Integration:Industrial reverse osmosis facilities in Saudi Arabia and Israel are adopting inline refractometry for brine concentration monitoring, opening capital equipment sales channels distinct from handheld markets.
Industry Challenges
- Optical Calibration Expertise Gap:Field service networks lack technicians trained in prism alignment and temperature compensation algorithms, forcing manufacturers to maintain expensive direct-service operations in remote aquaculture regions.
- Legacy System Integration Friction:Analog refractometer fleets in established marine research institutions resist digital retrofitting due to proprietary data format incompatibilities with modern laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seawater Refractometers Market |
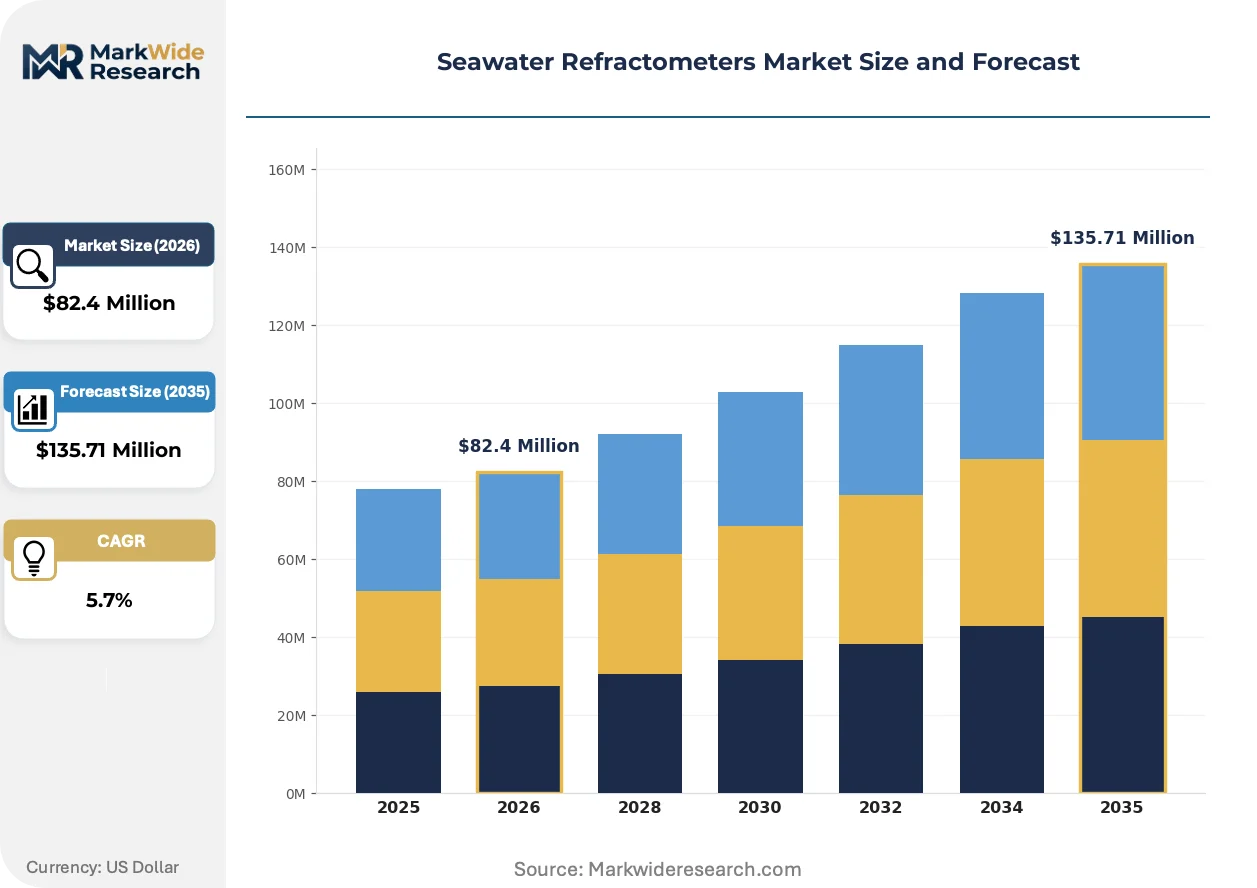
| Market Size in 2026 | $82.4 Million |
| Market Size in 2035 | $135.71 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Refractometers, Digital Refractometers, Benchtop Refractometers, Portable Refractometers Application: Aquaculture, Marine Research, Sailing, Water Quality Testing End User: Research Laboratories, Aquatic Farms, Educational Institutions, Environmental Agencies Technology: Optical Technology, Electronic Technology, Fiber Optic Technology, Ultrasonic Technology |
| Companies Covered | Red Sea, D-D The Aquarium Solution Ltd, Hanna Instruments, MISCO Refractometer, Atago, Laxco, Sper Scientific, Vee Gee Scientific, Milwaukee Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seawater Refractometers Market Trends and Innovations
Salinity measurement instrumentation is converging with networked water quality platforms, dissolving standalone device categories into integrated environmental monitoring ecosystems that demand interoperability standards and cloud-native data architectures.
Digital refractometry is automating field data capture through Bluetooth-enabled handheld units that stream readings directly to centralized aquaculture management platforms. Southeast Asian shrimp farm operators are deploying these connected instruments at scale, eliminating paper-based sampling logs and enabling predictive mortality alerts. The technology is automating compliance documentation for FDA seafood safety audits while compressing response times to salinity excursions that previously required manual intervention.
REACH substance restrictions are reshaping material specifications for optical component manufacturing across European supply chains. ECHA limitations on certain coating chemistries are forcing prism suppliers to qualify alternative anti-reflective treatments, extending validation timelines for laboratory-grade instruments. German and Dutch instrument manufacturers are absorbing these compliance costs into premium pricing tiers while Asian competitors gain share in price-sensitive aquaculture segments exempt from EU material rules.
Environmental agencies are consolidating procurement around multi-parameter water quality probes that bundle salinity with dissolved oxygen and pH sensing. United States coastal monitoring programs from California to Maine are retiring standalone refractometer fleets in favor of sonde-based platforms that reduce vessel deployment costs. This bundling is squeezing dedicated refractometer vendors into specialized niches—coral propagation, artisanal aquaculture, and educational markets—while industrial and regulatory buyers migrate to integrated systems.
Seawater Refractometers Market Segmentation
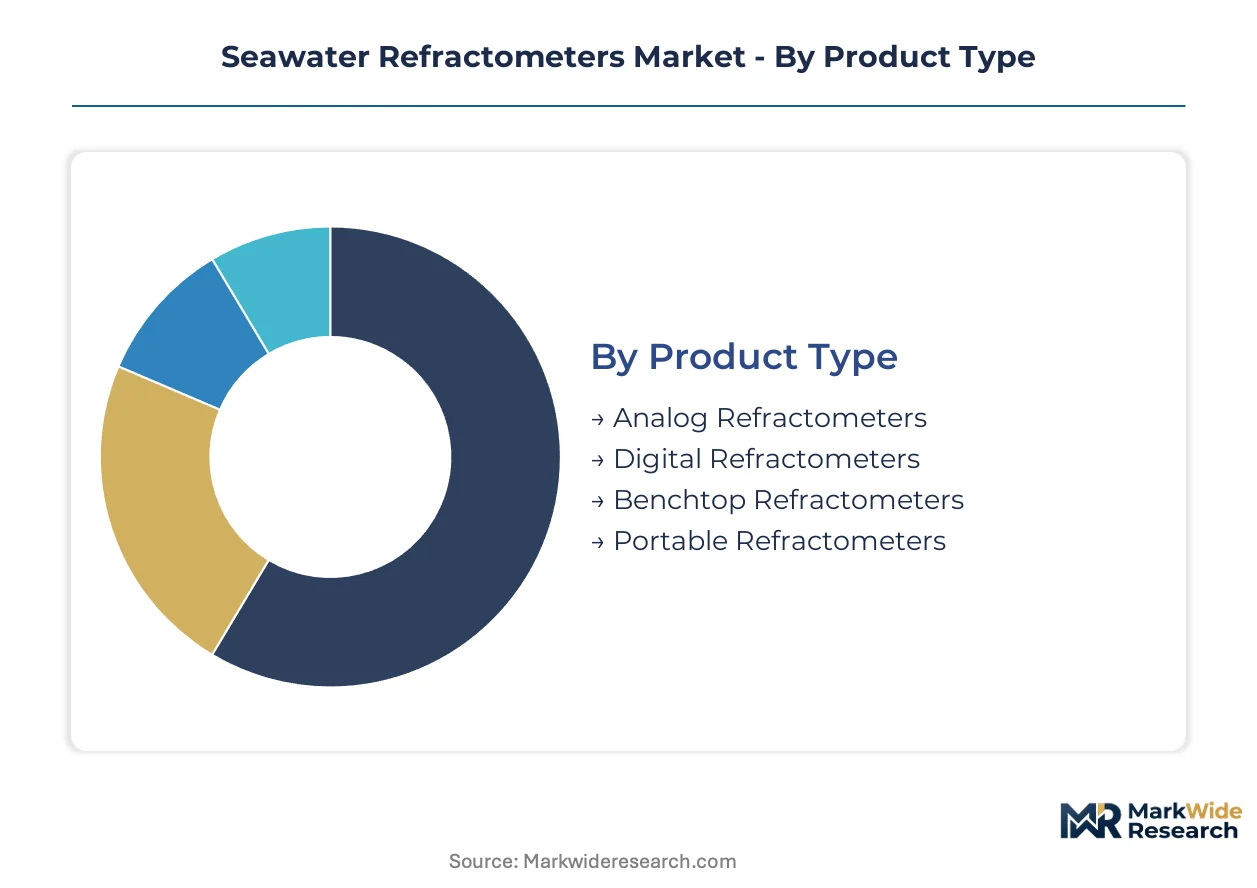
Seawater refractometer segmentation reveals divergent integration paths across product architectures. Standalone handheld units dominate field-deployed environmental compliance, while embedded sensor modules feed centralized aquaculture management platforms.
Product Type:
Digital refractometers embed most deeply into networked water quality systems, while analog and portable variants remain operationally isolated.
- Digital Refractometers:Bluetooth-enabled handheld units stream salinity readings directly to cloud-based aquaculture management platforms. Southeast Asian shrimp farm operators deploy these at scale for predictive mortality alerts and automated FDA compliance documentation.
- Portable Refractometers:Battery-powered optical units serve shoreline compliance sweeps by United States environmental agencies. Gulf shrimp farms and Pacific Northwest salmon hatcheries prioritize these for rapid field verification of EPA water quality standards.
- Analog Refractometers:Traditional optical instruments with manual prism reading retain installed base in educational settings and budget-constrained artisanal aquaculture operations.
- Benchtop Refractometers:Laboratory-grade units with temperature compensation algorithms anchor ISO 17025 accredited calibration workflows in marine research institutions.
Volume placements concentrate in portable refractometers; the faster expansion belongs to digital refractometers.
Application:
Application segments stratify by regulatory exposure and instrumentation sophistication required for compliance documentation.
- Aquaculture:Intensive farming operations in Southeast Asian shrimp ponds and Gulf Coast facilities mandate continuous salinity monitoring. Stock density increases elevate mortality risks from salinity fluctuations, accelerating procurement of real-time measurement systems.
- Marine Research:Coastal monitoring programs from California to Maine deploy multi-parameter sondes that bundle salinity sensing. Research laboratories pilot ultrasonic alternatives to eliminate optical fouling in high-particulate waters.
- Water Quality Testing:EPA-mandated dissolved salt tracking drives instrument replacement cycles at municipal and federal environmental monitoring stations.
- Sailing:Recreational vessel operators purchase handheld optical units for ballast water and engine cooling system salinity verification.
Revenue concentrates in aquaculture applications; steepest expansion trajectory appears in marine research as networked sensing platforms proliferate.
End User:
End user segments separate by procurement authority and calibration certification requirements.
- Environmental Agencies:United States coastal monitoring programs consolidate procurement around sonde-based multi-parameter platforms. These agencies retire standalone refractometer fleets to reduce vessel deployment costs across California to Maine jurisdictions.
- Aquatic Farms:Commercial operations in Gulf shrimp farming and Pacific Northwest salmon hatcheries prioritize Bluetooth-enabled handheld units for real-time water chemistry management.
- Research Laboratories:ISO 17025 accreditation mandates drive demand for certified calibration protocols and laboratory-grade benchtop instruments.
- Educational Institutions:University marine science programs and vocational training centers purchase analog and entry-level digital units for student laboratory instruction.
Procurement volume clusters with aquatic farms; the most rapid share gains occur among environmental agencies adopting integrated monitoring systems.
Technology:
Technology segments diverge by measurement principle and vulnerability to optical fouling in field conditions.
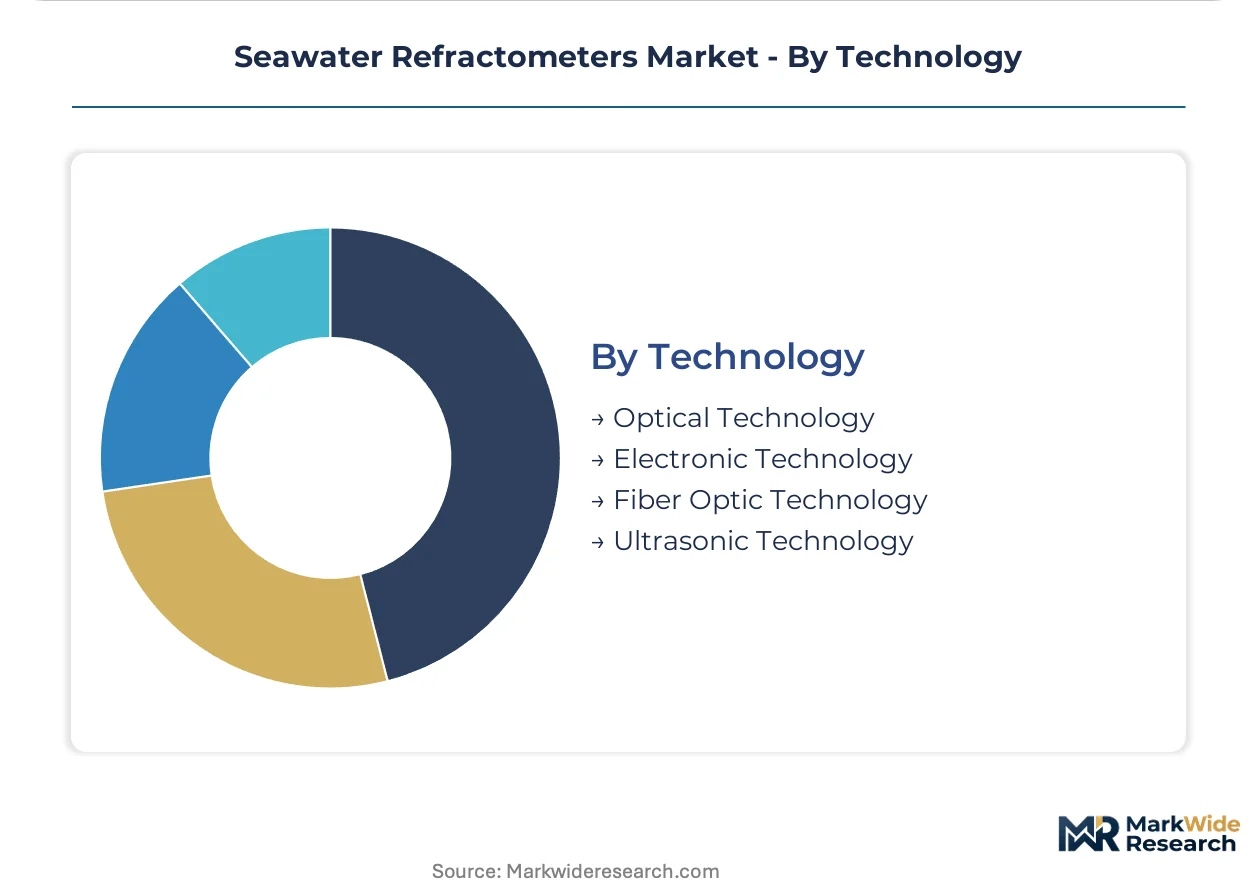
- Electronic Technology:Digital refractometers with semiconductor sensors and Bluetooth connectivity automate data capture for intensive aquaculture operations. These units eliminate manual transcription errors and enable predictive analytics platforms.
- Ultrasonic Technology:Emerging sensor architecture eliminates optical component degradation in high-particulate coastal waters. Marine research laboratories pilot these systems as substitutes for prism-based instruments.
- Optical Technology:Precision glass prism systems calibrated to the Practical Salinity Scale retain largest installed base despite margin compression from electronic alternatives.
- Fiber Optic Technology:Specialized sensing for inline industrial desalination applications in Saudi Arabian and Israeli reverse osmosis facilities enables brine concentration monitoring.
Installed base dominance resides with optical technology; electronic technology climbs fastest as aquaculture digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for aquaculture technology in Vietnam and Thailand concentrate instrument assembly operations for Southeast Asian shrimp farm supply chains. Coastal regulatory enforcement corridors in the United States and European Union marine research clusters drive differentiated demand patterns across precision salinity monitoring applications.
United States
Gulf shrimp farms and Pacific Northwest salmon hatcheries mandate EPA-compliant dissolved salt tracking at 0.1 parts per thousand resolution. FDA seafood safety protocols require automated documentation systems for intensive aquaculture operations. California to Maine coastal monitoring programs consolidate procurement around multi-parameter sonde platforms that bundle salinity sensing.
Vietnam
Intensive shrimp pond operations in the Mekong Delta elevate mortality risks from salinity fluctuations, accelerating Bluetooth-enabled handheld unit deployment. The country's national environmental regulator tightens effluent monitoring standards for coastal aquaculture zones. Ho Chi Minh City-based distributors channel instruments to Mekong Delta farming cooperatives undergoing digitization.
Germany
Precision glass prism manufacturing clusters supply laboratory-grade calibration standards to marine research institutions. ECHA REACH substance restrictions force reformulation of optical coatings and housing polymers, extending validation timelines for European-manufactured instruments. Hamburg and Bremen port authorities deploy salinity monitoring for ballast water treatment compliance.
Japan
Atago sustains technology leadership through precision optical systems calibrated for brackish water transitions in coastal aquaculture. METI industrial standards shape instrument specifications for desalination plant integration. Osaka-Kobe manufacturing corridors produce high-resolution refractometry components for export to Southeast Asian markets.
Saudi Arabia
Industrial reverse osmosis facilities adopt inline refractometry for brine concentration monitoring in desalination operations. The country's national water regulator mandates continuous salinity tracking for coastal discharge compliance. Jubail Industrial City hosts instrument integration projects linking refractometry to centralized plant control systems.
Seawater Refractometers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with precision optical instrument makers defending laboratory-grade margins while electronic module assemblers capture volume in aquaculture digitization. Market structure tilts toward consolidation at the premium tier and fragmentation in commodity handheld supply. Three archetypes dominate: reef-specialized premium instrument designers, digital platform integrators for intensive farming, and precision optical component fabricators. Capacity expansion in Southeast Asian assembly operations and strategic partnerships for IoT platform integration represent the dominant competitive moves reshaping positioning.
Among precision optical specialists, Atago and Red Sea exemplify divergent specialization strategies—Atago occupying the brackish water calibration niche while Red Sea anchors reef-specialized premium positioning for coral propagation facilities. Hanna Instruments represents the digital platform integrator archetype, with its electronic salinity testing systems deployed across Southeast Asian shrimp farm networks. Milwaukee Instruments and Vee Gee Scientific sit within the mid-tier electronic handheld segment, supplying environmental agencies and educational institutions with field-deployable units.
| Leading Market Players |
|---|
| Red Sea |
| D-D The Aquarium Solution Ltd |
| Hanna Instruments |
| MISCO Refractometer |
| Atago |
| Laxco |
| Sper Scientific |
| Vee Gee Scientific |
| Milwaukee Instruments |
| Others |
Pricing and Supply Chain Analysis
Bluetooth-enabled handheld unit assembly is migrating from Japanese precision optics houses to Vietnamese contract manufacturers, simultaneously compressing electronic module costs and fragmenting supply authority across Southeast Asian special economic zones. This geographic redistribution of digital refractometer production is decoupling pricing power from traditional German and Japanese optical clusters while creating tiered sourcing strategies calibrated to certification requirements.
Pricing Analysis
Lead-time premiums for laboratory-grade calibration standards command substantial markups over spot inventory of portable field units. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-certified benchtop instruments from Bluetooth-enabled aquaculture handhelds and entry-level analog optics for educational markets. Price differentiation hinges on certification tier and after-sales calibration service bundling. Cost compression in the portable segment is intensifying because Southeast Asian contract manufacturers are absorbing REACH compliance costs for European competitors. Environmental agencies exhibit lowest price sensitivity due to mandated procurement protocols, while artisanal aquaculture cooperatives in Vietnam and Thailand drive aggressive spot-market negotiation.
Supply Chain Analysis
Workforce availability constraints in Osaka-Kobe precision optics corridors and Hamburg glass prism manufacturing clusters are elevating automation investment thresholds for laboratory-grade instrument suppliers. Geographic supply concentration centers on Japan, Germany, and Vietnam for finished instruments, with China anchoring semiconductor sensor and Bluetooth module sourcing. Raw material dependencies include borosilicate glass prisms, anti-reflective optical coatings, and lithium-ion battery cells for handheld units. Single-source vulnerability concentrates in German precision glass prism fabrication for calibration standards. Distribution runs through Ho Chi Minh City and Bangkok distributors serving Mekong Delta shrimp farming cooperatives, with direct-service operations maintained by manufacturers in remote aquaculture regions lacking trained field technicians.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around digital platform capabilities as ultrasonic substitution threats and IoT integration mandates force analog specialists into acquisition targets or niche retreat.
For Market Incumbents: Acquire cloud-native data architecture capabilities to anchor aquaculture management platform integration. Backward integration into precision glass prism fabrication in Germany or Japan defends calibration service margins against Asian electronic competitors. Prioritize ISO 17025 certification investment to capture recurring revenue streams from research laboratories facing accreditation mandates. For New Entrants and Emerging Players: The price-point gap between Red Sea's reef-specialized premium instruments and Milwaukee's mid-tier electronic handhelds offers entry space for connected devices targeting artisanal aquaculture. Target Vietnam's Mekong Delta farming cooperatives undergoing digitization with simplified Bluetooth units priced below Hanna's platform-integrated systems. Deploy through Ho Chi Minh City distributors with localized technical support to bypass incumbent direct-service networks. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by digital platform integrators seeking optical calibration expertise or by precision instrument conglomerates filling aquaculture portfolio gaps. Long-term viability favors vendors with captive cloud infrastructure and recurring calibration service revenue rather than transactional hardware sellers. Watch ultrasonic sensor pilot outcomes at California and Maine coastal monitoring programs as inflection indicator for refractometer incumbency erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Bluetooth Platform Integration | Hanna Instruments dominates Southeast Asian shrimp farm networks through cloud-connected handheld deployment. |
| ISO 17025 Calibration Service Expansion | Atago and Red Sea capture recurring revenue from marine research laboratories facing accreditation mandates. |
| REACH-Compliant Material Reformulation | German manufacturers absorb extended validation timelines into premium pricing tiers for European markets. |
| Ultrasonic Sensor R&D Partnerships | Marine research institutions in California pilot optical alternatives threatening refractometer environmental monitoring share. |
| Vietnamese Assembly Capacity Buildout | Contract manufacturers in Ho Chi Minh City special economic zones serve Mekong Delta digitization demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this seawater refractometer market assessment. Primary interviews with aquaculture operations managers, environmental agency procurement officers, marine research laboratory directors, and precision instrument distributors were combined with EPA water quality standard documentation, FDA seafood safety protocol filings, and ECHA REACH substance restriction databases. Bottom-up triangulation across instrument shipment volumes and top-down reconciliation against aquaculture facility expansion permits validated segment sizing.
Data-stream reconciliation across electronic refractometer unit placements, optical instrument replacement cycles, and calibration service contract values informed the analytical framework. Segmentation dimensions modeled include product architecture, application intensity, end-user procurement authority, and measurement technology principle across the projection horizon. CAGRs were derived from instrument procurement patterns at Gulf shrimp farms and Pacific Northwest salmon hatcheries, Bluetooth adoption curves in Southeast Asian aquaculture, and ultrasonic sensor pilot expansion rates at coastal monitoring programs.
Inputs from EPA enforcement actions, FDA seafood safety audits, and ECHA coating chemistry restrictions were available through the study window; gaps in real-time Vietnamese and Thai aquaculture procurement data introduce uncertainty bands around Southeast Asian demand trajectories. Forecasts reflect assumptions regarding IoT platform integration timelines, ultrasonic sensor technical maturation, and REACH substance restriction expansion scope. Material deviation in EPA water quality standard enforcement intensity, Bluetooth module supply availability, or ultrasonic sensor accuracy benchmarks warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Industrial X-Ray CT Inspection Systems for Complex Metal Components Market
Analytical Instruments
Near Infrared Spectrum Instruments Market
Analytical Instruments
Metal Analyzers Market
Analytical Instruments
Real-Time Spectrum Analysis Market
Analytical Instruments
Infrared Thermometers Market
Analytical Instruments
TDLAS Moisture Analyzers Market
Analytical Instruments
Global Q-TOF Mass Spectrometry Market
Analytical Instruments
Global Raman Spectroscopy Market
Analytical Instruments
Air Sampler Market
Analytical Instruments
Global Mass Spectrometry Market
Analytical Instruments
Automated Microscopy Market
Analytical Instruments
Digital Moisture Analyzer Market
Analytical Instruments
Universal Probe Library Market
Analytical Instruments
Surface and Field Analytics Market
Analytical Instruments
Logic Analyzer Market
Analytical Instruments
Global Handheld LCR Meters Market